
 Medical Equipment Calibration Services Market | 2026-2036
Medical Equipment Calibration Services Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Equipment Calibration Services Market Intelligence
The integration of IoT sensors and cloud-based software for remote calibration is narrowing the gap between onsite and offsite service delivery models. This shift enables predictive maintenance, altering traditional service schedules for greater efficiency. Fluke Biomedical leverages its brand in test tools to lead in the diagnostic instrument segment. Transcat specializes in accredited services for life sciences clients, while Trescal competes on its broad geographic footprint.
Medical equipment calibration services systematically compare a device's measurements to a known standard, ensuring accuracy within tolerances like those in ISO/IEC 17025. This process guarantees that diagnostic and monitoring equipment provides reliable data for patient care and compliance. Preventive calibration is the largest service type, driven by OEM requirements. Predictive calibration, however, is expanding rapidly, especially for complex patient monitoring systems and laboratory analyzers.
Regulatory mandates from bodies such as the US FDA and the European Medicines Agency under its Medical Device Regulation (MDR) create a non-discretionary need for certified calibration. These frameworks stipulate stringent documentation and traceability requirements, directly influencing service provider protocols. The critical decision is balancing investment in advanced remote capabilities against the persistent need for high-touch, onsite expertise for complex instrumentation.
Market Dynamics
The increasing stringency of regulatory frameworks, particularly the documentation and traceability mandates within the European Union's Medical Device Regulation (MDR) and ISO 13485, is the central force compelling healthcare providers to seek more sophisticated and verifiable calibration services.
Growth Catalysts
- Expanding Diagnostic Infrastructure:The proliferation of independent clinical laboratories and outpatient diagnostic centers, especially in developed economies like Germany, requires frequent, documented calibration for a growing fleet of complex analytical instruments to ensure accurate patient testing.
- Regulatory Mandates:Stringent requirements from bodies such as the US FDA and the European Medicines Agency for auditable calibration records and traceability create a non-discretionary, recurring demand for certified services.
- Quality Management Standards:The widespread adoption of the ISO 13485 standard for medical device quality management systems formalizes the need for scheduled calibration as a core component of device lifecycle management and compliance.
Market Restraints
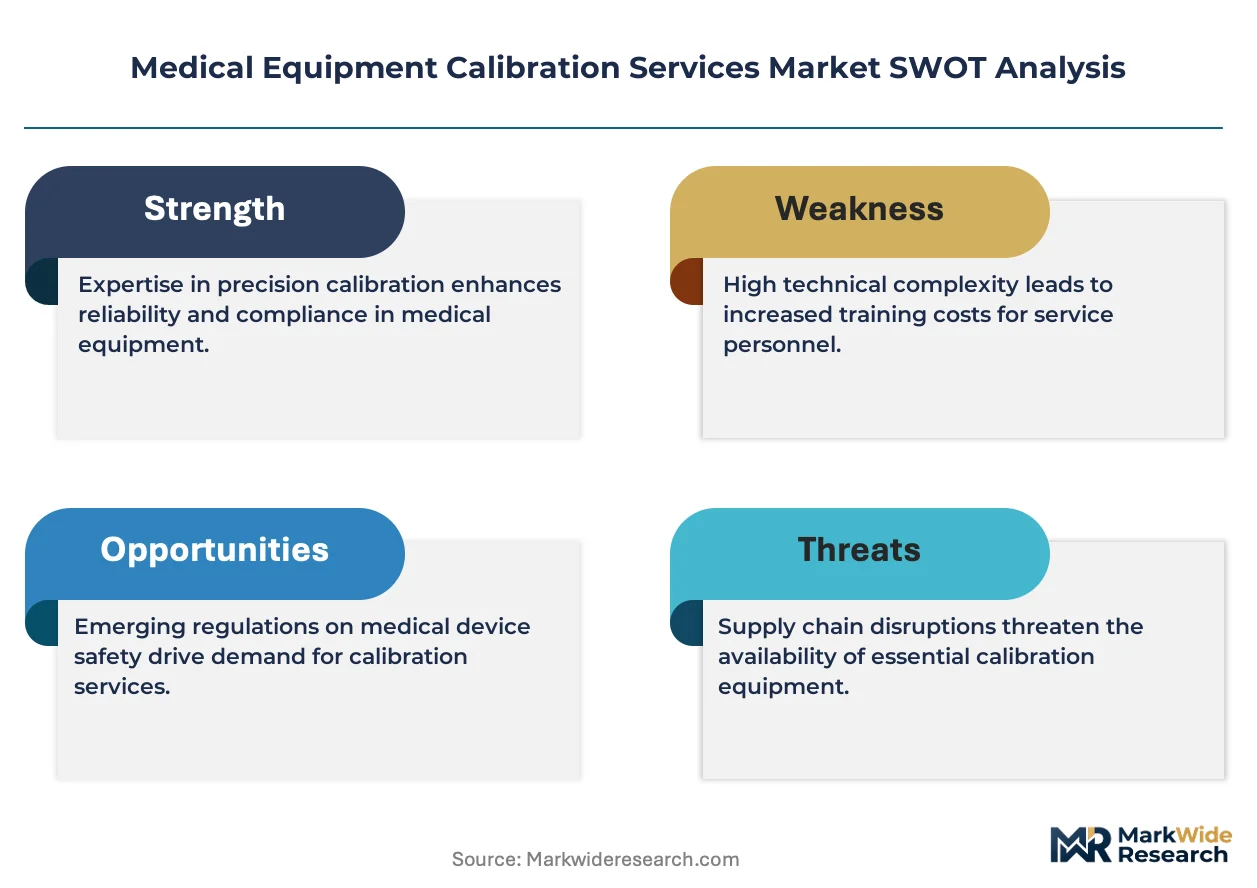
- High Capital Investment:The significant cost of acquiring and maintaining primary metrology standards and accredited laboratory environments creates a high barrier to entry, concentrating the market among established service providers.
- Technical Expertise Scarcity:A shortage of qualified metrology engineers and technicians with dual expertise in both advanced medical instrumentation and calibration science limits service capacity and drives up labor costs.
- Onsite Service Limitations:While remote services are growing, the calibration of large, complex, or integrated systems like MRI machines or robotic surgical suites still requires costly and logistically complex onsite expert intervention.
Strategic Opportunities
- Predictive Maintenance Models:Integrating AI and machine learning with data from IoT sensors offers an opportunity to move beyond fixed schedules to predictive calibration, optimizing equipment uptime and reducing service costs for hospitals.
- Service Expansion in Emerging Markets:As healthcare infrastructure modernizes in regions like Southeast Asia and Latin America, there is a significant opportunity to establish local, accredited calibration services to support new hospitals and labs.
- Calibration-as-a-Service (CaaS):Developing subscription-based service models that bundle software, remote monitoring, and scheduled onsite visits can create recurring revenue streams and deeper client integration for service providers.
Industry Challenges
- Data Security and Compliance:Service providers handling device data remotely must navigate complex data privacy regulations, such as HIPAA in the United States and GDPR in Europe, to ensure the security of sensitive information.
- Legacy System Integration:Integrating modern, cloud-based calibration management platforms with older, disparate hospital IT systems and asset management software presents a significant technical and operational hurdle for providers and clients.
- Standardization of Remote Procedures:A lack of universally accepted standards for performing and documenting remote calibrations for certain device types creates uncertainty and can slow adoption by risk-averse healthcare organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Equipment Calibration Services Market |
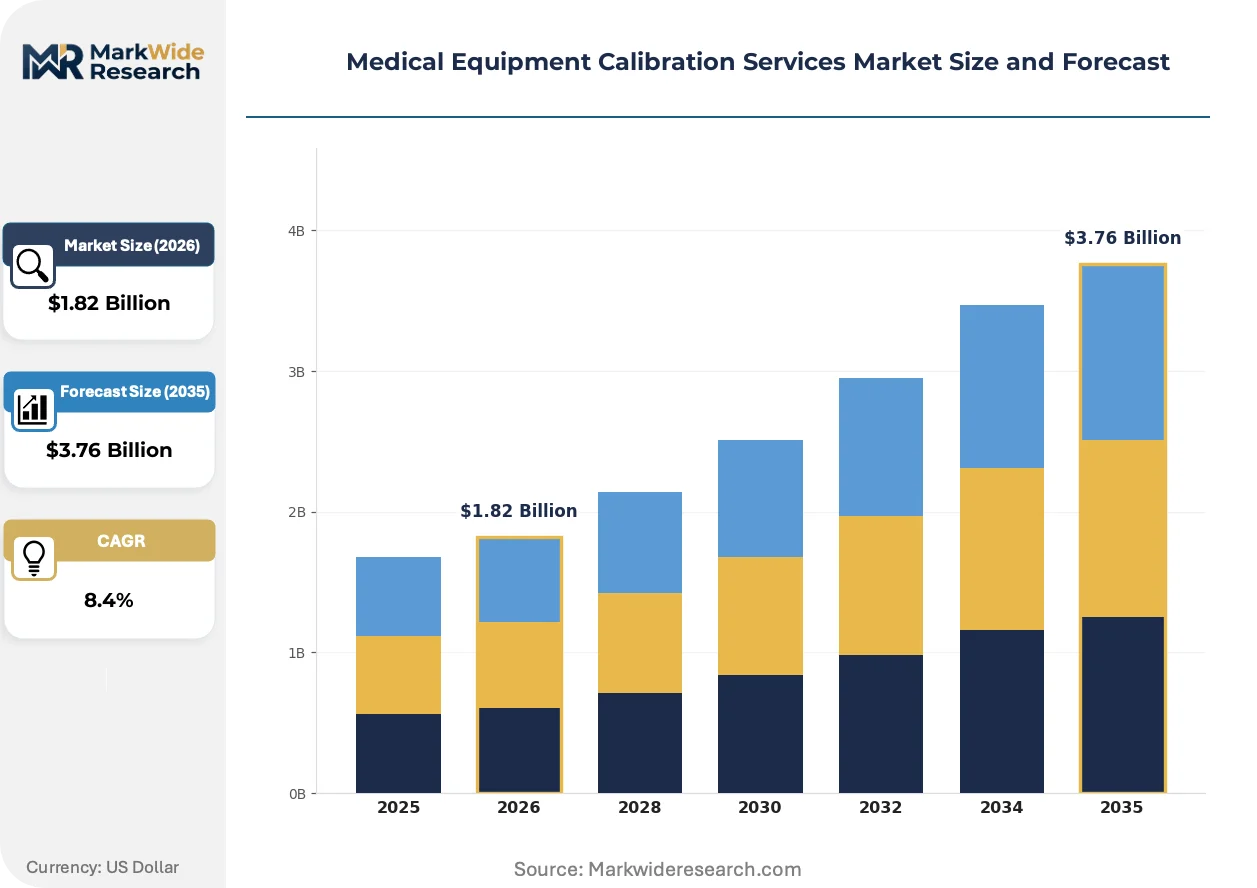
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.76 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Preventive Calibration, Corrective Calibration, Predictive Calibration, Emergency Calibration Equipment Category: Imaging Devices, Diagnostic Instruments, Surgical Tools, Patient Monitoring Systems, Laboratory Analyzers End User: Hospitals, Diagnostic Centers, Research Laboratories, Specialty Clinics, Rehabilitation Centers Delivery Model: Onsite Calibration, Remote Calibration, Third-Party Services, In-House Calibration |
| Companies Covered | Fluke Biomedical, Tektronix, Agilent Technologies, Ametek Test & Calibration, Transcat, Trescal, JM Test Systems, SIMCO Electronics, NS Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Equipment Calibration Services Market Strategic Shifts & Innovations
The market's evolution is marked by a transition from scheduled, manual interventions to data-driven, predictive service models. This change is driven by technological convergence and a demand for greater operational efficiency and auditable compliance within large-scale healthcare facilities.
Cloud-based calibration management software, integrated with IoT sensors, automates the collection of performance data from medical instruments in real time. Large hospital networks and multi-site diagnostic laboratory chains are the primary adopters, seeking to centralize oversight and streamline compliance. This integration is collapsing the traditional time lag between onsite measurement and offsite data analysis, enabling near-instant compliance reporting and asset performance review.
The global implementation of Unique Device Identification (UDI) systems, mandated by regulators like the US FDA and under the EU's MDR, is creating a new layer of required traceability. This system assigns a unique code to each device, linking its manufacturing data to its entire service history. Service providers are most affected, as they must now incorporate UDI data directly into calibration certificates and management software to maintain a complete, auditable device lifecycle record.
Large healthcare systems are increasingly favoring consolidated, multi-vendor service (MVS) contracts to streamline their asset management and compliance workflows. This model disrupts the traditional reliance on multiple OEM-exclusive or single-specialty service providers for different equipment types. The shift is most visible within integrated delivery networks (IDNs) in North America and Western Europe, where procurement seeks a single partner for calibrating diverse assets.
Medical Equipment Calibration Services Market Segmentation
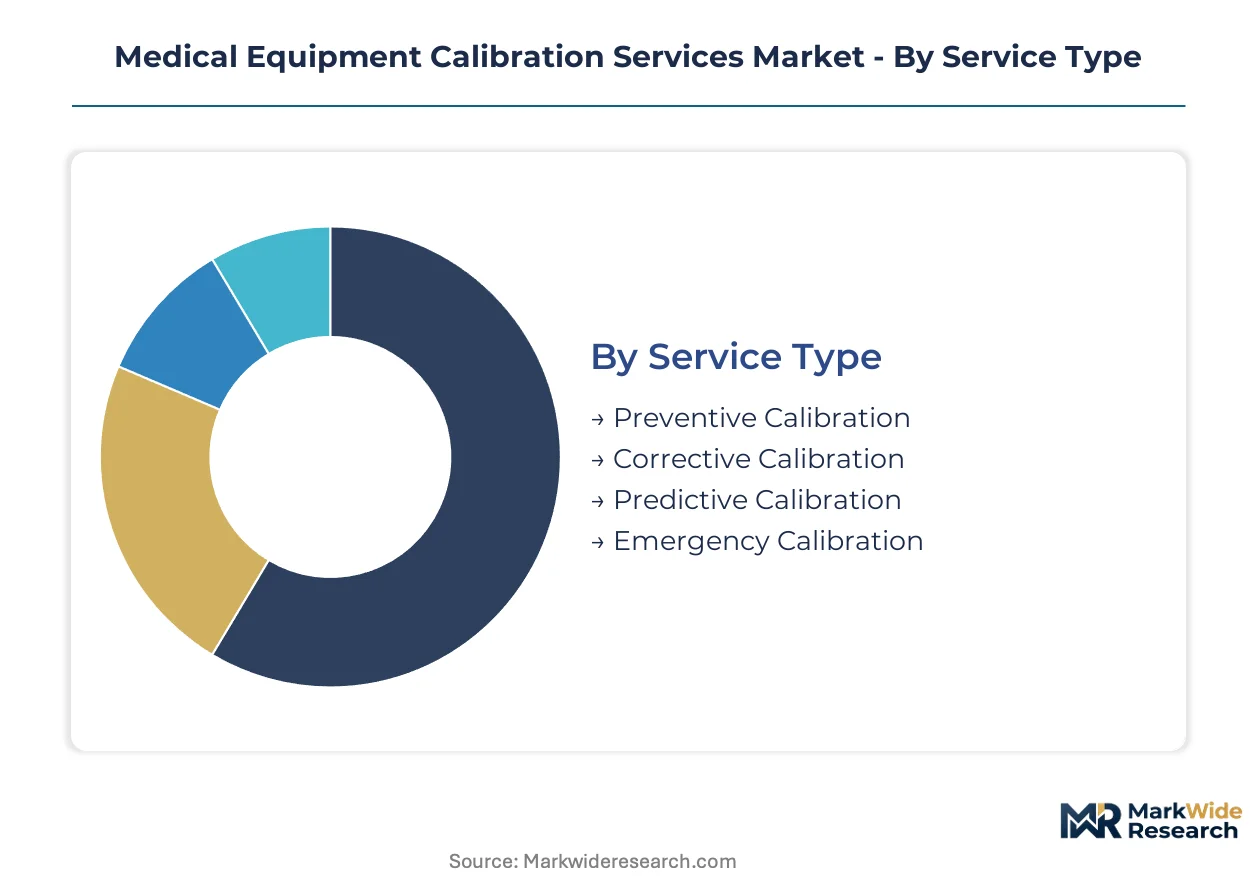
The segmentation of the Medical Equipment Calibration Services Market is critical for understanding the varied demands for precision, regulatory compliance, and operational efficiency across healthcare settings. Each segment reflects distinct operational requirements and technological dependencies that shape service delivery models.
Service Type:
The intensity of after-sales service requirements significantly differentiates calibration service types, reflecting varied operational needs and regulatory pressures.
- Preventive Calibration:This systematic process involves scheduled checks and adjustments to medical devices, ensuring they operate within specified tolerances before issues arise. OEM requirements often mandate this type of calibration to maintain warranty validity and device performance standards.
- Predictive Calibration:Utilizing data from IoT sensors and machine learning algorithms, this service anticipates potential deviations in equipment performance, scheduling calibration only when necessary. This model is rapidly expanding for complex patient monitoring systems and advanced laboratory analyzers.
- Corrective Calibration:This service addresses identified inaccuracies or malfunctions in medical equipment, restoring it to proper operating specifications.
- Emergency Calibration:Rapid response calibration services are deployed when critical medical equipment experiences sudden, unexpected performance failures.
By volume, Preventive Calibration commands the largest share. By growth pace, Predictive Calibration is ahead.
Equipment Category:
The diverse applications of medical devices dictate specialized calibration protocols and technical expertise across different equipment categories.
- Diagnostic Instruments:This category includes devices like spectrophotometers, centrifuges, and blood gas analyzers, crucial for accurate disease detection and patient assessment. Fluke Biomedical leverages its brand in test tools to lead service provision in this segment.
- Laboratory Analyzers:These sophisticated instruments, such as immunoassay and clinical chemistry analyzers, perform complex tests requiring high precision and frequent calibration to ensure reliable data output. Predictive calibration models are increasingly adopted for these systems.
- Imaging Devices:Equipment such as X-ray machines, CT scanners, and ultrasound systems require specialized calibration to ensure image quality and patient safety.
- Surgical Tools:Precision instruments used in operating rooms, including electrosurgical units and robotic surgical components, demand meticulous calibration for functional accuracy.
- Patient Monitoring Systems:Devices tracking vital signs, cardiac activity, and respiratory function need consistent calibration for continuous, reliable patient data.
Diagnostic Instruments and Laboratory Analyzers collectively drive substantial demand due to their high usage frequency and stringent accuracy requirements.
End User:
Different end-user profiles exhibit distinct procurement patterns and service level expectations for medical equipment calibration.
- Hospitals:These large healthcare facilities operate extensive fleets of diverse medical equipment, necessitating comprehensive calibration services for patient care and regulatory compliance. Large healthcare systems often favor consolidated multi-vendor service contracts to streamline operations.
- Diagnostic Centers:The proliferation of independent clinical laboratories and outpatient diagnostic centers, particularly in developed economies, generates significant demand for frequent, documented calibration of complex analytical instruments. These centers require auditable records for accreditation.
- Research Laboratories:Academic and commercial research facilities require calibrated equipment to ensure the accuracy and reproducibility of experimental results.
- Specialty Clinics:Focused medical practices, such as cardiology or ophthalmology clinics, require calibration for their specialized diagnostic and treatment devices.
- Rehabilitation Centers:Facilities providing physical and occupational therapy rely on calibrated equipment for accurate patient progress monitoring and treatment delivery.
Hospitals and Diagnostic Centers remain the primary revenue generators, driven by their extensive equipment fleets and continuous operational demands.
Delivery Model:
Operational logistics and technological integration define the effectiveness and reach of various calibration service delivery models.
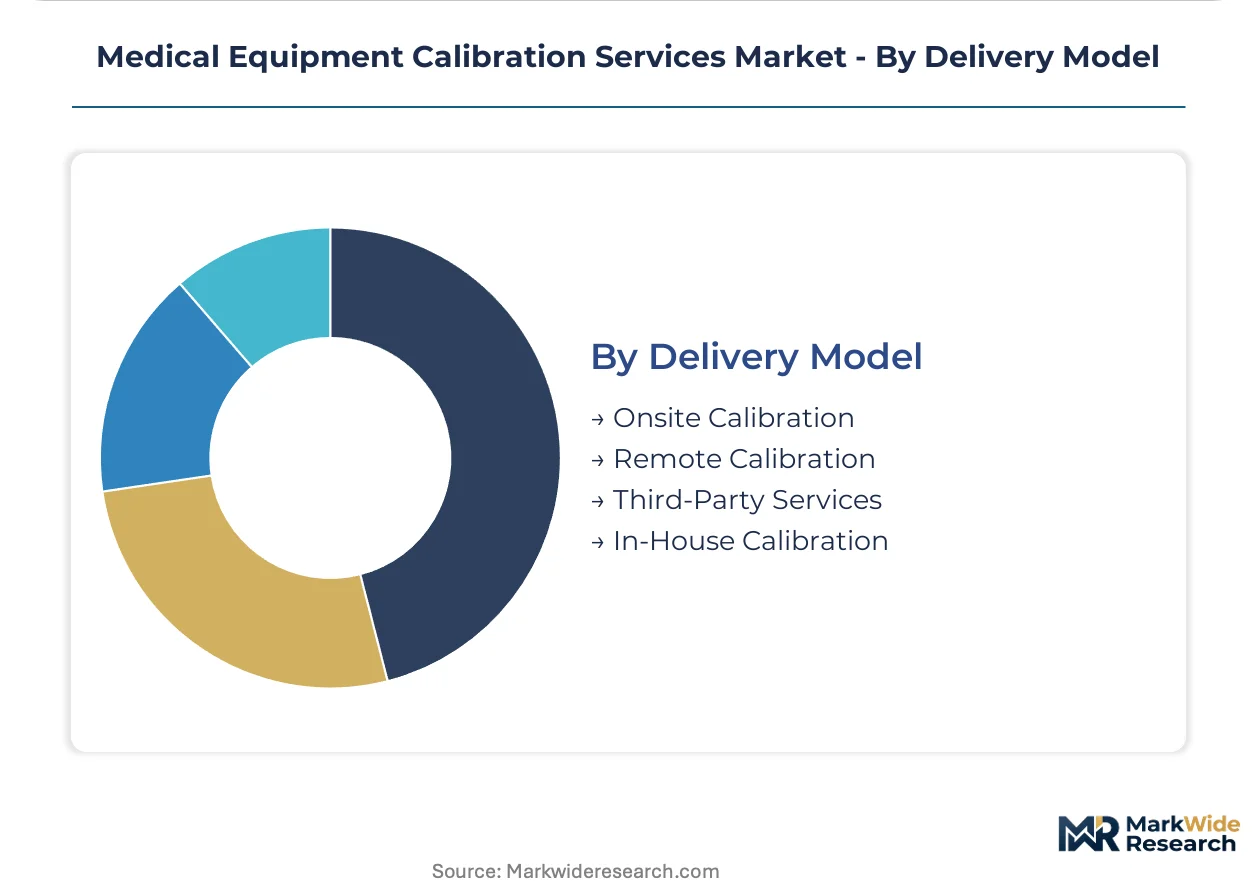
- Onsite Calibration:This model involves technicians performing calibration directly at the client's facility, essential for large, complex, or integrated systems like MRI machines. It requires high-touch, expert intervention.
- Remote Calibration:Leveraging IoT sensors and cloud-based software, this model allows for calibration and monitoring from a distant location, enabling predictive maintenance and greater efficiency. This approach narrows the gap between onsite and offsite service delivery.
- Third-Party Services:Independent calibration providers offer specialized services, often holding broad accreditations like ISO/IEC 17025, serving multiple healthcare clients. Transcat specializes in accredited services for life sciences clients.
- In-House Calibration:Some large healthcare organizations maintain their own metrology departments to perform calibration services internally, often for routine or high-volume equipment.
While Onsite Calibration maintains its necessity for intricate systems, Remote Calibration is gaining significant traction through technological advancements and efficiency gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical equipment manufactured in Germany often requires precise calibration services when deployed in hospitals across the United States. This cross-border flow of sophisticated devices creates a continuous demand for certified calibration services, aligning diverse regulatory landscapes. The expansion of advanced diagnostic centers globally further intensifies this need for accurate and compliant equipment maintenance.
United States
Extensive hospital networks and outpatient diagnostic centers drive significant demand for calibration services. The US FDA mandates stringent calibration records and traceability for medical devices, ensuring patient safety. Major medical technology hubs like Boston and Southern California demonstrate high concentrations of demand for specialized calibration expertise.
Germany
Germany's advanced clinical laboratory sector and robust medical device manufacturing base necessitate frequent, high-precision calibration. The European Medicines Agency's Medical Device Regulation (MDR) enforces strict compliance requirements for all medical equipment. Bavaria and North Rhine-Westphalia serve as key regions for both medical device production and sophisticated calibration service providers.
Japan
Japan's aging population and highly developed healthcare system require consistently accurate medical equipment. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees stringent quality and calibration standards for all devices. The Kanto region, including Tokyo, anchors significant demand from advanced hospitals and research institutions.
China
Rapid expansion of healthcare infrastructure and a growing domestic medical device industry fuel demand for calibration services in China. The National Medical Products Administration (NMPA) enforces increasingly strict regulations for device performance and traceability. The Yangtze River Delta region is a focal point for both medical device manufacturing and large-scale hospital development.
India
India's modernizing healthcare sector and burgeoning medical tourism industry generate substantial demand for reliable equipment calibration. The Central Drugs Standard Control Organization (CDSCO) provides guidelines for medical device regulation, including calibration. Bengaluru and the Delhi-National Capital Region are emerging as significant clusters for advanced diagnostic centers.
Medical Equipment Calibration Services Market Key Industry Players
On the supply side, the industry is tiered, with established metrology firms and specialized medical device service providers dominating. This structure reflects the high capital investment required for primary metrology standards and accredited laboratory environments. Strategic archetypes include large, multi-geography service providers, specialized niche players, and OEM-affiliated service divisions. Geographic expansion and strategic partnerships, particularly for remote service capabilities, represent dominant competitive moves.
Specialized providers in this market include Fluke Biomedical, which leverages its brand in test tools for diagnostic instrument calibration. Transcat occupies a strong position with its accredited services tailored for life sciences clients. Trescal exemplifies a service provider competing on a broad geographic footprint, offering extensive reach across various regions.
| Leading Market Players |
|---|
| Fluke Biomedical |
| Tektronix |
| Agilent Technologies |
| Ametek Test & Calibration |
| Transcat |
| Trescal |
| JM Test Systems |
| SIMCO Electronics |
| NS Medical Systems |
| Others |
Cost & Logistics Intelligence
Germany's advanced manufacturing clusters, particularly in Bavaria, influence the cost structure for high-precision medical equipment. This regional specialization impacts the downstream pricing power for calibration services, especially for complex analytical instruments.
Pricing Analysis
The technology-generation pricing gap between legacy analog devices and new IoT-enabled instruments creates distinct service tiers. Subscription-based service models dominate for predictive calibration, bundling software and remote monitoring. Price differentiation stems from accreditation level, such as ISO/IEC 17025, and the complexity of the instrument requiring calibration. Pricing softness reflects increased competition from multi-vendor service providers. Hospitals exhibit high price sensitivity for routine equipment, while research laboratories prioritize accuracy and certification over cost.
Supply Chain Analysis
Export control regimes for specialized metrology components, particularly from the United States and Germany, can restrict the flow of critical calibration standards. The supply chain for calibration services draws from highly specialized components like reference standards and high-precision sensors. Geographic concentration for these critical inputs lies in the US, Germany, and Japan. Single-source vulnerability for specific reference materials poses a structural risk. Distribution runs through a network of accredited third-party service providers and OEM-affiliated divisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is at a platform-economics inflection point, driven by the emergence of cloud-based calibration management ecosystems. Interoperability with hospital IT systems and asset management software is reshaping competitive positioning.
For Market Incumbents: Entrench market leadership by investing heavily in remote calibration capabilities and AI-driven predictive maintenance platforms. Consolidate smaller regional players to expand geographic reach and specialized expertise, particularly against the threat of new software-centric entrants. Control over accredited metrology standards serves as a critical lever for differentiation.
For New Entrants and Emerging Players: Pursue niche specialization in emerging device categories, such as robotic surgical tools, where established players may lack agile solutions. Target underpenetrated mid-sized diagnostic centers in developing economies with bundled Calibration-as-a-Service offerings. A digital-first go-to-market angle emphasizing data analytics and compliance reporting offers differentiation.
For Investors and Strategic Acquirers: Carve-out targets emerge from large medical device manufacturers seeking to divest non-core service divisions. The long-term viability of this market remains strong over the next decade due to non-discretionary regulatory demand. Acquisition targets should be accredited third-party providers with strong regional footprints or advanced remote capabilities. The signal to watch is the increasing adoption of UDI systems by major healthcare networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-driven Predictive Calibration Platforms | Optimizes equipment uptime for hospitals and reduces unscheduled maintenance interventions. |
| Secure ISO/IEC 17025 Accreditation Expansion | Ensures services meet global quality standards, critical for regulatory compliance and client trust. |
| Form Strategic Partnerships with Telemedicine Providers | Extends remote service reach and integrates calibration into broader digital health ecosystems. |
| Acquire Regional Accredited Calibration Labs | Expands geographic footprint and specialized technical expertise in high-demand areas like Germany. |
| Invest in Cybersecurity for Remote Data Management | Protects sensitive patient and device data, crucial for compliance with HIPAA and GDPR regulations. |
Research Approach
Operator-level perspectives from biomedical engineers, hospital procurement managers, regulatory compliance officers, and independent calibration service owners anchored the qualitative base. This primary research was triangulated with secondary data from FDA filings, EMA guidelines, ISO standards documentation, and industry association reports. Bottom-up analysis of equipment installations complemented top-down market sizing.
Scenario-bracketing involved modeling various adoption rates for predictive calibration and the expansion of diagnostic infrastructure across the analysis window. Segmentation dimensions included service type, equipment category, end user, delivery model, and regional regulatory stringency. Compound annual growth rates were derived from historical trends and projected technological advancements. The forecast considered the rate of new medical device approvals as a key input.
Sensitivities concentrate around unforeseen regulatory shifts or rapid technological obsolescence of current calibration methods. Forecasts reflect documented assumptions regarding healthcare spending and infrastructure development. Material shifts in global medical device manufacturing or accreditation requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Patient Lifting Equipment Market
Medical Equipment
Global Medical Equipment Cooling Market
Medical Equipment
Life Support Systems Market
Medical Equipment
Global Refrigerated Incubators Market
Medical Equipment
Global Medical Lasers Market
Medical Equipment
Equine Operating Tables Market
Medical Equipment
Global Medical Carts Market
Medical Equipment
Refurbished MRI Systems Market
Medical Equipment
Medical Ultrasonic Baths Market
Medical Equipment
Bench-Top Dental Autoclaves Market
Medical Equipment
MRI Transport Market
Medical Equipment
Global Blood Purification Equipment Market
Medical Equipment
Bone Densitometer Systems Market
Medical Equipment
North America Medical Carts Market
Medical Equipment
Global Medical Lighting Technologies Market
Medical Equipment
Global Capnography Equipment Market