
 North America Medical Automation Market | 2026-2036
North America Medical Automation Market Size, Share, and Industry Trends Forecast 2026-2036
North America Medical Automation Market Analytics
ISO 13485-compliant manufacturing is collapsing from a premium tier into a baseline expectation for vendor qualification across North American health systems. Siemens Healthineers leverages its imaging-to-robotics pipeline to sustain integrated system sales. GE Healthcare anchors its automation portfolio through enterprise-wide asset management platforms. Intuitive Surgical dominates robotic surgery installations with proprietary instrument ecosystems that lock in recurring revenue streams.
Medical automation encompasses electromechanical systems, software algorithms, and sensor networks engineered to execute clinical tasks with precision thresholds exceeding human capability, typically operating within sub-millimeter tolerances for surgical applications and microfluidic scales for laboratory processing. The primary commercial purpose centers on reducing procedural variability while compressing cycle times across diagnostic, therapeutic, and operational workflows. Robotic surgery and laboratory automation command the dominant share of current capital expenditure, with artificial intelligence and machine learning representing the fastest-expanding technology layer as hospitals seek predictive analytics for patient deterioration and resource allocation. Cloud computing infrastructure supports telehealth services and distributed inventory management, though margin pools remain concentrated in on-premise robotic platforms where service contracts extend equipment monetization over decade-long lifecycles.
FDA premarket clearance pathways for software-as-medical-device products shape development timelines and clinical evidence requirements for automation vendors seeking US market access. The Centers for Medicare and Medicaid Services reimbursement determinations directly influence hospital adoption velocity for capital-intensive robotic systems. Health Canada and the US Department of Health and Human Services coordinate on cybersecurity frameworks for connected medical devices, tightening interoperability standards. Stakeholders must monitor evolving FDA guidance on adaptive AI algorithms to determine whether continuous learning architectures require iterative regulatory submissions or qualify for predetermined change control plans.
Market Dynamics
Labor shortages across US hospital systems are accelerating capital deployment toward robotic surgery platforms and AI-enabled diagnostics, compressing traditional equipment replacement cycles from seven years to four.
Growth Catalysts
- FDA premarket notification pathways:The FDA's streamlined 510(k) review process for AI-enabled diagnostic devices is compressing time-to-market for software vendors, incentivizing clinical validation infrastructure investment.
- Texas Medical Center cluster:Concentrated procurement budgets across Houston's 61-member hospital consortium are creating demand anchors for integrated robotics and imaging systems.
- Cloud-native surgical planning:Distributed computing architectures are enabling real-time intraoperative guidance, expanding addressable procedures beyond traditional robotic surgery boundaries.
Market Restraints
- Proprietary instrument ecosystems:Locked consumable revenue models from dominant robotic surgery vendors inflate per-procedure costs, constraining adoption at mid-tier health systems.
- Neodymium supply concentration:Rare earth magnet dependencies for surgical motor assemblies create input cost volatility tied to Chinese export quotas.
- Cybersecurity framework fragmentation:Divergent Health Canada and HHS interoperability standards for connected devices force dual compliance architectures, extending development timelines.
Strategic Opportunities
- Canada's underpenetrated ambulatory surgery centers:Provincial health authority procurement reforms are opening capital windows for same-day robotic procedures outside traditional hospital infrastructure.
- AI-robotics convergence:Adaptive surgical algorithms paired with haptic feedback systems are creating autonomous suturing applications in microvascular reconstruction.
- Outcome-based reimbursement pilots:CMS bundled payment models for robotic-assisted joint replacement are aligning vendor incentives with postoperative complication reduction.
Industry Challenges
- Biomedical engineering talent scarcity:Cross-trained specialists capable of integrating mechanical systems with clinical workflows command premium compensation, constraining vendor scaling.
- ISO 13485 certification timelines:Quality management system audits for software-as-medical-device products extend 14-18 months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Medical Automation Market |
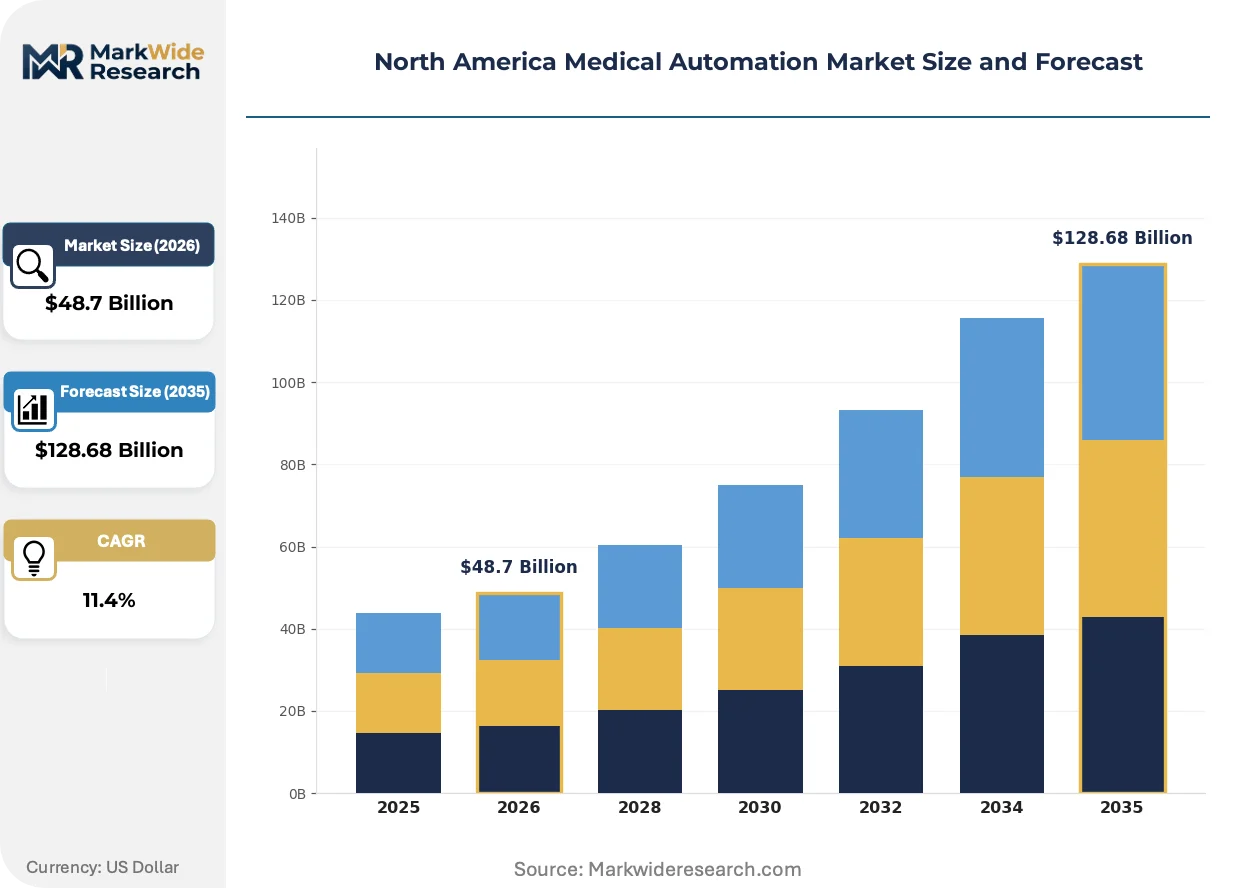
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Surgery, Automated Medication Dispensing, Patient Monitoring Systems, Laboratory Automation End User: Hospitals, Clinics, Research Laboratories, Diagnostic Centers Technology: Artificial Intelligence, Machine Learning, Robotics, Cloud Computing Application: Surgical Automation, Workflow Optimization, Inventory Management, Telehealth Services |
| Companies Covered | Siemens Healthineers, GE Healthcare, Philips Healthcare, Medtronic, Intuitive Surgical, Abbott, Thermo Fisher Scientific, Stryker, Danaher, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Medical Automation Market Evolving Landscape
Adaptive AI architectures are redefining regulatory boundaries and procurement criteria, forcing vendors to engineer continuous learning capabilities within predetermined change control frameworks.
Digital twin simulation is supplanting cadaveric training for robotic surgery credentialing. Academic medical centers in California's health technology corridor are adopting virtual operative environments at triple the rate of traditional wet labs. This shift is compressing surgeon onboarding from eighteen months to six while reducing proctored case requirements.
The FDA's predetermined change control plan guidance for adaptive AI algorithms is forcing vendors to architect locked algorithm update protocols before market entry. Device manufacturers must now validate entire learning trajectories rather than discrete software versions. Radiology automation vendors face the steepest compliance burden as image recognition models require continuous retraining on shifting patient populations.
Hospital procurement departments are consolidating vendor relationships around enterprise-wide automation platforms rather than point solutions. Integrated system contracts spanning imaging, robotics, and asset management are displacing discrete equipment purchases. This concentration is most visible across IDN-affiliated facilities in the US Southeast, where capital committees now mandate interoperability certifications as table stakes.
North America Medical Automation Market Segmentation
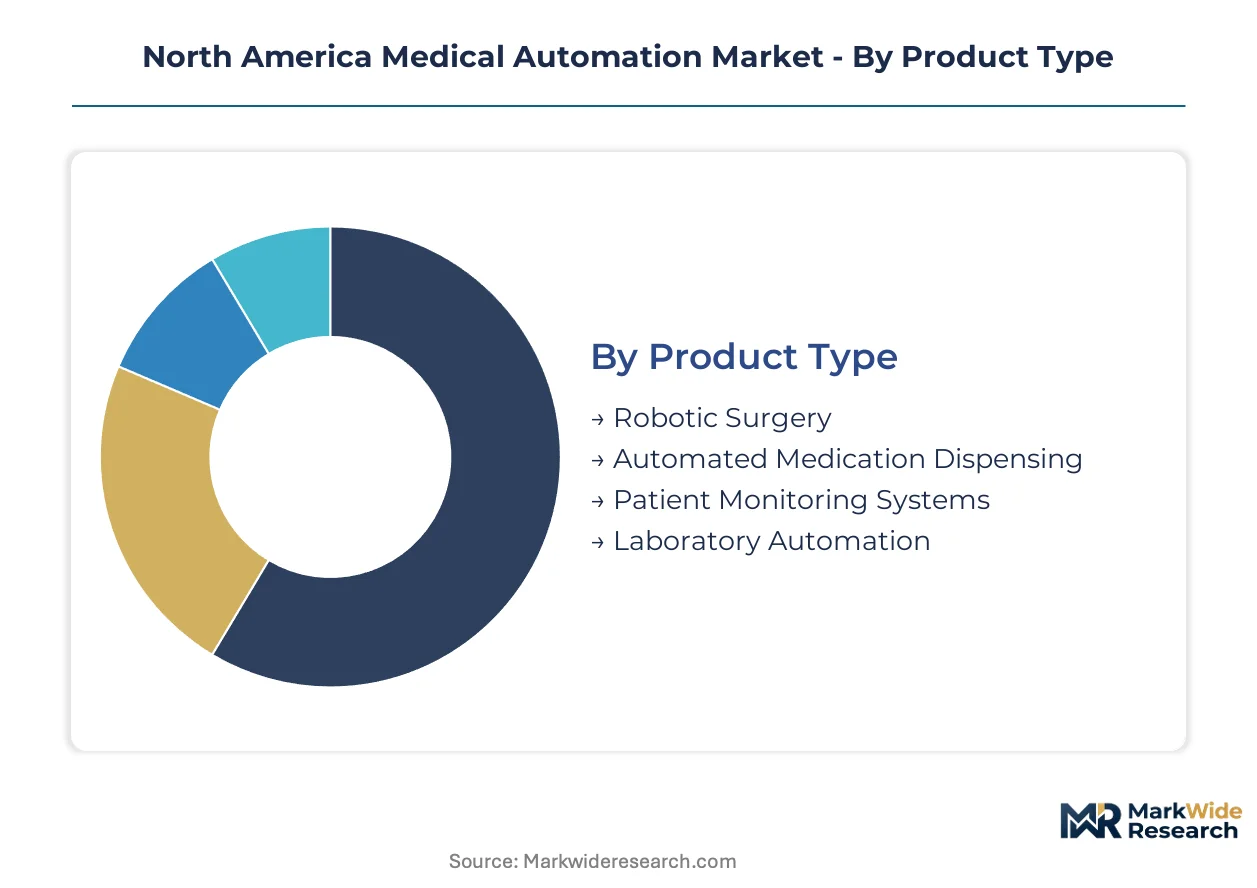
Medical automation procurement decisions fragment across product maturity, reimbursement pathways, and integration complexity. Hospital capital committees evaluate segments through distinct lenses: robotic platforms demand decade-long service commitments, while AI software layers compress replacement cycles to under four years.
Product Type:
Substitute pressure concentrates in medication dispensing and patient monitoring, where software-defined alternatives erode hardware-centric revenue models faster than in surgical robotics.
- Robotic Surgery:Electromechanical platforms with sub-millimeter precision tolerances execute minimally invasive procedures through proprietary instrument ecosystems. Demand clusters at Texas Medical Center and California's academic medical centers, where labor shortages accelerate capital deployment despite seven-figure unit costs.
- Automated Medication Dispensing:Cabinet-based inventory systems with barcode verification and weight-sensing drawers reduce dispensing errors in high-volume hospital pharmacies. Mid-tier health systems in the US Southeast prioritize these units as lower-risk automation entry points compared to surgical robotics.
- Patient Monitoring Systems:Continuous physiologic sensors with predictive analytics for deterioration detection.
- Laboratory Automation:Microfluidic processing systems and robotic sample handling for high-throughput diagnostic workflows.
Robotic Surgery anchors the volume base while Laboratory Automation gains share at the steepest rate.
End User:
Procurement authority concentrates differently across settings—IDN-affiliated hospitals command enterprise-wide contracts while ambulatory sites negotiate discrete equipment purchases.
- Hospitals:Integrated delivery networks with centralized capital committees deploy automation across imaging, surgery, and asset management through multi-year enterprise agreements. California's health technology corridor and Texas Medical Center cluster drive concentrated demand for integrated robotics and AI diagnostics.
- Clinics:Federally qualified health centers and specialty ambulatory sites acquire point solutions for workflow compression without full IT infrastructure.
- Research Laboratories:Academic medical centers and contract research organizations automate high-throughput screening and sample processing.
- Diagnostic Centers:Independent imaging and pathology facilities deploy AI-enabled interpretation tools for throughput expansion.
Hospitals capture the dominant procurement volume while Clinics expand most quickly as same-day surgical automation penetrates ambulatory settings.
Technology:
Margin pools stratify sharply—cloud infrastructure supports thin monetization while robotics hardware locks in decade-long service revenue streams.
- Artificial Intelligence:Adaptive algorithms for diagnostic interpretation and predictive patient deterioration modeling. FDA premarket notification requirements for continuous learning architectures force vendors to validate entire algorithm trajectories before market entry, compressing development timelines for locked-update protocols.
- Machine Learning:Pattern recognition systems trained on retrospective clinical data for workflow optimization and resource allocation.
- Robotics:Electromechanical systems with haptic feedback and autonomous suturing capabilities for microvascular reconstruction.
- Cloud Computing:Distributed infrastructure supporting telehealth services and real-time surgical planning across geographies.
Robotics commands the deepest margin capture while Artificial Intelligence expands most quickly as FDA streamlined pathways accelerate software-as-medical-device commercialization.
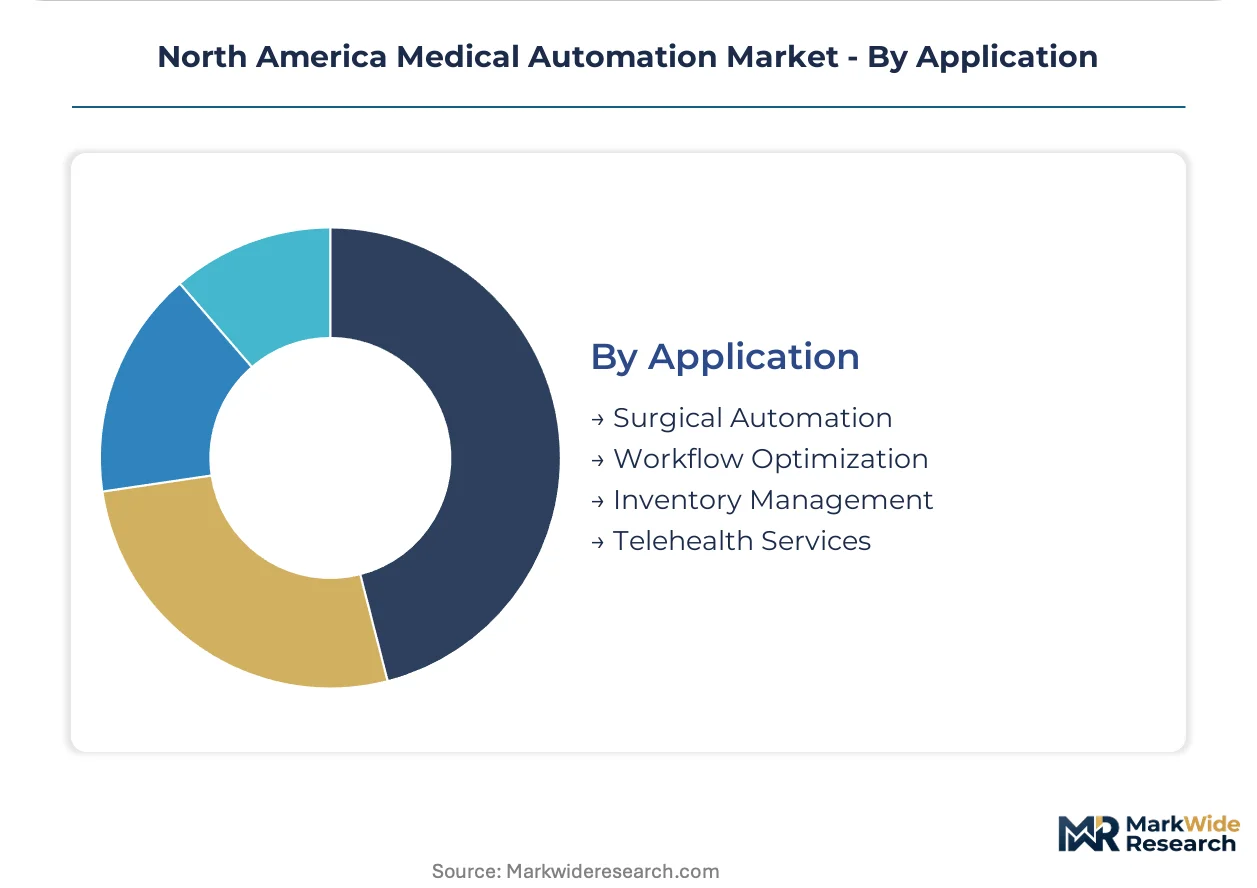
Application:
Reimbursement alignment varies dramatically—CMS bundled payments accelerate surgical automation while operational applications face productivity-proving hurdles.
- Surgical Automation:Robotic-assisted procedures with outcome-based reimbursement pilots for joint replacement and cardiac interventions. CMS bundled payment models align vendor incentives with postoperative complication reduction, accelerating adoption at IDN-affiliated facilities.
- Workflow Optimization:AI-driven scheduling and resource allocation for emergency department throughput and operating room utilization.
- Inventory Management:RFID-enabled supply tracking and predictive restocking for implantable devices and pharmaceuticals.
- Telehealth Services:Remote patient monitoring and virtual consultation platforms supported by cloud-native architectures.
Surgical Automation anchors capital expenditure concentration while Workflow Optimization gains share fastest as labor shortages force operational efficiency investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor manufacturing footprints concentrate in the United States and Germany, with final assembly of surgical robotics platforms anchored in California and Massachusetts while component sourcing spans Mexican maquiladora zones and Canadian precision machining corridors.
United States
FDA 510(k) clearance pathways and CMS reimbursement determinations drive hospital procurement velocity for capital-intensive robotic systems. The Texas Medical Center's 61-member hospital consortium commands concentrated demand for integrated imaging-to-robotics platforms. California's health technology corridor from San Francisco to San Diego anchors AI-enabled diagnostic development clusters.
Canada
Provincial health authority procurement reforms are opening capital windows for same-day robotic procedures at ambulatory surgery centers. Health Canada coordinates cybersecurity frameworks with HHS, tightening interoperability standards for connected medical devices. Ontario's Greater Toronto Area concentrates medical device manufacturing alongside Quebec's precision instrumentation corridor.
Mexico
Maquiladora zones in Baja California and Chihuahua supply precision-machined surgical instrument components under USMCA tariff preferences. COFEPRIS regulatory alignment with FDA standards accelerates cross-border device validation timelines. Monterrey's industrial cluster hosts contract manufacturers serving US-based robotic surgery vendors.
North America Medical Automation Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated imaging-to-robotics vendors commanding premium pricing while point-solution specialists compete on deployment speed. The market structure stratifies across three tiers: diversified conglomerates with enterprise-wide automation platforms, pure-play robotic surgery vendors with proprietary instrument ecosystems, and AI software vendors seeking regulatory pathways for continuous learning algorithms. Dominant competitive moves include strategic partnerships between hardware vendors and cloud infrastructure providers, plus vertical integration into consumable manufacturing to capture recurring revenue streams.
Among diversified health technology conglomerates, Siemens Healthineers and GE Healthcare exemplify the integrated platform archetype, anchoring enterprise-wide contracts that span imaging, robotics, and asset management. Intuitive Surgical occupies a distinct position as a pure-play robotic surgery specialist with locked consumable revenue models. These three companies represent the dominant competitive anchors against which mid-tier vendors and AI software entrants position their offerings.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Philips Healthcare |
| Medtronic |
| Intuitive Surgical |
| Abbott |
| Thermo Fisher Scientific |
| Stryker |
| Danaher |
| Others |
Value Network & Pricing Analysis
Multi-year service contract scale economies at Intuitive Surgical and Siemens Healthineers compress unit economics for mid-tier vendors while establishing price floors that deter speculative entrants. This concentration of installed-base monetization power shapes both upstream component sourcing decisions and downstream procurement negotiations across hospital systems.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure across robotic surgery and AI diagnostics, with ISO 13485-certified platforms commanding three-tier pricing separation between premium integrated systems, standard modular configurations, and economy point solutions. Price differentiation rests on after-sales service bundling and proprietary consumable lock-in rather than hardware performance alone. Cost compression in the mid-tier segment is intensifying because hospital GPOs consolidate vendor relationships around enterprise-wide platforms. Federally qualified health centers exhibit the highest price sensitivity, while IDN-affiliated academic medical centers prioritize interoperability certification over unit cost.
Supply Chain Analysis
Port congestion at Los Angeles-Long Beach and container availability constraints on trans-Pacific lanes are elevating inbound logistics costs for precision-machined surgical components. Manufacturing concentration spans Mexican maquiladora zones in Baja California, German precision engineering corridors, and Chinese rare earth processing facilities for neodymium magnet assemblies. Raw material dependencies include surgical-grade stainless steel, rare earth magnets, and specialized optical sensors. Single-source vulnerability in Chinese rare earth exports creates structural supply risk. Distribution runs through hospital GPO contracts and direct OEM service networks rather than traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through FDA premarket notification pathways creates switching costs that protect incumbent revenue streams.
For Market Incumbents: Shield installed-base monetization by deepening proprietary instrument ecosystems and accelerating ISO 13485 certification investments for AI-enabled software layers. Emerging AI software vendors with streamlined 510(k) pathways threaten consumable-revenue dominance. Capacity addition in Canadian precision machining corridors reduces neodymium supply exposure. For New Entrants and Emerging Players: Differentiate on ambulatory surgery center deployment speed, targeting Canada's underpenetrated provincial health authority procurement reforms for same-day robotic procedures. The most penetrable white space sits in AI-robotics convergence applications for microvascular reconstruction. A direct-to-clinic SaaS pricing model bypasses hospital capital committee approval cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors AI software vendors with locked-update algorithm architectures over hardware-centric robotic platforms. Long-term viability hinges on continuous learning regulatory pathways and CMS reimbursement alignment. Acquisition targets should demonstrate predetermined change control plan compliance. The signal to watch is FDA guidance evolution on adaptive AI iterative submissions versus predetermined change control qualification.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Predetermined Change Control Plan Submission | Locked-update protocols validate entire algorithm trajectories before market entry, compressing development timelines for adaptive AI architectures. |
| Hospital System Enterprise Partnership | IDN-affiliated facilities in the US Southeast mandate interoperability certifications, consolidating procurement around integrated imaging-to-robotics platforms. |
| Canadian Ambulatory Surgery Center Expansion | Provincial health authority reforms open capital windows for same-day robotic procedures outside traditional hospital infrastructure. |
| Software Companion Development for Robotic Platforms | Cloud-native surgical planning extends addressable procedures beyond traditional boundaries through real-time intraoperative guidance. |
| Reimbursement Strategy for CMS Bundled Payments | Outcome-based pilots for robotic-assisted joint replacement align vendor incentives with postoperative complication reduction metrics. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with hospital purchasing committees, biomedical engineers, GPO contracts managers, and FDA regulatory affairs specialists; and secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and Health Canada device licensing data. Bottom-up segmentation modeling triangulated against top-down market sizing across product type, end user, technology, and application dimensions.
Across the analysis window, the forecasting framework modeled volume and value outputs through multi-dimensional segmentation including robotic platform maturity tiers, AI software deployment models, and regional regulatory cluster variations. CAGRs were derived from equipment replacement cycle compression patterns and capital expenditure velocity indicators. Industry-specific inputs incorporated FDA premarket notification approval timelines and CMS reimbursement determination schedules.
Material uncertainties — FDA guidance evolution on adaptive AI algorithms, Chinese rare earth export quota shifts, and CMS bundled payment expansion decisions — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory pathway stability and hospital capital availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Proton and Ion Beam Therapy Dosimetry and QA Test Equipment Market
Medical Equipment
Medical Equipment Leasing Market
Medical Equipment
US Durable Medical Equipment Market
Medical Equipment
Global Operating Table Mattresses Market
Medical Equipment
Urodynamics Equipment and Disposables Market
Medical Equipment
US Medical Carts Market
Medical Equipment
Thermal Cycler Market
Medical Equipment
Patient Lifting Equipment Market
Medical Equipment
Dialysis Equipment Market
Medical Equipment
Global Medical Carts Market
Medical Equipment
Global Indirect Calorimeter Market
Medical Equipment
Asia-Pacific Medical Device Cleaning Market
Medical Equipment
Minor Surgical Lights Market
Medical Equipment
Asia-Pacific Medical Device Reprocessing Market
Medical Equipment
Medical Filter Market
Medical Equipment
Medical Cart Battery Market