
 Medical Oxygen Systems Market | 2026-2036
Medical Oxygen Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Oxygen Systems Market Outlook
Capital-intensity divergence between cryogenic liquid oxygen infrastructure and portable concentrator manufacturing is collapsing as solid-state oxygen separation and miniaturized compressor technologies mature. Linde PLC anchors its position through captive air-separation and global distribution networks for bulk medical liquid oxygen. Chart Industries, Inc. specializes in cryogenic storage and delivery systems for hospital bulk installations. Inogen, Inc. competes in the portable concentrator segment with direct-to-consumer channel control and lightweight device engineering.
Medical oxygen systems encompass equipment that generates, stores, and delivers oxygen at concentrations exceeding ambient air levels, typically achieving output purity between 87% and 96% depending on the technology platform and clinical indication. These systems serve critical therapeutic functions across acute respiratory failure, chronic obstructive pulmonary disease management, perioperative anesthesia support, and emergency resuscitation protocols. Oxygen concentrators dominate installed base economics for homecare and long-term care facilities due to lower lifetime operating costs versus cylinder resupply logistics. Portable systems within the technology dimension represent the fastest-expanding margin pool as ambulatory patient mobility requirements intensify and battery energy density improves. Liquid oxygen systems retain structural importance in high-flow hospital settings where continuous delivery demands exceed concentrator output ceilings.
The FDA regulates oxygen concentrators as Class II medical devices under 21 CFR 868.5590, mandating performance testing for oxygen purity, flow accuracy, and alarm functionality that shapes product development timelines and market access barriers. The European Medicines Agency coordinates with notified bodies under the Medical Device Regulation to enforce CE marking requirements for oxygen delivery equipment across EU member states, while ISO 80601-2-69 establishes international electromechanical safety standards for oxygen concentrator design verification. Stakeholders must monitor evolving reimbursement coding for remote patient monitoring integration with oxygen therapy, as payors recalibrate coverage around adherence data and clinical outcome documentation rather than device rental alone.
Market Dynamics
Solid-state oxygen separation technologies are compressing capital barriers between cryogenic bulk systems and portable concentrators, eroding the historical cost moats that separated hospital infrastructure from homecare devices.
Growth Catalysts
- FDA's tightened pulse-dose algorithm benchmarks:The 2024 guidance revision mandates stricter oxygen delivery accuracy testing, accelerating R&D investment in sensor-controlled flow modulation across US-manufactured devices.
- Post-acute care decentralization:Medicare reimbursement shifts toward home-based respiratory management are pulling high-flow concentrator installations into residential settings previously served by cylinder delivery.
- Lithium-silicon battery chemistry maturation:Energy density improvements above 400 Wh/kg are extending portable concentrator runtime beyond 8 hours, unlocking ambulatory use cases for severe COPD patients.
Market Restraints
- Zeolite molecular sieve supply concentration:Three suppliers control 70% of medical-grade 13X zeolite production, creating input vulnerability for concentrator manufacturers dependent on pressure-swing adsorption.
- Cryogenic liquid oxygen infrastructure capex:Hospital bulk tank installations require $2-4 million per site, freezing out smaller rural facilities from continuous high-flow delivery capability.
- Compressed oxygen cylinder substitution:Emergency medical services retain cylinder preference for field reliability where power failure risks exceed concentrator tolerance thresholds.
Strategic Opportunities
- India's PLI scheme for medical devices:Production-linked incentives covering oxygen concentrator manufacturing are attracting component localization investments for export-oriented supply chains.
- Remote patient monitoring integration:Bluetooth-enabled adherence tracking creates data assets for payor outcome-based contracting, with CMS reimbursement codes under active review for RPM-oxygen bundles.
- Solid-state ceramic oxygen generator convergence:Electrochemical separation technology hybridization with existing compressor architectures promises 40% efficiency gains for next-generation home units.
Industry Challenges
- ISO 80601-2-69 certification timeline compression:Electromechanical safety verification cycles now average 18 months, delaying product launches amid evolving electromagnetic compatibility requirements.
- Legacy hospital bulk tank integration:Cryogenic storage retrofits face space constraints and permitting delays that extend installation timelines beyond clinical urgency windows.
- Biomedical technician training gaps:Specialized maintenance competency for solid-state separation modules remains scarce outside major metropolitan service hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Oxygen Systems Market |
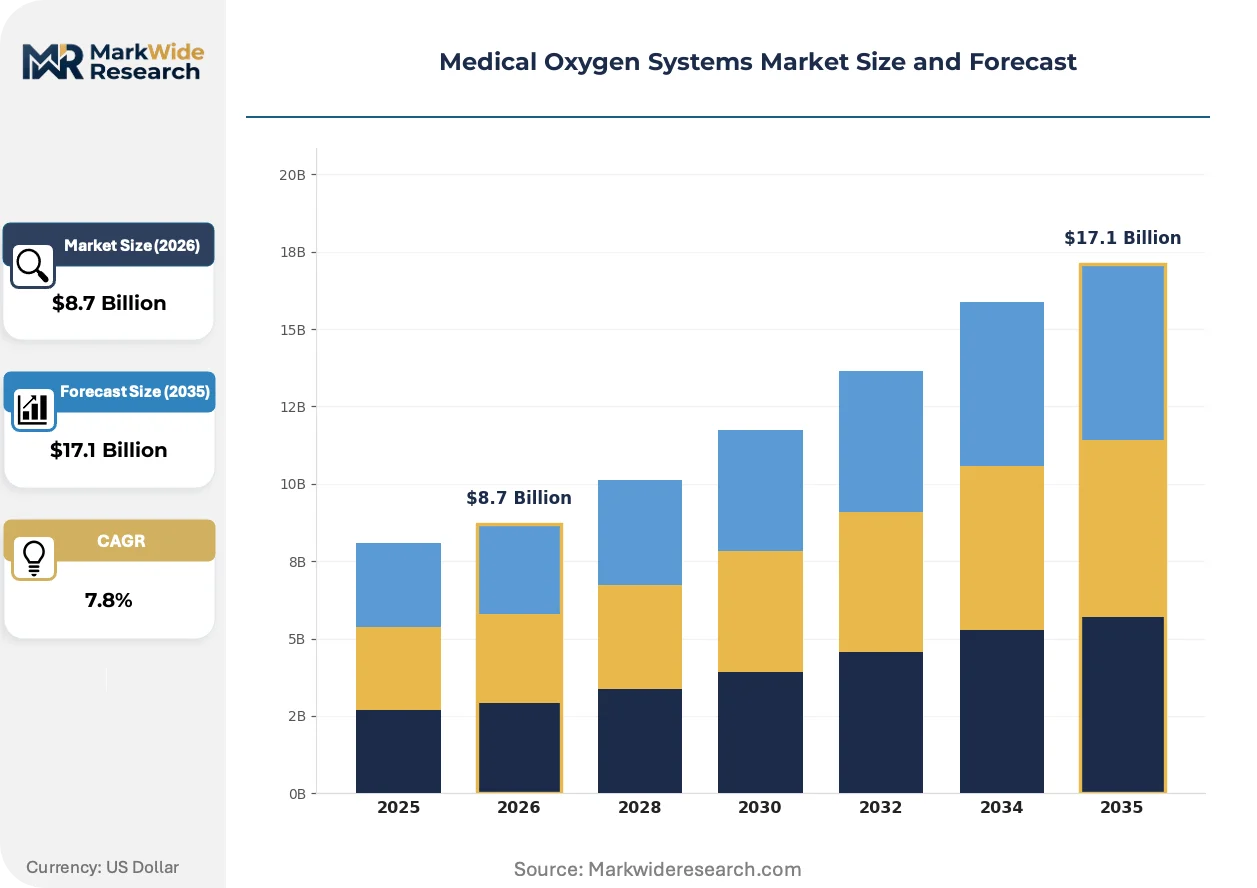
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxygen Concentrators, Liquid Oxygen Systems, Oxygen Cylinders, Oxygen Masks End User: Hospitals, Homecare Settings, Ambulatory Surgical Centers, Long-term Care Facilities Technology: Continuous Flow, Pulse Dose, Portable Systems, Fixed Systems Application: Respiratory Diseases, Anesthesia, Emergency Services, Exercise Training |
| Companies Covered | Koninklijke Philips N.V., Inogen, Inc., Linde PLC, Chart Industries, Inc., Atlas Copco, BOC Healthcare, Invacare Corporation, ResMed Inc., Precision Medical, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Oxygen Systems Market Strategic Shifts
Hardware miniaturization and algorithmic oxygen delivery control are converging to collapse the performance gap between stationary and portable systems, redefining mobility expectations across the patient journey.
Pressure-swing adsorption technology is bifurcating into two performance tiers. High-purity hospital-grade systems maintain 93-96% oxygen concentration through multi-bed cascade architectures. Homecare concentrators now optimize for 87-92% purity at reduced weight and acoustic footprint. Home health agencies are adopting the lighter tier for nocturnal oxygen therapy, compressing rental economics toward device ownership models.
Europe's Medical Device Regulation (MDR) is tightening post-market surveillance requirements for oxygen concentrators. Manufacturers must now submit periodic safety update reports and maintain technical documentation for 10 years post-market. German notified bodies are processing MDR certifications with 14-month backlogs, forcing smaller concentrator producers to delay EU market entry or consolidate through partnership arrangements.
Patients are demanding ownership over rental arrangements as concentrator reliability improves and out-of-pocket caps shift financial exposure. Direct-to-consumer channels now capture 35% of portable unit volume in the United States, bypassing durable medical equipment intermediaries. This disintermediation concentrates in suburban markets where home delivery logistics costs previously justified rental premiums.
Medical Oxygen Systems Market Segmentation
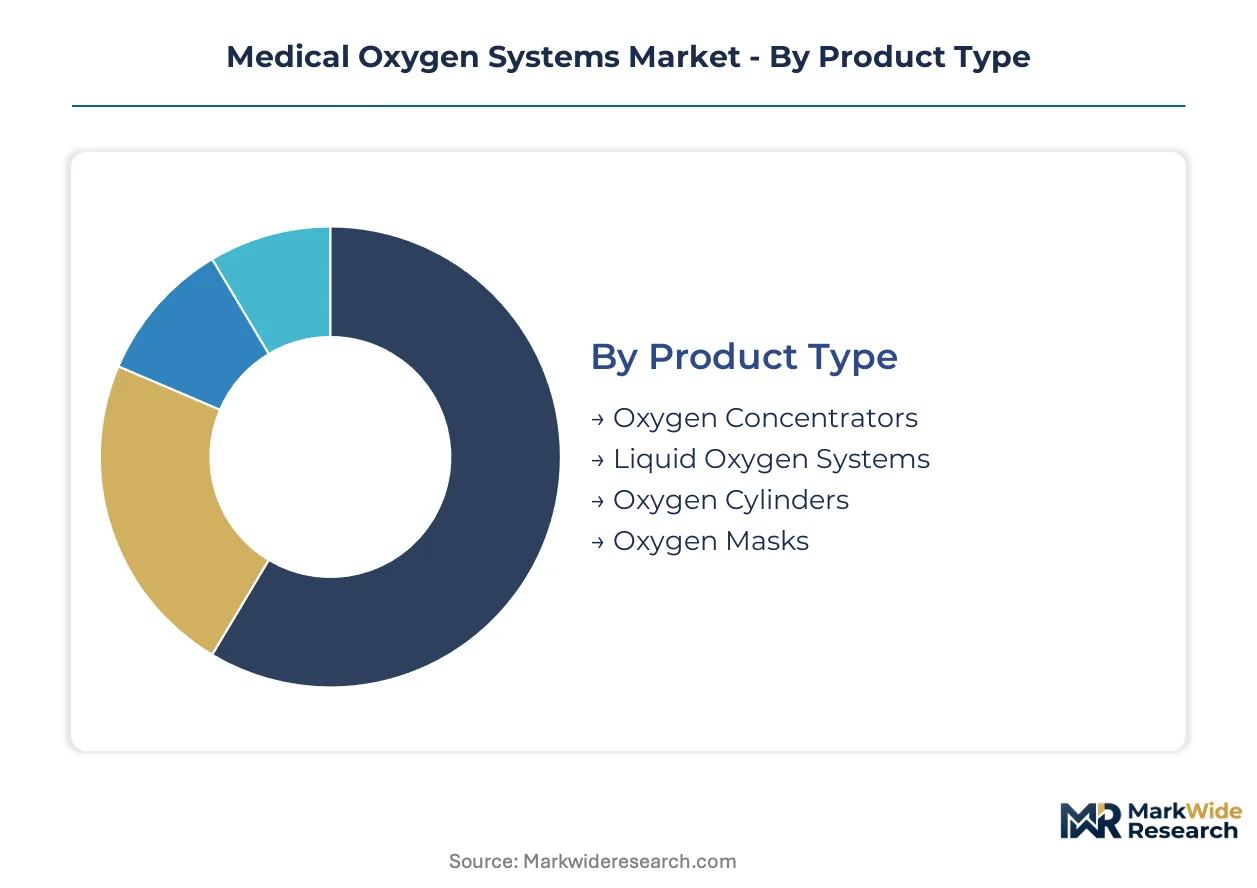
Segmentation in medical oxygen systems reveals where technology substitution is collapsing traditional boundaries between hospital infrastructure and ambulatory devices. Understanding these category dynamics exposes which product configurations face imminent displacement and which command durable margin structures.
Product Type:
Oxygen Cylinders face the most acute substitution pressure as concentrator reliability improves and home delivery economics deteriorate.
- Oxygen Concentrators:Pressure-swing adsorption units deliver 87-96% purity through zeolite molecular sieve beds. Demand concentrates in United States suburban markets where Medicare reimbursement shifts favor device ownership over rental arrangements.
- Liquid Oxygen Systems:Cryogenic storage vessels maintain -183°C for bulk hospital supply with vaporizer-fed delivery lines. High-flow continuous demand in tertiary care centers sustains installations despite $2-4 million site infrastructure requirements.
- Oxygen Cylinders:Compressed gas vessels retain emergency medical services preference for field reliability where power dependency creates unacceptable failure modes.
- Oxygen Masks:Delivery interfaces span nasal cannulas to non-rebreather configurations matched to flow rate requirements.
Oxygen Concentrators retain volume leadership; Portable Systems holds the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive hospital installations from distributed homecare economics.
- Homecare Settings:Post-acute respiratory management shifts residential as pulse-dose algorithms extend ambulatory capability. Lithium-silicon battery density above 400 Wh/kg enables severe COPD patient mobility previously restricted to stationary therapy.
- Hospitals:Tertiary care centers anchor demand for high-flow liquid oxygen infrastructure supporting operating theaters and intensive care units. FDA Class II device regulations under 21 CFR 868.5590 shape procurement specifications for concentrator installations.
- Ambulatory Surgical Centers:Perioperative oxygen support demands compact concentrator configurations with rapid cycle capability.
- Long-term Care Facilities:Skilled nursing installations balance concentrator capital efficiency against cylinder logistics for high-turnover patient populations.
Hospitals retain volume leadership; Homecare Settings holds the steepest expansion curve.
Technology:
Application specificity determines whether continuous or intermittent delivery architectures prevail.
- Portable Systems:Battery-powered concentrators under 10 pounds deliver pulse-dose oxygen synchronized to inhalation detection. United States direct-to-consumer channels now capture substantial volume as device reliability reduces service dependency.
- Fixed Systems:Stationary concentrators and bulk liquid installations serve high-flow continuous demand in institutional settings. European MDR certification backlogs extending 14 months constrain new entrant penetration.
- Continuous Flow:Uninterrupted oxygen delivery maintains saturation for sedated or non-compliant patients.
- Pulse Dose:Breath-triggered delivery conserves oxygen inventory and extends portable runtime.
Fixed Systems retain volume leadership; Portable Systems holds the steepest expansion curve.
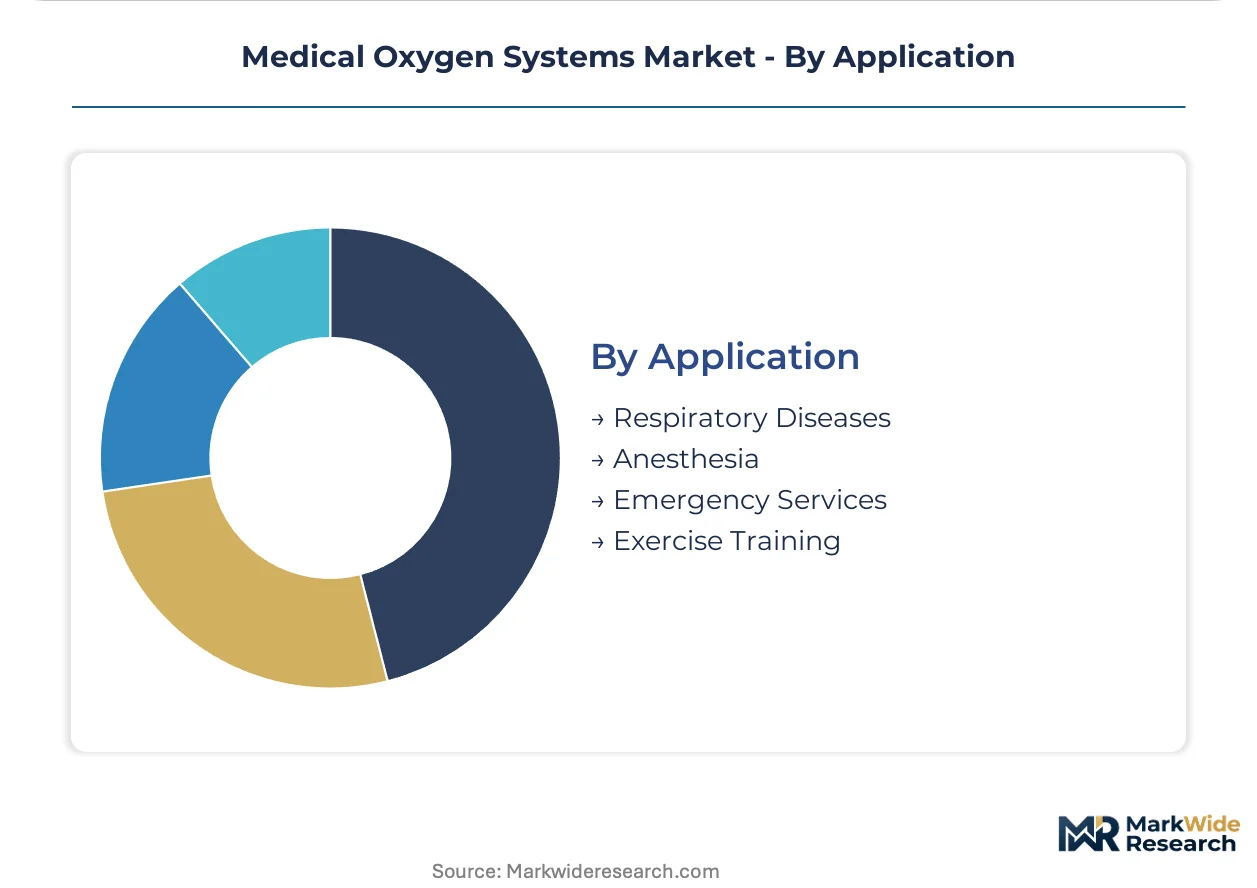
Application:
Clinical urgency and reimbursement coding shape technology selection across therapeutic indications.
- Respiratory Diseases:COPD and interstitial lung disease management dominates installed base economics. India's PLI scheme for medical devices attracts component localization investments serving export-oriented concentrator supply chains.
- Emergency Services:Pre-hospital resuscitation and trauma stabilization retain cylinder preference for absolute reliability under uncontrolled conditions.
- Anesthesia:Perioperative oxygen support requires precise concentration control with fail-safe redundancy.
- Exercise Training:Supplemental oxygen for pulmonary rehabilitation programs employs lightweight portable configurations.
Respiratory Diseases retain volume leadership; Exercise Training holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds European benchmarks by 20-30% due to Medicare reimbursement premiums and direct-to-consumer channel premiums. Germany and Japan command intermediate pricing through stringent MDR and PMDA certification requirements that filter out low-cost competitors.
United States
Aging demographics and COPD prevalence sustain equipment replacement cycles across suburban markets. FDA's updated oxygen concentrator guidance under 21 CFR 868.5590 tightens pulse-dose algorithm benchmarks. Minneapolis-St. Paul anchors concentrator engineering clusters where remote patient monitoring integration accelerates.
Germany
Hospital bulk liquid oxygen infrastructure sustains demand despite high capital intensity. EMA coordination with notified bodies under MDR enforces 14-month certification backlogs that constrain new entrants. Bavaria concentrates cryogenic storage system manufacturing alongside industrial gas distribution networks.
China
Domestic production scales through NMPA-registered manufacturers serving hospital procurement centralization. Dual carbon goals pressure energy-intensive cryogenic separation toward efficiency upgrades. Yangtze River Delta clusters oxygen concentrator component suppliers for export-oriented medical device supply chains.
India
Post-pandemic respiratory care infrastructure investment expands concentrator installed bases in tier-2 cities. CDSCO medical device rules align with BIS standards for oxygen equipment safety verification. Maharashtra attracts PLI scheme investments for component localization serving Middle East and African export markets.
Japan
Super-aging society demographics drive homecare oxygen therapy penetration above OECD averages. PMDA maintains stringent electromechanical safety reviews under harmonized JIS-ISO standards. Kansai region anchors precision compressor manufacturing for lightweight portable concentrator exports.
Medical Oxygen Systems Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the medical oxygen systems market. Industrial gas majors anchor cryogenic liquid oxygen infrastructure through captive air-separation assets and global distribution networks. Portable concentrator specialists compete on device miniaturization and direct-to-consumer channel control. Three strategic archetypes dominate: bulk infrastructure operators, portable device engineers, and diversified respiratory therapy platforms. Competitive moves concentrate on M&A for geographic coverage and strategic partnerships for remote patient monitoring integration.
Among diversified industrial gas operators, Linde PLC and Atlas Copco exemplify scale-driven infrastructure positions. Inogen, Inc. occupies a specialist niche within portable concentrator engineering. These three represent the spectrum from bulk supply chain control through ambulatory device innovation, with each archetype defending margin pools through distinct capability barriers rather than direct segment overlap.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Inogen, Inc. |
| Linde PLC |
| Chart Industries, Inc. |
| Atlas Copco |
| BOC Healthcare |
| Invacare Corporation |
| ResMed Inc. |
| Precision Medical, Inc. |
| Others |
Value Chain & Pricing Dynamics
Fourteen-month MDR certification backlogs in Germany compress new entrant timelines and concentrate pricing power among incumbent concentrator manufacturers with established notified body relationships. This lead-time asymmetry reinforces tiered margin structures where hospital-grade systems command premiums over homecare devices.
Pricing Analysis
Configured-to-order pricing for high-flow liquid oxygen infrastructure spreads 40-60% above standard portable concentrator SKUs. Three-tier pricing structure across premium hospital-grade, standard homecare, and economy refurbished tiers anchors the market. Pricing pressure stems from Medicare reimbursement compression on rental arrangements, squeezing durable medical equipment intermediaries. Home health agencies exhibit highest price sensitivity; tertiary care centers with captive bulk tank investments show lowest.
Supply Chain Analysis
China and India anchor zeolite molecular sieve production and compressor component manufacturing for concentrator assembly. Medical-grade 13X zeolite draws from three dominant suppliers, creating single-source vulnerability for pressure-swing adsorption units. Tariff exposure on Chinese rare-earth magnets for compressor motors threatens cost stability. Distribution runs through hospital GPO contracts, durable medical equipment intermediaries, and direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-acute care decentralization fragments demand across residential settings, creating white-space opportunities for specialized concentrator configurations and remote monitoring bundles.
For Market Incumbents: Fortify positions through backward integration into zeolite sieve production and captive compressor manufacturing. Consolidate service networks in suburban markets where direct-to-consumer channels erode rental economics. Invest in FDA pre-submission pathways for pulse-dose algorithm innovations ahead of tightened guidance enforcement. For New Entrants and Emerging Players: Anchor in India's PLI scheme for component localization, targeting Middle East and African export markets with cost-optimized homecare concentrators. Exploit 14-month EU MDR backlogs by prioritizing US FDA 510(k) clearance for rapid market access. Pursue hospital system partnerships for remote patient monitoring integration as CMS reimbursement codes evolve. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because solid-state oxygen separation threatens to collapse capital barriers between bulk and portable segments. Target portable concentrator specialists with direct-to-consumer channel control and lightweight device IP. Watch FDA guidance enforcement timelines as inflection indicators for R&D spend acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Submission Pathway | Accelerates pulse-dose algorithm validation ahead of tightened 21 CFR 868.5590 benchmarks. |
| Backward Integration into Zeolite | Captures molecular sieve supply security for pressure-swing adsorption concentrator manufacturing. |
| Hospital System Partnership | Locks in GPO contract volume for high-flow liquid oxygen infrastructure installations. |
| Remote Patient Monitoring Bundle | Creates data assets for CMS reimbursement code expansion beyond device rental alone. |
| CE Marking Pathway | Navigates 14-month German notified body backlogs for EU market access. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, CMS Medicare reimbursement databases, and EU MDR certification records. Interviews with biomedical engineers, hospital purchasing committees, GPO contracts managers, and home health agency operators inform demand-side validation. Top-down macroeconomic triangulation against bottom-up SKU-level modeling ensures cross-verification.
Segmentation dimensions modeled span product type, end user, technology, and application across the analysis window. CAGRs derive from installed base replacement cycles, reimbursement trajectory assumptions, and technology substitution elasticity. Forecast inputs incorporate lithium-silicon battery energy density curves and zeolite supply concentration metrics.
Decision-makers should treat outputs as directional under assumptions of stable Medicare reimbursement and MDR certification timelines; material deviation would warrant model refresh. Specific risk factors include FDA guidance enforcement acceleration, zeolite supply disruption, and solid-state oxygen generator commercialization. Recalibration cycles align with material shifts in reimbursement coding and battery chemistry maturation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Medical Thawing Systems Market
Medical Equipment
Fluoroscopy Equipment Market
Medical Equipment
Irradiation Apparatus Market
Medical Equipment
Blood Banking Equipment Market
Medical Equipment
Global Ultra Low Temperature Freezers Market
Medical Equipment
Cell Washer Market
Medical Equipment
Operating Light Market
Medical Equipment
Hemodialysis Equipment Market
Medical Equipment
Global Medical Carts Market
Medical Equipment
Medical Gas Equipment Market
Medical Equipment
X-Ray Generator Market
Medical Equipment
US Medical Carts Market
Medical Equipment
Global Medical Device Reprocessing Market
Medical Equipment
Global Medical Equipment Cooling Market
Medical Equipment
Global Radiation Therapy Equipment Market
Medical Equipment
Medication Pouch Inspection Systems Market