
 US Baghouse Filters Market | 2026-2036
US Baghouse Filters Market Size, Share, and Industry Trends Forecast 2026-2036
US Baghouse Filters Market Intelligence
Smart sensor integration into filter cleaning cycles is fragmenting traditional mechanical-only baghouse architectures into digitally monitored subsystems. Donaldson Company leverages its filtration R&D campus in Minnesota to sustain patent leadership in pulse-jet valve diagnostics. Imperial Systems anchors its position through backward integration into custom ductwork fabrication for metal fabrication shops. AGET Manufacturing Co. competes on turnkey installation speed across Ohio's automotive supplier base.
Baghouse filters are industrial air filtration devices comprising fabric bags supported by metal cages, designed to capture particulate matter from gas streams at temperatures ranging from ambient to 500°F depending on material selection, with pulse-jet cleaning using compressed air blasts to dislodge dust cakes. Their primary purpose is to enable process facilities to meet National Ambient Air Quality Standards while recovering valuable dust byproducts. Pulse jet systems dominate installed capacity owing to continuous-operation design and lower footprint requirements, while PTFE membrane materials command premium positioning due to hydrophobic surface properties that extend filter life in moist chemical processing environments. Dust collection applications absorb the majority of replacement filter demand as aging infrastructure in power generation drives retrofit cycles.
EPA enforcement of Maximum Achievable Control Technology standards under the Clean Air Act shapes product specifications, while OSHA combustible dust directives mandate explosion venting on baghouse units handling aluminum or organic fines. State implementation plans in Texas and California impose stricter opacity limits than federal baselines, forcing end users toward higher-efficiency media upgrades. Stakeholders must weigh capital allocation between incremental media improvements and full system replacements as digital monitoring capabilities redefine total cost of ownership calculations.
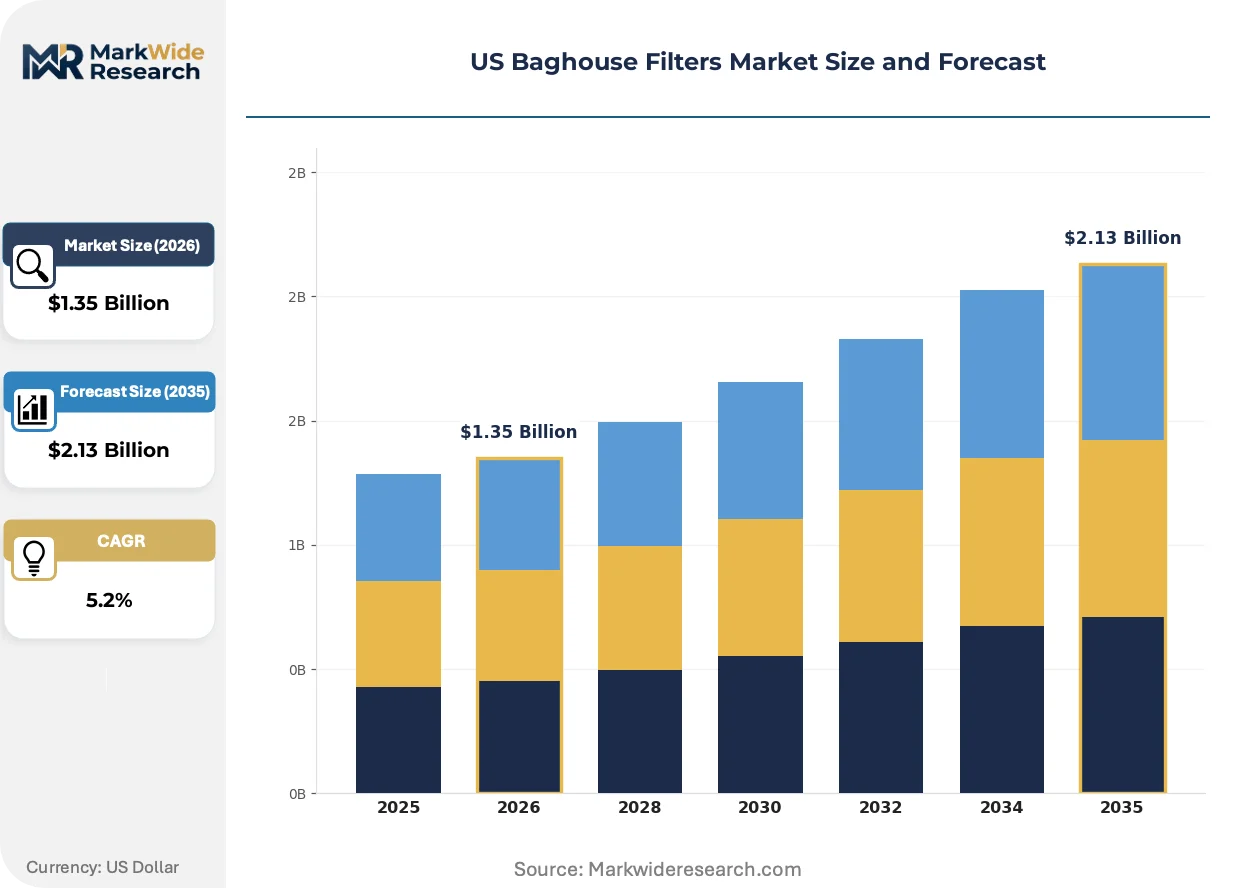
Market Dynamics
EPA Mercury and Air Toxics Standards are compressing particulate emission limits, forcing cement and steel facilities across the Midwest and Southeast into accelerated baghouse retrofit cycles. PTFE membrane materials are capturing premium positioning as facilities confront hydrophobic performance requirements in moist chemical processing environments.
Growth Catalysts
- MATS Compliance Deadlines:Cement kilns and secondary steel producers face EPA enforcement actions that mandate baghouse upgrades or replacement. Facilities in Ohio and Texas are prioritizing pulse-jet system installations to meet opacity limits.
- Petrochemical Cluster Expansion:Gulf Coast ethylene crackers and derivatives plants are adding filtration capacity as state implementation plans in Texas impose stricter baseline requirements than federal standards.
- Smart Sensor Integration:Digital pressure-drop monitoring and predictive cleaning algorithms are reducing compressed air consumption. Metal fabrication shops in the Midwest are retrofitting mechanical-only systems with IoT-enabled diagnostics.
Market Restraints
- PTFE Raw Material Concentration:Fluoropolymer resin supply concentrates among a limited producer base, exposing filter manufacturers to input cost volatility and allocation constraints during chemical sector demand spikes.
- Skilled Installation Labor Scarcity:Turnkey baghouse deployment requires certified welders and pneumatic technicians. The tight construction labor market in California and Texas extends project timelines.
- Long Asset Replacement Cycles:Steel-cage and housing structures operate for 15-20 years, compressing demand for full system replacements into episodic retrofit windows rather than continuous refresh patterns.
Strategic Opportunities
- OSHA Combustible Dust Enforcement:Aluminum smelters and organic powder processors must install explosion venting and suppression systems. This creates aftermarket attachment sales for safety-integrated baghouse configurations.
- Filter Media Upgrade Pathways:Aging polyester felt installations in legacy power generation represent a white space for PTFE membrane retrofits without full system replacement.
- Regional Service Network Density:Filter replacement demand concentrates in Ohio's automotive supplier corridor. Captive service contracts with predictive shipping algorithms can capture recurring revenue streams.
Industry Challenges
- Integration Complexity with Legacy Ductwork:Existing ventilation infrastructure in 1970s-era cement plants requires custom fabrication. Imperial Systems and regional metalworkers compete on measurement precision and field modification speed.
- Certification Timeline Compression:EPA Method 5 and Method 17 stack testing for compliance demonstration demands coordination with third-party auditors. Delays in test scheduling push facility startup dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Baghouse Filters Market |
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pulse Jet, Reverse Air, Shaker, Envelope Material: Fiberglass, Polyester, Nomex, PTFE Membrane, Cellulose End User Industry: Power Generation, Cement Manufacturing, Metal Fabrication, Chemical Processing, Pulp & Paper Application: Dust Collection, Fume Extraction, Pollution Control, Industrial Ventilation |
| Companies Covered | Amerair Industries LLC, Baghouse America Inc., Donaldson Company, Inc., Imperial Systems, Inc., Griffin Filters LLC, AGET Manufacturing Co., CECO Environmental Corp., Aircon Corp., Airex Industries Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Baghouse Filters Market Strategic Shifts & Innovations
Digital monitoring architectures are fragmenting traditional mechanical-only baghouse designs into sensor-rich subsystems. Three interconnected developments are reshaping competitive positioning and procurement patterns across the US market.
PTFE membrane filter media is migrating from conventional needle-punched felts in high-temperature applications above 400°F. Cement manufacturers in the Southeast are adopting membrane laminates at accelerated pace to handle alkali and moisture exposure in kiln exhaust streams. This technology compression is extending filter replacement intervals from 18 months to 36 months, reducing total consumables spend.
EPA enforcement of Maximum Achievable Control Technology standards under the Clean Air Act is tightening opacity limits for secondary aluminum smelters. Facilities must demonstrate continuous compliance through bag leak detection systems or face penalty actions. The Great Lakes metal casting corridor is responding with integrated pressure-drop trending and automated maintenance scheduling.
Aftermarket procurement is consolidating around predictive filter replacement contracts rather than spot purchasing. Large petrochemical operators in Texas are unbundling media supply from installation services, forcing traditional turnkey vendors into component-only pricing. This channel disintermediation is most visible among integrated steel producers seeking direct relationships with PTFE membrane converters.
US Baghouse Filters Market Segmentation
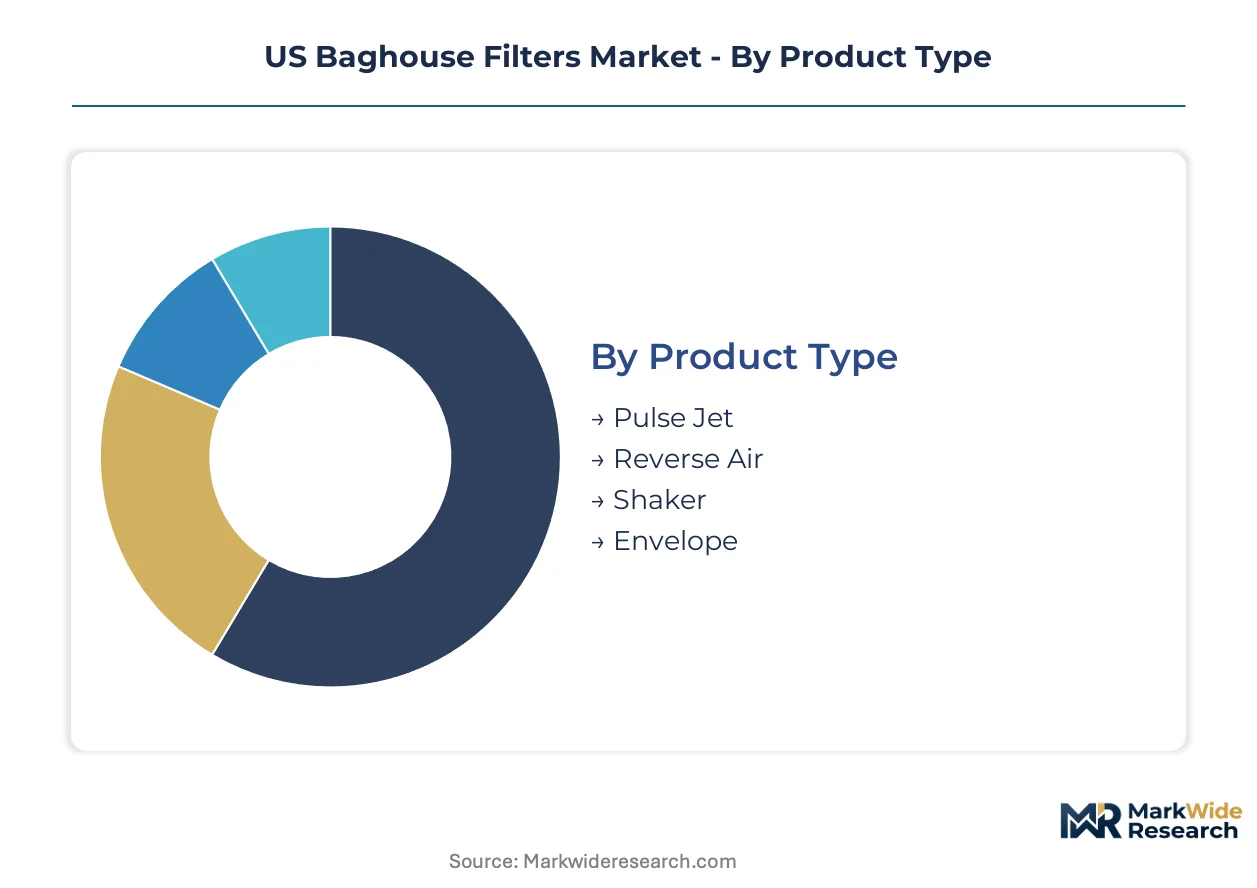
Baghouse filter procurement patterns vary sharply across product architectures, material specifications, and end-use intensities. Understanding these segment boundaries reveals where replacement cycles concentrate and where specification upgrades unlock margin expansion for component suppliers.
Product Type:
After-sales service intensity diverges dramatically across cleaning mechanism designs, with continuous-duty systems demanding predictive maintenance contracts and intermittent designs relying on break-fix relationships.
- Pulse Jet:Compressed air blasts dislodge dust cakes through high-velocity pulses without process interruption. Cement manufacturers across the Midwest and Southeast specify pulse-jet architectures to maintain continuous kiln operations under EPA Mercury and Air Toxics Standards enforcement.
- Reverse Air:Gentle airflow reversal cleans filter media through low-pressure fans, preserving delicate bag fabrics in high-temperature chemical processing. Texas petrochemical clusters favor reverse-air systems for handling abrasive catalyst fines without mechanical stress fractures.
- Shaker:Mechanical vibration dislodges particulate through motor-driven oscillation, suited for intermittent batch operations with lower capital budgets. Metal fabrication shops in Ohio's automotive supplier corridor deploy shaker units for welding fume capture on single-shift schedules.
- Envelope:Flat filter elements replace cylindrical bags in space-constrained retrofits, offering higher surface area per unit volume. Legacy power generation facilities in the Southeast specify envelope configurations to avoid structural modifications to existing ductwork.
Pulse Jet holds the largest share; momentum sits with Envelope configurations as retrofit constraints intensify.
Material:
Cost tier stratification separates commodity felts from membrane laminates, with price multiples of 3-5x between base polyester and PTFE constructions reshaping procurement committee dynamics.
- PTFE Membrane:Hydrophobic microporous surface layers laminated onto substrate felts block liquid penetration while maintaining gas permeability. Gulf Coast chemical processors specify PTFE membranes to handle moist acid gas streams without hydrolysis degradation.
- Fiberglass:Woven glass fiber constructions withstand sustained temperatures above 500°F in cement kiln exhaust applications. Facilities in California's Central Valley deploy fiberglass bags to meet South Coast Air Quality Management District opacity mandates.
- Polyester:Standard needle-punched felts serve ambient-temperature dust collection in woodworking and grain handling operations. Bulk commodity pricing makes polyester the default specification for budget-constrained metal fabrication shops.
- Nomex:Aramid fiber media resist thermal degradation in asphalt production and foundry operations. Ohio's secondary aluminum smelters specify Nomex for fume extraction at 350-400°F operating temperatures.
- Cellulose:Paper-based filter media capture fine particulate in low-temperature, low-moisture environments. Pulp and paper mills in the Pacific Northwest utilize cellulose for wood dust recovery with in-house media regeneration capabilities.
Polyester dominates installed volume; PTFE Membrane is climbing the fastest as hydrophobic performance requirements harden.
End User Industry:
Customer type segmentation separates process-integrated buyers seeking turnkey solutions from maintenance departments managing replacement filter procurement through MRO catalogs.
- Cement Manufacturing:Kiln exhaust filtration demands continuous-operation baghouses with alkali-resistant media. EPA enforcement of Maximum Achievable Control Technology standards drives upgrade cycles across Midwest and Southeast production facilities.
- Power Generation:Aging coal and biomass plants require retrofit filtration to meet National Ambient Air Quality Standards. Legacy installations represent the largest addressable base for media upgrade campaigns without full system replacement.
- Chemical Processing:Acid gas and solvent-laden streams necessitate corrosion-resistant housing materials and specialized membrane media. Texas and Louisiana petrochemical corridors concentrate demand for PTFE-specified systems.
- Metal Fabrication:Welding fume and grinding dust collection operates at smaller scale with higher unit count. Ohio's automotive supplier base generates recurring filter replacement demand through captive service contracts.
- Pulp & Paper:Wood dust recovery and lime kiln exhaust applications balance temperature resistance with cost sensitivity. Pacific Northwest mills prioritize in-house maintenance capabilities over vendor-managed service agreements.
Power Generation holds the largest share; Cement Manufacturing is expanding most quickly under MATS compliance pressure.
Application:
Volume concentration in dust collection versus specialized extraction systems determines whether procurement flows through OEM channel partners or direct mill supply relationships.
- Dust Collection:Particulate recovery from crushing, grinding, and conveying operations represents the foundational baghouse application. Cement and mining operations generate the majority of replacement filter demand through 18-36 month media refresh cycles.
- Pollution Control:Stack emission compliance systems integrate continuous monitoring with automated cleaning controls. EPA Method 5 and Method 17 testing requirements shape specification decisions for secondary steel and aluminum producers.
- Fume Extraction:Capture of volatile organic compounds and metal oxide vapors demands specialized hooding and ductwork integration. California metal fabrication shops face South Coast AQMD mandates for hexavalent chromium capture.
- Industrial Ventilation:General air quality maintenance in production facilities operates at lower differential pressure with extended filter life. Replacement cycles stretch to 48-60 months, compressing aftermarket revenue predictability.
Dust Collection commands the largest share; Pollution Control is gaining share fastest as opacity limits tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas petrochemical complexes supply PTFE membrane filters to Gulf Coast refineries under state implementation plans stricter than federal baselines. California cement manufacturers import fiberglass bag specifications from Nevada suppliers to meet South Coast Air Quality Management District opacity mandates.
Texas
Gulf Coast ethylene crackers drive pulse-jet system demand as the Texas Commission on Environmental Quality enforces opacity limits below federal thresholds. Houston-area petrochemical clusters specify PTFE membranes for moist acid gas streams in derivatives production.
California
Cement kiln operators in the Central Valley deploy fiberglass baghouses to satisfy South Coast AQMD particulate mandates. Los Angeles Basin metal fabricators retrofit shaker systems with smart pressure-drop monitoring for hexavalent chromium capture compliance.
Ohio
Secondary aluminum smelters in the Great Lakes corridor face EPA Maximum Achievable Control Technology enforcement for fume extraction systems. Cleveland-area automotive suppliers generate recurring Nomex filter demand through captive service contracts with predictive shipping algorithms.
Southeast
Carolina cement manufacturers accelerate baghouse retrofits as EPA Mercury and Air Toxics Standards compress emission limits for kiln exhaust. Georgia power generation facilities represent the largest addressable base for polyester-to-PTFE media upgrades without full system replacement.
Midwest
Illinois and Indiana steel producers install explosion-vented baghouses under OSHA combustible dust directives for aluminum fines handling. Chicago-area metal fabrication shops deploy envelope configurations in space-constrained welding fume retrofits.
US Baghouse Filters Market Key Industry Players
On the supply side, the industry is fragmented across turnkey system integrators, component specialists, and regional fabrication shops. Three archetypes dominate: filtration technology developers with captive R&D infrastructure, backward-integrated metalworkers controlling ductwork fabrication, and speed-focused installers serving automotive supplier corridors. Consolidation pressure operates through strategic partnerships for predictive maintenance software and geographic expansion into service network density.
Among Midwest-based filtration developers, Donaldson Company exemplifies the technology-led archetype through its Minnesota R&D campus. Imperial Systems occupies a position within the integrated metalworking tier, while AGET Manufacturing Co. represents the installation-speed specialist segment serving Ohio's automotive base.
| Leading Market Players |
|---|
| Amerair Industries LLC |
| Baghouse America Inc. |
| Donaldson Company, Inc. |
| Imperial Systems, Inc. |
| Griffin Filters LLC |
| AGET Manufacturing Co. |
| CECO Environmental Corp. |
| Aircon Corp. |
| Airex Industries Inc. |
| Others |
Cost & Logistics Intelligence
Gulf Coast petrochemical freight corridors linking Houston to Port Arthur concentrate PTFE resin inbound logistics costs, compressing margin structures for membrane filter converters while amplifying price differentiation between commodity felt suppliers and premium laminate specialists serving Texas refineries under TCEQ opacity mandates.
Pricing Analysis
Mechanical-only baghouse architectures trade at 40-60% discounts to IoT-enabled pulse-jet systems with integrated pressure-drop monitoring. Three-tier pricing structure across premium PTFE membrane, standard fiberglass, and economy polyester levels reflects certification grade differentiation and after-sales service bundling. Cost compression in commodity felt tiers is intensifying because automotive supplier procurement committees in Ohio prioritize unit cost over replacement interval optimization. Metal fabrication shops exhibit highest price sensitivity; petrochemical operators demonstrate lowest sensitivity due to compliance failure penalties.
Supply Chain Analysis
Tariff exposure between China and the United States dominates fluoropolymer resin procurement risk for domestic filter manufacturers. PTFE raw material supply concentrates in China, Japan, and the United States; woven fiberglass substrates draw from Mexico and Canada under USMCA preferential terms. Single-source vulnerability concentrates in fluoropolymer resin allocation during chemical sector demand spikes. Distribution runs through OEM channel partners for turnkey system sales and direct mill supply relationships for replacement filter procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Mercury and Air Toxics Standards enforcement is compressing replacement cycles into a high-growth disruption window as cement and steel facilities face accelerated retrofit deadlines without alternative compliance pathways.
For Market Incumbents: Insulate margin position through captive PTFE membrane conversion capacity and predictive maintenance software acquisitions. Threat from digitally native filtration startups with IoT-first architectures demands defensive patent filings in pulse-jet valve diagnostics. Backward integration into custom ductwork fabrication secures installation speed advantages in Ohio's automotive supplier corridor.
For New Entrants and Emerging Players: Aging polyester felt installations in legacy power generation represent the most penetrable entry point for PTFE membrane retrofit specialists without full system replacement capability. Secondary aluminum smelters in the Great Lakes corridor under EPA Maximum Achievable Control Technology enforcement offer concentrated demand for explosion-vented baghouse configurations. Channel partnership with regional metal fabrication shops accelerates field credibility establishment.
For Investors and Strategic Acquirers: Regional service network operators with predictive shipping algorithms and captive Nomex filter contracts anchor acquisition target archetypes for recurring revenue exposure. Long-term viability frames around digital monitoring adoption curves and regulatory enforcement continuity rather than commodity replacement cycles. Signal to watch is OSHA combustible dust directive expansion beyond aluminum into organic powder processing verticals.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Software Acquisition | Captures recurring service revenue from EPA Method 5 compliance monitoring requirements. |
| PTFE Membrane Conversion Capacity Expansion | Reduces fluoropolymer resin allocation risk from limited producer base concentration. |
| Regional Service Network Density Buildout | Secures filter replacement demand in Ohio's automotive supplier corridor through captive contracts. |
| Explosion Venting Safety Integration | Addresses OSHA combustible dust mandates for aluminum smelters and organic powder processors. |
| Envelope Configuration Product Line Extension | Captures space-constrained retrofit demand in 1970s-era cement plants without structural modifications. |
Research Approach
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this analysis. Primary interview data combined with EPA enforcement records, state implementation plan filings, customs trade data, and SEC 10-K disclosures from filtration technology developers. Bottom-up unit economics across pulse-jet, reverse-air, shaker, and envelope configurations triangulated against top-down market sizing from end-use industry capital expenditure patterns.
Scenario-bracketing around MATS compliance deadline phasing and petrochemical cluster expansion timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include cleaning mechanism architecture, filter media material specification, end-use industry intensity, and application type. CAGRs derived from replacement cycle compression rates and specification upgrade penetration curves. Forecast inputs incorporated skilled installation labor availability constraints in California and Texas construction markets.
Macroeconomic conditions sit as an overlay; deviation in industrial construction spending and fluoropolymer resin pricing volatility would shift the trajectory. Forecasts reflect documented assumptions regarding EPA enforcement continuity and state-level opacity limit tightening. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Industrial Air Filtration Market
Filters
Hydraulic Filters Market
Filters
Filtering Centrifuges Market
Filters
Residential Filters Market
Filters
String Wound Filter Materials Market
Filters
Global Tangential Flow Filtration Market
Filters
Compact Filters Market
Filters
Anti-Microbial Filter Market
Filters
Industrial Filtration Market
Filters
Chloramine Filter Market
Filters
Aerospace Filter Market
Filters
Nonwoven Air Conditioning Filter Market
Filters
Filter Media Market
Filters
Fabric Filter System Market
Filters
Filter Bag Market
Filters
Color Filter Glass Market