
 Europe Metal Casting Market | 2026-2036
Europe Metal Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Metal Casting Market Intelligence
Maintenance contracts for die-casting tooling and predictive furnace monitoring is restructuring how European foundries monetize long-term customer relationships. Georg Fischer AG leverages its Swiss-German service network to anchor aftermarket revenue streams across Central European automotive supply chains. Thyssenkrupp competes through integrated steel-to-casting verticality, while Cirex specializes in precision investment casting for aerospace turbine blades from its Netherlands operations.
Metal casting encompasses the pouring of molten ferrous or non-ferrous alloys into refractory molds to produce near-net-shape components with tolerances typically ranging from IT9 to IT14 depending on process control. The technique serves as the backbone of industrial manufacturing, delivering structural integrity for power transmission, fluid handling, and load-bearing assemblies where machining from solid would waste material and extend lead times. Sand casting retains the largest volume share across European foundries due to its flexibility with iron and steel alloys for industrial machinery and construction equipment, though die casting captures disproportionate margin pools from thin-wall aluminum automotive housings requiring dimensional repeatability below 0.1 millimeters. Investment casting occupies a premium niche in aerospace superalloy components where ceramic shell precision justifies higher unit economics.
EMA chemical safety assessments under REACH restrict certain binder formulations in sand casting, while the EU Green Deal carbon border mechanism shapes sourcing decisions for imported pig iron and scrap alloys. CE marking under the Machinery Directive governs casting integration into finished industrial equipment sold across the single market. Stakeholders must monitor how the F-Gas Regulation phase-down alters die-casting cell cooling systems and whether national transpositions of the EU AI Act create compliance thresholds for automated defect detection in foundry quality control.
Market Dynamics
Automotive OEM procurement of lightweight aluminum powertrain housings is restructuring European foundry capacity allocation, with Tier-1 suppliers anchoring precision die-casting investments in Germany's Baden-Württemberg and Bavaria clusters to serve electric vehicle platform demand.
Growth Catalysts
- EU Green Deal carbon border adjustments:Foundries in Germany, Italy, and France are accelerating electric melting furnace deployments to reduce Scope 1 emissions and avoid import tariffs on carbon-intensive pig iron.
- REACH compliance mandates:EMA chemical safety assessments are phasing out certain phenolic binder formulations in sand casting, creating replacement demand for inert gas filtration and water-based binder systems.
- Aluminum powertrain housing demand:Automotive OEMs are expanding thin-wall die-casting specifications for electric motor housings requiring dimensional repeatability below 0.1 millimeters.
Market Restraints
- Scrap alloy price volatility:Secondary aluminum and copper scrap input costs fluctuate with London Metal Exchange pricing, compressing margin predictability for independent foundries without long-term supply agreements.
- F-Gas Regulation phase-down:The EU-mandated reduction in hydrofluorocarbon refrigerants is forcing die-casting cell cooling system retrofits, adding unplanned capital burdens to mid-cap operators.
- Ceramic shell investment casting limitations:Aerospace superalloy component production remains constrained by furnace capacity and skilled technician availability in the Netherlands and Switzerland.
Strategic Opportunities
- Poland and Czech Republic industrial zones:Underpenetrated precision casting capacity in Central European manufacturing corridors offers greenfield sites for serving German automotive supply chains with lower labor cost structures.
- Predictive furnace monitoring:Machine learning-enabled thermal analytics are converging with legacy induction melting equipment to enable outcome-based maintenance contracts and reduce unplanned downtime.
- EU AI Act automated defect detection:National transpositions of the regulation are creating compliance-driven demand for computer vision systems in foundry quality control, favoring early technology adopters.
Industry Challenges
- Tooling engineer scarcity:Die-casting mold design and maintenance expertise is concentrating among aging workforces in Stuttgart and Turin industrial clusters, constraining capacity expansion timelines.
- CE marking integration complexity:Casting suppliers must synchronize Machinery Directive certification timelines with downstream industrial equipment OEMs, extending order-to-delivery cycles for construction and power transmission applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Metal Casting Market |
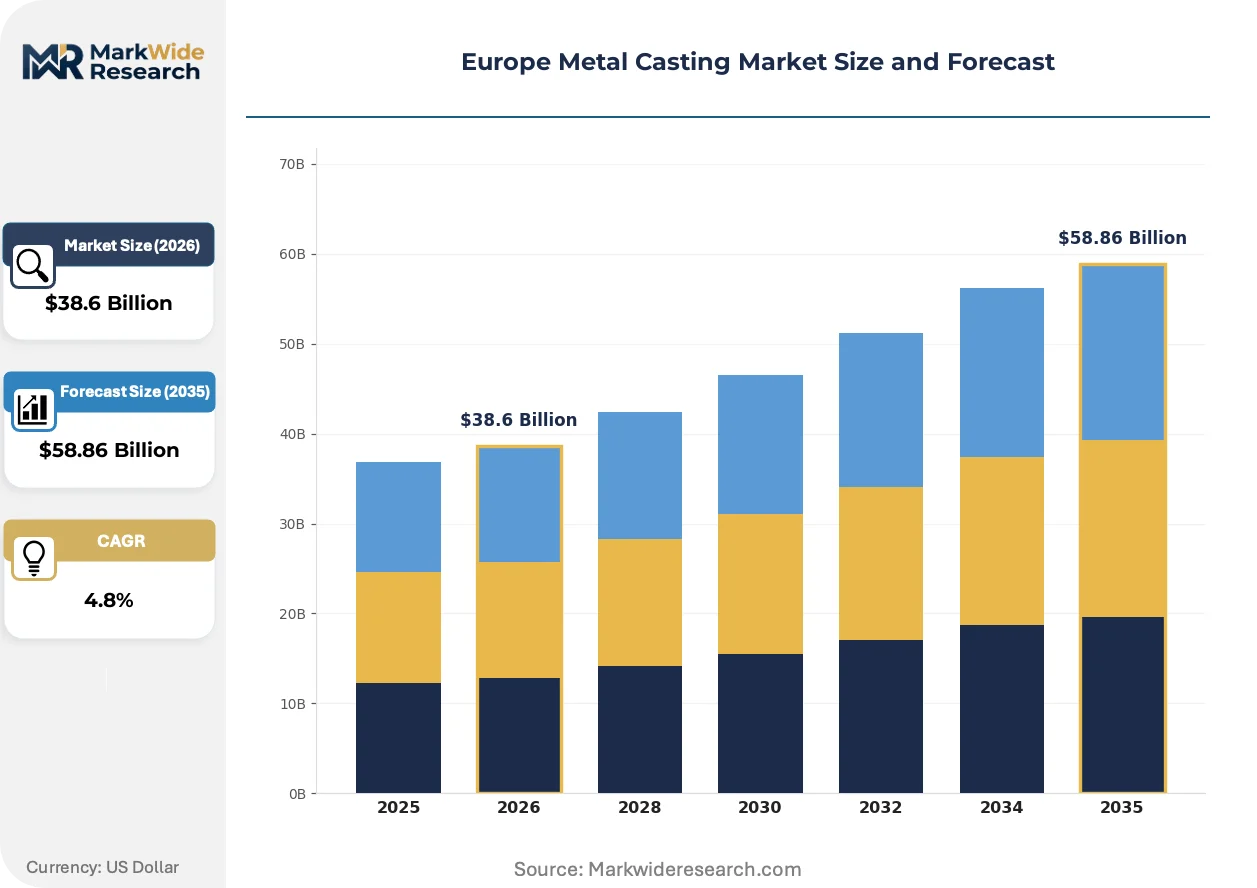
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.86 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sand Casting, Investment Casting, Die Casting, Permanent Mold Casting Application: Automotive Components, Aerospace Parts, Industrial Machinery, Consumer Goods Material: Aluminum, Iron, Steel, Copper End User: OEMs, Aftermarket Providers, Construction, Electrical Appliances |
| Companies Covered | Thyssenkrupp, Cirex, ArcelorMittal SA, FONDERIA AUGUSTA Srl, Novacast Ltd, Alcoa Corp, Zollern, Lucchini RS SpA, Georg Fischer AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Metal Casting Market Strategic Shifts & Innovations
Digitalization of furnace operations and regulatory pressure on carbon intensity are converging to reshape how European foundries monetize long-term customer relationships through predictive service models rather than transactional component supply.
Inert gas filtration technology is integrating into sand casting binder systems to replace phenolic resin formulations restricted under REACH. German and Italian foundries serving construction equipment OEMs are adopting these systems at accelerated pace to maintain automotive-adjacent certification status. The technology is integrating emissions compliance directly into production economics, compressing the cost gap between traditional and green binder chemistries.
REACH chemical safety assessments are expanding scope to cover silica dust exposure in fettling and finishing operations. Foundries across France, Spain, and Belgium are retrofitting automated grinding cells and vacuum extraction systems to preempt stricter occupational exposure limits. Investment casting specialists in the Netherlands face the steepest compliance timelines due to superalloy work-hardening properties that extend manual finishing requirements.
Automotive OEMs are consolidating supplier panels for aluminum powertrain housings around foundries with integrated machining and assembly capabilities. Tier-1 procurement teams in Baden-Württemberg are awarding multi-year platform contracts to vertically capable suppliers, displacing pure-play casting houses from electric vehicle supply chains. This concentration is most visible in Bavaria, where BMW and Siemens Energy procurement specifications now mandate in-house CNC finishing and leak-testing capacity.
Europe Metal Casting Market Segmentation
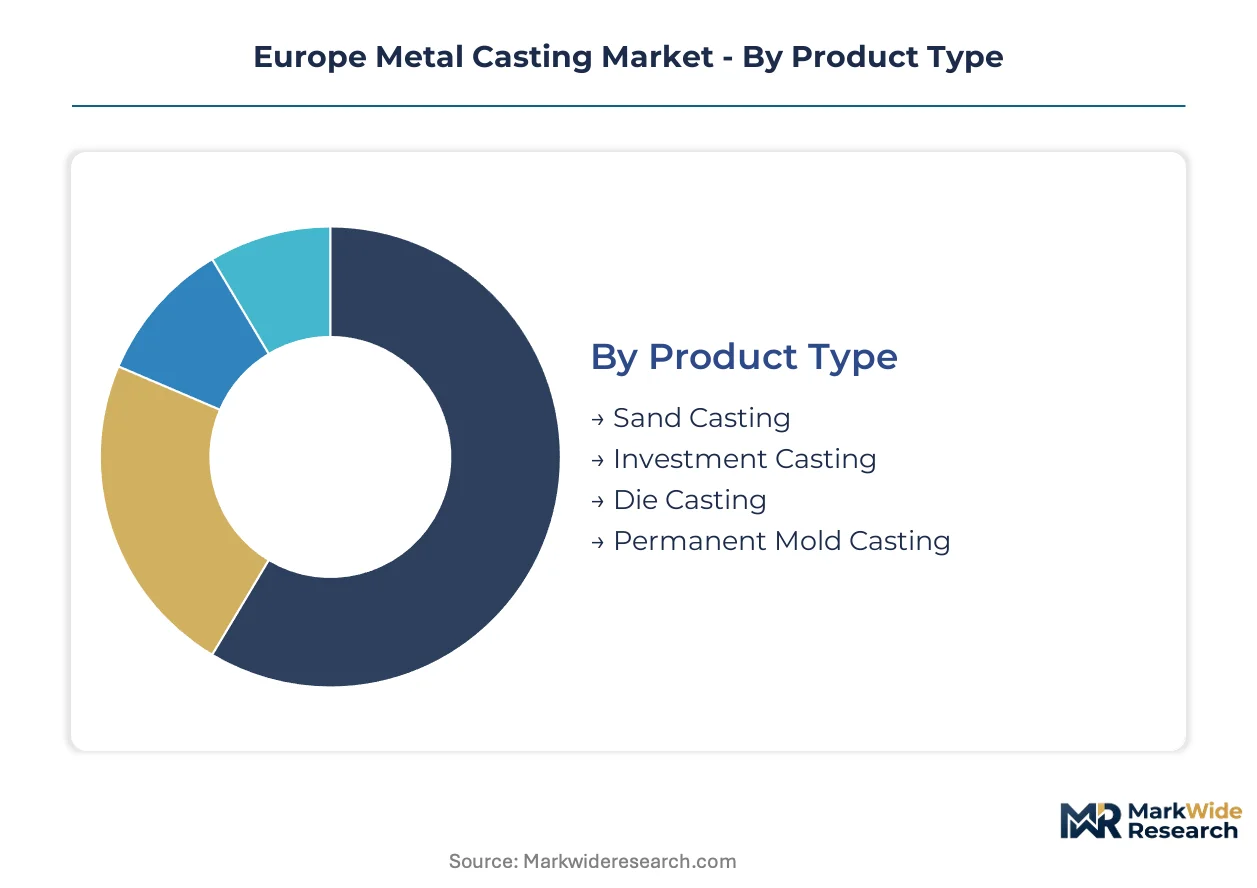
Process selection in European metal casting hinges on tolerance requirements, batch economics, and alloy compatibility. Each segment category reflects distinct technical trade-offs between dimensional precision, tooling investment, and production velocity.
Product Type:
Standardization decreases as dimensional precision increases across this spectrum, with sand casting offering maximum geometric flexibility while die casting enforces strict repeatability tolerances.
- Sand Casting:Refractory sand molds accommodate ferrous and non-ferrous alloys in single-piece to small-batch production. German and Italian foundries serving construction equipment OEMs in Baden-Württemberg and Lombardy deploy this process for engine blocks and transmission housings where surface finish requirements permit IT12-IT14 tolerances.
- Die Casting:Hardened steel dies under high-pressure injection produce thin-wall aluminum components with dimensional repeatability below 0.1 millimeters. Bavaria-based Tier-1 suppliers anchor capacity for electric vehicle powertrain housings as BMW and Siemens Energy consolidate procurement around vertically integrated suppliers.
- Investment Casting:Ceramic shell precision enables aerospace superalloy components from Netherlands and Switzerland operations.
- Permanent Mold Casting:Reusable metal molds balance tooling durability with aluminum and copper alloy versatility.
Most installed capacity flows through Sand Casting. Expansion is steepest in Die Casting.
Application:
Margin profiles diverge sharply between safety-critical aerospace specifications and cost-sensitive industrial machinery procurement.
- Automotive Components:Powertrain housings, transmission cases, and structural nodes dominate aluminum die-casting volume across German automotive clusters. REACH-compliant binder systems and electric melting investments are accelerating as OEMs enforce carbon border documentation for imported pig iron.
- Aerospace Parts:Turbine blades and structural castings in nickel-based superalloys command premium unit economics. Netherlands-based Cirex and Swiss specialists face furnace capacity constraints and skilled technician scarcity that limit output expansion despite sustained order backlogs.
- Industrial Machinery:Pump housings, valve bodies, and gear boxes consume gray and ductile iron castings from French and Spanish foundries.
- Consumer Goods:Decorative hardware and appliance components represent lower-margin, higher-volume aluminum and zinc casting.
Aerospace Parts commands the highest unit margins. Automotive Components is gaining share fastest.
Material:
Density-to-strength ratios and thermal conductivity requirements dictate alloy selection across end-use specifications.
- Aluminum:Lightweight properties and corrosion resistance position this alloy for electric vehicle powertrain housings and thermal management components. German foundries in Bavaria and Baden-Württemberg are expanding secondary aluminum melting capacity to meet automotive OEM carbon intensity targets under EU Green Deal compliance frameworks.
- Iron:Gray and ductile iron grades dominate industrial machinery and construction equipment applications where vibration damping and compressive strength outweigh weight considerations.
- Steel:Carbon and alloy steel castings serve power transmission and heavy machinery load-bearing assemblies.
- Copper:Electrical conductivity applications in motor windings and heat exchangers concentrate in Italian and Spanish foundry operations.
Iron retains the largest installed melting base. Aluminum is climbing the fastest.
End User:
Contract structures range from multi-year platform agreements with automotive OEMs to spot-market procurement from aftermarket distributors.
- OEMs:Original equipment manufacturers in automotive, aerospace, and industrial machinery sectors award multi-year contracts contingent on integrated machining, leak-testing, and CE marking compliance. Bavaria-based BMW procurement teams now mandate in-house CNC finishing capacity as a qualification threshold.
- Aftermarket Providers:Maintenance, repair, and operations distributors source replacement castings for aging industrial equipment fleets across Central European manufacturing corridors.
- Construction:Building infrastructure and heavy equipment OEMs procure iron and steel castings for structural and mechanical assemblies.
- Electrical Appliances:Motor housings and thermal management components in consumer and commercial equipment.
OEMs absorb the majority of precision die-casting output. Aftermarket Providers is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the largest installed foundry base while Italy maintains distinctive strength in precision investment casting for aerospace applications. France and Spain anchor iron casting capacity for industrial machinery, with Poland emerging as a cost-competitive alternative for automotive supply chains.
Germany
Automotive OEM procurement of aluminum powertrain housings for electric vehicle platforms drives die-casting investments in Bavaria and Baden-Württemberg. REACH compliance and EU Green Deal carbon border adjustments accelerate electric melting furnace deployments across Stuttgart and Munich industrial clusters. Thyssenkrupp and Georg Fischer AG anchor vertically integrated capacity serving BMW and Siemens Energy specifications.
Italy
Turin and Lombardy foundries specialize in precision investment casting for aerospace turbine blades and automotive components. EMA chemical safety assessments under REACH restrict phenolic binder formulations, prompting adoption of inert gas filtration systems. FONDERIA AUGUSTA Srl exemplifies the regional concentration of tooling engineering expertise constraining capacity expansion timelines.
France
Gray and ductile iron casting for construction equipment and industrial machinery dominates output from Auvergne-Rhône-Alpes and Hauts-de-France regions. CE marking under the Machinery Directive governs casting integration into finished equipment sold across the single market. Lucchini RS SpA represents the heavy-industry casting archetype serving power transmission and rail applications.
Poland
Underpenetrated precision casting capacity in Central European manufacturing corridors attracts greenfield investment for serving German automotive supply chains. Lower labor cost structures relative to Western Europe enable competitive positioning for Tier-2 component supply. Katowice and Wrocław industrial zones concentrate emerging die-casting capacity for aluminum automotive housings.
Netherlands
Cirex anchors aerospace superalloy investment casting from Dutch operations, facing furnace capacity constraints and skilled technician scarcity despite sustained order backlogs. F-Gas Regulation phase-down forces cooling system retrofits across die-casting cells serving precision applications. Rotterdam port logistics facilitate scrap alloy sourcing for secondary aluminum melting operations.
Europe Metal Casting Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with automotive OEMs consolidating procurement around vertically capable suppliers while aerospace retains fragmented specialist tiers. The market exhibits moderate concentration in aluminum die-casting alongside fragmentation in sand casting for industrial machinery. Three archetypes dominate: integrated steel-to-casting conglomerates, precision investment casting specialists, and regional sand casting houses serving construction equipment. Competitive moves center on electric melting technology deployment and predictive service contract expansion.
Among Swiss-German fabricators, Georg Fischer AG exemplifies the service-network archetype leveraging aftermarket revenue streams, while Thyssenkrupp represents integrated verticality from steel production through finished castings. Cirex occupies a distinctive position as a Netherlands-based precision investment casting specialist. These three entities anchor the competitive structure across automotive, aerospace, and industrial machinery supply chains respectively.
| Leading Market Players |
|---|
| Thyssenkrupp |
| Cirex |
| ArcelorMittal SA |
| FONDERIA AUGUSTA Srl |
| Novacast Ltd |
| Alcoa Corp |
| Zollern |
| Lucchini RS SpA |
| Georg Fischer AG |
| Others |
Cost & Logistics Intelligence
Electric melting furnace deployment across German and Italian foundries simultaneously compresses energy cost differentials and concentrates supply among capital-rich operators capable of absorbing EU Green Deal compliance investments. This technology transition rewards scaled producers with carbon border documentation capabilities while marginalizing independent foundries dependent on volatile scrap alloy spot markets.
Pricing Analysis
Capacity additions in Poland and the Czech Republic are reshaping price floors for aluminum die-casting components serving German automotive supply chains. Contract-based long-term offtake agreements dominate OEM procurement, with price differentiation driven by CE marking compliance status and integrated machining capabilities. Cost compression in standard-grade sand casting is intensifying because secondary aluminum scrap input costs fluctuate with London Metal Exchange pricing. Tier-1 automotive procurement teams exhibit lowest price sensitivity due to platform consolidation mandates, while aftermarket distributors remain most price-sensitive.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for electric vehicle powertrain housings, bypassing traditional distributor tiers. Supply concentrates in Germany, Italy, and France for precision die-casting capacity, with raw material flows drawing from Spanish and Belgian scrap processing hubs. The chain rests on secondary aluminum and copper scrap inputs, ceramic shell materials for investment casting, and phenolic resin binder alternatives. Single-source vulnerability characterizes aerospace superalloy furnace capacity in the Netherlands and Switzerland. Distribution runs through Tier-1 supplier networks anchored in Baden-Württemberg and Bavaria industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Metal Casting Market functions as a geographic-arbitrage play where Poland and Czech Republic labor cost structures undercut German foundry economics by 30-40% while maintaining EU regulatory equivalence.
For Market Incumbents: Deploy predictive furnace monitoring as a service-layer lever to anchor multi-year maintenance contracts and reduce customer churn. Consolidate tooling engineering expertise in Stuttgart and Turin clusters to defend against Polish greenfield entrants capturing Tier-2 automotive volume. CE marking integration complexity serves as a defensive moat against mid-cap competitors lacking downstream equipment certification capabilities. For New Entrants and Emerging Players: EU AI Act national transpositions in Germany and France open a window for computer vision system providers to capture compliance-driven demand from foundries retrofitting automated defect detection. Target underpenetrated precision casting capacity in Katowice and Wrocław industrial zones to serve Bavaria-based BMW procurement specifications. Position around outcome-based thermal analytics subscriptions rather than transactional equipment sales. For Investors and Strategic Acquirers: Valuations sit cheapest among regional sand casting houses serving construction equipment OEMs, where margin pressure from scrap volatility and REACH binder reformulation has compressed multiples. Long-term viability centers on electric melting technology deployment and captive secondary aluminum supply. Watch for F-Gas Regulation cooling system retrofit mandates as an inflection indicator forcing consolidation among mid-cap die-casting operators.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Melting Capacity Expansion | Reduces Scope 1 emissions to satisfy EU Green Deal carbon border documentation requirements for German automotive OEMs. |
| Backward Integration into Scrap Processing | Captures margin from secondary aluminum volatility while securing alloy quality for REACH-compliant binder systems. |
| Predictive Service Contract Launch | Transforms transactional component supply into recurring revenue through machine learning-enabled furnace monitoring. |
| Inert Gas Filtration Retrofit | Replaces restricted phenolic resin formulations to maintain certification status with construction equipment OEMs. |
| Polish Greenfield Site Development | Exploits labor cost arbitrage against Western European foundries while serving German Tier-1 supply chains. |
Research Approach
Bottom-up automotive and aerospace end-use modeling reconciled against top-down foundry capacity tracking forms the analytical core of this study. Primary interviews with foundry operations directors, Tier-1 supplier procurement leads, OEM platform engineers, and aftermarket service heads were validated against secondary sources including ECHA REACH registration databases, EU customs trade flows for scrap aluminum and pig iron, SEC filings from publicly traded metal processors, and national foundry association production statistics across Germany, Italy, and France.
Historical trendline analysis of installed melting capacity and process-specific output volumes informed the projection framework across the analysis window. Segmentation dimensions modeled include casting process type, alloy material grade, end-use application, and regional production cluster. CAGRs were derived from regression analysis of capacity utilization rates and OEM platform contract award patterns, with electric vehicle powertrain housing specifications and aerospace superalloy order backlogs serving as key demand-side inputs.
Revisions become necessary when EU Green Deal carbon border adjustment implementation timelines accelerate, F-Gas Regulation enforcement intensifies cooling system retrofit requirements, or automotive OEM supplier consolidation patterns shift unexpectedly. Forecasts reflect assumptions regarding scrap alloy price stability, REACH binder formulation grandfathering periods, and Polish labor cost competitiveness. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Nickel Sulfate Market
Metals
Lightweight Aluminium Pistons Market
Metals
Reconditioned Steel Drums Market
Metals
Stainless Steel 400 Series Market
Metals
Copper Chromium Black Market
Metals
Potassium Platinochloride Market
Metals
Asia-Pacific Metal Finishing Market
Metals
Global Aluminum Market
Metals
Steel Casting Market
Metals
Aluminum Casting Market
Metals
Metal Powder Market
Metals
Global Superconducting Wire Market
Metals
Middle-East and Africa Metal Finishing Market
Metals
Aluminum Flat-Rolled Products Market
Metals
US and Mexico Stainless Steel Market
Metals
Global Tin Market