
 Filtering Centrifuges Market | 2026-2036
Filtering Centrifuges Market Size, Share, and Industry Trends Forecast 2026-2036
Filtering Centrifuges Market Insights
Automated sedimentation control with real-time torque sensing is tilting engineering priorities toward self-optimizing bowl designs. Alfa Laval leverages its Nordic installed base to anchor aftermarket service contracts across Scandinavian dairy and marine applications. Andritz AG specializes in high-throughput drum systems for minerals processing, where abrasive slurries demand replaceable liner technology. GEA Group dominates pharmaceutical-grade disk centrifuge supply, competing on validated clean-in-place protocols that reduce batch changeover downtime.
Filtering centrifuges are mechanical separation devices that apply centrifugal force to dewater, clarify, or classify suspensions, typically operating at bowl speeds from 1,600 to over 10,000 rpm depending on particle size and density differential. Their primary purpose is to achieve solid-liquid separation without thermal degradation, preserving active compounds in temperature-sensitive process streams. Disk-type configurations lead in biopharmaceutical harvest operations where cell culture broths require gentle yet efficient clarification. Continuous operation mode is displacing batch cycles in large-scale chemical plants, as steady-state running cuts labor intensity and improves mass balance predictability. Portable deployment remains a niche, mainly serving remote mining camps and emergency wastewater response where fixed infrastructure proves impractical.
EPA effluent guidelines and FDA cGMP standards shape equipment specifications, forcing manufacturers to document material traceability and surface finish compliance for wetted components. REACH restrictions on chromium-plated bowls are pushing European suppliers toward ceramic-coated or duplex stainless steel alternatives that satisfy ECHA substance thresholds. EU MDR conformity requirements extend to centrifuges used in medical device manufacturing, adding validation layers for contract sterilization facilities. Stakeholders must weigh capital intensity against operating flexibility, as modular automatic systems with integrated clean-in-place circuits command premium positioning but reduce lifecycle validation costs.
Market Dynamics
Continuous operation mode is displacing batch cycles as pharmaceutical manufacturers scale biologics capacity, forcing centrifuge engineering priorities toward self-optimizing bowl designs with real-time torque sensing. This structural shift compresses validation timelines while tightening material traceability requirements under FDA cGMP and EU MDR standards.
Growth Catalysts
- EU MDR conformity mandates:Medical device manufacturers must validate centrifuge equipment used in contract sterilization facilities, expanding demand for documented surface finish compliance and material traceability in wetted components.
- Biologics capacity expansion:Pharmaceutical manufacturers are scaling cell culture harvest operations, driving adoption of disk-type configurations that clarify broths without thermal degradation of active compounds.
- REACH restrictions on chromium plating:ECHA substance thresholds are pushing European suppliers toward ceramic-coated and duplex stainless steel bowl alternatives, creating upgrade cycles in installed base equipment.
Market Restraints
- Capital intensity of modular systems:Automatic centrifuges with integrated clean-in-place circuits command premium positioning that limits adoption among mid-scale chemical processors.
- Supply concentration in engineering-intensive production:Germany dominates European manufacturing of high-specification units, creating geographic vulnerability for contract manufacturing organizations dependent on just-in-time delivery.
- Substitution by membrane filtration:Cross-flow systems are capturing share in low-solids biopharmaceutical applications where gentle processing requirements overlap with centrifuge use cases.
Strategic Opportunities
- Remote mining camp deployment:Portable centrifuge configurations serve emergency wastewater response and extraction operations where fixed infrastructure proves impractical, opening niche demand in resource extraction geographies.
- Aftermarket service contract anchoring:Nordic dairy and marine applications present recurring revenue potential through preventive maintenance and bowl replacement programs tied to installed base density.
- EPA effluent guideline tightening:US wastewater treatment facilities face upgraded solids separation requirements, creating specification windows for high-throughput drum systems with replaceable liner technology.
Industry Challenges
- Validation timeline compression:FDA cGMP and EU MDR documentation requirements extend commissioning periods for sterile separation equipment, straining project delivery schedules.
- Integration complexity with legacy batch systems:Chemical plants transitioning to continuous operation face control system retrofit challenges and mass balance recalibration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Filtering Centrifuges Market |
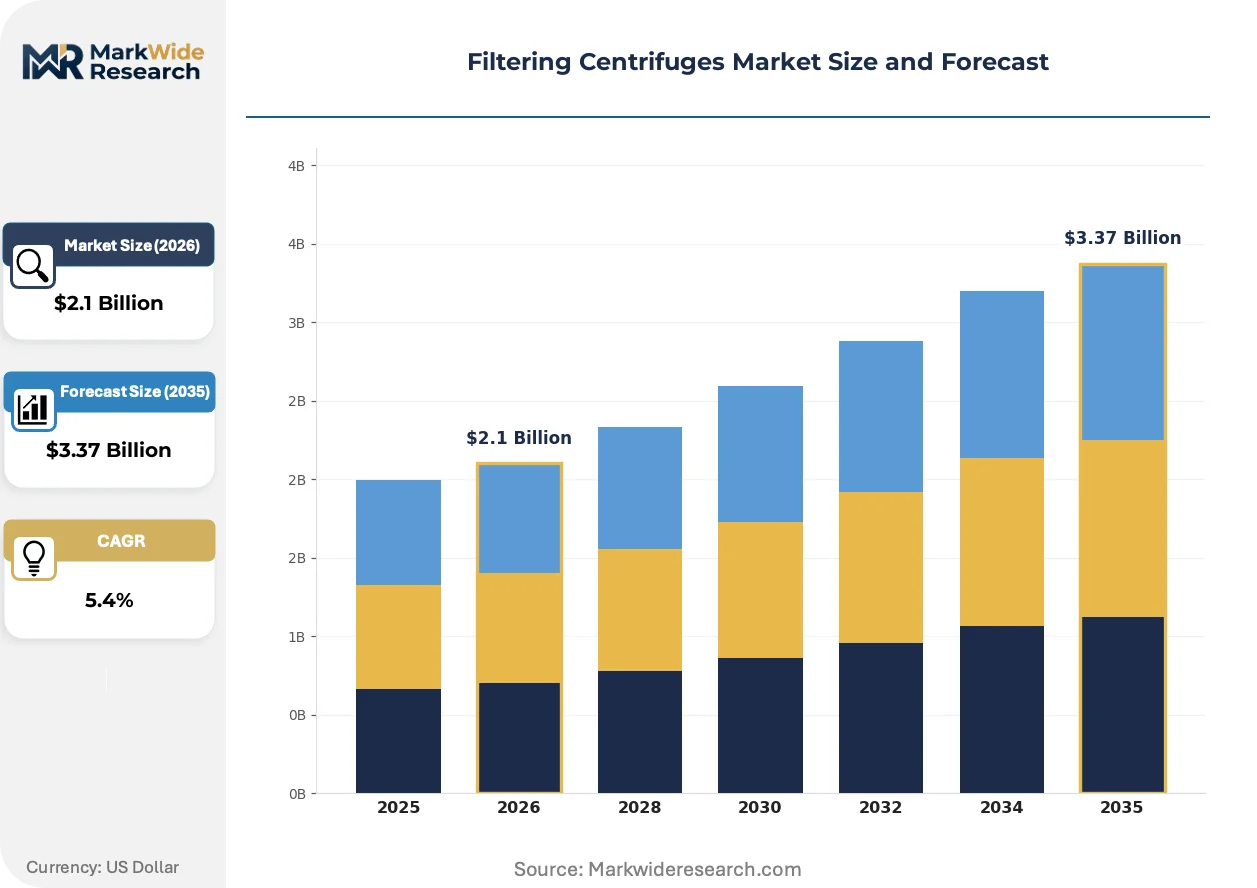
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disk-Type, Drum-Type, Tubular, Bag-Type End User: Pharmaceuticals, Food & Beverage, Chemical, Wastewater Treatment Operation Mode: Batch, Continuous, Semi-Automatic, Automatic Deployment Method: Portable, Stationary, Integrated, Standalone |
| Companies Covered | Alfa Laval, GEA Group, Andritz AG, Flottweg SE, Siebtechnik Tema, FLSmidth, Ferrum AG, Pall Corporation, Merck Millipore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Filtering Centrifuges Market Trends and Innovations
Equipment intelligence and materials engineering are converging to reshape competitive positioning in solid-liquid separation. Three developments are altering how centrifuge specifications are written and how suppliers capture value.
Self-optimizing bowl geometry is migrating from fixed-speed mechanical designs to variable-frequency drive systems with embedded torque feedback loops. Pharmaceutical harvest operations are adopting these configurations fastest, compressing batch changeover windows while reducing operator intervention. The technology is migrating from premium bioprocessing units toward mid-scale chemical applications as sensor costs decline.
REACH substance restrictions are forcing material specification changes across European supply chains. Chromium-plated bowls face phase-out timelines, accelerating qualification of ceramic-coated and super-duplex stainless alternatives. German engineering-intensive manufacturers are most affected, retooling surface treatment lines to maintain ECHA compliance without sacrificing abrasion resistance in minerals processing.
Service unbundling is fragmenting traditional equipment-plus-maintenance bundles. Dairy and marine operators in Scandinavia are separating bowl replacement and preventive maintenance from original equipment procurement, pressuring suppliers to price aftermarket components transparently. This pattern is most visible in Nordic markets where installed base density supports third-party service competition.
Filtering Centrifuges Market Segmentation
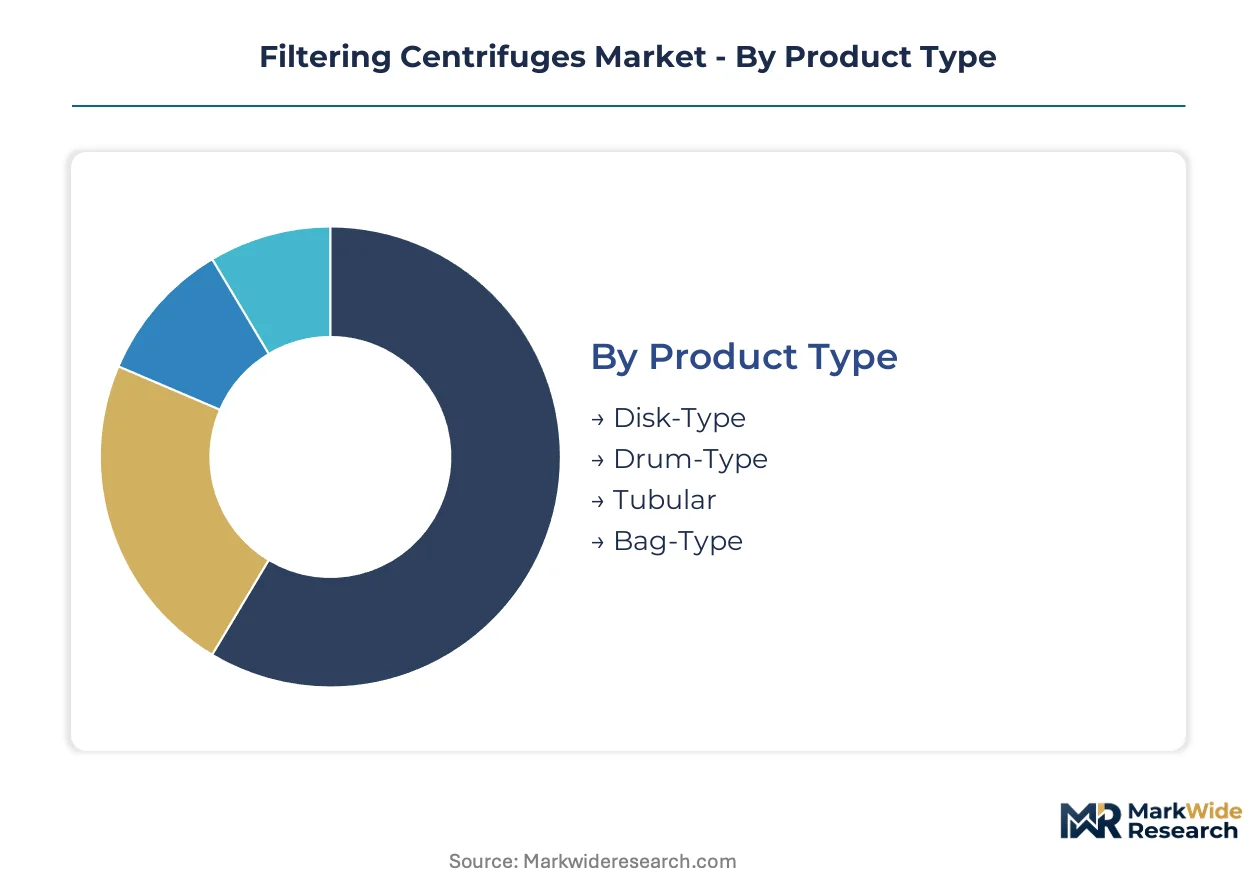
Equipment specification in filtering centrifuges diverges sharply across process intensity and regulatory exposure. Pharmaceutical harvest operations demand validated disk systems with clean-in-place circuits, while minerals processors prioritize abrasion-resistant drum configurations with replaceable liners.
Product Type:
Cost tier determines material specification and aftermarket attachment rates across centrifuge architectures.
- Disk-Type:Stacked conical discs multiply settling area within compact bowl geometries, achieving high separation factors at moderate speeds. Cell culture clarification in biopharmaceutical manufacturing concentrates demand in Germany and Switzerland, where EMA validation protocols require documented surface finish compliance for wetted components.
- Drum-Type:Cylindrical bowls with axial discharge ports handle abrasive slurries in minerals processing and chemical solids recovery. Scandinavian marine applications and Australian mining camps anchor installed base density for high-throughput drum systems with ceramic-coated liners replacing REACH-restricted chromium plating.
- Tubular:Slender high-speed bowls excel at liquid-liquid separation for fine particle clarification.
- Bag-Type:Filter media integration enables cake discharge without bowl opening, serving specialty chemical batch operations.
Disk-type holds installed capacity in pharmaceutical validation environments. Drum-type is rotating up the share rankings in resource extraction geographies.
End User:
Application-specific regulatory exposure shapes procurement criteria and lifecycle validation burdens.
- Pharmaceuticals:FDA cGMP and EU MDR documentation requirements govern sterile separation equipment for biologics harvest and blood plasma fractionation. German contract manufacturing organizations drive specification intensity, demanding torque-sensing bowl controls that compress batch changeover windows.
- Chemical:Continuous operation mode displaces batch cycles in large-scale polymer and catalyst recovery, cutting labor intensity while improving mass balance predictability. US Gulf Coast petrochemical complexes and Rotterdam-Belgium chemical clusters anchor demand for self-optimizing drive systems.
- Food & Beverage:Dairy clarification and edible oil refining prioritize clean-in-place protocols with validated CIP circuits.
- Wastewater Treatment:EPA effluent guideline tightening drives specification windows for high-solids dewatering in US municipal facilities.
Pharmaceuticals commands specification leadership. Chemical is expanding most quickly as continuous processing retrofits accelerate.
Operation Mode:
Customer type and scale determine automation intensity versus capital constraint tradeoffs.
- Continuous:Steady-state running eliminates batch cycle dead time, enabling real-time torque feedback loops that self-optimize bowl geometry. Large-scale chemical plants in Germany and the Netherlands adopt these configurations fastest, though integration complexity with legacy batch control systems strains project timelines.
- Automatic:Integrated clean-in-place circuits and sediment discharge automation reduce operator intervention for validated pharmaceutical operations. Premium positioning limits penetration among mid-scale chemical processors facing capital intensity constraints.
- Batch:Cyclical operation persists in specialty chemical and contract manufacturing where product changeover frequency defeats continuous economics.
- Semi-Automatic:Operator-supervised discharge balances labor cost against automation investment in regional dairy processing.
Continuous holds installed capacity in large-scale chemical processing. Automatic is climbing the fastest as pharmaceutical validation requirements tighten.
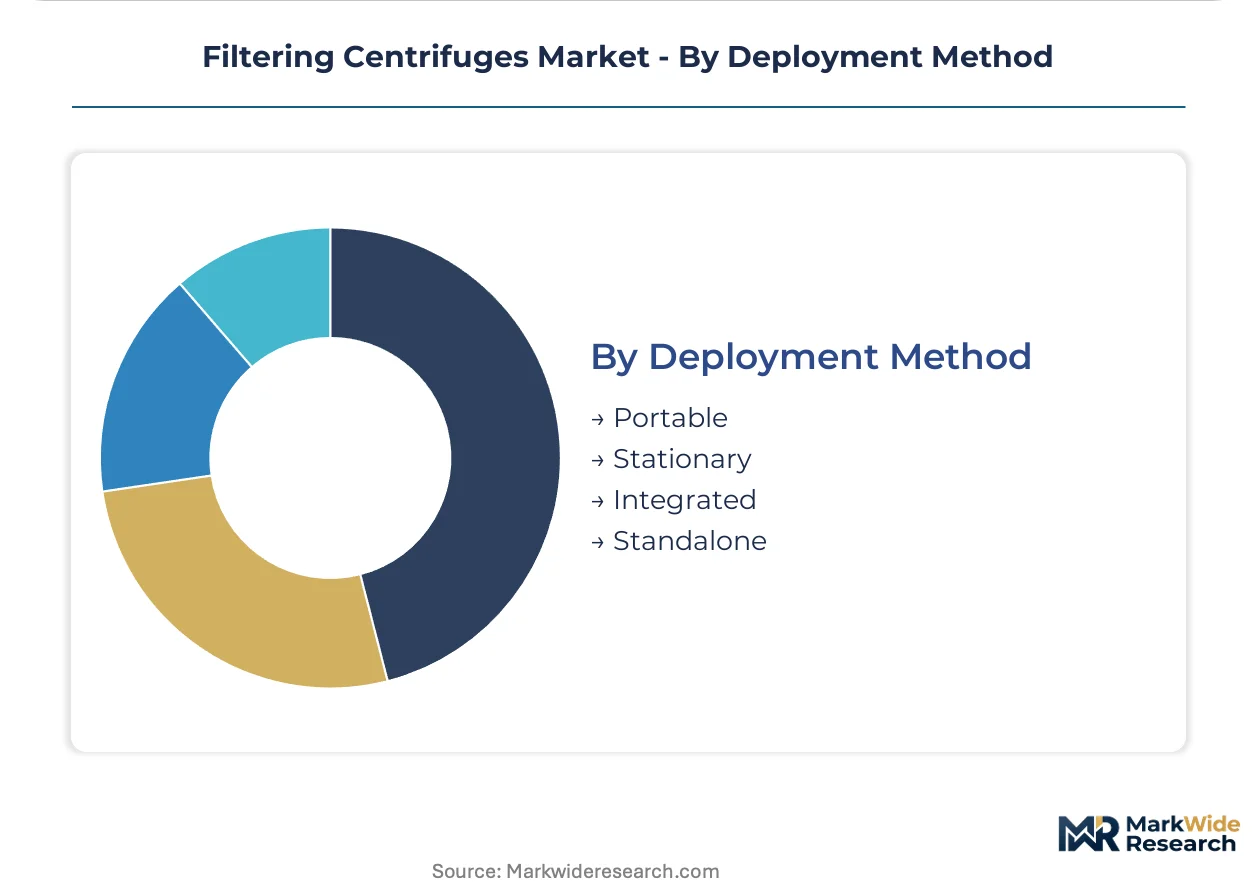
Deployment Method:
Geography and infrastructure availability dictate mobility requirements versus fixed installation economics.
- Stationary:Permanent installation dominates pharmaceutical manufacturing and municipal wastewater treatment, where validation documentation and utility integration favor fixed infrastructure. German engineering-intensive production serves contract manufacturing organizations across Europe with just-in-time delivery dependencies.
- Portable:Skid-mounted configurations with self-contained power and control systems serve remote mining camps in Western Australia and emergency wastewater response in US hurricane corridors. Niche demand concentrates where fixed infrastructure proves impractical or capital deployment timelines are compressed.
- Integrated:Centrifuge subsystems embedded within larger process trains reduce footprint in offshore platform and marine applications.
- Standalone:Independent operation persists in pilot-scale pharmaceutical development and regional food processing.
Stationary anchors pharmaceutical and municipal installed base. Portable is gaining share fastest in resource extraction and emergency response geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract manufacturers and engineering-intensive equipment fabricators dominate procurement patterns across key geographies. Demand concentrates where FDA and EMA validation requirements intersect with dense bioprocessing infrastructure.
Germany
Engineering-intensive centrifuge production serves contract manufacturing organizations across Europe with just-in-time delivery dependencies. EU MDR conformity mandates extend validation layers to equipment used in medical device manufacturing. The Rhine-Ruhr and Baden-Württemberg clusters anchor high-specification unit fabrication for pharmaceutical-grade disk systems.
United States
Gulf Coast petrochemical complexes and biologics manufacturers drive specification intensity for continuous operation systems. EPA effluent guidelines tighten solids separation requirements for municipal wastewater facilities. Greater Boston and San Diego biotech corridors anchor demand for validated clean-in-place protocols in cell culture harvest operations.
Switzerland
EMA validation protocols and pharmaceutical manufacturing density create premium positioning for documented surface finish compliance. REACH substance thresholds push suppliers toward ceramic-coated bowl alternatives. The Basel region concentrates blood plasma fractionation and biologics capacity requiring sterile separation equipment.
China
Domestic biopharmaceutical capacity expansion and chemical processing retrofits accelerate adoption of self-optimizing drive systems. NMPA standards govern equipment validation for pharmaceutical applications. The Yangtze River Delta anchors both domestic manufacturing and import substitution programs for high-throughput drum systems.
Australia
Remote mining camps in Western Australia generate niche demand for portable skid-mounted configurations with self-contained power systems. TGA standards influence equipment specification for pharmaceutical applications. The Pilbara region anchors extraction operations where fixed infrastructure proves impractical.
Filtering Centrifuges Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Engineering-intensive manufacturers in Germany and Nordic countries anchor premium-tier supply, while diversified industrial conglomerates capture scale-driven mid-market positions. Strategic archetypes separate into validation-focused pharmaceutical specialists, abrasion-resistant minerals processors, and aftermarket service bundlers. Competitive moves concentrate on geographic expansion into biologics manufacturing clusters and technology licensing for torque-sensing automation.
Among European-based engineering specialists, Alfa Laval, GEA Group, and Andritz AG occupy distinct positioning vectors. Alfa Laval exemplifies the aftermarket-anchored archetype with service contract density in dairy and marine applications. GEA Group represents the pharmaceutical-validation specialist tier with documented clean-in-place protocol leadership. Andritz AG sits within the minerals-processing durable-equipment segment where replaceable liner technology addresses abrasive slurry applications. These three anchors demonstrate how geographic origin and structural suffix patterns correlate with strategic specialization in solid-liquid separation equipment.
| Leading Market Players |
|---|
| Alfa Laval |
| GEA Group |
| Andritz AG |
| Flottweg SE |
| Siebtechnik Tema |
| FLSmidth |
| Ferrum AG |
| Pall Corporation |
| Merck Millipore |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Alpine corridor's freight cost dynamics amplify supply concentration effects in German engineering-intensive centrifuge production, compressing margins for mid-scale chemical processors while enabling premium price differentiation for validated pharmaceutical-grade units with documented EU MDR compliance.
Pricing Analysis
Cost-plus contracts indexed to duplex stainless steel and ceramic coating material baskets dominate procurement for high-specification pharmaceutical units. Three-tier pricing structure across premium validated systems, standard industrial configurations, and economy batch units separates FDA cGMP-compliant disk centrifuges from REACH-restricted chromium-plated legacy equipment. Pricing pressure stems from membrane filtration substitution in low-solids biopharmaceutical applications. Contract manufacturing organizations exhibit highest price sensitivity; biologics manufacturers with EMA validation requirements show lowest.
Supply Chain Analysis
Export control regimes limiting torque-sensing automation technology flows constrain supply chain flexibility for self-optimizing drive systems. Manufacturing concentrates in Germany, Switzerland, and Sweden for pharmaceutical-grade units; China and South Korea anchor mid-scale chemical processing equipment. Supply chains draw from duplex stainless steel foundries, ceramic coating specialists, and precision sensor manufacturers. Single-source vulnerability clusters around German engineering-intensive fabricators serving just-in-time European contract manufacturing. Distribution runs through OEM-direct channels for validated pharmaceutical systems and regional distributors for industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities expand faster than hardware as aftermarket bowl replacement and preventive maintenance programs decouple from original equipment procurement in Nordic dairy and marine applications.
For Market Incumbents: Pre-empt membrane filtration substitution by embedding torque-sensing automation into mid-scale chemical processing tiers before cross-flow systems capture share. Deepen backward integration into ceramic coating capabilities to offset REACH-restricted chromium plating phase-outs. Anchor service contract density in installed base clusters to resist third-party maintenance competition. For New Entrants and Emerging Players: Remote mining camps in Western Australia and emergency wastewater response corridors in US hurricane zones represent underpenetrated demand pockets where portable skid-mounted configurations bypass fixed infrastructure economics. Target portable deployment segments with self-contained power and control systems. Pursue technology licensing partnerships with established drive system suppliers to accelerate validation timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pharmaceutical-validation specialists with documented clean-in-place protocol leadership over commodity industrial suppliers. Long-term viability hinges on recurring revenue attachment rates in aftermarket service rather than equipment shipment volumes. Monitor EMA and FDA validation timeline compression as inflection indicator for consolidation pressure among engineering-intensive manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Aftermarket Service Unbundling | Separates bowl replacement and preventive maintenance from original equipment procurement in Nordic dairy applications. |
| Ceramic Coating Qualification | Replaces REACH-restricted chromium plating in German engineering-intensive manufacturing to maintain ECHA compliance. |
| Torque-Sensing Automation Licensing | Accelerates self-optimizing drive system adoption in mid-scale chemical processing beyond premium biopharmaceutical tiers. |
| Portable Configuration Development | Opens niche demand in Western Australian mining camps and US emergency wastewater response corridors. |
| EU MDR Validation Documentation | Extends compliance layers to contract sterilization facilities serving medical device manufacturers. |
Research Methodology
Cross-validation between primary interviews with plant engineers, aftermarket service heads, OEM procurement teams, and regulatory affairs specialists and secondary validation through EMA submission databases, FDA cGMP guidance documents, ECHA REACH substance restriction notices, and customs trade flow records anchors the qualitative findings. Bottom-up equipment shipment tallies by configuration type and top-down industry spend estimates triangulate market sizing across the analysis window.
Calibration against historical adoption curves for continuous operation mode displacement of batch cycles and ceramic coating substitution rates for chromium-plated bowls shapes the projection framework. Segmentation dimensions span product architecture, end-use regulatory exposure, operation automation intensity, and deployment mobility. CAGRs derive from fitted growth curves incorporating biologics capacity expansion trajectories and EPA effluent guideline enforcement timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by membrane filtration suppliers or export control expansion on automation components would shift outcomes. Material shifts in EU MDR validation timeline requirements or REACH substance restriction acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Sintered Metal Filters Market
Filters
Filter Paper Market
Filters
Industrial Filtration Market
Filters
Global Hollow Fiber Filtration Market
Filters
Drum Filters Market
Filters
Diatomaceous Filter Aid Market
Filters
Global Gas Phase Filtration Market
Filters
Europe Activated Carbon Market
Filters
Air Filtration Media Market
Filters
Global Liquid Filtration Market
Filters
GCC Industrial Air Filtration Market
Filters
Filtration and Separation Market
Filters
String Wound Filter Materials Market
Filters
Zeolite Adsorbents Market
Filters
High Purity Chemical Filters Market
Filters
Filters and Particle Monitoring Market