
 Industrial Air Filtration Market | 2026-2036
Industrial Air Filtration Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Air Filtration Market Analysis
Capital-intensity divergence between membrane technology leaders and commodity filter assemblers is bifurcating competitive returns. Mann+Hummel leverages its captive media production across automotive and industrial verticals. Freudenberg Filtration Technology anchors European demand through nanofiber R&D programs. Donaldson Company dominates aftermarket distribution networks in North American metalworking.
Industrial air filtration encompasses systems engineered to remove particulate matter, aerosols, and gaseous contaminants from process and ambient air streams, typically achieving efficiencies from MERV 8 through HEPA H14 depending on pore structure and electrostatic enhancement. Bag filters capture bulk dust loads in cement and metalworking facilities, while HEPA filters command premium positioning in pharmaceutical aseptic processing where single-pass efficiency exceeds 99.97% at 0.3 microns. Nanofiber technology is displacing conventional meltblown media in energy sector turbine inlet applications, and chemical filtration using activated carbon impregnates is extending service intervals in semiconductor fabrication.
OSHA permissible exposure limits for respirable crystalline silica and EPA National Ambient Air Quality Standards compel manufacturing facilities to upgrade legacy collection systems. FDA cGMP Annex 1 revisions for sterile pharmaceutical manufacturing mandate continuous monitoring of airborne particle concentrations. Stakeholders must weigh filter media substitution timelines against total cost of ownership models as energy efficiency metrics displace first-cost procurement criteria.
Market Dynamics
Filter media substitution timelines are compressing as energy efficiency metrics displace first-cost procurement criteria across pharmaceutical and semiconductor cleanroom installations. Total cost of ownership models now dominate capital allocation decisions for facility managers upgrading legacy dust collection infrastructure.
Growth Catalysts
- OSHA Silica Rule Enforcement:Permissible exposure limits for respirable crystalline silica compel cement and metalworking facilities to retrofit baghouse systems with high-efficiency cartridge filters.
- Pharmaceutical Cleanroom Expansion:FDA cGMP Annex 1 revisions mandate continuous airborne particle monitoring, driving HEPA filter replacement cycles in aseptic processing suites.
- Nanofiber Media Adoption:Energy sector turbine inlet applications are converting from meltblown to nanofiber surfaces, extending service intervals in combined-cycle power plants.
Market Restraints
- Specialized Media Supply Concentration:Captive production of electrospun nanofiber layers concentrates among three European chemical conglomerates, creating input bottlenecks for independent filter assemblers.
- Activated Carbon Price Volatility:Coconut shell charcoal costs fluctuate with Southeast Asian agricultural yields, compressing margins on chemical filtration modules for semiconductor fabrication.
- HEPA Certification Timeline Friction:EN 1822 testing protocols require extended laboratory validation, delaying product launches for manufacturers seeking pharmaceutical qualification.
Strategic Opportunities
- India Pharmaceutical Manufacturing:CDSCO alignment with PIC/S standards is accelerating cleanroom construction in Hyderabad and Ahmedabad bulk drug clusters.
- Filter-as-a-Service Models:Pressure differential monitoring with automated reorder triggers is displacing transactional spare parts purchasing among multi-site industrial operators.
- Carbon Capture Co-Location:Amine-based post-combustion systems require specialized corrosion-resistant filtration upstream of absorber columns, creating adjacent demand for chemical-resistant media.
Industry Challenges
- Electrospinning Technician Scarcity:Nanofiber production lines require operators trained in polymer rheology and high-voltage field management, skills concentrated in German and Swiss technical institutes.
- Legacy System Integration Complexity:Retrofitting HEPA final filters into existing HVAC ductwork designed for MERV 13 pre-filtration demands structural reinforcement and airflow recalculation.
- Cross-Border Certification Fragmentation:Divergent test methodologies between EN 1822 and IEST-RP-CC001 create redundant validation costs for suppliers serving both European and North American pharmaceutical markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Air Filtration Market |
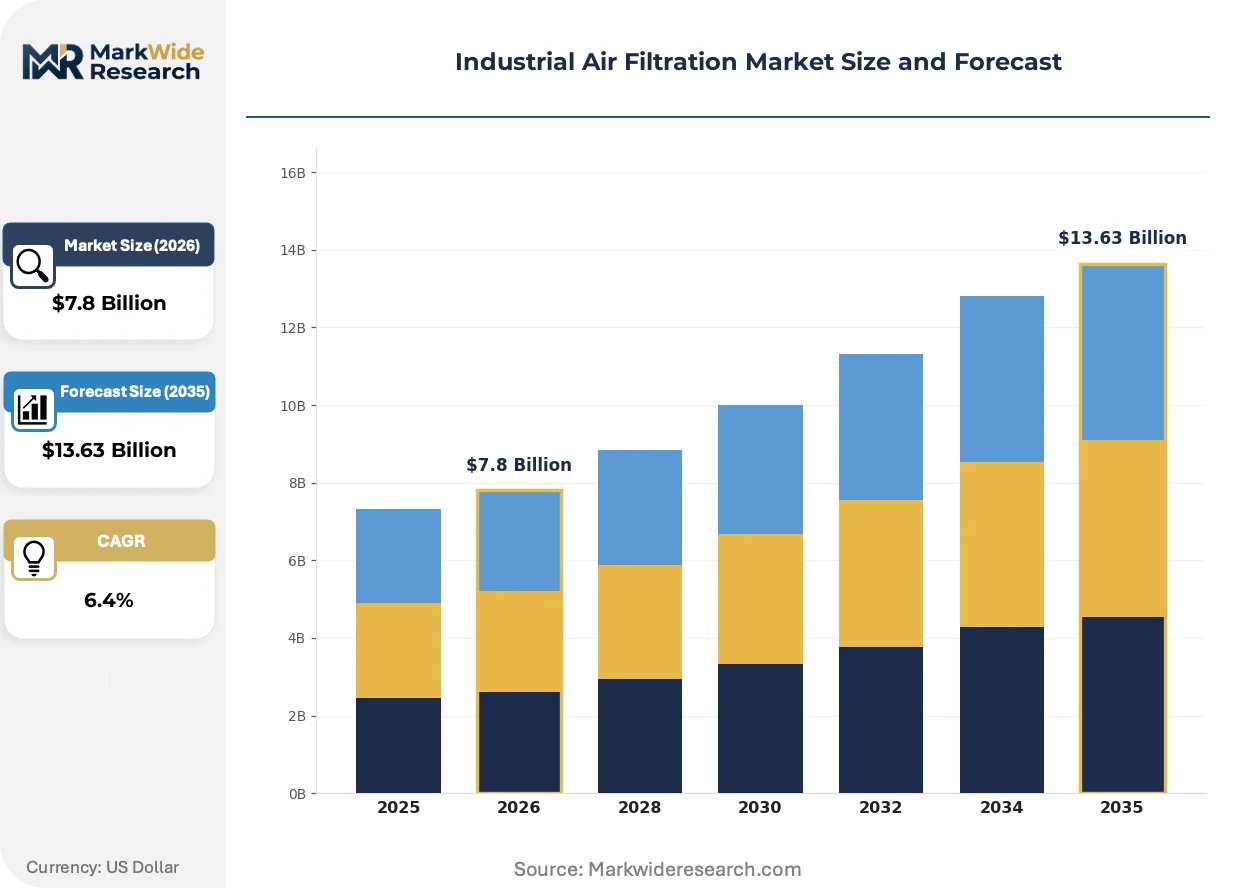
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bag Filters, HEPA Filters, Electrostatic Precipitators, Carbon Filters Application: Manufacturing, Food Processing, Pharmaceuticals, Metalworking Technology: Filtration Technology, Nanofiber Technology, Mechanical Filtration, Chemical Filtration End User: Aerospace, Automotive, Energy, Construction |
| Companies Covered | Mann+Hummel, Freudenberg Filtration Technology, Camfil, Honeywell International, AAF International, Donaldson Company, Cummins Filtration, Filtration Group Corporation, Parker Hannifin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Air Filtration Market Emerging Trajectories
Membrane technology advancement is fragmenting competitive returns between integrated media producers and commodity filter assemblers. Equipment buyers now prioritize energy consumption metrics over initial capital expenditure, reshaping vendor selection criteria across industrial verticals.
Electrospun nanofiber layers are bifurcating the premium media segment from conventional meltblown supply. Pharmaceutical manufacturers and gas turbine operators are specifying sub-micron fiber diameters for enhanced particle capture with reduced pressure drop. This performance tier is compressing margins for assemblers dependent on commodity meltblown imports while rewarding captive nanofiber production.
EPA National Ambient Air Quality Standards revisions are tightening particulate thresholds for non-attainment zones. Industrial facilities in Texas and California must upgrade to PM2.5-compliant collection systems ahead of state implementation plan deadlines. Metalworking and mineral processing operations are responding with dry fog dust suppression paired with final HEPA polishing stages.
Facility managers are consolidating supplier relationships around full-lifecycle service contracts. Predictive maintenance algorithms using pressure differential sensors are displacing calendar-based filter replacement schedules. This behavioral shift is most visible in German automotive manufacturing corridors, where multi-site operators negotiate enterprise pricing tied to guaranteed uptime metrics rather than unit volumes.
Industrial Air Filtration Market Segmentation
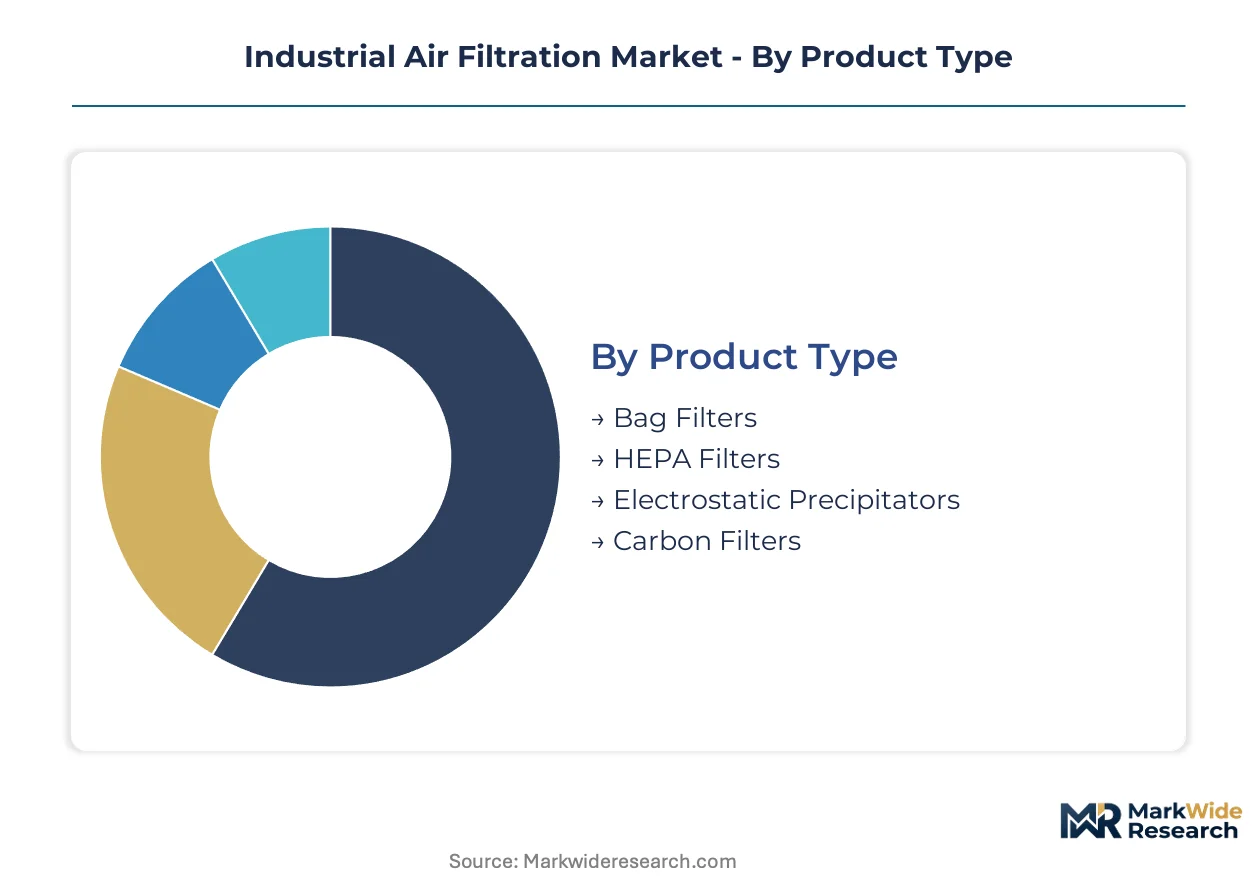
Industrial air filtration procurement decisions split sharply between energy-intensive continuous processes and intermittent batch operations. Segment boundaries blur where pharmaceutical cleanrooms demand HEPA final filtration paired with activated carbon chemical scrubbing.
Product Type:
Bag filters face the most acute substitution pressure as nanofiber cartridge alternatives capture share in cement and metalworking dust collection.
- Bag Filters:Woven or felted synthetic media configured in tubular sleeves for pulse-jet cleaning systems. Cement kilns and steel foundries in Germany's industrial corridor specify P84 polyimide blends for thermal stability above 200°C. OSHA silica enforcement is compressing replacement cycles from 24 months to 12 months in US metalworking.
- HEPA Filters:Pleated glass microfiber media bonded with water-resistant separators, achieving 99.97% efficiency at 0.3 microns per EN 1822 protocols. Pharmaceutical aseptic suites in Basel and Boston mandate H14 grade with continuous particle monitoring per FDA cGMP Annex 1 revisions.
- Electrostatic Precipitators:Ionization electrodes and collection plates for sub-micron particulate in high-temperature flue gas streams.
- Carbon Filters:Activated coconut shell or coal-based impregnates for VOC and odor removal in semiconductor fabrication.
Bag filters anchor the volume base while HEPA filters gain share at the steepest rate.
Application:
Cost tier stratification separates capital-intensive cleanroom infrastructure from commodity dust collection retrofits.
- Manufacturing:General industrial facilities deploy cartridge collectors for welding fume and grinding dust. Automotive paint shops in Stuttgart specify PTFE membrane media for moisture resistance.
- Food Processing:Washdown-rated stainless steel housings with FDA-compliant media for dairy powder and grain handling. EU Regulation 1935/2004 frames migration testing for food contact materials.
- Pharmaceuticals:ISO 14644-1 classified cleanrooms require terminal HEPA with redundant filtration stages. Hyderabad bulk drug clusters are expanding capacity under CDSCO alignment with PIC/S standards.
- Metalworking:Dry fog suppression paired with final polishing filtration for respirable silica compliance.
Manufacturing commands the largest installed base as pharmaceutical applications climb the fastest.
Technology:
Supply concentration in electrospun nanofiber media is bifurcating performance tiers between integrated producers and commodity assemblers.
- Filtration Technology:Conventional depth and surface filtration using meltblown polypropylene and glass microfiber. Gas turbine inlet systems in combined-cycle plants specify this proven technology for baseline protection.
- Nanofiber Technology:Electrospun polymer layers with sub-micron fiber diameters for enhanced capture efficiency at reduced pressure drop. Freudenberg's captive production in Germany supplies premium media for energy sector specifications.
- Mechanical Filtration:Inertial and interception mechanisms without electrostatic enhancement for coarse particulate loads.
- Chemical Filtration:Activated carbon and potassium permanganate impregnates for molecular contaminant removal in wafer fabrication.
Mechanical filtration retains the deepest installed base as nanofiber technology expands most quickly.
End User:
Customer type segmentation reflects divergent procurement sophistication between OEM specification engineers and facility maintenance managers.
- Aerospace:Cabin air recirculation and engine inlet filtration for particulate and ice crystal protection. FAA certification protocols govern filter qualification for commercial aviation.
- Automotive:Paint booth overspray collection and powertrain manufacturing dust control. German OEMs negotiate enterprise service contracts with guaranteed uptime metrics.
- Energy:Turbine inlet air filtration for combined-cycle and peaking power plants. Nanofiber surface layers extend service intervals in desert and coastal environments.
- Construction:Mobile dust collectors for silica-generating activities at demolition and concrete cutting sites.
Automotive anchors replacement parts volume while energy sector specifications drive technology upgrading.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical cleanrooms demand HEPA terminal filtration with redundant stages, while US metalworking facilities prioritize silica-compliant baghouse retrofits over energy efficiency. Chinese semiconductor fabs specify chemical filtration modules with extended service intervals. India's bulk drug clusters under CDSCO-PIC/S alignment are constructing ISO 14644-1 classified suites from scratch.
United States
OSHA silica rule enforcement compels cement and foundry operators to upgrade cartridge collectors in Texas and California non-attainment zones. EPA National Ambient Air Quality Standards revisions tighten PM2.5 thresholds ahead of state implementation deadlines. Houston-area petrochemical complexes are installing corrosion-resistant media upstream of carbon capture absorber columns.
Germany
Automotive paint shops in Stuttgart specify PTFE membrane media for moisture-resistant overspray collection under REACH-compliant formulations. Freudenberg's captive nanofiber production in Weinheim supplies premium media for energy sector turbine specifications. Bavarian combined-cycle plants are converting inlet systems from meltblown to electrospun surfaces for extended desert-environment service intervals.
China
MIIT carbon neutrality targets accelerate amine-based post-combustion filtration demand in Yangtze River Delta power generation clusters. GB standards for industrial emissions tighten particulate discharge limits for steel and cement producers. Shanghai semiconductor fabrication facilities are specifying activated carbon impregnates for molecular contaminant control in wafer processing suites.
India
CDSCO alignment with PIC/S standards mandates continuous airborne particle monitoring in Hyderabad and Ahmedabad bulk drug manufacturing corridors. BIS certification requirements for cleanroom equipment are accelerating domestic filter assembly capacity. Telangana's pharmaceutical cluster is constructing H14-grade terminal filtration infrastructure for export-oriented sterile API production.
Japan
METI energy efficiency directives drive turbine inlet upgrades at combined-cycle facilities in Chubu and Kansai industrial belts. JIS standards for HEPA filtration govern pharmaceutical aseptic processing in Osaka-based biologics manufacturing. Nagoya-area automotive OEMs are negotiating enterprise service contracts with guaranteed uptime metrics replacing unit-volume procurement.
Industrial Air Filtration Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in industrial air filtration supply. Captive media producers command premium positioning through in-house nanofiber production, while commodity assemblers compete on logistics reach and aftermarket service density. Two strategic archetypes dominate: vertically integrated chemical conglomerates with polymer R&D capabilities, and regional fabricators focused on bag and cartridge replacement cycles. Competitive moves concentrate on backward integration into electrospun media production and multi-site service contracting with predictive maintenance algorithms.
Among Germany-based integrated suppliers, Mann+Hummel and Freudenberg Filtration Technology exemplify the captive-production archetype spanning automotive and industrial verticals. Donaldson Company occupies a position within North American aftermarket distribution networks for metalworking dust collection. These three anchors illustrate how geographic concentration of polymer science expertise in German technical institutes and Midwestern US manufacturing corridors shapes competitive returns across membrane technology tiers.
| Leading Market Players |
|---|
| Mann+Hummel |
| Freudenberg Filtration Technology |
| Camfil |
| Honeywell International |
| AAF International |
| Donaldson Company |
| Cummins Filtration |
| Filtration Group Corporation |
| Parker Hannifin |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between German nanofiber producers and energy sector turbine operators lock in both electrospun media supply and price visibility across multi-year service intervals, insulating integrated manufacturers from coconut shell charcoal volatility while exposing commodity assemblers to spot market fluctuations.
Pricing Analysis
Project-based contracting dominates pharmaceutical cleanroom installations, with HEPA filter procurement tied to facility validation timelines rather than unit transactions. Price differentiation hinges on EN 1822 certification grade and captive media production, with Mann+Hummel and Freudenberg commanding premiums through in-house electrospinning capacity. Cost compression in bag filter tiers is intensifying because OSHA silica enforcement accelerates replacement cycles without proportional efficiency gains. Metalworking maintenance managers exhibit highest price sensitivity, while pharmaceutical quality engineers prioritize guaranteed uptime over unit cost.
Supply Chain Analysis
Germany and Switzerland anchor electrospun nanofiber production, feeding premium media specifications for energy sector turbine inlets and pharmaceutical terminal filtration. Raw material flows draw from Southeast Asian coconut shell charcoal for activated carbon impregnates, P84 polyimide from European chemical conglomerates, and glass microfiber from specialized meltblown operations. Single-source vulnerability concentrates in electrospinning technician labor pools trained at German and Swiss technical institutes. Distribution runs through multi-site service contracts with predictive maintenance algorithms displacing transactional spare parts purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as nanofiber media displaces conventional meltblown across energy and pharmaceutical applications, threatening margin structures for assemblers without captive polymer R&D capabilities.
For Market Incumbents: Fortify backward integration into electrospun media production to escape commodity pricing traps in bag filter tiers. Expand capacity reservation agreements with Hyderabad and Ahmedabad bulk drug clusters before CDSCO-PIC/S alignment saturates cleanroom construction demand. Nanofiber adoption curves threaten meltblown-dependent product lines without upstream polymer science investment. For New Entrants and Emerging Players: Anchor in India's pharmaceutical manufacturing corridor where domestic filter assembly capacity lags behind CDSCO regulatory mandates. Target carbon capture co-location opportunities in Texas and California petrochemical complexes requiring corrosion-resistant media specifications. Pursue Filter-as-a-Service models with pressure differential monitoring to bypass established aftermarket distribution networks. For Investors and Strategic Acquirers: Captive nanofiber producers with pharmaceutical qualification pathways represent the highest-conviction acquisition archetype in this sector. Long-term viability rests on polymer R&D depth and regulatory certification moats rather than manufacturing scale alone. Watch EN 1822 testing protocol harmonization with IEST-RP-CC001 as inflection signal for redundant validation cost elimination.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nanofiber Production | Captive electrospinning capacity insulates margins from input bottlenecks among European chemical conglomerates. |
| Filter-as-a-Service Model Deployment | Predictive maintenance algorithms with automated reorder triggers displace transactional spare parts purchasing in German automotive corridors. |
| Pharmaceutical Certification Investment | EN 1822 H14 qualification opens aseptic processing suites in Basel and Boston to terminal filtration suppliers. |
| Carbon Capture Co-Location Partnership | Amine-resistant media specifications upstream of absorber columns create adjacent demand in Houston petrochemical complexes. |
| India Cleanroom Construction Alignment | CDSCO-PIC/S standards compliance accelerates HEPA infrastructure demand in Hyderabad bulk drug clusters. |
Methodological Framework
A standing panel of plant engineers, maintenance directors at multi-site industrial operators, OEM procurement teams, and aftermarket service heads provided ongoing calibration across primary interview rounds. Secondary validation drew from OSHA enforcement databases, EPA National Ambient Air Quality Standards filings, FDA cGMP Annex 1 revision documents, and customs trade records for filter media imports. Bottom-up unit economics triangulated against top-down sector spend estimates to anchor volume and value outputs.
Consistency checks against external benchmarks validated projections across the analysis window, with segmentation modeling spanning product type, application technology, and end-user procurement sophistication. CAGRs were derived from installed base turnover rates, replacement cycle compression under regulatory enforcement, and technology substitution curves in nanofiber adoption. Forecast inputs incorporated OSHA silica rule implementation timelines, CDSCO-PIC/S alignment progress in Indian pharmaceutical clusters, and MIIT carbon neutrality targets in Chinese power generation.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement intensity and nanofiber cost parity achievement; material deviation in electrospinning capacity expansion or coconut shell charcoal supply disruption would warrant model refresh. Recalibration cycles align with material shifts in OSHA enforcement patterns, FDA cGMP revision implementation, and carbon capture project development velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Filter Media Market
Filters
Fabric Filters Market
Filters
High Purity Chemical Filters Market
Filters
Intake Filter Media Market
Filters
Filter Coatings Market
Filters
Global Depth Filtration Market
Filters
Industrial Filter Paper Market
Filters
Canada Filtration and Separation Market
Filters
Filter Bag Market
Filters
Global Liquid Filtration Market
Filters
High-Efficiency Particulate Air (HEPA) Filters Market
Filters
Global Laboratory Filtration Market
Filters
Global Cartridge Filters Market
Filters
United States Activated Carbon Market
Filters
Global Filter Market
Filters
Compact Filters Market