
 Homopolymer Acrylic Filter Bags Market | 2026-2036
Homopolymer Acrylic Filter Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Homopolymer Acrylic Filter Bags Market Analysis
Asset-light leasing models for filtration systems are reshaping competitive dynamics in the homopolymer acrylic filter bags sector. Donaldson Company Inc leverages its rental-service infrastructure to capture recurring revenue from cement and power clients. BWF Protec anchors European supply through backward integration into needle-punched nonwoven production. Zonel Filtech specializes in cost-optimized acrylic formulations for China's mid-tier industrial operators.
Homopolymer acrylic filter bags are woven or nonwoven media fabricated from 100% polyacrylonitrile fibers, typically rated for continuous operating temperatures of 125-140°C with hydrolysis resistance in moist flue gas environments. These bags capture particulate matter in pulse-jet and reverse-air baghouse systems across coal combustion, cement kiln, and metallurgical processes. The air filtration application dominates volume due to stationary source emission controls, while dust collection for cement and power generation commands the strongest margin pools. Liquid filtration represents a smaller but expanding segment as chemical processors adopt acrylic media for corrosive effluent treatment. The industrial end-user segment sustains the largest installed base, though water treatment utilities are emerging as a faster-growing buyer category.
EPA Maximum Achievable Control Technology standards and China's MEE emission enforcement are tightening particulate limits for coal-fired boilers and cement kilns, directly expanding replacement demand for certified filter media. REACH compliance in Europe restricts certain chemical treatments used in fiber finishing, pushing manufacturers toward certified acrylic formulations. Stakeholders must monitor regulatory divergence between jurisdictions to align product certification portfolios with import requirements and avoid stranded inventory in cross-border supply chains.
Market Dynamics
Emission enforcement across coal-dependent economies is compressing replacement cycles for filter media, forcing asset owners to prioritize certified acrylic formulations over lower-grade alternatives in high-temperature baghouse applications.
Growth Catalysts
- MEE particulate limits:China's Ministry of Ecology and Environment mandates sub-10mg/Nm³ stack emissions for coal-fired boilers, accelerating filter bag replacement in Shandong and Jiangsu industrial clusters.
- Cement kiln retrofits:Indian cement producers are expanding procurement of hydrolysis-resistant acrylic media as BIS emission norms tighten for particulate matter capture.
- Pulse-jet optimization:Advanced cleaning cycle algorithms extend acrylic bag service life in reverse-air systems, improving total cost of ownership for metallurgical processors.
Market Restraints
- Acrylonitrile price volatility:Feedstock costs for PAN fiber production fluctuate with crude oil derivatives, compressing margin stability for nonwoven manufacturers.
- Polytetrafluoroethylene substitution:PTFE membrane laminates capture premium applications above 150°C operating thresholds, displacing acrylic in ultra-high-temperature niches.
- REACH chemical restrictions:ECHA limitations on certain fiber-finishing treatments force reformulation costs for European suppliers seeking CE-marked product lines.
Strategic Opportunities
- Water treatment utilities:Chemical processors in Germany and the Netherlands are adopting acrylic media for corrosive effluent filtration, expanding beyond traditional air applications.
- Asset-light leasing:Rental-service infrastructure for filtration systems creates recurring revenue streams from cement and power clients seeking to avoid capital deployment.
- India PLI scheme:Production-linked incentives for domestic manufacturing of industrial components reduce import dependency for filter media in emission-control equipment.
Industry Challenges
- Certification timeline compression:Multi-jurisdiction product approval requirements for EPA, MEE, and BIS standards strain quality assurance bandwidth.
- Needle-punching skill scarcity:Specialized nonwoven fabrication expertise concentrates in European and Chinese manufacturing hubs, limiting geographic diversification of production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Homopolymer Acrylic Filter Bags Market |
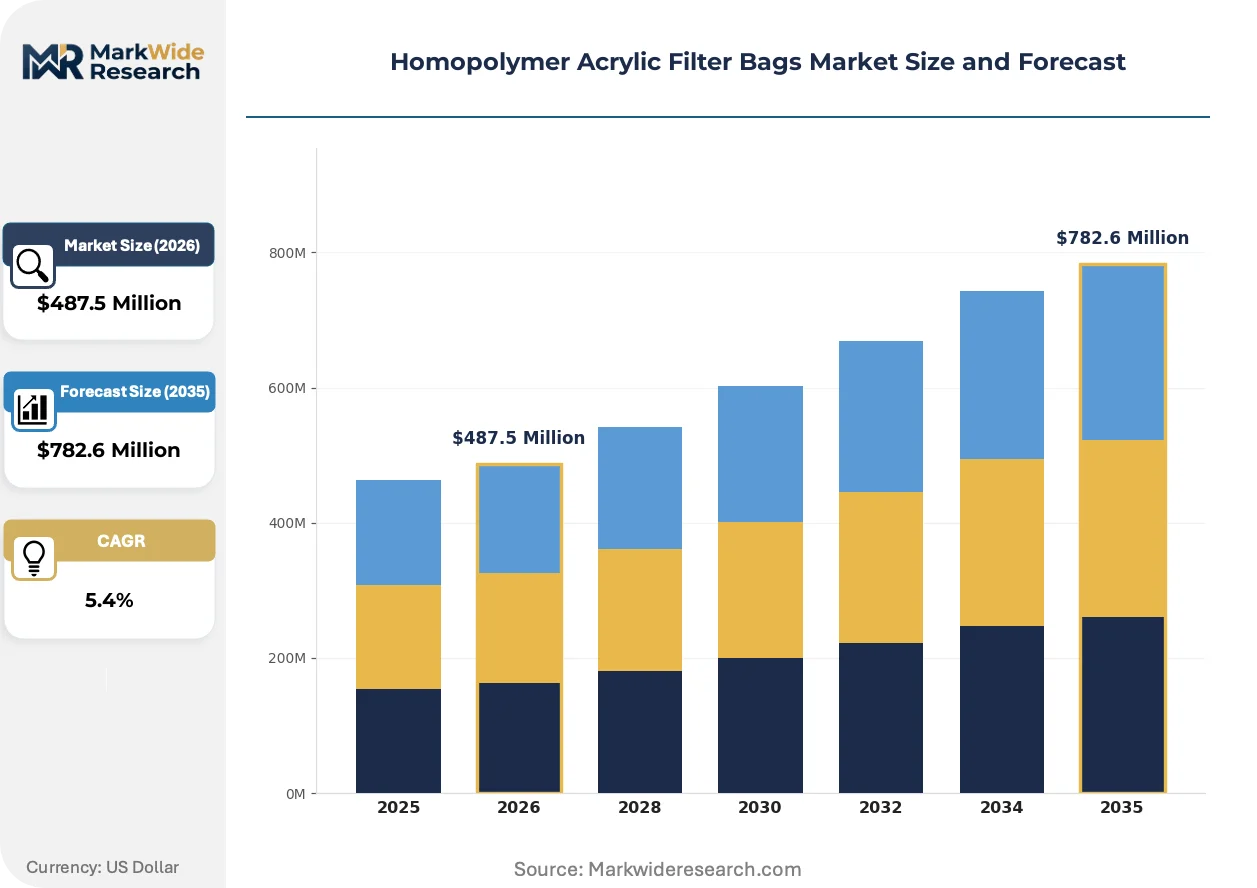
| Market Size in 2026 | $487.5 Million |
| Market Size in 2035 | $782.6 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Nylon, PP, Acrylic Application: Liquid Filtration, Air Filtration, Dust Collection, Chemical Processing End User: Industrial, Automotive, Water Treatment, Food & Beverage Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | SLY Inc, Amrit Filter, Donaldson Company Inc, Filtration Group Corporation, Ahlstrom-Munksjö, W. L. Gore & Associates, Zonel Filtech, BWF Protec, HL Filter USA LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Homopolymer Acrylic Filter Bags Market Emerging Trajectories
Digital integration of filtration asset management is converging with stricter emission verification protocols, reshaping how operators specify, monitor, and replace acrylic filter media across industrial baghouse systems.
Smart sensor-embedded filter bags are digitizing condition monitoring in pulse-jet systems. Cement plants in India and coal-fired facilities in China are piloting these installations to predict pressure-drop degradation. The technology is digitizing maintenance scheduling, compressing unplanned downtime windows while extending certified service intervals.
EPA Maximum Achievable Control Technology standards are tightening particulate limits for coal combustion sources. Stationary source operators must now document continuous compliance through stack monitoring systems. Coal-fired boiler segments in the United States are responding by specifying pre-certified acrylic formulations with validated hydrolysis resistance ratings.
Leasing models for complete filtration systems are displacing traditional capital purchase patterns. Cement and power generation buyers in China and India increasingly prefer operational expenditure structures over equipment ownership. This shift concentrates procurement authority with service providers who standardize on specific acrylic bag specifications across fleet deployments.
Homopolymer Acrylic Filter Bags Market Segmentation
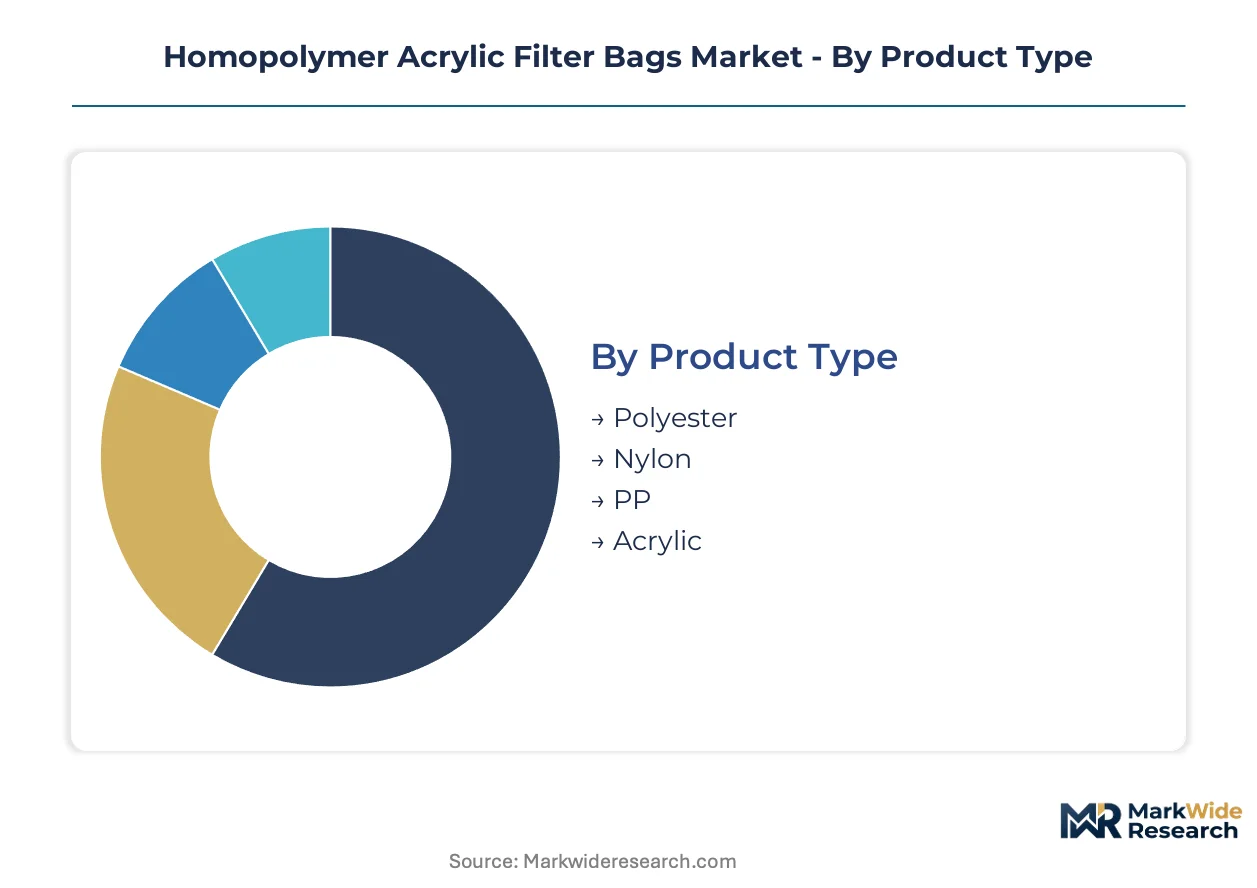
Homopolymer acrylic filter bags serve distinct operational environments where temperature thresholds, chemical exposure, and particulate loading dictate media specification. Procurement patterns diver sharply between capital-intensive industrial installations and maintenance-driven replacement cycles. Understanding these segment boundaries clarifies where formulation investments yield margin protection versus volume capture.
Product Type:
Material selection traces directly to thermal performance requirements and hydrolysis resistance in moist flue gas conditions.
- Acrylic:Continuous operating temperature ratings of 125-140°C with inherent hydrolysis resistance define this homopolymer construction. Coal-fired power retrofits in Shandong and Jiangsu provinces specify certified acrylic media as MEE particulate limits tighten replacement cycles.
- Polyester:Lower-cost synthetic fiber rated for 130-150°C dry applications dominates bulk commodity dust collection where moisture exposure remains minimal. Indian cement plants under BIS emission pressure increasingly specify hydrolysis-stabilized grades for kiln exhaust applications.
- Nylon:High tensile strength and abrasion resistance suit mechanical filtration with repeated flexing cycles. Abrasive dust environments in metallurgical processing favor nylon needle-punched constructions for extended service intervals.
- PP:Polypropylene media operate below 90°C with excellent chemical resistance to acids and alkalis. Chemical processing effluent treatment in German and Dutch facilities adopts PP for corrosive liquid filtration where thermal loads remain moderate.
The dominant share belongs to Acrylic, while PP is closing the gap fastest through chemical processing diversification.
Application:
Functional deployment separates stationary source emission control from process fluid treatment, with distinct certification and replacement economics.
- Air Filtration:Pulse-jet and reverse-air baghouse systems for industrial exhaust streams constitute the installed base volume. EPA Maximum Achievable Control Technology standards mandate validated hydrolysis resistance ratings for coal combustion sources.
- Dust Collection:Cement kiln and metallurgical process capture commands premium margin pools due to high-temperature operating windows and abrasive particulate loading. Indian cement producers expanding procurement drive specification intensity in this segment.
- Liquid Filtration:Corrosive effluent treatment in chemical processing represents a smaller but expanding application category. Water treatment utilities in Germany and the Netherlands are adopting acrylic media for aggressive chemical environments.
- Chemical Processing:Specialized media configurations handle reactive process streams with customized surface treatments. REACH compliance restrictions on fiber-finishing chemicals force reformulation investments for European supply.
Air Filtration retains volume leadership, though Liquid Filtration is expanding most quickly through utility sector adoption.
End User:
Buyer sophistication and procurement authority vary dramatically between owner-operated industrial facilities and outsourced utility service models.
- Industrial:Cement, power generation, and metallurgical operations sustain the largest installed base with direct procurement of certified media. Asset-light leasing models are displacing capital purchase patterns among Chinese and Indian operators.
- Water Treatment:Municipal and industrial utility buyers are emerging as faster-growing category through chemical effluent treatment adoption. Procurement concentrates with service providers who standardize specifications across fleet deployments.
- Automotive:Paint booth and manufacturing facility ventilation applications require consistent media performance with predictable replacement scheduling. OEM supplier qualification processes emphasize batch-to-batch specification stability.
- Food & Beverage:Hygienic processing environments demand FDA-compliant fiber grades with migration testing documentation. Application scope remains narrower due to temperature limitations and regulatory compliance burden.
Industrial end users command current procurement volume, while Water Treatment is gaining share fastest through utility outsourcing trends.
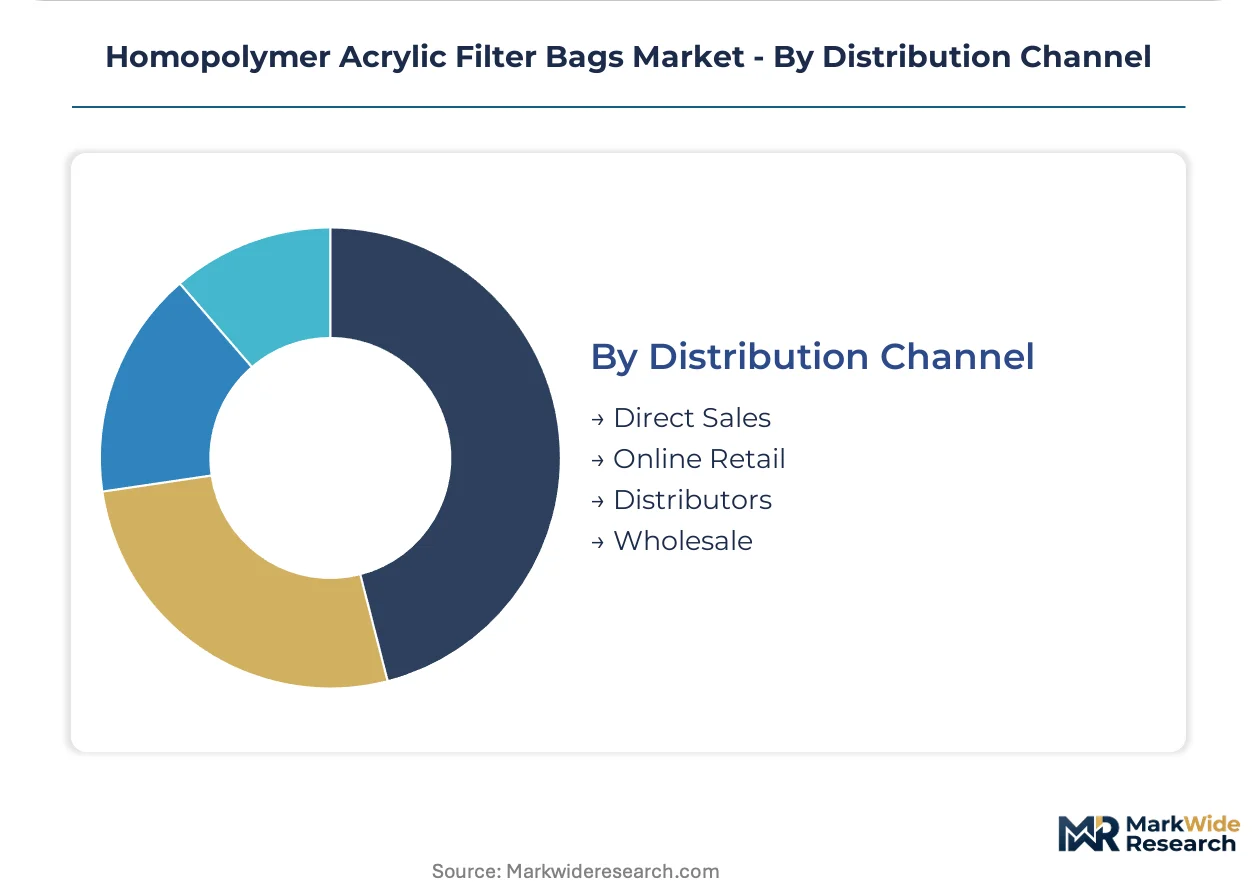
Distribution Channel:
Channel selection reflects transaction scale, technical specification complexity, and geographic proximity to manufacturing concentration.
- Direct Sales:Large-volume industrial accounts negotiate multi-year supply agreements with certified manufacturers. Technical service integration including baghouse optimization and predictive maintenance locks in specification authority.
- Distributors:Regional inventory positioning serves mid-tier operators with fragmented demand and emergency replacement requirements. European supply chains concentrate distributor networks around needle-punching manufacturing hubs.
- Wholesale:Bulk commodity grades move through wholesale channels for non-critical applications with standardized specifications. Price transparency compresses margin capture in this channel tier.
- Online Retail:Small-quantity procurement for maintenance departments and secondary system support operates through digital platforms. Specification risk concentrates where technical validation remains limited.
Direct Sales anchors revenue concentration, while Distributors are climbing the fastest through regional service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in acrylic fiber feedstocks are redirecting procurement strategies toward regional manufacturing clusters. Countries with backward-integrated needle-punching capacity capture margin pools that import-dependent markets forfeit to logistics costs.
China
Shandong and Jiangsu provinces host the densest concentrations of coal-fired power retrofit activity. MEE enforcement of sub-10mg/Nm³ stack emissions compresses filter replacement cycles to 18-24 months. Qingdao-based fabricators supply certified acrylic media to domestic cement and metallurgical operators under GB standards compliance.
India
Cement kiln expansions in Rajasthan and Madhya Pradesh drive specification intensity for hydrolysis-resistant media. BIS emission norms for particulate matter tighten procurement standards beyond legacy polyester alternatives. The PLI scheme for industrial component manufacturing incentivizes domestic filter media production to reduce import dependency.
Germany
Chemical processors in the Rhine-Ruhr and Bavarian industrial corridors adopt acrylic media for corrosive effluent treatment. REACH restrictions on fiber-finishing chemicals force reformulation investments for CE-marked product lines. Stuttgart-area engineering firms integrate predictive maintenance algorithms into baghouse system contracts.
United States
EPA Maximum Achievable Control Technology standards mandate validated hydrolysis resistance for coal combustion sources. Ohio River Valley power operators specify pre-certified acrylic formulations with documented continuous compliance. Texas Gulf Coast petrochemical complexes expand procurement for moist flue gas applications.
Netherlands
Water treatment utilities in Rotterdam and Eindhoven industrial zones pioneer acrylic media adoption for aggressive chemical environments. Port of Antwerp-Rotterdam-Amsterdam logistics hubs position distributors for emergency replacement inventory across Benelux cement operations. ECHA chemical restrictions align with domestic sustainability procurement criteria.
Homopolymer Acrylic Filter Bags Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in needle-punched nonwoven fabrication. The vendor base stratifies between full-service filtration system providers and material-focused fabricators. Three archetypes dominate: asset-light leasing operators, backward-integrated European suppliers, and cost-optimized Asian specialists. Competitive moves concentrate on rental-service infrastructure expansion and regional distributor network consolidation.
Among North American platform integrators, Donaldson Company Inc and Filtration Group Corporation exemplify the asset-light service model. SLY Inc occupies a position within the component specialist tier. European supply chains anchor through BWF Protec and Ahlstrom-Munksjö, representing backward-integrated fabrication archetypes. Zonel Filtech sits within the Asia-Pacific cost-optimization segment. W. L. Gore & Associates anchors premium membrane laminate applications above standard acrylic temperature thresholds.
| Leading Market Players |
|---|
| SLY Inc |
| Amrit Filter |
| Donaldson Company Inc |
| Filtration Group Corporation |
| Ahlstrom-Munksjö |
| W. L. Gore & Associates |
| Zonel Filtech |
| BWF Protec |
| HL Filter USA LLC |
| Others |
Supply Flow & Price Mechanics
Shandong province's needle-punching capacity concentration grants domestic fabricators pricing leverage over import-dependent buyers in India and Southeast Asia. This geographic supply asymmetry compresses margin pools for distributors while cementing cost advantages for backward-integrated operators serving MEE-compliant coal power retrofits.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation tracks certification grade against EPA, MEE, and BIS standards alongside volume scale commitments in multi-year offtake agreements. Pricing pressure stems from acrylonitrile feedstock volatility tied to crude oil derivatives, squeezing nonwoven manufacturers without captive PAN fiber supply. Mid-tier cement operators in India's Rajasthan cluster exhibit highest price sensitivity, while German chemical processors prioritize validated hydrolysis resistance over unit cost.
Supply Chain Analysis
Acrylonitrile monomer supply draws from petrochemical complexes in China, South Korea, and the United States. Raw material dependencies center on PAN fiber precursor, specialized needle-punching equipment, and REACH-compliant fiber-finishing chemicals. Supply chain risk concentrates in single-source vulnerability for high-tenacity acrylic staple fiber rated above 3.0 denier. Distribution runs through direct sales channels for large-volume industrial accounts and regional distributor networks serving emergency replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized needle-punching expertise concentrates in European and Chinese manufacturing hubs, constraining geographic diversification of homopolymer acrylic filter bag production. This capability scarcity amplifies returns for operators who control certified fabrication assets.
For Market Incumbents: Build switching-cost moats through predictive maintenance algorithm integration into baghouse service contracts. Cement and power clients in China and India increasingly outsource filtration asset management, concentrating procurement authority with service providers. Defend against PTFE membrane substitution in ultra-high-temperature niches by extending certified acrylic temperature ratings through advanced fiber finishing. Prioritize backward integration into PAN fiber production to insulate margin from acrylonitrile volatility. For New Entrants and Emerging Players: India's water treatment utility sector offers underpenetrated white-space as chemical effluent treatment adoption accelerates. Municipal procurement in Gujarat and Tamil Nadu industrial corridors favors service-based models over capital equipment ownership. Target mid-tier metallurgical processors in Vietnam and Indonesia with cost-optimized acrylic formulations below European certification tiers. Establish distributor partnerships with regional inventory positioning to capture emergency replacement demand outside Shandong-Jiangsu supply clusters. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors asset-light leasing operators with recurring revenue visibility from cement and power fleet deployments. Long-term viability hinges on regulatory enforcement durability across coal-dependent economies rather than breakthrough filtration technology. Acquisition targets should demonstrate validated MEE, EPA, and BIS certification portfolios with established technical service integration. Monitor MEE particulate limit revision announcements as the primary inflection signal for replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PAN Fiber | Captive acrylonitrile supply insulates margin from petrochemical volatility affecting Shandong fabricators. |
| Predictive Maintenance Algorithm Development | Smart sensor integration extends certified service intervals for Indian cement plant deployments. |
| Regional Distributor Network Consolidation | Emergency inventory positioning captures replacement cycles compressed by MEE enforcement timelines. |
| Water Treatment Utility Service Contracts | Rotterdam and Eindhoven municipal adoption creates recurring revenue beyond traditional air applications. |
| Multi-Jurisdiction Certification Investment | Simultaneous EPA, MEE, and BIS approval reduces stranded inventory risk in cross-border supply chains. |
Methodological Framework
Operator-level perspectives from plant maintenance directors, OEM procurement leads, baghouse system engineers, and regional distribution channel partners anchored the qualitative base. These primary insights combined with secondary validation from EPA MACT enforcement records, MEE emission compliance databases, BIS certification registries, and customs trade flow data. Bottom-up demand modeling triangulated against top-down market sizing across product type, application, end user, and distribution channel dimensions.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeling spanning material grade tier, emission control application, industrial versus utility buyer archetype, and regional regulatory cluster. CAGRs derived from replacement cycle analysis tied to enforcement intensity in coal power and cement kiln segments. Forecast inputs incorporated acrylonitrile price trajectory assumptions and needle-punching capacity expansion timelines in China and India.
The forecast holds incumbent behavior within observed patterns; aggressive moves by PTFE membrane laminate specialists or asset-light filtration service platforms would shift outcomes. Cross-checking against MEE particulate limit enforcement statistics and Indian PLI scheme disbursement rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Aerospace Filter Market
Filters
Fabric Filter System Market
Filters
Round Plate Filter Press Market
Filters
Filter Bag Market
Filters
Global Sterile Filtration Market
Filters
Global Tangential Flow Filtration Market
Filters
GCC Industrial Air Filtration Market
Filters
Global Cartridge Filters Market
Filters
Single-Use Filtration Assemblies Market
Filters
Global Lamella Clarifier Market
Filters
Diatomaceous Filter Aid Market
Filters
Fabric Filters Market
Filters
Canada Filtration and Separation Market
Filters
Industrial Air Filtration Market
Filters
Filtration and Separation Market
Filters
Coolant Filtration Skids Market