
 Filtration and Separation Market | 2026-2036
Filtration and Separation Market Size, Share, and Industry Trends Forecast 2026-2036
Filtration and Separation Market Analysis
OEM-direct procurement for industrial filtration systems is tilting toward integrated solution providers. Parker-Hannifin Corporation leverages its Motion Systems division to bundle filtration with fluid power equipment, locking in multi-year service contracts. MANN+HUMMEL anchors European automotive and industrial air filtration through captive R&D centers in Germany and China. Donaldson Company, Inc. specializes in ruggedized dust collection and engine intake systems for mining and agriculture, competing on field durability rather than price.
Filtration and separation encompasses mechanical, membrane, and electrostatic processes that remove particulates, microorganisms, or dissolved contaminants from fluid or gas streams, typically achieving retention ratings from 0.1 microns in membrane systems to 100+ microns in coarse bag filters. The primary commercial purpose centers on protecting downstream equipment, ensuring product purity, and enabling regulatory compliance across process industries. Membrane filters command premium positioning in biopharmaceutical sterile processing, where integrity-testable polyethersulfone and PVDF layers justify unit costs tenfold above depth filter alternatives. Ultrafiltration and reverse osmosis systems in water treatment applications are displacing conventional chemical clarification as municipalities face stricter effluent limits on dissolved solids and emerging contaminants.
The EPA enforces Maximum Contaminant Level Goals under the Safe Drinking Water Act, forcing municipal end users to upgrade aging granular media plants with membrane bioreactor technology. REACH and the EU Green Deal restrict per- and polyfluoroalkyl substances in membrane chemistries, compelling manufacturers like 3M Company and Pall Corporation to reformulate hydrophobic coatings. China's MEE implements discharge permit trading for industrial wastewater, tightening enforcement in the Yangtze River Economic Belt. ISO 13408 and FDA sterilization validation requirements for pharmaceutical filtration create barrier-to-entry moats around validated membrane suppliers. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance costs for multi-plant operators will widen competitive gaps between regionally focused and globally integrated suppliers.
Market Dynamics
Membrane bioreactor technology is displacing conventional granular media filtration as municipalities confront tightening effluent standards on dissolved solids and emerging contaminants, forcing wholesale plant upgrades across aging infrastructure bases.
Growth Catalysts
- EPA Clean Water Act Enforcement:Maximum Contaminant Level Goals under the Safe Drinking Water Act compel municipal operators to replace legacy clarification systems with membrane-based purification, accelerating equipment replacement cycles in US water treatment facilities.
- India's Pharmaceutical Manufacturing Corridors:Sterile filtration capacity is expanding rapidly around Hyderabad and Ahmedabad as domestic drug production scales to serve export markets, driving demand for integrity-testable polyethersulfone membrane systems.
- China's GB Standards for Industrial Wastewater:The Ministry of Ecology and Environment implements stricter discharge permit trading in the Yangtze River Economic Belt, compelling chemical and textile processors to install ultrafiltration and reverse osmosis systems.
Market Restraints
- PVDF and Polyethersulfone Raw Material Concentration:Specialty polymer supply chains concentrate among a limited cohort of chemical manufacturers, exposing membrane producers to input cost volatility and qualification delays for alternative formulations.
- REACH and EU Green Deal Restrictions:Per- and polyfluoroalkyl substance limitations in membrane chemistries compel manufacturers to reformulate hydrophobic coatings, extending R&D timelines and raising compliance costs for European market access.
- Granular Media Substitution Persistence:Conventional sand and anthracite filtration retains cost advantages in coarse particulate removal applications above 10 microns, limiting membrane penetration in budget-constrained municipal segments.
Strategic Opportunities
- Indonesia's Untreated Industrial Effluent:Textile and palm oil processing clusters around Jakarta and Surabaya lack adequate wastewater infrastructure, creating first-mover advantages for membrane system providers offering build-operate-transfer models.
- ISO 13408 Validation Services:Pharmaceutical filtration creates barrier-to-entry moats around validated membrane suppliers, enabling premium positioning for firms offering integrated integrity testing and regulatory documentation packages.
- Electrostatic-Mechanical Hybrid Systems:Convergence of electrostatic precipitation with bag filtration addresses sub-micron particulate capture in metalworking and powder coating applications, opening industrial air treatment segments previously served by single-technology solutions.
Industry Challenges
- Membrane Integrity Testing Certification:FDA sterilization validation requirements demand specialized technical personnel for bubble point and diffusion testing protocols, constraining deployment speed for biopharmaceutical filtration projects.
- Legacy Plant Retrofit Integration:Municipal water treatment facilities built in the 1970s-1980s require extensive civil works modifications to accommodate membrane bioreactor footprints, compressing project margins and extending commissioning timelines.
- Cross-Jurisdictional Compliance Divergence:Multi-plant operators face widening cost structures as EPA, ECHA, and China's MEE impose non-harmonized substance restrictions and testing protocols, fragmenting product portfolios and inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Filtration and Separation Market |
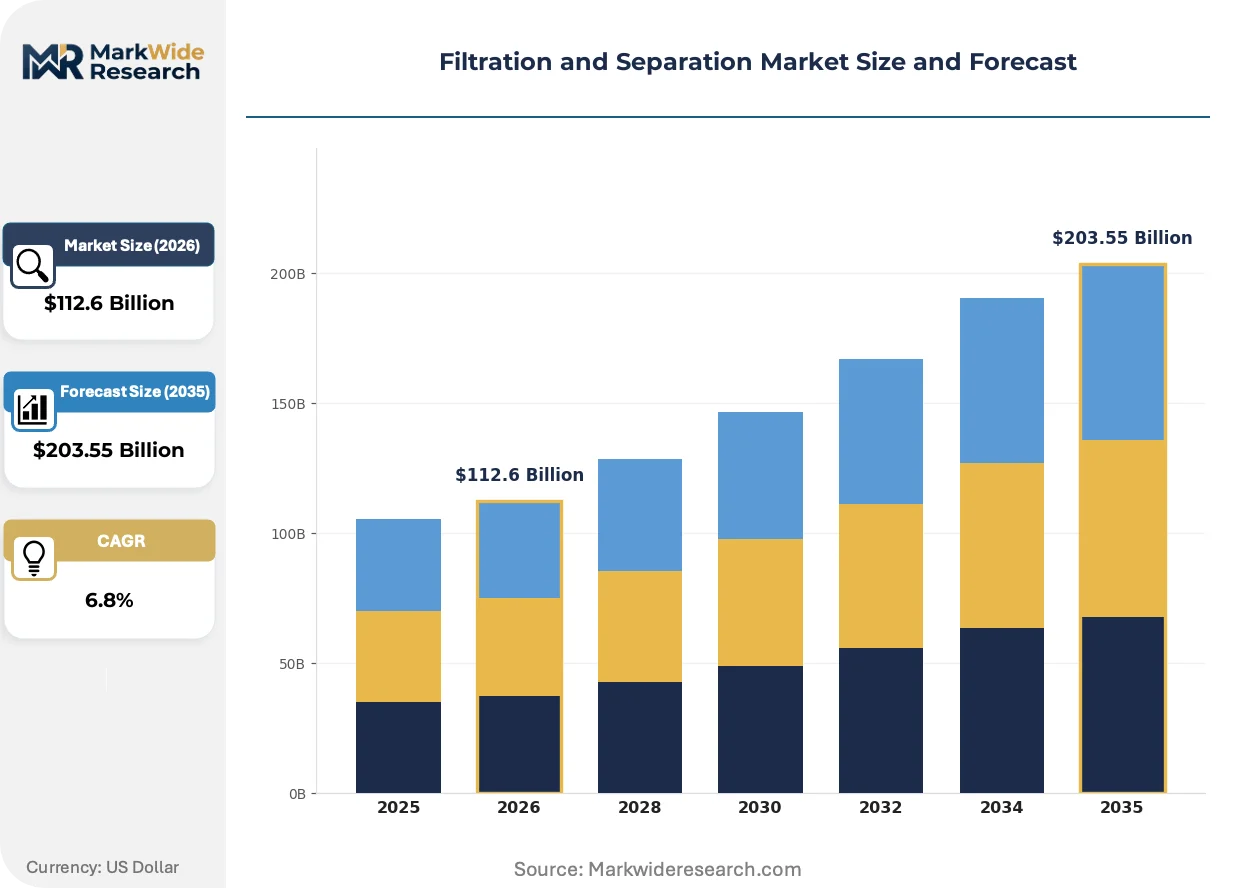
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $203.55 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Filters, Depth Filters, Cartridge Filters, Bag Filters Application: Water Treatment, Air Purification, Chemical Processing, Food & Beverage Technology: Microfiltration, Ultrafiltration, Reverse Osmosis, Nanofiltration End User: Pharmaceuticals, Oil & Gas, Manufacturing, Municipalities |
| Companies Covered | Parker-Hannifin Corporation, Eaton Corporation, 3M Company, Pall Corporation, Donaldson Company, Inc., MANN+HUMMEL, Alfa Laval AB, GEA Group AG, Pentair Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Filtration and Separation Market Emerging Trajectories
Digital twin technology is virtualizing filtration system design and predictive maintenance protocols, compressing commissioning cycles and enabling remote performance optimization across distributed municipal and industrial installations.
Computational fluid dynamics coupled with machine learning algorithms is virtualizing filter media configuration testing, allowing manufacturers to simulate pressure drop and retention efficiency across variable flow conditions without physical prototyping. Municipal engineering consultants in Germany and the Netherlands are adopting these tools to shorten design validation phases. The structural consequence is a compression in R&D expenditure recovery timelines, favoring firms with captive simulation capabilities over traditional empirical testing approaches.
REACH authorization requirements for perfluorinated compounds are forcing membrane manufacturers to accelerate hydrophobic coating reformulation programs, with ECHA's 2023 restriction proposals targeting PTFE-based vent filters used in sterile pharmaceutical processing. European biopharma manufacturers are responding by qualifying alternative polyvinylidene fluoride membranes and demanding supplier transparency on fluorine content across entire bill-of-materials structures.
Equipment-as-a-service contracting is displacing capital purchase models in North American industrial water treatment, with chemical processors preferring per-cubic-meter pricing tied to guaranteed effluent quality outcomes. This shift concentrates vendor risk on performance uptime and membrane replacement scheduling. The pattern is most visible in Texas and Louisiana petrochemical corridors, where integrated water management contracts now bundle filtration with chemical feed and residual handling services.
Filtration and Separation Market Segmentation
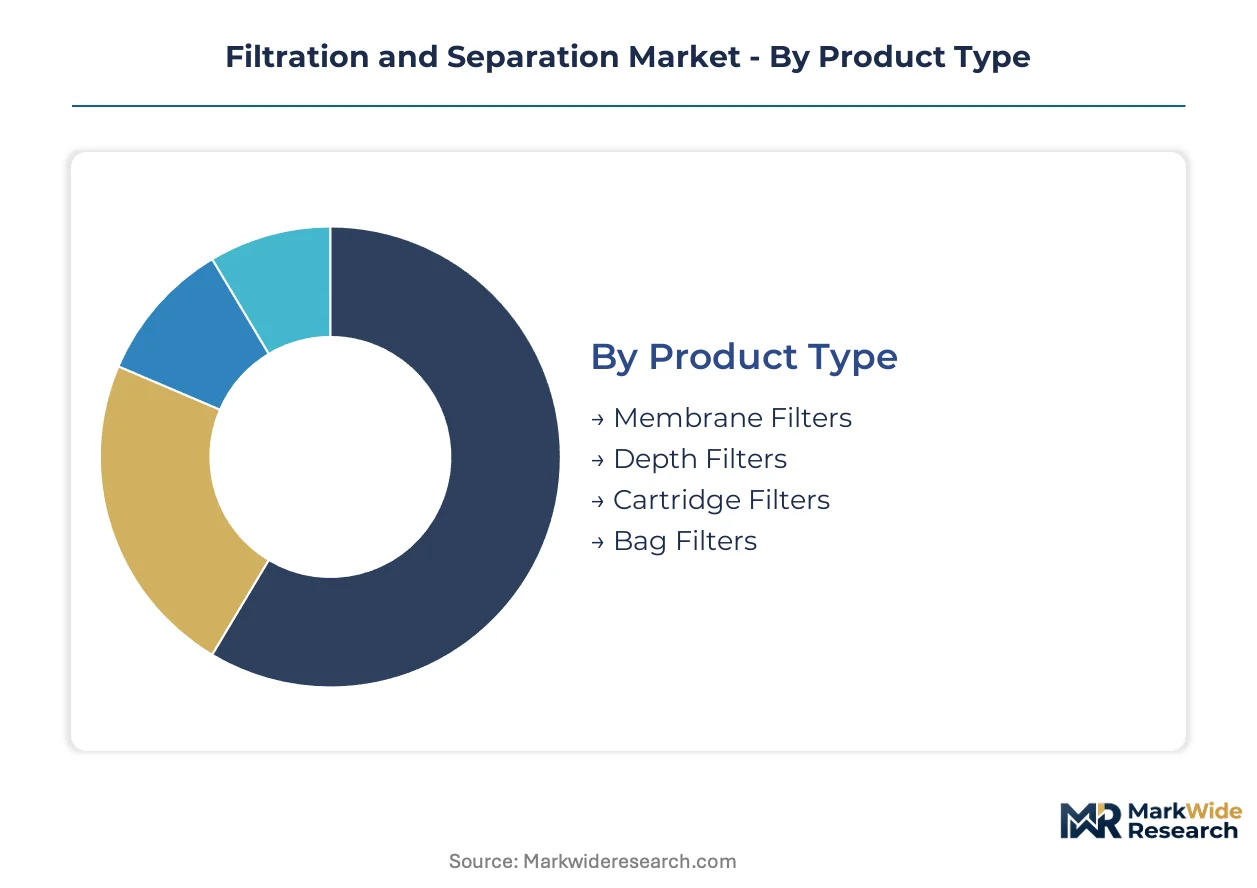
Segmentation in filtration and separation reflects divergent performance requirements across purity thresholds, flow rates, and regulatory validation levels. Product architecture, application environment, and end-user compliance burden collectively determine supplier positioning and margin structure.
Product Type:
Cost tier stratification separates premium membrane systems from commodity depth and bag alternatives, with qualification requirements driving purchasing behavior.
- Membrane Filters:Polyethersulfone and PVDF layers achieve sub-micron retention with integrity-testable performance, commanding tenfold premiums over depth alternatives in biopharmaceutical sterile processing. Demand concentrates in India's pharmaceutical corridors around Hyderabad and Ahmedabad, where export-oriented drug production mandates validated sterile filtration capacity.
- Depth Filters:Graded-density cellulose and diatomaceous earth matrices capture coarse particulates above 1 micron through tortuous path mechanisms, serving as pre-filters to protect downstream membrane systems. Municipal water treatment operators in the US deploy these for cost-effective clarification ahead of ultrafiltration stages, balancing capex constraints against EPA discharge permit requirements.
- Cartridge Filters:Pleated polypropylene configurations offer modular replacement and standardized housing compatibility across industrial process streams.
- Bag Filters:Felt and mesh constructions handle high-dirt-load applications in mining and agriculture, competing on field durability and rapid changeout cycles.
Membrane filters command the established base. The steepest expansion runs through cartridge systems in modular industrial deployments.
Application:
Application environment dictates material compatibility, regulatory exposure, and replacement frequency, with water and air treatment representing divergent technical and commercial logics.
- Water Treatment:Municipal and industrial effluent systems deploy membrane bioreactors, ultrafiltration, and reverse osmosis to meet tightening dissolved solids limits. China's MEE enforces discharge permit trading in the Yangtze River Economic Belt, compelling textile and chemical processors to upgrade from conventional clarification. Indonesia's untreated industrial clusters around Jakarta and Surabaya present build-operate-transfer opportunities for membrane providers.
- Air Purification:Engine intake and dust collection systems in mining and agriculture require ruggedized media with pulse-clean compatibility. Donaldson Company anchors this segment through field-proven durability rather than price competition.
- Chemical Processing:Corrosive stream compatibility and high-temperature tolerance drive fluoropolymer and stainless steel media selection.
- Food & Beverage:Hygienic design standards and FDA-compliant materials govern filtration in dairy, brewing, and bottled water applications.
Water treatment anchors volume. Air purification delivers the most stable replacement revenue streams.
Technology:
Technology selection maps directly to contaminant size, with pore structure determining capital intensity and operating energy requirements.
- Microfiltration:0.1-10 micron porous membranes remove bacteria and suspended solids without phase change, serving as pre-treatment to ultrafiltration and reverse osmosis. Biopharmaceutical manufacturers employ polyethersulfone microfiltration for cell culture clarification, with ISO 13408 validation creating supplier lock-in.
- Ultrafiltration:1-100 nanometer molecular weight cut-off separates macromolecules and colloids, enabling protein concentration and wastewater organics recovery. REACH restrictions on perfluorinated compounds are forcing coating reformulation for hydrophobic ultrafiltration membranes in European markets.
- Reverse Osmosis:Dense polyamide thin-film composites reject dissolved ions and emerging contaminants, displacing chemical clarification in municipal plants facing EPA Maximum Contaminant Level Goals.
- Nanofiltration:Intermediate selectivity targets divalent ions and small organics, bridging ultrafiltration and reverse osmosis performance.
Reverse osmosis holds the installed base. Ultrafiltration is climbing the fastest in industrial water reuse applications.
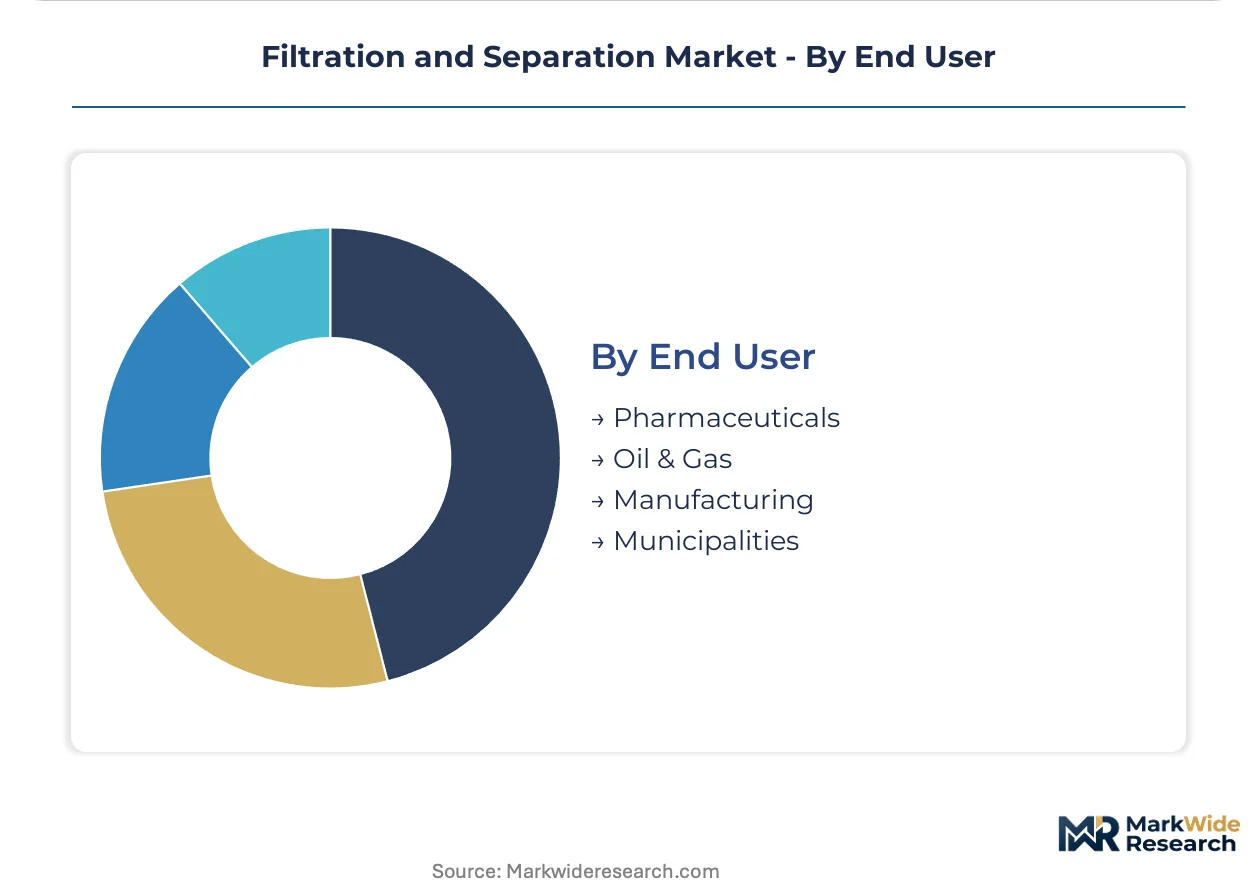
End User:
End-user compliance burden and technical sophistication determine specification authority, with pharmaceuticals demanding validated systems and municipalities prioritizing lifecycle cost.
- Pharmaceuticals:Sterile filtration requires integrity-testable membranes with documented FDA sterilization validation, creating barrier-to-entry moats around qualified suppliers. Parker-Hannifin bundles filtration with fluid power equipment to secure multi-year service contracts in this segment.
- Oil & Gas:Produced water treatment and refining process streams demand corrosion-resistant materials and high-pressure ratings.
- Manufacturing:Metalworking coolant recycling and powder coating overspray capture drive demand for electrostatic-mechanical hybrid systems.
- Municipalities:Aging infrastructure replacement cycles accelerate as EPA Clean Water Act enforcement tightens effluent standards on dissolved solids and emerging contaminants.
Pharmaceuticals capture premium positioning. Municipalities represent the deepest volume pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Clean Water Act enforcement and China's GB standards for industrial wastewater are accelerating equipment replacement cycles across municipal and industrial installations worldwide. India's pharmaceutical manufacturing corridors are scaling sterile filtration capacity to serve export markets. The EU Green Deal's REACH restrictions on perfluorinated compounds are reshaping membrane chemistry formulation priorities.
United States
Municipal water treatment operators are replacing legacy granular media plants with membrane bioreactor technology to meet EPA Maximum Contaminant Level Goals under the Safe Drinking Water Act. The agency's tightening effluent standards on dissolved solids and emerging contaminants are forcing wholesale infrastructure upgrades. Equipment-as-a-service contracting is displacing capital purchase models in Texas and Louisiana petrochemical corridors.
China
The Ministry of Ecology and Environment implements discharge permit trading for industrial wastewater in the Yangtze River Economic Belt, compelling textile and chemical processors to install ultrafiltration and reverse osmosis systems. GB standards enforcement is tightening across manufacturing hubs. Textile clusters around Shanghai and chemical processors in Jiangsu province are driving membrane system demand.
Germany
REACH authorization requirements for perfluorinated compounds are forcing membrane manufacturers to accelerate hydrophobic coating reformulation programs. ECHA's restriction proposals target PTFE-based vent filters used in sterile pharmaceutical processing. Municipal engineering consultants in Germany are adopting computational fluid dynamics tools to shorten design validation phases.
India
Sterile filtration capacity is expanding rapidly around Hyderabad and Ahmedabad as domestic drug production scales to serve export markets. CDSCO alignment with FDA standards is driving demand for integrity-testable polyethersulfone membrane systems. Pharmaceutical manufacturing corridors in Telangana and Gujarat are attracting integrated solution providers offering multi-year service contracts.
Indonesia
Textile and palm oil processing clusters around Jakarta and Surabaya lack adequate wastewater infrastructure, creating first-mover advantages for membrane system providers. The country's national environmental regulator is tightening industrial discharge enforcement. Build-operate-transfer models are emerging as preferred procurement structures for untreated effluent treatment capacity.
Filtration and Separation Market Vendor Landscape
On the supply side, the industry is consolidating around integrated solution providers with captive R&D capabilities and multi-year service contract portfolios. The vendor base stratifies into three tiers: diversified industrial conglomerates bundling filtration with adjacent equipment, pure-play membrane specialists competing on validation credentials, and regional fabricators serving price-sensitive coarse filtration segments. Dominant competitive moves include backward integration into specialty polymer supply chains and geographic expansion through build-operate-transfer contracting models.
Among diversified industrial equipment providers, Parker-Hannifin Corporation and Eaton Corporation exemplify the bundling archetype, leveraging fluid power and electrical infrastructure divisions to lock in multi-year filtration service agreements. Donaldson Company, Inc. occupies a specialist position in ruggedized dust collection applications. MANN+HUMMEL represents the European-centric R&D-intensive tier, anchoring automotive and industrial air filtration through captive development centers.
| Leading Market Players |
|---|
| Parker-Hannifin Corporation |
| Eaton Corporation |
| 3M Company |
| Pall Corporation |
| Donaldson Company, Inc. |
| MANN+HUMMEL |
| Alfa Laval AB |
| GEA Group AG |
| Pentair Plc |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Economic Belt's freight corridors carry specialty polymer feedstocks from Shanghai ports to membrane manufacturers in Jiangsu province, with logistics cost volatility amplifying price spreads between validated pharmaceutical-grade systems and commodity depth filters. This transport-cost dynamic intersects with raw material concentration among German and Japanese chemical suppliers to create tiered pricing power across certification levels.
Pricing Analysis
Certification level creates the primary spread, with FDA-validated polyethersulfone membranes commanding substantial premiums over CE-marked industrial alternatives. Three-tier pricing structure separates integrity-testable pharmaceutical systems from standard municipal water membranes and economy bag filters for mining applications. Pricing pressure stems from REACH-driven reformulation costs for hydrophobic coatings, compressing margins on European-bound shipments. Municipal procurement teams exhibit highest price sensitivity, while biopharmaceutical sterile filtration buyers prioritize validation documentation over unit cost.
Supply Chain Analysis
Export-control restrictions on advanced polymer synthesis equipment limit capacity expansion outside Germany, Japan, and the United States, constraining membrane substrate availability. Specialty PVDF and polyethersulfone resin production draws from captive petrochemical complexes in these three markets, with Chinese membrane assemblers dependent on qualified imported substrates. Single-source vulnerability concentrates around fluoropolymer precursor supply, where two German chemical groups control global output. Distribution runs through OEM-direct channels for industrial systems and specialized distributors for validated pharmaceutical components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane bioreactor penetration in municipal water treatment sits at early-cycle expansion, with EPA enforcement of dissolved solids limits creating replacement tailwinds across aging US infrastructure bases.
For Market Incumbents: Pre-empt coating reformulation bottlenecks by accelerating in-house production of fluorine-free hydrophobic membrane layers before REACH restrictions tighten. Lock multi-year service contracts with Texas and Louisiana petrochemical processors through equipment-as-a-service bundling, defending against emerging integrated water management specialists. For New Entrants and Emerging Players: Pursue build-operate-transfer opportunities in Indonesia's untreated textile clusters around Jakarta and Surabaya, where membrane infrastructure gaps outpace local supplier capability. Target pharmaceutical validation services as the most penetrable segment, offering ISO 13408 documentation packages to Indian sterile filtration capacity expansions in Hyderabad and Ahmedabad corridors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to monetize non-core filtration divisions amid portfolio streamlining pressures. Five-to-ten-year viability hinges on regulatory validation moats rather than manufacturing scale alone. Watch for CDSCO-FDA alignment milestones in India as inflection indicators for export-oriented sterile filtration demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Polymers | Captive PVDF supply secures margin control against German chemical supplier concentration. |
| Build-Operate-Transfer Contracting | Indonesia's untreated effluent clusters enable first-mover positioning in emerging wastewater infrastructure. |
| Fluorine-Free Coating Development | REACH compliance for PTFE alternatives opens retained European biopharmaceutical market access. |
| Integrated Validation Services | ISO 13408 documentation bundling creates supplier lock-in with Indian pharmaceutical exporters. |
| Equipment-as-a-Service Transition | Per-cubic-meter pricing shifts vendor risk to performance outcomes in Texas petrochemical corridors. |
Methodological Framework
The analysis maps membrane system sub-sectors, each validated through municipal engineering consultants, pharmaceutical manufacturing executives, and aftermarket service directors. Primary interviews with plant managers at US water treatment facilities, procurement leads at Indian pharmaceutical corridors, and channel partners in European distribution networks combined with secondary validation from EPA enforcement records, ECHA restriction proposals, and CDSCO regulatory alignment documents. Bottom-up equipment shipment tracking and top-down infrastructure investment analysis provided triangulation across the projection horizon.
Assumptions held regulatory enforcement trajectories fixed at announced EPA, REACH, and MEE implementation schedules while varying municipal capital availability and industrial discharge permit pricing. The analytical framework modeled segmentation across technology tier, end-use compliance burden, geographic regulatory cluster, and membrane chemistry type. CAGRs derived from equipment replacement cycle analysis and penetration rate modeling for membrane bioreactor displacement of granular media systems. Forecast inputs incorporated polymer feedstock cost indices and validation timeline distributions for pharmaceutical-grade membrane qualification.
Sensitivities concentrate around REACH perfluorinated compound restriction timing and EPA enforcement intensity variations across US municipal budget cycles. Forecasts reflect these documented assumptions without forward-year precision. Material shifts in ECHA authorization scope or MEE discharge permit trading implementation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Residential Filters Market
Filters
Canada Filtration and Separation Market
Filters
String Wound Filter Materials Market
Filters
High Purity Chemical Filters Market
Filters
Global Filter Market
Filters
Homopolymer Acrylic Filter Bags Market
Filters
Global Filter Press Market
Filters
Industrial Filter Paper Market
Filters
Nonwoven Filter Media Market
Filters
Adsorbent Market
Filters
Global Baghouse Filters Market
Filters
Aerospace Filter Market
Filters
Global Pleated Filters Market
Filters
Furnace Filters Market
Filters
Filters and Particle Monitoring Market
Filters
Global Gas Filtration Media Market