
 Residential Filters Market | 2026-2036
Residential Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Filters Market Intelligence
Tech-enabled homeowners are reorganizing procurement patterns in the residential filters sector, shifting volume from contractor channels toward direct-to-consumer platforms. 3M leverages its materials science depth to sustain pricing power in pleated media. Honeywell anchors its position through thermostat-to-filter ecosystem bundling. Blueair competes on Scandinavian design credentials and quiet operation benchmarks.
Residential filters are porous media devices engineered to remove particulates, volatile organic compounds, or biological contaminants from indoor air and potable water streams, typically rated by MERV efficiency grades or micron retention thresholds that determine capture rates for specified particle sizes. HEPA-grade products command the steepest margin pools as asthma and allergy prevalence drives clinical-grade expectations into ordinary households. Activated carbon segments are expanding fastest as odor removal and VOC concerns merge with wildfire smoke events. Electrostatic variants remain a mature, cost-driven category with thinner differentiation.
EPA indoor air quality advisories and ASHRAE ventilation standards shape minimum efficiency expectations, while FTC green marketing guidelines constrain environmental claims on packaging. The EU Ecodesign Directive and REACH chemical restrictions govern export-bound manufacturers, adding compliance layers for carbon sourcing and frame adhesives. Stakeholders must monitor how MERV-13 mandates in building codes cascade into replacement cycle acceleration and private-label qualification hurdles.
Market Dynamics
Smart home integration is collapsing the traditional contractor-mediated procurement channel, rerouting residential filter demand toward direct-to-consumer platforms and app-enabled replenishment systems that bypass HVAC service networks entirely.
Growth Catalysts
- ASHRAE 62.2 ventilation standards:The standard's MERV-13 minimum efficiency recommendations are accelerating replacement cycles in new construction and retrofits across the United States.
- Wildfire smoke events:Recurring air quality emergencies in California, Oregon, and Colorado are creating episodic demand spikes for activated carbon and HEPA-grade filtration.
- IoT-enabled filter monitoring:Pressure-drop sensors and airflow analytics embedded in smart thermostats are triggering automated replenishment orders before performance degradation.
Market Restraints
- Polypropylene meltblown supply concentration:Filter media production clusters in Germany and South Korea create vulnerability to petrochemical input volatility and freight cost spikes.
- REACH chemical restrictions:The EU Ecodesign Directive's evolving substance limitations complicate carbon sourcing and adhesive formulations for export-bound manufacturers.
- Electrostatic precipitator substitutes:Washable electronic air cleaners in commercial HVAC retrofits threaten disposable filter volumes in multi-unit residential applications.
Strategic Opportunities
- Subscription bundling with utility demand-response programs:Texas and Arizona utilities are piloting filter-replacement incentives tied to peak-load thermostat adjustments.
- Clinical-grade HEPA penetration in ordinary households:Asthma and allergy prevalence is collapsing the price premium barrier between medical and consumer channels.
- Voice-commerce integration:Amazon Alexa and Google Home native ordering capabilities are capturing replenishment moments at point-of-alert.
Industry Challenges
- MERV-13 test facility certification backlog:ASHRAE 52.2 laboratory accreditation delays are stretching private-label qualification timelines for new market entrants.
- Smart home protocol fragmentation:Matter, Zigbee, Z-Wave, and proprietary ecosystems require redundant SKU development and inventory duplication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Filters Market |
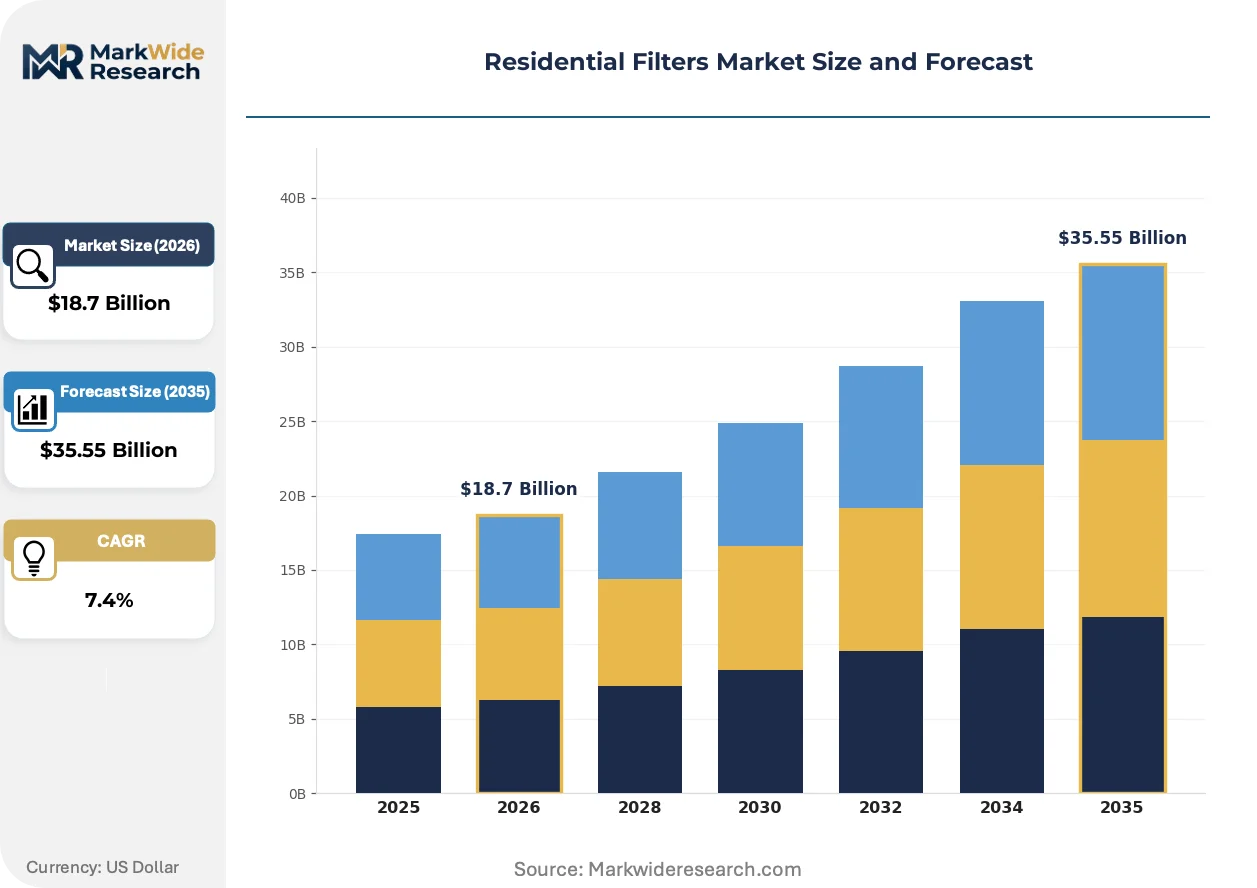
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $35.55 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA, Activated Carbon, UV Filters, Electrostatic Application: Air Purification, Water Filtration, Odor Removal, HVAC Systems Filter Grade: Residential Grade, Commercial Grade, HEPA Grade, Industrial Grade Distribution Channel: Online Retail, Home Improvement Stores, Specialty Stores, Direct Sales |
| Companies Covered | Lennox International, Brita, 3M, Air King, Pentair, Honeywell, Blueair, Coway, Dyson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Filters Market Strategic Shifts & Innovations
Filtration technology is converging with sensor networks and predictive analytics, transforming passive media replacement into data-driven air quality management systems that anticipate contamination events rather than merely responding to them.
Electret-charged synthetic media is miniaturizing pleat depths while maintaining capture efficiency, enabling slimmer filter profiles that fit legacy ductwork without retrofit. HVAC contractors in Sun Belt states are specifying these compressed formats for attic installations with severe space constraints. The technology is miniaturizing the form factor threshold for MERV-13 performance, expanding addressable housing stock by fifteen to twenty percent in mature suburban markets.
EPA indoor air quality advisories are tightening voluntary efficiency benchmarks ahead of anticipated federal building code harmonization. The agency's Clean Air in Buildings Challenge is creating procurement pull for enhanced filtration in schools and municipal facilities. California's Title 24 energy code updates are incorporating these advisory thresholds as mandatory compliance checkpoints for new residential construction permits.
Replenishment behavior is fragmenting across channel types as tech-enabled homeowners abandon annual contractor service contracts for just-in-time direct ordering. Amazon Subscribe and Save and manufacturer-native subscription platforms are displacing wholesale distributor relationships for replacement cycles. This disintermediation concentrates most visibly in Texas, Florida, and Arizona metropolitan markets where cooling-season filter change frequency peaks at quarterly intervals.
Residential Filters Market Segmentation
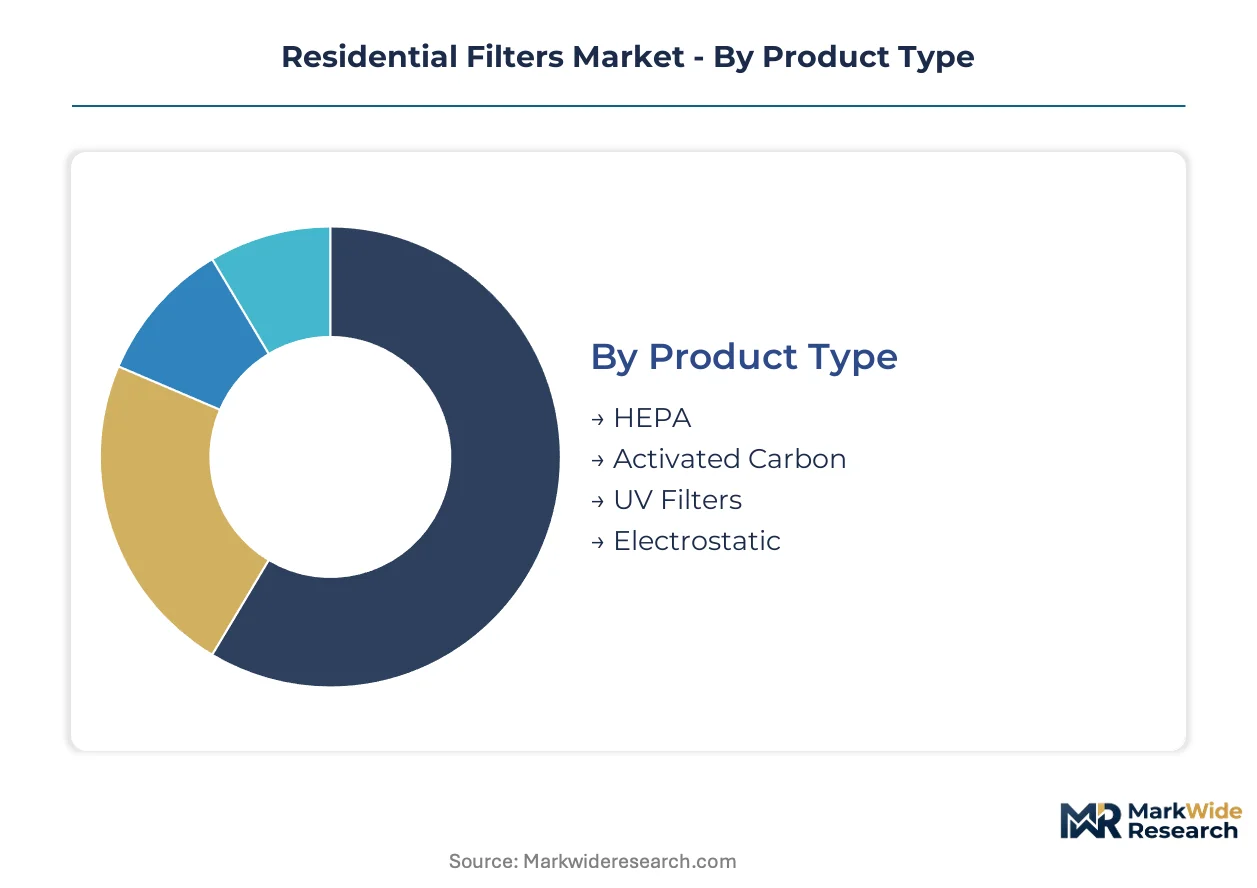
Segmentation in residential filters reveals how margin pools concentrate around clinical-grade specifications and smart-enabled replenishment channels. Understanding these splits exposes where technology premiums override commodity pricing and which procurement pathways are collapsing traditional distribution.
Product Type:
Margin pools concentrate in clinical-grade media where asthma prevalence and wildfire smoke events justify steep price premiums over commodity alternatives.
- HEPA:Fibrous media capturing 99.97% of 0.3-micron particles through dense pleat configurations. Demand clusters in California, Oregon, and Colorado metropolitan areas where wildfire smoke advisories trigger emergency procurement. Asthma and allergy prevalence is collapsing the medical-consumer price barrier.
- Activated Carbon:Porous carbonaceous substrate adsorbing VOCs, odors, and gaseous contaminants through surface area binding. Sun Belt states with extended cooling seasons drive replacement frequency as humidity accelerates saturation. Wildfire smoke events create episodic demand spikes that override normal replenishment cycles.
- UV Filters:Ultraviolet-C lamp arrays neutralizing biological contaminants in passing airstreams. HVAC contractor channels dominate specification for whole-home installations.
- Electrostatic:Permanently charged synthetic fibers attracting particles through electrostatic attraction. Cost-driven category with thinner differentiation and thinner margins.
The dominant share belongs to HEPA, while Activated Carbon is closing the gap fastest.
Application:
Volume concentrates in climate-dependent replacement cycles where cooling season length dictates filter change frequency.
- Air Purification:Standalone and whole-home systems removing particulates from conditioned indoor air. Texas, Florida, and Arizona cooling loads drive quarterly replacement intervals that exceed national averages.
- Water Filtration:Point-of-use and point-of-entry systems treating potable water for sediment, chlorine, and microbial contaminants. Municipal water quality advisories in specific metropolitan areas trigger upgrade cycles.
- Odor Removal:Targeted filtration addressing pet, cooking, and smoke odors through adsorptive media. Pet ownership demographics and wildfire exposure shape geographic concentration.
- HVAC Systems:Central forced-air heating and cooling equipment requiring regular media replacement. ASHRAE 62.2 MERV-13 recommendations are accelerating replacement cycles in new construction.
Air Purification commands the largest volume position, though Water Filtration is expanding most quickly as municipal infrastructure concerns mount.
Filter Grade:
Specification tiers separate clinical-grade expectations from basic dust capture, with regulatory thresholds driving upgrade migration.
- Residential Grade:Basic particulate capture typically rated MERV 8-11 for standard household dust and pollen. Price-sensitive segment vulnerable to private-label substitution.
- Commercial Grade:Enhanced durability and efficiency for multi-unit residential and light commercial installations. Building code harmonization is elevating minimum specifications.
- HEPA Grade:Certified 99.97% efficiency at 0.3 microns meeting medical and cleanroom standards. Steepest margin pool as clinical expectations penetrate ordinary households.
- Industrial Grade:Heavy-duty construction for extreme particulate loads and extended service intervals. Limited residential applicability outside specialized environments.
HEPA Grade captures the premium tier, while Commercial Grade is gaining share fastest as code minimums rise.
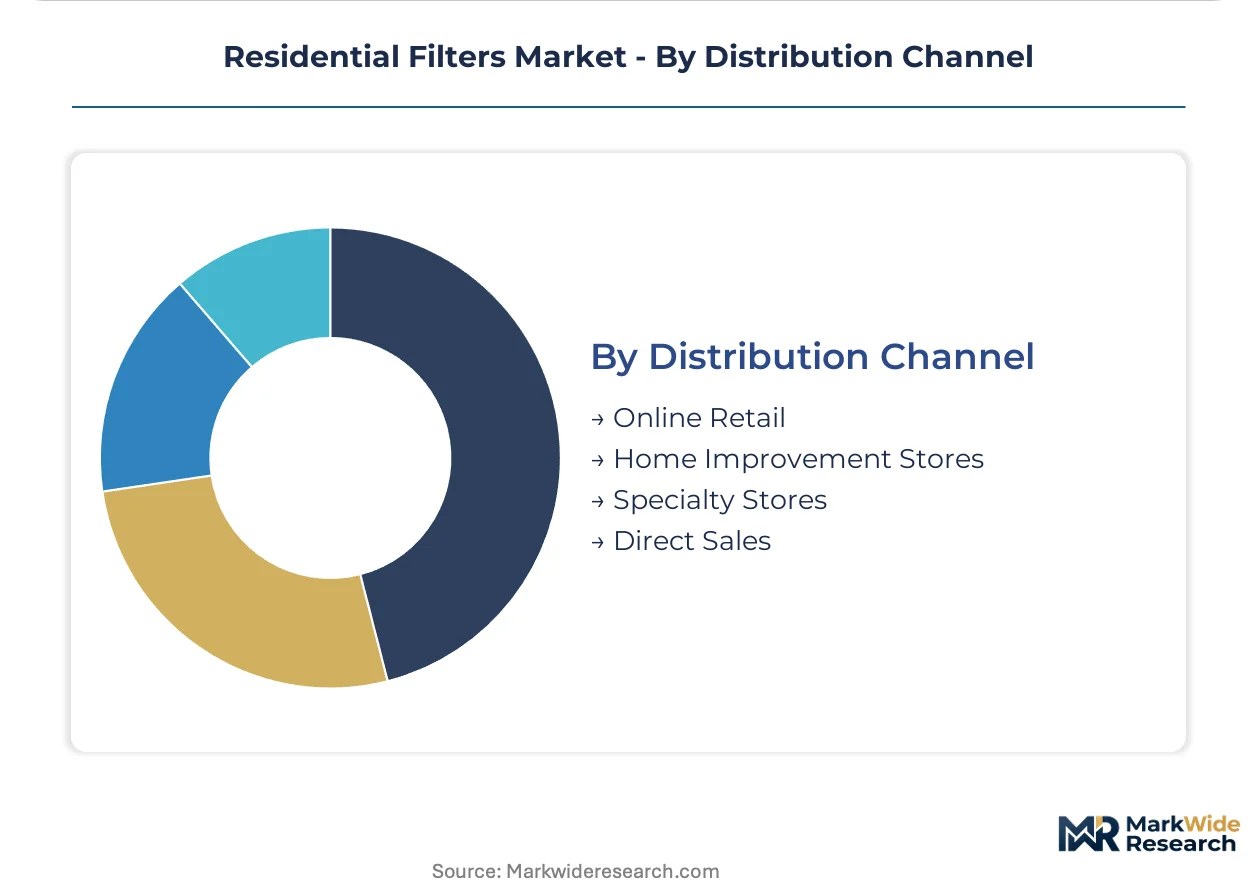
Distribution Channel:
Channel economics are inverting as smart home integration collapses contractor-mediated procurement.
- Online Retail:Direct-to-consumer platforms with subscription replenishment and IoT-triggered reordering. Amazon Subscribe and Save and manufacturer-native platforms displace wholesale relationships.
- Home Improvement Stores:Big-box retail with seasonal merchandising and contractor bulk purchasing. Loses share to just-in-time direct ordering.
- Specialty Stores:Focused retailers emphasizing air quality expertise and premium product curation. Survives on clinical-grade consultation.
- Direct Sales:Manufacturer-direct relationships including HVAC contractor networks and utility partnership programs. Traditional channel under pressure from disintermediation.
Online Retail holds the dominant position, while Direct Sales is losing ground fastest to platform economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German filter media producers export pleated synthetic substrates to North American HVAC manufacturers, establishing a transatlantic supply corridor that feeds Sun Belt residential construction.
United States
Texas, Florida, and Arizona cooling loads drive quarterly replacement cycles that exceed national averages. ASHRAE 62.2 ventilation standards and EPA indoor air quality advisories tighten minimum efficiency thresholds for new construction permits. Dallas-Fort Worth and Phoenix metropolitan clusters concentrate HVAC contractor networks and smart home integration pilot programs.
Germany
Polypropylene meltblown production clusters in Baden-Württemberg and North Rhine-Westphalia supply premium media to export markets. REACH chemical restrictions and EU Ecodesign Directive compliance requirements govern carbon sourcing and adhesive formulations. Stuttgart's industrial corridor hosts electret-charged synthetic media development facilities serving European HVAC OEMs.
China
Domestic air quality concerns and urban middle-class expansion drive demand for clinical-grade filtration in Shanghai, Beijing, and Shenzhen. GB standards and MIIT industrial policies shape local manufacturing compliance. Yangtze River Delta manufacturing clusters produce cost-optimized pleated media for export-bound private-label brands.
South Korea
Seoul Capital Area density and seasonal fine dust events sustain replacement frequency above East Asian averages. MFDS regulatory frameworks and KOSHA occupational safety guidelines influence product certification requirements. Busan-Ulsan industrial corridor concentrates filter media production for domestic appliance OEMs and regional export.
Japan
Kanto region humidity and pollen seasons drive activated carbon and HEPA-grade adoption in Tokyo, Yokohama, and Chiba metropolitan areas. METI energy efficiency standards and JIS certification requirements constrain product qualification timelines. Nagoya industrial cluster hosts precision pleating equipment manufacturers supplying domestic HVAC supply chains.
Residential Filters Market Key Industry Players
Listed leaders compete with private specialists across materials science depth and smart home ecosystem integration. The vendor base stratifies into three tiers: diversified conglomerates with captive media production, focused filtration specialists, and platform-native brands. Three strategic archetypes dominate: materials-science incumbents leveraging polymer expertise, thermostat-to-filter ecosystem bundlers, and design-forward premium challengers. Competitive moves concentrate on smart home protocol partnerships and subscription infrastructure buildout.
Among diversified conglomerates, 3M and Honeywell exemplify materials-science and ecosystem-bundling archetypes respectively. Blueair occupies a position within the design-forward premium tier. These three anchors illustrate how competitive positioning fragments across technical depth, platform control, and aesthetic differentiation rather than converging on a single winning formula.
| Leading Market Players |
|---|
| Lennox International |
| Brita |
| 3M |
| Air King |
| Pentair |
| Honeywell |
| Blueair |
| Coway |
| Dyson |
| Others |
Cost & Logistics Intelligence
Capacity utilization at Baden-Württemberg meltblown facilities shapes both supply concentration and price floors for pleated media, as German producers leverage scale economies to maintain premium positioning against Asian competitors while petrochemical input volatility compresses margins for undifferentiated electrostatic tiers.
Pricing Analysis
Current-generation electret-charged synthetic media commands substantial premiums over prior-generation fiberglass pleats, while next-generation IoT-enabled filter systems with embedded pressure sensors introduce subscription-based recurring revenue models. Three-tier pricing structure across premium HEPA, standard pleated, and economy fiberglass levels stratifies the market, with MERV-13 certification and smart home compatibility as primary price differentiation drivers. Cost compression in the economy tier is intensifying because private-label import substitution from Yangtze River Delta manufacturers erodes brand premiums. HVAC contractors exhibit highest price sensitivity due to bulk procurement volumes, while tech-enabled direct-to-consumer buyers show lowest sensitivity when clinical-grade specifications justify wellness positioning.
Supply Chain Analysis
Strategic stockpiling of polypropylene resin dominates inventory strategy among German and South Korean media producers, while North American distributors maintain lean just-in-time replenishment to minimize working capital exposure. Geographic supply concentration clusters in Germany, South Korea, and China, with the Yangtze River Delta feeding cost-optimized private-label volumes. Raw material dependencies center on polypropylene meltblown substrates, activated carbon from coconut shell or coal sources, and frame adhesives subject to REACH chemical restrictions. Single-source vulnerability from petrochemical feedstock concentration in the Gulf Coast creates supply chain risk. Distribution runs through HVAC contractor networks for whole-home systems, direct-to-consumer platforms for replacement cycles, and big-box retail for emergency procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
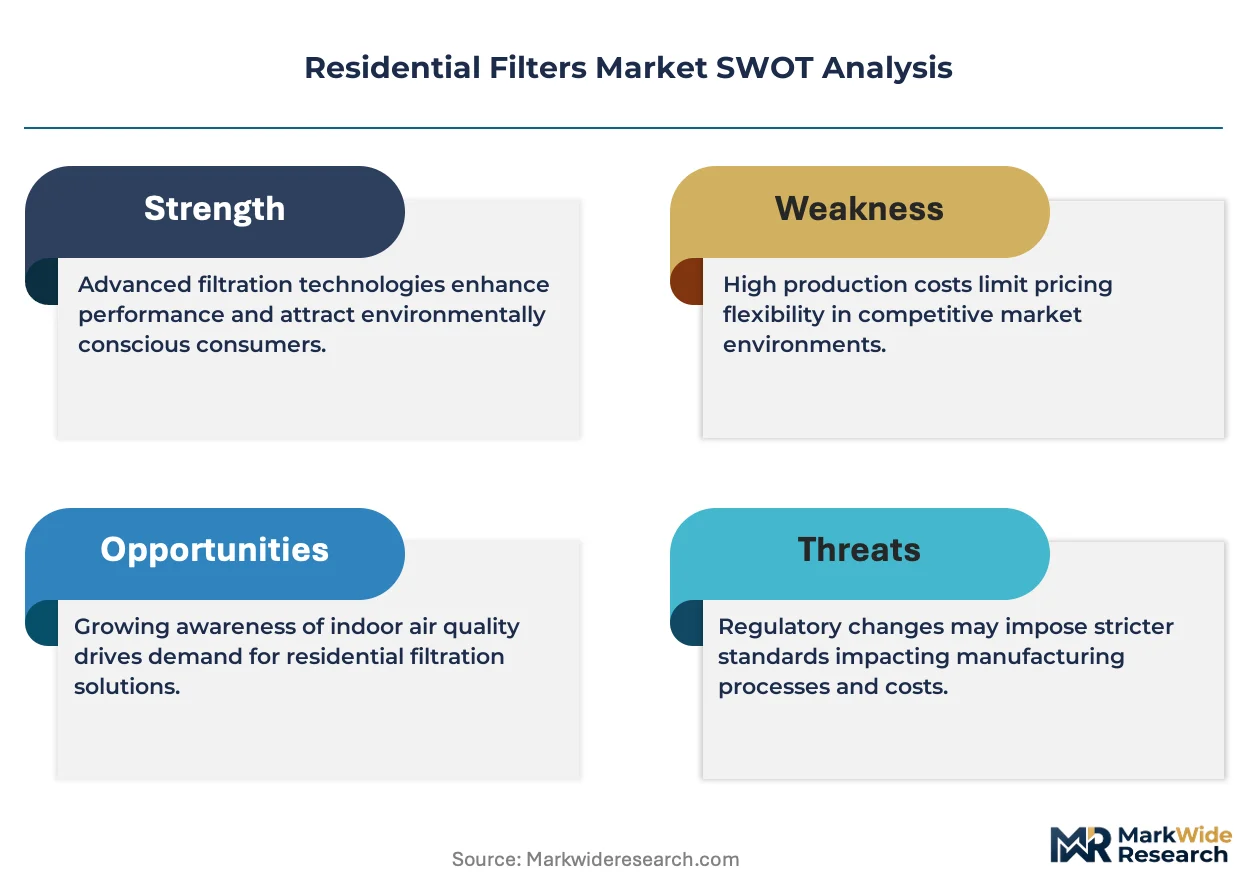
The residential filters market presents a defensive moat through regulatory entrenchment, as ASHRAE 62.2 MERV-13 mandates and EPA indoor air quality advisories create compliance barriers that favor incumbents with certified test facilities and established distribution relationships.
For Market Incumbents: Shield market position by securing ASHRAE 52.2 laboratory accreditation ahead of qualification backlogs that threaten new entrant timelines, and deepen backward integration into electret-charged synthetic media production to defend against polypropylene supply volatility from Korean and German concentration. Smart home protocol fragmentation poses immediate threat requiring redundant SKU development, while subscription infrastructure buildout represents the critical lever for recurring revenue conversion.
For New Entrants and Emerging Players: Anchor in voice-commerce integration and utility demand-response bundling as white-space targets, where Amazon Alexa native ordering capabilities and Texas-Arizona utility pilot programs remain underpenetrated by established HVAC-centric incumbents. The most penetrable segment comprises tech-enabled homeowners in Sun Belt metropolitan markets abandoning annual contractor contracts, with go-to-market execution through direct-to-consumer platforms offering just-in-time replenishment.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform-native brands with IoT-enabled replenishment infrastructure, positioning subscription-capable filtration specialists for superior cash flow quality across the analysis window. Acquisition targets should emphasize manufacturers with captive electret media production and smart home ecosystem partnerships. The signal to watch is MERV-13 building code adoption velocity in municipal jurisdictions, which would accelerate replacement cycle frequency and consolidate volume toward certified suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Home Ecosystem Integration | Amazon Alexa and Google Home native ordering captures replenishment moments at point-of-alert. |
| Subscription Infrastructure Buildout | Manufacturer-native platforms displace wholesale distributor relationships for replacement cycles. |
| Backward Integration into Media Production | Captive electret-charged synthetic media supply defends margin against petrochemical volatility. |
| ASHRAE 52.2 Laboratory Accreditation | Certification backlog creates qualification hurdles that protect incumbents from private-label entrants. |
| Utility Demand-Response Partnership | Texas and Arizona pilot programs tie filter replacement incentives to peak-load thermostat adjustments. |
Research Approach
The analysis maps HEPA-grade, activated carbon, electrostatic, and UV filter sub-sectors, each validated through HVAC contractor interviews, smart home platform engineering leads, and retail category buyer discussions. Primary fieldwork with plant managers at German and South Korean meltblown facilities, procurement directors at North American HVAC OEMs, and utility demand-response program officers combined with secondary validation from EPA indoor air quality advisories, ASHRAE technical standards, EU Ecodesign Directive documentation, and customs trade data. Bottom-up shipment modeling and top-down construction permit analysis provided triangulation across data sources.
Consistency checks against external benchmarks validated volume and value outputs throughout the forecast period. The analytical framework modeled product type, application, filter grade, and distribution channel segmentation dimensions across the projection horizon. CAGRs derived from replacement cycle frequency analysis incorporating cooling season length, wildfire smoke event patterns, and smart home penetration trajectories. Forecast inputs included MERV-13 building code adoption timelines and IoT-enabled replenishment platform growth curves.
Material uncertainties — petrochemical input volatility, REACH chemical restriction evolution, and smart home protocol standardization outcomes — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory harmonization and technology adoption curves without claiming predictive certainty. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Global Hollow Fiber Filtration Market
Filters
Global Depth Filtration Market
Filters
Homopolymer Acrylic Filter Bags Market
Filters
Nonwoven Filter Media Market
Filters
US Baghouse Filters Market
Filters
Melt-Blown Polypropylene Filters Market
Filters
Filter Coatings Market
Filters
Diatomaceous Filter Aid Market
Filters
Chloramine Filter Market
Filters
North America Gas Filtration Media Market
Filters
Filter Bag Market
Filters
Global Pleated Filters Market
Filters
Industrial Air Filtration Market
Filters
Drum Filters Market
Filters
GCC Industrial Air Filtration Market
Filters
Fabric Filters Market