
 Fabric Filter System Market | 2026-2036
Fabric Filter System Market Size, Share, and Industry Trends Forecast 2026-2036
Fabric Filter System Market Foresight
Modular baghouse configurations delivered as pre-assembled skids is recalibrating procurement patterns among cement and power plant operators. Donaldson Company leverages its North American manufacturing footprint to dominate aftermarket filter bag supply. Freudenberg Filtration Technologies anchors European demand through specialized membrane laminates for chemically aggressive flue gases. Parker Hannifin Corporation competes on integrated pulse cleaning controls that reduce compressed air consumption.
A fabric filter system captures particulate matter from industrial gas streams using woven or felted textile media supported by wire cages and housed in steel vessels, with typical operating differentials of 50 to 150 mm water gauge and filtration velocities between 0.5 and 2.0 meters per minute depending on dust characteristics. The primary purpose is to achieve regulatory compliance for stack emissions while recovering valuable process dusts in cement kilns, coal boilers, and metallurgical operations. Baghouse filters occupy the largest installed base due to decades of proven performance in high-load mining and power generation environments, though cartridge filters represent the fastest-growing product category as manufacturers seek compact footprints for retrofit installations. Pulse jet technology leads new system sales because its online cleaning capability sustains continuous production, while electrostatic precipitators face displacement in sub-300 MW power units where fabric filters achieve lower outlet emissions.
EPA Maximum Achievable Control Technology standards and the EU Industrial Emissions Directive enforce stringent particulate limits that directly mandate fabric filter upgrades across coal-fired power and cement calcination. China's MEE enforces ultra-low emission thresholds of 10 mg per cubic meter for key industrial sectors, compelling domestic retrofit investments. India's CEA notification on particulate standards for thermal power plants creates parallel compliance-driven replacement cycles. Stakeholders must monitor regulatory calibration timelines in each jurisdiction to align capital deployment with enforcement windows.
Market Dynamics
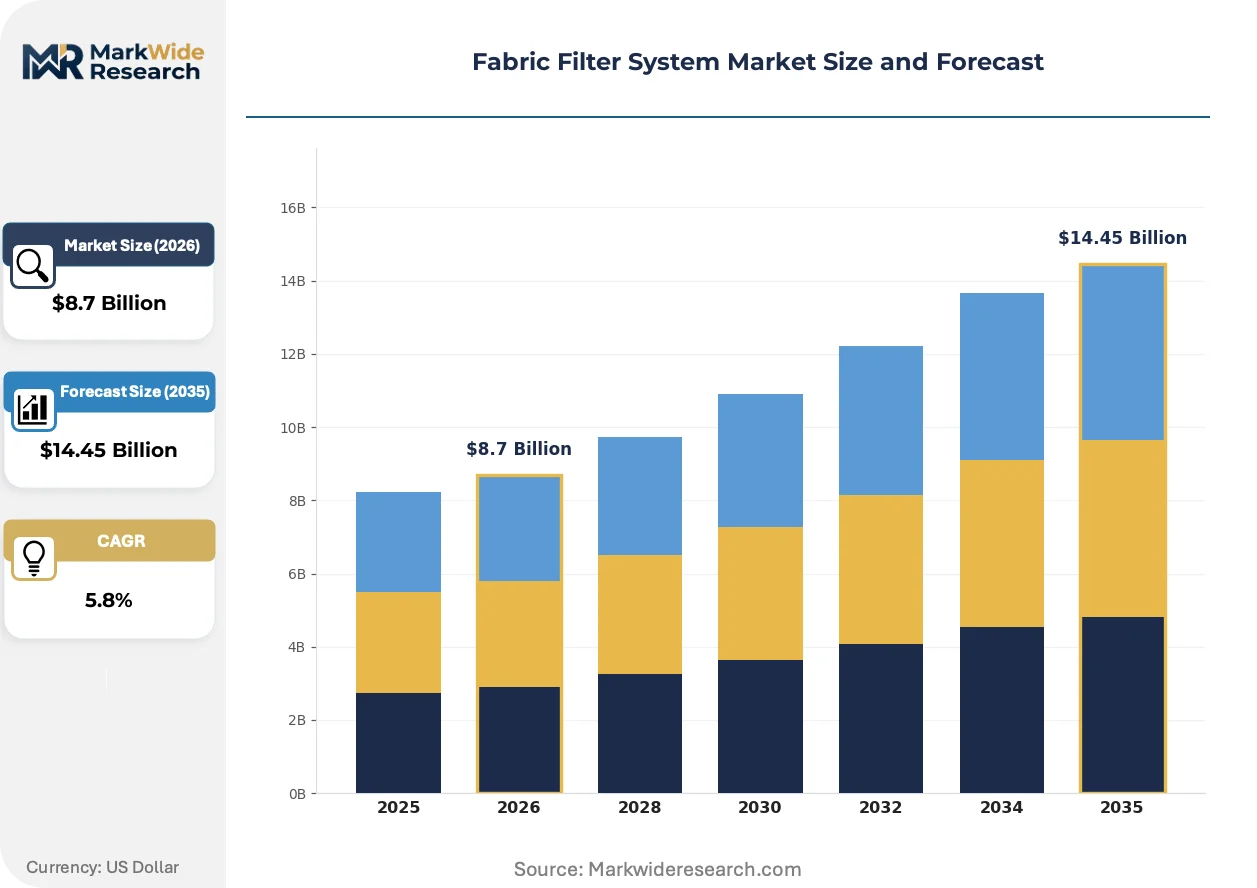
Regulatory tightening across cement and power sectors is compressing replacement cycles for legacy electrostatic precipitators, forcing operators toward pulse jet fabric filters that achieve single-digit particulate emissions. This structural shift is reshaping capital allocation patterns among heavy industry buyers.
Growth Catalysts
- China's MEE ultra-low emission mandate:The 10 mg per cubic meter threshold for industrial flue gases is compelling domestic cement and steel producers to retrofit existing dust collection infrastructure with high-efficiency baghouse systems.
- India's CEA thermal power notification:Stricter particulate limits for coal-fired units are triggering compliance-driven procurement waves across state and private generation assets.
- Membrane laminate technology:Advanced PTFE membrane composites are extending filter bag lifespans in chemically aggressive kiln environments, reducing total cost of ownership for cement calcination operators.
Market Restraints
- Specialized felting supply concentration:High-performance needle-punch nonwovens for hot-gas filtration depend on a narrow supplier base concentrated in Western Europe, creating input vulnerability.
- Wet electrostatic precipitator substitution:Sub-micron particulate and acid mist applications in metallurgical smelting increasingly favor WESP technology over dry fabric filtration.
- Compressed air infrastructure requirements:Pulse jet cleaning systems demand substantial capital investment in plant air compression and drying capacity, limiting adoption at smaller industrial facilities.
Strategic Opportunities
- Indonesia's nickel processing expansion:Battery-grade nickel smelter construction is creating demand for high-temperature fabric filtration in rotary kiln and electric furnace off-gas handling.
- EU Industrial Emissions Directive revision:Anticipated tightening of Best Available Techniques reference documents will mandate Best Available Techniques upgrades across lime and cement kilns.
- Cartridge-to-baghouse hybrid designs:Converging pleated cartridge compactness with baghouse durability is opening retrofit pathways in space-constrained European power plants.
Industry Challenges
- Filtration media engineering talent scarcity:Deep expertise in fiber selection, scrim reinforcement, and surface treatment for chemically aggressive applications concentrates among a shrinking cohort of specialized engineers.
- Legacy control system integration:Retrofitting pulse jet cleaning controls into existing mechanical shaker baghouses requires custom PLC programming and compressed air manifold reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fabric Filter System Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baghouse Filters, Cartridge Filters, Pulse Jet Filters, Electrostatic Precipitators Application: Cement Production, Power Generation, Chemical Processing, Food Processing End User: Manufacturing, Mining, Oil & Gas, Automotive Technology: Mechanical Filtration, Electrostatic Filtration, Wet Scrubbing, Hybrid Systems |
| Companies Covered | Donaldson Company, Inc., Parker Hannifin Corporation, Pall Corporation, Freudenberg Filtration Technologies, FLSmidth & Co. A/S, Ahlstrom-Munksjö Oyj, Kimberly-Clark Corporation, Babcock & Wilcox, Nederman Corporation Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fabric Filter System Market Shifts & Advancements
Modularization of system delivery and predictive maintenance integration are compressing project timelines and reshaping buyer-supplier relationships across heavy industrial applications. These shifts are reducing field construction duration while elevating digital service content in vendor contracts.
Pre-assembled skid-mounted baghouse units with integrated pulse cleaning manifolds and control enclosures are modularizing project execution for cement plant expansions. EPC contractors in India and China are specifying these configurations to compress commissioning schedules and reduce site labor requirements. This delivery format is compressing the competitive advantage of traditional field-erected suppliers.
EPA Maximum Achievable Control Technology standards for coal-fired electric generating units are mandating fabric filter retrofits that achieve outlet loadings below 0.015 grains per dry standard cubic foot. Utilities in the US Midwest and Southeast are procuring pulse jet systems with advanced pressure-drop monitoring to demonstrate continuous compliance. This regulatory pressure is displacing electrostatic precipitators in sub-300 MW units where fabric filters achieve lower residual emissions.
Aftermarket service contracts are unbundling from original equipment supply as power plant operators seek specialized filter bag changeout and cage inspection providers. Independent service firms with hot-work certification and confined-space rescue capabilities are capturing recurring revenue streams previously retained by OEMs. This pattern is most visible in Germany's lignite power sector and Australia's metallurgical coal processing facilities.
Fabric Filter System Market Segmentation
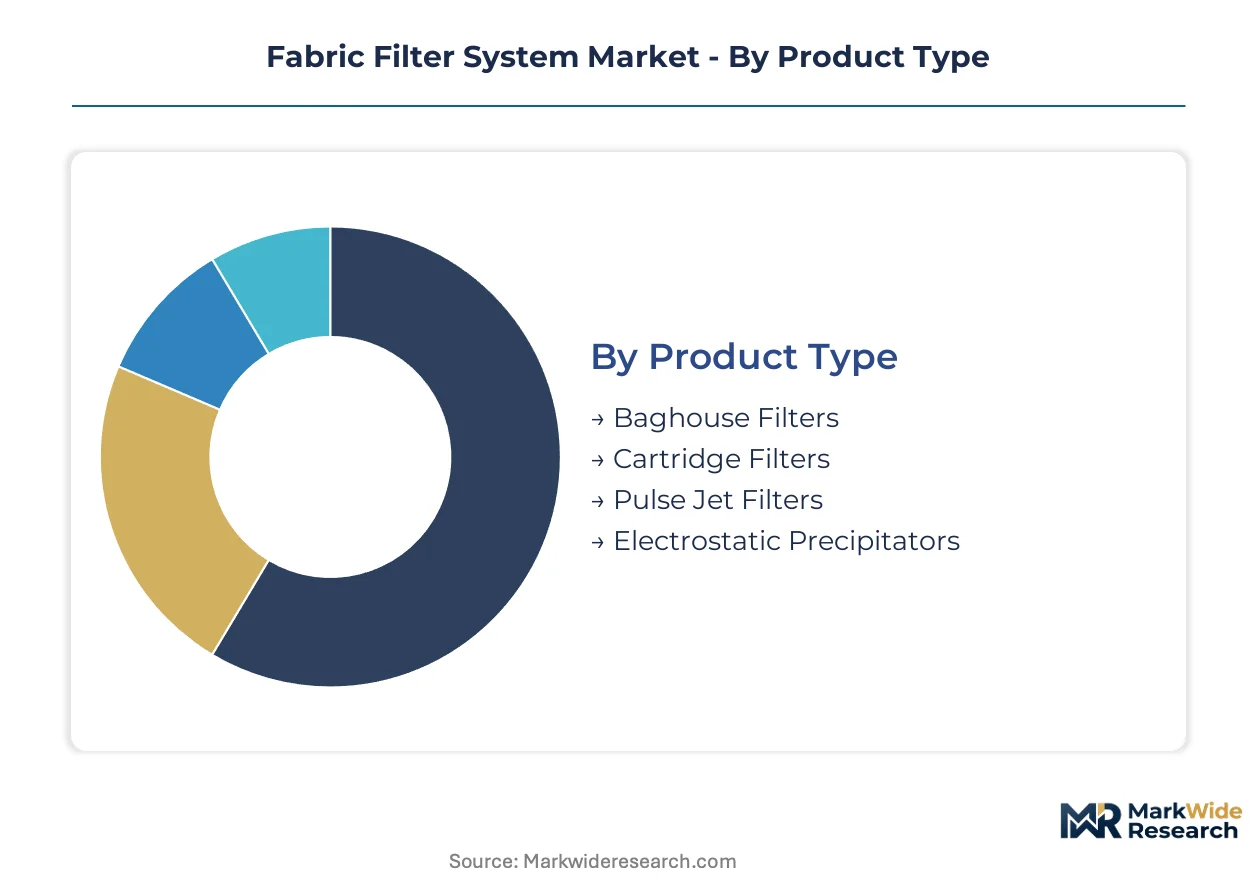
Segmentation in fabric filter systems tracks how procurement criteria diverge across emission intensity, temperature tolerance, and regulatory stringency. Buyers in cement and power prioritize continuous-duty reliability over first cost, while chemical processors weigh chemical resistance more heavily than thermal durability.
Product Type:
Capital intensity and footprint constraints drive divergent buyer preferences across high-volume continuous operations versus space-limited retrofits.
- Baghouse Filters:Woven or felted textile media supported by wire cages in steel vessels, operating at 50-150 mm water gauge differential. Cement kilns in India and China specify these for decades-proven performance in high-dust-load environments where GB and BIS particulate limits apply.
- Cartridge Filters:Pleated cylindrical elements delivering compact filtration surface area in reduced footprints. European power plant retrofits favor these where building envelope constraints prevent baghouse expansion, though membrane laminate compatibility limits chemical exposure tolerance.
- Pulse Jet Filters:Online cleaning capability sustains continuous production without process interruption. Compressed air infrastructure requirements concentrate adoption at larger facilities with captive compressor capacity.
- Electrostatic Precipitators:Ionization-based particulate collection with lower pressure drop but higher residual emissions. Displacement accelerates in sub-300 MW power units where fabric filters achieve single-digit outlet loadings.
Baghouse filters lead on scale; cartridge filters lead on momentum.
Application:
Process temperature and dust chemistry segment demand into specialized media engineering requirements.
- Cement Production:Rotary kiln off-gas handling demands PTFE membrane laminates for alkali resistance at 250°C-plus operating temperatures. China's MEE ultra-low emission mandate of 10 mg per cubic meter compels domestic retrofit investment.
- Power Generation:Coal-fired boiler flue gas treatment requires acid-resistant finishes for SO3 exposure. India's CEA notification triggers compliance-driven procurement across state generation assets.
- Chemical Processing:Aggressive solvent vapors and corrosive particulate necessitate specialized scrim reinforcement and surface treatments. Procurement concentrates among Western European suppliers with deep felting expertise.
- Food Processing:Hygienic design standards and FDA compliance requirements govern stainless steel construction and clean-in-place compatibility. Batch operation patterns favor mechanical shaker cleaning over continuous pulse jet systems.
Cement production anchors installed base; power generation drives replacement velocity.
End User:
Operational continuity requirements and maintenance access patterns shape system specification priorities.
- Manufacturing:Metalworking and mineral processing operations generate abrasive dust loads requiring heavy-duty needle-punch felts with scrim reinforcement. Preventive maintenance windows dictate offline versus online cleaning technology selection.
- Mining:Crushing and conveying operations produce high-concentration coarse particulate demanding robust cage construction and snap-ring retention systems. Remote site locations favor modular skid delivery to minimize field erection labor.
- Oil & Gas:Catalytic cracking and fluid coking units handle high-temperature process gases with sticky particulate characteristics. Specialized surface treatments prevent blinding and maintain permeability.
- Automotive:Paint booth overspray and foundry operations require flame-retardant media and explosion venting design. Compact footprints align with just-in-time manufacturing facility layouts.
Manufacturing commands volume share; mining exhibits steepest expansion trajectory.
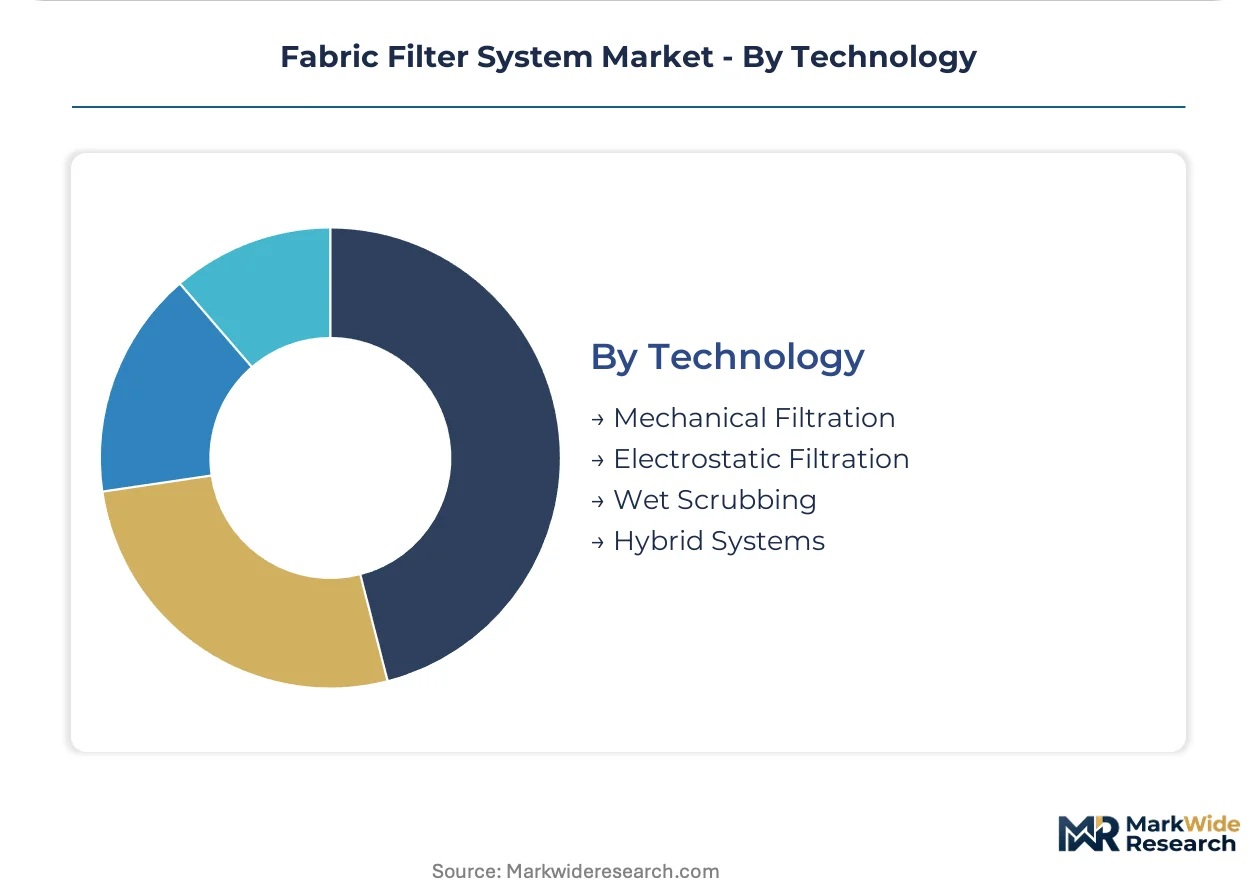
Technology:
Cleaning mechanism and energy input differentiate total cost of ownership across operating lifecycles.
- Mechanical Filtration:Shaker or reverse-air cleaning with offline bag compartments. Lower capital cost suits batch operations with scheduled downtime, though labor-intensive maintenance elevates lifecycle cost.
- Electrostatic Filtration:Corona discharge ionization with rapped plate collection. Energy efficiency advantages erode as fabric filter pressure drop optimization improves and emission limits tighten.
- Wet Scrubbing:Liquid contact absorption for sticky or hygroscopic particulate. Water treatment and sludge disposal costs concentrate adoption in metallurgical applications where acid gas co-removal is required.
- Hybrid Systems:Combined electrostatic-fabric or wet-dry configurations for complex gas streams. Capital premium limits deployment to specialized chemical and metallurgical off-gas treatment.
Mechanical filtration retains legacy installed base; pulse jet configurations within electrostatic filtration are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fabric filter technology first achieved industrial scale in the United States during the 1920s coal power expansion, then migrated to Western Europe and Japan as environmental standards tightened in the 1970s. Today procurement concentrates in Asia-Pacific cement corridors and North American power retrofits.
China
Cement calcination and steel smelting dominate system procurement as MEE enforces 10 mg per cubic meter ultra-low emission thresholds. GB standards for particulate matter tighten quarterly inspection protocols across Shanxi and Hebei industrial clusters. Tangshan steel producers retrofit pulse jet baghouses to meet enforcement windows closing in 2025.
United States
Coal-fired power plant compliance drives replacement cycles as EPA Maximum Achievable Control Technology mandates outlet loadings below 0.015 grains per dry standard cubic foot. Midwest utilities in Ohio and Indiana procure pulse jet systems with continuous pressure-drop monitoring. Appalachian coal processing facilities upgrade legacy electrostatic precipitators ahead of state implementation plan deadlines.
India
Cement kiln expansion and thermal power generation anchor demand as BIS particulate limits converge with CEA notification requirements for state generation assets. Gujarat and Rajasthan cement producers specify PTFE membrane laminates for alkali resistance above 250°C. UltraTech Cement and Ambuja Cements deploy modular skid-mounted units to compress commissioning at new kiln lines.
Germany
Lignite power sector maintenance contracts and chemical processing resilience requirements sustain aftermarket intensity. EU Industrial Emissions Directive revisions anticipate tighter Best Available Techniques reference documents for lime kilns. Rhenish lignite operators in North Rhine-Westphalia unbundle filter bag changeout services from OEM supply contracts.
Indonesia
Battery-grade nickel smelter construction creates high-temperature filtration demand for rotary kiln and electric furnace off-gas handling. Morowali and Weda Bay industrial parks specify fabric filters for HPAL and RKEF process lines. Chinese EPC contractors dominate equipment procurement for Tsingshan Holding Group and Huayou Cobalt expansion projects.
Fabric Filter System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across membrane laminate specialization and aftermarket service density. The vendor base stratifies into three tiers: integrated filtration conglomerates with captive media production, regional system fabricators serving cement EPC contractors, and independent service firms capturing recurring maintenance revenue. Consolidation pressure concentrates among Western European felting specialists and North American aftermarket providers. Dominant competitive moves include backward integration into needle-punch nonwoven supply and technology licensing agreements for pulse jet control systems.
Within the integrated conglomerate tier, Donaldson Company, Inc. and Parker Hannifin Corporation exemplify premium positioning through North American manufacturing footprints and compressed air control integration. Freudenberg Filtration Technologies occupies a specialized position among European membrane laminate suppliers serving chemically aggressive flue gas applications. These three entities represent distinct archetypes: Donaldson anchors aftermarket filter bag supply, Parker Hannifin competes on pulse cleaning automation, and Freudenberg concentrates on PTFE composite durability for cement calcination environments.
| Leading Market Players |
|---|
| Donaldson Company, Inc. |
| Parker Hannifin Corporation |
| Pall Corporation |
| Freudenberg Filtration Technologies |
| FLSmidth & Co. A/S |
| Ahlstrom-Munksjö Oyj |
| Kimberly-Clark Corporation |
| Babcock & Wilcox |
| Nederman Corporation Inc. |
| Others |
Supply & Pricing Matrix
Captive needle-punch nonwoven production anchors both supply security and margin control for Western European filtration specialists serving cement calcination and power generation markets. This backward integration into high-performance felting capacity insulates membrane laminate suppliers from raw polymer volatility while commanding premium positioning against commodity baghouse fabricators.
Pricing Analysis
Project-based equipment procurement with long-term aftermarket service bundling dominates capital allocation patterns among cement EPC contractors and utility operators. Price differentiation hinges on membrane certification grade for MEE ultra-low emission compliance and compressed air control integration sophistication. Cost compression in standard needle-punch felts is intensifying as Chinese domestic suppliers expand PTFE composite capacity. State generation assets in India exhibit acute price sensitivity due to tariff-regulated procurement frameworks, while multinational cement producers prioritize lifecycle cost over first cost.
Supply Chain Analysis
ISO 9001 and ATEX certification gating restricts qualified filter media supply to Western European and North American specialists with proven hot-gas filtration track records. Geographic supply concentration centers on Germany, the United States, and Japan for high-temperature scrim reinforcement and PTFE membrane laminates. Raw material dependencies include PTFE resin from fluoropolymer specialists, stainless steel wire for cage construction, and high-tenacity aramid fiber for alkali-resistant felts. Single-source vulnerability in specialized felting equipment creates bottleneck risk for capacity expansion. Distribution runs through OEM direct sales for large project equipment and authorized distributors for aftermarket filter bag replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fabric filter system market functions as a stable compounder anchored by regulatory ratchet effects that mandate continuous compliance investment regardless of industrial cycle position.
For Market Incumbents: Acquire specialized membrane laminate engineering teams to deepen PTFE composite expertise for China's 10 mg per cubic meter enforcement windows. Cement producers in India and Indonesia are consolidating procurement around single-source aftermarket providers, threatening fragmented regional fabricators. Backward integration into captive needle-punch capacity in Germany or the United States secures input cost visibility against polymer volatility. For New Entrants and Emerging Players: Predictive maintenance algorithms for pulse jet pressure-drop optimization represent a technology-first wedge into service contracts previously retained by OEMs. Independent filter bag changeout providers with confined-space rescue certification capture recurring revenue in Germany's lignite power sector and Australia's metallurgical coal processing. Target nickel smelter construction in Indonesia's Morowali industrial park where Chinese EPC contractors specify fabric filters for HPAL process lines. For Investors and Strategic Acquirers: Roll-up economics work for regional aftermarket service providers because regulatory compliance mandates create predictable replacement cycles with limited demand elasticity. The 5-10 year viability window favors platforms consolidating filter bag changeout and cage inspection capabilities across European power generation assets. Watch for MEE enforcement timeline acceleration in Hebei and Shanxi industrial clusters as the inflection indicator for Chinese domestic retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Needle-Punch Capacity | Captive felting production insulates margin from PTFE resin volatility and secures MEE compliance-grade membrane supply. |
| Predictive Maintenance Platform Development | Pressure-drop monitoring algorithms compress service intervals and displace OEM aftermarket contracts at German lignite operators. |
| Modular Skid-Mounted System Delivery | Pre-assembled baghouse configurations reduce Indian cement plant commissioning schedules and site labor requirements. |
| Membrane Laminate Technology Licensing | PTFE composite expertise transfer enables Chinese domestic suppliers to meet GB standard ultra-low emission thresholds. |
| Aftermarket Service Contract Unbundling | Independent filter bag changeout providers capture recurring revenue streams from OEMs in Australia's metallurgical coal sector. |
Research Methodology
Coverage spans Asia-Pacific cement corridors, North American power retrofits, and European chemical processing clusters, with primary inputs from each. The analysis combines structured interviews with plant engineers at cement and power generation facilities, procurement leads at EPC contractors, and aftermarket service heads at independent filter bag providers. Secondary validation draws from EPA MACT compliance filings, CEA notification documents, MEE ultra-low emission enforcement protocols, and EU Industrial Emissions Directive revision drafts. Bottom-up project pipeline tracking triangulates against top-down regulatory mandate sizing.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon. The analytical framework models demand by product type (baghouse, cartridge, pulse jet, electrostatic precipitator), application (cement production, power generation, chemical processing, food processing), end user (manufacturing, mining, oil and gas, automotive), and technology (mechanical filtration, electrostatic filtration, wet scrubbing, hybrid systems). CAGRs derive from regulatory enforcement timeline phasing and cement kiln capacity expansion schedules. Industry-specific forecast inputs include MEE inspection protocol intensity and CEA compliance deadline clustering.
The model holds under steady regulatory enforcement intensity; deviation in MEE timeline acceleration or CEA notification delay would shift replacement cycle phasing. Forecasts reflect assumptions regarding polymer supply continuity and compressed air infrastructure availability at smaller industrial facilities. A model refresh is warranted upon material change in EU Industrial Emissions Directive revision scope or Indonesia's nickel smelter construction pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Global Laboratory Filtration Market
Filters
Sintered Metal Filters Market
Filters
North America Gas Filtration Media Market
Filters
Industrial Filter Paper Market
Filters
Industrial Air Filtration Market
Filters
Global Industrial Filters Market
Filters
US Baghouse Filters Market
Filters
Nonwoven Air Conditioning Filter Market
Filters
Ceramic Filters Market
Filters
Global Depth Filtration Market
Filters
Global Filtration and Contamination Control Market
Filters
Coolant Filtration Systems Market
Filters
Filters and Particle Monitoring Market
Filters
Nonwoven Filter Media Market
Filters
Liquid Filter Bags Market
Filters
Global Tangential Flow Filtration Market