
 Filter Bag Market | 2026-2036
Filter Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Filter Bag Market Intelligence
The EU Green Deal's focus on industrial emissions is hardening requirements for particulate matter control across multiple sectors. Donaldson Company, Inc. leverages its extensive portfolio for diverse industrial dust collection needs. W.L. Gore & Associates, Inc. specializes in high-performance membrane filter bags for demanding applications, while Parker Hannifin Corporation sustains its market presence through a vast global distribution network.
A filter bag is a fabric-based filtration device designed to capture and remove particulate matter from air or gas streams within a baghouse system. These bags are constructed from materials like polyester, aramid, or PTFE to withstand specific operating temperatures and chemical exposures. Needle felt bags command a significant market share due to their balance of performance and cost, while membrane filter bags offer superior filtration efficiency for critical applications. Air pollution control for cement manufacturers and power generation plants remains the primary application.
Regulatory frameworks from the US Environmental Protection Agency (EPA) and China's Ministry of Ecology and Environment (MEE) set stringent limits on industrial particulate emissions. Compliance with these standards, along with Europe's Industrial Emissions Directive, is a primary demand driver. Navigating the evolving landscape of material science to develop filters that meet future, more stringent emissions limits will be critical for manufacturers.
Market Dynamics
The central force shaping the filter bag market is the global convergence of stringent air pollution regulations. Mandates from bodies like the US EPA and China's MEE compel heavy industries to invest in advanced particulate control technologies.
Growth Catalysts
- Industrial Policy in China:The nation's "dual carbon" goals are accelerating upgrades in high-emission sectors like steel and cement production, directly spurring demand for new baghouse installations and replacement filters.
- Cement Sector Growth:Expansion of cement manufacturing facilities in developing economies to support infrastructure projects creates a foundational demand stream for fabric filter systems for clinker cooler and kiln exhaust gas cleaning.
- High-Temperature Media:Innovations in materials like aramid and PTFE fibers enable filter bags to operate in harsh environments such as waste incineration and biomass power plants, opening new application segments.
Market Restraints
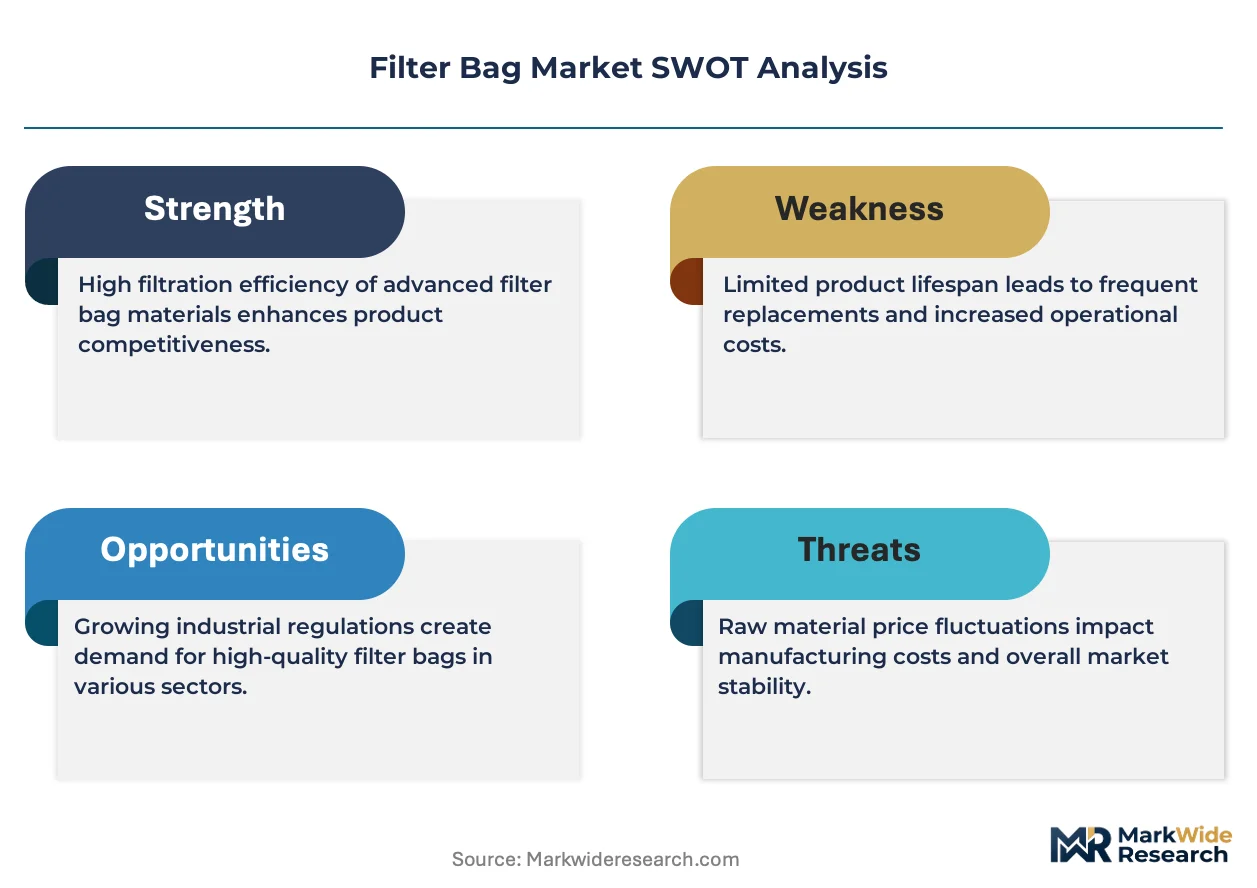
- Raw Material Volatility:Prices for key polymers like PTFE and fiberglass are subject to global supply chain disruptions and energy cost fluctuations, creating unpredictable cost structures for filter bag manufacturers.
- Finite Operational Lifespan:Filter bags require periodic replacement, and their lifespan can be drastically reduced by process upsets like temperature spikes, creating operational risks and unplanned downtime for end-users.
- Alternative Technologies:In certain large-scale applications, such as coal-fired power plants, electrostatic precipitators (ESPs) remain a competitive alternative, limiting the addressable market for fabric filters.
Strategic Opportunities
- Battery Manufacturing Dust:The rapid growth of gigafactories creates a new, high-value application for capturing hazardous dust from lithium, cobalt, and nickel processing during battery production.
- EU Carbon Border Adjustment:The EU's CBAM policy incentivizes producers of imported goods like steel and cement to upgrade their environmental controls, including filtration, to avoid carbon-related tariffs.
- SME Market in Southeast Asia:Industrial clusters in nations like Vietnam and Indonesia present an opportunity as local environmental agencies begin to enforce stricter air quality rules on smaller factories.
Industry Challenges
- Regulatory Patchwork:Manufacturers and end-users must navigate a complex and often divergent set of emission standards, such as the US EPA's NESHAP and Europe's Industrial Emissions Directive, increasing compliance costs.
- Material Science Advancement:There is constant pressure to innovate filter media that offers higher efficiency, better chemical resistance, and greater temperature tolerance to meet future regulations, which requires substantial R&D investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Filter Bag Market |
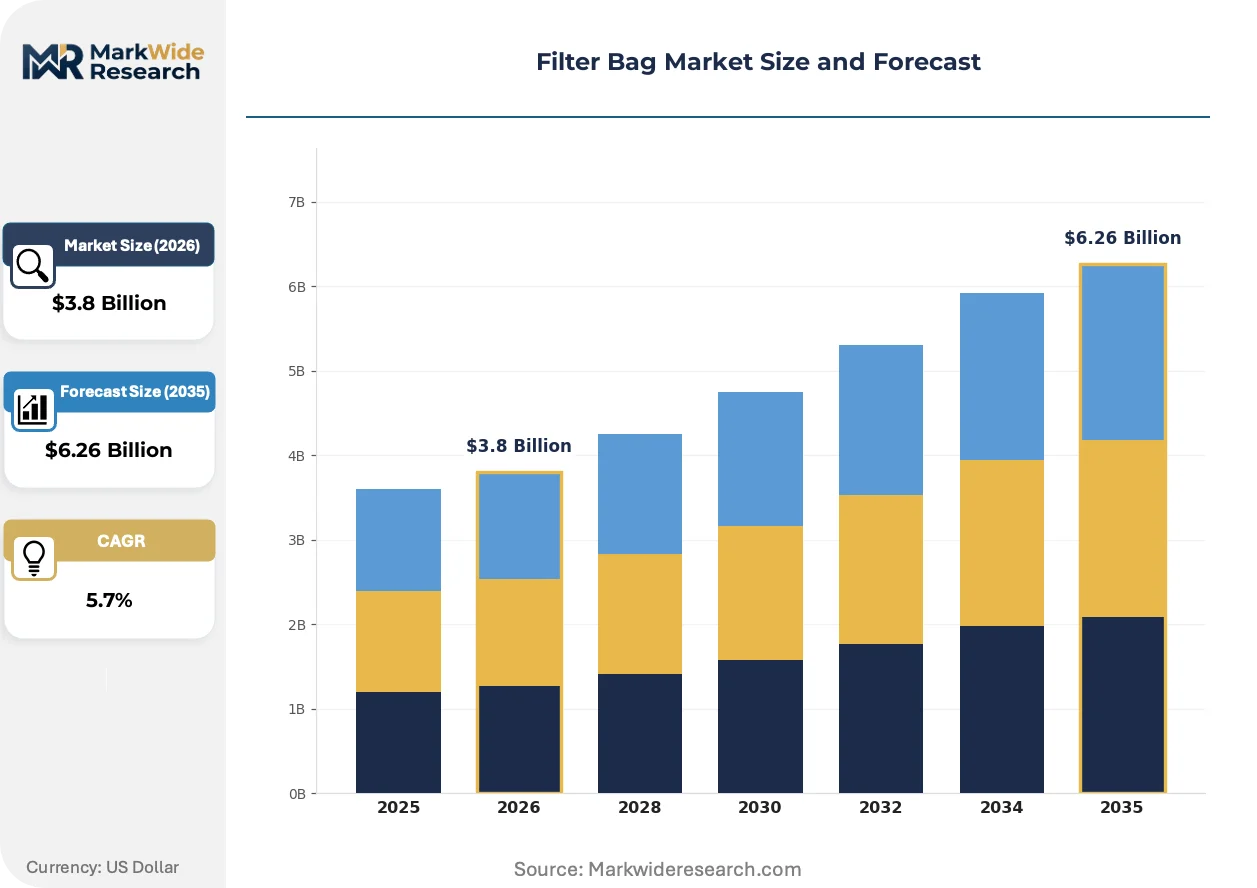
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Filter Bags, Needle Felt Bags, Woven Bags, Membrane Filter Bags, Composite Filter Bags Application: Air Pollution Control, Industrial Dust Collection, Liquid Filtration, Food & Beverage Processing, Chemical Processing End User: Cement Manufacturers, Power Generation Plants, Pharmaceutical Manufacturers, Metal Processing Units, Paper Mills Installation Type: Baghouse Filters, Cartridge Filters, Cyclone Filters, Wet Scrubbers, Electrostatic Precipitators |
| Companies Covered | Parker Hannifin Corporation, Babcock & Wilcox Enterprises, Inc., Donaldson Company, Inc., Thermax Limited, W.L. Gore & Associates, Inc., Eaton Corporation, General Electric Company, BWF Envirotech, Camfil AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Filter Bag Market Strategic Shifts & Innovations
Performance optimization is becoming the primary focus, shifting the market beyond mere regulatory compliance. This evolution prioritizes filtration efficiency, operational longevity, and the ability to handle increasingly complex industrial gas streams, redefining value for end-users.
Advanced ePTFE membrane laminates provide surface-level filtration, which prevents fine particulates from deeply embedding within the filter media. Industries with valuable or hazardous dust, such as chemicals and pharmaceuticals, are steadily adopting this technology. The superior cleanability and extended lifespan of these membranes means this technology is expanding into applications like food processing, which were traditionally served by less expensive needle felt bags.
Europe’s Green Deal framework, particularly its Zero Pollution Action Plan, is driving stricter emissions limits across the continent. This policy directly influences the revision of Best Available Techniques (BAT) standards, compelling industrial operators to upgrade their air pollution control systems. Sectors like waste-to-energy and metals processing are most impacted, spurring investment in high-performance filter bags to ensure compliance with new PM2.5 targets.
Operators of heavy industrial facilities are increasingly evaluating filtration products based on a Total Cost of Ownership (TCO) model, not just initial unit price. This approach considers factors like energy consumption from pressure drop, filter lifespan, and maintenance labor, disrupting the sales process for commodity bags. The TCO mindset is most prevalent in North American and European cement plants and power stations, where system reliability is paramount.
Filter Bag Market Segmentation
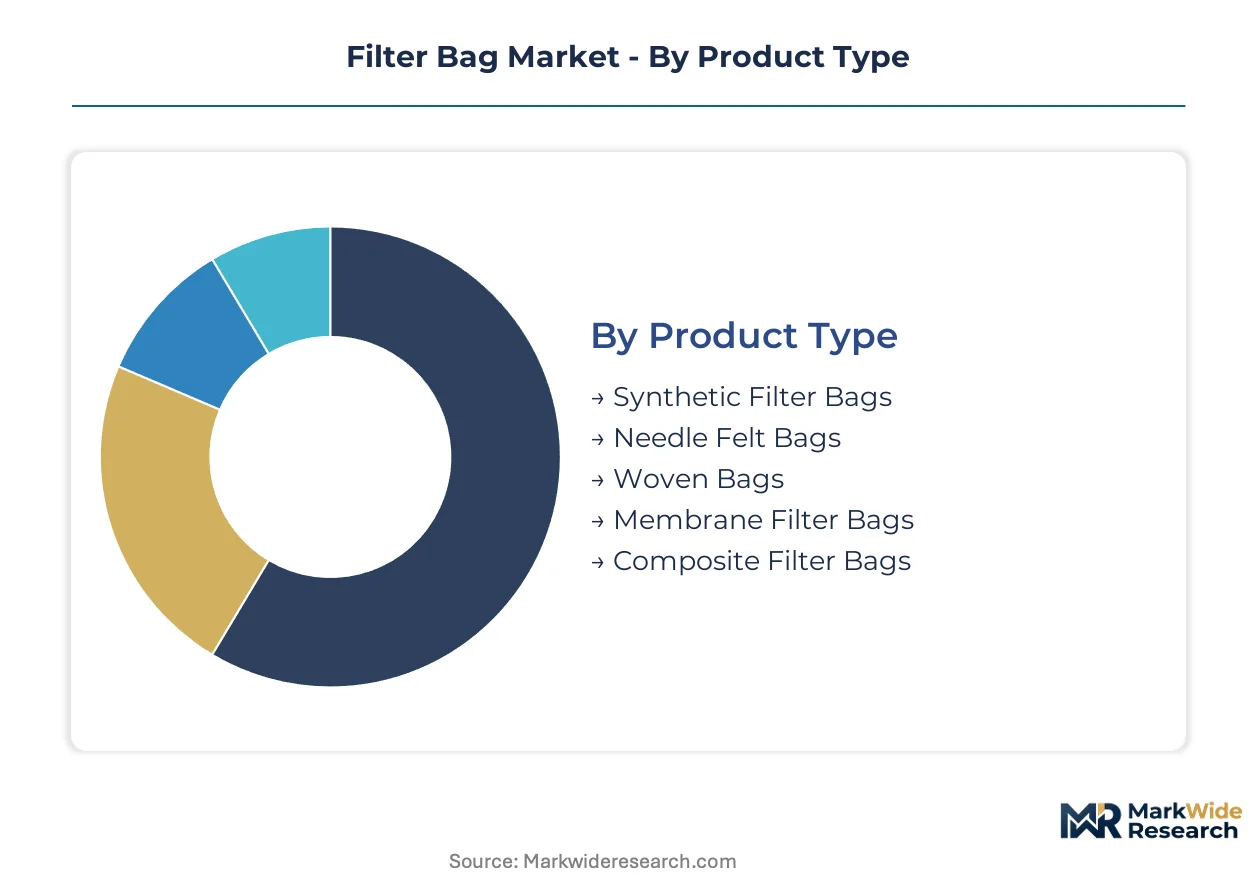
The filter bag market's structure reflects diverse material science, application requirements, and end-user needs. Understanding these segments clarifies where investment and innovation are concentrating for particulate matter control. This granular view reveals distinct demand patterns across industrial landscapes.
Product Type:
Supply concentration in the filter bag market heavily favors established material types that balance performance and cost efficiency. Manufacturers prioritize sourcing reliable polymers and fibers for consistent product quality across various industrial settings.
- Needle Felt Bags:These bags are constructed from synthetic fibers like polyester or polypropylene, mechanically interlocked to form a dense filter medium. Demand concentrates in general industrial dust collection across China, driven by their balanced performance and cost-effectiveness for regulatory compliance.
- Membrane Filter Bags:Featuring an ePTFE membrane laminate applied to a felt substrate, these bags offer surface-level filtration and superior particulate capture. Industries handling valuable or hazardous dust, such as pharmaceuticals and chemicals in Europe, are rapidly adopting this technology due to its enhanced cleanability and extended lifespan.
- Synthetic Filter Bags:Comprised of various synthetic fibers, these bags offer chemical resistance and temperature tolerance suitable for diverse industrial environments.
- Woven Bags:Made from woven fabrics, these bags provide good mechanical strength and are often used in less demanding filtration applications.
- Composite Filter Bags:These combine different materials or layers to achieve enhanced performance characteristics, such as improved efficiency or chemical resistance.
Today's leader: Needle Felt Bags. Tomorrow's challenger: Membrane Filter Bags.
Application:
The application landscape for filter bags remains dominated by core industrial processes requiring stringent air quality management. These critical uses drive significant volume and technological advancements in filtration media.
- Air Pollution Control:This application involves capturing fine particulate matter from industrial exhaust streams to meet environmental emission standards. Cement manufacturing and power generation plants, particularly in India, represent significant demand due to strict MEE and EPA regulations.
- Industrial Dust Collection:This segment focuses on removing airborne dust and debris generated during various manufacturing processes to protect equipment and worker health. Factories across Southeast Asia are investing in these systems as local environmental agencies begin enforcing stricter air quality rules.
- Liquid Filtration:Filter bags are employed to remove solid particulates from liquid streams in various industrial processes, ensuring product purity or wastewater treatment.
- Food & Beverage Processing:This application utilizes filter bags for hygiene-sensitive filtration tasks, removing impurities from ingredients or finished products to meet strict quality standards.
- Chemical Processing:Filter bags are crucial for separating solids from liquids or gases in chemical production, often requiring materials resistant to corrosive substances.
Air Pollution Control applications demonstrate the steepest expansion trajectory, while Food & Beverage Processing shows emerging demand for high-performance options.
End User:
End-user demand patterns for filter bags are heavily influenced by sector-specific regulatory pressure and operational scale. Heavy industries with significant emission profiles continue to be the primary consumers of filtration solutions.
- Cement Manufacturers:This sector utilizes filter bags extensively for clinker cooler and kiln exhaust gas cleaning to control particulate emissions. Expansion of cement manufacturing in developing economies, particularly in Vietnam, creates a foundational demand stream for new filter systems.
- Power Generation Plants:These facilities, including coal-fired and biomass plants, rely on filter bags to remove fly ash and other particulates from flue gas. North American power stations are increasingly evaluating filtration products based on a total cost of ownership model, prioritizing filter lifespan and energy efficiency.
- Pharmaceutical Manufacturers:This industry requires high-efficiency filter bags to prevent cross-contamination and ensure product purity in controlled environments.
- Metal Processing Units:These facilities use filter bags to capture metallic dust and fumes generated during smelting, grinding, and other operations, protecting workers and the environment.
- Paper Mills:Filter bags are employed in paper production for dust collection from wood processing and boiler exhaust, maintaining air quality within the plant.
Regulatory compliance remains the primary demand driver for Cement Manufacturers, while Power Generation Plants focus on optimizing total operational costs.
Installation Type:
The prevalence of various installation types dictates the form factor and performance requirements for filter bags. Established systems dominate, but alternative technologies exert competitive pressure in specific large-scale contexts.
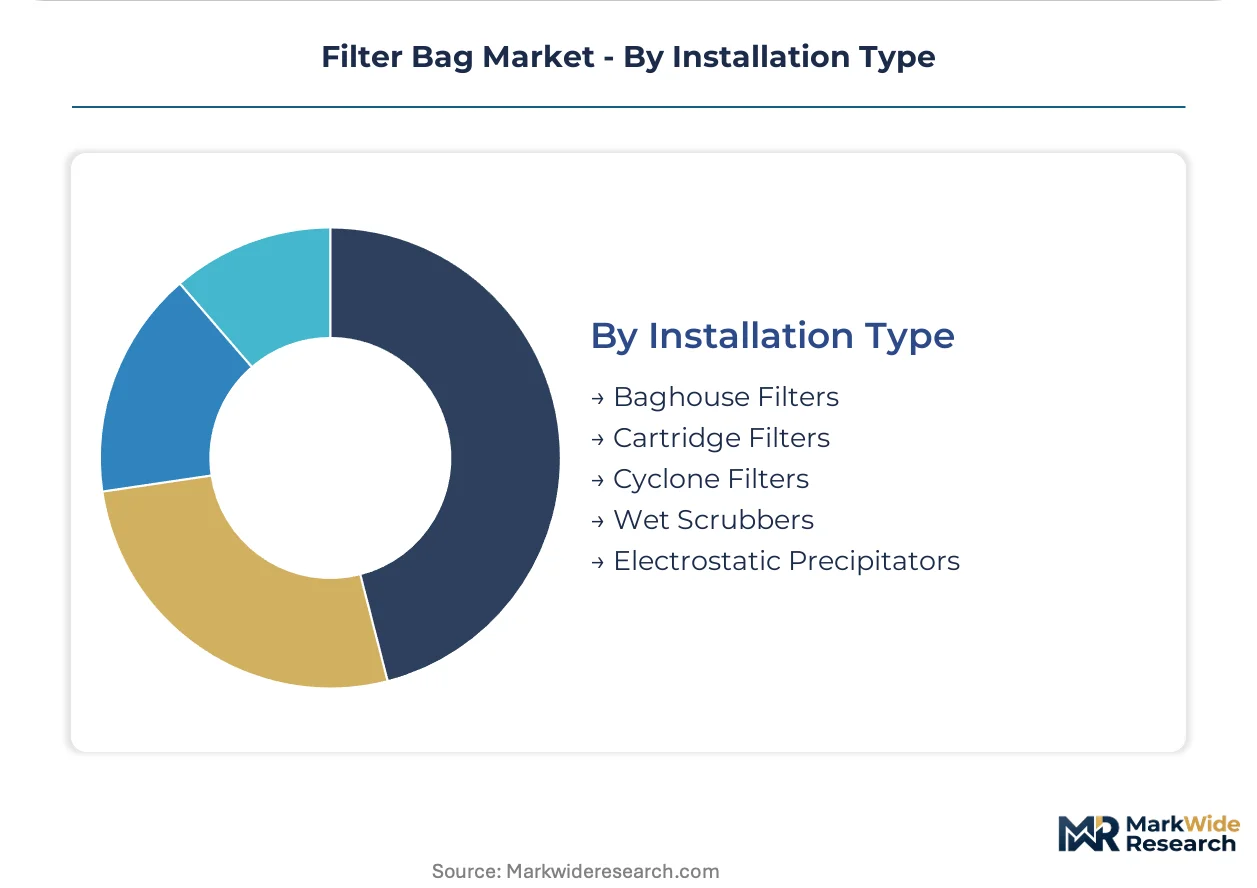
- Baghouse Filters:These large industrial dust collectors house numerous filter bags that capture particulate matter from gas streams. Baghouse systems remain the most common installation for fabric filters across heavy industries in Germany.
- Electrostatic Precipitators:These devices use an electrostatic charge to remove particulates from gas streams, offering an alternative to baghouses in certain large-scale applications. In coal-fired power plants in the United States, ESPs remain a competitive alternative to fabric filters.
- Cartridge Filters:These compact filtration units use pleated media cartridges, often employed in applications requiring high efficiency in a smaller footprint.
- Cyclone Filters:These mechanical separators use centrifugal force to remove larger particulates from gas streams, often serving as pre-filters for baghouses.
- Wet Scrubbers:These air pollution control devices remove particulates and gaseous pollutants by bringing the contaminated gas stream into contact with a scrubbing liquid.
Baghouse Filters represent the established standard, while Electrostatic Precipitators offer a strong competitive dynamic in specific large-scale industrial settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The industrial filtration sector, where filter bags found early applications, scaled in industrialized economies. These regions developed foundational technologies for particulate matter control. Today, demand shifts, driven by environmental mandates and industrial expansion.
China
Demand for filter bags in China is propelled by "dual carbon" goals and upgrades in steel and cement production. China's MEE enforces stringent emission limits, compelling operators to invest in advanced filtration. Industrial zones across the Yangtze River Delta see investment in new baghouse installations.
United States
Stricter air quality mandates from the US EPA drive investment in filtration system upgrades. NESHAP compels industrial facilities to control particulate emissions. Power stations and cement manufacturers in the Midwest evaluate filter products based on total cost of ownership.
Germany
Industrial emissions control hardens requirements across multiple sectors due to the EU Green Deal. Europe's Industrial Emissions Directive necessitates upgrades in air pollution control for waste-to-energy and metals processing. Heavy industries in the Ruhr area adopt advanced filter bags for compliance with new PM2.5 targets.
India
Significant demand for air pollution control in India stems from cement manufacturing and power generation plants. Environmental regulations mandate strict particulate emission limits for industrial facilities. Rapid infrastructure expansion in states like Gujarat drives the need for fabric filter systems for clinker cooler and kiln exhaust gas cleaning.
Vietnam
Expansion of cement manufacturing facilities in Vietnam creates a foundational demand stream for new filter systems. Local environmental agencies in Southeast Asia enforce stricter air quality rules on smaller factories. Industrial clusters near Ho Chi Minh City present opportunities as factories invest in industrial dust collection systems.
Filter Bag Market Key Industry Players
Premium-margin players sit above commodity-margin players across product performance and application specificity in the filter bag market. The market exhibits a tiered structure, with specialists focusing on high-performance membrane filter bags alongside broader manufacturers offering cost-effective needle felt options. Two strategic archetypes emerge: technology innovators driving material science advancements and integrated solution providers offering complete dust collection systems. Portfolio diversification and strategic partnerships are dominant competitive moves.
Specialists in high-performance filtration, W.L. Gore & Associates, Inc. exemplifies the focus on advanced membrane filter bags for demanding applications. Donaldson Company, Inc. occupies a position as an integrated solution provider, leveraging its extensive portfolio for diverse industrial dust collection needs. Parker Hannifin Corporation, with its vast global distribution network, represents a player focused on market presence and broad accessibility across various industrial segments. These entities anchor distinct competitive approaches, from niche technological superiority to comprehensive market coverage.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Babcock & Wilcox Enterprises, Inc. |
| Donaldson Company, Inc. |
| Thermax Limited |
| W.L. Gore & Associates, Inc. |
| Eaton Corporation |
| General Electric Company |
| BWF Envirotech |
| Camfil AB |
Cost & Logistics Intelligence
The EU Green Deal's stringent emissions targets gate access for filter bag manufacturers, compelling investment in advanced materials. This mandate influences both qualified supply availability and premium-tier pricing for high-performance solutions.
Pricing Analysis
Commodity-driven pricing coexists with value-based models in the filter bag market. Pricing stratifies across premium, standard, and economy tiers, driven by filtration efficiency and material science innovation. Raw material volatility, particularly for PTFE and fiberglass, creates upstream pricing pressure. North American and European power stations, focused on Total Cost of Ownership, exhibit lower price sensitivity compared to general industrial dust collection in China, which prioritizes initial cost-effectiveness for regulatory compliance.
Supply Chain Analysis
Dual-sourcing requirements for critical filter bag components are increasingly common among large industrial buyers. Supply for raw materials like polyester, aramid, and PTFE largely concentrates in China and specific European chemical hubs. Global supply chain disruptions and energy cost fluctuations present a significant structural risk for manufacturers. Distribution runs through a blend of direct sales from integrated solution providers and extensive global networks managed by broad-portfolio companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The filter bag market functions as a stable compounder, driven by the persistent global convergence of stringent air pollution regulations. Industrial operators continuously upgrade filtration systems to meet evolving environmental mandates.
For Market Incumbents:Anticipate increased regulatory complexity by investing in advanced material science R&D for next-generation filter media. Reinforce market leadership through strategic partnerships with end-users in high-growth regions like Southeast Asia. The threat of alternative technologies like electrostatic precipitators in large-scale applications necessitates continuous product differentiation. Deepen vertical integration into specialized fiber production to mitigate raw material volatility.
For New Entrants and Emerging Players:Advanced ePTFE membrane laminates offer a technology-first wedge into high-value applications. Target the growing battery manufacturing dust segment for hazardous material capture, which is a significant white space. Focus on the SME market in Southeast Asia, particularly Vietnam, as local environmental agencies enforce stricter air quality rules. A direct sales approach emphasizing Total Cost of Ownership benefits over initial price can penetrate these emerging opportunities.
For Investors and Strategic Acquirers:Roll-up economics work for specialized filter bag manufacturers because of the fragmented nature of niche application providers. The market demonstrates long-term viability over the next 5-10 years, driven by persistent environmental compliance needs. Target acquisition profiles include regional specialists with strong intellectual property in high-performance membrane technologies. The signal to watch is the acceleration of PM2.5 targets in emerging economies, indicating future demand for premium filtration solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand ePTFE Membrane Production | Addresses demand for superior filtration efficiency in critical applications like pharmaceuticals and battery manufacturing. |
| Invest in South Asian Manufacturing Hubs | Capitalizes on infrastructure expansion and tightening environmental regulations in countries like India and Vietnam. |
| Develop TCO-focused Sales Programs | Aligns with procurement trends in North American and European power generation plants and cement facilities. |
| Form Partnerships for Waste-to-Energy Projects | Secures market share in a high-temperature application segment driven by EU Green Deal emission limits. |
| Diversify into Industrial Dust Collection Systems | Leverages existing filter bag expertise to offer complete solutions for factories in Southeast Asia. |
Research Approach
Direct dialogue with plant managers, procurement leads, environmental compliance officers, and R&D directors provided qualitative market insights. This primary research was validated through extensive secondary sources, including EPA and MEE regulatory documents, industry association reports, and material science journals. Bottom-up and top-down triangulation ensured data integrity across all segments.
A bottom-up approach aggregated segment-level data, which was then cross-referenced with top-down macroeconomic indicators over the projection horizon. Segmentation dimensions modeled included product type, application, end-user, installation type, and regional regulatory stringency. Compound annual growth rates were derived from historical trends and projected regulatory impacts. Key forecast inputs included expected industrial output growth in China and India, alongside anticipated material science advancements.
The model holds under current regulatory and economic conditions; deviation in global energy prices or unforeseen technological disruptions would shift the outlook materially. Forecasts reflect documented assumptions regarding environmental policy enforcement and industrial expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
High-Efficiency Particulate Air (HEPA) Filters Market
Filters
Zeolite Adsorbents Market
Filters
Canada Filtration and Separation Market
Filters
Global High Temperature Filters Market
Filters
Global Sterile Filtration Market
Filters
Air Filtration Media Market
Filters
Filter Paper Market
Filters
Nonwoven Filter Media Market
Filters
Industrial Filter Paper Market
Filters
Global Depth Filtration Market
Filters
Coolant Filtration Skids Market
Filters
Filter Coatings Market
Filters
Melt-Blown Polypropylene Filters Market
Filters
Filtering Centrifuges Market
Filters
Activated Carbon Filter Market
Filters
Global Filter Market