
 China Material Testing Market | 2026-2036
China Material Testing Market Size, Share, and Industry Trends Forecast 2026-2036
China Material Testing Market Intelligence
Shanghai's testing laboratory capacity is decoupling from traditional equipment import dependence as domestic certification networks mature. SGS Group leverages its joint-venture infrastructure to anchor premium service tiers along the eastern seaboard. Bureau Veritas competes through localized accreditation scope, while Hunan Innov Testing Instrument Co. sustains domestic pricing advantages in mechanical testing benches.
China material testing encompasses the systematic evaluation of physical, chemical, and thermal properties in metals, polymers, composites, and ceramics, typically performed under controlled load, temperature, or environmental conditions to verify conformance to GB/T standards or client specifications. The discipline serves primarily to prevent structural failure, extend product lifecycles, and satisfy mandatory pre-market certification across regulated industries. Mechanical testing occupies the largest revenue share due to its ubiquity in construction and automotive compliance workflows, whereas non-destructive testing represents the fastest-expanding technology segment as aerospace and electronics manufacturers pursue zero-defect quality protocols without destroying high-value components. Chemical testing margins concentrate in rare-earth and battery material certification, where supply chain traceability requirements have intensified.
MIIT mandates GB standard compliance for automotive and telecommunications materials, while SAMR oversees market-access certification and laboratory accreditation integrity. NMPA imposes biocompatibility and material purity testing on medical device substrates, creating specialized demand for cleanroom-capable labs. Stakeholders must monitor how dual carbon goals reshape material specification priorities across energy-intensive industries.
Market Dynamics
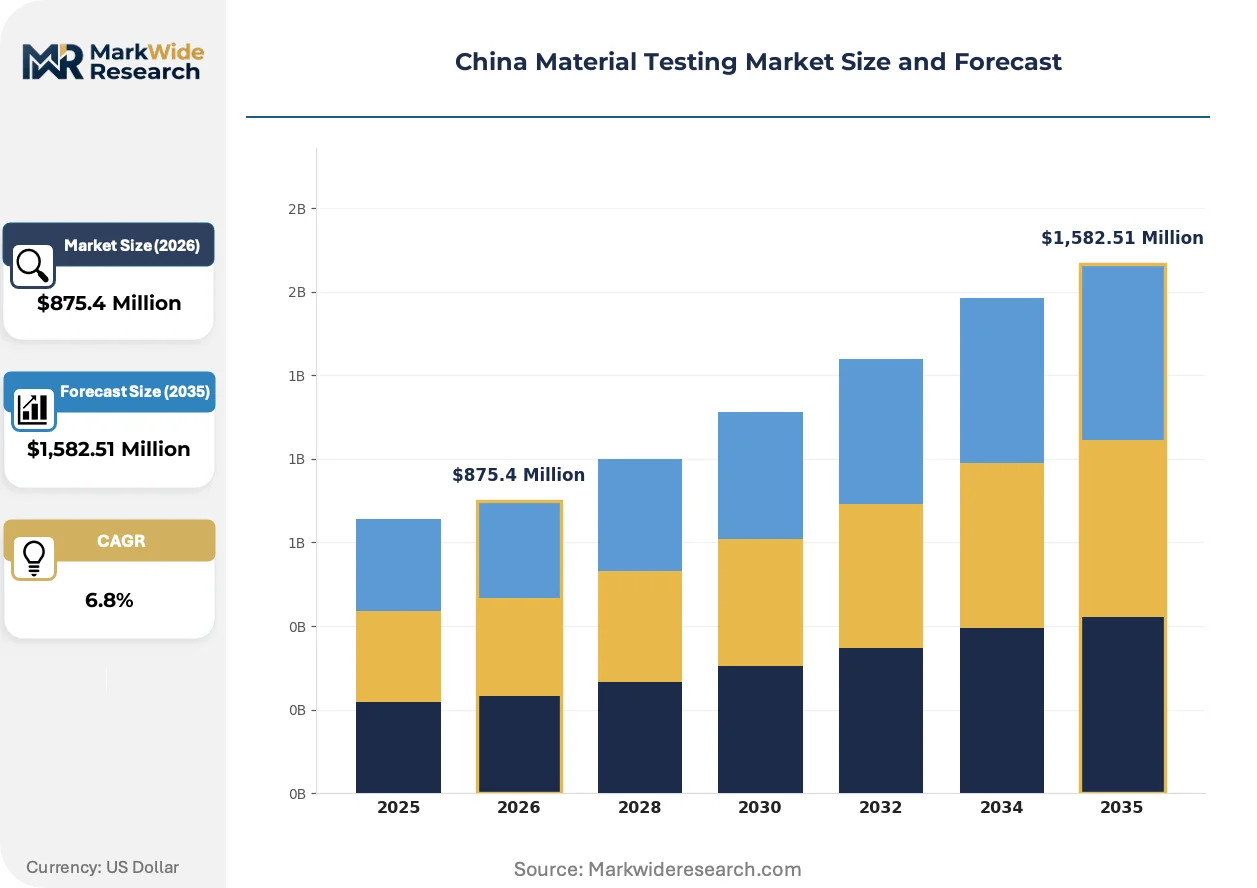
MIIT's tightening GB standard enforcement is forcing domestic manufacturers to upgrade in-house testing infrastructure rather than rely on third-party certification, fundamentally restructuring laboratory demand patterns across automotive and telecommunications supply chains.
Growth Catalysts
- Automotive electrification:Battery cell manufacturers require expanded thermal runaway and electrolyte purity testing to satisfy MIIT technical directives for new energy vehicle certification.
- GB/T standard harmonization:Alignment between national standards and ISO protocols reduces retesting costs for exporters, accelerating laboratory accreditation investments in Jiangsu and Zhejiang provinces.
- Aerospace cluster densification:Shanghai's C919 supply base generates concentrated demand for non-destructive testing services to support airframe material qualification workflows.
Market Restraints
- High-purity gas supply concentration:Argon and helium for inert atmosphere testing depend on limited domestic production, exposing laboratories to import price volatility.
- Reference material scarcity:Certified reference materials for rare-earth element analysis remain concentrated in state-controlled distributors, constraining chemical testing scale-up.
- Cross-border accreditation friction:Mutual recognition agreements between SAMR and foreign bodies lag actual trade volumes, forcing redundant testing for export-bound components.
Strategic Opportunities
- Western region laboratory networks:Chengdu and Xi'an aerospace hubs remain underserved by accredited mechanical testing facilities relative to their manufacturing growth rates.
- Dual carbon compliance services:MEE carbon intensity reporting requirements create new demand for embodied carbon testing of construction materials and industrial metals.
- Medical device substrate specialization:NMPA biocompatibility mandates for implantable devices open cleanroom-capable laboratory niches beyond traditional industrial testing.
Industry Challenges
- Metallurgist talent scarcity:Qualified failure analysis engineers with GB/T certification experience command premium wages that compress laboratory margins.
- Equipment calibration backlog:SAMR-accredited calibration providers face queue times exceeding six months for universal testing machine verification, delaying laboratory commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Material Testing Market |
| Market Size in 2026 | $875.4 Million |
| Market Size in 2035 | $1,582.51 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Testing, Fatigue Testing, Chemical Testing, Thermal Testing Application: Aerospace, Construction, Automotive Manufacturing, Electronics Technology: Non-Destructive Testing, Destructive Testing, Material Analysis, Equipment Calibration End User: Manufacturers, Research Institutions, Quality Control Labs, Regulatory Bodies |
| Companies Covered | SGS Group, Intertek Group plc, Bureau Veritas, TÜV Nord Group, DEKRA Testing & Certification Co. Ltd, ZwickRoell, Shimadzu Corporation, Hunan Innov Testing Instrument Co., China Inspection and Certification (Group) Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Material Testing Market Strategic Shifts & Innovations
Digital twin integration and automated inspection protocols are compressing traditional testing cycles while MIIT pushes real-time data reporting mandates that favor connected laboratory infrastructure over standalone equipment.
Computed tomography scanning is automating internal defect detection in additive-manufactured aerospace components. Commercial aviation suppliers in Shanghai and Xi'an adopt inline CT systems to replace destructive sectioning for titanium lattice structures. This compression of qualification timelines is automating batch release decisions previously requiring manual metallographic review.
MIIT's 2024 directive on battery material traceability mandates blockchain-linked test reporting for cathode active materials entering automotive supply chains. Cell manufacturers must submit verified chemical composition data to provincial industrial databases before shipment. This regulatory layer most heavily affects ternary lithium producers in Fujian and Hunan, which are retrofitting laboratory information management systems to enable automated data transmission.
Consolidated procurement by state-owned vehicle groups is compressing supplier lists for material testing services. SAIC and BYD now require pre-approved laboratory networks with dedicated capacity allocation, displacing fragmented spot-market contracting. This concentration is most visible in the Yangtze River Delta, where tier-one battery suppliers negotiate multi-year testing service agreements with guaranteed turnaround clauses.
China Material Testing Market Segmentation
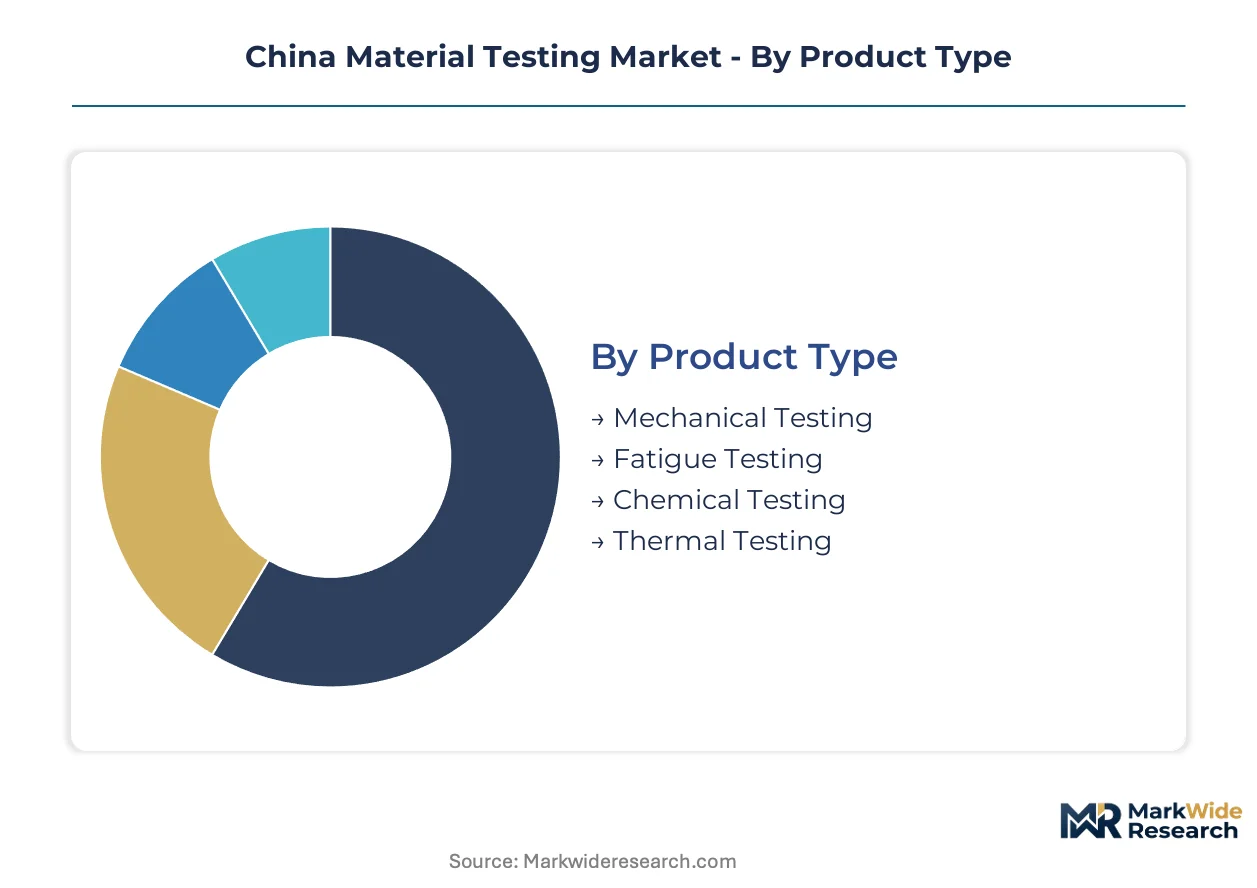
Segmentation in China's material testing market reveals how regulatory pressure and manufacturing specialization reshape service demand. Testing providers configure capabilities around GB standard enforcement intensity and end-user certification workflows rather than generic equipment categories.
Product Type:
Mechanical testing equipment specifications dominate capital allocation decisions across Yangtze River Delta manufacturing bases.
- Mechanical Testing:Universal testing machines and hardness testers verify tensile strength and deformation limits under GB/T 228 protocols. Construction steel mills in Jiangsu province deploy these systems continuously to satisfy SAMR batch-release requirements for structural reinforcement bars.
- Chemical Testing:Spectrometry and chromatography systems analyze elemental composition and contaminant thresholds in rare-earth and battery materials. Fujian cathode producers now face MIIT-mandated blockchain-linked reporting for electrolyte purity verification.
- Fatigue Testing:Cyclic load simulators assess durability limits for automotive suspension components and aerospace fasteners.
- Thermal Testing:Differential scanning calorimetry and thermogravimetric analysis characterize phase transitions in polymer composites and ceramic substrates.
Mechanical testing leads on scale; chemical testing leads on momentum.
Application:
End-use certification intensity varies sharply across manufacturing verticals, with aerospace and automotive commanding premium pricing tiers.
- Automotive Manufacturing:Battery cell thermal runaway testing and electrolyte analysis absorb the fastest-growing laboratory capacity in the Yangtze River Delta. MIIT technical directives for new energy vehicle certification force domestic OEMs to expand in-house testing infrastructure or secure dedicated third-party capacity.
- Aerospace:Non-destructive testing for C919 airframe materials concentrates demand in Shanghai and Xi'an clusters. Computed tomography scanning of titanium lattice structures replaces destructive sectioning, compressing qualification timelines for commercial aviation suppliers.
- Construction:Structural steel and concrete compliance testing follows GB 50017 standards for seismic performance verification.
- Electronics:Semiconductor substrate purity and solder joint reliability testing supports PCB manufacturing in Guangdong and Jiangsu provinces.
Automotive manufacturing leads on scale; aerospace leads on momentum.
Technology:
Technology selection hinges on whether component destruction is permissible and whether real-time data transmission satisfies MIIT reporting mandates.
- Non-Destructive Testing:Ultrasonic, radiographic, and eddy current methods detect internal defects without destroying high-value aerospace and electronics components. Shanghai's C919 supply base drives concentrated adoption of automated inspection protocols that compress traditional testing cycles.
- Destructive Testing:Tensile, compression, and impact tests remain mandatory for construction material batch certification under SAMR oversight.
- Material Analysis:Microscopy and spectroscopy techniques characterize grain structure and phase distribution for failure investigation.
- Equipment Calibration:SAMR-accredited verification services for universal testing machines face queue times exceeding six months, delaying laboratory commissioning across multiple provinces.
Destructive testing leads on scale; non-destructive testing leads on momentum.
End User:
Procurement authority concentrates with manufacturers consolidating supplier lists versus fragmented spot-market contracting.
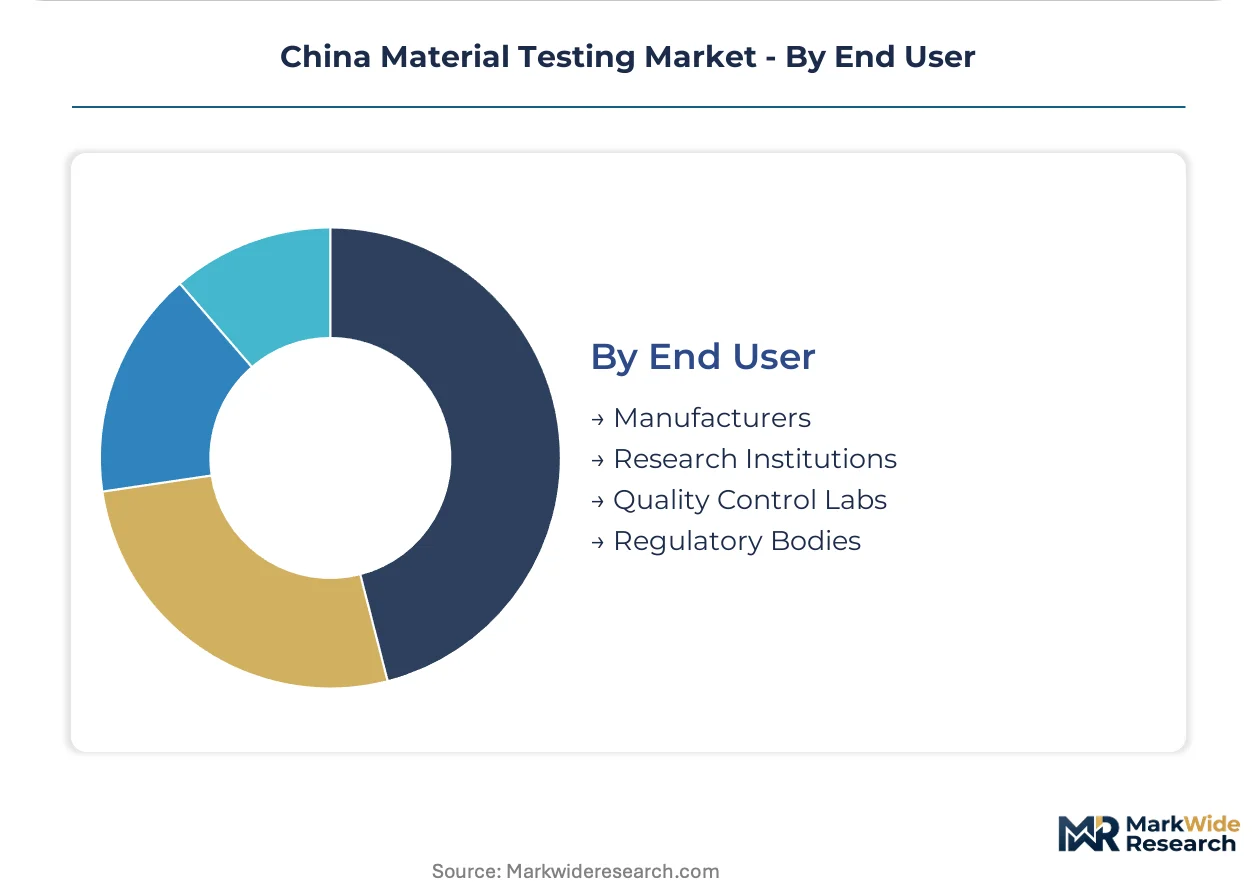
- Manufacturers:SAIC and BYD now require pre-approved laboratory networks with dedicated capacity allocation, displacing fragmented contracting patterns. State-owned vehicle groups negotiate multi-year testing service agreements with guaranteed turnaround clauses in the Yangtze River Delta.
- Quality Control Labs:Independent third-party facilities pursue SAMR accreditation expansion to capture outsourced certification demand from mid-tier suppliers.
- Research Institutions:Universities and national labs perform frontier materials characterization for defense and advanced manufacturing programs.
- Regulatory Bodies:SAMR, MIIT, and NMPA directly commission reference material validation and inter-laboratory comparison studies.
Manufacturers lead on scale; quality control labs lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the dominant share of Asia-Pacific material testing demand while Japan maintains specialized aerospace and automotive certification depth. South Korea's battery material testing infrastructure is expanding fastest among the three markets.
China
Yangtze River Delta manufacturing clusters and Pearl River Delta electronics bases absorb the bulk of mechanical and chemical testing capacity. MIIT's GB standard enforcement and SAMR accreditation mandates force continuous laboratory upgrades across Jiangsu and Guangdong provinces. Shanghai hosts the densest concentration of C919 aerospace suppliers requiring non-destructive testing protocols.
Japan
Automotive OEMs and precision electronics manufacturers sustain demand for thermal and fatigue testing systems. METI oversees JIS standard harmonization with ISO protocols to reduce export retesting burdens. Nagoya's industrial corridor concentrates automated inspection equipment deployment for Toyota and Honda supply chains.
South Korea
Battery cell producers drive the fastest capacity expansion for electrolyte purity and thermal runaway verification. MFDS regulates medical device material biocompatibility, creating specialized cleanroom laboratory demand. Seoul Capital Area hosts Samsung SDI and LG Energy Solution testing facilities with dedicated cathode material qualification workflows.
Germany
Automotive electrification and industrial machinery exports sustain premium-tier mechanical testing demand. KBA enforces material certification for vehicle structural components entering EU markets. Bavaria's automotive supplier network integrates inline CT scanning for additive-manufactured titanium components.
United States
Aerospace primes and defense contractors concentrate non-destructive testing investment in California and Washington state. FAA mandates airframe material qualification protocols that exceed commercial aviation standards. Pacific Northwest clusters around Boeing suppliers deploy automated ultrasonic inspection for composite wing structures.
China Material Testing Market Key Industry Players
European testing conglomerates anchor the premium certification tier; Chinese domestic specialists hold volume-driven mechanical equipment segments. Bureaucratic accreditation depth separates multinational laboratories from mid-tier competitors. Three archetypes dominate: global certification networks with joint-venture infrastructure, state-linked domestic equipment fabricators, and specialized NDT technology licensors. Competitive dynamics center on SAMR accreditation scope expansion and multi-year capacity reservation agreements with state-owned vehicle groups.
Within the multinational certification tier, SGS Group and Bureau Veritas occupy positions defined by localized joint-venture infrastructure and SAMR accreditation breadth. Hunan Innov Testing Instrument Co. exemplifies the domestic equipment archetype, sustaining pricing advantages in mechanical testing benches through manufacturing proximity to Yangtze River Delta demand clusters. These three entities represent the structural split between premium service networks and volume equipment supply.
| Leading Market Players |
|---|
| SGS Group |
| Intertek Group plc |
| Bureau Veritas |
| TÜV Nord Group |
| DEKRA Testing & Certification Co. Ltd |
| ZwickRoell |
| Shimadzu Corporation |
| Hunan Innov Testing Instrument Co. |
| China Inspection and Certification (Group) Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Metallurgist scarcity in the Yangtze River Delta widens pricing spreads between SAMR-accredited premium laboratories and mid-tier mechanical testing providers. GB/T certification premiums compress margins for domestic equipment fabricators competing against SGS and Bureau Veritas joint-venture networks.
Pricing Analysis
Capacity additions in Jiangsu and Zhejiang provinces are reshaping price floors for mechanical testing services as domestic laboratories expand SAMR accreditation scope. Three-tier pricing structure across premium certification, standard compliance, and economy equipment tiers separates multinational joint ventures from domestic specialists. Cost compression in economy-tier universal testing machines intensifies as Hunan Innov and regional fabricators scale production. Battery cell manufacturers show least price sensitivity due to MIIT-mandated thermal runaway testing requirements, while construction steel mills prioritize per-test cost minimization.
Supply Chain Analysis
Qualified failure analysis engineers in Shanghai and Xi'an command wage premiums that constrain laboratory commissioning timelines. Equipment manufacturing concentrates in Germany, Japan, and China, with ZwickRoell and Shimadzu supplying high-precision universal testing machines to aerospace clusters. Rare-earth certified reference materials and high-purity argon for inert atmosphere testing rest on state-controlled distribution channels. Single-source vulnerability in helium supply exposes CT scanning operations to import price volatility. Distribution runs through SAMR-accredited calibration networks with six-month queue times for universal testing machine verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT's 2024 battery material traceability directive compounds laboratory demand across cathode active material supply chains, creating structural capacity reservation opportunities.
For Market Incumbents: Deepen vertical integration into rare-earth reference material distribution to circumvent state-controlled supply bottlenecks. Secure multi-year capacity reservation agreements with SAIC and BYD procurement networks before consolidated supplier lists harden. Defend against domestic equipment fabricators by expanding SAMR accreditation scope into NMPA biocompatibility testing for medical device substrates. For New Entrants and Emerging Players: Cloud-based laboratory information management systems offer the lowest-friction entry path for ternary lithium producers requiring blockchain-linked MIIT reporting. Target cleanroom-capable biocompatibility testing niches in Xi'an and Chengdu aerospace corridors where accredited mechanical facilities lag manufacturing growth. Pursue partnership models with provincial industrial databases rather than capital-intensive equipment ownership. For Investors and Strategic Acquirers: State-owned vehicle groups are the most active acquirer in this space, consolidating pre-approved laboratory networks through dedicated capacity agreements. Long-term viability hinges on positioning at the intersection of dual carbon compliance services and automotive electrification testing. Watch for MEE carbon intensity reporting rule expansion as the inflection signal for embodied carbon testing demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Reference Materials | Secures rare-earth supply chains against state-controlled distributor concentration. |
| Multi-Year Capacity Reservation Agreements | Locks in guaranteed turnaround clauses with SAIC and BYD procurement networks. |
| SAMR Accreditation Scope Expansion | Captures NMPA biocompatibility mandates for implantable medical device substrates. |
| Blockchain-Linked LIMS Deployment | Enables automated MIIT data transmission for cathode material traceability compliance. |
| Cleanroom Laboratory Commissioning | Addresses underserved Xi'an and Chengdu aerospace hub demand for NDT services. |
Research Approach
Bottom-up automotive and aerospace demand modeling reconciled against top-down equipment import and laboratory accreditation tracking forms the analytical core of this study. Primary interviews with SAMR accreditation officers, MIIT technical directive drafters, Tier 1 battery supplier quality directors, and universal testing machine procurement managers combined with secondary validation against MIIT technical directive filings, SAMR laboratory accreditation registries, customs equipment import records, and provincial industrial database disclosures. Triangulation across these sources validates capacity utilization estimates and pricing tier boundaries.
Historical trendline analysis of laboratory commissioning rates and equipment import volumes established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product type, application vertical, testing technology, and end-user procurement authority dimensions. CAGRs were derived from regression analysis of accreditation expansion timelines and manufacturing cluster densification rates. MIIT enforcement intensity indices and dual carbon policy implementation pace served as scenario-weighting inputs.
The model assumes a particular technology adoption path; alternative pathways for computed tomography scanning automation would alter the outlook for destructive testing displacement timelines. Forecasts reflect assumptions regarding SAMR accreditation queue resolution and helium supply chain stabilization. Material deviation in MIIT enforcement intensity or MEE carbon reporting rule expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Global Distillate Oil Testing Service Market
Testing Equipment
Mud Sediment Tester Market
Testing Equipment
Durometers Market
Testing Equipment
Laboratory Ware Market
Testing Equipment
Flammability Test Chamber Market
Testing Equipment
Analytical Gel Permeation Chromatography Market
Testing Equipment
Global Chromatography Columns Market
Testing Equipment
Glass Testing Equipment Market
Testing Equipment
Glass Testing Instruments Market
Testing Equipment
Geochemical Services Market
Testing Equipment
Sand Testing Equipments Market
Testing Equipment
Global Liquid Chromatography Instruments Market
Testing Equipment
Binary High Pressure Gradient Liquid Chromatography System Market
Testing Equipment
Process Analytical Technology Market
Testing Equipment
Global Chromatography Instruments Market
Testing Equipment
Stack Emissions Real-Time Speciation and Compliance Test Systems Market