
 String Wound Filter Materials Market | 2026-2036
String Wound Filter Materials Market Size, Share, and Industry Trends Forecast 2026-2036
String Wound Filter Materials Market Outlook
Polypropylene yarn is rebalancing cost-performance economics across the string wound filter category as thermal stability improvements displace cotton and rayon in chemical processing loops. Schweitzer-Mauduit International leverages captive resin compounding to anchor North American supply security for industrial end users. Parker Hannifin Corporation competes through fluid systems integration, extending filter cartridge pull-through across hydraulic and process water accounts. Coats Group Plc dominates industrial sewing yarn supply, positioning its technical fibers as preferred feedstock for precision-wound depth filters.
String wound filter materials are cylindrical depth filtration media manufactured by spirally winding textile yarns around a perforated core, with controlled tension and spacing creating a graded density structure that traps particulates across the filter depth rather than solely at the surface; typical constructions achieve nominal ratings from 0.5 to 150 microns and operate at temperatures up to 160°F depending on yarn polymer. Polypropylene formulations lead volume given chemical inertness and cost efficiency in water treatment and food processing, while fiberglass yarns command premium positioning in high-temperature oil filtration where thermal degradation resistance determines replacement cycles. The application split reveals water treatment as the mature volume base with municipal infrastructure renewal sustaining replacement demand, whereas chemical processing represents the fastest-growing margin pool as semiconductor fabrication and battery electrolyte purification drive specification tightening.
EPA Safe Drinking Water Act amendments and NSF/ANSI Standard 42 certification requirements shape municipal procurement protocols in the United States, while China's GB standards for industrial wastewater discharge enforce filtration performance minimums that elevate product replacement frequency in manufacturing zones. ISO 2941 collapse pressure testing and ISO 4572 multi-pass filtration ratings provide cross-border quality benchmarks that determine supplier qualification for OEM channel access. Stakeholders must monitor polymer feedstock volatility and regional certification divergence to calibrate manufacturing footprint and inventory positioning against specification fragmentation.
Market Dynamics
Polypropylene yarn thermal stability advances are compressing replacement cycles in chemical processing loops while EPA filtration mandates accelerate cartridge refresh rates at municipal water treatment facilities across the United States.
Growth Catalysts
- EPA Safe Drinking Water Act amendments:Tightening filtration mandates at United States municipal plants are forcing accelerated cartridge replacement schedules, sustaining baseline demand for polypropylene and fiberglass wound media.
- Semiconductor fabrication:Battery electrolyte purification and chip manufacturing processes in China's industrial corridor surrounding Shanghai are tightening micron specifications and driving premium material pull-through.
- Polypropylene thermal stability:Next-generation resin formulations are displacing cotton and rayon cores in high-temperature chemical loops, expanding addressable process conditions.
Market Restraints
- Propylene feedstock volatility:Crude oil and natural gas price swings directly compress resin compounding margins and destabilize yarn pricing for filter manufacturers.
- China supply concentration:Industrial textile spinning capacity clusters in Zhejiang and Jiangsu provinces, creating geographic vulnerability to regional energy rationing or logistics disruption.
- Membrane filtration substitution:Hollow-fiber ultrafiltration systems are capturing share in sub-micron pharmaceutical and biotechnology applications where string wound depth filters face performance ceilings.
Strategic Opportunities
- India industrial wastewater enforcement:Central Pollution Control Board discharge mandates are elevating filtration compliance costs for textile and chemical processors in Gujarat and Tamil Nadu manufacturing zones.
- NSF/ANSI Standard 42 certification premium:Third-party validation protocols are creating pricing stratification between certified and uncertified cartridge suppliers in North American municipal procurement.
- Digital inventory integration:Predictive maintenance platforms are enabling direct-to-plant filter replenishment contracts, compressing distributor layers and capturing margin.
Industry Challenges
- ISO 4572 multi-pass testing expertise:Certified laboratory capacity for hydraulic filtration ratings remains concentrated in Germany and the United States, creating qualification bottlenecks for Asian manufacturers seeking OEM channel access.
- Core-to-yarn bonding chemistry:Adhesive selection for polypropylene-to-stainless-core attachment in high-pressure applications requires formulation expertise that resides with a narrow supplier base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | String Wound Filter Materials Market |
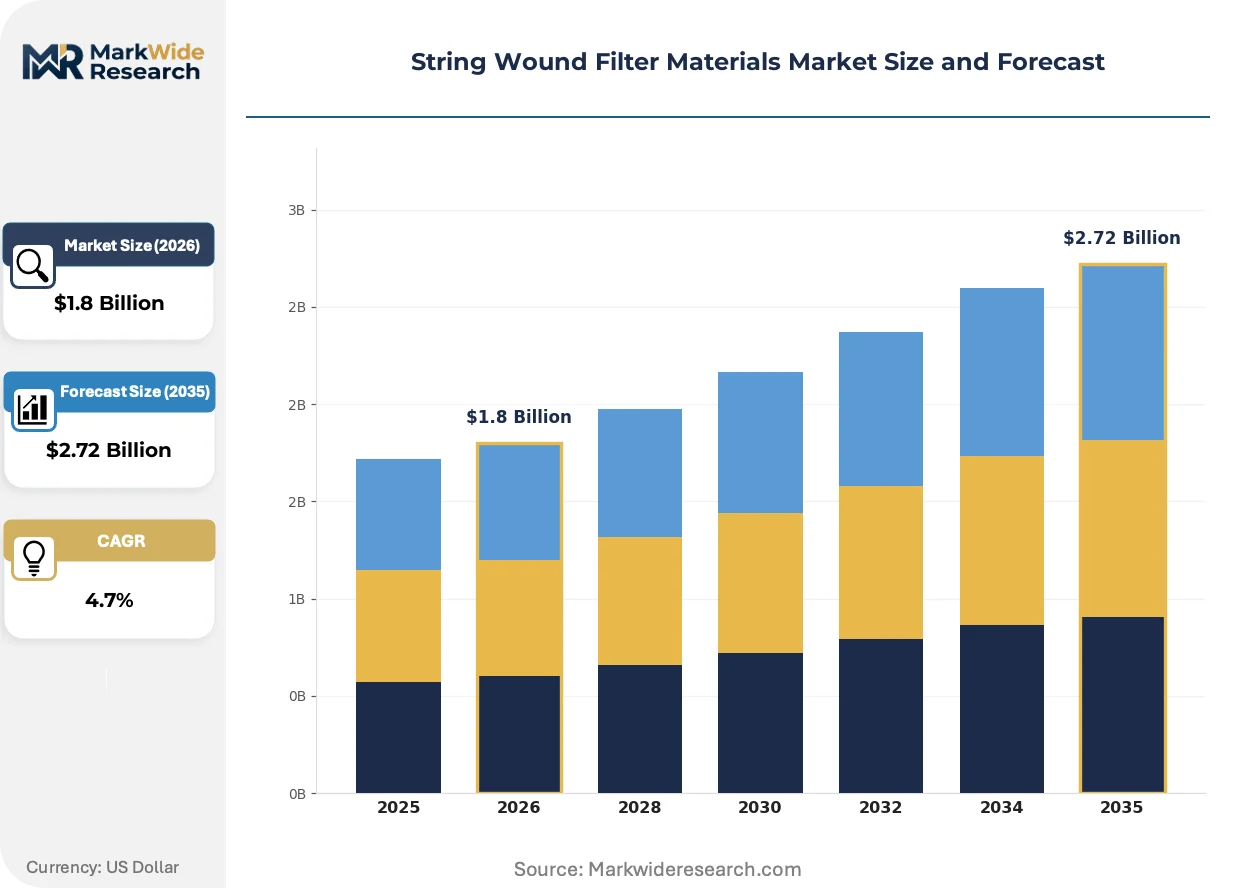
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Fiberglass, Nylon, Polyester Application: Water Treatment, Oil Filtration, Chemical Processing, Food & Beverage End User: Industrial, Municipal, Residential, Commercial Technology: Winding, Layering, Resin Coating, Pre-coating |
| Companies Covered | Schweitzer-Mauduit International, Inc., Coats Group Plc, William Barnet and Son, Micronics Engineered Filtration Group, United Filters International, Parker Hannifin Corporation, SUEZ S.A., MMP Filtration Pvt. Ltd., Hongtek Filtration Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
String Wound Filter Materials Market Strategic Shifts
Material science breakthroughs in polymer thermal stability and regulatory pressure on discharge quality are compressing filter replacement economics while reshaping procurement specifications across industrial water treatment.
Multilayer polypropylene-nylon hybrid yarns are absorbing thermal stress in chemical processing loops previously reserved for fiberglass constructions. Semiconductor foundries in Taiwan and South Korea are adopting these formulations at accelerated trial rates. The technology is absorbing margin from premium fiberglass suppliers while expanding polypropylene's addressable temperature envelope.
China's GB standards for industrial wastewater discharge are tightening suspended solids limits in manufacturing zones surrounding Shanghai and Shenzhen. Textile processors face elevated filtration performance minimums that compress cartridge service intervals. Chemical processing plants in these corridors are responding with upgraded micron ratings and more frequent changeout schedules.
Direct procurement relationships between filter manufacturers and municipal water treatment operators are displacing traditional distributor channels in the United States. Large utilities in California and Texas are consolidating supplier lists and negotiating multi-year cartridge supply agreements. This concentration is most visible in Sun Belt states where infrastructure renewal bonds are funding filtration system upgrades.
String Wound Filter Materials Market Segmentation
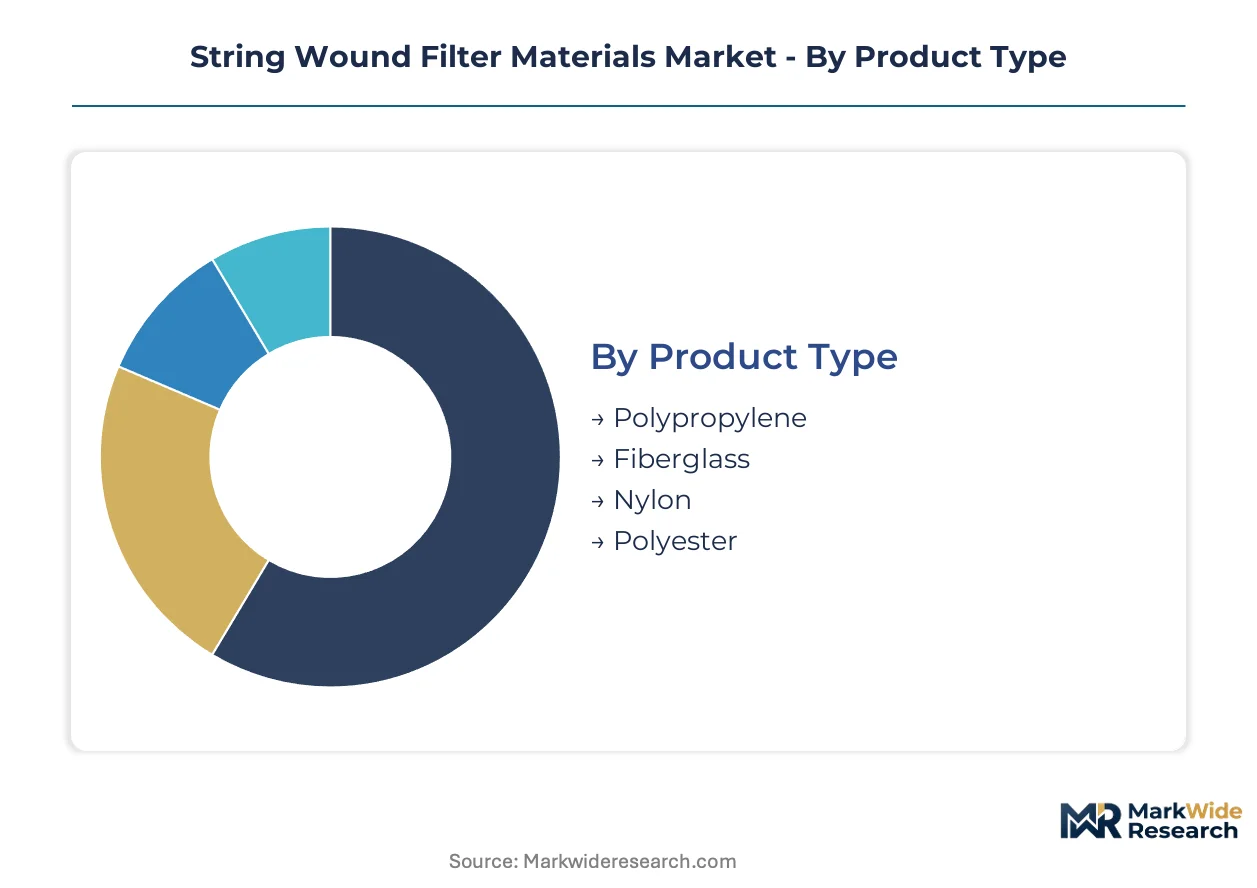
Segmentation in string wound filter materials reveals distinct procurement logics across polymer chemistry, process application, and end-user scale. Buyers prioritize thermal stability and chemical compatibility in industrial settings, while municipal operators weight certification compliance and lifecycle cost.
Product Type:
Cost-performance economics and chemical resistance drive polymer selection, with thermal envelope expansion reshaping substitution patterns between commodity and specialty yarns.
- Polypropylene:Manufactured from melt-spun isotactic polypropylene resin, this yarn delivers chemical inertness across pH 1-14 ranges and operational temperatures to 160°F. Municipal water treatment plants in the United States specify polypropylene for NSF/ANSI Standard 42 certified cartridges, with EPA Safe Drinking Water Act amendments accelerating replacement program volumes.
- Fiberglass:Continuous filament E-glass or S-glass constructions withstand temperatures exceeding 300°F in hydraulic oil and high-temperature chemical loops. Demand concentrates in semiconductor fabrication coolant systems and power generation turbine oil filtration where thermal degradation resistance determines service intervals.
- Nylon:Polyamide 6 and 6,6 yarns offer abrasion resistance and tensile strength for food processing and pharmaceutical applications requiring mechanical durability during steam sterilization cycles.
- Polyester:PET-based spun yarns provide dimensional stability and moisture resistance in general industrial water treatment where cost minimization outweighs specialty performance requirements.
Polypropylene leads on scale; fiberglass leads on momentum as thermal stability advances compress replacement economics in chemical processing.
Application:
Process severity and fluid contamination profiles dictate specification tightening, with sub-micron requirements in emerging technologies outpacing traditional water treatment refresh rates.
- Water Treatment:Municipal infrastructure renewal and industrial process water loops drive volume, with cartridge ratings from 1 to 50 microns addressing suspended solids removal. China's GB standards for industrial wastewater discharge are elevating performance minimums in manufacturing zones surrounding Shanghai.
- Chemical Processing:Battery electrolyte purification and semiconductor wet process chemicals demand 0.5 to 10 micron absolute ratings with extractables control. Taiwan and South Korea foundries are trialing multilayer polypropylene-nylon hybrids previously reserved for fiberglass constructions.
- Oil Filtration:Hydraulic fluid and lubricating oil maintenance in power generation and heavy equipment relies on fiberglass and high-temperature polypropylene formulations to manage particulate loading without viscosity degradation.
- Food & Beverage:Edible oil clarification, wine and juice filtration, and brewing operations require FDA-compliant yarn chemistries with steam sterilization compatibility.
Water treatment commands installed base volume; chemical processing climbs fastest on specification tightening in semiconductor and battery supply chains.
End User:
Procurement scale and technical capability separate direct manufacturer relationships from distributor-mediated supply, with consolidation trends favoring integrated sourcing at the largest accounts.
- Industrial:Chemical processors, refineries, and manufacturing plants specify custom micron ratings and core materials, negotiating multi-year supply agreements with direct procurement terms.
- Municipal:Water treatment authorities in California and Texas are consolidating supplier lists and negotiating multi-year cartridge agreements funded by infrastructure renewal bonds.
- Commercial:Food service, healthcare facilities, and building maintenance operations purchase through distributor channels with standardized NSF-certified SKUs.
- Residential:Point-of-use and point-of-entry systems represent replacement-driven demand with price-sensitive procurement through retail and e-commerce channels.
Industrial leads on margin contribution; municipal leads on contract duration and volume consolidation.
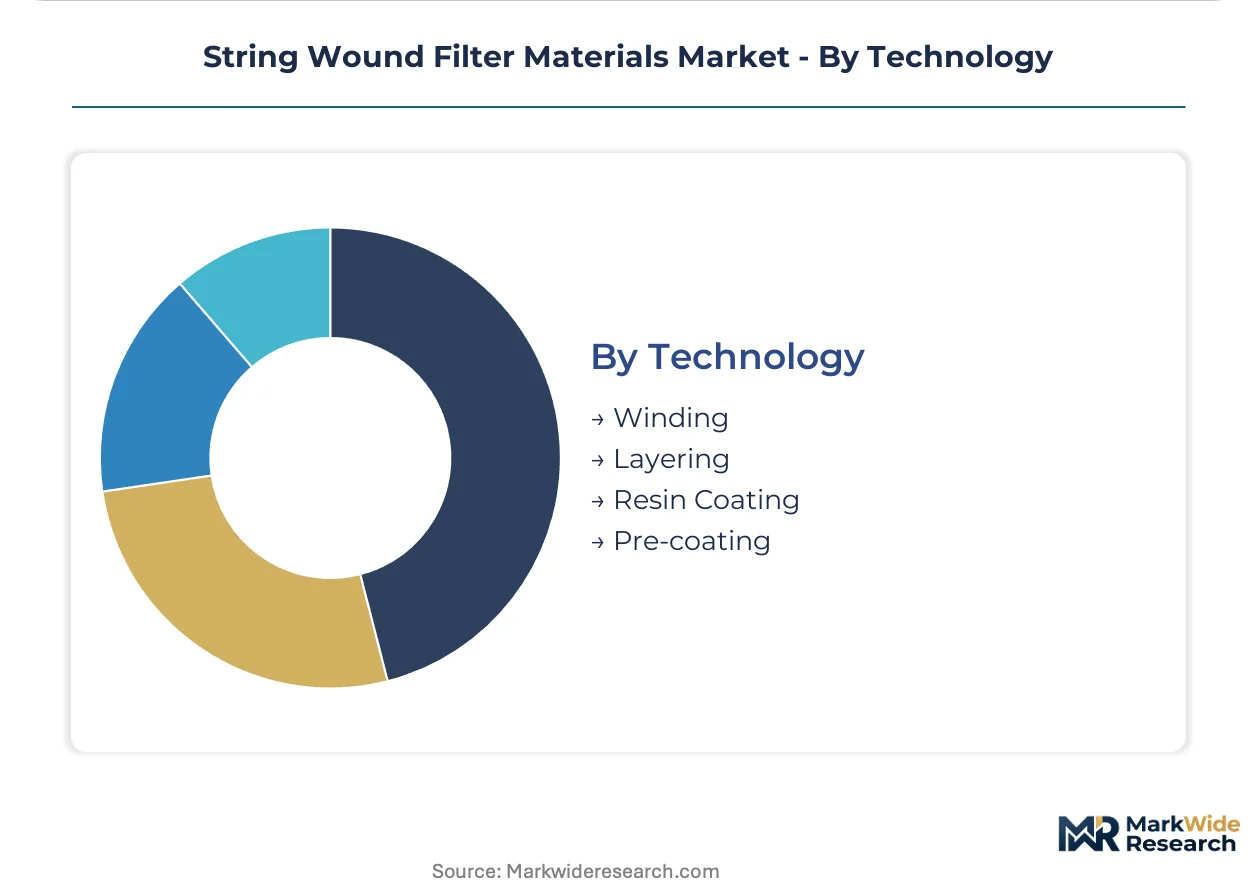
Technology:
Manufacturing process selection determines filtration efficiency, structural integrity, and chemical compatibility for specific fluid environments.
- Winding:Controlled tension spiral winding of continuous filament or spun yarn creates graded density depth filtration with nominal to absolute ratings from 0.5 to 150 microns.
- Layering:Discrete density zones engineered through sequential winding of different yarn deniers or polymer types optimize dirt-holding capacity and flow characteristics.
- Resin Coating:Thermoset or thermoplastic binders stabilize fiber matrix structure in high-differential-pressure applications, with adhesive selection critical for core-to-yarn bonding chemistry.
- Pre-coating:Surface-applied filter aids or activated media enhance initial efficiency and target specific contaminant chemistries in specialty process applications.
Winding dominates production scale; layering gains fastest on performance customization demands from semiconductor and chemical processing end users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's industrial corridor surrounding Shanghai concentrates the most intensive specification tightening for string wound filter materials, with semiconductor foundries and battery electrolyte purification plants driving sub-micron demand. Municipal water treatment renewal in the United States and industrial wastewater enforcement in India are expanding replacement program volumes across divergent regulatory frameworks.
United States
Municipal water treatment plants in California and Texas are consolidating supplier lists around multi-year cartridge agreements funded by infrastructure renewal bonds. EPA Safe Drinking Water Act amendments are accelerating replacement schedules at facilities serving Sun Belt population growth. Industrial chemical processors along the Gulf Coast are specifying thermal-stabilized polypropylene for high-temperature process loops.
China
Semiconductor fabrication and battery electrolyte purification in the Yangtze River Delta are tightening micron specifications beyond traditional water treatment baselines. GB standards for industrial wastewater discharge are elevating filtration performance minimums in manufacturing zones surrounding Shanghai. Textile processors in Zhejiang province are responding with upgraded cartridge ratings and compressed service intervals.
Germany
Automotive hydraulic systems and power generation turbine oil maintenance are sustaining demand for high-temperature fiberglass constructions. REACH compliance requirements are shaping polymer selection protocols for chemical processing applications. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia are specifying ISO 4572-certified cartridges for OEM equipment integration.
India
Central Pollution Control Board discharge mandates are elevating filtration compliance costs for textile and chemical processors in Gujarat and Tamil Nadu manufacturing zones. Industrial wastewater treatment plants in these corridors are expanding cartridge replacement frequencies to meet tightening suspended solids limits. Domestic yarn spinning capacity is scaling to reduce import dependence from Zhejiang and Jiangsu suppliers.
Japan
Precision electronics manufacturing and pharmaceutical processing in the Kanto and Kansai regions are driving absolute-rated cartridge specifications with extractables control. METI industrial efficiency guidelines are promoting predictive maintenance platforms that compress filter replacement cycles. Semiconductor material suppliers in Kyushu are trialing multilayer polypropylene-nylon hybrid yarns for wet process chemical filtration.
String Wound Filter Materials Market Competitive Environment
Global majors compete with regional champions across resin compounding and fluid systems integration, creating a tiered structure where captive raw material supply separates premium positioning from commodity competition. The vendor base distributes across integrated polymer producers, specialized yarn spinners, and filter cartridge assemblers with varying degrees of backward control. Three archetypes dominate: resin-integrated manufacturers with captive polypropylene supply, precision yarn specialists serving technical filtration specifications, and fluid systems integrators bundling cartridges with hydraulic and process equipment. Competitive moves concentrate on direct procurement relationships with municipal utilities and semiconductor foundries, plus certification investments for NSF/ANSI and ISO qualification bottlenecks.
Among North American resin-integrated players, Schweitzer-Mauduit International anchors supply security through captive compounding capabilities. Parker Hannifin Corporation occupies a position as a fluid systems integrator extending filter pull-through across hydraulic accounts. Coats Group Plc exemplifies the precision yarn specialist archetype, with technical fiber positioning as preferred feedstock for depth filter construction. These three represent distinct competitive vectors: upstream material control, downstream system bundling, and intermediate component specialization.
| Leading Market Players |
|---|
| Schweitzer-Mauduit International, Inc. |
| Coats Group Plc |
| William Barnet and Son |
| Micronics Engineered Filtration Group |
| United Filters International |
| Parker Hannifin Corporation |
| SUEZ S.A. |
| MMP Filtration Pvt. Ltd. |
| Hongtek Filtration Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
EPA Safe Drinking Water Act amendments gate qualified supply for municipal cartridge procurement and simultaneously stratify pricing access across certified and uncertified supplier tiers. Municipal water treatment operators in California and Texas consolidate supplier lists around multi-year agreements, compressing distributor margins while elevating certified manufacturers to premium pricing positions.
Pricing Analysis
Propylene resin cost pass-through directly compresses yarn pricing for filter manufacturers and destabilizes contract negotiations across the supply base. Three-tier pricing structure across premium, standard, and economy levels separates NSF/ANSI Standard 42 certified cartridges from uncertified alternatives and commodity imports. Pricing pressure stems from propylene feedstock volatility tied to crude oil and natural gas swings. Municipal procurement teams exhibit lowest price sensitivity given regulatory compliance mandates, while residential point-of-use buyers drive aggressive cost minimization.
Supply Chain Analysis
Dual-sourcing requirements from semiconductor foundries and municipal utilities mandate multi-supplier qualification that fragments procurement across competing yarn spinners. Manufacturing gravity centers on China, the United States, and Germany for resin compounding and precision winding equipment. Raw material dependencies span isotactic polypropylene resin, continuous filament E-glass, and polyamide 6,6 polymer. Single-source vulnerability concentrates in Zhejiang and Jiangsu provinces where energy rationing disrupts textile spinning capacity. Distribution runs through direct manufacturer relationships with large utilities and semiconductor accounts, bypassing traditional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
String wound filter materials function as a stable compounder anchored by infrastructure replacement cycles and regulatory compliance mandates that sustain baseline demand regardless of macroeconomic volatility.
For Market Incumbents: Hedge against membrane filtration substitution by accelerating thermal stability R&D in polypropylene-nylon hybrid formulations. Secure captive resin compounding capacity to insulate margin from propylene volatility. Defensive consolidation through ISO 4572 certification investment locks out Asian competitors seeking OEM channel access.
For New Entrants and Emerging Players: Mid-sized Indian textile processors facing Central Pollution Control Board discharge mandates represent an underserved buyer archetype with compressed procurement sophistication and urgent compliance timelines. White-space targets include Gujarat and Tamil Nadu manufacturing zones with elevated cartridge replacement frequencies. A technical service bundled with rapid certification support captures share from distant Chinese suppliers.
For Investors and Strategic Acquirers: Valuations sit cheapest among precision yarn specialists with technical fiber positioning but limited backward integration into resin supply. The five-to-ten year viability framing favors manufacturers with NSF/ANSI and ISO qualification depth that barriers Asian competition. Acquisition targets include regional cartridge assemblers with municipal utility relationships. The signal to watch is semiconductor foundry qualification timelines for multilayer hybrid yarns.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polypropylene supply insulates margin from propylene volatility and secures municipal contract pricing power. |
| ISO 4572 Certification Investment | Multi-pass filtration laboratory qualification unlocks OEM equipment integration channels in Germany and the United States. |
| Multilayer Hybrid Yarn Development | Polypropylene-nylon thermal stability expansion displaces fiberglass in semiconductor wet process chemical loops. |
| Direct Municipal Utility Relationships | Multi-year cartridge agreements with California and Texas water treatment authorities compress distributor margin capture. |
| India Manufacturing Footprint Expansion | Domestic yarn spinning capacity reduces import dependence from Zhejiang and Jiangsu suppliers for CPCB compliance demand. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at municipal water treatment facilities, procurement leads at semiconductor foundries, filtration equipment OEMs, and resin compounding specialists with secondary validation. Trade data from customs records, EPA enforcement databases, SEC 10-K filings from listed materials companies, and GB standards documentation from China's Standardization Administration anchored supply-side modeling. Bottom-up cartridge demand estimates triangulated against top-down polymer consumption figures.
Segment-weighting approaches distributed value and volume across polymer chemistry, application severity, and end-user procurement scale dimensions throughout the projection horizon. Modeled dimensions included polypropylene versus fiberglass versus nylon yarn types, water treatment versus chemical processing versus oil filtration applications, and municipal versus industrial versus commercial end-user tiers. CAGRs derived from replacement cycle compression rates tied to regulatory mandate tightening and specification elevation in semiconductor fabrication. Industry-specific inputs encompassed EPA Safe Drinking Water Act amendment implementation timelines and China's GB wastewater discharge standard revision schedules.
Underlying measurement precision varies by segment; municipal water treatment replacement volumes carry tighter precision than emerging semiconductor fabrication demand. Forecasts reflect assumptions regarding regulatory enforcement continuity and resin thermal stability advancement trajectories. Deviation in propylene feedstock pricing or semiconductor capital expenditure cycles would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Fiberglass Filters Market
Filters
Global Cartridge Filters Market
Filters
North America Gas Filtration Media Market
Filters
Global Gas Phase Filtration Market
Filters
Ceramic Filters Market
Filters
Activated Carbon Market
Filters
High Purity Chemical Filters Market
Filters
Filter Coatings Market
Filters
Nonwoven Air Conditioning Filter Market
Filters
Air Filtration Media Market
Filters
US Baghouse Filters Market
Filters
Filter Bag Market
Filters
GCC Industrial Air Filtration Market
Filters
Global Lamella Clarifier Market
Filters
Drum Filters Market
Filters
Global Pleated Filters Market