
 Filter Media Market | 2026-2036
Filter Media Market Size, Share, and Industry Trends Forecast 2026-2036
Filter Media Market Analytics
Market Context
EPA National Ambient Air Quality Standards is realigning capital deployment across the filtration value chain. DuPont leverages its fluoropolymer chemistry leadership to dominate high-temperature membrane supply for coal-fired plant retrofits. Freudenberg Group anchors European automotive cabin air demand through its nonwoven composites platform. Donaldson Company competes in industrial dust collection through specialized pleated cartridge designs.
Technical Definition and Segments
Filter media encompasses porous materials engineered to separate particulate matter from fluid streams, with pore ratings spanning 0.1 to 100 microns depending on polypropylene, glass fiber, or activated carbon substrate selection. Synthetic media leads product type revenue due to chemical resistance in corrosive process environments, while activated carbon commands premium positioning in beverage filtration for contaminant adsorption. Glass fiber occupies mature volume share in HVAC applications where temperature stability outweighs disposal cost concerns.
Regulatory Frame
FDA food contact substance regulations and OSHA permissible exposure limits shape material selection and validation protocols for filtration systems in food processing and manufacturing facilities. The EU F-Gas Regulation and REACH chemical restrictions are forcing reformulation of membrane binders and support layers. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions to anticipate raw material substitution timelines.
Market Dynamics
EPA National Ambient Air Quality Standards enforcement is compressing replacement cycles across coal-fired generation, forcing utilities to accelerate synthetic membrane procurement ahead of regulatory deadlines rather than deferring capital maintenance.
Growth Catalysts
- Mercury and Air Toxics Standards:MATS compliance deadlines in US power generation are mandating high-efficiency particulate filtration retrofits, creating immediate demand for pleated synthetic cartridges rated below 2.5 microns.
- Semiconductor fab construction:Taiwan, South Korea, and Arizona facility buildouts require ultra-pure water systems with 0.1-micron membrane arrays, concentrating procurement for polyethersulfone and PVDF substrates.
- Activated carbon reactivation services:Industrial buyers in beverage and pharmaceutical sectors are outsourcing spent carbon regeneration rather than landfill disposal, expanding the service-attached media model.
Market Restraints
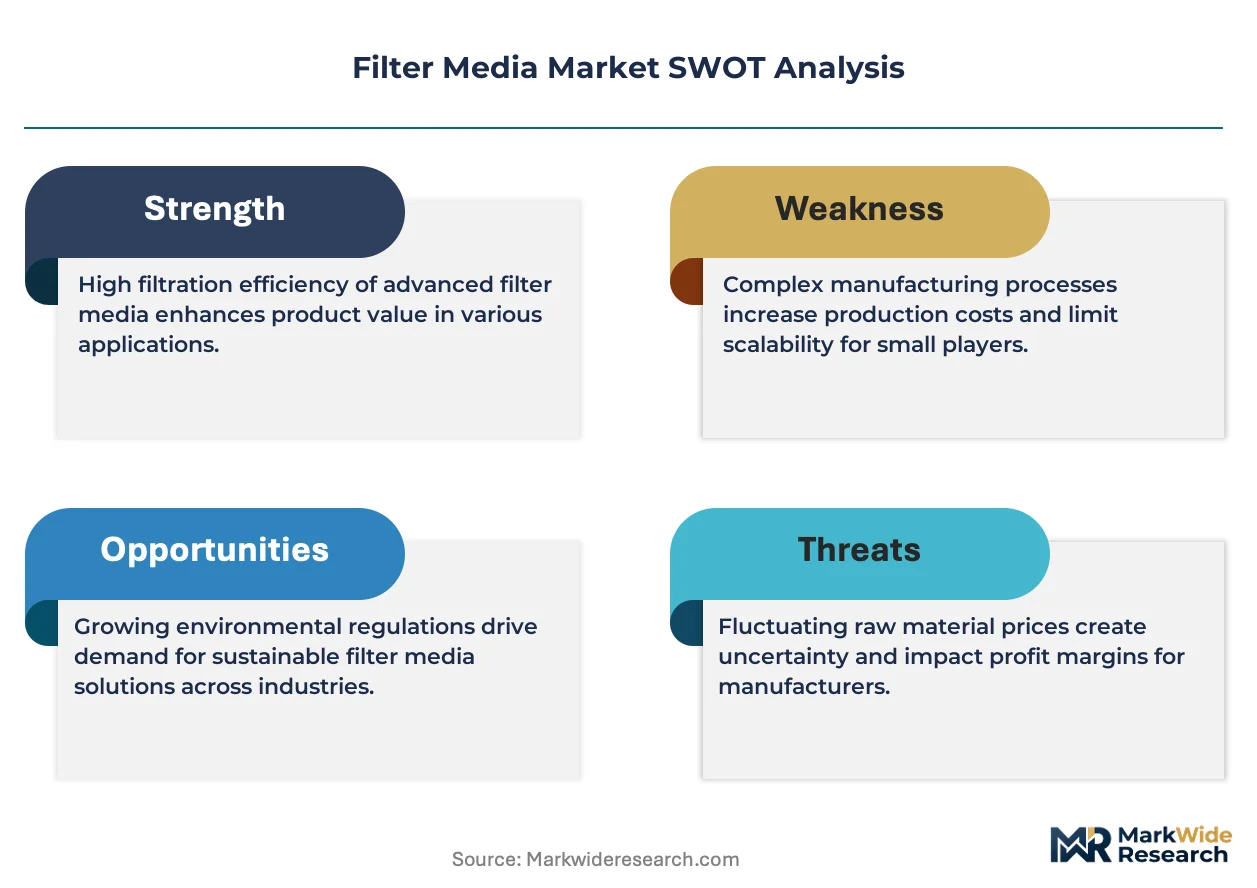
- Fluoropolymer feedstock concentration:PTFE and PVDF resin supply concentrates among three Japanese and Chinese chemical conglomerates, exposing membrane fabricators to force majeure pricing volatility.
- Glass fiber disposal economics:Hazardous waste classification of spent HVAC filters in Germany and California imposes landfill diversion costs that compress margins on low-value replacement cycles.
- Per- and polyfluoroalkyl substance restrictions:REACH and state-level US bans on PFAS are forcing reformulation of membrane binders and support scrims, extending R&D timelines by 18-24 months.
Strategic Opportunities
- India municipal water infrastructure:AMRUT 2.0 city water scheme allocations are expanding membrane bioreactor deployments in tier-2 cities, creating first-mover positions for foreign technology licensors.
- Hydrogen electrolyzer cathode air filtration:PEM stack manufacturers require sub-micron particulate control to protect platinum catalyst layers, opening specialty media specifications absent incumbent supply.
- Direct-to-facility e-procurement platforms:Industrial MRO distributors are launching subscription filter replacement programs, capturing lifetime value through predictive consumption algorithms.
Industry Challenges
- Membrane casting technician scarcity:Solvent-phase inversion and track-etching process expertise concentrates among retiring European and Japanese specialists, constraining quality-scaled production expansion.
- Multi-jurisdiction PFAS compliance:Divergent EPA, ECHA, and state-level substance restrictions force parallel product line maintenance, fragmenting production runs and inflating inventory carrying costs.
- Legacy HVAC system interface standards:Building automation protocols in installed base equipment lack digital pressure-drop monitoring, blocking predictive maintenance upsell to facility managers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Filter Media Market |
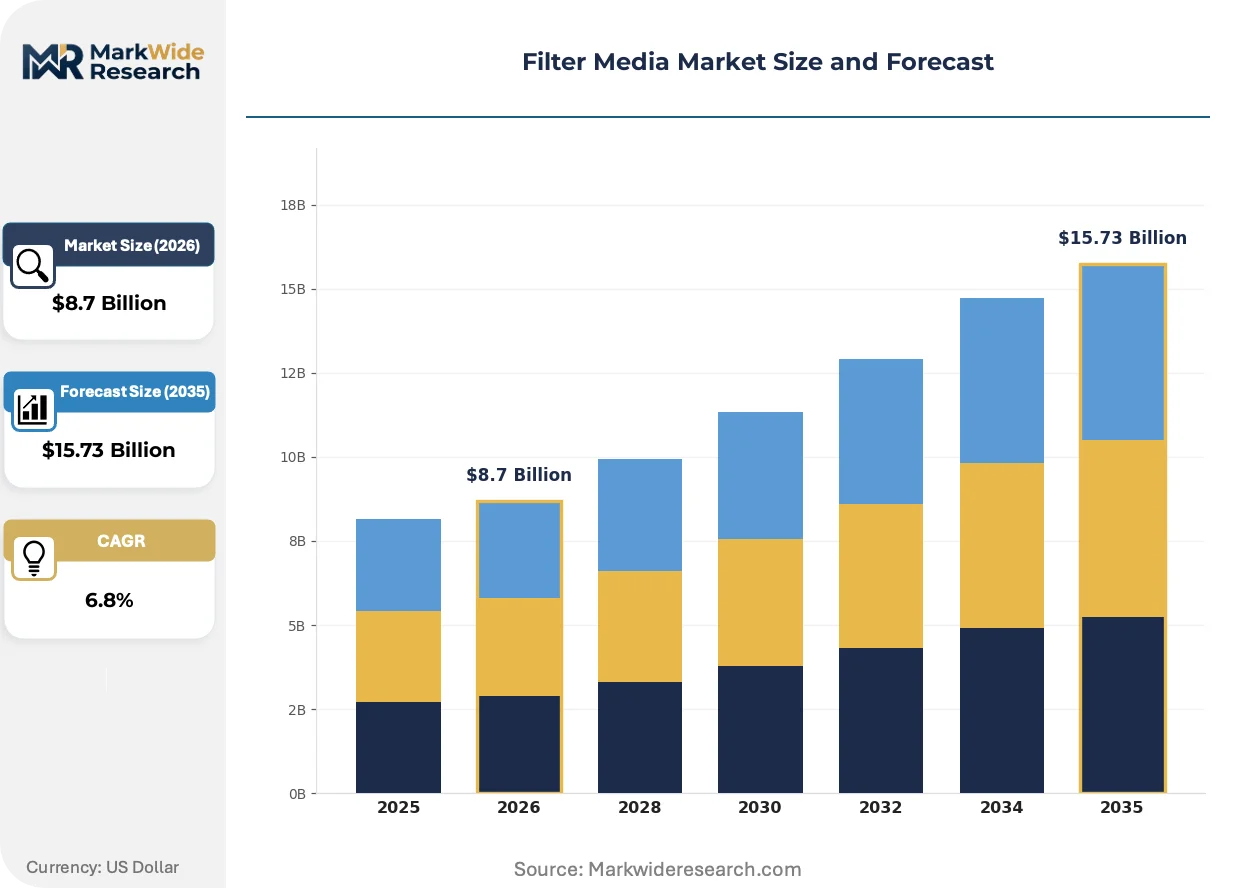
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activated Carbon, Synthetic Media, Glass Fiber, Fiber Media End User: Water Treatment, Air Filtration, Industrial Processes, HVAC Systems Material: Polyester, Polypropylene, Metal, Cotton Application: Dust Collection, Oil Filtration, Chemical Processing, Beverage Filtration |
| Companies Covered | DuPont, Freudenberg Group, 3M, Parker-Hannifin Corporation, Johns Manville, Donaldson Company, Inc., Ahlstrom-Munksjo Oyj, Sandler Group, Mann+Hummel International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Filter Media Market Evolving Landscape
Electrospun nanofiber deposition is compressing the performance gap between conventional meltblown and membrane technologies, enabling mid-tier pricing for sub-micron efficiency ratings previously reserved for fluoropolymer products.
Nanofiber surface loading media is overtaking depth-loading cellulose in industrial dust collection. Power generation and cement plant operators are specifying nanofiber-laminated pleated cartridges to extend filter life by 40-60% in high-humidity environments. This technology is overtaking conventional cellulose-polyester blends in applications where pulse-cleaning energy costs dominate total cost of ownership calculations.
EU F-Gas Regulation phase-down schedules are eliminating hydrofluorocarbon blowing agents in membrane support foam production. German and Italian membrane fabricators are reformulating with pentane and CO2-based alternatives, accepting 15-20% thermal conductivity penalties in exchange for compliance continuity. HVAC original equipment manufacturers in Northern Europe are qualifying these reformulated supports for 2027 product generations.
Consolidated procurement through integrated facility management contracts is displacing fragmented MRO purchasing. Multinational food and beverage processors are awarding five-year filtration service contracts to single-source providers, bundling media supply with changeout labor and waste handling. This concentration is most visible in Benelux and US Midwest dairy processing clusters, where three contractors now control 60% of membrane replacement volume.
Filter Media Market Segmentation
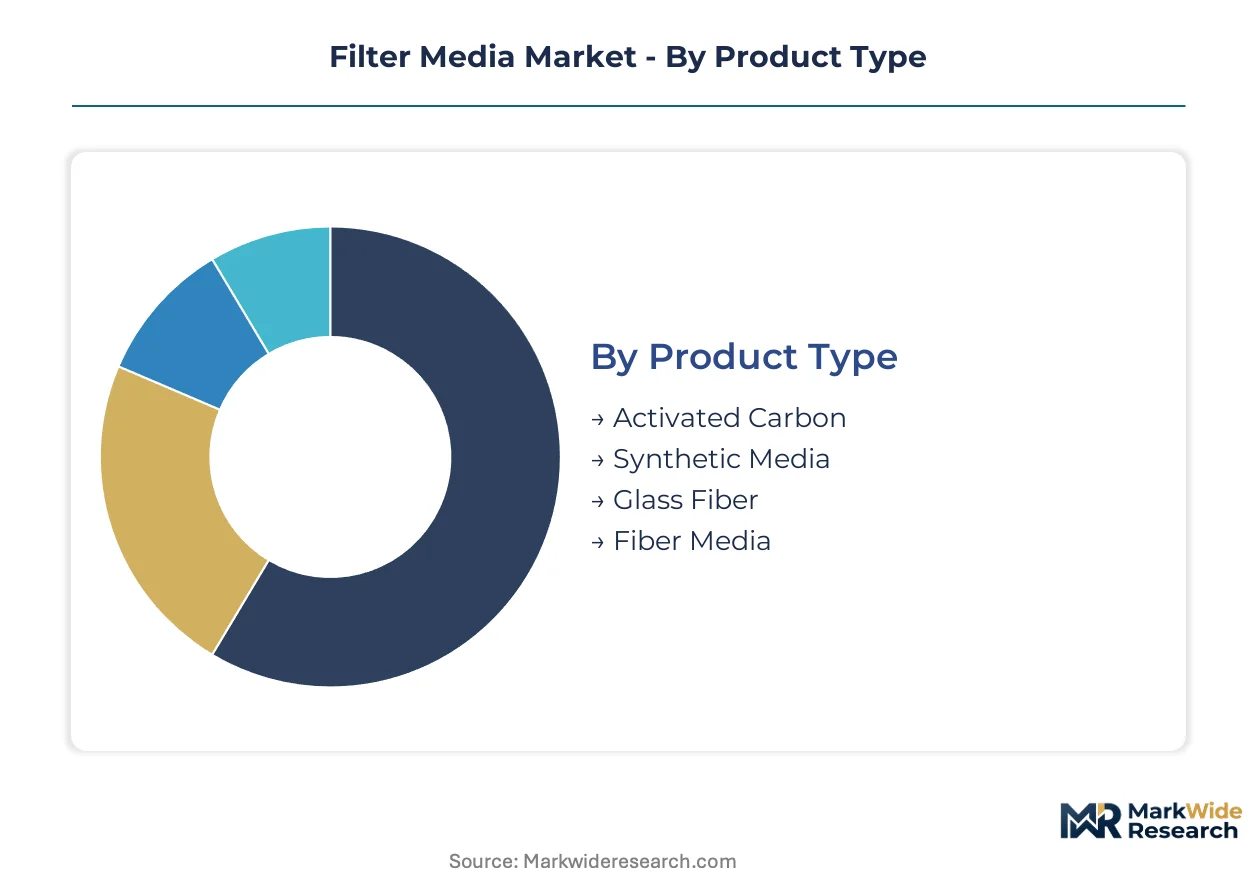
Filter media procurement decisions pivot on chemical compatibility, temperature tolerance, and disposal economics. Buyers select substrates based on contaminant type and regulatory pressure rather than commodity pricing alone.
Product Type:
Cost tier differentiation separates premium chemical-resistant formulations from commodity cellulose alternatives.
- Activated Carbon:Porous carbon substrates engineered for adsorption of organic compounds and chlorine. Beverage processors in Germany and California specify reactivatable grades to avoid landfill penalties under hazardous waste rules.
- Synthetic Media:Polymer-based nonwovens including polypropylene and PTFE laminates. US power generators facing EPA MATS deadlines are accelerating procurement of pleated synthetic cartridges rated below 2.5 microns.
- Glass Fiber:Borosilicate microfiber mats for high-temperature stability. HVAC replacement demand concentrates in commercial buildings where disposal economics matter less than fire safety ratings.
- Fiber Media:Cellulose and blended natural fiber substrates for general industrial dust collection. Cement plants in India specify these for pulse-jet systems where humidity stays moderate.
Synthetic media leads volumes today; activated carbon is gaining share fastest.
End User:
Application maturity determines whether buyers prioritize performance specifications or total cost of ownership.
- Water Treatment:Membrane bioreactors and ultrafiltration systems for municipal and industrial purification. India's AMRUT 2.0 scheme is expanding membrane deployments in tier-2 cities.
- Air Filtration:HVAC and cleanroom particulate control. Semiconductor fabs in Taiwan and Arizona require sub-micron efficiency for wafer production environments.
- Industrial Processes:Chemical, pharmaceutical, and food manufacturing filtration. OSHA permissible exposure limits mandate validated media selection for worker protection.
- HVAC Systems:Commercial and residential building air handling. EU F-Gas Regulation is forcing reformulation of membrane support foams in Northern European equipment.
Water treatment leads volumes today; air filtration is expanding most quickly.
Material:
Supply concentration risk varies sharply by polymer chemistry and geographic sourcing.
- Polyester:Thermoplastic polymer spunbond and meltblown nonwovens. Automotive cabin air demand in Germany anchors volume through Freudenberg's nonwoven composites platform.
- Polypropylene:Chemically resistant thermoplastic for corrosive process streams. PTFE and PVDF resin supply concentrates among Japanese and Chinese chemical conglomerates, exposing fabricators to pricing volatility.
- Metal:Stainless steel and specialty alloy wire mesh for high-temperature or high-pressure applications. Hydrogen electrolyzer manufacturers are specifying sub-micron sintered metal for cathode air protection.
- Cotton:Natural cellulose fiber for food-grade and biodegradable applications. Limited to low-temperature, non-corrosive environments where compostability outweighs synthetic durability.
Polyester leads volumes today; polypropylene is climbing the fastest.
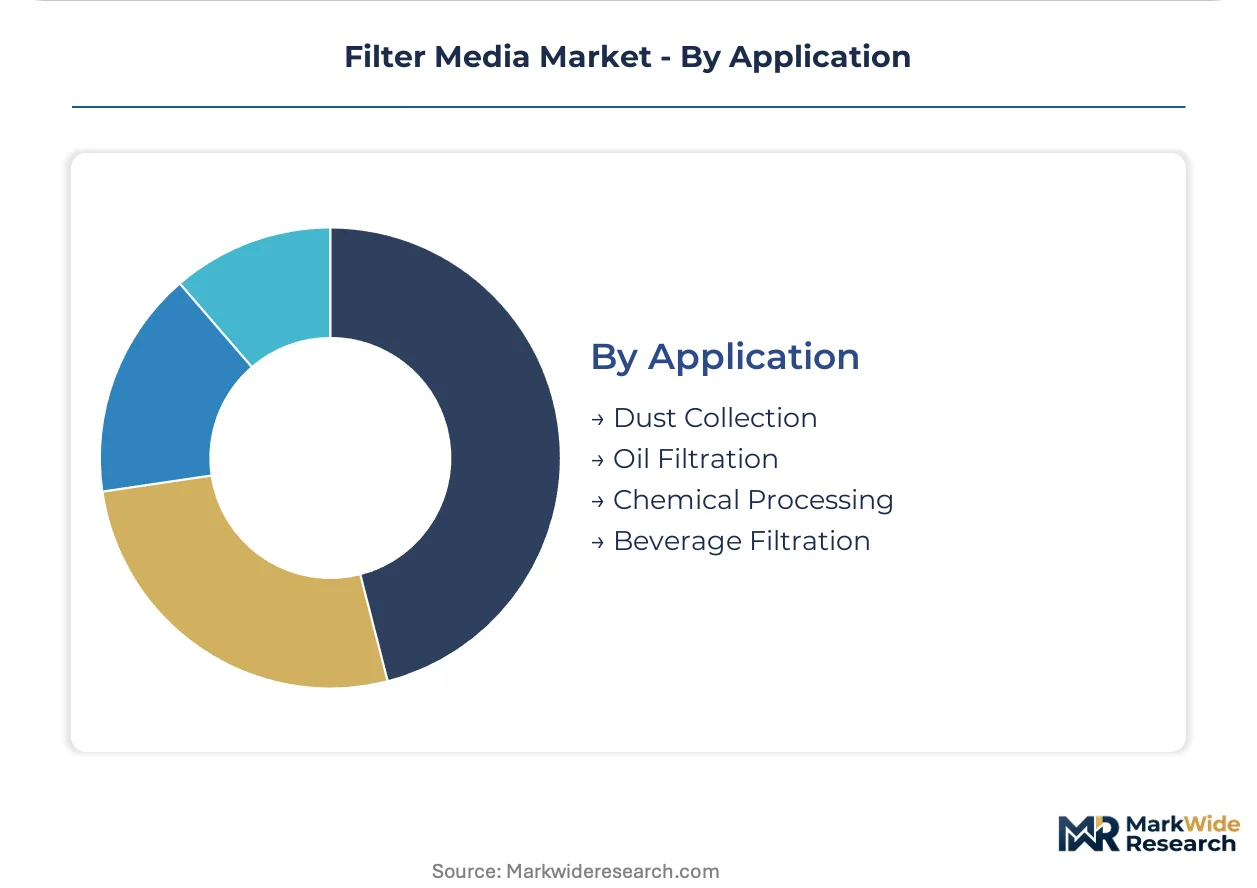
Application:
Customer type fragmentation separates heavy industrial buyers from precision manufacturing and consumables processors.
- Dust Collection:Pleated cartridge and baghouse systems for particulate control. Nanofiber-laminated designs are extending filter life by 40-60% in high-humidity cement and power generation environments.
- Oil Filtration:Hydraulic and lubricant fluid purification for machinery protection. Mining and construction equipment fleets specify high-collapse-pressure media for severe-duty cycles.
- Chemical Processing:Corrosive fluid and gas separation in petrochemical and specialty chemical plants. REACH chemical restrictions are forcing reformulation of membrane binders and support scrims.
- Beverage Filtration:Wine, beer, and bottled water clarification with adsorptive and membrane stages. Integrated facility management contracts are consolidating procurement in Benelux and US Midwest dairy clusters.
Dust collection leads volumes today; beverage filtration is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Membrane casting technicians concentrate in Germany and Japan, constraining quality-scaled production expansion elsewhere. Their expertise anchors regional competitive positioning.
United States
EPA Mercury and Air Toxics Standards enforcement compresses replacement cycles across coal-fired generation. Utilities accelerate synthetic membrane procurement ahead of regulatory deadlines. Arizona semiconductor fabs require ultra-pure water systems with sub-micron membrane arrays.
Germany
EU F-Gas Regulation phase-down eliminates hydrofluorocarbon blowing agents in membrane support foam. Freudenberg Group anchors automotive cabin air demand through nonwoven composites. Hazardous waste classification of spent HVAC filters imposes landfill diversion costs.
China
PTFE and PVDF resin supply concentrates among domestic chemical conglomerates, exposing fabricators to force majeure pricing volatility. Municipal water infrastructure expansion drives membrane bioreactor deployments. Yangtze River Delta cities concentrate procurement for industrial filtration.
India
AMRUT 2.0 city water scheme allocations expand membrane bioreactor deployments in tier-2 cities. BIS standards shape material selection protocols. Gujarat and Maharashtra industrial clusters create first-mover positions for foreign technology licensors.
Japan
Solvent-phase inversion and track-etching process expertise concentrates among retiring specialists. METI industrial standards validate membrane performance claims. Osaka-Kobe manufacturing corridor maintains specialty media specifications for hydrogen electrolyzer applications.
Filter Media Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive polymer chemistry capabilities. Consolidation concentrates among European and North American entities with backward integration into fluoropolymer resin supply. Three archetypes dominate: integrated materials-science conglomerates, specialized filtration-system fabricators, and regional nonwoven producers. Capacity expansion and technology licensing represent the dominant competitive moves.
Among diversified materials-science conglomerates, DuPont exemplifies the integrated archetype through fluoropolymer chemistry leadership. Freudenberg Group occupies a position within specialized filtration-system fabricators, anchoring European automotive cabin air demand. Donaldson Company represents the industrial dust-collection specialist tier, competing through pleated cartridge designs. These three entities collectively illustrate the competitive spectrum from upstream chemical control to application-specific engineering.
| Leading Market Players |
|---|
| DuPont |
| Freudenberg Group |
| 3M |
| Parker-Hannifin Corporation |
| Johns Manville |
| Donaldson Company, Inc. |
| Ahlstrom-Munksjo Oyj |
| Sandler Group |
| Mann+Hummel International GmbH |
| Others |
Value Network & Pricing Analysis
Electrospun nanofiber deposition is compressing cost economics for sub-micron filtration while simultaneously concentrating production capability among European and Japanese equipment specialists with proprietary multi-nozzle array technology. This manufacturing transition rewards early capital deployment in precision fiber spinning infrastructure, reshaping pricing power toward technology licensors and away from commodity meltblown converters.
Pricing Analysis
Bundled service contracts separate pricing trajectories from unbundled media-only transactions. Three-tier pricing structure across premium fluoropolymer membranes, standard synthetic nonwovens, and economy cellulose blends anchors the market. Price differentiation rests on reactivation service inclusion and MATS compliance certification tier. Cost compression in economy cellulose tiers is intensifying because cement plant buyers in India prioritize pulse-jet energy savings over media lifespan. Municipal water utilities exhibit highest price sensitivity; semiconductor fabs show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and Chinese chemical conglomerates controlling PTFE and PVDF resin supply. Raw material flows draw from fluoropolymer feedstock streams, borosilicate glass fiber melt capacity, and activated carbon reactivation infrastructure. Geographic supply concentration clusters in Germany, Japan, and China. Tariff exposure on fluoropolymer imports threatens membrane fabricator margins. Distribution runs through integrated facility management contractors consolidating five-year service agreements in Benelux and US Midwest dairy clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Filter Media Market functions as a stable compounder where regulatory compliance mandates create non-discretionary replacement demand across power generation and water infrastructure. EPA MATS deadlines and EU F-Gas phase-down schedules institutionalize revenue visibility.
For Market Incumbents: Extend fluoropolymer chemistry leadership through captive resin supply agreements with Japanese chemical conglomerates. Defend against nanofiber substitution threats by embedding predictive pressure-drop monitoring into HVAC system retrofits. Prioritize certification investment for hydrogen electrolyzer cathode air specifications absent incumbent supply.
For New Entrants and Emerging Players: EPA Mercury and Air Toxics Standards enforcement in the United States opens a window for pleated synthetic cartridge specialists with sub-2.5-micron ratings. Target membrane bioreactor deployments in India's AMRUT 2.0 tier-2 cities where foreign technology licensors command first-mover premiums. Pursue direct-to-facility e-procurement platforms with predictive consumption algorithms capturing lifetime filter replacement value.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional nonwoven producers lacking backward integration into fluoropolymer resin supply. Long-term viability favors diversified materials-science conglomerates with captive polymer chemistry capabilities across the next decade. Watch hydrogen electrolyzer cathode air filtration procurement as inflection signal for specialty media specification premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Resin | DuPont's chemistry leadership anchors high-temperature membrane supply for coal-fired plant retrofits. |
| Technology Licensing to Tier-2 Cities | AMRUT 2.0 allocations in India expand membrane bioreactor deployments for foreign licensors. |
| Subscription Filter Replacement Programs | Industrial MRO distributors capture lifetime value through predictive consumption algorithms. |
| Hydrogen Electrolyzer Specification Development | PEM stack manufacturers require sub-micron particulate control protecting platinum catalyst layers. |
| Reactivation Service Infrastructure Buildout | Beverage processors in Germany and California specify reactivatable grades avoiding landfill penalties. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with membrane casting technicians, plant engineers at power generation facilities, procurement leads at semiconductor fabs, and aftermarket service heads at industrial distributors combined with secondary validation. Secondary sources include EPA enforcement databases, EU F-Gas Regulation compliance filings, SEC 10-K disclosures from diversified materials conglomerates, and customs trade data on fluoropolymer resin imports. Triangulation between consumption-side project pipelines and production-capacity announcements ensures dimensional consistency.
Input-output matrices map raw material flows through fabrication stages to end-use consumption across the projection horizon. Segmentation dimensions modeled include product type tier, end-use application maturity, material chemistry family, and regional regulatory cluster. CAGRs derive from regression analysis against regulatory deadline schedules and capital expenditure tracking. Forecast inputs incorporate membrane replacement cycle compression from EPA MATS enforcement and semiconductor fab construction pipelines in Taiwan, South Korea, and Arizona.
Revisions become necessary when regulatory deadline extensions, fluoropolymer force majeure events, or PFAS restriction scope expansions materialize beyond baseline assumptions. Forecasts reflect documented assumptions about compliance cost pass-through rates and technician availability for solvent-phase inversion processes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Activated Carbon Filter Market
Filters
Fabric Filter System Market
Filters
Intake Filter Media Market
Filters
Melt-Blown Polypropylene Filters Market
Filters
Color Filter Glass Market
Filters
Activated Carbon Market
Filters
Anti-Microbial Filter Market
Filters
Homopolymer Acrylic Filter Bags Market
Filters
Nonwoven Filter Media Market
Filters
Global Tangential Flow Filtration Market
Filters
Filter Bag Market
Filters
Filter Coatings Market
Filters
Industrial Filter Paper Market
Filters
Zeolite Adsorbents Market
Filters
Ceramic Filters Market
Filters
Global Sterile Filtration Market