
 Europe Specialty Printing Consumables Market | 2026-2036
Europe Specialty Printing Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Specialty Printing Consumables Market Foresight
Aftermarket service revenue is narrowing as equipment vendors bundle managed print services with proprietary consumable contracts. HP Inc. leverages its PageWide technology to lock in ink subscription models across enterprise fleets. Canon Inc. sustains margin pools through its imagePRESS toner ecosystem and direct channel control in Western Europe. Fujifilm Europe GmbH anchors its position in wide-format UV ink segments for display graphics.
Specialty printing consumables encompass formulated inks, dry toners, coated substrates, and functional coatings engineered for specific print technologies, with viscosity, particle size, and curing chemistry calibrated to substrate and speed requirements. These materials enable high-fidelity reproduction, durability, and regulatory compliance across commercial and industrial output. Inks dominate product-type value pools due to recurring replenishment cycles and formulation complexity, while digital printing technology captures the fastest expansion as on-demand production displaces conventional make-ready. Packaging application demand leads absolute volume, though textile printing via pigment ink systems shows structural momentum in Southern European manufacturing clusters.
REACH and the EU Green Deal constrain volatile organic compound formulations and mandate circularity disclosures for ink and toner packaging, compelling reformulation investments by chemical suppliers. ECHA substance-of-very-high-concern listings directly restrict specific pigment chemistries, forcing qualified alternative sourcing. CE marking under the Machinery Directive shapes equipment-consumable interoperability standards. Stakeholders must monitor evolving EU Chemicals Strategy for Sustainability targets and assess captive formulation capabilities against third-party specialty ink suppliers.
Market Dynamics
Digital inkjet adoption in European packaging converters is compressing traditional offset make-ready cycles and forcing consumable suppliers to reconfigure viscosity and curing specifications for shorter production runs.
Growth Catalysts
- Short-run packaging demand:European food and beverage brands now require batch-specific labeling with variable data, pulling UV-curable and water-based ink volumes into regional converting facilities.
- REACH substance restrictions:ECHA listings of pigment chemistries as substances of very high concern are accelerating qualified alternative sourcing investments by specialty ink formulators.
- Pigment ink systems:Textile printing clusters in Southern Europe are adopting pigment-based formulations for synthetic fabric decoration, bypassing water-intensive dye-sublimation processes.
Market Restraints
- Petrochemical feedstock volatility:Acrylic and polyurethane resin costs for UV ink oligomers fluctuate with naphtha cracking margins, squeezing formulation margin pools.
- Equipment vendor lock-in:Managed print service contracts from HP PageWide and Canon imagePRESS ecosystems restrict third-party consumable penetration in enterprise fleet accounts.
- CE marking interoperability:Machinery Directive compliance testing for consumable-equipment pairing adds certification overhead before market entry.
Strategic Opportunities
- Eastern European print infrastructure:Poland and Czech Republic packaging converters remain underpenetrated by premium specialty ink suppliers versus German and Benelux markets.
- EU Green Deal circularity mandates:Extended producer responsibility frameworks for ink cartridge and toner packaging create first-mover advantage for closed-loop collection systems.
- UV-LED and electron beam convergence:Hybrid curing systems combining instant polymerization with energy efficiency are opening retrofit opportunities in existing wide-format installations.
Industry Challenges
- Formulation chemist scarcity:REACH-compliant pigment substitution and low-migration food packaging ink development require specialized toxicology and polymer science expertise that European labor pools struggle to supply.
- Legacy RIP software integration:Color management workflows from pre-digital press eras obstruct seamless adoption of expanded-gamut ink sets in established print shops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Specialty Printing Consumables Market |
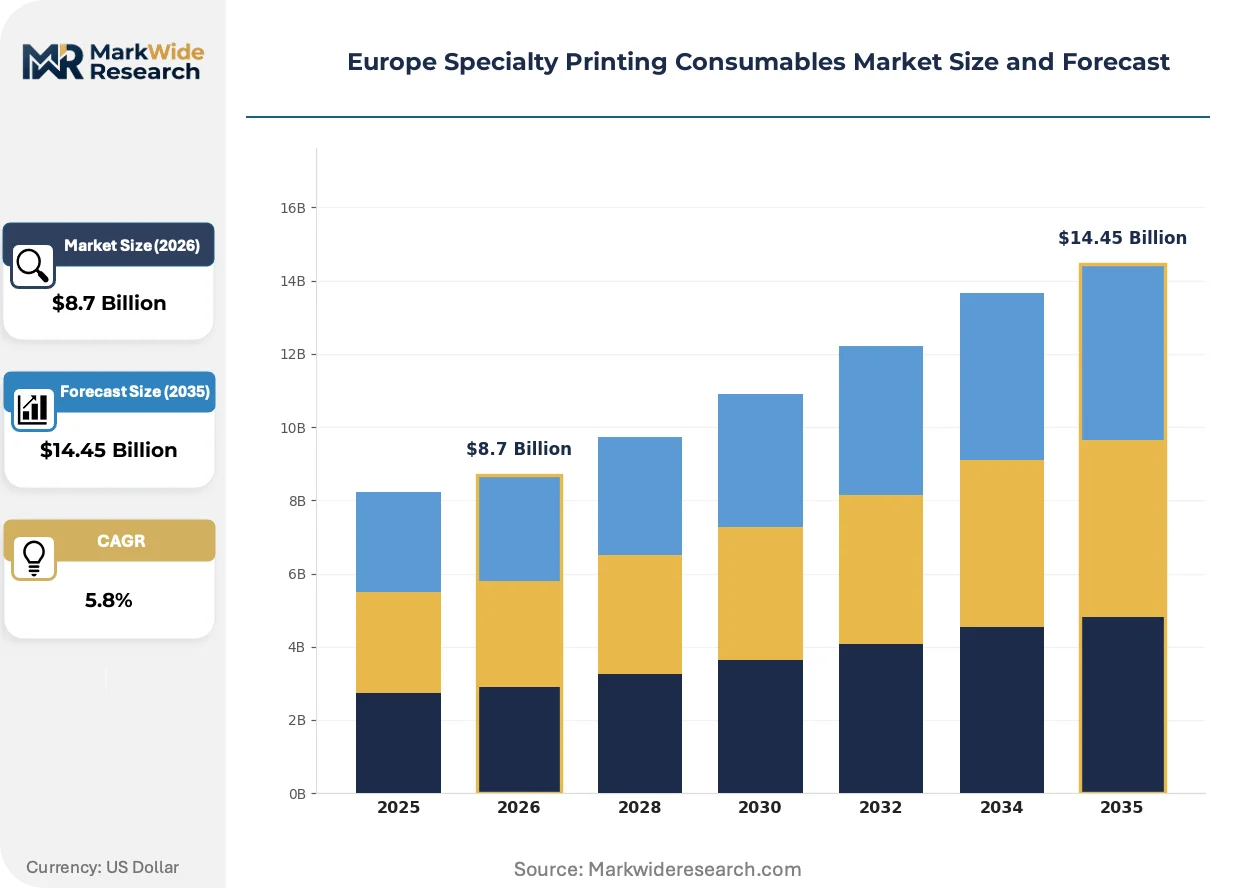
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inks, Toners, Media, Coatings Application: Packaging, Advertising, Textile, Commercial Printing Technology: Digital Printing, Flexography, Lithography, Screen Printing End User: Retail, Manufacturing, Advertising Agencies, Print Shops |
| Companies Covered | HP Inc., Canon Inc., Xerox Corporation, Epson Europe B.V., Fujifilm Europe GmbH, Ricoh Europe PLC, Konica Minolta Business Solutions Europe GmbH, Brother International Europe Ltd., DIC Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Specialty Printing Consumables Market Shifts & Advancements
Active chemistry reformulation, curing hardware evolution, and procurement model compression are simultaneously reshaping how European converters specify and replenish consumable inventories.
Water-based UV ink technology is hybridizing the durability of radiation-cured films with the regulatory compliance profile of aqueous systems. German flexible packaging converters are piloting these formulations for direct food-contact applications at commercial speeds. This convergence is hybridizing the historical separation between high-performance industrial inks and regulatory-safe consumer packaging grades.
REACH authorization requirements under the EU Chemicals Strategy for Sustainability are forcing disclosure of full substance compositions down to 0.1% weight thresholds. Specialty ink suppliers must now maintain granular supply chain documentation for every pigment and additive batch. Wide-format display graphics manufacturers face the steepest compliance burden due to complex multi-component formulations.
Subscription-based replenishment contracts are displacing spot purchasing in enterprise and industrial print environments. Equipment vendors bundle predictive monitoring with locked consumable supply, compressing independent distributor margins. This transition is most visible in German industrial print shops where fleet standardization favors single-source vendor relationships over multi-brand procurement.
Europe Specialty Printing Consumables Market Segmentation
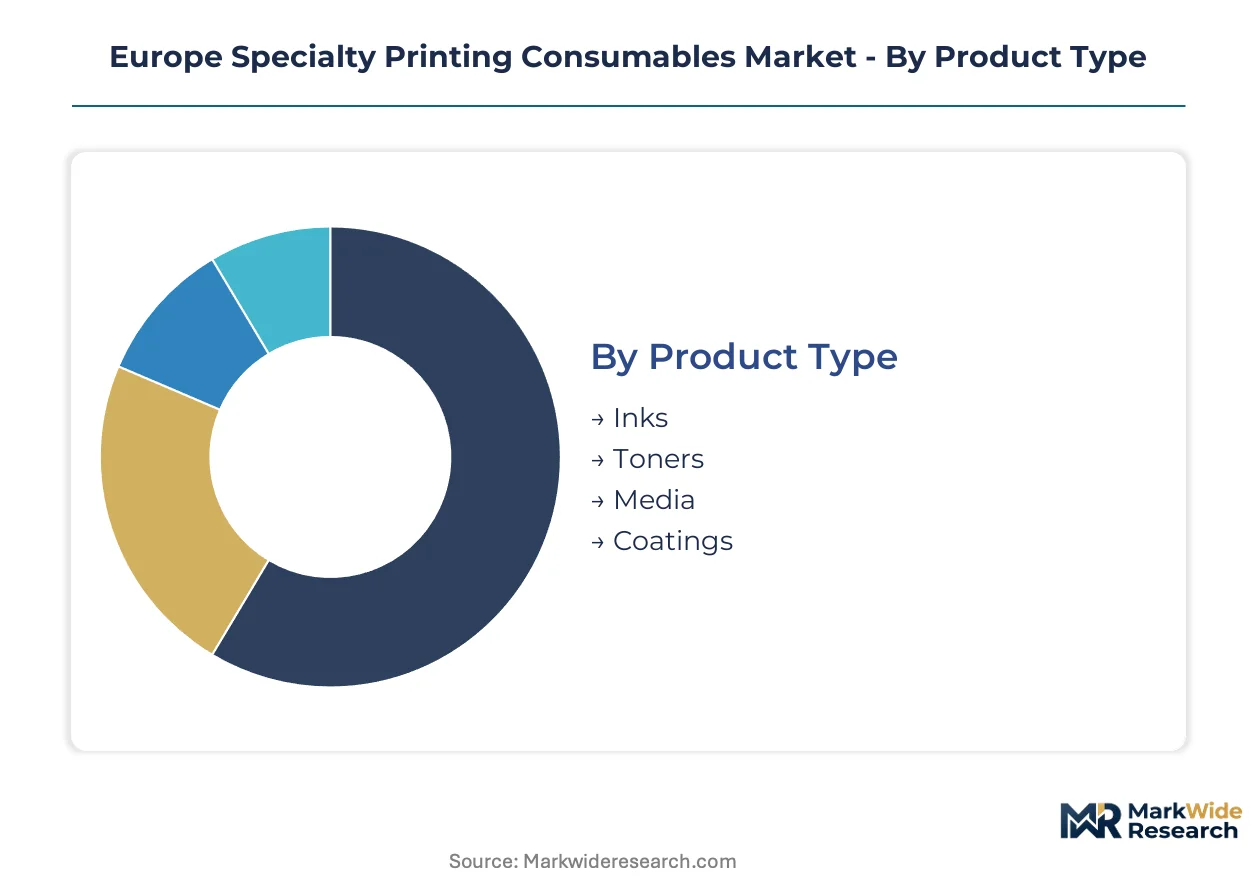
Consumable specification varies sharply across print technologies and end-use requirements in Europe. Formulation chemistry, substrate compatibility, and regulatory compliance profiles differ fundamentally between segments, creating distinct procurement patterns and margin structures for suppliers.
Product Type:
Cost tier differentiation separates commodity replenishment cycles from premium formulation investments.
- Inks:Formulated dispersions of pigments or dyes with calibrated viscosity and surface tension for specific printhead technologies. German flexible packaging converters and Italian textile printers drive premium UV-curable and pigment ink volumes through recurring replenishment contracts.
- Toners:Dry polymer particles engineered with controlled particle size distribution and charge characteristics for electrophotographic fusion. Enterprise fleet contracts in France and the Netherlands concentrate demand for chemically produced color toner cartridges with locked-in supply agreements.
- Media:Coated and uncoated substrates including synthetic films, papers, and textiles with surface treatments for ink adhesion.
- Coatings:Functional overprint varnishes and protective layers applied post-print for durability enhancement.
Inks command the established base. The steepest expansion runs through coatings as food-contact compliance requirements intensify.
Application:
End-use performance requirements dictate formulation investment intensity and certification burden.
- Packaging:Primary and secondary packaging applications demanding migration-controlled formulations for direct food contact. Spanish and Portuguese converters are expanding short-run flexible packaging capacity with UV-inkjet systems, pulling specialty consumable volumes from traditional offset suppliers.
- Advertising:Display graphics and point-of-sale materials requiring weather-resistant outdoor durability. Wide-format installations in the UK and Poland sustain solvent and UV-curable ink demand for billboard and retail signage applications.
- Textile:Fabric decoration via direct-to-garment and roll-to-roll pigment systems.
- Commercial Printing:General document and marketing collateral production.
Packaging anchors revenue concentration. Advertising applications are gaining share fastest as retail environments digitize visual merchandising.
Technology:
Print speed and substrate versatility determine consumable chemistry specifications and equipment-consumable bundling intensity.
- Digital Printing:Inkjet and electrophotographic systems enabling variable data and on-demand production without physical makeready. Nordic packaging converters are retrofitting existing lines with single-pass inkjet arrays, forcing reformulation of viscosity and curing specifications for shorter run lengths.
- Flexography:Rotary relief printing with solvent-based, water-based, or UV-curable inks for high-volume flexible packaging.
- Lithography:Planographic offset printing dominating long-run commercial and publication work.
- Screen Printing:Stencil-based thick-film deposition for textiles, ceramics, and industrial graphics.
Lithography retains the volume base. Digital printing is climbing the fastest as converter capital shifts toward on-demand capability.
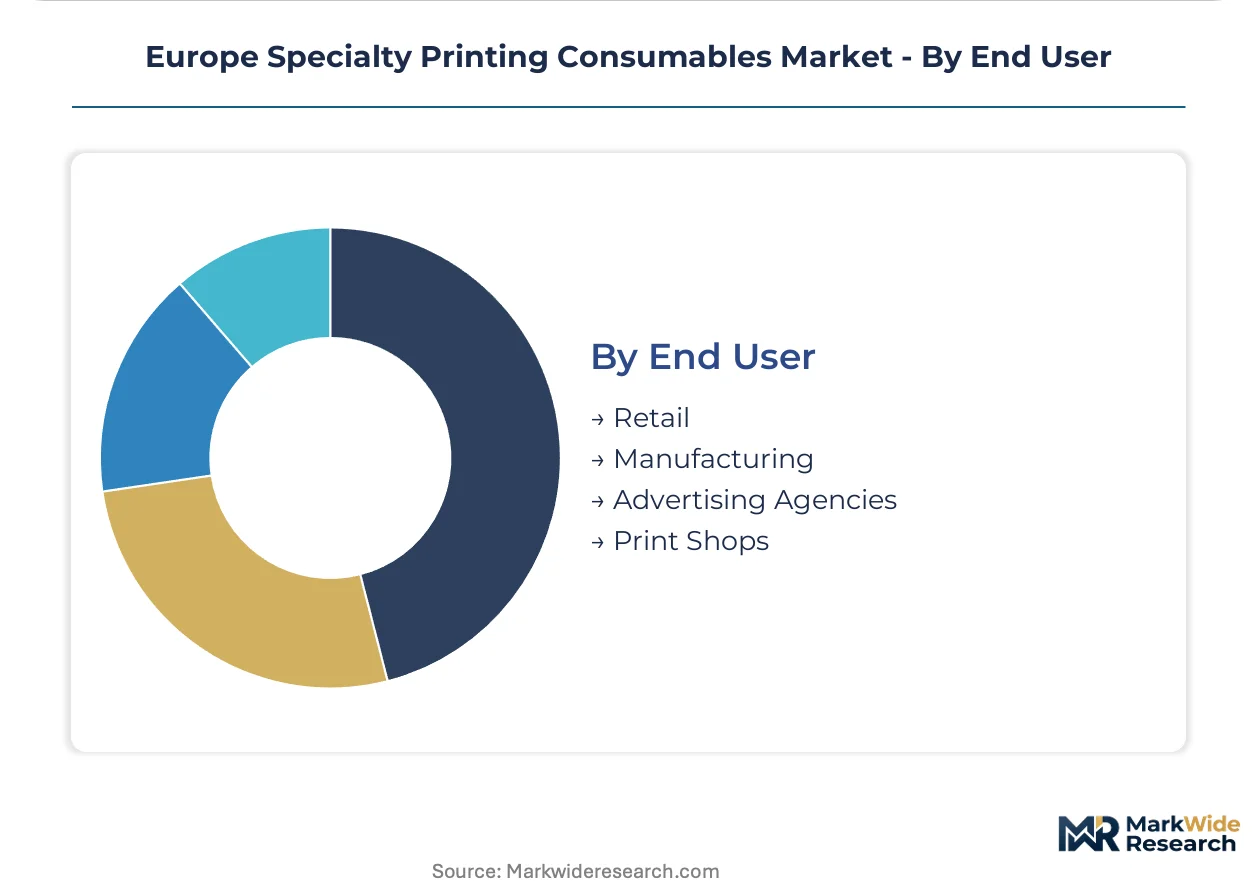
End User:
Customer scale and procurement sophistication create distinct channel and pricing structures.
- Retail:Brand owners and retailers controlling private-label packaging specifications and sustainability disclosures. Major grocery and apparel chains in Germany and France are mandating REACH-compliant ink certifications and circular packaging formats from their converter suppliers.
- Manufacturing:Industrial producers integrating print decoration into production lines for labeling and functional marking.
- Advertising Agencies:Creative services firms specifying print production for campaign materials.
- Print Shops:Commercial service providers executing outsourced production for business customers.
Print shops represent the established demand foundation. Retail direct procurement is expanding most quickly as brand owners internalize sustainability compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Southern European textile clusters show the highest price elasticity for commodity pigment inks, while German flexible packaging converters absorb premium formulations with minimal volume sensitivity. This demand-elasticity contrast shapes regional supplier strategies across the continent.
Germany
Industrial print shops in Bavaria and North Rhine-Westphalia drive premium consumable uptake through fleet standardization and locked vendor contracts. REACH authorization requirements under ECHA substance-of-very-high-concern listings force continuous reformulation investments by ink suppliers serving the Düsseldorf-Ruhr packaging corridor.
United Kingdom
Wide-format display graphics installations in London and the Midlands sustain solvent and UV-curable ink demand for retail signage applications. CE marking under the Machinery Directive shapes equipment-consumable interoperability testing, adding certification overhead for suppliers entering British markets post-Brexit regulatory divergence.
France
Enterprise fleet contracts in the Île-de-France region concentrate demand for chemically produced color toner cartridges with managed print service bundling. The EU Green Deal's extended producer responsibility frameworks are pushing Paris-based converters toward closed-loop collection systems for ink cartridge packaging.
Italy
Textile printing clusters in Lombardy and Piedmont are adopting pigment-based formulations for synthetic fabric decoration, bypassing water-intensive dye-sublimation processes. EFSA migration-controlled formulation requirements for food-contact applications constrain flexible packaging ink development in Emilia-Romagna converting facilities.
Poland
Packaging converters in the Warsaw and Łódź industrial zones remain underpenetrated by premium specialty ink suppliers relative to German and Benelux markets. Polish print infrastructure offers expansion opportunity as short-run flexible packaging capacity expands with EU cohesion fund support for manufacturing modernization.
Europe Specialty Printing Consumables Market Competitive Landscape
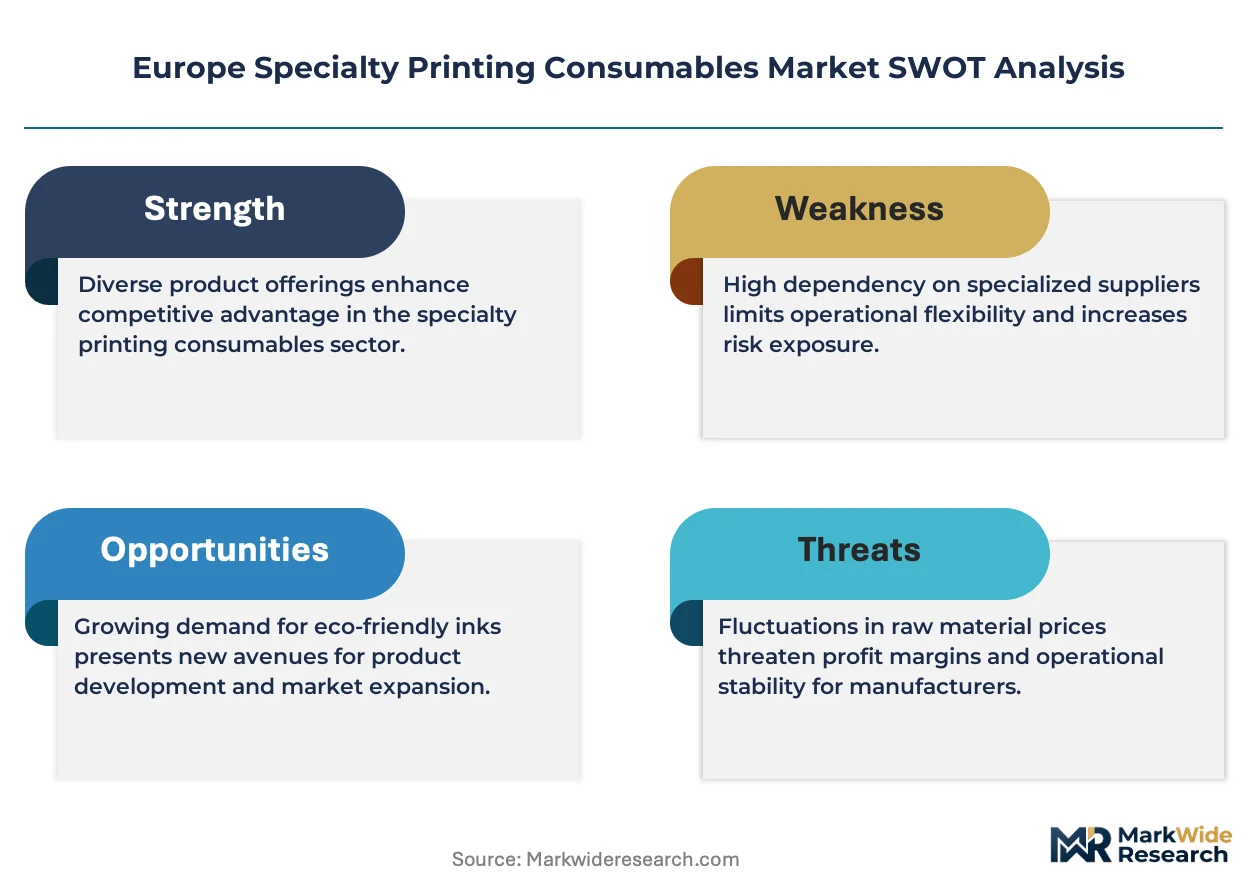
Capability concentration sits with specialty chemical formulators possessing REACH-compliant pigment substitution expertise; scale advantage sits with equipment vendors bundling consumable supply through managed print service contracts. The market structures around three tiers: integrated printer-hardware vendors with locked subscription models, independent specialty ink formulators serving converting facilities, and regional distributors squeezed by direct channel expansion. Dominant competitive moves include backward integration into resin and pigment supply by chemical specialists, and geographic expansion into Eastern European converting markets by Western European formulators.
Within the integrated vendor tier, HP Inc., Canon Inc., and Fujifilm Europe GmbH exemplify contrasting strategic positions. HP Inc. represents the subscription-lock archetype through predictive monitoring and fleet-standardized replenishment. Canon Inc. occupies a position emphasizing direct channel control and toner ecosystem captivity in Western European enterprise accounts. Fujifilm Europe GmbH anchors the wide-format specialization vector, with its European GmbH structure indicating regional subsidiary operations focused on UV ink segments for display graphics applications.
| Leading Market Players |
|---|
| HP Inc. |
| Canon Inc. |
| Xerox Corporation |
| Epson Europe B.V. |
| Fujifilm Europe GmbH |
| Ricoh Europe PLC |
| Konica Minolta Business Solutions Europe GmbH |
| Brother International Europe Ltd. |
| DIC Corporation |
| Others |
Supply & Pricing Matrix
REACH substance-of-very-high-concern listings create a dual chokepoint that widens pricing spreads between compliant and non-compliant ink tiers while forcing supply chain reconfiguration toward qualified alternative pigment sources. ECHA disclosure mandates down to 0.1% weight thresholds compel batch-level documentation investments that concentrate formulation capability among larger chemical suppliers.
Pricing Analysis
Aftermarket consumable subscriptions now drive lifetime value for equipment vendors bundling predictive monitoring with locked replenishment contracts. Pricing stratifies across REACH-compliant premium formulations, standard industrial grades, and economy spot-market alternatives. Cost compression in economy pigment tiers reflects acrylic resin volatility tied to naphtha cracking margins. Brand owners and retail procurement teams show highest price sensitivity for commodity display graphics inks, while German flexible packaging converters absorb premium migration-controlled formulations with minimal volume pushback.
Supply Chain Analysis
Extended payment terms from packaging converters strain working capital for specialty ink formulators serving Southern European textile clusters. Pigment supply concentrates in Germany, China, and India, with resin feedstocks drawing from Belgian and Dutch petrochemical complexes. Single-source vulnerability runs through ECHA-authorized pigment alternatives for food-contact applications. Distribution runs through converter-direct relationships in Germany and regional distributor networks in Poland and Czech Republic.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates opportunity as short-run packaging demand splinters procurement across dozens of converter-specific formulations. Variable data requirements and REACH compliance tiers multiply addressable niches beyond the reach of bundled vendor ecosystems.
For Market Incumbents: Insulate margin pools by deepening captive resin formulation capabilities against petrochemical feedstock volatility. Extend direct channel control into Polish and Czech packaging corridors before Western European formulators establish beachheads. Lock enterprise fleet accounts through expanded predictive monitoring subscriptions that compress independent distributor access.
For New Entrants and Emerging Players: Eastern European print infrastructure offers the most penetrable white-space, with Warsaw and Łódź packaging converters underserved by premium specialty ink technical support. Pigment ink systems for synthetic textile decoration in Lombardy and Piedmont clusters present a second entry vector. Lead with REACH-compliant formulation documentation and rapid batch certification turnaround as the core go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialty chemical formulators with captive toxicology expertise and ECHA pre-authorization track records. Five-to-ten year viability hinges on circularity mandate compliance infrastructure. Watch for UV-LED curing hardware retrofit cycles as the signal indicating inflection toward energy-efficient formulation demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive oligomer production insulates margin pools from naphtha cracking volatility. |
| REACH Pre-Authorization Investment | ECHA substance documentation capabilities differentiate suppliers for food-contact packaging converters. |
| Eastern European Geographic Expansion | Polish and Czech converter markets remain underpenetrated by premium formulation technical support. |
| Closed-Loop Collection System Deployment | EU Green Deal extended producer responsibility frameworks create first-mover packaging circularity advantage. |
| UV-LED Curing Formulation Development | Energy-efficient instant polymerization aligns with converter retrofit demand across wide-format installations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with packaging converter procurement leads, specialty ink formulation chemists, equipment vendor account managers, and ECHA regulatory affairs specialists. Secondary validation drew from ECHA substance registration databases, EU customs trade flows for pigment and resin categories, Cefic chemical industry reports, and SEC filings from publicly traded printing equipment manufacturers. Bottom-up volume estimates from converter capacity installations were triangulated against top-down chemical supplier revenue allocations across product categories.
Calibration anchored volume and value outputs to disclosed equipment placements and consumable yield assumptions across the projection horizon. Segmentation modeling spanned product type, print technology, application end-use, and country-level regulatory cluster. CAGRs were derived from converter capital expenditure trajectories and technology substitution curves. Forecast inputs included ECHA substance restriction timelines and EU cohesion fund disbursement patterns for Eastern European manufacturing modernization.
Practitioners should monitor ECHA authorization list expansions and acrylic resin futures pricing for early signals of margin compression or formulation cost spikes. Forecasts reflect assumptions about REACH compliance cost pass-through rates and digital press adoption velocity. Macroeconomic deviation in EU manufacturing output, regulatory acceleration under the Chemicals Strategy for Sustainability, or breakthrough water-based UV curing speeds would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Global Conductive Inks Market
Printing Inks
Rotogravure Printing Inks Market
Printing Inks
Food Grade Inks Market
Printing Inks
Solvent-Based Inks Market
Printing Inks
Water-Borne Inks and Paints Market
Printing Inks
UV Cured Inks Market
Printing Inks
Global Digital Fabrication Inkjet Inks Market
Printing Inks
Continuous Inkjet Ink Market
Printing Inks
Offset Ink Market
Printing Inks
Global Dye Sublimation Inks Market
Printing Inks
Screen Printing Inks Market
Printing Inks
Specialty Ink Market
Printing Inks
Molecular Ink Market
Printing Inks
Global Decorative Print Market
Printing Inks
Anti-Counterfeit Printing Ink Market
Printing Inks
Global Water-Based Inks Market