
 Chloramine Filter Market | 2026-2036
Chloramine Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Chloramine Filter Market Analytics
North American activated carbon manufacturers is broadening specialty media output to serve rising municipal procurement cycles. Pentair leverages its commercial channel density across U.S. water districts to sustain recurring filter replacement revenue. Aquasana anchors direct-to-consumer positioning with NSF/ANSI 42 and 53 certified systems for chloramine reduction.
A chloramine filter employs catalytic activated carbon, KDF redox media, or integrated reverse osmosis membranes to chemically reduce monochloramine and ammonia residuals below detectable thresholds, typically targeting sub-1 ppm output for potable and process water applications. Activated carbon formulations dominate unit volume due to lower capital cost and established regeneration infrastructure, while reverse osmosis configurations command premium positioning in pharmaceutical and semiconductor process lines where ultrapure specifications apply. Municipal application demand outpaces residential growth as U.S. cities convert from free chlorine to chloramine disinfection for distribution system stability.
EPA Stage 2 DBPR enforcement, NSF/ANSI Standard 42 certification requirements, and state-level primacy agency audits collectively elevate product validation barriers for new entrants. California's Division of Drinking Water maintains the nation's most stringent chloramine residual limits, forcing manufacturers to submit additional performance data beyond federal minimums. Stakeholders must track pending EPA regulatory reviews on disinfection byproduct precursor controls to anticipate the next wave of municipal upgrade cycles.
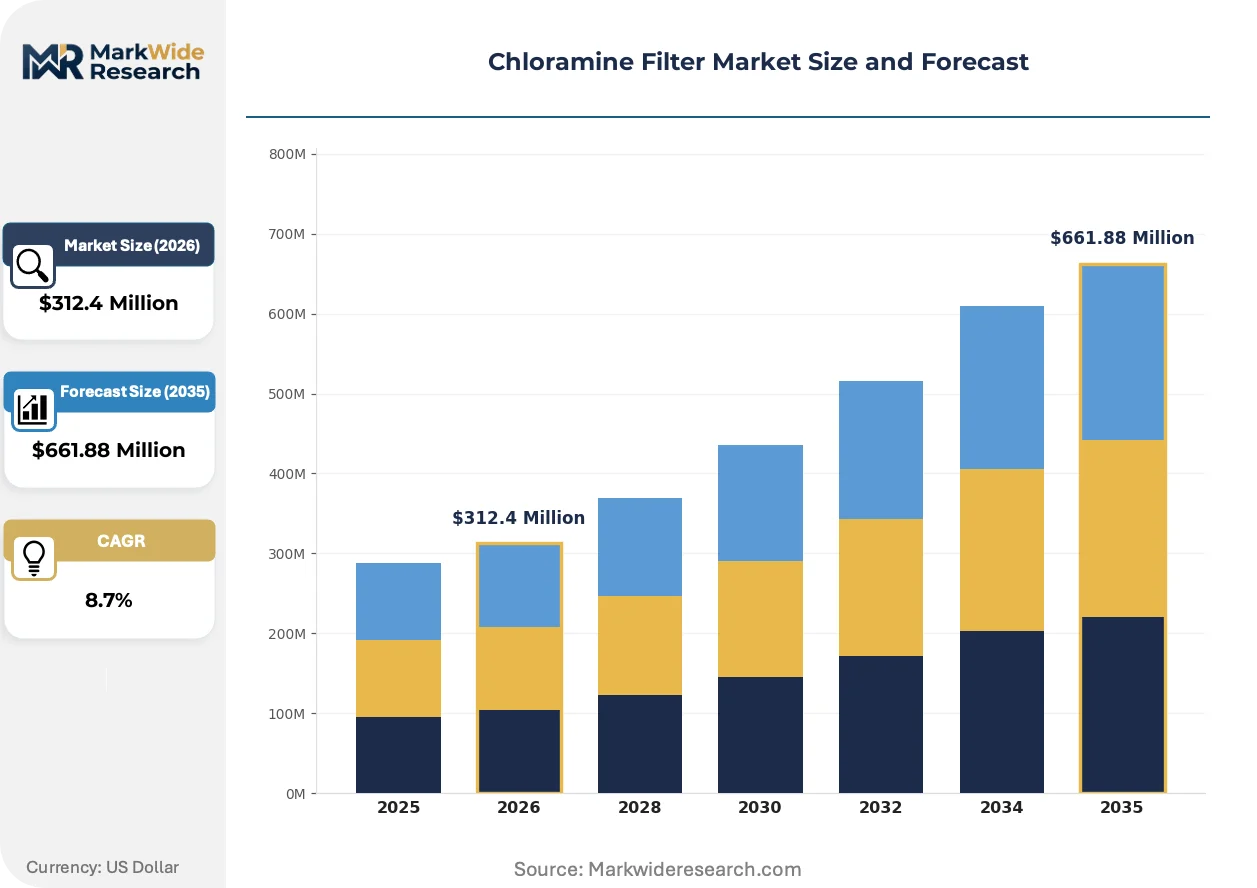
Market Dynamics
Municipal water districts are accelerating chloramine filter procurement as EPA Stage 2 DBPR enforcement tightens residual limits and legacy free-chlorine systems face mandatory retrofit cycles across U.S. distribution networks.
Growth Catalysts
- EPA Stage 2 DBPR:Federal disinfectant byproduct rules force municipal utilities to upgrade filtration infrastructure, creating sustained procurement demand for certified reduction systems.
- Activated carbon regeneration infrastructure:Established spent-media reactivation facilities in California and Texas lower lifecycle costs for large-scale municipal deployments.
- Semiconductor process water:Ultrapure specifications in chip fabrication drive reverse osmosis membrane adoption for sub-ppb chloramine removal in critical rinse applications.
Market Restraints
- Coconut shell activated carbon supply:Sri Lankan and Indonesian feedstock concentration exposes manufacturers to weather-related harvest volatility and freight cost spikes.
- NSF/ANSI 42 and 53 certification timelines:Extended third-party validation periods delay product launches and lock out unfinanced entrants from municipal bidding.
- Free chlorine residual systems:Legacy chlorine disinfection infrastructure in smaller utilities creates substitution inertia despite chloramine distribution stability advantages.
Strategic Opportunities
- Point-of-entry residential systems:California and Texas homeowners face rising water quality complaints as municipal chloramine conversion accelerates, opening direct-to-consumer channels.
- KDF-catalytic carbon hybrid media:Converging redox and adsorption technologies enable single-vessel designs that reduce footprint and maintenance intervals for commercial buildings.
- Pharmaceutical compendial water:USP Purified Water and Water for Injection standards create specification-driven demand for validated chloramine reduction skids in drug manufacturing.
Industry Challenges
- Catalytic carbon formulation expertise:Specialized surface modification chemistry requires rare technical talent, constraining production scale-up for qualified suppliers.
- Legacy distribution system compatibility:Retrofit installations must integrate with aging cast-iron and concrete infrastructure without disrupting continuous supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chloramine Filter Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Filter Type: Activated Carbon, Reverse Osmosis, Biofilter, KDF Application: Residential, Commercial, Industrial, Municipal End User: Households, Water Treatment Plants, Food&Beverage Industry, Aquariums Technology: Gravity, Pressure, Ultraviolet, Filtration |
| Companies Covered | APEC Water Systems, Aquasana, Pentair, Culligan International Company, 3M Company, US Water Systems, Kinetico, Home Master, iSpring, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chloramine Filter Market Evolving Landscape
Smart monitoring systems and predictive media replacement algorithms are compressing maintenance cycles and reshaping how municipal operators manage distributed filtration assets.
Catalytic activated carbon with enhanced surface modification is automating residual detection and backwash scheduling in municipal treatment plants. Water districts in Texas and California are deploying sensor-integrated vessels that trigger regeneration based on actual breakthrough rather than fixed intervals. This capability is automating labor allocation and reducing unplanned downtime in 24/7 distribution operations.
EPA's pending review of disinfection byproduct precursor controls is tightening maximum contaminant level goals for total organic halides. Municipal procurement specifications are preemptively requiring enhanced chloramine reduction performance beyond current Stage 2 minimums. California's Division of Drinking Water is already enforcing stricter residual limits, forcing manufacturers to submit supplemental validation data for state approval.
Specification-driven procurement is consolidating vendor selection around NSF/ANSI-certified systems with documented third-party performance data. Municipal engineers are disqualifying uncertified alternatives from bid packages, compressing the qualified supplier base. Texas water districts exemplify this pattern, where certification status now functions as a pre-qualification gate rather than a scored evaluation criterion.
Chloramine Filter Market Segmentation
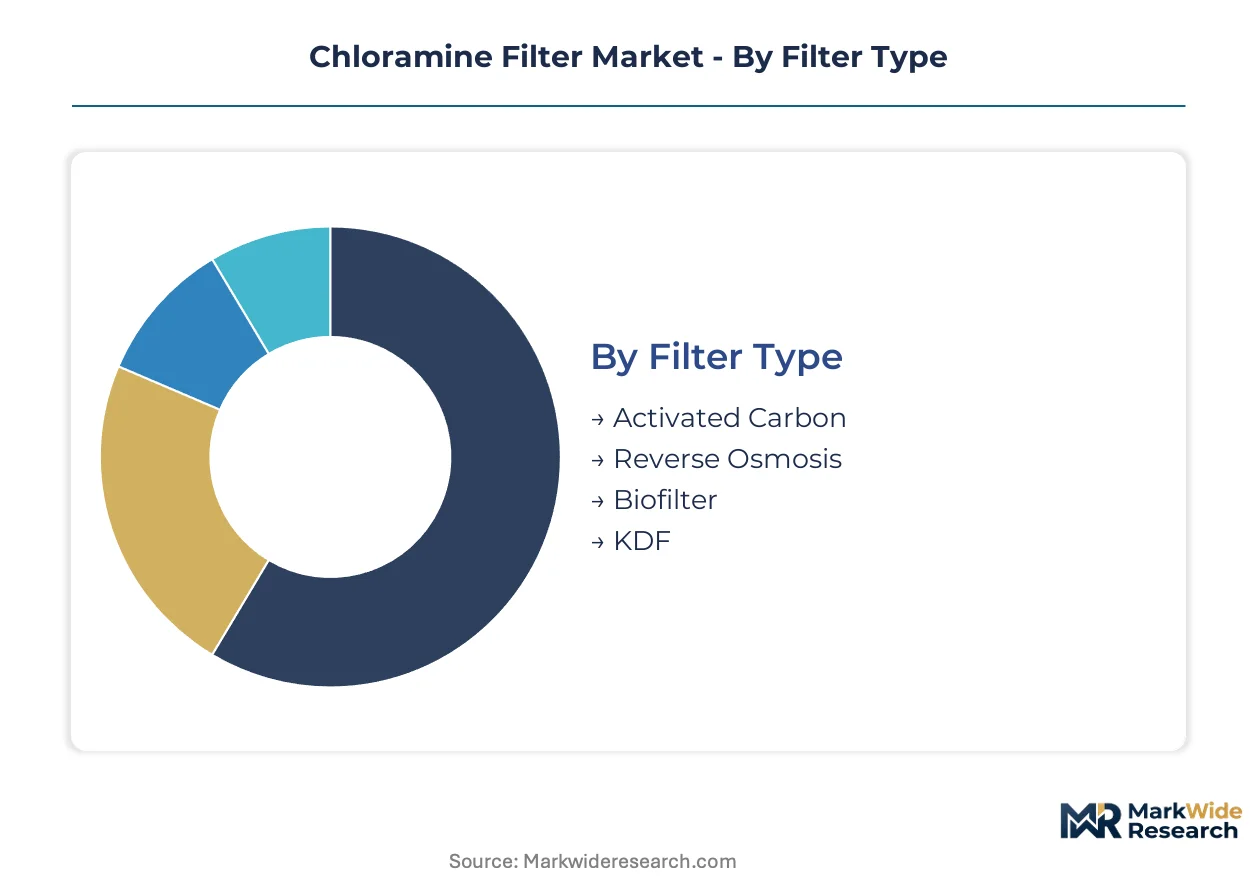
Chloramine filter procurement varies sharply across installation scale and water quality specifications. Municipal buyers prioritize certified performance and regeneration economics, while residential purchasers trade upfront cost against maintenance simplicity.
Filter Type:
Customization intensity spans from commodity activated carbon to engineered catalytic formulations requiring proprietary surface chemistry.
- Activated Carbon:Coconut shell and bituminous coal formulations dominate municipal procurement due to established reactivation infrastructure in California and Texas. EPA Stage 2 DBPR compliance drives specification toward catalytic grades with enhanced monochloramine reduction kinetics.
- Reverse Osmosis:Thin-film composite membranes achieve sub-ppb chloramine removal for semiconductor rinse water and pharmaceutical compendial applications. Premium positioning reflects membrane replacement costs and pre-treatment requirements.
- Biofilter:Biological ammonia oxidation systems serve niche aquarium and aquaculture applications where chemical residual tolerance is minimal.
- KDF:Copper-zinc redox media functions as standalone point-of-use cartridges or hybrid pre-treatment layers extending activated carbon service life.
Leading the category by volume: Activated Carbon. Expanding most quickly: Reverse Osmosis.
Application:
Cost tier separation distinguishes capital-intensive municipal infrastructure from recurring-replacement residential units.
- Residential:Point-of-entry and point-of-use systems target California and Texas homeowners confronting municipal chloramine conversion. NSF/ANSI 42 and 53 certification functions as a mandatory purchase filter.
- Municipal:Large-scale filtration vessels with automated backwash and regeneration systems anchor procurement volume. Water districts prioritize lifecycle cost over capital expenditure.
- Commercial:Mid-scale installations serve hotels, hospitals, and office complexes requiring continuous supply without process water purity demands.
- Industrial:Process-integrated skids address semiconductor fabrication and pharmaceutical manufacturing specifications.
Capturing the largest installed base: Municipal. Gaining share fastest: Residential.
End User:
Customer type determines specification stringency from aesthetic preference to regulatory compulsion.
- Water Treatment Plants:Municipal utilities drive bulk procurement with multi-year service contracts and performance-based replacement scheduling.
- Households:Direct-to-consumer channels emphasize installation simplicity and third-party certification over technical performance differentiation.
- Food&Beverage Industry:Breweries and bottled water processors require chloramine reduction to protect flavor profiles and prevent packaging degradation.
- Aquariums:Public and private aquaria demand zero-residual systems protecting sensitive species from gill and tissue damage.
Generating the highest contract value: Water Treatment Plants. Showing steepest growth trajectory: Households.
Technology:
Maturity gradient separates gravity-fed legacy designs from pressure-driven and UV-augmented contemporary systems.
- Pressure:Forced-flow configurations dominate commercial and industrial installations, enabling higher throughput and integration with existing distribution pressure.
- Filtration:Mechanical separation combined with adsorptive media represents the baseline architecture across all application tiers.
- Gravity:Low-cost countertop and pitcher systems serve price-sensitive residential segments with limited flow rate requirements.
- Ultraviolet:UV augmentation targets disinfection assurance downstream of chloramine reduction, particularly in pharmaceutical and food safety contexts.
Holding the broadest deployment: Filtration. Climbing fastest: Pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sri Lankan and Indonesian coconut shell harvests anchor activated carbon feedstock supply for chloramine filtration media, concentrating upstream vulnerability in tropical coastal zones while downstream demand clusters in North American municipal water districts.
United States
EPA Stage 2 DBPR enforcement drives municipal procurement across Texas and California water districts. California's Division of Drinking Water enforces stricter chloramine residual limits than federal minimums, forcing supplemental manufacturer validation. Dallas-Fort Worth metro utilities deploy sensor-integrated catalytic carbon vessels with automated breakthrough detection.
Canada
Health Canada guidelines on disinfection byproducts accelerate provincial utility upgrades in Ontario and British Columbia. The country's national water quality regulator maintains alignment with EPA thresholds while allowing provincial primacy agencies to tighten local standards. Toronto-area treatment plants pilot smart monitoring systems for predictive media replacement.
Germany
REACH compliance requirements and ECHA chemical safety protocols shape specialty carbon import specifications for industrial process water. German municipal utilities prioritize lifecycle cost optimization over capital expenditure in filtration procurement. Bavarian semiconductor fabrication clusters drive demand for sub-ppb chloramine removal in ultrapure rinse applications.
China
MIIT industrial water reuse mandates and tightening MEE discharge standards expand municipal and industrial filtration deployment. GB standards for drinking water quality increasingly reference chloramine reduction performance in high-density urban distribution systems. Yangtze River Delta municipalities convert legacy chlorine systems to chloramine for distribution stability.
Japan
METI energy efficiency guidelines and JIS standards for water treatment equipment shape procurement specifications for commercial and industrial end users. Japanese pharmaceutical manufacturers require validated chloramine reduction skids for USP Purified Water compliance. Kansai region semiconductor fabs specify reverse osmosis membranes for critical process water.
Chloramine Filter Market Competitive Landscape
Global majors compete with regional champions across certification depth and channel density, creating a tiered structure where NSF/ANSI validation status functions as a pre-qualification gate rather than a scored criterion. The vendor base separates into three archetypes: diversified filtration conglomerates with municipal service contracts, direct-to-consumer specialists leveraging third-party certification for homeowner trust, and industrial process-integrated skid fabricators serving semiconductor and pharmaceutical specifications. Capacity expansion and strategic certification investments represent the dominant competitive moves, with players racing to preempt California's supplemental validation requirements.
Among U.S.-based diversified water treatment companies, Pentair, Culligan International Company, and 3M Company occupy positions across municipal, commercial, and residential application tiers. Pentair exemplifies the municipal-focused archetype through commercial channel density in water districts. Culligan International Company represents the service-contract model with recurring replacement revenue streams. 3M Company sits within the diversified industrial conglomerate tier, leveraging cross-divisional filtration expertise.
| Leading Market Players |
|---|
| APEC Water Systems |
| Aquasana |
| Pentair |
| Culligan International Company |
| 3M Company |
| US Water Systems |
| Kinetico |
| Home Master |
| iSpring |
| Others |
Value Network & Pricing Analysis
Municipal procurement specifications demanding NSF/ANSI 42 and 53 certification with supplemental California validation data force manufacturers to absorb extended third-party testing costs, compressing margins on standard-grade systems while creating pricing power for pre-certified suppliers.
Pricing Analysis
Extended warranty and media replacement service bundling separates municipal contract winners from commodity competitors. Three-tier pricing structure across premium catalytic carbon, standard activated carbon, and economy KDF systems reflects certification depth and regeneration service inclusion. Pricing pressure stems from coconut shell feedstock volatility in Sri Lanka and Indonesia. Municipal water districts exhibit lowest price sensitivity due to lifecycle cost optimization mandates, while residential direct-to-consumer buyers prioritize upfront capital minimization.
Supply Chain Analysis
Regional distribution centers in Houston, Los Angeles, and Toronto anchor hub-and-spoke fulfillment patterns for activated carbon media and replacement cartridges. Upstream supply concentrates in Sri Lankan and Indonesian coconut shell plantations, Chinese bituminous coal processing facilities, and German specialty carbon modification labs. Raw material dependencies span tropical feedstock harvests, copper-zinc alloy for KDF media, and thin-film composite membranes from Japanese and Korean fabrication lines. Single-source vulnerability in Sri Lankan coconut shell supply exposes manufacturers to monsoon-related harvest disruptions. Distribution runs through municipal procurement contracts, commercial installer networks, and direct-to-consumer e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive control over catalytic carbon formulation expertise to escape feedstock volatility and certification bottlenecks.
For Market Incumbents: Lock in municipal service contract renewals by embedding predictive monitoring systems that automate replacement scheduling. Deepen backward integration into coconut shell carbon reactivation facilities in California and Texas to secure regeneration economics against emerging competitors lacking spent-media infrastructure. For New Entrants and Emerging Players: The price-point gap between NSF-certified premium systems and uncertified economy alternatives creates white-space opportunity in Texas residential point-of-entry installations. Target California homeowners in counties completing chloramine conversion without supplemental state validation requirements. Pursue white-label partnerships with established commercial installers to bypass extended certification timelines. For Investors and Strategic Acquirers: The window for entry favors specialty catalytic carbon formulators with proprietary surface modification chemistry. Long-term viability hinges on securing technical talent pools concentrated in German and Japanese industrial carbon research clusters. Monitor EPA pending reviews on disinfection byproduct precursor controls as the signal for accelerated municipal upgrade cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Catalytic Carbon Formulation Acquisition | Captures scarce technical talent for enhanced monochloramine reduction kinetics. |
| California Supplemental Validation Investment | Preempts state-level approval barriers before EPA Stage 2 enforcement tightens. |
| Spent-Media Reactivation Facility Expansion | Lowers lifecycle costs for Texas and California municipal contract bidding. |
| Smart Monitoring Platform Integration | Enables predictive replacement algorithms for 24/7 distribution operations. |
| Residential Direct-to-Consumer Channel Buildout | Captures Texas and California homeowner demand from municipal chloramine conversion. |
Research Methodology
Independent corroboration across municipal water district procurement officers, activated carbon manufacturing technical directors, and NSF certification laboratory managers underwrites the qualitative findings. Primary interviews with commercial installer networks, residential system distributors, and semiconductor fab process engineers combined with secondary validation from EPA enforcement databases, California Division of Drinking Water approval records, and customs trade data on coconut shell carbon imports. Bottom-up unit shipment estimates triangulate against top-down municipal capital expenditure tracking.
Rate-of-change decomposition across filter type, application tier, and end-user category structures the analytical framework over the projection horizon. Segmentation dimensions span activated carbon grade, reverse osmosis membrane specification, municipal versus residential installation scale, and regional regulatory stringency clusters. CAGRs derive from installed base turnover modeling and procurement cycle timing analysis. Industry-specific forecast inputs include EPA Stage 2 DBPR enforcement pace and California supplemental validation approval timelines.
Inputs from municipal procurement databases and carbon reactivation facility utilization reports were available through the study window; gaps in real-time residential point-of-use installation tracking introduce uncertainty bands around household segment projections. Forecasts reflect documented assumptions on regulatory enforcement intensity and feedstock harvest stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Filter Paper Market
Filters
Industrial Filtration Market
Filters
Filter Coatings Market
Filters
North America Gas Filtration Media Market
Filters
Global Pleated Filters Market
Filters
Canada Filtration and Separation Market
Filters
US Baghouse Filters Market
Filters
Europe Industrial Air Filtration Market
Filters
Nonwoven Filter Media Market
Filters
High-Efficiency Particulate Air (HEPA) Filters Market
Filters
Fabric Filter System Market
Filters
Liquid Filter Bags Market
Filters
ePTFE Filter Film Market
Filters
Homopolymer Acrylic Filter Bags Market
Filters
Zeolite Adsorbents Market
Filters
Global Gas Filtration Media Market