
 Sheet Molding and Bulk Molding Compounds Market | 2026-2036
Sheet Molding and Bulk Molding Compounds Market Size, Share, and Industry Trends Forecast 2026-2036
Sheet Molding and Bulk Molding Compounds Market Analytics
Multi-source resin procurement is recalibrating how compounders manage feedstock risk across polyester and vinyl ester supply chains. Menzolit leverages captive blending capacity in Europe to secure margin on technical grades. IDI Composites International anchors North American demand through specialized fire-resistant formulations for electrical infrastructure. Toray Industries extends its position via high-performance fiber integration into structural SMC for transportation OEMs.
Sheet molding and bulk molding compounds are fiber-reinforced thermoset materials typically comprising 25-35% glass fiber in unsaturated polyester or vinyl ester resin matrices, compression- or injection-molded at 130-170°C to produce rigid, heat-resistant parts for structural and electrical applications. The automotive parts segment dominates volume as Class-A body panels and battery enclosures displace metal stampings. Bulk molding compound occupies the fastest-expanding margin pool in precision electrical housings where flame-retardant grades command specification premiums. Fire-resistant composites sustain above-average pricing power in construction materials where building codes mandate enhanced ignition resistance.
EPA fuel-economy mandates and EU automotive CO2 regulations are tightening material specifications and accelerating metal-to-composite substitution in vehicle platforms. REACH compliance in Europe and evolving GB standards in China govern resin chemistry and volatile emissions, shaping which compound formulations gain market access. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with diverging certification requirements.
Market Dynamics
Automotive OEMs are reconfiguring vehicle architectures around thermoset composites as EPA fuel-economy standards and EU CO2 mandates harden metal displacement requirements, compressing design cycles and forcing resin suppliers to synchronize formulation roadmaps with platform engineering timelines.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:US passenger-vehicle lightweighting programs are accelerating SMC substitution for steel body panels and structural reinforcements to meet fleet efficiency targets.
- Electric vehicle battery enclosures:Thermal runaway protection requirements are pulling fire-resistant BMC grades into high-volume EV platform contracts across multiple OEM supply chains.
- Germany's automotive manufacturing cluster:Concentrated OEM engineering centers in Stuttgart and Munich are driving specification convergence for Class-A surface SMC across European supply bases.
Market Restraints
- Styrene price volatility:Unsaturated polyester resin feedstock costs fluctuate with benzene derivative markets, compressing compounder margins during petrochemical upcycles.
- Glass fiber supply concentration:Three producers control over seventy percent of roving supply for thermoset reinforcement, creating bottleneck risk during demand surges.
- REACH registration complexity:ECHA chemical substance evaluation timelines extend eighteen to thirty-six months, delaying new vinyl ester formulation commercialization in European markets.
Strategic Opportunities
- India automotive lightweighting:PLI scheme incentives for domestic EV manufacturing are opening specification windows for localized SMC production serving Maruti Suzuki and Tata Motors platforms.
- Construction facade panels:Fire-resistant composite cladding is penetrating mid-rise commercial building codes as aluminum composite panel substitution accelerates following Grenfell-type incidents.
- Carbon fiber-SMC hybridization:High-performance fiber integration into structural automotive grades is creating specification premiums for transportation applications requiring stiffness-to-weight ratios beyond standard glass reinforcement.
Industry Challenges
- Compression molding technician scarcity:Tooling setup and cure cycle optimization expertise is retiring faster than vocational programs replenish skilled operators, constraining capacity expansion at mid-tier molders.
- Multi-jurisdiction certification timelines:Simultaneous UL 94 flammability, FMVSS 302 automotive, and EN 13501 construction fire testing extends product qualification to twenty-four months, delaying revenue recognition on new grade launches.
- Legacy press retrofit requirements:Existing hydraulic compression equipment requires control system upgrades to handle variable fiber length SMC and precision temperature profiling, demanding capital deployment without volume guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sheet Molding and Bulk Molding Compounds Market |
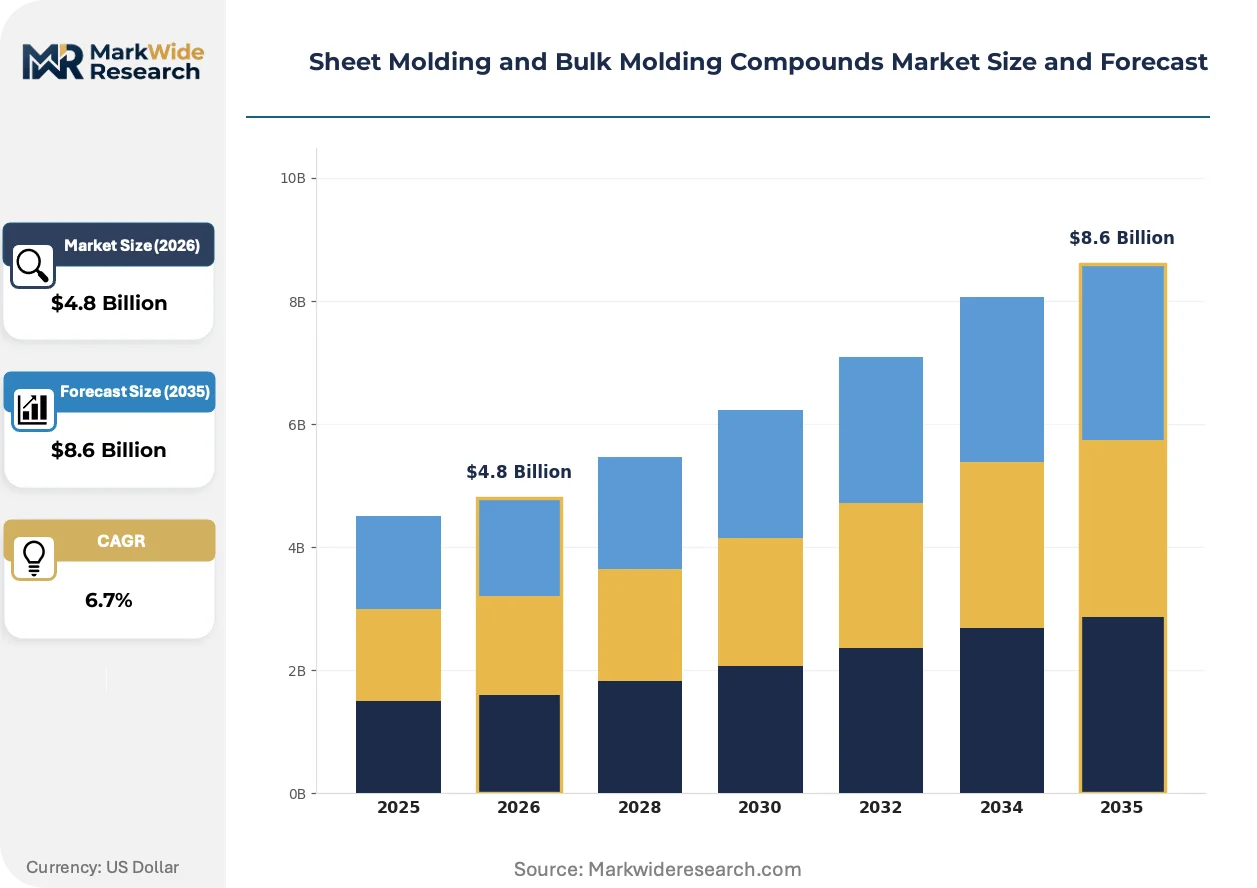
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet Molding Compound, Bulk Molding Compound, Electrical Insulation, Fire-Resistant Composites Application: Automotive Parts, Construction Materials, Electrical Housings, Industrial Equipment End User: OEMs, Tier-1 Suppliers, Manufacturers, Construction Companies Distribution Channel: Direct Sales, Online Platforms, Distributors, Retailers |
| Companies Covered | Menzolit, Polytec Group, IDI Composites International, Polynt SPA, AOC, Continental Structural Plastics (Teijin), Core Molding Technologies, Toray Industries, Polynt-Reichhold, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sheet Molding and Bulk Molding Compounds Market Evolving Landscape
Material science advances and regulatory chemistry constraints are converging to redefine formulation priorities, with fiber architecture, resin reactivity, and molding automation advancing in parallel rather than sequential development cycles.
Low-profile additive technology is integrating surface-quality enhancers directly into SMC resin matrices to eliminate post-mold sanding on Class-A automotive panels. BMW and Mercedes-Benz exterior programs are specifying these grades for hood and decklid applications where paint-line compatibility must match steel substrates. The technology is integrating cosmetic performance with structural function, collapsing traditional trade-offs between surface finish and mechanical properties that previously required separate process steps.
REACH SVHC candidate list expansion is forcing reformulation of cobalt-based cure promoters across European compounder portfolios. ECHA substance of very high concern designations for cobalt salts are triggering substitution programs for polyester and vinyl ester hardener systems, compressing approved chemical inventories and extending qualification protocols. German and French automotive suppliers are most exposed, with Tier-1 molders accelerating peroxide-based alternative testing to maintain market access.
Direct long-fiber thermoplastic competition is compressing SMC's historical dominance in semi-structural automotive brackets and underbody shields. Procurement teams at Stellantis and Ford are running parallel sourcing evaluations for hybrid vehicle battery trays, with compression-molded thermosets competing against injection-molded PP-LFT for cost-sensitive volume programs. The behavior is most visible in North American C-segment crossover platforms where tooling amortization and cycle-time economics dominate material selection criteria.
Sheet Molding and Bulk Molding Compounds Market Segmentation
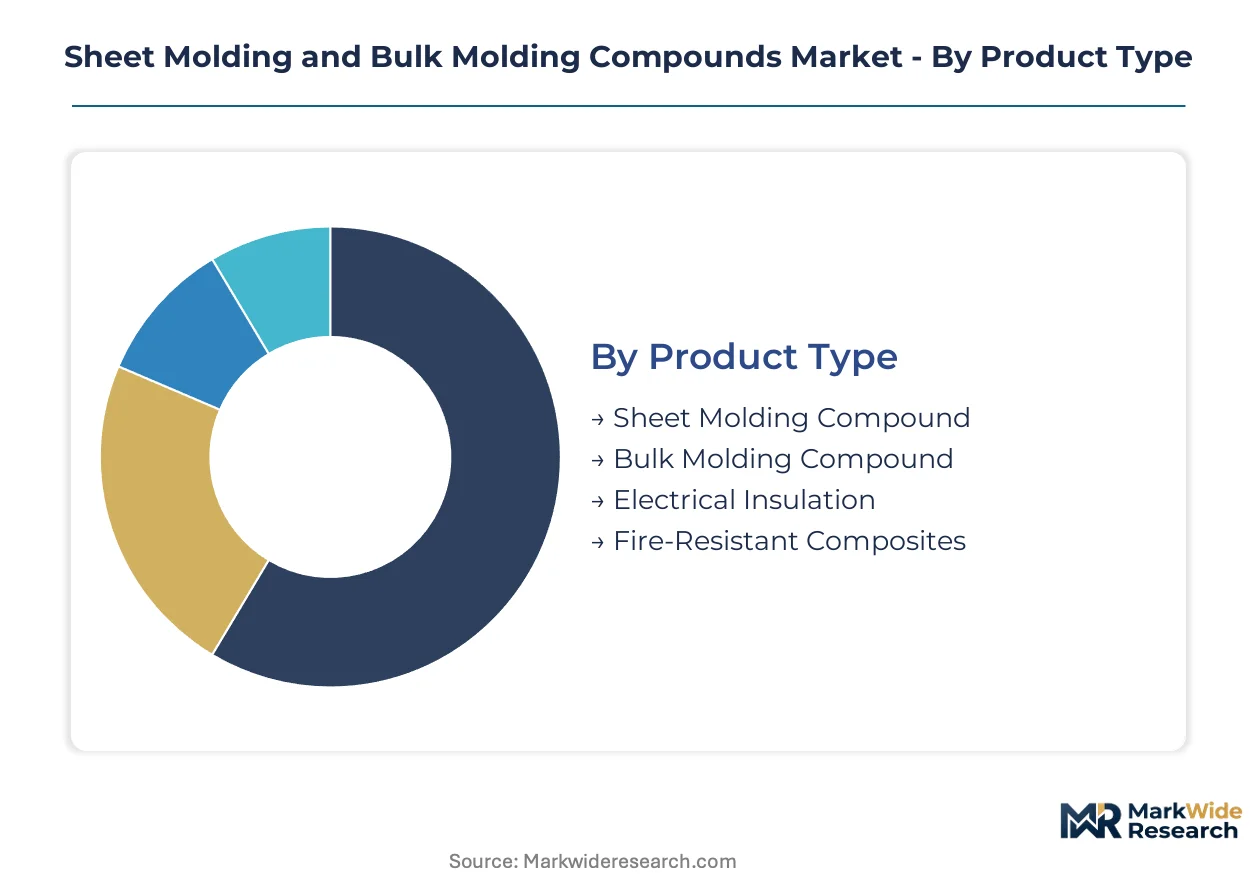
Segmentation in sheet molding and bulk molding compounds reflects divergent technical requirements across automotive lightweighting, electrical fire safety, and construction durability mandates. Buyers prioritize distinct performance matrices—surface finish, flame retardancy, or structural stiffness—that reshape procurement patterns and supplier specialization.
Product Type:
Cost tier differentiation separates commodity formulations from specification-grade compounds commanding formulation premiums.
- Sheet Molding Compound:Glass-reinforced thermoset sheets comprising 25-35% fiber content, compression-molded at 130-170°C for rigid structural parts. Demand concentrates in Germany and the United States where BMW, Mercedes-Benz, and domestic OEMs specify Class-A surface grades for hood and decklid panels to meet EPA fuel-economy targets.
- Bulk Molding Compound:Premixed dough-like compound injection- or compression-molded for complex geometries requiring tight dimensional tolerance. Precision electrical housings for EV battery enclosures in China and the United States are pulling fire-resistant BMC grades into high-volume platform contracts.
- Electrical Insulation:Low-conductivity formulations serving transformer housings and switchgear components.
- Fire-Resistant Composites:Halogen-free and intumescent grades mandated by EU construction codes and GB standards in China.
Sheet Molding Compound leads volumes today; Bulk Molding Compound is gaining share fastest.
Application:
Application segmentation tracks where metal-to-composite substitution delivers regulatory compliance or total-cost advantages.
- Automotive Parts:Body panels, battery enclosures, and structural reinforcements displacing steel stampings. German and US passenger-vehicle lightweighting programs concentrate procurement for under-hood and exterior applications.
- Construction Materials:Fire-resistant facade panels and cladding systems penetrating commercial building codes. EU member states and China are accelerating aluminum composite panel substitution following enhanced ignition resistance mandates.
- Electrical Housings:Precision-molded enclosures for power distribution and EV charging infrastructure.
- Industrial Equipment:Corrosion-resistant housings for chemical processing and agricultural machinery.
Automotive Parts dominates current offtake; Construction Materials is climbing the fastest on code-driven substitution.
End User:
Customer type determines specification authority and volume commitment scale.
- OEMs:Vehicle manufacturers and appliance producers with direct formulation approval authority. BMW, Mercedes-Benz, and Stellantis engineering centers in Germany and the United States drive Class-A surface specifications and synchronize resin roadmaps with platform timelines.
- Tier-1 Suppliers:Contract molders serving OEM assembly lines with certified compound grades. Concentrated automotive supply bases in Stuttgart, Munich, and Detroit manage compression molding capacity and cure cycle optimization.
- Manufacturers:Industrial equipment producers sourcing electrical and structural components.
- Construction Companies:Project-based buyers procuring facade and cladding systems through specification-driven tenders.
OEMs command specification authority today; Tier-1 Suppliers are expanding procurement influence fastest through platform integration.
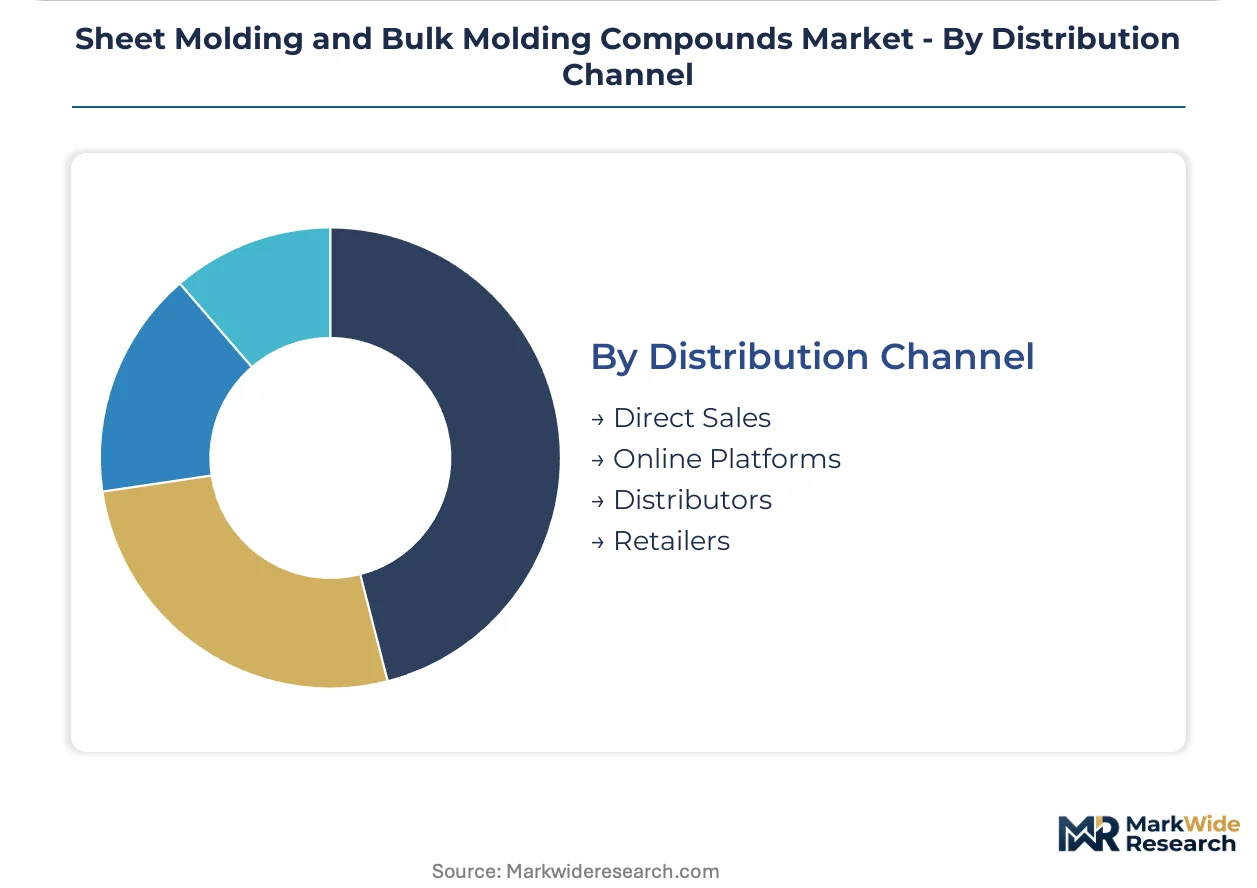
Distribution Channel:
Channel selection reflects order size, technical service requirements, and geographic proximity to molding operations.
- Direct Sales:Long-term supply agreements between compounders and high-volume molders. Menzolit and IDI Composites International anchor European and North American demand through direct technical service relationships.
- Distributors:Regional inventory holders serving mid-tier molders with shorter lead time requirements.
- Online Platforms:Emerging channels for standard-grade compounds and small-batch procurement.
- Retailers:Limited presence; hardware-focused outlets for repair and maintenance quantities.
Direct Sales captures the largest volume commitment; Distributors are expanding coverage fastest into secondary manufacturing clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive manufacturing cluster concentrates the most advanced Class-A surface specifications for thermoset composites, with Stuttgart and Munich engineering centers driving formulation roadmaps across European supply chains.
Germany
BMW and Mercedes-Benz exterior programs specify low-profile additive SMC for hood and decklid applications. REACH SVHC candidate list expansion forces cobalt-based cure promoter substitution across polyester formulations. Stuttgart and Munich Tier-1 molders manage compression molding capacity and cure cycle optimization for platform synchronization.
United States
EPA Corporate Average Fuel Economy standards accelerate SMC substitution for steel body panels in passenger-vehicle lightweighting programs. UL 94 flammability and FMVSS 302 automotive testing extends product qualification timelines for new grade launches. Detroit-area automotive supply bases anchor North American demand through specialized fire-resistant formulations for electrical infrastructure.
China
GB standards and dual carbon goals govern resin chemistry and volatile emissions for construction and automotive applications. NMPA and MIIT oversight shapes which compound formulations gain market access for EV battery enclosures. Yangtze River Delta manufacturing clusters pull fire-resistant BMC grades into high-volume platform contracts for domestic OEMs.
Japan
METI industrial policy and JIS standards frame material specifications for transportation and electrical applications. PMDA regulatory pathways influence medical-adjacent composite uses in diagnostic equipment housings. Kanto region engineering centers integrate high-performance fiber into structural SMC for stiffness-to-weight optimization.
India
PLI scheme incentives for domestic EV manufacturing open specification windows for localized SMC production. BIS certification requirements and DGFT trade policies shape import substitution strategies for polyester and vinyl ester feedstocks. Maharashtra and Gujarat automotive corridors concentrate Tier-1 molder capacity serving Maruti Suzuki and Tata Motors platforms.
Sheet Molding and Bulk Molding Compounds Market Competitive Landscape
Global majors compete with regional champions across formulation specialization and captive blending capacity. The vendor base organizes around three tiers: integrated resin-compounders controlling upstream polyester supply, independent compounders sourcing multi-source feedstock, and captive molders with in-house compounding for proprietary grades. Two dominant competitive moves define current positioning: backward integration into resin production to secure margin on technical grades, and geographic expansion through localized blending facilities to serve OEM platform engineering timelines.
Among European-based compounders, Menzolit exemplifies the integrated resin-compounder archetype through captive blending capacity. IDI Composites International occupies a position as an independent compounder anchoring North American demand. Toray Industries sits within the materials science conglomerate tier, representing high-performance fiber integration strategies for structural transportation applications.
| Leading Market Players |
|---|
| Menzolit |
| Polytec Group |
| IDI Composites International |
| Polynt SPA |
| AOC |
| Continental Structural Plastics (Teijin) |
| Core Molding Technologies |
| Toray Industries |
| Polynt-Reichhold |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap compounders across Germany and Japan anchor supply discipline through generational ownership horizons that resist short-term margin compression. Their captive blending investments in Stuttgart and Nagoya manufacturing corridors synchronize resin formulation roadmaps with BMW and Toyota platform engineering timelines, embedding pricing power through technical-grade specialization rather than commodity volume.
Pricing Analysis
Styrene and benzene derivative pass-through clauses dominate unsaturated polyester resin contracts, with quarterly adjustments tracking petrochemical feedstock indices. Pricing stratifies across Class-A surface grades, fire-resistant BMC formulations, and commodity electrical housings, with flame-retardant certification tiers commanding specification premiums. Cost compression in standard glass-reinforced grades is intensifying as direct long-fiber thermoplastic alternatives capture semi-structural automotive brackets. Tier-1 automotive suppliers exhibit highest price sensitivity due to tooling amortization pressures, while electrical infrastructure buyers prioritize UL 94 certification over unit cost.
Supply Chain Analysis
Compression molding technician scarcity in Michigan and Baden-Württemberg production clusters constrains capacity expansion despite order backlog accumulation. Manufacturing gravity centers on Germany, China, and the United States, with Yangtze River Delta facilities serving domestic EV battery enclosure demand. Feedstock dependencies encompass glass fiber rovings from three dominant producers, cobalt-based cure promoters facing REACH substitution mandates, and vinyl ester resins subject to ECHA registration delays. Single-source vulnerability in high-performance fiber supply creates bottleneck risk during demand surges. Distribution runs through direct technical service relationships for high-volume molders, with regional distributors covering secondary manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance costs in Europe run substantially higher than GB standard adherence in China, creating arbitrage opportunities for compounders with dual-registered formulation portfolios. This regulatory cost differential rewards geographic flexibility in production placement.
For Market Incumbents: Acquire captive resin blending capacity to secure margin on technical grades threatened by styrene price volatility and glass fiber supply concentration. Menzolit's European integration model demonstrates defensibility through upstream control over polyester formulation. IDI Composites International anchors North American position through specialized fire-resistant grades for electrical infrastructure, insulating against commodity substitution. Certification investment in UL 94 and EN 13501 fire testing creates switching costs that lock in OEM platform specifications. For New Entrants and Emerging Players: Mid-tier construction facade panel buyers in India and Southeast Asia represent underserved procurement segments with limited local fire-resistant composite supply. PLI scheme incentives for domestic EV manufacturing in Maharashtra and Gujarat automotive corridors open specification windows for localized SMC production serving Maruti Suzuki and Tata Motors platforms. Carbon fiber-SMC hybridization for stiffness-critical transportation applications offers specification premium capture with lower volume thresholds than commodity automotive programs. For Investors and Strategic Acquirers: Valuations sit cheapest among independent compounders lacking backward integration into resin production, particularly those exposed to cobalt-based cure promoter reformulation costs. Long-term viability hinges on formulation agility across REACH, GB standards, and evolving EPA chemistry constraints. Acquisition target archetype: regional compounders with certified fire-resistant grades and established OEM platform relationships. Watch ECHA substance of very high concern designations for cobalt salts as inflection indicator forcing accelerated consolidation among reformulation-lagged producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive polyester supply secures margin on technical grades amid styrene volatility. |
| Fire-Resistant Formulation Certification | UL 94 and EN 13501 testing creates specification lock-in for electrical infrastructure buyers. |
| Localized Blending Facility Expansion | Regional compounding in India and China aligns with PLI incentives and domestic OEM platform timelines. |
| Cobalt-Free Cure System Development | Peroxide-based alternatives maintain REACH market access as ECHA SVHC restrictions harden. |
| Carbon Fiber-SMC Hybridization | High-performance fiber integration commands specification premiums from transportation OEMs. |
Research Methodology
Bottom-up automotive and electrical housing modeling reconciled against top-down resin supply and compounding capacity tracking forms the analytical core of this study. Primary interviews with plant managers at Tier-1 molders, procurement leads at BMW and Stellantis, distribution channel partners serving secondary manufacturing clusters, and technical R&D directors at resin suppliers generated demand-side intelligence. Secondary validation drew from ECHA REACH registration databases, EPA fuel-economy compliance filings, customs and trade data tracking glass fiber and polyester resin flows, and SEC disclosures from publicly listed materials conglomerates.
Input-output matrices linking styrene derivative costs, glass fiber roving availability, and compression molding capacity utilization to end-use segment volumes drove projection construction across the analysis window. Segmentation dimensions encompassed product type tier, application industry, end-user specification authority, and regional production hub clustering. CAGRs were derived from regression analysis of historical substitution rates for metal-to-composite displacement, adjusted for regulatory acceleration effects. Industry-specific forecast inputs included EPA Corporate Average Fuel Economy standard stringency trajectories and EU automotive CO2 mandate phase-in schedules.
Underlying measurement precision varies by segment; automotive parts and electrical housings carry tighter precision than construction materials given more consolidated buyer concentration and standardized testing protocols. Forecasts embed assumptions regarding REACH SVHC list expansion timing, cobalt salt substitution program acceleration, and PLI scheme incentive continuity in India. Material deviation in ECHA substance evaluation timelines, styrene price volatility amplitude, or glass fiber producer capacity expansion plans warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Cyclohexane Market
Bulk Chemicals
Acrylamide Market
Bulk Chemicals
Propionic Acid Market
Bulk Chemicals
Metallurgical Coke Market
Bulk Chemicals
Carbon Black Market
Bulk Chemicals
Electronic Batio3 Powder Market
Bulk Chemicals
Clomiphene Citrate Market
Bulk Chemicals
North America Potassium Permanganate Market
Bulk Chemicals
Commodity Plastics Market
Bulk Chemicals
Chloroacetophenone Market
Bulk Chemicals
Isopentane Market
Bulk Chemicals
Paraxylene(PX) Market
Bulk Chemicals
Europe Lithium Chloride Market
Bulk Chemicals
Global Lithium Carbonate Market
Bulk Chemicals
Diisopropylbenzene Market
Bulk Chemicals
Acetyl Tributyl Citrate Market