
 Global Membrane Filters Market | 2026-2036
Global Membrane Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Membrane Filters Market Foresight
A capital-intensity divergence between players is redrawing competitive boundaries in membrane filtration. DuPont leverages its polymer science heritage to control proprietary polyethersulfone formulations. Danaher Corporation anchors North American bioprocessing demand through Pall Corporation's installed base. Merck KGaA sustains European pharmaceutical loyalty with integrated validation services.
Membrane filters are thin, porous barriers engineered with defined pore sizes ranging from 0.1 micrometers in microfiltration to sub-nanometer dimensions in reverse osmosis, typically manufactured through phase inversion or track-etching processes to achieve precise separation of particles, microorganisms, or dissolved solutes from liquid or gas streams. Reverse osmosis membranes command premium pricing in desalination and ultrapure water systems where energy efficiency and salt rejection rates determine total cost of ownership. Polyethersulfone dominates biopharmaceutical applications for its thermal stability and low protein binding, while polytetrafluoroethylene competes aggressively in aggressive chemical processing environments.
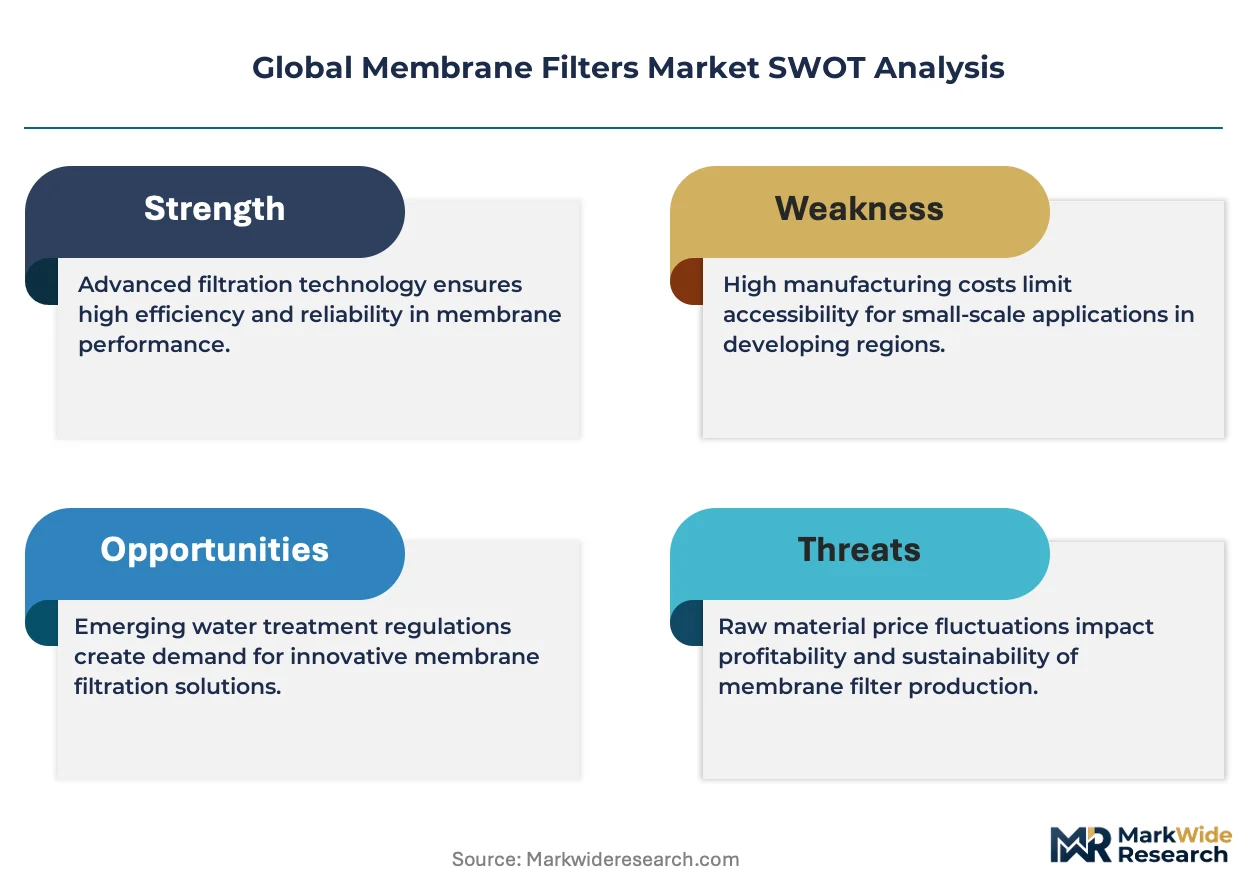
FDA enforces Process Validation guidance that mandates documented membrane performance in sterile drug manufacturing, while EMA's Annex 1 revision tightens contamination control expectations for aseptic processing. REACH and RoHS constrain material choices in European electronics manufacturing, pushing fluoropolymer alternatives toward compliant formulations. Stakeholders must weigh regulatory compliance investments against the margin compression from commoditized microfiltration segments.
Market Dynamics
Biologics manufacturing scale-up is compressing membrane replacement cycles as single-use systems displace stainless steel infrastructure, forcing suppliers to validate performance under higher throughput conditions.
Growth Catalysts
- EMA Annex 1 Revision:The updated contamination control guidance mandates enhanced filtration redundancy in aseptic processing, compelling pharmaceutical manufacturers to upgrade existing membrane installations.
- Polyethersulfone thermal stability:This material's superior protein binding characteristics are accelerating adoption in mAb purification workflows where temperature cycling demands exceed polysulfone limits.
- China's dual carbon goals:Energy efficiency mandates in desalination and wastewater treatment are driving membrane replacement toward low-pressure high-recovery configurations.
Market Restraints
- Fluoropolymer feedstock volatility:PTFE membrane production faces input cost pressure from fluorspar concentrate supply concentration in Mongolia and China.
- Phase inversion equipment scarcity:Precision casting line capacity constraints in Germany and Japan limit rapid capacity expansion for asymmetric membrane architectures.
- REACH substance restrictions:Candidate list expansion for per- and polyfluoroalkyl substances creates formulation uncertainty for hydrophobic membrane coatings in European electronics manufacturing.
Strategic Opportunities
- Cell and gene therapy viral filtration:Emerging demand for nanometer-precision membranes in lentivirus and AAV clarification offers premium pricing outside commoditized microfiltration.
- India PLI scheme for active pharmaceutical ingredients:Domestic bioprocessing capacity expansion creates localized membrane validation and service requirements.
- Digital twin integration:Convergence of membrane performance modeling with IoT sensor networks enables predictive replacement scheduling and service contract bundling.
Industry Challenges
- Cleanroom validation technician scarcity:FDA Process Validation documentation requirements exceed available qualified personnel for membrane integrity testing protocol execution.
- Legacy system integration friction:Retrofitting single-use membrane skids into existing stainless steel infrastructure requires custom manifold engineering and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Membrane Filters Market |
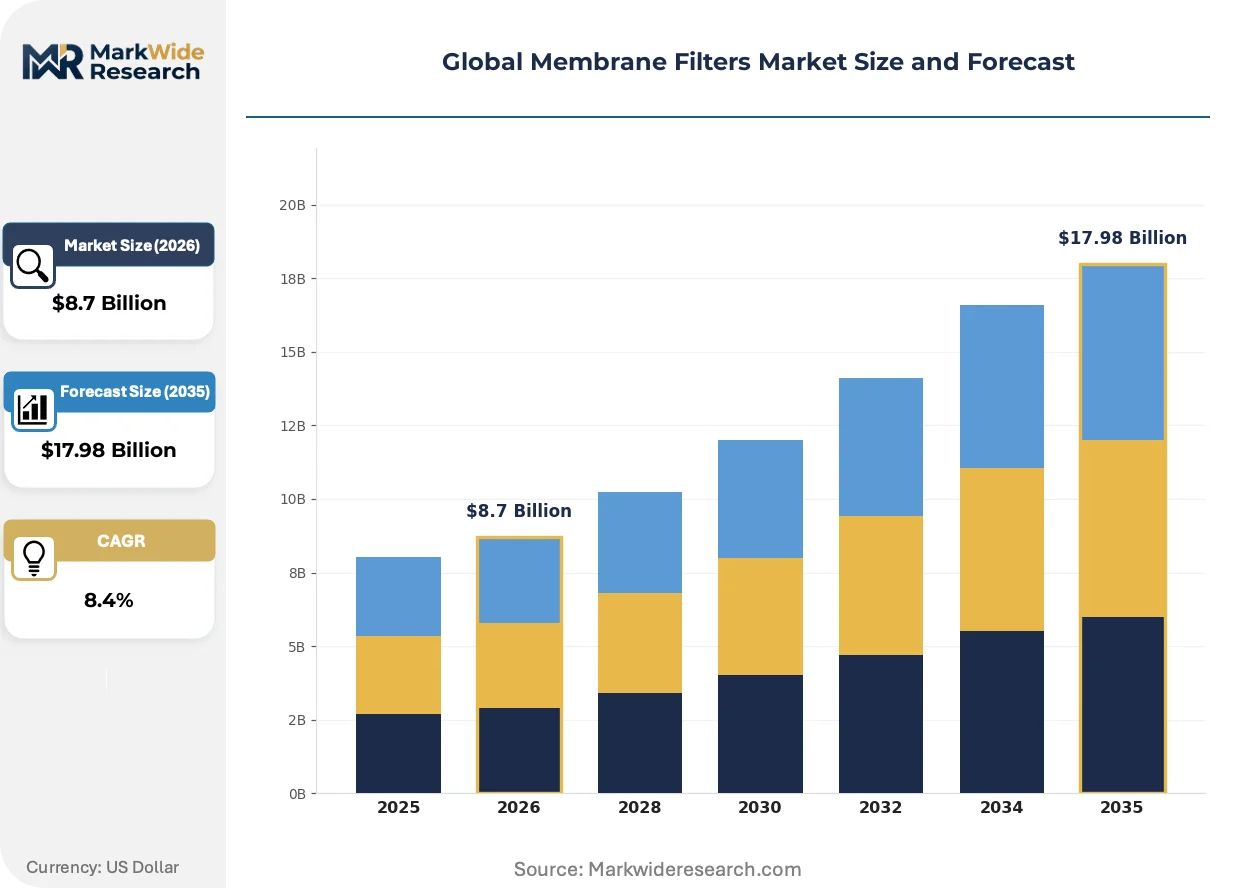
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfiltration, Ultrafiltration, Nanofiltration, Reverse Osmosis Material: Polyethersulfone, Cellulose Acetate, Polytetrafluoroethylene, Polyvinylidene Fluoride, Polyamide Application: Pharmaceutical Processing, Food & Beverage, Wastewater Treatment, Electronics Manufacturing End User: Biotech Firms, Chemical Plants, Research Laboratories, Municipal Water Suppliers |
| Companies Covered | DuPont, Merck KGaA, Danaher Corporation, Thermo Fisher Scientific, Pall Corporation, Toray Industries, Alfa Laval, GEA Group, Koch Separation Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Membrane Filters Market Shifts & Advancements
Membrane architecture is fragmenting as application-specific designs displace generic platforms, with manufacturers optimizing pore geometry and surface chemistry for single-process dominance rather than multi-purpose flexibility.
Track-etched polycarbonate membranes are decomposing the microfiltration market into precision-segmented niches. Diagnostic device manufacturers in the United States and Germany are adopting these for controlled cell sorting applications where uniform pore distribution outweighs cost sensitivity. The technology is decomposing volume-based competition into specification-driven procurement where certificate of analysis depth determines supplier selection.
REACH authorization timelines for perfluorinated substances are compressing fluoropolymer membrane development pipelines. ECHA's 2023 restriction proposal on PFAS in industrial applications forces reformulation of hydrophobic vent filters before sunset dates. Medical device manufacturers are accelerating validation of silicone-based alternatives in Switzerland and Germany to preempt supply discontinuity.
Consolidated buying by contract development and manufacturing organizations is compressing supplier negotiation cycles. Large molecule outsourcing specialists in Massachusetts and Bavaria are unbundling membrane procurement from equipment OEM service agreements, forcing direct price transparency. This pattern concentrates in mammalian cell culture applications where annual membrane spend exceeds qualification-driven switching costs.
Global Membrane Filters Market Segmentation
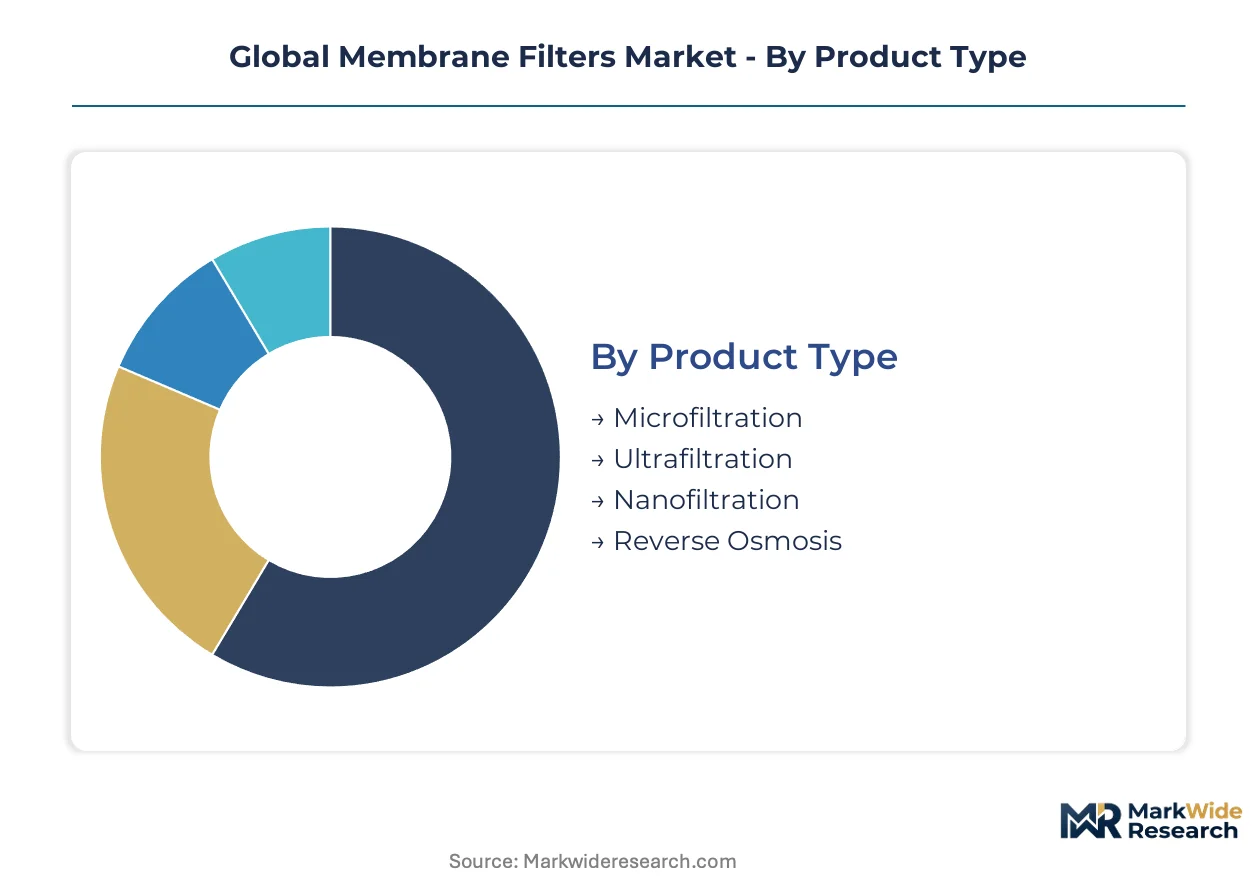
Membrane filter procurement channels diverge sharply by technical specification and regulatory burden. Pharmaceutical buyers validate through OEM service agreements while municipal contractors bid on total cost of ownership metrics.
Product Type:
Microfiltration and reverse osmosis membranes move through equipment OEMs with bundled validation services, while ultrafiltration and nanofiltration increasingly route through direct distribution for replacement cycles.
- Microfiltration:Pore structures ranging from 0.1 to 10 micrometers retain bacteria and suspended solids in sterile drug manufacturing. Demand clusters in German and United States bioprocessing corridors where FDA Process Validation mandates documented integrity testing protocols.
- Reverse Osmosis:Dense polyamide thin-film composites achieve sub-nanometer separation for desalination and ultrapure water generation. China's coastal provinces drive replacement demand as MEE enforces energy efficiency standards in municipal treatment facilities.
- Ultrafiltration:1-100 nanometer pore ratings concentrate proteins and remove viruses in mAb purification workflows.
- Nanofiltration:Selective divalent ion rejection suits water softening and selective pharmaceutical separations.
Microfiltration dominates installed base. Reverse osmosis is where expansion concentrates.
Material:
Material selection tracks end-use thermal and chemical resistance requirements, with premium formulations commanding qualification-driven pricing.
- Polyethersulfone:Amorphous thermoplastic withstands repeated steam sterilization cycles without hydrolytic degradation. Massachusetts and Bavaria biotech clusters specify this for single-use bioreactor harvest applications where protein binding minimization determines yield.
- Polytetrafluoroethylene:Fluoropolymer backbone delivers extreme chemical inertness for aggressive solvent processing. Electronics manufacturers in Japan and Germany accelerate validation of alternative formulations as ECHA advances PFAS restriction timelines.
- Cellulose Acetate:Hydrophilic surface chemistry suits diagnostic device applications with cost-sensitive membrane requirements.
- Polyvinylidene Fluoride:Mechanical robustness and chemical resistance balance outdoor membrane bioreactor durability needs.
- Polyamide:Interfacial polymerization creates thin-film composite layers for reverse osmosis and nanofiltration selectivity.
Polyethersulfone anchors biopharmaceutical loyalty. Polytetrafluoroethylene faces reformulation pressure.
Application:
Application segmentation reflects divergent performance validation standards and replacement cycle economics across regulated industries.
- Pharmaceutical Processing:Sterile filtration and virus removal steps require documented membrane integrity under FDA and EMA guidance. Single-use system adoption in United States and German CDMOs compresses replacement intervals while raising qualification documentation burdens.
- Wastewater Treatment:Membrane bioreactor configurations achieve tertiary treatment in water-stressed regions. China's Yangtze and Yellow River basins drive module replacement as dual carbon goals mandate energy recovery optimization.
- Food & Beverage:Dairy protein concentration and beverage clarification employ sanitary-grade ultrafiltration with CIP protocol compatibility.
- Electronics Manufacturing:Ultrapure water systems for semiconductor fabrication require sub-ppb ionic contamination control.
Pharmaceutical processing commands premium pricing. Wastewater treatment is climbing the fastest.
End User:
End user categories separate qualification-capable buyers from price-sensitive procurement with limited technical validation resources.
- Biotech Firms:Mammalian cell culture specialists in Massachusetts, Bavaria, and Switzerland specify validated membrane trains with certificate of analysis depth. EMA Annex 1 revision forces filtration redundancy upgrades in existing aseptic suites.
- Municipal Water Suppliers:Desalination and advanced treatment operators in China and Saudi Arabia optimize total cost of ownership through energy-efficient reverse osmosis module selection.
- Chemical Plants:Aggressive process streams demand fluoropolymer or ceramic membrane durability.
- Research Laboratories:Small-batch filtration needs route through distributor catalog purchasing with minimal technical support.
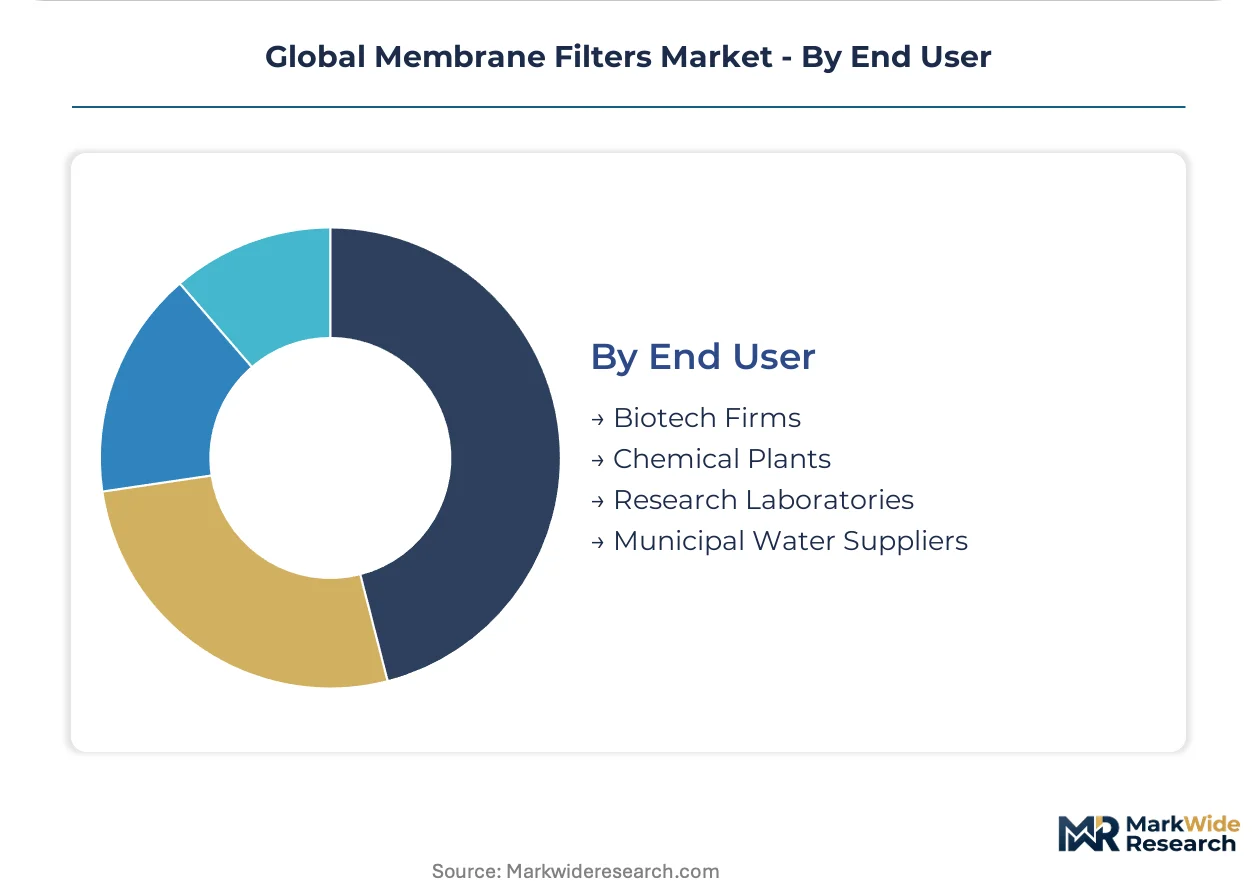
Biotech firms concentrate premium demand. Municipal water suppliers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Municipal contractors in China negotiate on total cost of ownership metrics while biotech clusters in Massachusetts and Bavaria absorb premium pricing for validated membrane trains.
United States
FDA Process Validation mandates drive membrane integrity documentation in sterile drug manufacturing. The bioprocessing corridor between Boston and Cambridge concentrates mammalian cell culture specialists specifying polyethersulfone membranes for single-use harvest applications. CDMO consolidation in Massachusetts unbundles membrane procurement from equipment OEM service agreements.
Germany
EMA Annex 1 revision forces filtration redundancy upgrades in existing aseptic suites. REACH substance restrictions constrain fluoropolymer formulation choices for electronics manufacturers. The Bavaria biotech cluster sustains demand for integrated validation services alongside membrane supply.
China
Dual carbon goals and MEE energy efficiency standards accelerate membrane replacement in coastal desalination facilities. The PLI scheme for active pharmaceutical ingredients expands domestic bioprocessing capacity. Yangtze River basin municipalities optimize membrane bioreactor configurations for tertiary wastewater treatment.
Japan
METI efficiency mandates push semiconductor fabricators toward ultrapure water systems with sub-ppb ionic contamination control. Track-etched polycarbonate membrane adoption concentrates in diagnostic device manufacturing. Precision casting line capacity constraints in domestic asymmetric membrane production limit rapid supply expansion.
Switzerland
Swissmedic oversight sustains pharmaceutical membrane validation standards comparable to EMA requirements. Medical device manufacturers accelerate silicone-based hydrophobic vent filter validation ahead of PFAS restriction timelines. The Basel biotech corridor maintains premium membrane specification for biologics purification workflows.
Global Membrane Filters Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics. Consolidated buying by large-molecule outsourcing specialists compresses supplier negotiation cycles. Three archetypes dominate: polymer science heritage players controlling proprietary formulations, bioprocessing-anchored integrators with installed base leverage, and precision manufacturing specialists in track-etched architectures. Capacity expansion in asymmetric membrane casting and strategic partnerships for digital twin integration represent the dominant competitive moves.
Within the polymer science tier, DuPont exemplifies formulation control through proprietary polyethersulfone heritage. Danaher Corporation, through Pall Corporation, anchors North American bioprocessing demand with validation-integrated service models. Merck KGaA occupies a position sustaining European pharmaceutical loyalty through combined membrane supply and regulatory documentation depth.
| Leading Market Players |
|---|
| DuPont |
| Merck KGaA |
| Danaher Corporation |
| Thermo Fisher Scientific |
| Pall Corporation |
| Toray Industries |
| Alfa Laval |
| GEA Group |
| Koch Separation Solutions |
| Others |
Supply & Pricing Matrix
Ninety-day polyethersulfone resin inventory cycles in German precision casting facilities anchor pricing power for asymmetric membrane architectures, compressing margin flexibility for distributors while amplifying formulation-control premiums for polymer-science heritage players.
Pricing Analysis
After-market validation service contracts generate lifetime value multiples exceeding membrane hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates OEM-integrated membrane trains with FDA documentation depth from catalog microfiltration and commodity reverse osmosis replacements. Cost compression in standard-grade microfiltration is intensifying because CDMO procurement unbundling forces direct price transparency. Municipal water suppliers in China exhibit highest price sensitivity, while Massachusetts biotech clusters absorb premium qualification-driven pricing.
Supply Chain Analysis
Port congestion on Asia-Europe container lanes elevates inbound logistics costs for fluoropolymer concentrate shipments from Mongolian mining corridors. Manufacturing gravity centers on Germany, Japan, and China for phase inversion casting equipment and asymmetric membrane production. Feedstock supply draws from Chinese fluorspar processing, Saudi petrochemical derivatives, and European specialty polymer compounding. Single-source vulnerability concentrates in precision track-etching equipment from Japanese suppliers. Distribution runs through equipment OEM bundling for pharmaceutical validation-integrated sales and direct distribution for municipal replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane filtration incumbents face substitution pressure from ceramic and electrospun nanofiber alternatives in aggressive chemical processing, requiring defensive positioning around validation-integrated service models.
For Market Incumbents: Consolidate formulation-control advantages through captive polyethersulfone resin supply and backward integration into precision casting line capacity. Deepen FDA Process Validation documentation services to raise switching costs against ceramic membrane substitutes in biologics harvest applications.
For New Entrants and Emerging Players: Validation technician scarcity in cleanroom integrity testing protocols opens white-space for third-party membrane qualification services. Target India's PLI-driven API manufacturing expansion with localized validation partnerships. Pursue digital twin integration for predictive replacement scheduling as the primary go-to-market wedge.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-optimized membrane filtration divisions lacking bioprocessing validation depth. Long-term viability hinges on exposure to cell and gene therapy viral filtration rather than commoditized microfiltration. Watch ECHA PFAS restriction implementation timelines as inflection signals for fluoropolymer membrane reformulation investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyethersulfone Resin | DuPont's polymer science heritage secures proprietary formulation control against feedstock volatility. |
| Digital Twin Integration for Predictive Maintenance | IoT sensor convergence enables service contract bundling and replacement scheduling optimization. |
| Cell and Gene Therapy Viral Filtration Development | Nanometer-precision membranes command premium pricing outside commoditized microfiltration segments. |
| Localized Validation Services in India | PLI scheme expansion creates domestic bioprocessing membrane qualification and service requirements. |
| Silicone-Based Hydrophobic Vent Filter Validation | Swiss and German medical device manufacturers preempt ECHA PFAS restriction supply discontinuity. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 483 inspection observations, EMA guidance documents, and customs trade data for fluoropolymer feedstock flows. Membrane procurement directors at Massachusetts CDMOs, cleanroom validation technicians in Bavaria, and municipal water treatment operators in China's Yangtze basin contributed operational perspective. Bottom-up membrane unit economics triangulate against top-down pharmaceutical capital expenditure tracking.
Segmentation dimensions modeled span filtration technology type, material chemistry, application vertical, and end-user qualification capability across the analysis window. CAGRs derive from replacement cycle compression in single-use bioprocessing and energy efficiency mandate-driven desalination upgrades. Forecast inputs incorporate EMA Annex 1 compliance timelines and China's MEE enforcement intensity for membrane bioreactor configurations.
Underlying assumptions cover sustained FDA Process Validation documentation requirements and REACH substance restriction trajectories, with deviation risk concentrated in ECHA PFAS sunset date acceleration and fluorspar supply chain disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Vapor Barrier Films Market
Membrane Materials
Global Medical Membranes Market
Membrane Materials
Breather Membranes Market
Membrane Materials
Membrane Polymers Market
Membrane Materials
Oxygen Barrier Films Market
Membrane Materials
Polyvinyl Chloride Membranes Market
Membrane Materials
Global Membrane Technology Market
Membrane Materials
Global Roofing Membranes Market
Membrane Materials
North America Ceramic Membranes Market
Membrane Materials
Fuel Cell Gas Diffusion Layer Market
Membrane Materials
PTFE Membrane Market
Membrane Materials
SBS Modified Bitumen Membrane Market
Membrane Materials
Global Membrane Chromatography Market
Membrane Materials
Nanoporous Membranes Market
Membrane Materials
Asia-Pacific, Middle East and Africa Macrofiltration Market
Membrane Materials
Hollow Fibers Membrane Market