
 Nonwoven Air Conditioning Filter Market | 2026-2036
Nonwoven Air Conditioning Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Nonwoven Air Conditioning Filter Market Intelligence
Replacement filter sales for residential systems is fragmenting as direct-to-consumer and subscription models challenge traditional HVAC service channels. Freudenberg Group leverages its material science expertise to offer specialized media for diverse industrial environments, including cleanrooms. Meanwhile, 3M Company sustains a strong brand presence in the consumer-facing pleated filter segment. Donaldson Company specializes in high-performance filtration for heavy-duty industrial and automotive applications.
Nonwoven air conditioning filters are disposable media made from entangled polyester or polypropylene fibers bonded together. Their primary function is capturing airborne particulates like dust and pollen from air streams in HVAC systems. The commercial application segment commands a significant share, driven by air quality rules in offices and healthcare. Filters with higher Filtration Efficiency ratings, such as MERV 13 and HEPA, expand rapidly due to health-focused building codes.
Regulatory frameworks from the EPA in the United States and the EU's REACH directive govern material safety and environmental impact. Concurrently, global standards like ISO 16890 are reshaping product development by establishing a universal classification system for filter performance. Navigating the trade-offs between filtration efficiency, energy consumption, and material sustainability will define future product strategy for manufacturers.
Market Dynamics
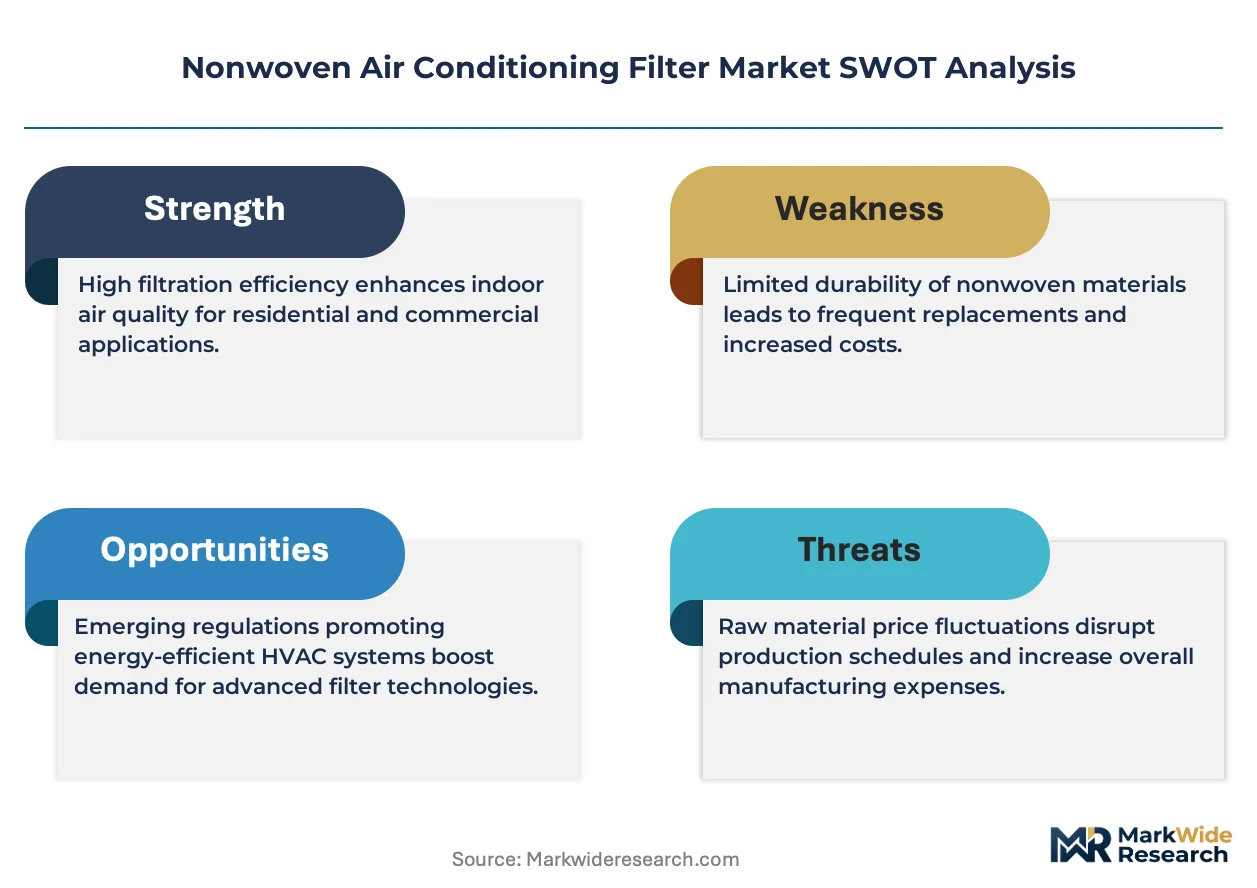
The fundamental market dynamic is the structural tension between demands for higher filtration efficiency, driven by health standards, and the resulting energy consumption penalty. This trade-off between air purity and operational cost is the central challenge defining product innovation and market segmentation.
Growth Catalysts
- Global Filtration Standards:The implementation of ISO 16890 provides a unified performance classification system, compelling manufacturers to produce higher-efficiency media and simplifying procurement for commercial buyers seeking specific particulate matter protection levels.
- Healthcare Infrastructure Expansion:Significant construction of hospitals and life science facilities, particularly in China, necessitates the use of advanced nonwoven filters to maintain sterile environments and meet stringent air quality regulations for patient care.
- Residential Air Quality Focus:A heightened consumer focus on indoor air quality is spurring adoption of higher-rated filters, such as MERV 13, in homes across North America and Europe to capture allergens, pollutants, and airborne pathogens.
Market Restraints
- Raw Material Volatility:The market is exposed to price fluctuations in petroleum-derived polymers like polypropylene and polyester, which are the primary inputs for nonwoven media and can compress manufacturer margins.
- Energy Consumption Penalty:Filters with high MERV or HEPA ratings create increased airflow resistance, forcing HVAC systems to consume more energy, which translates to higher utility costs for commercial and industrial building operators.
- Reusable Filter Competition:The availability of washable and reusable filter alternatives presents a substitution threat, especially in the residential segment where consumers may prioritize lower long-term cost over optimal filtration performance.
Strategic Opportunities
- Antimicrobial Filter Media:Incorporating antimicrobial or antiviral agents directly into nonwoven fibers creates a value-added product category for environments with high infection control requirements, such as public transportation and healthcare facilities.
- Direct-to-Consumer Channels:The development of subscription-based e-commerce models for residential filter replacements allows manufacturers to bypass traditional retail and build direct relationships with homeowners, capturing recurring revenue.
- Sensor-Integrated Smart Filters:Embedding pressure and particulate sensors into filter frames enables predictive maintenance alerts for building management systems, optimizing replacement cycles and ensuring consistent HVAC performance.
Industry Challenges
- End-of-Life Sustainability:Manufacturers face pressure to address the environmental impact of disposable polypropylene filters, requiring investment in developing recyclable materials or establishing effective take-back programs to align with circular economy principles.
- Regulatory Compliance Complexity:Adhering to chemical safety regulations like the EU's REACH directive requires extensive material testing and documentation, adding cost and complexity to product development and market access.
- Fragmented Replacement Cycles:Inconsistent filter replacement practices among residential and small commercial users lead to unpredictable demand patterns and suboptimal system performance, complicating inventory management for distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonwoven Air Conditioning Filter Market |
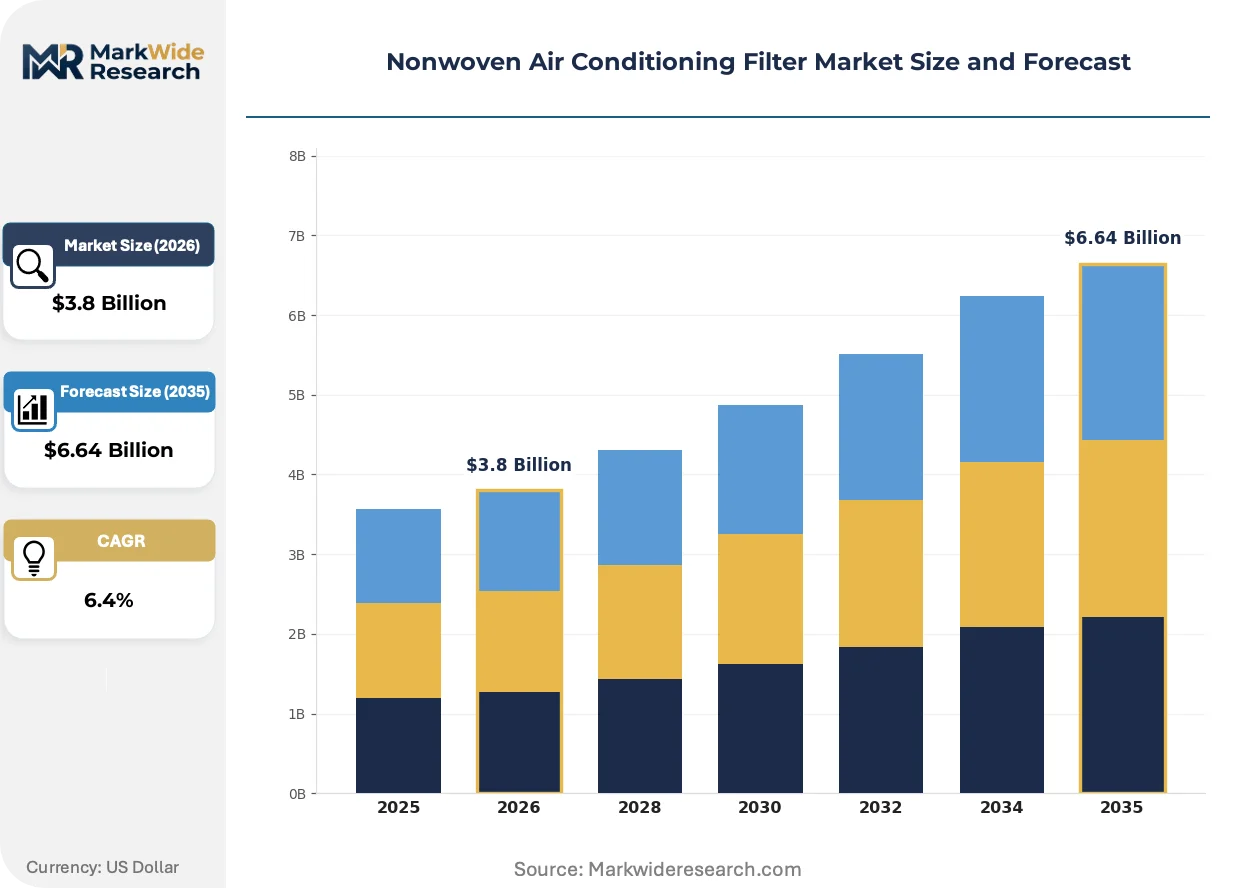
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panel Filters, Pleated Filters, HEPA Filters, Activated Carbon Filters Application: Residential, Commercial, Industrial, Automotive Filtration Efficiency: MERV 8, MERV 11, MERV 13, HEPA Material: Polyester, Polypropylene, Fiberglass, Others |
| Companies Covered | 3M Company, Freudenberg Group, Donaldson Company, MANN+HUMMEL, Parker Hannifin Corporation, Camfil AB, Ahlstrom, Toray Industries, Hollingsworth & Vose, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonwoven Air Conditioning Filter Market Strategic Shifts & Innovations
Product development is shifting from passive filtration media toward functional materials and integrated systems. This evolution is driven by the convergence of material science, sensor technology, and new commercial models that prioritize performance verification and operational efficiency over initial purchase price.
Electrostatically charged media represents a significant product evolution, using an electrical charge to attract and capture fine particulates more effectively than mechanical filtration alone. Commercial building operators are adopting these filters to meet higher efficiency targets without incurring prohibitive energy penalties. This technology is virtualizing the traditional trade-off between particle capture and airflow resistance, enabling higher performance from existing HVAC infrastructure.
Guidance from government bodies like the US EPA, which recommends MERV 13 filtration for public buildings and schools, directly shapes institutional procurement. This policy push accelerates the replacement of lower-grade filters in the education and government sectors. As a result, filter manufacturers are aligning product portfolios to emphasize certified performance in the ePM1 and ePM2.5 particle size ranges targeted by these standards.
Direct-to-consumer sales models, often based on subscriptions, are disrupting the residential filter replacement market. This channel shift circumvents traditional HVAC contractors and retail stores, allowing brands to engage directly with homeowners through e-commerce platforms. This trend is especially prominent in the United States, where convenience and automated replacement schedules appeal to consumers seeking to improve indoor air quality with minimal effort.
Nonwoven Air Conditioning Filter Market Segmentation
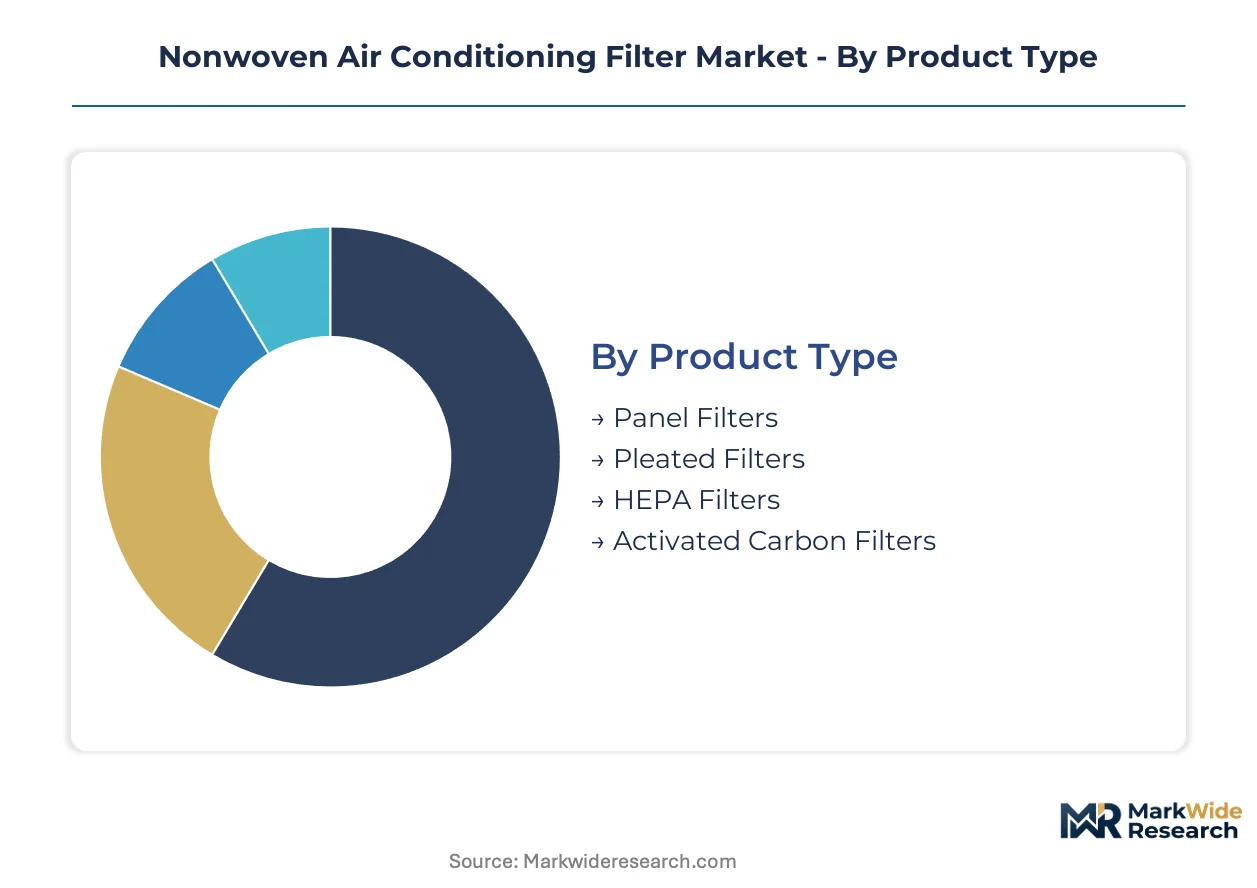
The nonwoven air conditioning filter market exhibits diverse segments, each addressing specific air quality needs and operational environments. Understanding these categories is crucial for manufacturers to tailor product development and for buyers to select optimal filtration solutions. This segmentation reveals distinct demand drivers and technological requirements across various end-use applications.
Product Type:
The product type segmentation delineates the functional range of nonwoven filters, from general particulate capture to specialized air purification, serving a broad spectrum of commercial and residential applications.
- HEPA Filters:These filters capture 99.97% of particles 0.3 microns in size, utilizing dense nonwoven media to meet stringent air purity standards. Demand is concentrating in healthcare facilities and cleanrooms, driven by critical infection control requirements and regulatory mandates.
- Pleated Filters:Constructed with a greater surface area of nonwoven material, these filters offer enhanced particle capture efficiency and longer service life compared to flat panels. Commercial buildings and residential HVAC systems in North America increasingly adopt pleated designs for improved indoor air quality.
- Panel Filters:Basic panel filters provide foundational air filtration.
- Activated Carbon Filters:Activated carbon filters absorb gaseous pollutants and odors.
The dominant share belongs to Pleated Filters, while HEPA Filters are closing the gap fastest.
Application:
This segmentation highlights how diverse operational environments dictate specific filtration requirements, influencing filter design and performance specifications across various end-user groups.
- Commercial:Commercial applications encompass offices, retail spaces, and healthcare facilities, where air quality regulations and occupant health drive the adoption of higher-efficiency nonwoven filters. Demand is particularly strong in China, fueled by extensive new construction projects and infrastructure development.
- Industrial:Industrial settings, including manufacturing plants and processing facilities, require robust nonwoven filters capable of handling heavy particulate loads and specific contaminants. Donaldson Company specializes in high-performance filtration for these demanding heavy-duty environments.
- Residential:Residential users seek higher MERV-rated filters for indoor air quality.
- Automotive:Automotive applications utilize nonwoven filters for cabin air filtration.
The Commercial segment commands the largest volume, with Industrial applications expanding significantly.
Filtration Efficiency:
This category delineates the performance tiers of nonwoven filters, directly correlating to their ability to capture airborne particulates and impacting overall air quality outcomes.
- MERV 13:MERV 13 filters capture smaller particles, including airborne bacteria and viruses, making them increasingly mandated by health-focused building codes and government recommendations for public spaces. The US EPA recommends this level for public buildings, driving procurement shifts.
- HEPA:HEPA-rated nonwoven filters offer the highest level of particulate filtration, critical for sterile environments and applications requiring ultra-clean air. Healthcare infrastructure expansion, particularly in China, boosts demand for these high-efficiency solutions.
- MERV 8:MERV 8 filters offer basic filtration for larger particles.
- MERV 11:MERV 11 filters capture finer particles and allergens.
Growth is concentrated in HEPA and MERV 13 filters, while MERV 8 maintains a foundational presence.
Material:
The material segmentation underscores the foundational polymer choices that define filter performance characteristics, cost structures, and environmental impact across the industry.
- Polypropylene:Polypropylene fibers are widely used due to their cost-effectiveness, chemical resistance, and ability to be electrostatically charged, enhancing particle capture. However, raw material volatility in petroleum-derived polymers can impact manufacturer margins.
- Polyester:Polyester nonwoven media offers good strength, durability, and moisture resistance, making it suitable for various filter designs and industrial environments. Freudenberg Group leverages its material science expertise to offer specialized polyester media.
- Fiberglass:Fiberglass is a traditional filter material for lower-efficiency panel filters.
- Others:This segment includes specialized materials for niche applications.
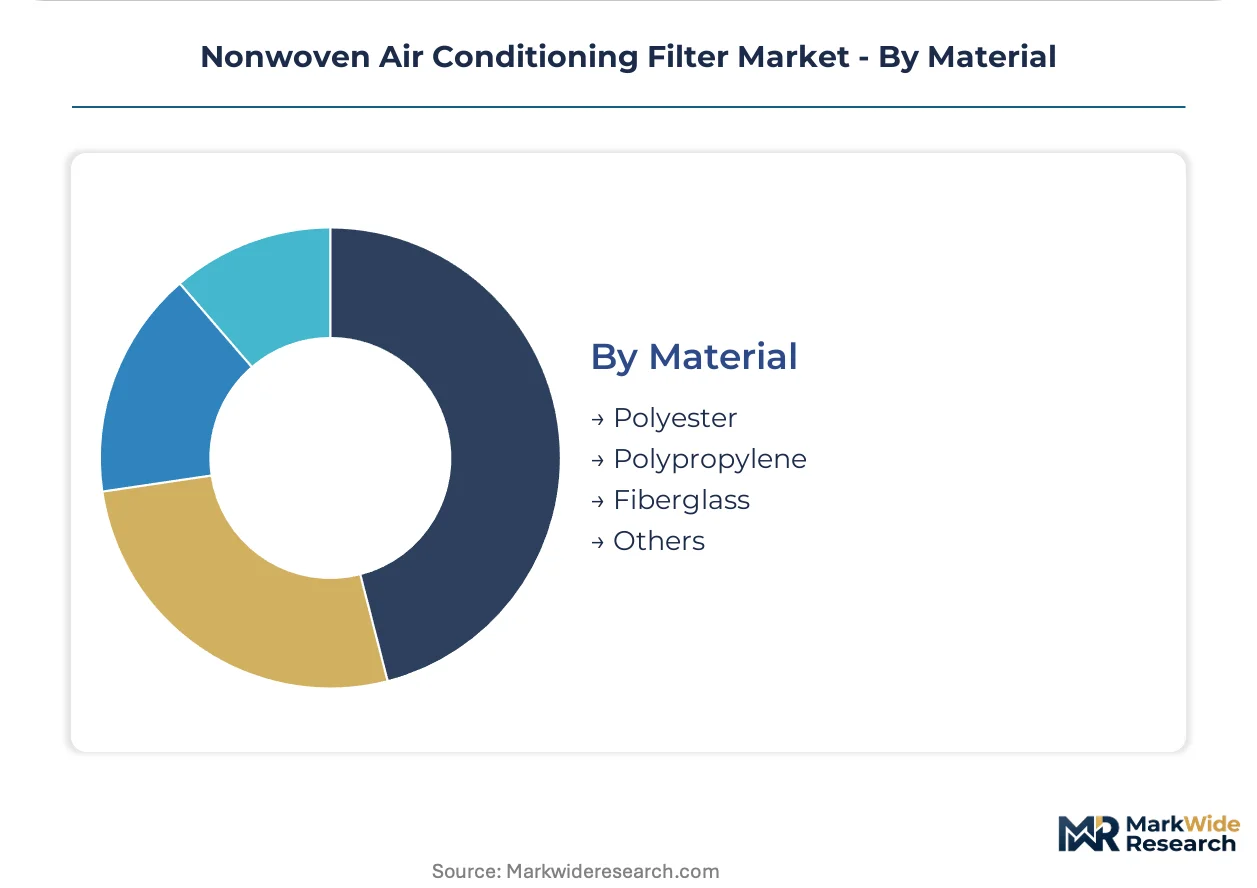
The market prefers Polypropylene and Polyester, with Fiberglass serving traditional requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The nonwoven air conditioning filter market exhibits varied demand elasticity across regions. Commercial and industrial segments, particularly in developed economies, prioritize performance and regulatory compliance over initial cost. Conversely, residential consumers often demonstrate higher price sensitivity, balancing filtration efficiency with replacement affordability.
China
Demand is propelled by extensive commercial and industrial construction, especially for healthcare facilities. China's dual carbon goals and stringent GB standards are pushing for higher efficiency and sustainable materials in HVAC systems. Major infrastructure projects in the Yangtze River Delta and Pearl River Delta regions require advanced filtration to meet air quality mandates.
United States
Higher MERV-rated filters are increasingly adopted in residential and public buildings due to a heightened focus on indoor air quality. The US EPA recommends MERV 13 filtration for public buildings and schools, influencing procurement. Urban centers like New York City and Los Angeles are implementing building codes that drive the use of advanced filtration technologies.
Germany
Industrial applications and cleanroom environments drive demand for high-performance nonwoven filters across manufacturing sectors. EU's REACH directive governs material safety and environmental impact, shaping product development for manufacturers. The automotive and pharmaceutical clusters in Bavaria and Baden-Württemberg require specialized filtration media for their production facilities.
India
Rapid urbanization and infrastructure development, particularly in healthcare and commercial real estate, are fueling filter demand. BIS standards for air quality and HVAC systems are gradually tightening, influencing product specifications. Major metropolitan areas like Delhi-NCR and Mumbai are experiencing significant growth in commercial spaces requiring enhanced air purification.
Nonwoven Air Conditioning Filter Market Key Industry Players
Specialized material science innovators and established HVAC component providers split the market for nonwoven air conditioning filters. The industry exhibits a tiered structure, with a few large integrated players alongside numerous niche specialists focusing on specific end-use applications. These archetypes compete through continuous portfolio diversification into higher-efficiency media and strategic partnerships for technology co-development. Capacity expansion in emerging markets also represents a key competitive move among leading manufacturers.
Among global industrial conglomerates, 3M Company and Freudenberg Group represent distinct approaches within the market. The Minnesota-based 3M Company, with its diversified portfolio, anchors a strong brand presence in the consumer-facing pleated filter segment, emphasizing accessibility and broad distribution. Meanwhile, the German-headquartered Freudenberg Group occupies a position as a material science innovator, leveraging its expertise to offer specialized media for diverse industrial environments, including cleanrooms. Donaldson Company, a US-based entity, further exemplifies specialization in high-performance filtration for heavy-duty industrial and automotive applications, targeting demanding operational conditions and robust performance requirements.
| Leading Market Players |
|---|
| 3M Company |
| Freudenberg Group |
| Donaldson Company |
| MANN+HUMMEL |
| Parker Hannifin Corporation |
| Camfil AB |
| Ahlstrom |
| Toray Industries |
| Hollingsworth & Vose |
| Others |
Cost & Logistics Intelligence
Underutilization in certain regional nonwoven media production facilities drives competitive pricing pressures, influencing supplier investment decisions and market entry strategies. This capacity overhang shapes manufacturer margins, especially in commodity-grade filter segments.
Pricing Analysis
After-sales filter replacements for residential systems represent a significant recurring revenue stream, often structured through subscription-based e-commerce models. Price differentiation stems from filtration efficiency ratings, such as MERV 13 versus HEPA, and brand recognition in consumer-facing segments like 3M Company. Pricing softness reflects raw material volatility for polypropylene, compressing manufacturer margins for basic panel filters. Commercial buyers prioritize performance and regulatory compliance, while residential consumers exhibit higher price sensitivity for initial filter purchase.
Supply Chain Analysis
Trade tensions impacting specialized filtration media components could disrupt supply flows for advanced nonwoven filters, particularly those requiring unique polymer formulations. Geographic supply concentrates in China and Germany, reflecting their respective strengths in polymer production and advanced manufacturing. The industry draws from petroleum-derived polymers like polypropylene and polyester as primary inputs. Commodity price volatility for these raw materials represents a structural risk for manufacturers. Distribution runs through a fragmented network of HVAC service channels and increasingly direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nonwoven air conditioning filter market is at a platform-economics inflection, driven by the emergence of smart building management systems that demand sensor-integrated filter interoperability. This ecosystem shift creates new value capture opportunities beyond traditional passive media sales.
For Market Incumbents:
Build a regulatory compliance moat by investing in advanced material science for higher-efficiency media, addressing the threat from lower-cost disposable alternatives. Integrate sensor technology into filter frames, leveraging R&D to provide predictive maintenance data for commercial HVAC systems. This approach counters margin pressure from raw material volatility and strengthens customer retention through value-added services. Consolidate market share in key commercial segments through strategic acquisitions of regional distributors.
For New Entrants and Emerging Players:
Mid-market commercial buildings in rapidly urbanizing regions like India represent a penetrable entry point for nonwoven filter solutions, especially those aligning with evolving BIS standards. Focus on subscription-based direct-to-consumer models for residential filter replacements in North America and Europe, capitalizing on convenience. Offer antimicrobial filter media for public transportation and healthcare facilities as a value-added go-to-market angle. Target niche industrial applications requiring specialized filtration for specific contaminants.
For Investors and Strategic Acquirers:
Capital is best deployed toward specialized material science innovators and digitally integrated filter manufacturers with strong intellectual property in functional media. The market's long-term viability is secured by persistent global health concerns and tightening air quality regulations, ensuring sustained demand for high-efficiency filtration. Target acquisition archetypes include companies developing recyclable filter materials or sensor-integrated smart filter technologies. Watch for accelerated adoption of ISO 16890 certification as a key inflection indicator for product differentiation.
| Strategic Initiative | Industry Significance |
|---|---|
| Material Science Investment | Developing advanced polymer blends improves filtration efficiency and addresses end-of-life sustainability challenges for polypropylene filters. |
| Direct-to-Consumer Channel Expansion | Establishing subscription models bypasses traditional HVAC contractors, capturing recurring revenue from residential consumers in North America. |
| Sensor Integration R&D | Embedding particulate sensors into filters enables predictive maintenance for commercial building management systems, optimizing replacement cycles. |
| Global Certification Alignment | Achieving ISO 16890 and ePM1 certifications unlocks procurement opportunities in health-focused public buildings and schools. |
| Antimicrobial Media Development | Incorporating antiviral agents into nonwoven fibers creates value-added products for healthcare facilities and public transportation. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, industry association reports, and trade publications to ensure data validity. The analysis incorporated insights from interviews with HVAC system engineers, material science R&D directors, procurement managers, and residential channel partners. This approach employed both bottom-up market sizing and top-down validation to construct a robust market overview.
The forecast inputs considered historical market performance, technological advancements in filtration media, and evolving regulatory landscapes across the analysis window. Segmentation dimensions modeled include product type, application, filtration efficiency, material, and regional adoption patterns. Compound annual growth rates were derived from a multi-factor regression model incorporating macroeconomic indicators and specific construction project pipelines. The model integrated new health-focused building codes and raw material price projections.
Practitioners should monitor significant shifts in global trade policies and polymer manufacturing capacity for early signals impacting market dynamics. Forecasts reflect assumptions about technology adoption rates and regulatory enforcement. Material shifts in major construction project timelines or health-focused building codes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Air Filtration Media Market
Filters
Hydraulic Filters Market
Filters
Aerospace Filter Market
Filters
Ceramic Filters Market
Filters
Color Filter Glass Market
Filters
Europe Activated Carbon Market
Filters
Europe Industrial Air Filtration Market
Filters
Filter Media Market
Filters
Intake Filter Media Market
Filters
Respirator Cartridges and Filters Market
Filters
ePTFE Filter Film Market
Filters
High Purity Chemical Filters Market
Filters
Global Liquid Filtration Market
Filters
Furnace Filters Market
Filters
Single-Use Filtration Assemblies Market
Filters
Activated Carbon Filter Market