
 Global Ethylene Vinyl Acetate Resins Market | 2026-2036
Global Ethylene Vinyl Acetate Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ethylene Vinyl Acetate Resins Market Intelligence
A transition from single-source to multi-source procurement for specialized grades is repositioning buyer-supplier dynamics in the ethylene vinyl acetate resins market. Large-scale producers like Dow Inc. leverage their extensive global manufacturing footprint to serve high-volume segments. In contrast, Arkema SA differentiates through its focus on high-performance resins for demanding applications. Sinopec Corporation anchors its market presence through deep integration with downstream industries across the Asia-Pacific region, ensuring a stable offtake for its production.
Ethylene vinyl acetate resins are copolymers produced from the polymerization of ethylene and vinyl acetate monomers. The vinyl acetate (VA) content, which can range from under 4% to over 40%, is the critical determinant of the material's properties, including flexibility, adhesion, and clarity. Applications like packaging films and foam materials typically utilize low to medium vinyl acetate content grades. High and ultra-high VA content resins command premium pricing and are essential for performance-driven uses such as solar panel encapsulation and specialty hot-melt adhesives.
Product safety and environmental regulations create a complex compliance landscape for market participants. The US Food and Drug Administration (FDA) governs the use of EVA resins in food-contact applications like packaging films. In Europe, the European Chemicals Agency (ECHA) oversees substance registration under the REACH framework. Similarly, China's GB standards impose strict requirements on materials used in consumer goods. Navigating these varied international standards is critical for securing global market access and maintaining brand reputation.
Market Dynamics
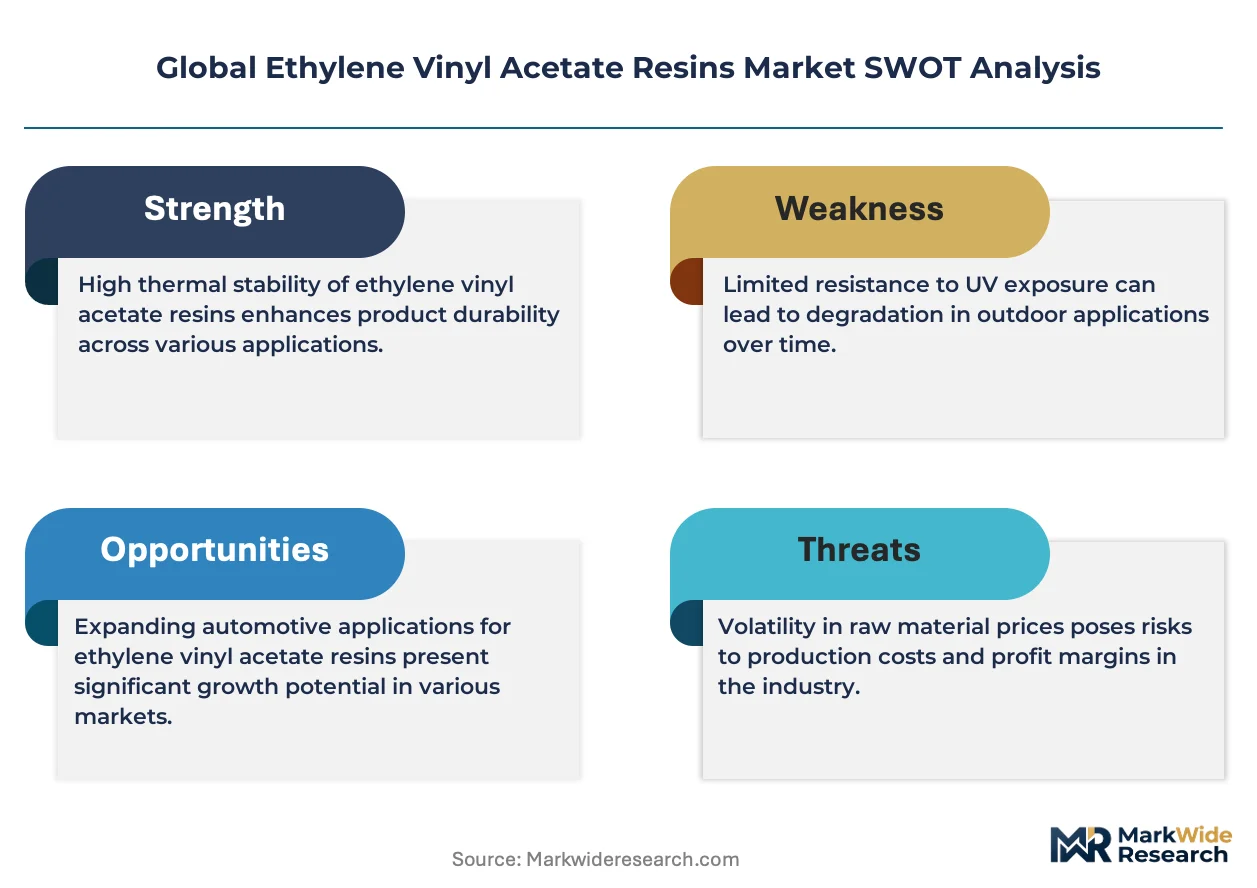
The ethylene vinyl acetate resins market is defined by a structural bifurcation between high-volume, commodity-grade materials and premium-priced, high-performance specialty grades. This division is driven by demand from the solar energy sector for high vinyl acetate content resins, creating distinct pricing tiers and technology requirements.
Growth Catalysts
- Renewable Energy Mandates:Government policies promoting solar energy, such as incentives in the United States and national targets in India, directly stimulate demand for EVA resins as the primary encapsulant material for photovoltaic modules.
- Footwear and Foam Production:The expansion of footwear and consumer goods manufacturing in Southeast Asian countries, particularly Vietnam and Indonesia, provides a consistent volume outlet for low-to-medium VA content grades used in foam midsoles and padding.
- Adhesive Formulation Advances:The development of higher-performance hot-melt adhesives for packaging, bookbinding, and woodworking applications requires EVA resins with specific melt flow indices and adhesion properties, creating demand for specialized grades.
Market Restraints
- Feedstock Price Volatility:The market is exposed to price fluctuations in ethylene and vinyl acetate monomer (VAM), both of which are derived from petrochemical feedstocks and are subject to crude oil price instability and supply disruptions.
- Substitution by Alternative Polymers:In performance-critical applications like photovoltaic encapsulation and flexible films, EVA resins face substitution threats from materials like polyolefin elastomers (POEs), which can offer superior durability and thermal stability.
- Complex Food-Contact Compliance:Navigating disparate food-contact regulations, such as the FDA framework in the US and European Food Safety Authority (EFSA) rules in the EU, adds cost and complexity for producers of packaging-grade resins.
Strategic Opportunities
- Biomedical and Pharmaceutical Applications:There is an emerging opportunity for high-purity, biocompatible EVA grades in medical applications, including drug delivery systems and flexible tubing, which command significant price premiums over industrial grades.
- Bio-Based Feedstock Development:The creation of bio-based EVA resins from renewable sources like sugarcane-derived ethanol presents an opportunity to meet corporate sustainability goals and appeal to environmentally conscious customers in consumer goods and packaging.
- Wire and Cable Insulation:The demand for halogen-free flame-retardant (HFFR) cable compounds, particularly for infrastructure projects in Europe and North America, opens a niche for specialized EVA grades as a base polymer.
Industry Challenges
- Navigating Global Chemical Regulations:Manufacturers face a significant operational burden in ensuring compliance with multiple chemical control laws, including the EU's REACH registration and China's stringent GB standards for consumer products.
- High Capital Investment:Expanding production capacity for EVA resins, especially for high-pressure polymerization processes required for high-VA grades, involves substantial capital expenditure and long lead times for plant construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ethylene Vinyl Acetate Resins Market |
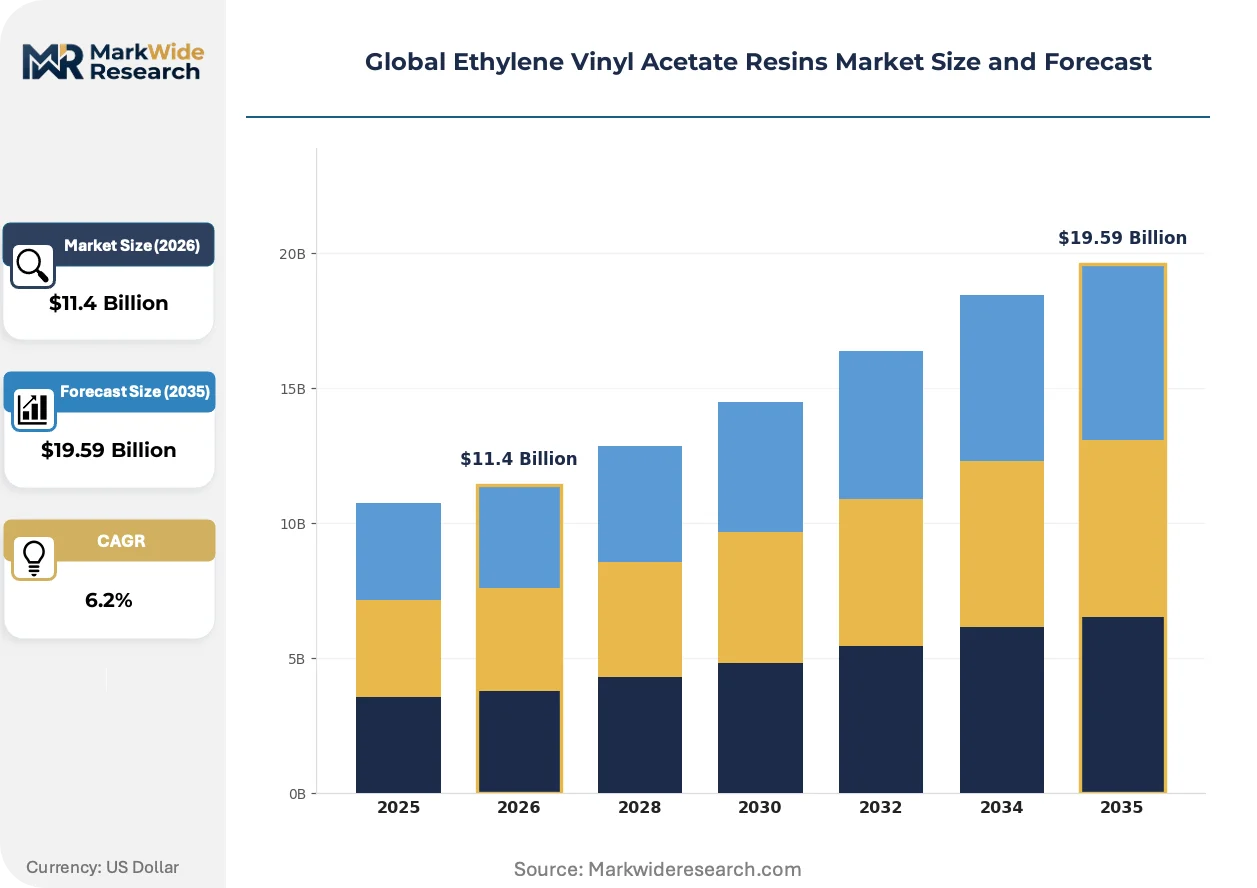
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $19.59 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Vinyl Acetate Content, Medium Vinyl Acetate Content, High Vinyl Acetate Content, Ultra-High Vinyl Acetate Content Form: Granules, Powder, Emulsions, Films, Sheets Application: Packaging Films, Footwear Materials, Adhesives, Solar Panels, Wire & Cable Insulation End User: Consumer Goods Manufacturers, Construction Suppliers, Electronics Producers, Footwear Assemblers, Renewable Energy Firms |
| Companies Covered | ExxonMobil Corporation, Dow Inc., Arkema SA, Celanese Corporation, DuPont, LyondellBasell Industries, Sinopec Corporation, Hanwha Total Petrochemical, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ethylene Vinyl Acetate Resins Market Strategic Shifts & Innovations
Performance differentiation and sustainability are the core themes shaping product development in the ethylene vinyl acetate resins market. Innovations focus on enhancing material properties for demanding applications while addressing regulatory pressures and consumer preferences for environmentally responsible materials.
Metallocene-catalyzed EVA resins represent a significant product evolution, offering superior clarity, toughness, and sealing performance compared to conventionally produced grades. Packaging film extruders and specialty adhesive formulators are the primary adopters of these advanced materials. This technology is converging with polyolefin chemistry, enabling the creation of novel copolymers that bridge the performance gap between standard EVA and other high-performance elastomers.
The European Union's Circular Economy Action Plan is a key regulatory driver influencing material design. This framework incentivizes the development of monomaterial packaging solutions and products that are easier to recycle. The flexible packaging segment is most affected, spurring investment in new EVA grades and tie-layer resins that improve the recyclability of multilayer film structures without compromising barrier performance.
A notable behavioral shift is occurring as converters and end-users diversify their supply base for critical resin grades. This move away from single-source dependencies aims to mitigate supply chain risks for specialized materials, such as those used in solar panels and medical devices. The trend is most visible among large manufacturers in China and South Korea who are qualifying secondary and tertiary suppliers to build resilience.
Global Ethylene Vinyl Acetate Resins Market Segmentation
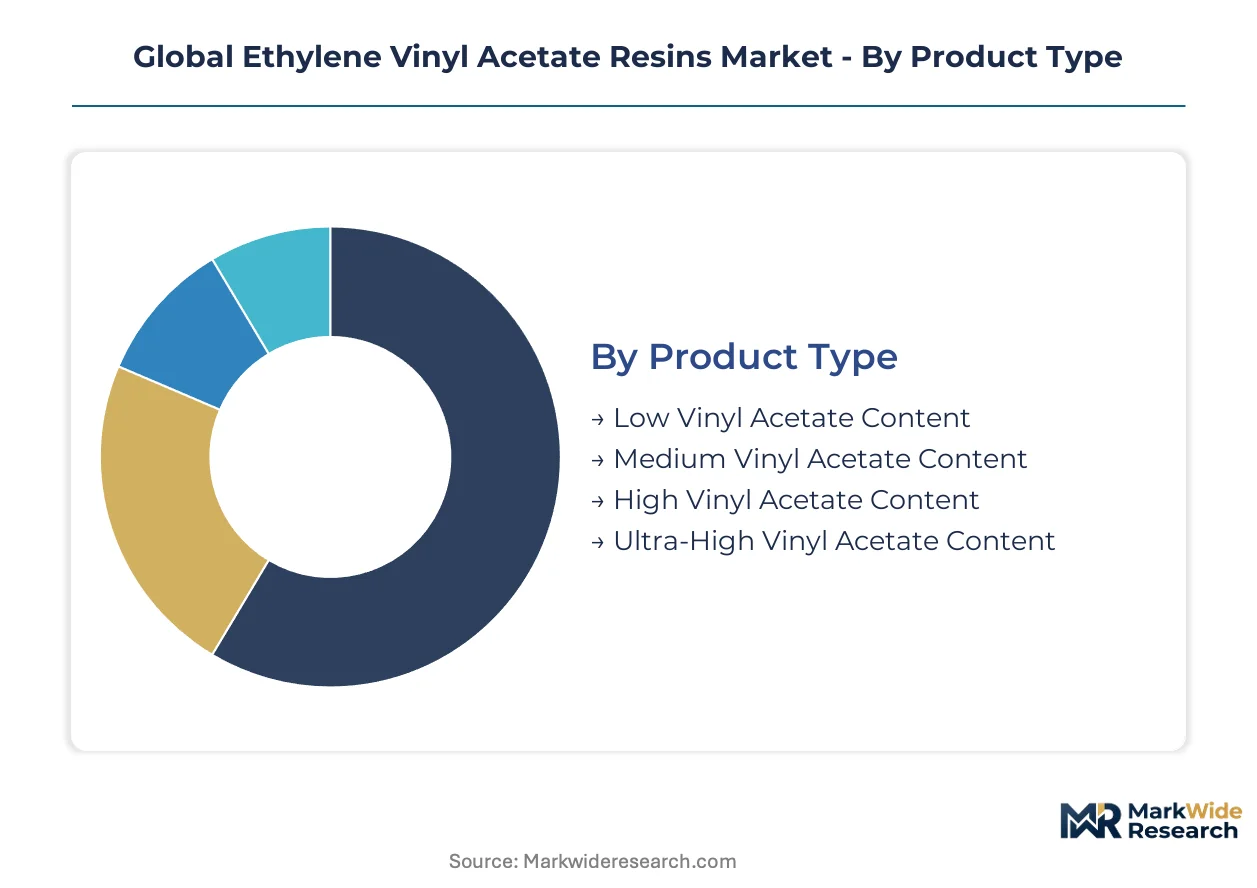
The ethylene vinyl acetate resins market is segmented to reflect the diverse material properties and application requirements across various end-use sectors. Understanding these segments helps differentiate between commodity volumes and specialized, performance-driven grades. The market's structural bifurcation between high-volume materials and premium-priced, high-performance specialty grades directly influences this segmentation.
Product Type:
The market for ethylene vinyl acetate resins is sharply divided by the vinyl acetate content, which determines material flexibility and adhesion characteristics.
- Low Vinyl Acetate Content:These resins contain less than 4% vinyl acetate, providing stiffness and good mechanical properties suitable for general-purpose applications. They are often used in film and sheet extrusion where rigidity is preferred.
- Medium Vinyl Acetate Content:Resins in this category typically contain 4% to 20% vinyl acetate, offering a balance of flexibility, toughness, and adhesion. Footwear materials and some packaging films widely utilize these grades.
- High Vinyl Acetate Content:With vinyl acetate content ranging from 20% to 40%, these resins exhibit enhanced flexibility, clarity, and strong adhesive properties. Demand concentrates in specialty applications like hot-melt adhesives for packaging and bookbinding, particularly in Europe.
- Ultra-High Vinyl Acetate Content:These grades feature over 40% vinyl acetate, delivering superior adhesion, elasticity, and optical clarity. The solar energy sector drives significant demand for these resins, which are essential for photovoltaic panel encapsulation in markets like Germany and the United States.
Mature deployment sits with Low Vinyl Acetate Content. Newer deployment is concentrated in Ultra-High Vinyl Acetate Content.
Form:
Ethylene vinyl acetate resins are available in various physical forms to suit different processing methods and end-use requirements.
- Granules:This is the most common and versatile form, widely used for extrusion, injection molding, and compounding processes. Granular EVA is a primary raw material for packaging films and footwear components across Asia-Pacific.
- Powder:Powdered EVA resins are often utilized in specialized adhesive formulations, coatings, and masterbatches due to their fine particle size. This form facilitates uniform dispersion in complex mixtures.
- Emulsions:EVA emulsions are aqueous dispersions used extensively in water-based adhesives, paints, and textile finishes, offering environmentally friendly formulation options. Construction suppliers in China increasingly adopt these for various building applications.
- Films:Pre-fabricated EVA films serve as encapsulants in solar panels and as flexible packaging materials, providing specific barrier and adhesive properties.
- Sheets:EVA sheets are employed in foam products, protective padding, and specialized industrial gaskets, valued for their cushioning and impact resistance.
Granules dominate current consumption, while Emulsions are gaining traction for specialized uses.
Application:
The diverse properties of EVA resins allow their use across a broad spectrum of industrial and consumer applications.
- Packaging Films:EVA resins impart flexibility, puncture resistance, and good sealing properties to various packaging films, including stretch and shrink films. Consumer goods manufacturers globally rely on these films for product protection.
- Footwear Materials:EVA foam is a staple in footwear midsoles, insoles, and outsoles, providing lightweight cushioning and shock absorption. Footwear assemblers in Vietnam and Indonesia are major consumers.
- Adhesives:Hot-melt adhesives formulated with EVA resins offer strong bonding for packaging, woodworking, and product assembly. The demand for specialized grades with specific melt flow indices is expanding.
- Solar Panels:High-performance EVA films encapsulate photovoltaic cells, protecting them from environmental degradation and ensuring long-term module efficiency. Government incentives for renewable energy in India directly stimulate this application.
- Wire & Cable Insulation:EVA resins provide flexibility, flame retardancy, and electrical insulation for power and telecommunications cables. Infrastructure projects in North America utilize these specialized compounds.
Packaging films represent a large volume base. Solar panel encapsulation offers the steepest expansion trajectory.
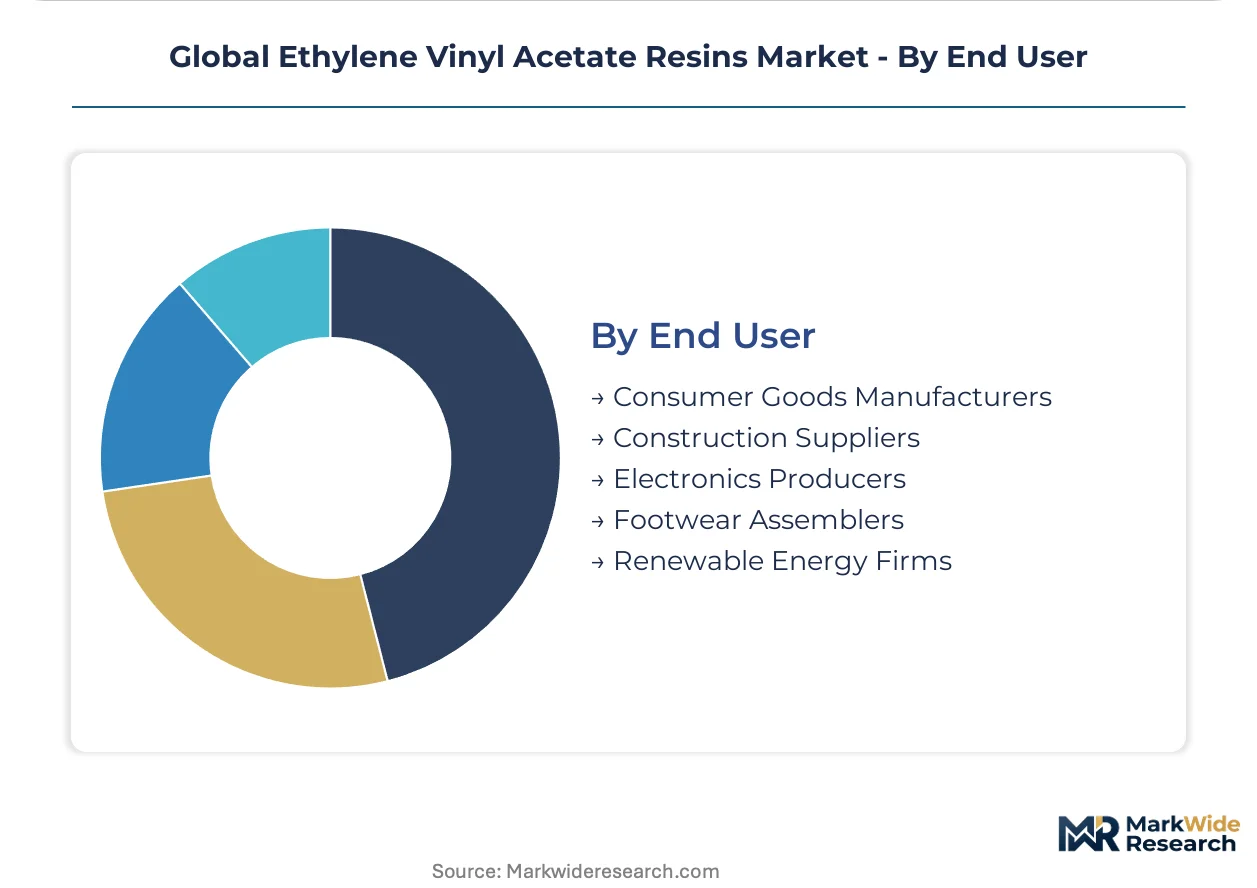
End User:
Different industries leverage EVA resins for their specific product manufacturing and operational needs.
- Consumer Goods Manufacturers:This segment utilizes EVA in toys, sporting goods, and various household items due to its flexibility, durability, and processing ease.
- Construction Suppliers:EVA resins find application in sealants, adhesives for flooring, and insulation materials within the construction sector.
- Electronics Producers:EVA is used in electronics for shock absorption, sealing, and as a component in some encapsulants.
- Footwear Assemblers:These manufacturers are significant consumers of EVA for shoe components, particularly in the athletic and casual footwear categories. Footwear production hubs in Southeast Asia drive substantial demand.
- Renewable Energy Firms:Companies involved in solar energy production heavily rely on EVA for encapsulating photovoltaic cells, ensuring the longevity and performance of solar modules. This segment represents a high-value market for specialized EVA grades.
Footwear assemblers constitute a mature end-user segment. Renewable energy firms are a rapidly expanding consumer base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability in the Middle East and Asia-Pacific shapes the global ethylene vinyl acetate resins market. Demand for EVA resins diversifies across applications, from solar panels to footwear. Compliance with varied international standards remains critical for market participants.
China
China's vast manufacturing base for footwear and electronics drives significant demand for EVA resins. The country's GB standards impose strict requirements on materials used in consumer goods. Manufacturing hubs in the Yangtze River Delta utilize large volumes for foam materials and packaging films. This ensures stable offtake for local producers.
United States
Incentives for renewable energy in the United States directly stimulate demand for high VA content EVA resins. The US Food and Drug Administration (FDA) governs the use of EVA resins in food-contact applications, influencing packaging film formulations. Solar panel manufacturers in California increasingly rely on these specialized encapsulants. Infrastructure projects across the Midwest also use EVA for cable insulation.
Germany
Germany's strong focus on renewable energy and high-performance materials boosts demand for ultra-high VA content EVA. The European Chemicals Agency (ECHA) oversees substance registration under the REACH framework. Manufacturers in Bavaria utilize advanced EVA grades for demanding applications like solar panel encapsulation. The EU's Circular Economy Action Plan also influences packaging material design.
India
National targets for solar energy deployment in India directly stimulate demand for EVA resins in photovoltaic modules. Government policies promote solar energy adoption, creating a consistent market. Manufacturing facilities in Gujarat integrate EVA into packaging films and footwear components. This supports the country's expanding industrial base.
Vietnam
Footwear and consumer goods manufacturing in Vietnam provides a consistent volume outlet for low-to-medium VA content grades. The country's export-oriented policies support industrial expansion. Footwear assemblers in Ho Chi Minh City are major consumers of EVA for foam midsoles and padding. Packaging film producers also utilize EVA for various consumer products.
Global Ethylene Vinyl Acetate Resins Market Key Industry Players
Geographic expansion dominates the current competitive landscape in the ethylene vinyl acetate resins market. The market exhibits a tiered structure, with global chemical giants operating alongside specialized resin manufacturers. Three strategic archetypes emerge: large-scale commodity producers, high-performance specialty resin providers, and regionally integrated suppliers. Portfolio diversification into advanced grades and deep integration with downstream industries represent key competitive moves.
Large-scale commodity producers like Dow Inc. exemplify global manufacturing capabilities, serving high-volume segments across multiple geographies. Arkema SA represents the archetype of a high-performance specialist, focusing on advanced resins for demanding applications such as solar panel encapsulation. Sinopec Corporation, a Chinese state-owned enterprise, anchors its market presence through deep integration with downstream industries across the Asia-Pacific region. These players collectively shape the market dynamics through their distinct operational models, strategic priorities, and extensive product portfolios. Their diverse approaches contribute to the structural bifurcation observed in the market.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Dow Inc. |
| Arkema SA |
| Celanese Corporation |
| DuPont |
| LyondellBasell Industries |
| Sinopec Corporation |
| Hanwha Total Petrochemical |
| SABIC |
| Others |
Cost & Logistics Intelligence
A clear bifurcation between commodity and high-performance grades shapes both pricing dynamics and supply chain configurations for ethylene vinyl acetate resins. This divergence means distinct cost structures and procurement strategies are necessary for market participants.
Pricing Analysis
Service bundling for specialty EVA resins often includes technical support and regulatory guidance, unbundled for commodity grades. The dominant pricing structure is contract-based long-term offtake for high-volume users, while spot market transactions cover smaller, immediate needs. Price differentiation stems from vinyl acetate content and specific regulatory certifications, such as FDA approval for food contact applications. Pricing pressure stems from feedstock price volatility, particularly for ethylene and vinyl acetate monomer. Footwear assemblers exhibit high price sensitivity, whereas renewable energy firms show lower sensitivity for ultra-high VA content encapsulants.
Supply Chain Analysis
Reverse logistics for EVA resins primarily involve material waste management and recycling initiatives, not extensive refurbishment programs. Geographic supply concentration for EVA resins centers in China, the Middle East, and Southeast Asia. The market draws from petrochemical feedstocks like ethylene and vinyl acetate monomer (VAM). Feedstock price volatility represents a structural supply chain risk for all producers. Distribution runs through a dual model: direct sales channels to large-scale manufacturers and a network of regional distributors serving smaller, specialized buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ethylene vinyl acetate resins market is experiencing a vertical-integration race, with players pursuing upstream control over key petrochemical feedstocks to secure supply stability.
For Market Incumbents:Extend production capacity for high-performance EVA grades in strategic regions like Asia-Pacific to meet solar energy demand. Invest in R&D for metallocene-catalyzed EVA resins to offer superior material properties, countering substitution threats from polyolefin elastomers. Secure long-term feedstock contracts to mitigate price volatility risks. Pursue advanced certifications like REACH compliance across expanded product portfolios to maintain market access.
For New Entrants and Emerging Players:The EU's Circular Economy Action Plan in Europe opens a window for bio-based EVA resin development, targeting environmentally conscious packaging solutions. Focus on high-purity, biocompatible EVA grades for emerging biomedical applications, leveraging unmet demand for specialized materials. Partner with specialized formulators to penetrate niche markets requiring tailored adhesive or encapsulant solutions. Target underpenetrated regional markets for wire and cable insulation with halogen-free flame-retardant compounds.
For Investors and Strategic Acquirers:Re-rating potential sits with mid-sized specialty resin producers given their innovation in high-VA and bio-based solutions. The long-term viability of the EVA market is robust, driven by persistent demand from renewable energy and specialized industrial sectors over the next decade. Identify acquisition targets with strong intellectual property in advanced material formulations or unique feedstock access. Practitioners should monitor increased M&A activity for advanced material startups for early signals of market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for High-VA Grades | Increases supply of critical material for solar panel encapsulation in key markets. |
| Backward Integration into VAM Production | Secures raw material supply and mitigates feedstock price volatility for manufacturers. |
| Green Manufacturing Transition | Addresses regulatory pressures and consumer preferences for sustainable products in Europe. |
| Long-term Supply Agreements with Converters | Ensures stable offtake for EVA resin producers, particularly in the packaging segment. |
| Joint Ventures in Bio-Based EVA Development | Accelerates innovation in renewable materials, appealing to environmentally conscious end-users. |
Research Approach
Industry reports from plastics associations, company annual reports, and government energy policy documents formed the secondary backbone for this analysis. This initial data was cross-referenced with primary interviews involving petrochemical procurement managers, EVA resin R&D directors, packaging film extruders, and solar panel manufacturers. The approach combined bottom-up data aggregation from granular market segments with top-down validation against macroeconomic indicators.
A bottom-up analytical lens was applied to project market volumes and values across the analysis window. The model segmented the market by vinyl acetate content, physical form, application, end-user, and regional production hub. Compound annual growth rates were derived from historical trends, demand projections from key end-use sectors, and anticipated technological shifts. Key forecast inputs included renewable energy installation rates and footwear production volumes in Southeast Asia.
The model assumes a particular technology adoption path; alternative pathways for polyolefin elastomers would alter the outlook. Forecasts reflect assumptions regarding feedstock availability and regulatory stability in major markets. Practitioners should monitor crude oil price fluctuations and new chemical regulations for early signals of market shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global UV Curable Resins and Formulated Products Market
Polymers & Resins
Polylysine Market
Polymers & Resins
Plastic Calendering Resins Market
Polymers & Resins
Global Hydroxypropyl Cellulose Market
Polymers & Resins
Silicone Resins Market
Polymers & Resins
Global One Component Polyurethane Foam Market
Polymers & Resins
Global Impregnating Resins Market
Polymers & Resins
North America Polyamide Market
Polymers & Resins
Low Density Polyethylene Market
Polymers & Resins
Europe Polypropylene Market
Polymers & Resins
Asia-Pacific Fluoropolymer Market
Polymers & Resins
Southeast Asia Modified Polypropylene Market
Polymers & Resins
Global PEEK Market
Polymers & Resins
North America Polycarbonate (PC) Market
Polymers & Resins
Gel Polymer Electrolytes Market
Polymers & Resins
Middle East Polymer Market