
 Color Filter Glass Market | 2026-2036
Color Filter Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Color Filter Glass Market Intelligence
Specialty optics distribution is tilting toward direct OEM partnerships and consolidated photonics distributors. Schott AG leverages its vertically integrated melting and finishing operations to sustain premium positioning in fluorescence-grade filter substrates. Hoya Corporation anchors Asian supply through proprietary ion-exchange strengthening and precision coating lines in Japan. Kopp Glass differentiates via deep specialization in custom color formulations for theatrical and architectural lighting, occupying a defensible niche against volume competitors.
Color filter glass is a selectively absorbing or transmitting optical material manufactured with dissolved metal oxides, rare-earth elements, or interference coatings to achieve precise spectral cutoff wavelengths, typically specified between 280 nm and 2500 nm for ultraviolet through infrared applications. Its primary industrial purpose is to isolate specific wavelength bands in imaging sensors, laser systems, and analytical instruments while suppressing stray light and thermal drift. Optical glass and coated glass variants capture the dominant margin pools, as multilayer dielectric coatings on borosilicate substrates command price premiums for narrowband biomedical and semiconductor inspection applications. Specialty glass formulations incorporating fused silica are gaining fastest in ultraviolet lithography and spaceborne sensors where thermal expansion coefficients below 0.55 ppm/K are mandatory.
EMA medical device regulations and FDA 21 CFR Part 820 quality system requirements shape product certification pathways for filter glass integrated into diagnostic imaging and surgical navigation systems. REACH substance restrictions and RoHS hazardous material limits are forcing reformulation of traditional colorants toward cerium, neodymium, and other compliant dopant systems. ISO 10110 surface quality specifications govern acceptance criteria for scratch-dig tolerances in high-performance assemblies. Stakeholders must monitor evolving spectral performance requirements from next-generation CMOS sensor architectures and quantum dot display backlights to align R&D roadmaps with downstream specification shifts.
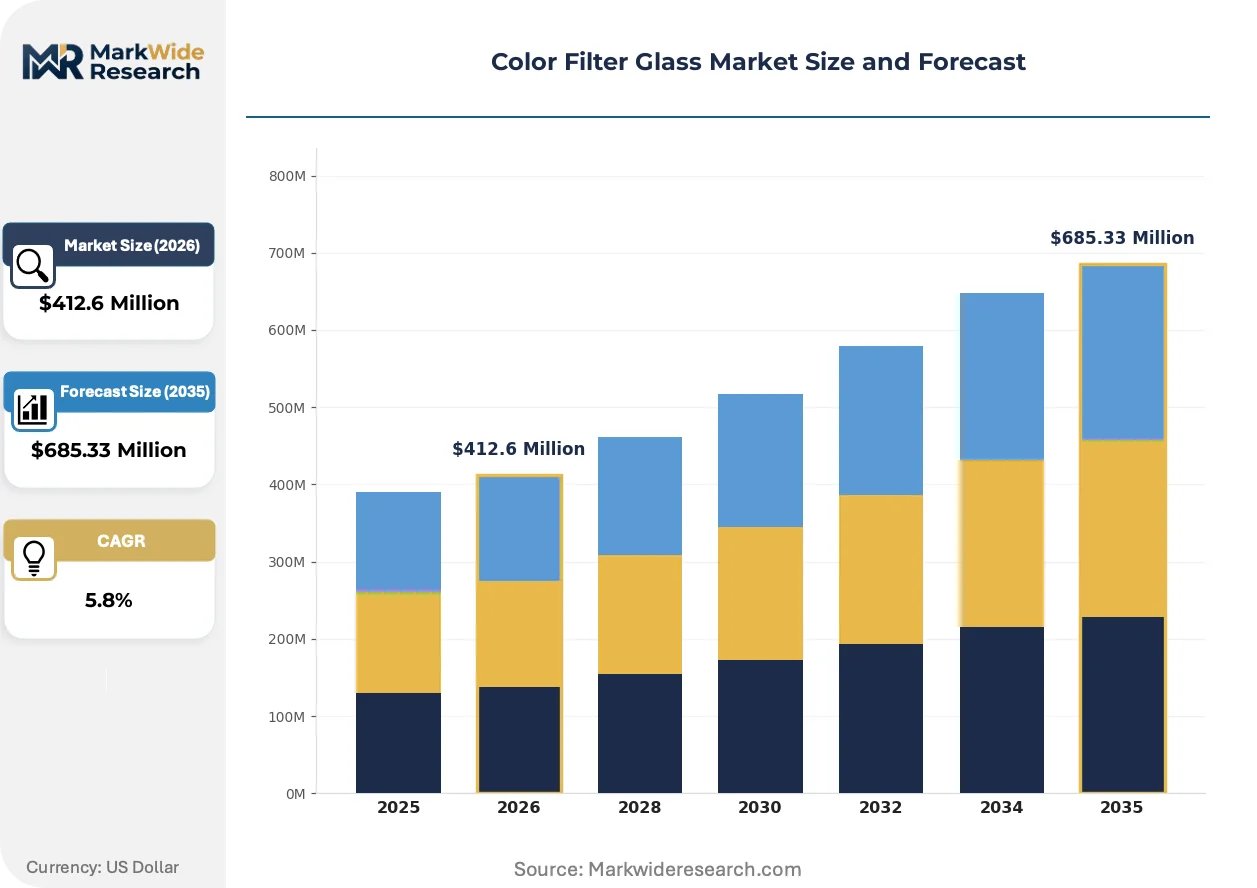
Market Dynamics
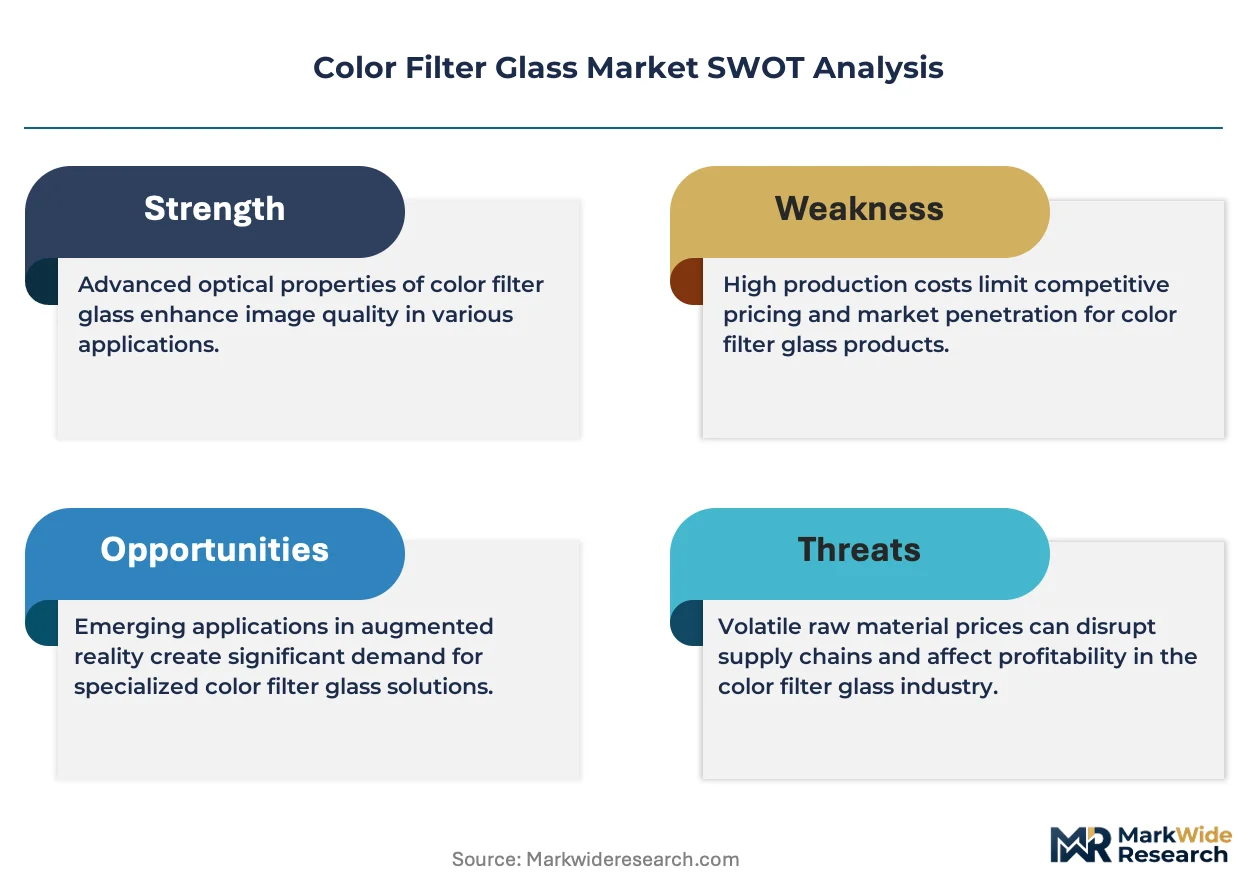
REACH substance restrictions on cadmium-based colorants are forcing wholesale reformulation of traditional color filter glass dopant systems, compressing established supply chains while opening margin pools for rare-earth specialists with certified alternative chemistries.
Growth Catalysts
- EMA MDR certification pathways:Diagnostic imaging OEMs in Germany and Switzerland now mandate fluorescence-grade filter substrates meeting ISO 10110 surface quality specifications, pulling volume through certified channels.
- Osaka Prefecture precision optics cluster:Ion-exchange strengthened borosilicate substrates from Japanese suppliers anchor CMOS sensor assembly lines for semiconductor inspection equipment.
- Quantum dot display backlight architectures:Narrowband spectral requirements from next-generation display manufacturers are displacing broadband filter specifications in volume procurement.
Market Restraints
- Rare-earth oxide supply volatility:Neodymium and cerium price swings constrain margin predictability for reformulated colorant systems.
- Schott AG melting capacity concentration:Premium fluorescence-grade substrate supply concentrates in Bavaria, creating single-source vulnerability for biomedical instrument OEMs.
- Fused silica thermal expansion floors:Coefficients below 0.55 ppm/K remain technically unachievable in conventional borosilicate matrices, limiting ultraviolet lithography penetration.
Strategic Opportunities
- Spaceborne sensor qualification:Thermal expansion specifications for orbital imaging platforms remain underpenetrated by commercial glass suppliers.
- Direct OEM partnership channels:Consolidated photonics distributors in Rochester, New York are ceding procurement relationships to substrate-to-system vertical relationships.
- EU Green Deal sustainable chemistry mandates:REACH-compliant rare-earth dopant systems attract preferential sourcing status from ESG-committed buyers.
Industry Challenges
- ISO 10110 scratch-dig certification timelines:Surface quality validation for high-performance assemblies extends qualification cycles by 8-14 months.
- Fluorescence microscopy system integration:Legacy tungsten-halogen illumination architectures resist retrofit with LED-optimized narrowband filter stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Color Filter Glass Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Glass, Clear Glass, Coated Glass, Specialty Glass Application: Consumer Electronics, Automotive Lighting, Medical Devices, Photography Material: Borosilicate, Soda-lime, Quartz, Fused Silica End User: Manufacturers, Retailers, Distributors, Laboratories |
| Companies Covered | Schott AG, Hoya Corporation, Newport Corporation, Kopp Glass, Thorlabs, Andover Corporation, Sydor Optics, Isuzu Glass Ltd., Optima Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Color Filter Glass Market Strategic Shifts & Innovations
Spectral precision requirements from biomedical imaging and semiconductor metrology are compressing filter specification tolerances while digitizing quality assurance protocols across substrate finishing operations.
Interferometric surface metrology is digitizing acceptance testing for scratch-dig tolerances and flatness specifications. Optical instrument manufacturers in Germany now require digital certificate chains traceable to ISO 10110-7 inspection protocols. This compression of quality documentation is displacing manual visual inspection labor and enabling real-time supplier scorecarding.
REACH Annex XVII cadmium restrictions are forcing pigment system migrations across European coating operations. ECHA enforcement timelines are compressing reformulation windows to 18-24 months for legacy product lines. Biomedical filter applications face the steepest compliance gradients given FDA 21 CFR Part 820 overlap with EMA MDR quality system requirements.
Consolidated photonics distributors are losing procurement influence to direct substrate-to-OEM relationships. Rochester, New York precision optics clusters now bypass distribution layers for fluorescence-grade borosilicate substrates. Channel disintermediation concentrates volume with vertically integrated melters capable of certificate-of-analysis customization.
Color Filter Glass Market Segmentation
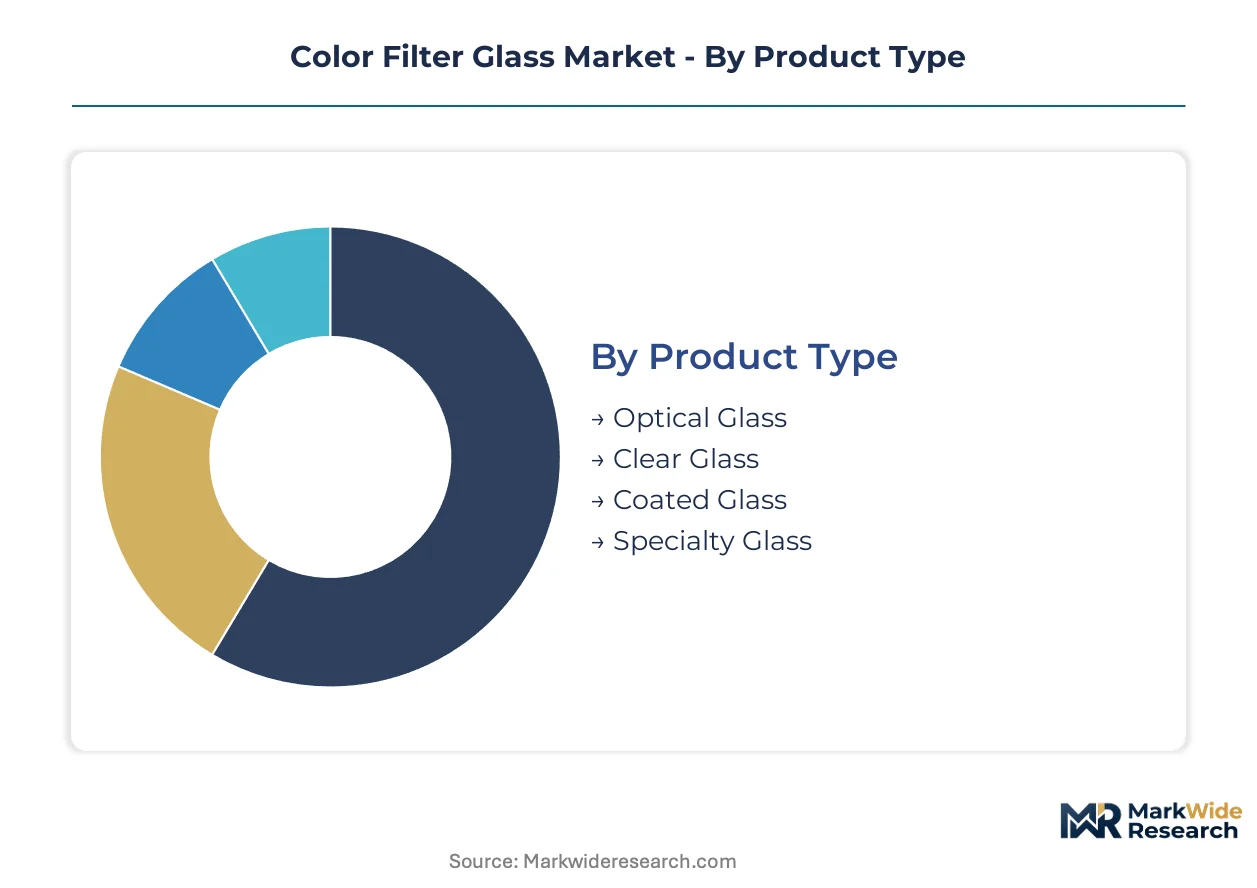
Color filter glass procurement patterns diverge sharply across product grades and end-use specifications. Application-driven spectral requirements and material thermal constraints dictate supplier selection and pricing architecture across each segment boundary.
Product Type:
Precision imaging systems span ultraviolet lithography to infrared sensing, demanding substrate formulations matched to wavelength transmission and thermal stability requirements.
- Optical Glass:Dissolved metal oxide dopants in borosilicate matrices achieve selective spectral absorption between 280 nm and 2500 nm. Diagnostic imaging OEMs in Germany and Switzerland now mandate fluorescence-grade substrates meeting ISO 10110 surface quality specifications, pulling volume through certified channels.
- Coated Glass:Multilayer dielectric coatings on precision substrates command price premiums for narrowband biomedical and semiconductor inspection applications. Osaka Prefecture precision optics clusters anchor CMOS sensor assembly lines with ion-exchange strengthened variants.
- Clear Glass:Unpigmented borosilicate or soda-lime substrates serve as coating foundations and protective windows in general illumination systems.
- Specialty Glass:Custom rare-earth formulations address REACH-compliant alternatives to cadmium-based colorants for theatrical and architectural lighting.
The dominant share belongs to Optical Glass, while Coated Glass is closing the gap fastest.
Application:
End-use specifications compress tolerance windows and digitize quality documentation across substrate finishing operations.
- Consumer Electronics:Quantum dot display backlight architectures demand narrowband spectral precision, displacing broadband filter specifications in volume procurement from Asian display manufacturers.
- Medical Devices:EMA MDR certification pathways and FDA 21 CFR Part 820 quality system requirements shape product qualification for diagnostic imaging and surgical navigation integration.
- Automotive Lighting:LED-optimized filter stacks replace legacy tungsten-halogen illumination architectures in forward lighting and cabin ambient systems.
- Photography:Professional imaging equipment maintains demand for precision-cut filter substrates with interferometric surface metrology documentation.
Medical Devices commands the largest revenue pool, though Consumer Electronics is expanding most quickly.
Material:
Thermal expansion coefficients and chemical durability determine substrate suitability for extreme environments and precision optics.
- Fused Silica:Thermal expansion below 0.55 ppm/K enables ultraviolet lithography and spaceborne sensor applications where conventional matrices fail. Orbital imaging platforms remain underpenetrated by commercial suppliers.
- Borosilicate:Ion-exchange strengthening and precision coating compatibility anchor volume production for fluorescence microscopy and CMOS sensor assemblies.
- Quartz:Crystalline silicon dioxide substrates serve high-temperature and corrosive environment applications outside standard glass matrices.
- Soda-lime:Cost-effective compositions support general lighting and consumer-grade optical applications with less stringent thermal specifications.
Borosilicate holds the dominant position, while Fused Silica is gaining share fastest.
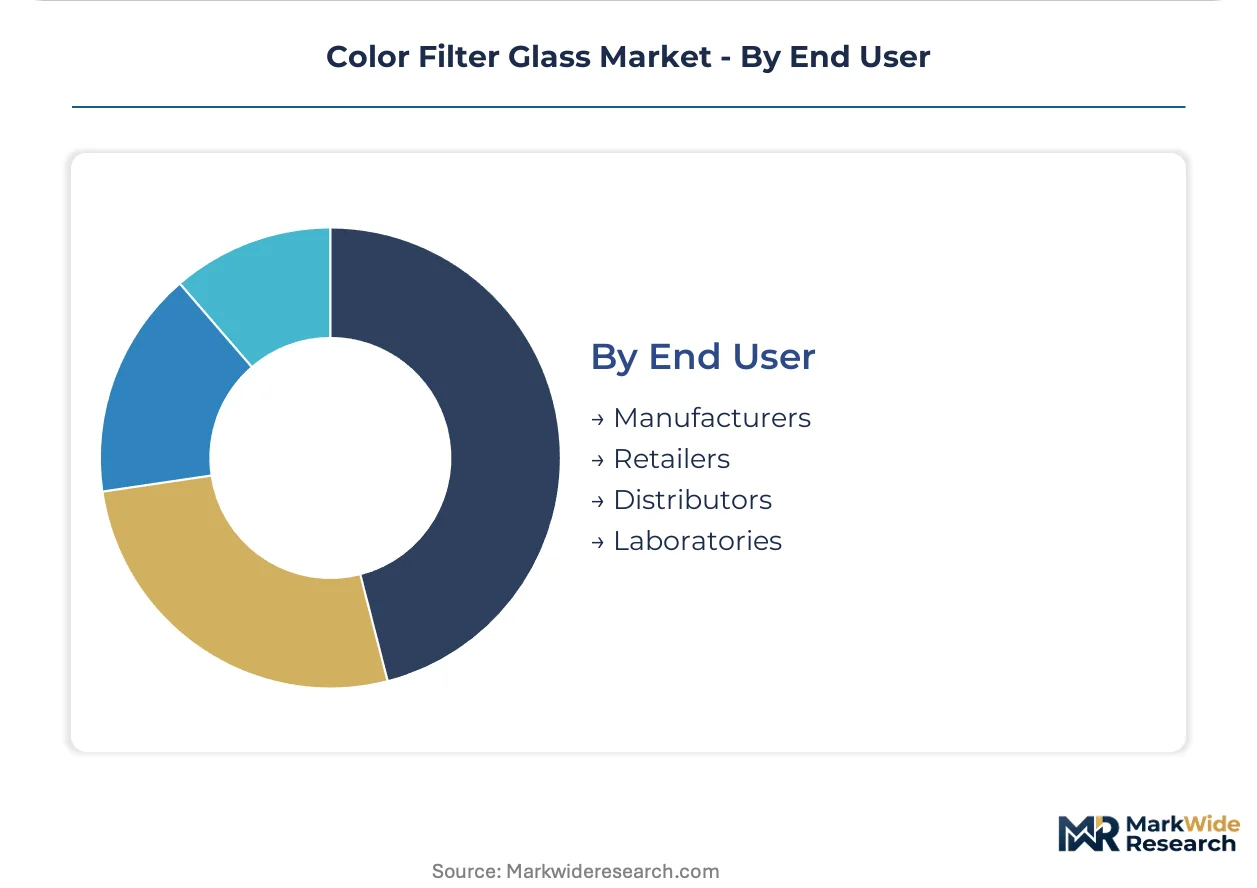
End User:
Procurement channel structure is shifting from consolidated distribution toward direct substrate-to-system relationships.
- Manufacturers:Optical instrument OEMs in Germany and Japan are expanding direct procurement of coated filter substrates, bypassing distributor layers for certificate-of-analysis customization.
- Laboratories:Research and quality control facilities demand small-batch precision with digital certificate chains traceable to ISO 10110-7 inspection protocols.
- Distributors:Rochester, New York precision optics clusters and consolidated photonics distributors are ceding procurement influence to vertical relationships.
- Retailers:General photography and lighting accessory channels serve hobbyist and replacement markets with standard grade products.
Manufacturers represent the largest procurement volume, while Laboratories is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA certification requirements for diagnostic imaging systems pull procurement through German and Swiss channels. REACH substance restrictions on cadmium-based colorants are accelerating rare-earth dopant migrations across European coating operations. Production concentrates in precision optics clusters spanning Bavaria, Osaka Prefecture, and Rochester, New York.
Germany
Fluorescence microscopy OEMs in Bavaria now mandate ISO 10110 surface quality specifications for filter substrates. EMA MDR certification pathways compress supplier qualification timelines for biomedical instrument integration. The Mainz-based precision optics cluster anchors melting and finishing operations for premium fluorescence-grade materials.
Japan
CMOS sensor manufacturers in Osaka Prefecture drive ion-exchange strengthened borosilicate substrate volumes for semiconductor inspection equipment. METI industrial standards govern optical material certification for export-oriented precision instruments. The Kansai region hosts proprietary coating lines serving Asian display and imaging sensor assembly operations.
United States
FDA 21 CFR Part 820 quality system requirements shape filter glass integration into surgical navigation and diagnostic imaging platforms. Rochester, New York precision optics clusters bypass distributor layers for direct substrate procurement from vertically integrated melters. The FDA-EMA regulatory overlap creates dual-certification premiums for biomedical-grade materials.
Switzerland
Swissmedic medical device regulations align with EMA MDR pathways for diagnostic imaging component qualification. REACH-compliant rare-earth dopant systems attract preferential sourcing from ESG-committed instrument OEMs. The Jura Arc watchmaking and precision engineering corridor extends optical component finishing capabilities into medical device supply chains.
China
NMPA medical device registration requirements are tightening fluorescence filter substrate documentation for imported diagnostic platforms. MIIT industrial policies support domestic precision optics capabilities through standards harmonization with ISO protocols. The Yangtze River Delta display manufacturing corridor generates narrowband filter demand from quantum dot backlight architectures.
Color Filter Glass Market Key Industry Players
Vertically integrated melters and specialized coating houses split the market into distinct capability tiers. Premium fluorescence-grade substrate supply concentrates among German and Japanese operators with captive melting capacity. Three archetypes dominate: full-process melter-finishers, coating-specialized fabricators, and rare-earth dopant formulators. Capacity expansion in certified rare-earth alternatives and direct OEM partnership structures represent the dominant competitive vectors reshaping procurement relationships.
Among German-based melter-finishers, Schott AG exemplifies the vertically integrated archetype with captive supply from raw material through certified finishing. Hoya Corporation anchors the Japanese precision coating tier through proprietary substrate strengthening and multilayer deposition capabilities. Kopp Glass occupies a position within the specialized formulation segment, representing custom colorant expertise for non-biomedical illumination applications.
| Leading Market Players |
|---|
| Schott AG |
| Hoya Corporation |
| Newport Corporation |
| Kopp Glass |
| Thorlabs |
| Andover Corporation |
| Sydor Optics |
| Isuzu Glass Ltd. |
| Optima Inc. |
| Others |
Cost & Logistics Intelligence
Rare-earth oxide supply volatility compresses margin predictability across all pricing tiers while forcing buyers toward long-term offtake structures or premium spot premiums. This input-cost uncertainty stratifies the market into three distinct procurement modes: configured-to-order fluorescence-grade substrates commanding substantial customization premiums, certified standard grades for volume biomedical applications, and economy-grade architectural lighting materials competing on unit cost.
Pricing Analysis
Configured-to-order pricing for ISO 10110-certified fluorescence-grade substrates commands substantial premiums over standard catalog specifications. Price differentiation hinges on surface quality certification tier and customization depth, with EMA MDR-compliant documentation adding further cost layers. Pricing pressure stems from rare-earth dopant cost volatility, particularly neodymium and cerium oxide swings. Diagnostic imaging OEMs in Germany and Switzerland show lowest price sensitivity due to regulatory compliance requirements, while theatrical lighting buyers in North America resist premium tiers.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard for qualified buyers of volume borosilicate substrates. Geographic supply concentrates in Germany, Japan, and the United States, with melting operations anchored in Bavaria and Osaka Prefecture. Raw material dependencies include rare-earth oxides, high-purity silica sand, and specialty metal oxide dopants. Single-source vulnerability around Schott AG's fluorescence-grade capacity creates structural risk for biomedical instrument OEMs. Distribution runs through direct substrate-to-system relationships, bypassing consolidated photonics distributors in Rochester, New York.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among diagnostic imaging OEMs in Germany and Japan has shifted negotiating leverage toward buyers capable of certificate-of-analysis customization at volume scale.
For Market Incumbents: Pre-empt rare-earth supply chain disruptions by securing backward integration into certified cerium and neodymium oxide sources or binding long-term offtake agreements with Australian and Canadian mining operations. Defend fluorescence-grade positioning through captive ion-exchange strengthening capacity expansion in Bavaria or Osaka Prefecture, as emerging Chinese suppliers threaten standard-grade segments with cost-competitive borosilicate alternatives. For New Entrants and Emerging Players: Spaceborne sensor qualification represents the most penetrable white-space target, as thermal expansion specifications below 0.55 ppm/K remain underserved by commercial fused silica suppliers. Target theatrical and architectural lighting segments with REACH-compliant rare-earth formulations, where Kopp Glass's specialization leaves room for price-competitive alternatives. Pursue direct OEM partnership structures rather than distributor channels to capture certificate-customization premiums. For Investors and Strategic Acquirers: REACH Annex XVII cadmium restriction enforcement timelines reshape the acquisition landscape toward rare-earth dopant formulators with certified alternative chemistries. Long-term viability favors vertically integrated melter-finishers with captive raw material access and ISO 10110-certified finishing operations. Monitor ECHA enforcement acceleration and FDA-EMA regulatory harmonization progress as inflection indicators for premium-grade demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Oxide Supply | Captive neodymium and cerium sourcing insulates margin predictability from commodity volatility. |
| ISO 10110-7 Digital Certificate Chain Deployment | Interferometric surface metrology documentation displaces manual inspection labor across German OEM qualification protocols. |
| Direct OEM Partnership Channel Development | Vertically integrated melters capture procurement relationships ceded by Rochester, New York distributors. |
| REACH-Compliant Dopant System R&D Investment | Cerium and neodymium formulations replace cadmium-based colorants ahead of ECHA enforcement deadlines. |
| Spaceborne Sensor Qualification Program | Fused silica thermal expansion below 0.55 ppm/K addresses underpenetrated orbital imaging platform specifications. |
Research Approach
The analysis maps optical glass, coated glass, specialty glass, and clear glass sub-sectors, each validated through melting operations managers, precision optics procurement leads at biomedical instrument OEMs, fluorescence microscopy system integrators, and rare-earth oxide supply specialists. Primary interview findings triangulate against secondary sources including ECHA REACH substance restriction filings, FDA 21 CFR Part 820 quality system documentation, ISO 10110 surface quality standards, and customs trade data for borosilicate and fused silica substrate flows. Bottom-up volume estimates from individual facility capacities reconcile with top-down demand projections from CMOS sensor and quantum dot display manufacturing forecasts.
Assumption sets held regulatory enforcement timelines and rare-earth oxide price volatility bands fixed while varying biomedical imaging equipment installation rates and semiconductor inspection capital expenditure cycles across the projection horizon. The analytical framework models product type, application, material composition, and end-user channel segmentation dimensions. CAGRs derive from compound growth trajectory analysis applied to certified substrate volume flows and premium coating operation throughput. Forecast inputs include fluorescence microscopy OEM procurement patterns and quantum dot display backlight architecture adoption curves.
Practitioners should monitor ECHA enforcement acceleration, FDA-EMA regulatory harmonization progress, and rare-earth oxide supply disruption events for early signals requiring forecast reassessment. The analysis reflects assumptions about continued REACH compliance migration and sustained precision optics cluster concentration in Bavaria, Osaka Prefecture, and Rochester, New York. Macroeconomic contraction in biomedical capital equipment, regulatory timeline delays, or breakthrough synthetic rare-earth alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Air Filtration Media Market
Filters
Diatomaceous Filter Aid Market
Filters
Activated Carbon Market
Filters
High-Efficiency Particulate Air (HEPA) Filters Market
Filters
Global Depth Filtration Market
Filters
Liquid Filter Bags Market
Filters
Global Gas Filtration Media Market
Filters
String Wound Filter Materials Market
Filters
United States Activated Carbon Market
Filters
Global Liquid Filtration Market
Filters
Global Filter Press Market
Filters
Fabric Filter System Market
Filters
Coolant Filtration Systems Market
Filters
Hydraulic Filters Market
Filters
Nonwoven Air Conditioning Filter Market
Filters
Global High Temperature Filters Market