
 US Assisted Living Facility Market | 2026-2036
US Assisted Living Facility Market Size, Share, and Industry Trends Forecast 2026-2036
US Assisted Living Facility Market Intelligence
CMS reimbursement recalibration is consolidating capital deployment toward Medicare-certified wings and skilled nursing co-locations. Brookdale Senior Living leverages its national footprint to sustain occupancy premiums across hybrid-financed properties. Atria Senior Living anchors development pipelines in high-migration corridors with purpose-built memory care infrastructure. Five Star Senior Living differentiates through operational density in New England markets where regulatory compliance costs deter new entrants.
Assisted living facilities provide residential housing with personalized support services for older adults requiring assistance with activities of daily living, typically offering 24-hour supervision, medication management, and coordinated health monitoring in non-institutional settings. Memory care segments command the highest per-unit revenue premiums due to specialized staffing ratios and secured-environment construction standards. Private-pay service models dominate margin capture, while Medicaid-funded capacity faces structural compression from state budget variability and reimbursement lag. Skilled nursing co-locations within integrated campuses represent the fastest-growing facility type as operators pursue acuity-escalation strategies.
CMS, state Medicaid agencies, and OSHA shape facility licensure, staffing mandates, and workplace safety protocols that directly determine operating cost structures and market access eligibility. HIPAA compliance requirements govern electronic health record systems and inter-provider data exchange, creating technology investment thresholds that favor scaled operators over independent facilities. Stakeholders must monitor state-level certificate-of-need reform movements and Medicaid waiver expansion decisions that will determine competitive positioning across the next decade.
Market Dynamics
CMS reimbursement recalibration is compressing private-pay margins while simultaneously redirecting capital toward Medicare-certified skilled nursing co-locations, forcing operators to rebalance acuity mix across their portfolios.
Growth Catalysts
- Medicaid Waiver Expansion:State-level 1915(c) HCBS waivers are extending community-based long-term care eligibility to higher-acuity residents previously excluded from assisted living reimbursement.
- Sun Belt Retiree Migration:Florida, Arizona, and Texas are absorbing disproportionate inbound senior population flows, concentrating demand in markets with lower per-unit development costs.
- Memory Care Premium Capture:Purpose-built dementia units command elevated per-bed revenue through specialized staffing ratios and secured-environment construction standards that justify rate premiums.
Market Restraints
- Labor Cost Escalation:Certified nursing assistant wages are rising faster than reimbursement rate adjustments in Medicaid-dependent states, compressing operating margins.
- Certificate-of-Need Freeze:CON moratoria in New York, Illinois, and Kentucky block new market entry regardless of demonstrated demand, entrenching incumbent operators.
- Interest Rate Sensitivity:Floating-rate construction debt exposure leaves development pipelines vulnerable to Federal Reserve policy tightening and refinancing risk.
Strategic Opportunities
- Technology-Enabled Remote Monitoring:Integration of passive sensor arrays and predictive analytics platforms is reducing nighttime staffing requirements while maintaining regulatory compliance.
- PACE Program Partnerships:Medicare-funded Program of All-Inclusive Care for the Elderly contracts offer capitated revenue streams that align operator incentives with acute care cost avoidance.
- Conversion of Obsolete Hotel Inventory:Underperforming hospitality assets in suburban corridors present adaptive reuse opportunities with expedited entitlement timelines.
Industry Challenges
- Licensed Practical Nurse Shortage:Pipeline constraints for LPN certification programs are extending time-to-fill for critical medication administration positions.
- EHR Interoperability Fragmentation:HIPAA-compliant data exchange between assisted living platforms and hospital systems requires costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Assisted Living Facility Market |
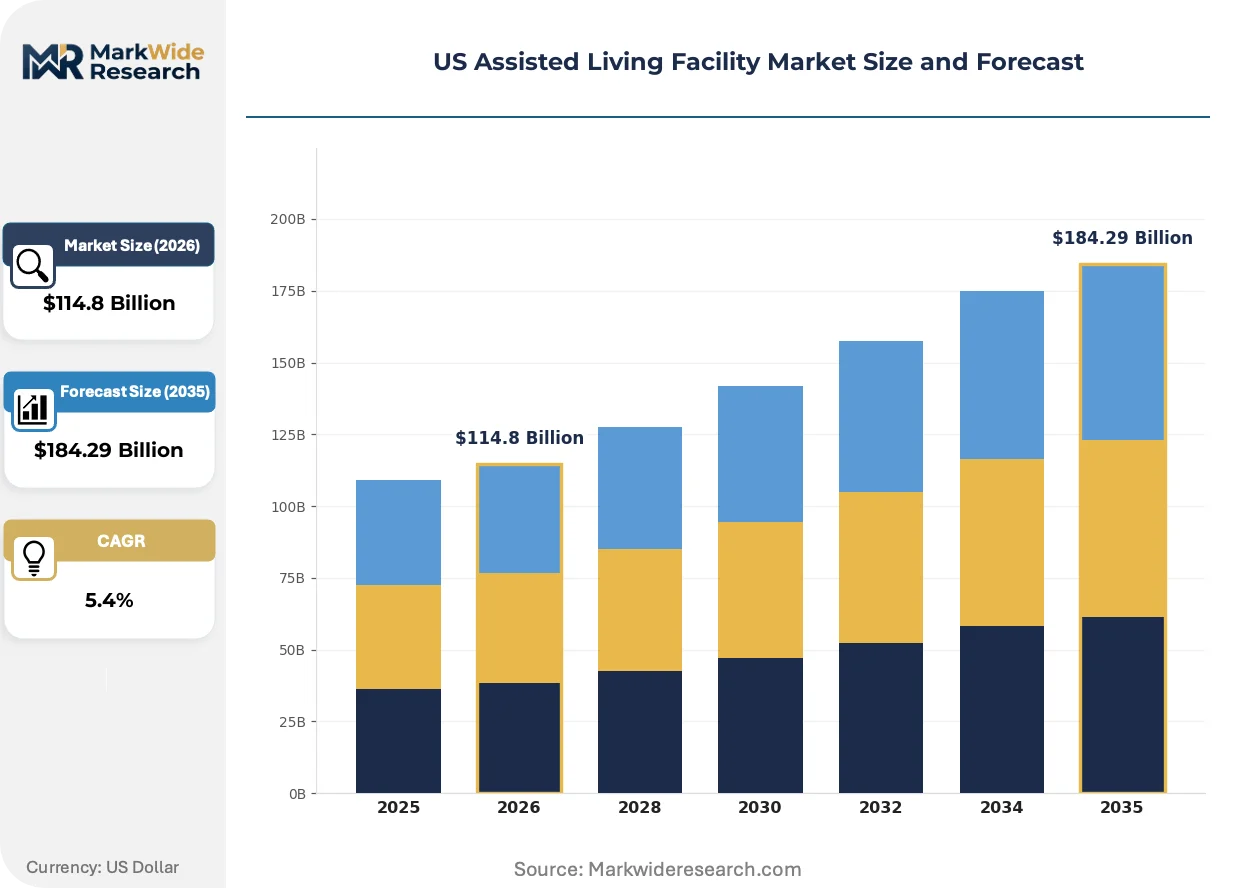
| Market Size in 2026 | $114.8 Billion |
| Market Size in 2035 | $184.29 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Facility Type: Independent Living, Memory Care, Respite Care, Skilled Nursing Service Model: Private Pay, Medicaid Funded, Medicare Certified, Hybrid Financing Occupancy Level: Full Capacity, Partial Capacity, Transitioning, Short-Term Care Type: Assisted Living, Residential Care, Home Health, Adult Day Care |
| Companies Covered | Erickson Living, Sonida Senior Living, Brookdale Senior Living, Integral Senior Living, Pacifica Senior Living, Atria Senior Living, Senior Lifestyle Corp, Watermark Retirement Communities, Five Star Senior Living, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Assisted Living Facility Market Strategic Shifts & Innovations
Facility design and service delivery models are pivoting toward acuity-escalation capabilities as operators seek to capture residents longer into their care continuum while defending against hospital-at-home disintermediation.
Passive fall-detection sensor networks are converging with AI-powered gait analysis to enable predictive intervention before acute events trigger emergency department transfers. Large multi-state operators are deploying these systems across memory care wings first, where wandering patterns and nocturnal instability create highest liability exposure. The technology is converging with existing nurse call infrastructure to reduce false alarm fatigue while maintaining OSHA workplace safety compliance.
OSHA's updated workplace violence prevention standards for healthcare settings are mandating comprehensive safety risk assessments and incident reporting protocols that extend to assisted living environments. Facilities must now document environmental design modifications and staff training hours that previously fell outside federal enforcement scope. Memory care operators in California and Washington are absorbing the highest compliance costs due to state supplement requirements exceeding federal baselines.
Adult children are consolidating site selection authority through digital aggregator platforms that commoditize amenity comparisons and accelerate decision velocity. Traditional referral relationships with discharge planners and geriatric care managers are yielding to algorithmic matching services that weight online reputation metrics above clinical quality indicators. This channel shift is most pronounced in Texas and Florida markets where inbound relocating families lack established local provider relationships.
US Assisted Living Facility Market Segmentation
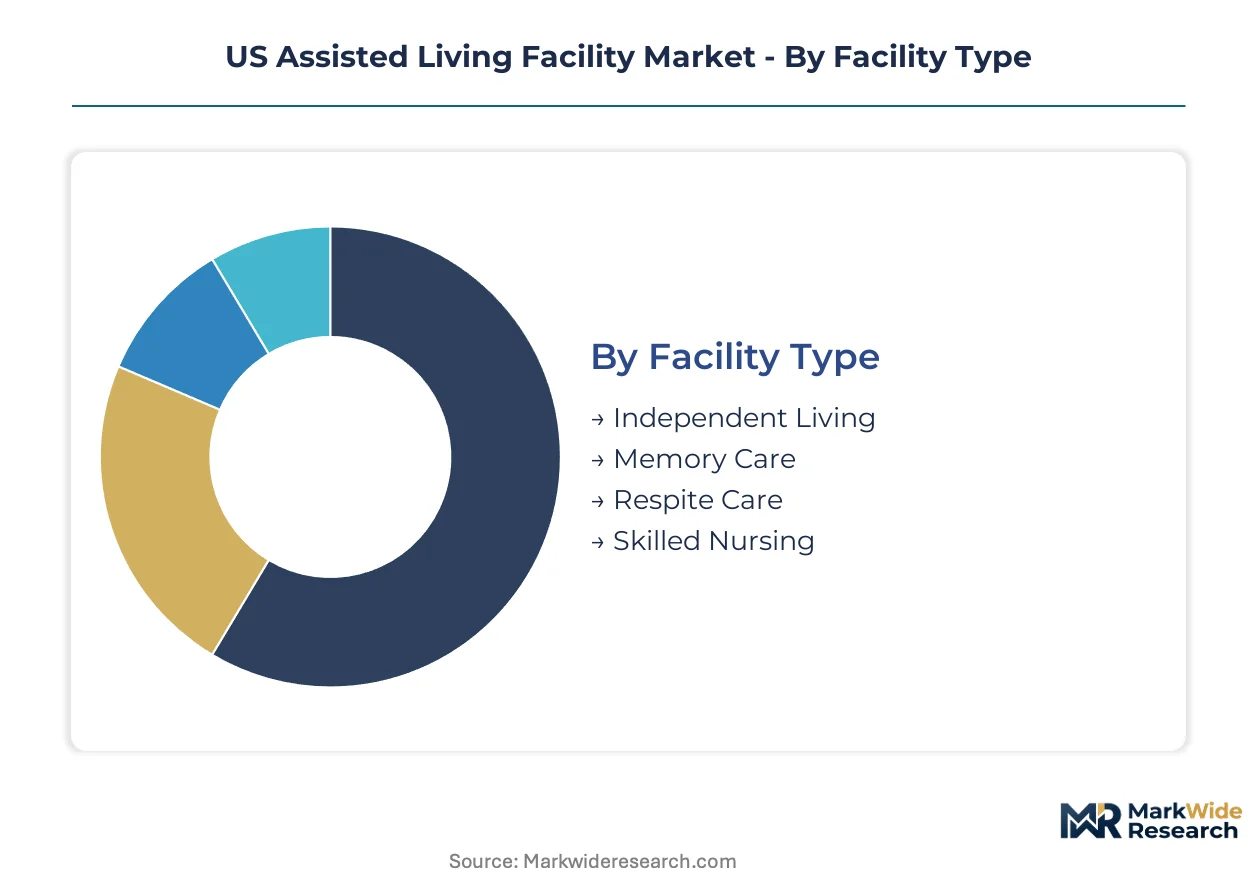
Segmentation reveals how capital deployment, reimbursement pathways, and acuity thresholds fragment the assisted living landscape. Operators configure portfolios across these dimensions to balance margin stability against regulatory exposure.
Facility Type:
Capital intensity varies sharply across facility types, with construction costs and specialized infrastructure requirements driving financing structure decisions.
- Independent Living:Lowest per-unit construction burden with standard residential finishes and minimal clinical infrastructure. Demand concentrates in Florida and Arizona master-planned communities where amenity density attracts private-pay retirees seeking lifestyle transitions without medical oversight.
- Memory Care:Purpose-built secured environments with specialized HVAC, wander-resistant layouts, and elevated staffing ratios. Texas markets absorb disproportionate new supply as operators chase reimbursement premiums for dementia-specific care.
- Respite Care:Short-stay capacity embedded within larger campuses or standalone facilities serving post-acute discharge pathways.
- Skilled Nursing:Highest capital intensity with Medicare certification requirements, clinical laboratory infrastructure, and CMS-mandated quality measurement systems.
Most installed capacity flows through Independent Living. Expansion is steepest in Memory Care.
Service Model:
Revenue predictability and payer mix concentration determine operator risk profiles and valuation multiples in transaction markets.
- Private Pay:Unrestricted rate-setting authority with monthly fees adjusted for acuity escalation. Sun Belt portfolios command occupancy premiums where inbound wealthy retirees lack established Medicaid eligibility.
- Medicaid Funded:State-determined reimbursement schedules with coverage gaps for room and board components. Kentucky and Illinois operators face structural margin compression from rate lag against wage inflation.
- Medicare Certified:Skilled nursing co-locations capturing post-acute revenue through bundled payment arrangements.
- Hybrid Financing:Blended payer structures balancing private-pay margin capture with Medicaid-funded occupancy stabilization.
Private Pay anchors revenue concentration across institutional portfolios. Hybrid Financing is expanding most quickly as operators seek payer diversification.
Occupancy Level:
Operational leverage and fixed cost absorption vary directly with census stability, shaping staffing models and marketing expenditure intensity.
- Full Capacity:Optimal fixed cost coverage with waitlist pricing power and reduced vacancy marketing spend.
- Partial Capacity:Discounting pressure and elevated sales commission structures to fill available units.
- Transitioning:Temporary census disruption from renovation, ownership change, or regulatory citation remediation.
- Short-Term:Respite and rehabilitation stays with higher per-diem rates but elevated turnover costs.
Full Capacity operations dominate mature market positions. Short-Term programming is gaining share fastest as hospitals seek discharge velocity partners.
Care Type:
Regulatory licensure boundaries and staffing ratio mandates create distinct operational economics across care categories.
- Assisted Living:State-licensed residential care with medication administration and activities-of-daily-living support. Arizona and Texas maintain lighter regulatory burdens that accelerate new entrant timelines.
- Residential Care:Board-and-care models with lower acuity thresholds and reduced clinical oversight requirements.
- Home Health:Medicare-certified skilled services delivered in private residences, competing for same patient population.
- Adult Day Care:Non-residential daytime programming capturing family caregiver respite demand.
Assisted Living contains the dominant installed base. Home Health is climbing the fastest as hospital-at-home programs expand CMS reimbursement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified nursing assistants and licensed practical nurses concentrate disproportionately in Sun Belt metros where lower living costs attract healthcare talent from higher-tax northern states.
Florida
Retiree migration from the Northeast and Midwest sustains occupancy premiums in master-planned senior communities. The state's Agency for Health Care Administration oversees assisted living licensure with lighter staffing mandates than peer jurisdictions. Tampa Bay and Orlando corridors absorb the majority of new memory care development as operators chase private-pay demographics.
Texas
Corporate relocations from California and New York bring aging parents seeking proximity to adult children. Texas Health and Human Services Commission maintains streamlined licensing pathways that compress new entrant timelines relative to CON states. Dallas-Fort Worth and Austin metroplexes lead construction starts for hybrid-financed properties blending independent living with skilled nursing co-locations.
Arizona
Seasonal resident patterns create unique census volatility requiring flexible staffing models. The Arizona Department of Health Services regulates assisted living with minimal Medicaid waiver restrictions compared to Illinois or Kentucky. Phoenix and Tucson suburbs host the densest concentration of purpose-built memory care campuses targeting dementia-specific rate premiums.
California
Higher acuity thresholds and stringent staffing ratios elevate operating costs above national medians. Cal/OSHA enforces workplace violence prevention standards exceeding federal baselines, particularly in memory care environments. Los Angeles and San Diego operators absorb compliance premiums through private-pay rate structures that filter out Medicaid-dependent residents.
Illinois
Certificate-of-need moratoria entrench incumbent operators regardless of demonstrated demand growth. The Illinois Department of Public Health maintains restrictive Medicaid reimbursement schedules that compress margins for hybrid-financed properties. Chicago suburbs concentrate the state's remaining development activity in high-income corridors where private-pay concentration offsets regulatory burden.
US Assisted Living Facility Market Key Industry Players
The competitive structure tilts toward national multi-state operators with portfolio scale sufficient to amortize compliance technology and centralized procurement. Regional specialists retain footholds in CON-protected markets where regulatory barriers deter national entry. Three archetypes dominate: integrated health system affiliates, private-equity backed rollup platforms, and family-owned regional chains. Consolidation through distressed asset acquisition and joint-venture development with REITs represent the dominant competitive vectors.
Among national-scale operators, Brookdale Senior Living, Atria Senior Living, and Five Star Senior Living exemplify the multi-state portfolio archetype. Brookdale occupies a position emphasizing geographic diversification across Sun Belt and Northeast corridors. Atria represents development-forward strategies anchored in high-migration metropolitan areas. Five Star sits within the regional density model, concentrating operational expertise in protected New England markets where regulatory complexity filters competition.
| Leading Market Players |
|---|
| Erickson Living |
| Sonida Senior Living |
| Brookdale Senior Living |
| Integral Senior Living |
| Pacifica Senior Living |
| Atria Senior Living |
| Senior Lifestyle Corp |
| Watermark Retirement Communities |
| Five Star Senior Living |
| Others |
Cost & Logistics Intelligence
Private-pay luxury tiers versus Medicaid-dependent economy segments bifurcate the assisted living landscape, with this divergence manifesting in both rate-setting authority and procurement concentration across specialized construction inputs and clinical staffing pools.
Pricing Analysis
Bundled all-inclusive monthly fees dominate private-pay operations while unbundled à la carte service menus characterize Medicaid-funded capacity. Three-tier pricing structure across premium memory care, standard assisted living, and economy residential care segments anchors market stratification. Price differentiation rests on staffing ratios and amenity density rather than geographic location alone. Cost compression in Medicaid-dependent tiers is intensifying because state reimbursement schedules lag wage inflation in certified nursing assistant markets.
Supply Chain Analysis
Regional distribution centers for medical supplies and dietary provisions operate through hub-and-spoke patterns radiating from Dallas-Fort Worth and Tampa logistics clusters. Geographic supply concentration draws from domestic manufacturers in Ohio and Pennsylvania for specialized furniture, Mexico for construction materials, and regional foodservice distributors for meal programs. Raw material dependencies include wander-resistant flooring systems, specialized HVAC filtration units, and electronic health record hardware. Single-source vulnerability in licensed practical nurse staffing pools creates operational risk. Distribution runs through group purchasing organizations serving multi-state operator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
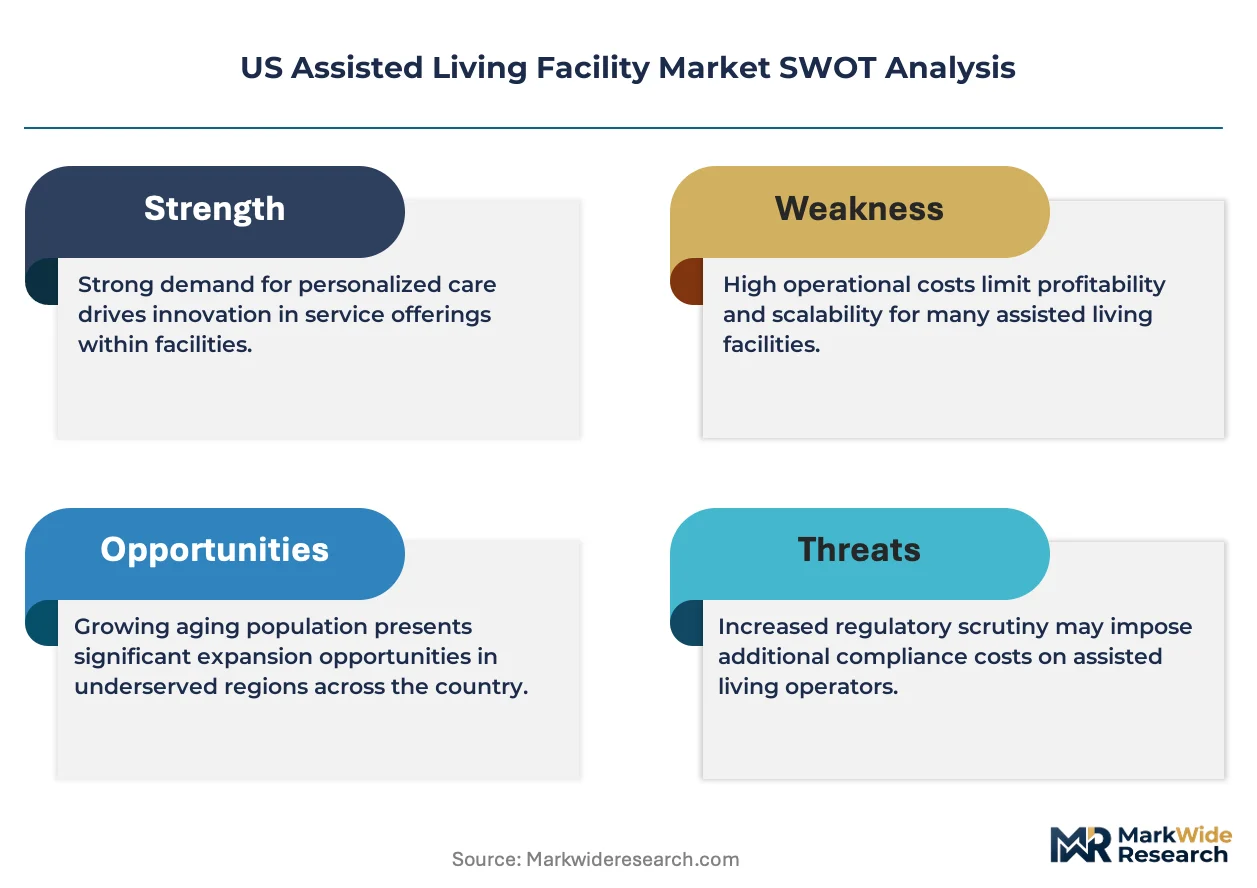
This market functions as a geographic-arbitrage play where Texas and Florida's lighter regulatory burdens and lower construction costs extract margin premiums unavailable to operators in certificate-of-need states like Illinois and New York.
For Market Incumbents: Acquire distressed independent living assets in Sun Belt corridors to densify existing footprints and capture inbound retiree migration flows. Consolidation of fragmented regional chains in CON-protected New England markets builds defensive moats against national entrants. Labor cost escalation in Medicaid-dependent states threatens margin stability; vertical integration into in-house certified nursing assistant training programs reduces time-to-fill for critical positions. For New Entrants and Emerging Players: Digital aggregator platforms for adult children represent the most penetrable channel disruption opportunity, bypassing traditional discharge planner referral relationships. Target Texas suburban corridors where corporate relocations concentrate aging parent demand without entrenched incumbent relationships. Conversion of obsolete suburban hotel inventory offers expedited entitlement timelines relative to ground-up construction in supply-constrained markets. For Investors and Strategic Acquirers: Consolidation pressure builds where floating-rate construction debt exposure meets Federal Reserve policy tightening, creating distressed acquisition opportunities in development pipelines. Long-term viability favors operators with hybrid-financed payer diversification rather than pure Medicaid concentration. Monitor state-level 1915(c) HCBS waiver expansion decisions as the critical inflection signal for community-based long-term care eligibility shifts.| Strategic Initiative | Industry Significance |
|---|---|
| PACE Program Partnership | Medicare-funded capitated contracts align operator incentives with acute care cost avoidance in California and Florida markets. |
| Memory Care Campus Development | Purpose-built dementia units command elevated per-bed revenue through specialized staffing ratios and secured-environment construction standards. |
| Technology-Enabled Remote Monitoring | Passive sensor arrays reduce nighttime staffing requirements while maintaining OSHA workplace safety compliance in Texas facilities. |
| Certificate-of-Need Market Entry | Strategic acquisitions in Illinois and Kentucky entrench incumbent positions where regulatory barriers block new supply regardless of demand. |
| Adaptive Hospitality Conversion | Underperforming suburban hotel assets offer expedited entitlement timelines for assisted living repositioning in Arizona and Florida corridors. |
Research Approach
Direct dialogue with assisted living facility operators, state Medicaid agency administrators, construction lenders specializing in healthcare real estate, and geriatric care managers anchored qualitative findings. Secondary validation drew from CMS reimbursement databases, state certificate-of-need filings, OSHA workplace safety enforcement records, and American Health Care Association industry surveys. Bottom-up facility-level capacity data and top-down demographic projection models were triangulated to establish market sizing.
Installed base estimates and revenue forecasts across the projection horizon reflect segmentation by facility type, service model, and care acuity tier. CAGRs were derived from demographic migration patterns, construction pipeline tracking, and reimbursement rate trajectory analysis. Industry-specific forecast inputs include state-level Medicaid waiver expansion schedules and Federal Reserve policy assumptions affecting construction finance availability.
State budget variability, CMS reimbursement recalibration timing, and labor market tightening in certified nursing assistant pools are the dominant revision risks that could alter trajectory assumptions. Stakeholders should weight assumptions against their own operating context and geographic exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Facilities
Qatar Senior Living Market
Healthcare Facilities
US Skilled Nursing Facility Market
Healthcare Facilities
Private Office-Based Clinics Market
Healthcare Facilities
Hospital Lighting Market
Healthcare Facilities
Global Healthcare Facilities Management Market
Healthcare Facilities
US Skilled Nursing Facility and Rehabilitation Market
Healthcare Facilities
Global Ambulatory Surgery Centers (Ascs) Market
Healthcare Facilities
US Office-Based Labs Market
Healthcare Facilities
US Ambulatory Surgery Centers Market
Healthcare Facilities
Sauna and Spa Market
Healthcare Facilities
Asia-Pacific Smart Hospital Market
Healthcare Facilities
Confinement Center Market
Healthcare Facilities
US Ambulatory Surgical Centers Market
Healthcare Facilities
Trauma Care Centers Market
Healthcare Facilities
Micro-Hospitals Market
Healthcare Facilities
US and Europe Ambulatory Surgery Centers Market