
 Confinement Center Market | 2026-2036
Confinement Center Market Size, Share, and Industry Trends Forecast 2026-2036
Confinement Center Market Insights
A capital-intensity divergence between boutique operators and hospital-affiliated chains is redrawing competitive boundaries in the confinement center landscape. Thomson Medical Group leverages its integrated hospital infrastructure to sustain premium pricing across Singapore and Malaysia. Paradise Confinement Center anchors its position through specialized postnatal culinary programs and dedicated lactation consulting. NannySOS Confinement Agency competes via flexible home-based deployment models that reduce fixed facility overhead.
Confinement centers provide structured residential or domiciliary care programs for mothers during the postpartum recovery period, typically spanning 28 to 56 days with supervised nutrition, infant handling, and maternal health monitoring. These facilities combine traditional postnatal practices with modern nursing protocols to reduce postpartum complications and support early infant development. Postnatal care and maternity support services dominate revenue generation, while infant care segments exhibit faster growth as dual-income households seek specialized newborn handling expertise. Private centers capture the deepest margin pools through premium room configurations and personalized service tiers, whereas hospital-based facilities extend reach through insurance partnerships and clinical credibility.
Singapore's Ministry of Health licensing framework and Malaysia's Private Healthcare Facilities and Services Act shape facility standards, staffing ratios, and permissible service scopes across Southeast Asian operations. Health Canada and PMRA guidelines influence ingredient sourcing for postnatal nutritional programs in North American expansion corridors. Stakeholders must monitor evolving neonatal care certification requirements and telehealth integration mandates as regulatory bodies tighten oversight of hybrid in-person and remote service delivery models.
Market Dynamics
Dual-income household penetration in Southeast Asian urban clusters is restructuring confinement center demand toward domiciliary and hybrid service models that reduce residential facility dependency. Malaysia's Ministry of Health licensing tightening and Singapore's premium pricing tolerance are bifurcating operator strategies across the strait.
Growth Catalysts
- Postnatal nutrition certification:Health Canada and PMRA guidelines for ingredient traceability are elevating program credibility among North American diaspora segments seeking standardized care abroad.
- Neonatal telehealth mandates:Hybrid in-person and remote monitoring protocols are expanding service addressable market beyond physical facility catchment zones.
- First-time mother urban concentration:Singapore's premium private center segment captures outsized margin pools from demographic clustering in high-density housing estates.
Market Restraints
- Licensed nurse supply scarcity:Malaysia's Ministry of Health staffing ratio requirements face structural shortage of neonatal-certified practitioners in secondary cities.
- Facility capex escalation:Premium room configurations with negative pressure infant handling zones require construction inputs subject to regional construction cost volatility.
- Home-based service substitution:Flexible deployment models from non-facility agencies erode residential center utilization rates in price-sensitive segments.
Strategic Opportunities
- Insurance partnership channels:Hospital-affiliated chains can extend reach through clinical credibility and reimbursement integration with private health plans.
- Lactation consulting specialization:Dedicated certification programs create service differentiation in markets where informal caregiver networks dominate infant feeding support.
- Traditional-modern protocol convergence:Integration of herbal postnatal baths with vital sign monitoring technology appeals to intergenerational household decision units.
Industry Challenges
- Neonatal care certification timelines:Staff upskilling for hybrid telehealth delivery faces lag between training completion and regulatory approval of remote monitoring scopes.
- Cross-border regulatory fragmentation:Operators expanding from Singapore into Malaysia encounter divergent facility standards under the Private Healthcare Facilities and Services Act versus city-state licensing frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Confinement Center Market |
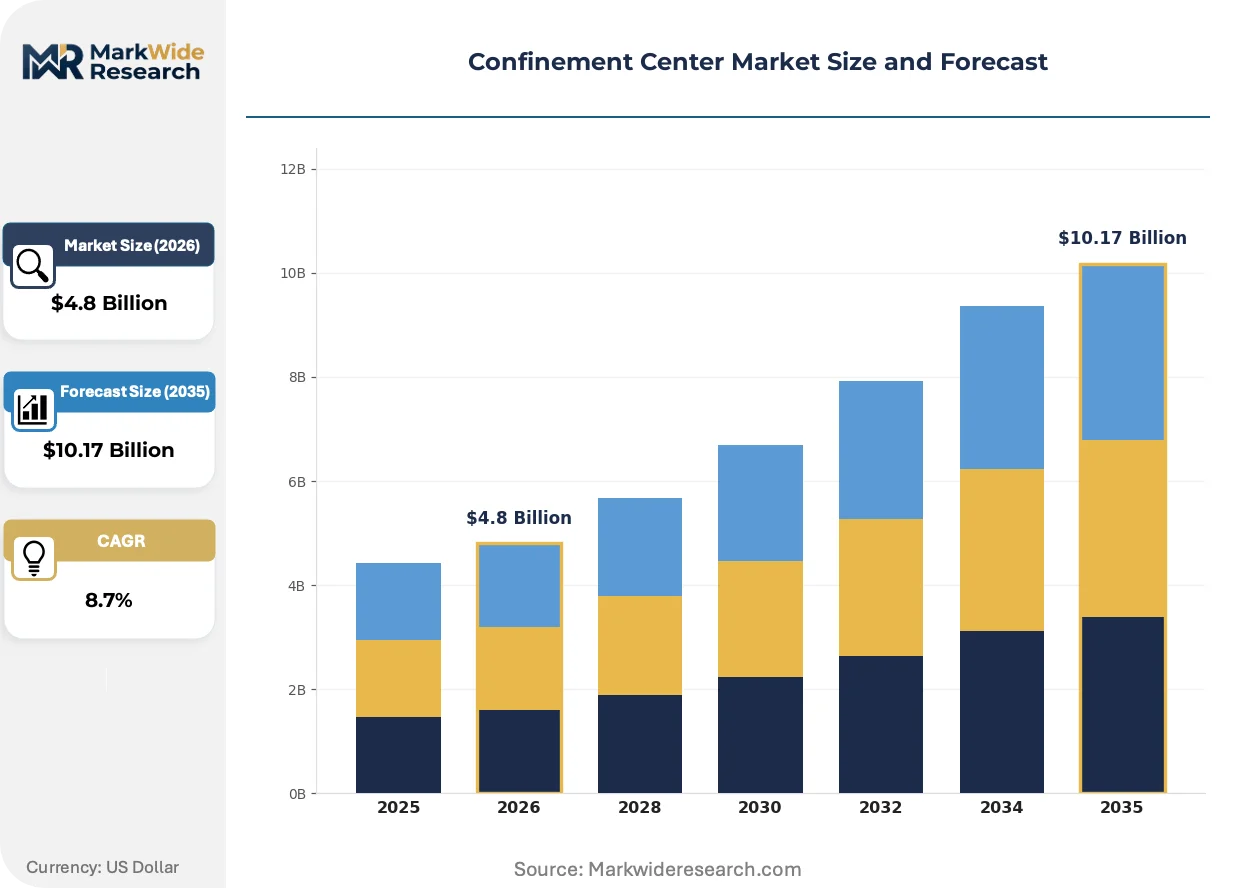
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Postnatal Care, Maternity Support, Infant Care, Family Workshops Facility Type: Private Centers, Hospitals, Community Facilities, Home-Based Care Pricing Model: Fixed Packages, Hourly Rates, Subscription Plans, Pay-Per-Visit Client Type: New Mothers, Couples, Families, Healthcare Providers |
| Companies Covered | PEM Confinement Nanny Agency, Thomson Medical Group, Paradise Confinement Center, Allure Post Natal Center, NannySOS Confinement Agency, Fernwood Confinement Center, Confinement Angels, Sweet Pea Confinement Center, Mandarin Confinement Center, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Confinement Center Market Trends and Innovations
Digital health infrastructure is penetrating postnatal care protocols, compressing the traditional 28-to-56-day residential model into modular service bundles. Regulatory bodies are mandating telehealth integration while consumer preference fragments across facility-based, home-based, and hybrid delivery modes.
Remote infant monitoring systems with FDA-cleared vital sign sensors are decomposing the historical requirement for 24-hour on-site nursing presence. Premium private centers in Singapore are adopting these platforms to maintain clinical oversight while reducing labor density. The technology is decomposing fixed facility cost structures and enabling fractional service pricing that undercuts traditional residential packages.
Malaysia's Ministry of Health is tightening licensing requirements for maternity facilities through enhanced staffing ratio mandates and equipment specification protocols. The regulatory friction is accelerating consolidation among boutique operators unable to absorb compliance costs. Hospital-affiliated chains with integrated infrastructure are capturing displaced demand from non-compliant independent centers.
Subscription-based care packages are displacing single-episode residential bookings among dual-income households seeking flexibility. Digital platforms broker on-demand lactation consulting and meal delivery without facility residency. This behavioral pivot is most visible in Singapore's premium segment where space constraints and return-to-work pressures compress traditional confinement duration expectations.
Confinement Center Market Segmentation
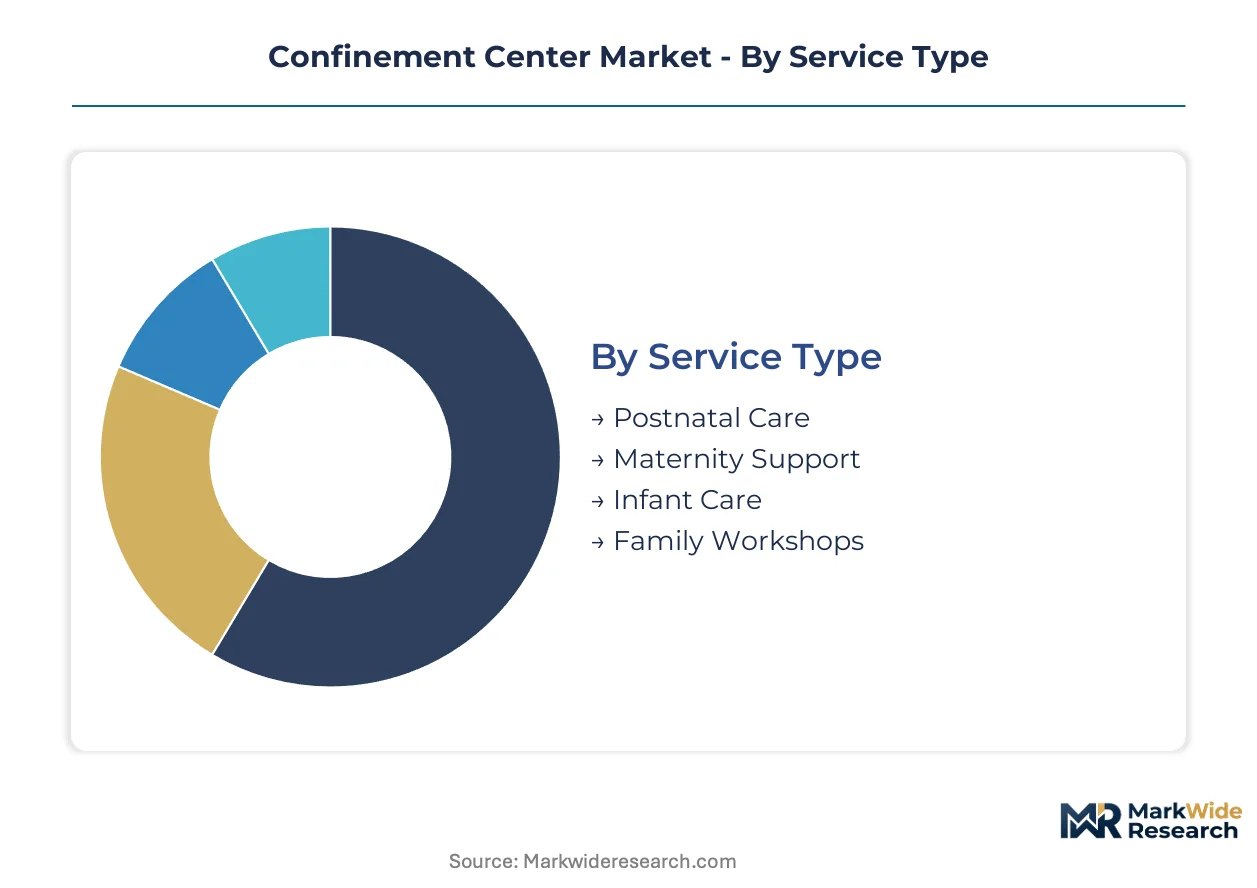
Confinement center operators deploy distinct service architectures to capture value across divergent household structures and recovery preferences. Channel strategy determines which segments reach clients through residential facilities versus domiciliary deployment or digital intermediation.
Service Type:
Postnatal care services flow predominantly through private center and hospital-affiliated channels, while infant care segments increasingly leverage hybrid telehealth platforms to extend beyond physical catchment zones.
- Postnatal Care:Structured 28-to-56-day residential programs combine traditional recovery practices with vital sign monitoring and wound care supervision. Singapore's premium private centers concentrate demand from first-time mothers in high-density housing estates where intergenerational support networks have thinned.
- Infant Care:Specialized newborn handling expertise including feeding protocols, sleep conditioning, and early developmental monitoring. Dual-income households across Malaysia's Klang Valley and Singapore's satellite towns drive expansion here as informal caregiver availability contracts.
- Maternity Support:Lactation consulting, emotional wellness counseling, and peer network facilitation delivered through both facility-based and home-based channels.
- Family Workshops:Educational programming on infant care techniques, sibling integration, and postpartum nutrition targeting extended family decision units.
Postnatal care dominates installed base. Infant care is where expansion concentrates.
Facility Type:
Cost tier stratification separates capital-intensive residential operations from asset-light deployment models, with margin structure varying dramatically across the spectrum.
- Private Centers:Boutique operators and premium chains offering personalized room configurations, specialized culinary programs, and dedicated nursing ratios. Malaysia's Ministry of Health licensing tightening is consolidating this segment as compliance costs displace independent operators.
- Hospitals:Integrated maternity and postnatal units leveraging clinical credibility, neonatal intensive care proximity, and insurance reimbursement pathways. Thomson Medical Group exemplifies this model across Singapore and Malaysia with sustained premium pricing power.
- Community Facilities:Non-profit and government-subsidized centers emphasizing accessibility over amenity density.
- Home-Based Care:Flexible deployment models reducing fixed facility overhead through nanny dispatch and meal delivery services. NannySOS Confinement Agency competes here via on-demand staffing platforms.
Hospitals anchor clinical credibility. Home-based care is climbing the fastest.
Pricing Model:
Customer type and service duration preferences dictate which pricing architectures gain traction among dual-income households versus extended family units.
- Fixed Packages:Comprehensive 28-day or 56-day residential bundles with predetermined service inclusions and accommodation tiers. Premium private centers in Singapore rely on this structure to capture upfront commitment from time-constrained professionals.
- Subscription Plans:Modular monthly arrangements for lactation consulting, meal delivery, and telehealth monitoring without facility residency. Digital platforms broker these services to compress traditional confinement duration expectations.
- Hourly Rates:À la carte nursing and caregiver dispatch for partial support needs.
- Pay-Per-Visit:Single-episode consultations for specific postnatal concerns or infant feeding challenges.
Fixed packages dominate residential bookings. Subscription plans are gaining share fastest.
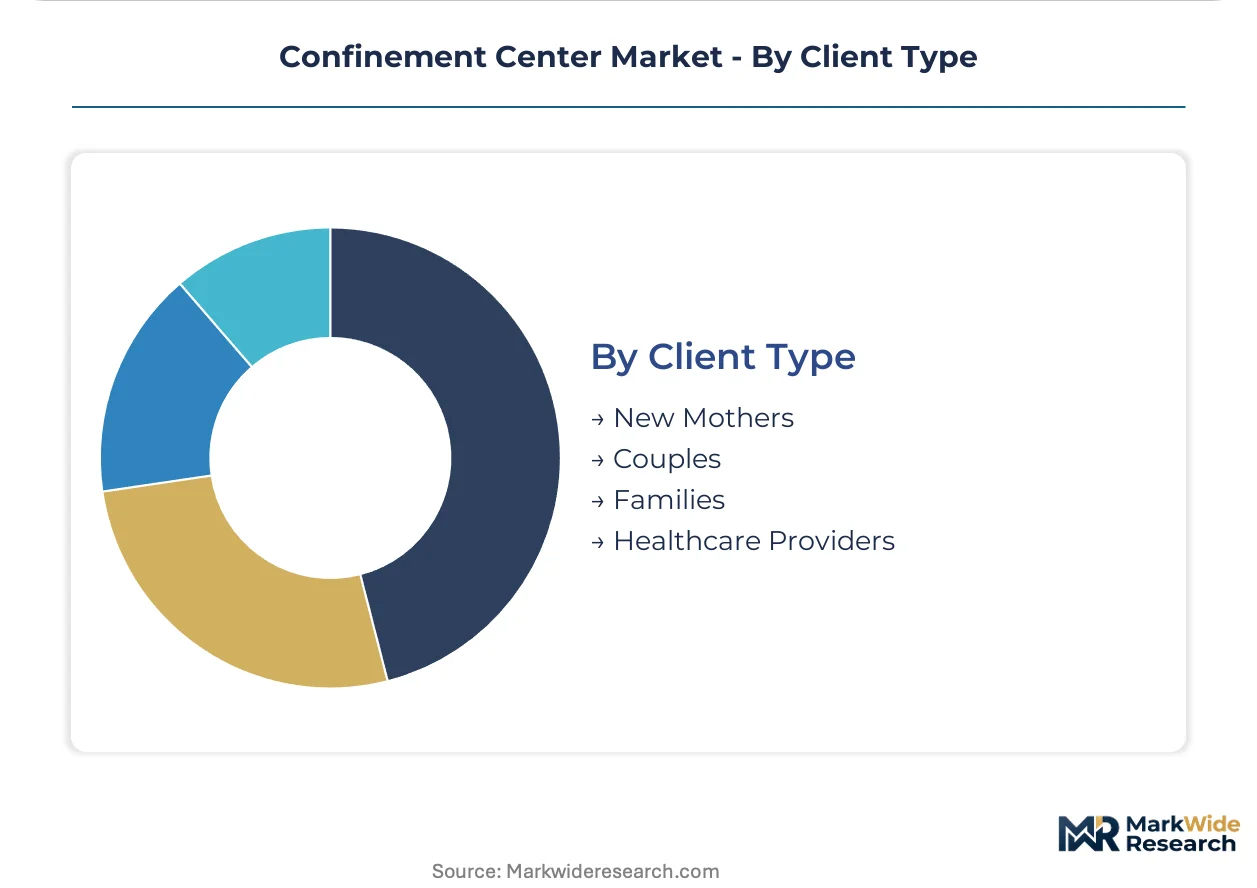
Client Type:
Application focus varies sharply between maternal recovery prioritization and infant-centric service delivery, with decision-making authority distributed across household structures.
- New Mothers:Primary service recipients seeking physical recovery support, lactation establishment, and emotional wellness resources. Urban first-time mothers in Singapore's premium segment drive highest per-client revenue through extended stays and amenity upgrades.
- Couples:Dual-income partners prioritizing convenient service integration with compressed return-to-work timelines and minimal household disruption.
- Families:Extended household units including grandparents and siblings where intergenerational negotiation shapes traditional versus modern protocol preferences.
- Healthcare Providers:Referring physicians, midwives, and hospital discharge planners directing high-risk cases toward clinically supervised postnatal environments.
New mothers anchor volume. Couples represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across the confinement center landscape. Singapore's premium segment absorbs sustained pricing power, while Malaysia's secondary cities exhibit acute sensitivity to facility cost escalation.
Singapore
First-time mothers in high-density housing estates drive concentrated demand for premium private centers with dedicated nursing ratios. The Ministry of Health licensing framework mandates enhanced staffing protocols and equipment specifications for maternity facilities. The central region's Orchard Road and Novena medical corridors host the deepest concentration of boutique operators competing on amenity density.
Malaysia
Klang Valley dual-income households seek specialized newborn handling expertise as informal caregiver availability contracts. The Private Healthcare Facilities and Services Act tightens operational standards through enhanced staffing ratio requirements and facility certification protocols. Kuala Lumpur's Mont Kiara and Bangsar districts concentrate hospital-affiliated chains capturing demand from displaced independent operators.
China
Post-90s parents in tier-one cities prioritize scientific postnatal protocols over traditional household confinement practices. NMPA guidelines influence neonatal care equipment sourcing and telehealth platform integration for hybrid service delivery. Shanghai's Pudong and Xuhui districts anchor premium center expansion targeting return-to-work professionals seeking compressed recovery timelines.
Canada
North American diaspora segments seek standardized postnatal care abroad with traceable ingredient protocols for traditional nutritional programs. Health Canada and PMRA guidelines elevate program credibility through mandated supply chain documentation for herbal preparations. Toronto's Richmond Hill and Vancouver's Richmond concentrate demand from Chinese-Canadian families arranging cross-border confinement stays.
Australia
Urban professional couples in Sydney and Melbourne fragment demand across facility-based, home-based, and hybrid delivery modes. TGA oversight of neonatal monitoring devices shapes telehealth integration requirements for remote service expansion. The Sydney metropolitan area's Chatswood and Hurstville clusters host the highest density of culturally specialized operators serving East Asian immigrant households.
Confinement Center Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the confinement center market. Hospital-affiliated chains leverage clinical credibility and insurance partnerships to sustain premium pricing, while boutique operators compete through specialized culinary programs and dedicated lactation consulting. Three archetypes dominate: integrated hospital systems, premium private centers, and flexible home-based agencies. Consolidation accelerates through regulatory compliance cost displacement, while technology licensing for remote monitoring platforms reshapes service delivery economics.
Among hospital-affiliated operators, Thomson Medical Group exemplifies the integrated infrastructure archetype across Singapore and Malaysia. Paradise Confinement Center occupies a position within the premium boutique tier, representing specialized postnatal culinary differentiation. NannySOS Confinement Agency anchors the flexible deployment segment, exemplifying asset-light models that reduce fixed facility overhead through on-demand staffing platforms.
| Leading Market Players |
|---|
| PEM Confinement Nanny Agency |
| Thomson Medical Group |
| Paradise Confinement Center |
| Allure Post Natal Center |
| NannySOS Confinement Agency |
| Fernwood Confinement Center |
| Confinement Angels |
| Sweet Pea Confinement Center |
| Mandarin Confinement Center |
| Others |
Pricing and Supply Chain Analysis
Ninety-day ingredient procurement lead times for postnatal herbal programs tether pricing power to supply chain resilience across Singapore and Malaysia. Facility operators absorbing Malaysia's Ministry of Health compliance costs pass through margin pressure via premium tier adjustments, while boutique centers lacking backward integration into ingredient sourcing face acute vulnerability to Health Canada and PMRA documentation requirements.
Pricing Analysis
Subscription-based after-sales revenue tiers now drive lifetime value capture as dual-income households fragment traditional 28-day residential commitments into modular service bundles. Three-tier pricing structure across premium, standard, and economy levels separates hospital-affiliated chains with insurance reimbursement pathways from boutique culinary specialists and flexible home-based agencies. Price differentiation hinges on nursing certification grade and room amenity density, with Singapore's Orchard Road corridor commanding sustained premiums while Malaysia's secondary cities exhibit acute sensitivity to facility cost escalation. Cost compression in the home-based tier is intensifying because NannySOS-style dispatch platforms eliminate fixed overhead burdens.
Supply Chain Analysis
Just-in-time inventory strategies dominate postnatal meal program operations, though premium centers maintain strategic stockpiles of NMPA-cleared neonatal monitoring devices to ensure service continuity. Ingredient sourcing concentrates in China for herbal preparations, Malaysia for fresh produce integration, and Canada for diaspora-facing traceability documentation. Supply chain risk rests on single-source vulnerability for neonatal-certified nursing talent in Malaysia's secondary cities, where staffing ratio mandates outpace training pipeline output. Distribution runs through hospital discharge planner networks for high-acuity cases and digital brokerage platforms for flexible home-based deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified neonatal nursing scarcity constrains expansion velocity across Southeast Asian operations, with Malaysia's Ministry of Health staffing mandates widening the gap between compliance requirements and available practitioner supply.
For Market Incumbents: Compound clinical credibility advantages through telehealth platform licensing and insurance partnership deepening. Thomson Medical Group's integrated infrastructure model demonstrates how hospital-affiliated chains capture displaced demand from boutique operators facing Malaysia's Private Healthcare Facilities and Services Act compliance costs. Vertical integration into lactation consulting certification programs defends margin pools against NannySOS-style flexible deployment substitution. For New Entrants and Emerging Players: Home-based lactation consulting gaps in Singapore's satellite towns present white-space entry points where premium private centers under-serve compressed return-to-work timelines. Malaysia's Klang Valley secondary cities offer the most penetrable geography given staffing shortage displacement of independent operators. Digital platform brokerage of on-demand meal delivery and remote infant monitoring provides asset-light go-to-market positioning without facility capex exposure. For Investors and Strategic Acquirers: Carve-out targets emerge from hospital system maternity unit divestitures seeking operational focus. Five-to-ten year viability hinges on telehealth integration depth and cross-border regulatory navigation capability. Acquisition archetypes center on boutique operators with established culinary differentiation and stranded patient referral relationships. Watch neonatal telehealth mandate progression across Singapore's Ministry of Health and Malaysia's regulatory evolution as inflection indicator for platform licensing value.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Licensing | Remote infant monitoring with FDA-cleared sensors decomposes 24-hour nursing presence requirements. |
| Insurance Partnership Deepening | Reimbursement integration with private health plans extends hospital-affiliated chain reach beyond cash-pay segments. |
| Lactation Consulting Certification | Dedicated programs create differentiation where informal caregiver networks dominate infant feeding support. |
| Cross-Border Regulatory Navigation | Operators bridging Singapore's Ministry of Health framework with Malaysia's Private Healthcare Facilities and Services Act capture consolidation benefits. |
| Herbal Ingredient Traceability Investment | Health Canada and PMRA documentation elevates program credibility among North American diaspora segments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with confinement center directors, neonatal nursing certification program administrators, hospital discharge planners, and Health Canada regulatory affairs specialists. Secondary validation drew from Singapore's Ministry of Health licensing databases, Malaysia's Private Healthcare Facilities and Services Act compliance records, NMPA medical device registration filings, and Health Canada PMRA ingredient guidance documents. Bottom-up service volume modeling triangulated against top-down healthcare expenditure flow analysis.
Across the analysis window, forecasts employed segmented modeling across service type, facility architecture, pricing model, and client household structure dimensions. CAGRs were derived from regression analysis against dual-income household penetration rates, neonatal telehealth mandate adoption curves, and regulatory compliance cost trajectories. Industry-specific inputs incorporated nursing certification pipeline throughput and construction cost indices for negative pressure infant handling zones.
Forecasts assume regulatory continuity in Singapore's Ministry of Health framework and Malaysia's Private Healthcare Facilities and Services Act; material policy shifts would require re-modeling. Neonatal telehealth scope expansions, cross-border staffing mobility agreements, and construction input volatility represent specific revision triggers. Revision becomes warranted when licensed nurse supply shortages breach operational viability thresholds in targeted expansion geographies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Facilities
Micro-Hospitals Market
Healthcare Facilities
Trauma Care Centers Market
Healthcare Facilities
US Hospital Facilities Market
Healthcare Facilities
Hospital Lighting Market
Healthcare Facilities
Global Healthcare Facilities Management Market
Healthcare Facilities
US Skilled Nursing Facility Market
Healthcare Facilities
US Ambulatory Surgery Centers Market
Healthcare Facilities
US Assisted Living Facility Market
Healthcare Facilities
US and Europe Ambulatory Surgery Centers Market
Healthcare Facilities
US Ambulatory Surgical Centers Market
Healthcare Facilities
Asia-Pacific Smart Hospital Market
Healthcare Facilities
Longevity Clinic Chain Infrastructure Market
Healthcare Facilities
Global Healthcare Architecture Market
Healthcare Facilities
Assisted Living Facilities Market
Healthcare Facilities
Private Office-Based Clinics Market
Healthcare Facilities
US Skilled Nursing Facility and Rehabilitation Market