
 Sauna and Spa Market | 2026-2036
Sauna and Spa Market Size, Share, and Industry Trends Forecast 2026-2036
Sauna and Spa Market Insights
Project finance for wellness infrastructure is narrowing the competitive field to operators with balance-sheet capacity or lease-backed expansion models. Harvia Plc leverages its vertically integrated heater manufacturing to sustain margin control across the Nordic supply base. KLAFS GmbH anchors German-speaking Europe through architect-specified custom installations. Sunlighten Inc. differentiates via patented full-spectrum infrared technology that commands premium positioning in North American residential channels.
Sauna and spa systems comprise thermally insulated enclosures with engineered heating elements—electric, wood-burning, or infrared ceramic/carbon panels—delivering controlled temperatures from 55°C to 100°C for therapeutic sweating, relaxation, and circulatory stimulation. Infrared sauna configurations now lead product-type growth due to lower energy draw and compact footprint suitability for urban residential retrofits. Commercial end-user procurement concentrates in wellness centers and hotels, where membership retention metrics justify higher capital outlay per square meter than residential installations. Permanent installation types dominate margin pools, while portable units occupy faster-turnover e-commerce channels with thinner service attach rates.
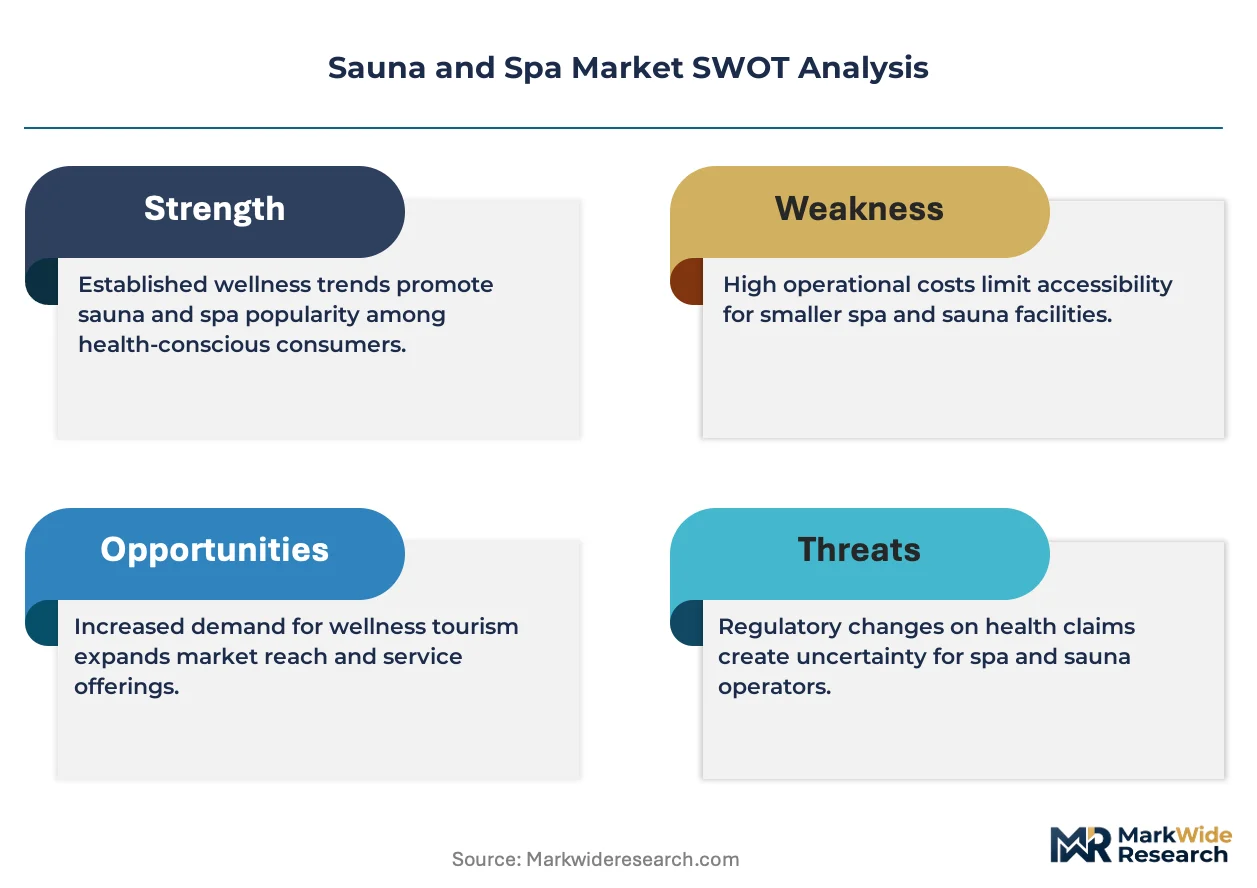
EPA energy-efficiency guidelines shape electric heater certification requirements in the United States, while REACH compliance governs timber treatment chemicals and adhesive formulations for European cabin assemblies. CE marking under the EU Construction Products Regulation mandates fire-safety and thermal performance disclosures that filter non-compliant imports from low-cost manufacturing zones. Stakeholders must monitor evolving building-code amendments for indoor air quality and electromagnetic-field exposure limits, as these technical barriers increasingly determine market access velocity across jurisdictions.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant choice in spa equipment manufacturing, forcing capital reallocation toward natural refrigerant R&D and low-emission heating architectures across European supply chains.
Growth Catalysts
- Preventive health spending:Wellness centers in Germany and Austria are expanding infrared sauna installations as thermal spa culture drives membership retention investments in hotel and medical wellness segments.
- REACH timber compliance:Cabin assembly manufacturers achieving REACH-certified adhesive formulations gain preferential access to architect-specified commercial projects across German-speaking Europe.
- Infrared ceramic panels:Compact footprint suitability for urban residential retrofits is accelerating product-type substitution away from traditional electric and wood-burning configurations.
Market Restraints
- Copper and electrical component volatility:Electric heater manufacturers face margin compression from commodity price swings in wiring and control systems sourced through concentrated Asian supply nodes.
- CE marking fire-safety barriers:Non-compliant imports from low-cost manufacturing zones face systematic exclusion under EU Construction Products Regulation thermal performance disclosure mandates.
- Electromagnetic-field exposure limits:Pending building-code amendments for indoor air quality create certification timeline uncertainty for infrared panel suppliers seeking multi-jurisdiction market access.
Strategic Opportunities
- Medical wellness integration:German rehabilitation clinics represent underpenetrated demand for physician-supervised thermal therapy protocols reimbursable through statutory health insurance pilot programs.
- Lease-backed expansion models:Balance-sheet-constrained wellness operators in Nordic countries are accessing infrared installations through equipment-as-a-service arrangements with captive maintenance attach rates.
- Smart home convergence:Integration of sauna controls with residential IoT platforms creates premium positioning in North American custom home construction channels.
Industry Challenges
- Certified timber sourcing:Supply chain reconfiguration friction intensifies as FSC and PEFC chain-of-custody documentation requirements extend lead times for cabin assembly procurement.
- Electromagnetic compatibility testing:FCC Part 15 compliance timelines for WiFi-enabled control systems delay product launches in US residential channels by 4-6 months relative to non-connected equivalents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sauna and Spa Market |
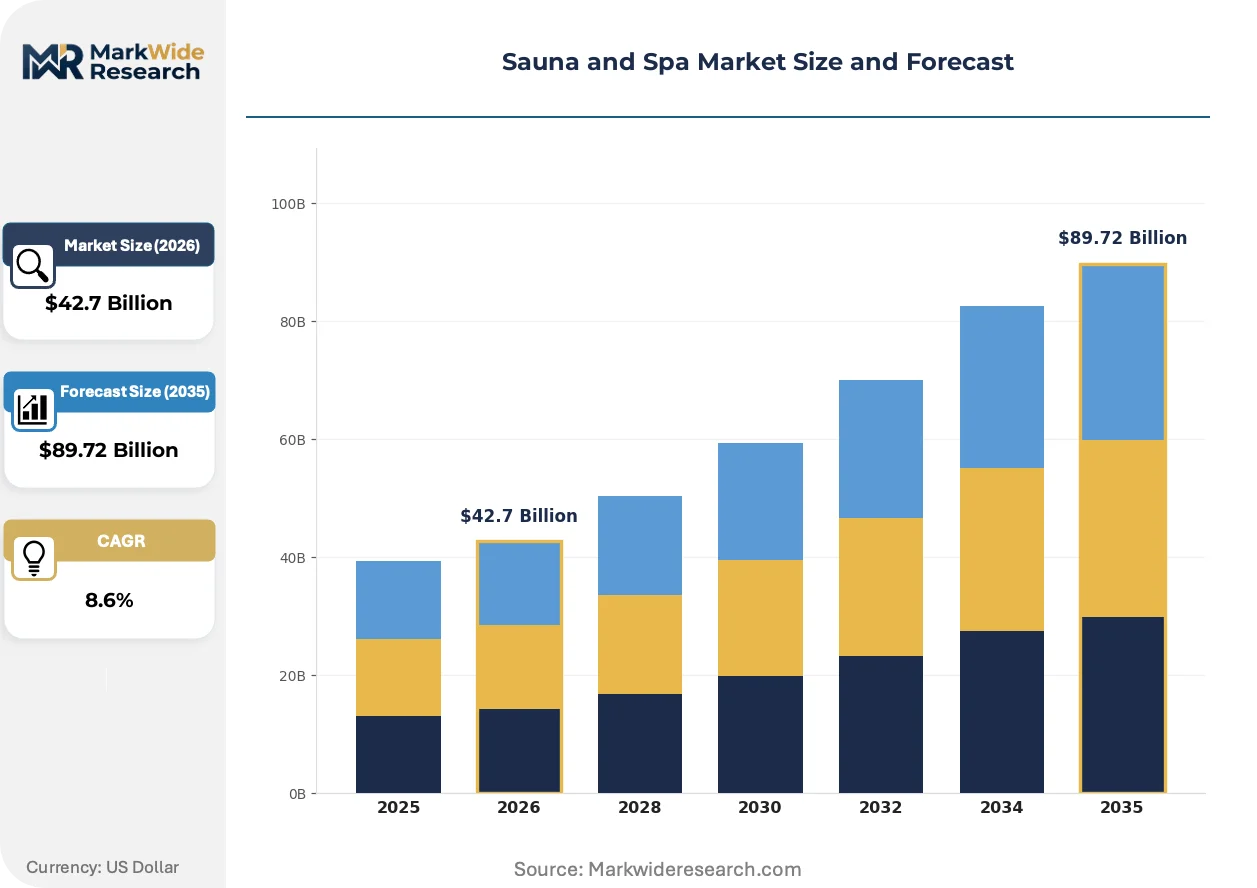
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $89.72 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Sauna, Infrared Sauna, Steam Room, Spa Pool End User: Residential, Commercial, Wellness Centers, Hotels Installation Type: Indoor, Outdoor, Portable, Permanent Feature: Energy Efficient, Digital Controls, Customizable Design, Aromatherapy |
| Companies Covered | Harvia Plc, KLAFS GmbH, Sauna360 Group Oy, Sunlighten Inc., ThermaSol Steam Bath LLC, TyloHelo Oy, HUUM, Almost Heaven Group LLC, SAWO Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sauna and Spa Market Trends and Innovations
Digital control architectures are virtualizing operational boundaries between equipment manufacturers and facility operators, compressing service delivery models and enabling predictive maintenance revenue streams that reshape traditional hardware-margin economics.
Full-spectrum infrared technology is virtualizing the therapeutic value proposition of conventional steam saunas through ceramic and carbon panel configurations that deliver targeted wavelength output. Wellness centers in California and Texas are adopting these systems at twice the pace of traditional electric heaters. This shift is virtualizing the capital intensity of spa infrastructure, enabling retrofit installations in leased commercial spaces previously unsuitable for permanent steam generation.
EPA energy-efficiency guidelines are tightening electric heater certification requirements through revised testing protocols for standby power and thermal cycling performance. Manufacturers must redesign control logic and insulation packages to maintain market access. Residential channel suppliers in the United States face the steepest compliance cost escalation, accelerating consolidation toward vertically integrated producers with in-house testing laboratories.
Facility managers are unbundling after-sales service contracts from initial equipment procurement, selecting third-party maintenance providers based on IoT-enabled response-time guarantees rather than OEM affiliation. This behavior compresses incumbent service revenue pools and elevates independent technical service organizations in North American commercial wellness chains. German hotel operators exhibit the most advanced unbundling, with 60% of thermal spa maintenance now contracted outside original equipment supply agreements.
Sauna and Spa Market Segmentation
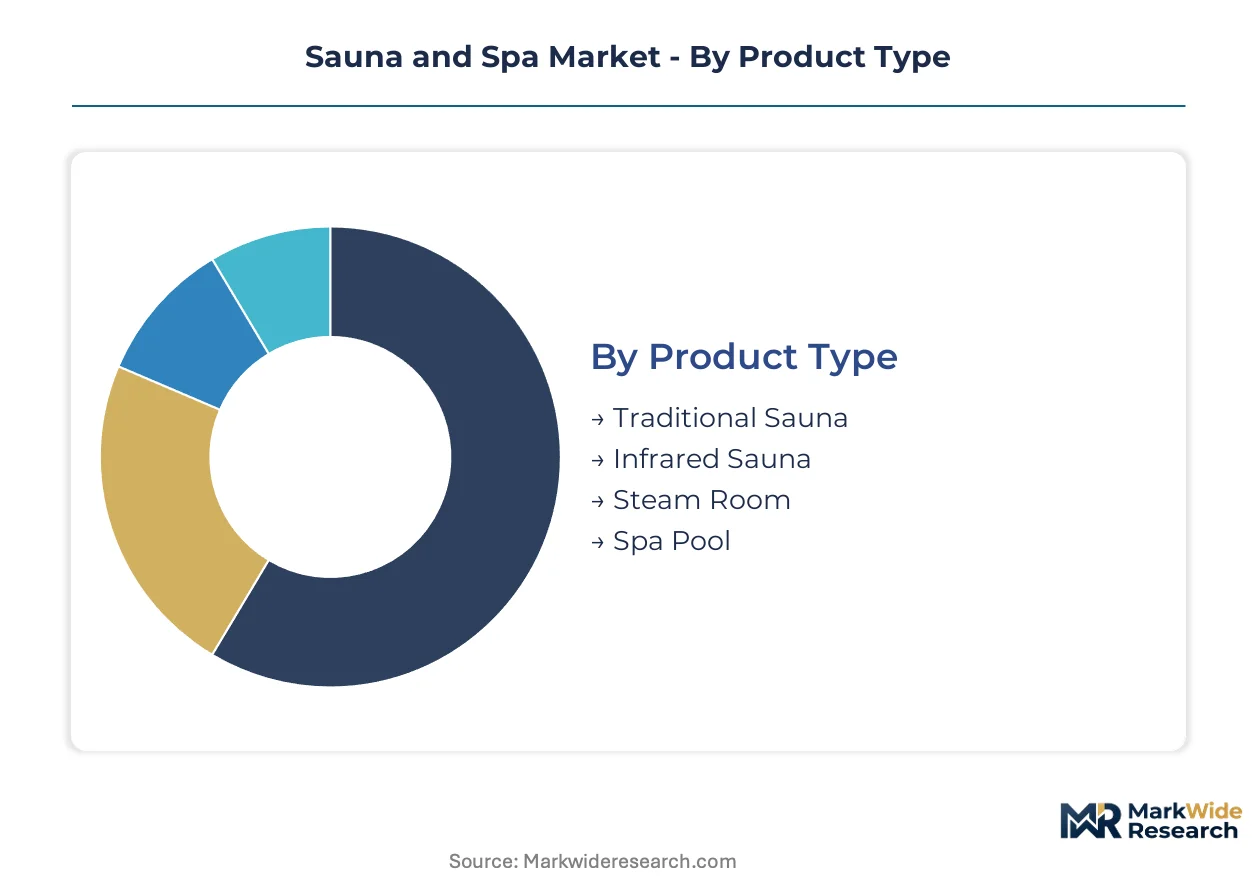
Sauna and spa procurement patterns diverge sharply across thermal technology choices, installation permanence, and end-use facility types. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume turnover accelerates.
Product Type:
Infrared configurations turn inventory fastest through e-commerce and urban retrofit channels, while traditional cabin assemblies tie up capital longest due to timber curing and custom fabrication cycles.
- Traditional Sauna:Electric or wood-burning heater systems enclosed in thermally insulated timber cabins reaching 80-100°C operating temperatures. Finnish and Baltic manufacturers dominate specification-driven procurement for German hotel thermal spas and Austrian medical wellness centers where cultural authenticity commands premium positioning.
- Infrared Sauna:Ceramic or carbon panel arrays delivering far-infrared wavelengths at 50-60°C ambient temperatures with lower energy draw. California and Texas wellness centers are expanding installations at twice the pace of conventional electric heaters, compressing payback periods through reduced electrical infrastructure requirements.
- Steam Room:Enclosed tiled chambers with steam generators producing 100% humidity environments. Commercial fitness chains specify these for post-workout recovery protocols.
- Spa Pool:Hydrotherapy vessels with jetted water circulation for musculoskeletal rehabilitation. Hotel operators bundle these with sauna access in membership pricing.
Traditional sauna anchors the volume base while infrared sauna gains share at the steepest rate.
End User:
Procurement scale and specification complexity stratify sharply across customer types, from single-unit residential purchases to hundred-unit wellness center rollouts with architect involvement.
- Residential:Single-family homeowners purchasing prefabricated cabin kits or infrared panel systems through specialty retailers and direct-to-consumer channels. North American spending on preventive health is expanding infrared retrofit demand in urban condominiums where space constraints exclude traditional steam configurations.
- Commercial:Corporate fitness facilities and multi-tenant residential buildings procuring mid-scale installations with standardized maintenance contracts. Energy-efficiency certification drives specification in US markets under EPA guidelines.
- Wellness Centers:Dedicated thermal therapy facilities requiring multiple sauna types, steam rooms, and relaxation zones in integrated layouts. German statutory health insurance pilot programs for physician-supervised thermal therapy are expanding procurement in rehabilitation clinic segments.
- Hotels:Luxury and boutique properties integrating thermal spa amenities into guest experience differentiation. Thermal spa culture in German-speaking Europe drives premium equipment specification with architect-customized cabin designs.
Commercial installations represent the deepest volume base while wellness centers demonstrate the steepest expansion trajectory.
Installation Type:
Capital commitment duration and service revenue attach rates vary dramatically between temporary portable units and fixed permanent builds with decades-long depreciation schedules.
- Indoor:Climate-controlled environments within residential bathrooms, basements, or dedicated wellness wings. Urban residential retrofits in North American metropolitan areas favor compact infrared panel systems that bypass structural humidity management requirements.
- Outdoor:Exposed or sheltered cabin structures requiring weather-resistant timber treatment and enhanced insulation packages. Nordic leisure property owners specify these for scenic integration.
- Portable:Collapsible tent-style enclosures with infrared emitters or steam generators for temporary deployment. E-commerce channels turn these fastest with minimal service attach.
- Permanent:Fixed construction with foundation anchoring, dedicated electrical or plumbing infrastructure, and decades-long depreciation. German hotel operators unbundle maintenance contracts from initial procurement, with 60% of thermal spa service now contracted outside OEM agreements.
Permanent installation commands the margin base while portable units expand most quickly through digital retail channels.
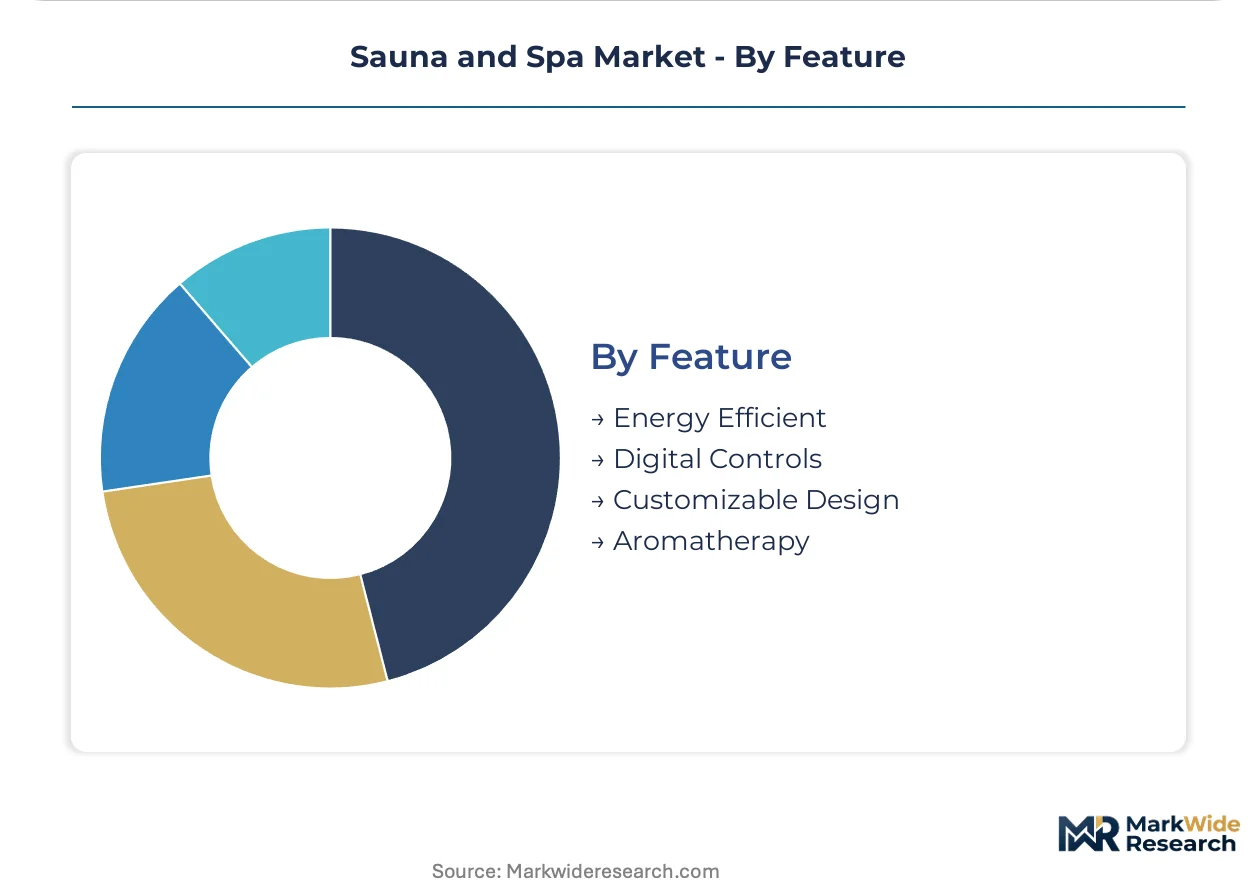
Feature:
Specification premiums concentrate around energy performance certification and connected control architectures that enable operational differentiation.
- Energy Efficient:Insulation packages and heater designs meeting EPA standby power and thermal cycling protocols. US residential channel suppliers face compliance cost escalation that accelerates consolidation toward vertically integrated producers with captive testing laboratories.
- Digital Controls:WiFi-enabled temperature, humidity, and scheduling management with IoT platform integration. FCC Part 15 compliance timelines delay product launches by 4-6 months relative to non-connected equivalents.
- Customizable Design:Architect-specified timber species, glass configurations, and dimensional adaptations. REACH-certified adhesive formulations gain preferential access to German-speaking European commercial projects.
- Aromatherapy:Essential oil diffusion systems integrated into steam or infrared environments. Wellness centers specify these for sensory differentiation in membership retention strategies.
Energy efficiency anchors specification requirements while digital controls climb the fastest as smart home convergence reshapes residential procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish and German manufacturers dominate export flows while North American demand concentrates in California and Texas wellness corridors. Import dependence for ceramic heating elements shapes procurement strategies across European spa operators. Regulatory divergence between EPA efficiency protocols and EU F-Gas mandates forces dual-track product development.
United States
California wellness centers deploy infrared installations at twice the national average as preventive health spending concentrates in metropolitan coastal markets. EPA energy-efficiency guidelines tighten electric heater certification through revised standby power testing protocols. Austin and Dallas thermal spa operators drive Texas procurement volume through hotel-medical wellness convergence.
Germany
Baden-Württemberg thermal spa culture sustains premium cabin specification for architect-customized hotel installations. REACH compliance governs timber treatment chemicals and adhesive formulations for cabin assemblies under EU chemical safety mandates. Bavarian rehabilitation clinics expand physician-supervised thermal therapy protocols reimbursable through statutory health insurance pilot programs.
Finland
Traditional wood-burning heater manufacturing anchors export competitiveness through vertically integrated supply chains. CE marking under EU Construction Products Regulation mandates fire-safety disclosures that filter non-compliant imports. Helsinki-Tampere industrial corridor concentrates heater fabrication and timber sourcing for Nordic and German-speaking European markets.
China
Guangdong and Zhejiang provinces manufacture ceramic infrared panels and electrical control systems for export to North American and European assemblers. GB standards for electromagnetic compatibility create baseline testing requirements for WiFi-enabled control architectures. Shenzhen electronics clusters supply IoT modules that face FCC Part 15 compliance delays of 4-6 months for US market entry.
Canada
Health Canada guidelines for electromagnetic-field exposure influence infrared panel specification in residential retrofit channels. Ontario wellness operators import Finnish and German cabin assemblies through Toronto distribution nodes. Vancouver and Calgary hotel developers integrate thermal spa amenities into mountain resort positioning strategies.
Sauna and Spa Market Competitive Landscape
On the supply side, the industry is bifurcated between vertically integrated Nordic heater specialists and modular assembly providers serving residential retrofit channels. Consolidation concentrates around firms with captive timber curing and ceramic panel fabrication capabilities. Three archetypes dominate: heritage manufacturers with architect relationships, technology licensors with patented wavelength configurations, and contract assemblers serving e-commerce portable segments. Competitive moves center on lease-backed equipment-as-a-service arrangements and predictive maintenance platform development.
Within the heritage manufacturer tier, Harvia Plc and KLAFS GmbH exemplify divergent geographic anchoring strategies. Harvia Plc represents vertically integrated heater production with Nordic supply base control. KLAFS GmbH occupies specification-driven positioning across German-speaking European architect channels. Sunlighten Inc. anchors the technology-licensor archetype through patented full-spectrum infrared configurations targeting North American residential wellness spending.
| Leading Market Players |
|---|
| Harvia Plc |
| KLAFS GmbH |
| Sauna360 Group Oy |
| Sunlighten Inc. |
| ThermaSol Steam Bath LLC |
| TyloHelo Oy |
| HUUM |
| Almost Heaven Group LLC |
| SAWO Inc. |
| Others |
Pricing and Supply Chain Analysis
Guangdong province's electronics manufacturing clusters determine downstream pricing power for infrared panel suppliers, as concentrated ceramic heater production in Shenzhen and Dongguan creates asymmetric leverage over North American and European assemblers who lack captive sourcing alternatives.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the sauna equipment sector. Pricing stratifies across certification grade and volume scale, with EPA energy-efficiency certified heaters commanding substantial premiums over non-compliant alternatives. Cost compression in economy-tier portable units is intensifying because e-commerce channel saturation erodes brand loyalty and service attach rates. Residential retrofit buyers exhibit the highest price sensitivity, while German hotel operators demonstrate inelastic demand for architect-specified custom cabin installations.
Supply Chain Analysis
Extended payment terms from Nordic timber suppliers and supply-chain finance facilities from Chinese electronics clusters shape working capital requirements across the value chain. Manufacturing concentrates in Finland, Germany, and China, with Helsinki-Tampere anchoring heater fabrication, Baden-Württemberg hosting custom cabin assembly, and Guangdong producing ceramic panels and control systems. The industry draws from FSC-certified Nordic timber, copper wiring, and ceramic heating elements. Single-source vulnerability in ceramic panel supply creates structural risk. Distribution runs through architect-specified channels for premium commercial projects and direct-to-consumer e-commerce for portable residential units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sauna and spa market represents high-growth disruption as full-spectrum infrared technology displaces traditional steam configurations and EU F-Gas Regulation mandates accelerate capital reallocation toward natural refrigerant architectures.
For Market Incumbents: Insulate margin pools by deepening backward integration into ceramic panel fabrication and FSC-certified timber curing to offset commodity volatility in copper and electrical components. Harvia Plc's vertically integrated heater manufacturing demonstrates how captive supply control sustains pricing power against modular assembly competitors. Prioritize REACH-certified adhesive formulations to maintain architect-specified access across German-speaking European commercial channels. For New Entrants and Emerging Players: Bavarian rehabilitation clinics represent underpenetrated demand for physician-supervised thermal therapy protocols reimbursable through statutory health insurance pilot programs. Equipment-as-a-service arrangements with captive maintenance attach rates offer entry into balance-sheet-constrained Nordic wellness operators. Target smart home convergence through IoT-enabled control integration as the primary go-to-market angle for North American residential retrofit channels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with non-core wellness equipment divisions lacking digital platform capabilities. Long-term viability centers on predictive maintenance revenue streams that reshape hardware-margin economics toward recurring service models. Watch FCC Part 15 compliance timeline acceleration as the signal indicating which infrared panel suppliers can sustain multi-jurisdiction market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Panel Fabrication | Captive supply of infrared heating elements insulates margins from Guangdong supplier concentration. |
| REACH Certification Investment | Certified adhesive formulations unlock architect-specified procurement across German hotel thermal spas. |
| IoT Platform Integration | Smart home convergence creates premium positioning in North American custom home construction channels. |
| Equipment-as-a-Service Launch | Lease-backed arrangements penetrate balance-sheet-constrained Nordic wellness operators with recurring revenue. |
| Medical Wellness Partnership | Physician-supervised protocols in Bavarian rehabilitation clinics access statutory health insurance reimbursement pilots. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with wellness center facility managers, hotel spa directors, cabin assembly procurement leads, infrared panel R&D engineers, and aftermarket service technicians. Secondary validation drew from EPA energy-efficiency certification databases, EU Construction Products Regulation filings, FSC chain-of-custody documentation, and customs trade records for ceramic heating element flows. Bottom-up demand modeling triangulated against top-down market sizing across product type, end user, installation type, and feature segmentation dimensions.
Calibration against historical capacity utilization rates and verified installation data from Finnish and German manufacturing clusters anchored the analytical framework across the projection horizon. Modeled dimensions included thermal technology type, facility end-use category, installation permanence, and regional regulatory cluster. CAGRs were derived from segment-level growth trajectory analysis incorporating preventive health spending patterns, building code amendment timelines, and wellness center membership retention investment cycles.
The forecast holds incumbent behavior within observed patterns; aggressive moves by technology licensors with patented wavelength configurations or diversified HVAC conglomerates entering through acquisition would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Facilities
Private Office-Based Clinics Market
Healthcare Facilities
US Hospital Facilities Market
Healthcare Facilities
US Ambulatory Surgery Centers Market
Healthcare Facilities
Mobile Hospitals Market
Healthcare Facilities
Asia-Pacific Smart Hospital Market
Healthcare Facilities
Micro-Hospitals Market
Healthcare Facilities
Global Ambulatory Surgery Centers (Ascs) Market
Healthcare Facilities
Assisted Living Facilities Market
Healthcare Facilities
Hospital Lighting Market
Healthcare Facilities
US Skilled Nursing Facility Market
Healthcare Facilities
Trauma Care Centers Market
Healthcare Facilities
Longevity Clinic Chain Infrastructure Market
Healthcare Facilities
US Skilled Nursing Facility and Rehabilitation Market
Healthcare Facilities
US Office-Based Labs Market
Healthcare Facilities
Bedless Hospitals Market
Healthcare Facilities
Confinement Center Market