
 US Ambulatory Surgery Centers Market | 2026-2036
US Ambulatory Surgery Centers Market Size, Share, and Industry Trends Forecast 2026-2036
US Ambulatory Surgery Centers Market Intelligence
Physician-owned partnerships is bifurcating from hospital-affiliated joint ventures as the dominant ownership model for new center development. HCA Healthcare sustains the largest national footprint through its Surgery Partners affiliate network, while Tenet Healthcare anchors market presence via USPI's joint-venture structure with nonprofit health systems. AMSURG differentiates through its exclusive focus on gastroenterology and ophthalmology partnerships with large physician groups.
Ambulatory surgery centers are Medicare-certified facilities designed for same-day surgical procedures requiring general, regional, or local anesthesia, with physical plant standards mandating distinct preoperative holding, operating, and post-anesthesia recovery zones. Orthopedic surgery and gastroenterology dominate procedure volume, with pain management representing the fastest-expanding category as spinal cord stimulator implants and radiofrequency ablation shift outpatient. Physician practices and independent centers capture disproportionate margin pools compared to hospital-integrated models due to lower overhead structures and direct payer contracting.
CMS maintains the definitive reimbursement framework through annual ASC fee schedule updates, while state-level certificate-of-need regulators determine facility licensing in thirty-five states. OSHA bloodborne pathogen standards and Joint Commission accreditation requirements shape clinical staffing and infection control protocols. Stakeholders must monitor whether Medicare's site-neutral payment push accelerates further procedure migration from hospital outpatient departments to freestanding centers.
Market Dynamics
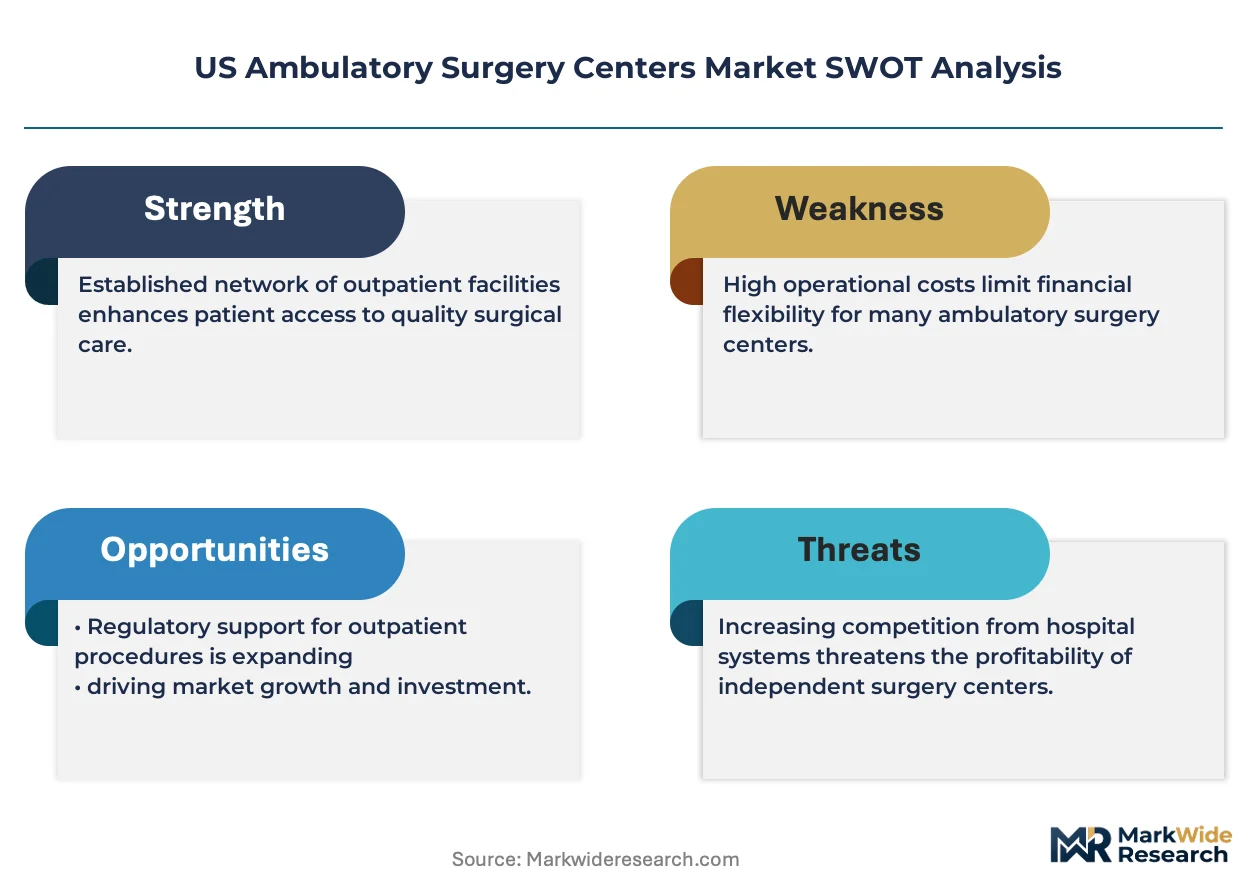
Medicare Advantage plans are aggressively steering elective orthopedic procedures toward outpatient settings, compressing hospital outpatient department volumes while CMS annually expands the ASC-approved procedure list through fee schedule updates.
Growth Catalysts
- CMS Reimbursement Expansion:Annual updates to the ASC fee schedule add complex procedures previously restricted to hospital settings, directly enlarging addressable procedure volume for freestanding centers.
- Certificate-of-Need Reform:Southeastern states including Florida and Georgia have eliminated or loosened CON restrictions, accelerating independent center development and physician-owned partnership formations.
- Spinal Cord Stimulator Migration:Pain management procedures including neurostimulator implants and radiofrequency ablation are shifting outpatient, creating fastest-expanding category demand.
Market Restraints
- Reimbursement Compression:Medicare's site-neutral payment push threatens to narrow margin differentials between ASCs and hospital outpatient departments.
- Capital Intensity:Physical plant standards mandating distinct preoperative holding, operating, and post-anesthesia recovery zones require substantial facility investment.
- Anesthesia Staffing Constraints:Limited CRNA and anesthesiologist supply in rural sub-regions restricts expansion into underserved geographies.
Strategic Opportunities
- Cardiovascular Procedure Migration:CMS evaluation of cardiac catheterization and structural heart procedures for ASC approval creates potential white-space expansion.
- Direct Employer Contracting:Self-insured employers in Texas and North Carolina are negotiating bundled rates directly with independent centers, bypassing traditional payer intermediaries.
- Gastroenterology Volume Capture:Colorectal cancer screening mandates and aging demographics concentrate demand for endoscopy partnerships with large physician groups.
Industry Challenges
- Joint Commission Accreditation Timeline:New centers face 12-18 month certification cycles before Medicare enrollment, delaying revenue generation.
- EHR Integration Complexity:Physician practices acquiring independent centers encounter interoperability friction with hospital-system legacy platforms.
- Infection Control Protocol Staffing:OSHA bloodborne pathogen standards require dedicated compliance personnel that smaller centers struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Ambulatory Surgery Centers Market |
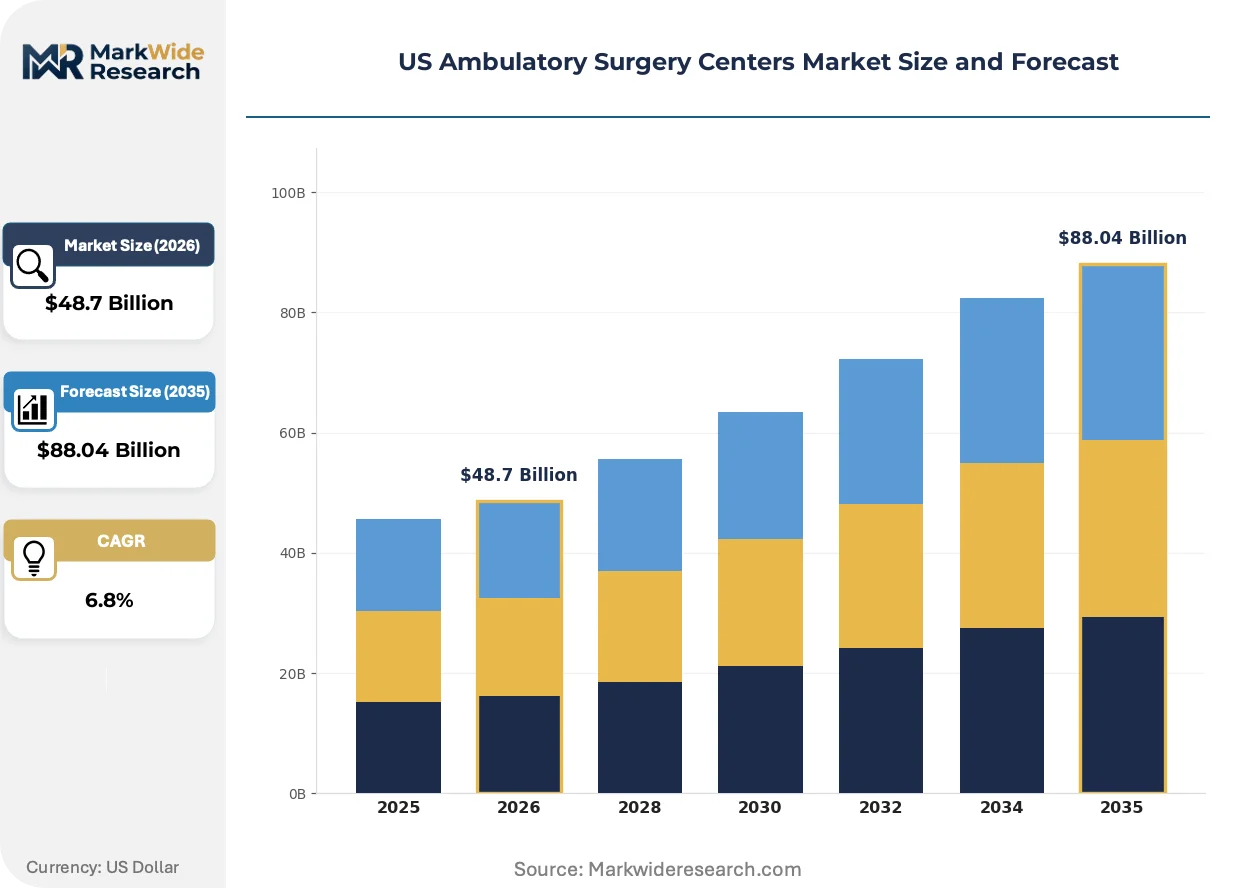
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Orthopedic Surgery, Gastroenterology, Ophthalmology, Pain Management End User: Physician Practices, Hospitals, Independent Centers, Specialty Clinics Technology: Outpatient Surgery Systems, Telehealth Solutions, Imaging Equipment, Anesthesia Devices Service Type: Preoperative Services, Surgical Services, Postoperative Care, Recovery Management |
| Companies Covered | HCA Healthcare, Tenet Healthcare, USPI, SCA Health, AMSURG, Surgery Partners, United Surgical Partners International, Optum, Envision Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Ambulatory Surgery Centers Market Strategic Shifts & Innovations
Robotics and advanced imaging are compressing procedure times and recovery windows, enabling same-day discharge for interventions previously requiring overnight observation.
Robotic-assisted surgical platforms are bifurcating orthopedic and spine procedure economics. Large physician groups in metropolitan Texas markets are deploying capital for MAKO and ROSA systems, compressing case duration and enabling higher daily throughput. This technology is bifurcating competitive positioning between capital-rich partnership structures and smaller independent centers unable to finance platform acquisition.
CMS site-neutral payment proposals are reshaping facility strategy. The 2024 outpatient prospective payment system rule accelerated procedure migration discussions, pressuring hospital-affiliated joint ventures to defend volume. ASCs in certificate-of-need states are responding by accelerating certificate applications before potential regulatory tightening.
Employer direct contracting is disrupting traditional payer channel dominance. Self-insured manufacturers and logistics employers in Tennessee and South Carolina are negotiating episode-based rates with gastroenterology-focused centers. This channel shift concentrates in states with weak hospital system consolidation, where employers possess sufficient leverage to bypass commercial intermediaries.
US Ambulatory Surgery Centers Market Segmentation
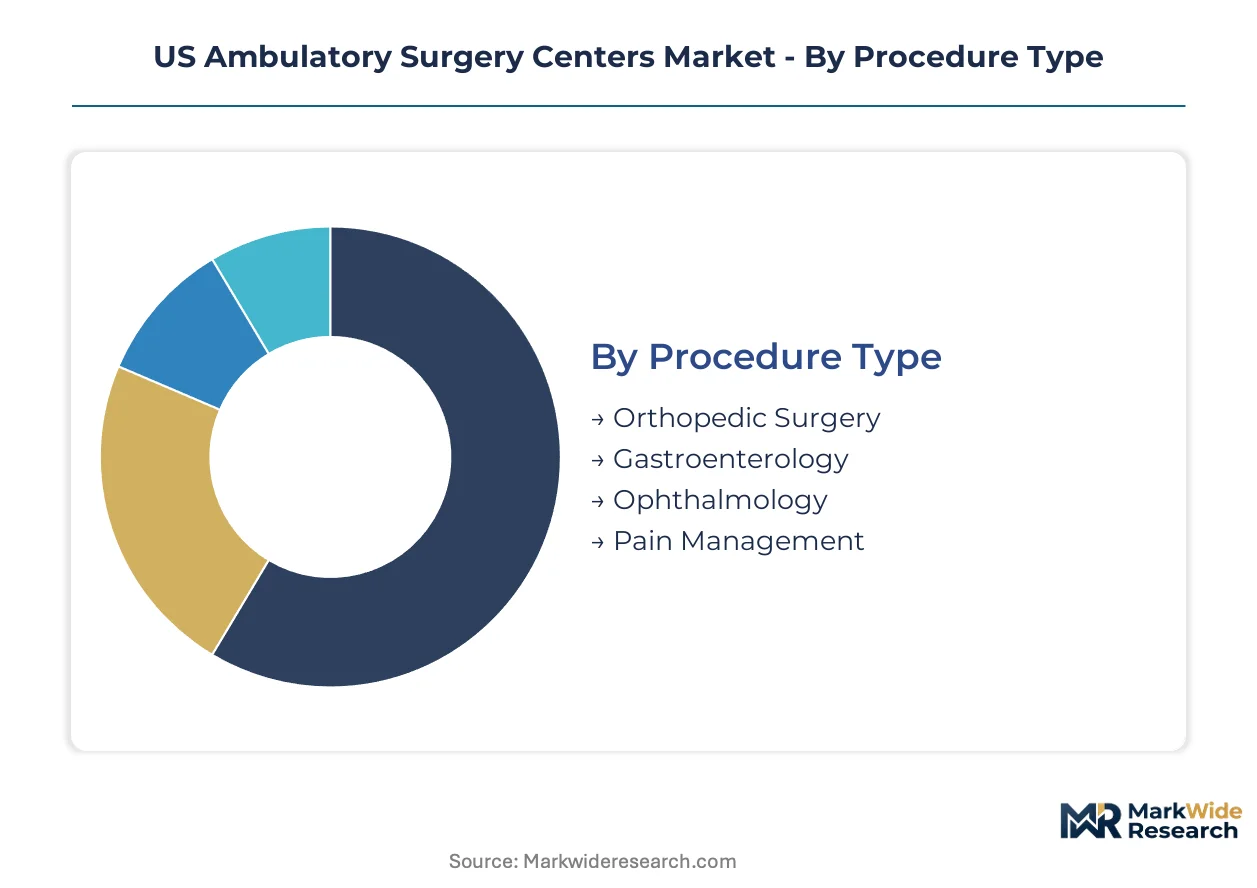
Segmentation in the US ASC market reveals how CMS reimbursement rules and state-level licensing create divergent investment returns across procedure categories and facility types. Ownership structure and technology deployment determine margin capture more than raw procedure volume.
Procedure Type:
CMS fee schedule differentiation separates high-reimbursement orthopedic procedures from volume-driven gastroenterology services.
- Orthopedic Surgery:Joint replacement and arthroscopic procedures command premium Medicare reimbursement rates. Demand concentrates in Florida and Texas metropolitan markets where Medicare Advantage plans aggressively steer elective cases toward outpatient settings.
- Gastroenterology:Colonoscopy and upper endoscopy procedures generate high annual case volumes with predictable scheduling. Screening mandates in southeastern states drive partnerships between independent centers and large physician groups.
- Ophthalmology:Cataract extraction dominates volume with short procedure times enabling high daily throughput.
- Pain Management:Spinal cord stimulator implants and radiofrequency ablation represent the category expanding most quickly as commercial payers approve outpatient neurostimulator placement.
Established volume favors gastroenterology; emerging adoption favors pain management.
End User:
Capital access and payer contracting leverage separate four distinct ownership models with divergent cost structures.
- Physician Practices:Direct physician ownership minimizes overhead through lean staffing and focused specialty concentration. Texas and North Carolina markets show dense clustering of orthopedic-focused partnerships exploiting direct employer contracting opportunities.
- Hospitals:Health system-affiliated joint ventures leverage existing payer contracts and EHR infrastructure. Hospital-integrated models sacrifice margin for volume security through captive referral networks.
- Independent Centers:Freestanding facilities maximize margin through direct payer negotiation and procedure mix optimization.
- Specialty Clinics:Single-specialty concentration enables equipment standardization and staff specialization.
Margin optimization favors physician practices; volume security favors hospital-affiliated structures.
Technology:
Equipment depreciation schedules and FDA clearance pathways determine capital deployment sequencing.
- Outpatient Surgery Systems:Robotic platforms compress procedure duration and enable complex case migration. MAKO and ROSA system deployments concentrate in capital-rich Texas partnerships with sufficient case volume to justify acquisition.
- Telehealth Solutions:Preoperative screening and postoperative monitoring reduce in-person visit requirements. Remote patient monitoring adoption accelerates in rural sub-regions facing anesthesia staffing constraints.
- Imaging Equipment:C-arm fluoroscopy and portable MRI reduce hospital dependency for intraoperative guidance.
- Anesthesia Devices:Targeted delivery systems enable moderate sedation protocols with reduced CRNA supervision requirements.
Capital efficiency favors telehealth solutions; clinical differentiation favors robotic surgery systems.
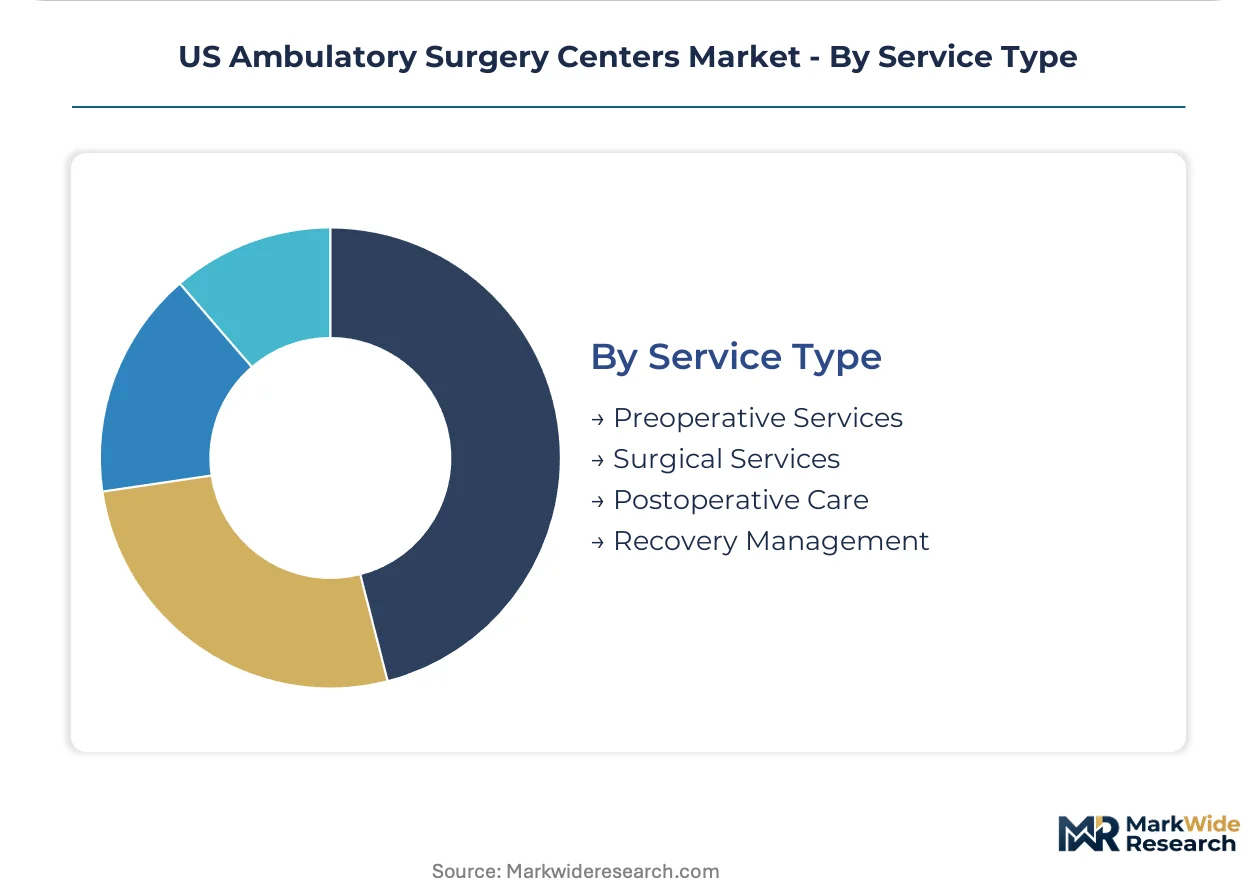
Service Type:
Staffing ratios and physical plant standards vary sharply across the surgical episode.
- Preoperative Services:Patient screening and anesthesia evaluation determine case cancellation rates. Florida centers invest heavily in preoperative nursing to minimize same-day surgical delays.
- Surgical Services:Operating room utilization drives facility economics with block scheduling optimization. Georgia independent centers achieve highest throughput through dedicated orthopedic block schedules.
- Postoperative Care:PACU staffing represents the largest variable cost category with strict Joint Commission monitoring requirements.
- Recovery Management:Discharge planning and patient education reduce emergency department bounce-backs.
Cost concentration favors postoperative care; operational leverage favors surgical services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Florida exports ASC development expertise to Georgia and the Carolinas as certificate-of-need reform spreads across the southeastern United States, reshaping facility investment patterns.
Florida
Medicare Advantage penetration and retiree population density drive orthopedic procedure demand. CMS ASC fee schedule updates expand reimbursable procedure lists annually. Miami-Dade and Tampa Bay metropolitan clusters concentrate physician-owned partnership formations exploiting direct payer contracting.
Texas
Self-insured employer density and weak hospital system consolidation enable direct bundled-rate negotiations. OSHA bloodborne pathogen standards shape clinical staffing protocols. Dallas-Fort Worth and Houston medical corridors anchor capital-rich partnerships deploying robotic surgical platforms.
Georgia
Certificate-of-need elimination accelerates independent center licensing and development timelines. Joint Commission accreditation requirements govern facility certification cycles. Atlanta metropolitan sub-region leads southeastern volume for gastroenterology-focused physician practice acquisitions.
North Carolina
Manufacturing employer self-insurance plans negotiate episode-based rates with independent centers. HIPAA privacy rules structure patient data exchange between acquired practices and hospital-system EHR platforms. Research Triangle and Charlotte metro areas concentrate pain management procedure migration.
Tennessee
Logistics and automotive employer direct contracting disrupts traditional commercial payer channels. CMS site-neutral payment proposals pressure hospital-affiliated joint venture margins. Nashville and Memphis sub-regions host SCA Health and Surgery Partners headquarters operations anchoring national management services.
US Ambulatory Surgery Centers Market Key Industry Players
Player mix skews toward hospital-affiliated joint ventures and physician-owned partnerships competing for Medicare Advantage steerage contracts. Market structure concentrates around three national management companies controlling multi-state facility networks. Strategic archetypes include integrated health system captives, independent physician partnerships, and private equity-backed consolidation platforms. Dominant competitive moves encompass certificate-of-need state expansion racing and robotic surgical platform deployment for orthopedic differentiation.
Among national-scale operators, HCA Healthcare anchors market presence through Surgery Partners affiliate networks spanning southeastern and southwestern states. Tenet Healthcare occupies a position within hospital-integrated tier structures via USPI joint ventures with nonprofit health systems. AMSURG exemplifies specialty-focused archetype concentration through exclusive gastroenterology and ophthalmology partnerships with large physician groups in metropolitan Texas and Florida markets.
| Leading Market Players |
|---|
| HCA Healthcare |
| Tenet Healthcare |
| USPI |
| SCA Health |
| AMSURG |
| Surgery Partners |
| United Surgical Partners International |
| Optum |
| Envision Healthcare |
| Others |
Cost & Logistics Intelligence
Episode-based bundled contracts with self-insured employers lock in both anesthesia staffing access and procedural price visibility for independent centers negotiating outside traditional payer networks. CMS site-neutral payment proposals compress margin differentials between freestanding ASCs and hospital outpatient departments, forcing supply chain reconfiguration toward lower-cost equipment sourcing.
Pricing Analysis
Robotic surgical platform pricing gaps separate capital-rich physician partnerships deploying MAKO and ROSA systems from independent centers relying on conventional instrumentation. Three-tier pricing structure across premium technology, standard equipment, and economy leasing arrangements reflects case volume commitments and maintenance bundling. Pricing pressure stems from Medicare's reimbursement compression as site-neutral rules narrow historical ASC premiums. Physician-owned partnerships exhibit lowest price sensitivity due to direct payer contracting leverage, while hospital-affiliated joint ventures face acute margin scrutiny from health system overhead allocation.
Supply Chain Analysis
Germany and Japan anchor precision surgical instrument manufacturing, while China dominates disposable consumables and basic anesthesia device production. Domestic ASC supply chains draw from Mexican maquiladora zones for sterilization equipment and Canadian sources for specialized implants. Single-source vulnerability concentrates in robotic platform maintenance agreements tethered to OEM service networks. Distribution runs through GPO contracts for hospital-affiliated centers and direct manufacturer relationships for independent physician partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of certified CRNA staffing in rural sub-regions constrains expansion velocity for independent centers, creating acquisition premiums for facilities with locked-in anesthesia coverage. This capability gap rewards early certificate-of-need positioning in reforming southeastern states.
For Market Incumbents: Secure anesthesia staffing through employment guarantees and training partnerships before rural supply exhaustion accelerates. Defend Medicare Advantage steerage contracts by accelerating robotic platform deployment in Texas metropolitan corridors. Consolidate independent gastroenterology centers in Florida before certificate-of-need reform saturates addressable licensing slots. For New Entrants and Emerging Players: Post-acute remote monitoring services represent underserved layers where hospital-affiliated joint ventures under-invest. Target pain management procedure migration in North Carolina Research Triangle sub-regions with direct employer contracting pitches. Pursue telehealth-enabled preoperative screening to bypass capital-intensive physical plant requirements. For Investors and Strategic Acquirers: Multi-specialty independent centers with locked-in CON approvals in Georgia and South Carolina offer the most defensible acquisition archetype. Long-term viability hinges on CMS maintaining ASC fee schedule expansion against site-neutral pressure. Watch Medicare Advantage penetration rates in Florida retiree corridors as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Certificate-of-Need Positioning | Early licensing in Georgia and the Carolinas secures addressable market before regulatory saturation. |
| Robotic Platform Deployment | MAKO and ROSA acquisition in Texas metros compresses case duration and enables Medicare Advantage contracting. |
| Direct Employer Contracting | Bypassing commercial payer intermediaries in Tennessee and South Carolina captures self-insured logistics volumes. |
| Anesthesia Staffing Lock-in | CRNA employment guarantees in rural sub-regions remove expansion constraints before supply exhaustion. |
| Gastroenterology Partnership Formation | Colonoscopy screening mandates in Florida concentrate demand with large physician groups. |
Research Approach
Cross-validation between CMS Medicare cost report data and state-level certificate-of-need filing records anchors the qualitative findings on facility development patterns. Primary interviews with ASC administrators, anesthesiologist group practice managers, hospital system joint venture directors, and GPO contracts specialists combine with secondary validation from CMS ASC fee schedule updates, OSHA enforcement databases, Joint Commission accreditation records, and state health department licensing filings. Bottom-up facility count triangulation against top-down Medicare reimbursement flow analysis ensures dimensional consistency.
Sensitivity analysis around CMS site-neutral payment implementation timing and Medicare Advantage penetration trajectories shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include procedure category, ownership structure, technology deployment tier, and service type with state-level regulatory cluster overlays. CAGRs derive from procedure volume elasticity to reimbursement rate changes and demographic screening mandate expansion. Forecast inputs incorporate anesthesia staffing supply curves and robotic platform depreciation schedules.
Underlying assumptions cover CMS fee schedule continuation, CON reform stability, and commercial payer outpatient authorization trends, with deviation risk concentrated in federal site-neutral rule acceleration and state-level regulatory reversal. Recalibration cycles align with material shifts in Medicare Advantage enrollment patterns and certificate-of-need legislative action.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Facilities
US Skilled Nursing Facility and Rehabilitation Market
Healthcare Facilities
Ambulatory Surgical Centers Market
Healthcare Facilities
US Ambulatory Surgical Centers Market
Healthcare Facilities
Mobile Hospitals Market
Healthcare Facilities
US Assisted Living Facility Market
Healthcare Facilities
Assisted Living Facilities Market
Healthcare Facilities
Qatar Senior Living Market
Healthcare Facilities
Global Ambulatory Surgery Centers (Ascs) Market
Healthcare Facilities
US Skilled Nursing Facility Market
Healthcare Facilities
Trauma Care Centers Market
Healthcare Facilities
Global Healthcare Architecture Market
Healthcare Facilities
Private Office-Based Clinics Market
Healthcare Facilities
US and Europe Ambulatory Surgery Centers Market
Healthcare Facilities
US Hospital Facilities Market
Healthcare Facilities
Global Healthcare Facilities Management Market
Healthcare Facilities
Hospital Lighting Market