
 US Office-Based Labs Market | 2026-2036
US Office-Based Labs Market Size, Share, and Industry Trends Forecast 2026-2036
US Office-Based Labs Market Intelligence
Subscription-based maintenance contracts for imaging and surgical equipment is hardening into the core revenue model for device vendors serving office-based labs. Siemens Healthineers AG leverages long-term service agreements to sustain recurring revenue streams across cardiology and gastroenterology installations. GE Healthcare anchors its competitive stance through predictive maintenance software that reduces equipment downtime in high-throughput physician practices. Abbott differentiates by embedding point-of-care diagnostic connectivity into lab workflows, creating stickier provider relationships.
US office-based labs are clinical facilities operated by physicians within non-hospital settings, equipped with fluoroscopy, ultrasound, endoscopy, and minor surgical suites that meet ASC-level sterility and imaging resolution standards for same-day diagnostic and interventional procedures. Imaging Systems and Diagnostic Equipment represent mature, high-margin categories where replacement cycles and AI-enhanced image processing drive upgrade revenue. Treatment Devices in pain management and cardiology applications capture the fastest expansion as specialists move spinal cord stimulator trials and peripheral vascular interventions out of hospital outpatient departments.
FDA device clearance pathways, CMS site-neutral payment rules, and state-level certificate-of-need regulations collectively determine which procedures migrate to office-based settings and what equipment qualifies for reimbursement. OSHA bloodborne pathogen standards and state radiology licensing boards impose facility compliance costs that favor larger multi-specialty lab operators over solo practitioners. Stakeholders must monitor whether proposed CMS cuts to office-based lab fee schedules reverse the procedural migration trend or accelerate consolidation into scaled platform operators.
Market Dynamics
CMS site-neutral payment policies are compressing reimbursement differentials between hospital outpatient departments and physician-owned facilities, redirecting capital toward ASC-level sterility suites and fluoroscopy-equipped procedure rooms in cardiology and gastroenterology practices.
Growth Catalysts
- Texas-Florida-Arizona physician rollouts:Specialist practices in these states are accelerating lab buildouts to capture shifting procedural volumes from hospital systems.
- IRA site-neutral payment expansion:The Inflation Reduction Act's payment parity provisions strengthen the economic case for office-based interventional procedures.
- AI-enhanced image processing:Real-time fluoroscopic guidance and automated lesion detection reduce procedure times and expand treatable patient populations.
Market Restraints
- Certificate-of-need state barriers:New York, Illinois, and Washington maintain CON laws that block physician-owned lab entry despite federal payment incentives.
- Specialized technician scarcity:Radiologic technologists with fluoroscopy and endoscopy certification command premium wages in competitive metropolitan markets.
- Equipment financing costs:Rising interest rates extend payback periods for C-arm and ultrasound systems, squeezing solo practitioner margins.
Strategic Opportunities
- Spinal cord stimulator trials:Pain management specialists are migrating temporary implant procedures from hospital settings to office-based suites.
- OSHA bloodborne pathogen compliance services:Third-party safety consultants can capture recurring revenue from multi-specialty lab operators seeking scaled compliance infrastructure.
- Remote patient monitoring integration:Post-procedure cardiac and vascular monitoring creates new revenue streams tethered to initial intervention sites.
Industry Challenges
- Multi-state licensing complexity:Physician owners expanding across Texas, Florida, and Arizona face fragmented radiology supervisor and facility accreditation requirements.
- ASC-level sterility retrofit costs:Converting existing medical office space to meet Joint Commission or AAAHC surgical standards demands HVAC, flooring, and sterilization infrastructure investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Office-Based Labs Market |
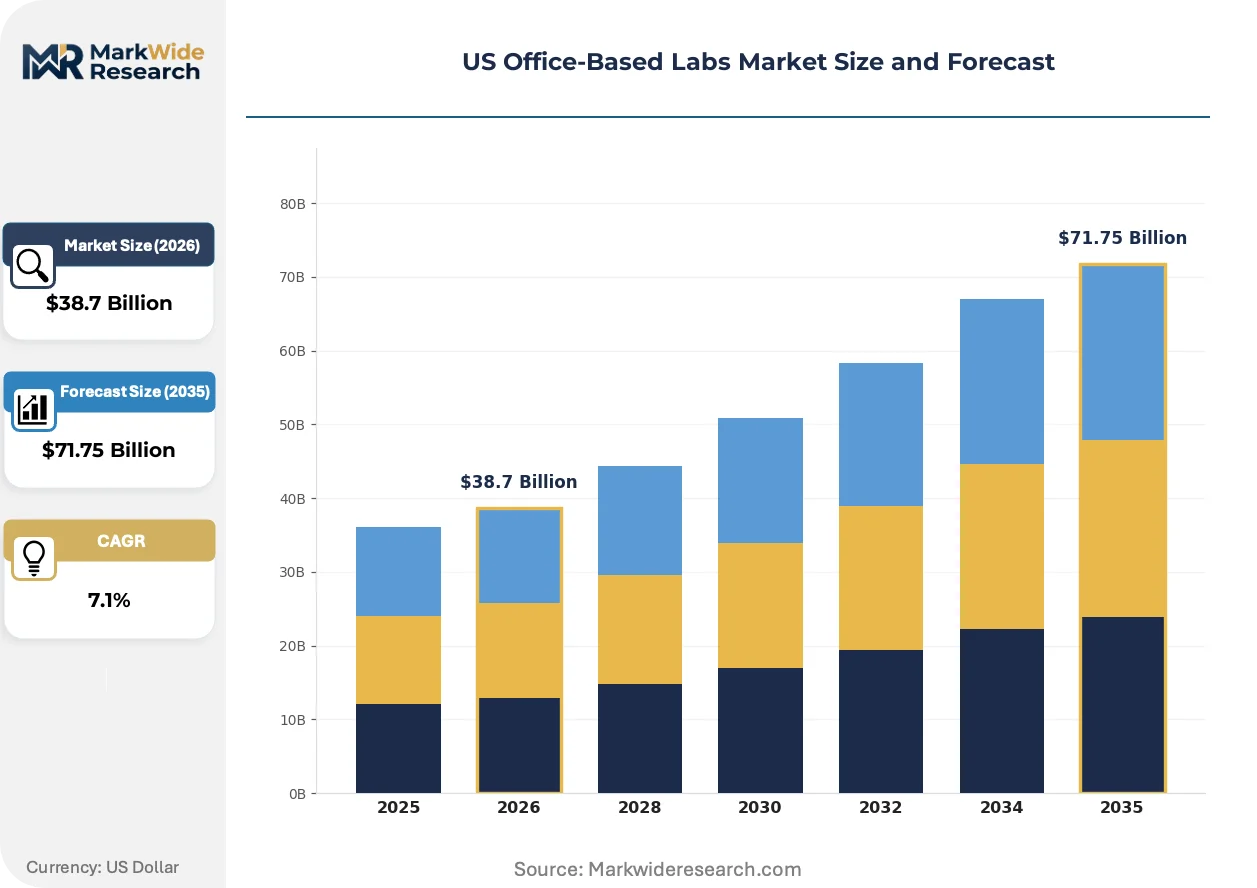
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $71.75 Billion |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Systems, Surgical Instruments, Diagnostic Equipment, Treatment Devices End User: Physicians, Surgeons, Specialists, Technicians Application: Pain Management, Cardiology, Gastroenterology, Dermatology Service Type: Consulting, Maintenance, Training, On-Site Services |
| Companies Covered | GE Healthcare, Siemens Healthineers AG, Medtronic PLC, Boston Scientific Corporation, Abbott, Koninklijke Philips N.V., Cardiovascular Systems, Inc., Surgical Care Affiliates, Surgery Partners, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Office-Based Labs Market Strategic Shifts & Innovations
Device vendors and physician operators are converging on predictive service models and point-of-care connectivity that reduce equipment downtime and tighten clinical workflow integration.
AI-powered fluoroscopic guidance is integrating real-time anatomical mapping and lesion characterization into peripheral vascular and cardiac catheterization procedures. Interventional cardiologists in high-throughput Texas and Florida practices are adopting these systems to reduce contrast dye volumes and radiation exposure. The technology is integrating procedure standardization across physician-owned networks, enabling consistent outcomes measurement that satisfies payor quality reporting requirements.
CMS site-neutral payment rules are eliminating reimbursement premiums for hospital outpatient department procedures, flattening the economic playing field for office-based alternatives. The policy shift compresses capital deployment timelines as specialists accelerate ASC-level lab construction to capture migrated volumes. Cardiology and gastroenterology practices in Arizona and Florida are responding by bundling facility fees into episode-based contracts with commercial payors.
Subscription-based equipment maintenance is displacing transactional service calls as the dominant vendor-provider relationship model. Siemens Healthineers and GE Healthcare are unbundling predictive maintenance software from hardware sales, creating recurring revenue streams tied to uptime guarantees. This shift concentrates most visibly in multi-site cardiology groups across Texas metropolitan corridors where equipment standardization reduces training and inventory costs.
US Office-Based Labs Market Segmentation
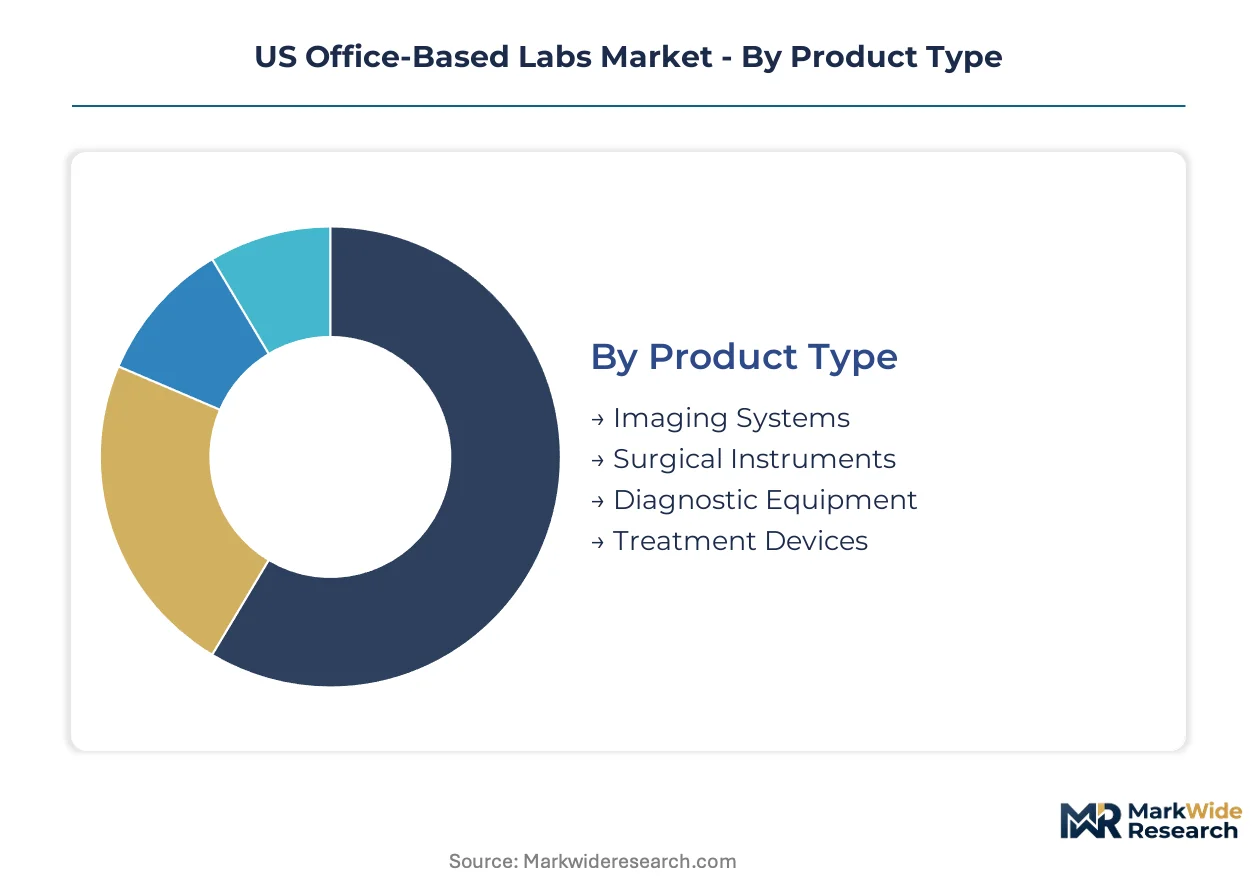
Segmentation reveals how capital flows diverge between standalone imaging suites and embedded diagnostic systems across physician practices. Equipment procurement patterns vary sharply by procedural volume and reimbursement pathway.
Product Type:
Imaging systems operate as standalone capital installations requiring dedicated procedure rooms, while surgical instruments and diagnostic equipment embed into integrated workflows with tighter vendor lock-in.
- Imaging Systems:Fluoroscopy C-arms, ultrasound platforms, and digital radiography units deliver real-time anatomical visualization for interventional procedures. Texas and Florida cardiology groups concentrate replacement demand here as AI-enhanced image processing drives upgrade cycles amid site-neutral payment expansion.
- Surgical Instruments:Sterile disposable and reusable tools for minor procedures including biopsy forceps, electrocautery devices, and suturing equipment. Arizona gastroenterology practices embed these into ASC-level suites to capture migrated endoscopic volumes from hospital outpatient departments.
- Diagnostic Equipment:Point-of-care analyzers and pathology workstations enabling same-day results.
- Treatment Devices:Spinal cord stimulators, peripheral vascular intervention tools, and cardiac ablation systems.
Volume placements concentrate in Imaging Systems; the faster expansion belongs to Treatment Devices.
End User:
Procurement authority shifts from individual practitioners to consolidated purchasing groups as multi-site cardiology networks scale across metropolitan corridors.
- Physicians:Primary care and specialty clinicians operating solo or small-group practices with direct equipment acquisition decisions. Solo practitioners in Texas face extended financing payback periods for C-arm systems amid rising interest rates, compressing margins and accelerating consolidation into larger platforms.
- Surgeons:Orthopedic, vascular, and general surgeons performing incision-based procedures requiring sterile field maintenance. Florida surgical groups drive demand for ASC-level sterility retrofits as procedural migration accelerates under IRA payment parity provisions.
- Specialists:Cardiologists, gastroenterologists, and pain management physicians with procedure-heavy practice models.
- Technicians:Radiologic technologists and endoscopy nurses operating equipment under physician supervision.
Procurement volume clusters with Specialists; Technicians are gaining influence fastest through equipment usability requirements.
Application:
Reimbursement velocity determines application attractiveness, with cardiology and pain management leading procedural migration while dermatology lags due to lower facility fee differentials.
- Pain Management:Spinal cord stimulator trials, nerve blocks, and injection therapies performed in office-based suites. Arizona pain specialists are expanding fastest here as temporary implant procedures shift from hospital settings, supported by commercial payor episode-based contracting.
- Cardiology:Diagnostic catheterization, peripheral vascular intervention, and electrophysiology procedures requiring fluoroscopy and hemodynamic monitoring. Texas metropolitan practices anchor demand as AI-powered fluoroscopic guidance reduces contrast volumes and radiation exposure.
- Gastroenterology:Colonoscopy, upper endoscopy, and advanced interventional procedures.
- Dermatology:Mohs surgery, cosmetic procedures, and minor excisions with lower capital intensity.
Cardiology captures the steepest placement volume; Pain Management is climbing the fastest as reimbursement parity matures.
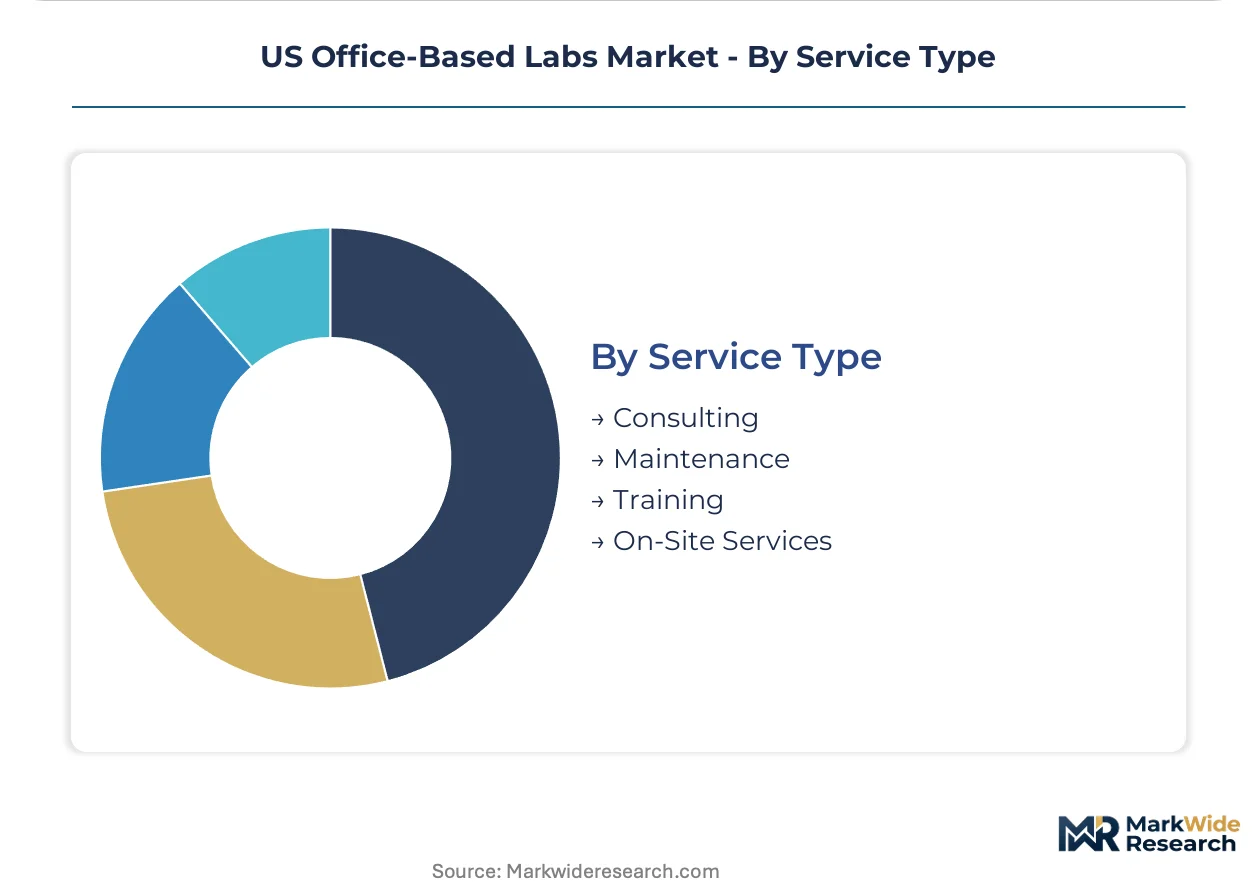
Service Type:
Vendor business models pivot from transactional hardware sales toward recurring revenue streams tethered to uptime guarantees and workflow integration.
- Consulting:Regulatory compliance, facility design, and operational efficiency advisory for new lab construction. Multi-specialty operators across Texas and Florida engage consultants to navigate fragmented state licensing and OSHA bloodborne pathogen standards.
- Maintenance:Preventive service contracts, predictive software subscriptions, and emergency repair coverage. Predictive maintenance platforms from major vendors displace break-fix models as cardiology groups standardize equipment across metropolitan networks.
- Training:Physician and staff certification on new imaging and interventional systems.
- On-Site Services:Embedded technical support and procedure-day assistance for high-complexity cases.
Maintenance contracts dominate recurring revenue; Consulting is expanding most quickly amid sterility retrofit demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment production concentrates in established manufacturing hubs while procedural demand clusters in Sun Belt metropolitan corridors. Texas, Florida, and Arizona anchor consumption growth as physician-owned lab construction accelerates. Rust Belt states retain legacy manufacturing capacity but face regulatory barriers to new facility entry.
Texas
Metropolitan Dallas-Fort Worth and Houston corridors drive imaging system procurement as multi-site cardiology networks standardize fluoroscopy platforms. CMS site-neutral payment rules strengthen the economic case for ASC-level lab construction. Texas physician groups in Austin and San Antonio are bundling facility fees into episode-based contracts with commercial payors.
Florida
Gastroenterology and pain management practices in Miami-Dade and Tampa Bay markets expand endoscopy suite capacity. The state's absence of certificate-of-need laws enables rapid facility licensing compared to Northeast markets. Orlando and Jacksonville surgical groups drive demand for sterility retrofit consulting services.
Arizona
Phoenix and Tucson pain specialists migrate spinal cord stimulator trials from hospital outpatient departments. IRA payment parity provisions compress reimbursement differentials that previously favored hospital settings. Flagstaff and Prescott cardiology practices adopt AI-enhanced fluoroscopic guidance systems to reduce procedure times.
California
Los Angeles and San Francisco Bay Area multi-specialty groups face OSHA bloodborne pathogen compliance costs that favor scaled operators over solo practitioners. The state's radiology licensing boards impose technician certification requirements that constrain rapid expansion. San Diego physician networks concentrate procurement authority through consolidated purchasing groups.
New York
Certificate-of-need laws block physician-owned lab entry despite federal payment incentives. Metropolitan hospital systems retain procedural volumes that migrate to office-based settings elsewhere. Buffalo and Rochester specialists face constrained capital deployment options compared to Sun Belt counterparts.
US Office-Based Labs Market Key Industry Players
Capital-heavy imaging system manufacturers compete with asset-light service and consulting providers for share of physician lab budgets. The vendor structure concentrates around three tiers: diversified medical technology conglomerates with full imaging portfolios, specialized interventional device companies with procedure-specific tools, and third-party compliance and operational consulting firms. Dominant competitive moves include predictive maintenance software unbundling from hardware sales and multi-year service contract anchoring to reduce customer churn.
Among diversified imaging manufacturers, GE Healthcare and Siemens Healthineers AG exemplify the capital-intensive archetype with long-term service agreement strategies. Abbott occupies a position bridging diagnostic equipment and point-of-care connectivity integration. These three companies represent contrasting approaches to recurring revenue generation through subscription-based maintenance models rather than transactional equipment sales.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers AG |
| Medtronic PLC |
| Boston Scientific Corporation |
| Abbott |
| Koninklijke Philips N.V. |
| Cardiovascular Systems, Inc. |
| Surgical Care Affiliates |
| Surgery Partners |
| Others |
Cost & Logistics Intelligence
AI-enhanced fluoroscopy tiering separates premium imaging platforms from commodity C-arm systems, with that bifurcation manifesting in both subscription-based maintenance pricing and concentrated vendor supply relationships anchored to Siemens Healthineers and GE Healthcare service networks. Cardiology groups in Texas and Florida face divergent capital deployment timelines depending on which tier they select, while supply chain dependencies for advanced image processing components tighten vendor lock-in.
Pricing Analysis
Margin tightening in imaging equipment reflects CMS site-neutral payment compression and extended financing payback periods for solo practitioners. Subscription-based maintenance contracts dominate vendor-provider relationships, with price differentiation resting on AI software bundling and predictive uptime guarantees. Cost-down pressure accelerates as rising interest rates squeeze small-group cardiology practices, making multi-specialty networks the least price-sensitive buyers due to volume scale and consolidated procurement authority.
Supply Chain Analysis
Single-source vulnerability sits with specialized fluoroscopy tube manufacturers in Germany and Japan, where precision imaging component production concentrates. Supply chains draw from rare earth elements for detector arrays, semiconductor chips for image processing, and sterile disposable manufacturing in Mexico and Costa Rica. Tariff exposure on Chinese-sourced electronic components presents structural risk. Distribution runs through manufacturer-direct sales teams and third-party medical equipment financiers serving physician-owned practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US office-based labs represent a consolidation play as CMS reimbursement compression and certificate-of-need regulatory fragmentation force undercapitalized solo practitioners toward scaled platform operators.
For Market Incumbents: Acquire distressed cardiology practice assets in Texas and Florida metropolitan corridors to capture migrating procedural volumes. Defensive positioning demands embedding predictive maintenance software deeper into workflow integration to raise switching costs against emerging AI-native imaging vendors. Consolidate purchasing authority across multi-site networks to offset margin pressure from extended equipment financing terms. For New Entrants and Emerging Players: Enter via OSHA bloodborne pathogen compliance consulting services targeting Arizona and Florida multi-specialty lab operators facing sterility retrofit mandates. Pain management spinal cord stimulator trials offer the most penetrable application segment as hospital outpatient migration accelerates under IRA payment parity. A go-to-market angle tethering remote patient monitoring integration to initial intervention sites captures recurring revenue stickiness. For Investors and Strategic Acquirers: Re-rating potential sits with scaled platform operators possessing consolidated GPO contracts and cross-state licensing infrastructure given CMS site-neutral payment expansion. Long-term viability over the next decade favors multi-specialty networks with proven episode-based contracting capabilities. Watch for proposed CMS fee schedule cuts as the critical inflection signal determining whether procedural migration accelerates or reverses.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enhanced Fluoroscopy Platform Launch | Reduces contrast dye volumes and radiation exposure in Texas cardiology practices. |
| Multi-State Licensing Infrastructure Buildout | Enables rapid Arizona-Florida-Texas expansion amid fragmented radiology supervisor requirements. |
| Predictive Maintenance Software Unbundling | Creates recurring revenue streams tied to uptime guarantees for GE Healthcare and Siemens. |
| Episode-Based Payor Contracting | Bundles facility fees with commercial insurers in Dallas-Fort Worth and Houston markets. |
| OSHA Compliance Service Acquisition | Captures recurring revenue from multi-specialty operators seeking scaled safety infrastructure. |
Research Approach
FDA 510(k) filings, CMS Medicare cost report data, and state certificate-of-need regulatory databases formed the secondary backbone, supplemented by primary interviews with interventional cardiologists, GPO contracts managers, biomedical equipment financiers, and sterility retrofit consultants. Bottom-up and top-down triangulation validated equipment procurement patterns and reimbursement pathway shifts across the analysis window.
Bottom-up modeling aggregated procedure volume projections by cardiology, gastroenterology, and pain management application segments, while top-down analysis cross-checked capital expenditure patterns against site-neutral payment policy impacts. Modeled dimensions included product type, end-user procurement authority, application reimbursement velocity, and service type recurring revenue potential. CAGRs derived from equipment replacement cycle timing and AI upgrade adoption curves in high-throughput physician practices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt CMS fee schedule revisions or CON law expansion in currently unrestricted states. Forecasts reflect documented assumptions regarding IRA payment parity implementation pace and technician wage inflation in competitive metropolitan markets. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Facilities
Micro-Hospitals Market
Healthcare Facilities
Mobile Hospitals Market
Healthcare Facilities
US and Europe Ambulatory Surgery Centers Market
Healthcare Facilities
Private Office-Based Clinics Market
Healthcare Facilities
Bedless Hospitals Market
Healthcare Facilities
US Ambulatory Surgery Centers Market
Healthcare Facilities
Global Ambulatory Surgery Centers (Ascs) Market
Healthcare Facilities
Ambulatory Surgical Centers Market
Healthcare Facilities
US Skilled Nursing Facility and Rehabilitation Market
Healthcare Facilities
Trauma Care Centers Market
Healthcare Facilities
Assisted Living Facilities Market
Healthcare Facilities
Qatar Senior Living Market
Healthcare Facilities
Global Healthcare Facilities Management Market
Healthcare Facilities
US Assisted Living Facility Market
Healthcare Facilities
Confinement Center Market
Healthcare Facilities
US Ambulatory Surgical Centers Market