
 Assisted Living Software Market | 2026-2036
Assisted Living Software Market Size, Share, and Industry Trends Forecast 2026-2036
Assisted Living Software Market Analysis
HIPAA interoperability mandates are broadening the cost-of-entry calculus for new assisted living software vendors. PointClickCare leverages deep integration with pharmacy and billing networks to sustain competitive moats. WellSky anchors its position through specialized post-acute care workflows that dominate skilled nursing transitions. Eldermark competes on purpose-built tools for smaller independent operators navigating compliance complexity.
Assisted living software encompasses integrated digital platforms that automate resident care planning, medication administration tracking, financial billing, and staff scheduling across senior care facilities. These systems typically operate on cloud-native architectures with API connectivity to electronic health records, enabling real-time data exchange between caregivers, physicians, and family portals. Care Management modules lead product type demand as facilities prioritize fall prevention, wound care protocols, and chronic disease monitoring. Cloud-Based deployment is expanding fastest among multi-site operators seeking centralized oversight, while On-Premise installations retain footholds in regions with stringent data sovereignty requirements. Senior Living Communities represent the core end-user segment, though Home Care Agencies are emerging as a distinct growth vector for mobile-first platforms.
FDA oversight of software-as-a-medical-device intersects with CMS reimbursement rules to shape product development roadmaps and go-to-market timing. State-level Medicaid agencies impose additional certification requirements that fragment vendor compliance burdens across jurisdictions. Stakeholders must weigh interoperability investments against the risk of stranded technology assets as federal standards consolidate.
Market Dynamics
Cloud-native architectures are compressing deployment timelines for multi-facility operators while HIPAA interoperability mandates force legacy system overhauls across US senior care networks.
Growth Catalysts
- Interoperability Mandates:HIPAA regulations in the United States compel electronic health record integration, accelerating replacement cycles for outdated on-premise installations.
- Fall Prevention Protocols:Care Management modules embed sensor-driven analytics to reduce liability exposure and insurance premiums for senior living communities.
- Germany:Multi-site operators in Germany prioritize centralized oversight tools, driving cloud-based procurement across Bavaria and North Rhine-Westphalia.
Market Restraints
- Data Sovereignty Requirements:Regional data localization laws in Australia and Japan fragment vendor compliance architectures and inflate engineering overhead.
- Skilled Nursing Transitions:Specialized post-acute care workflows demand costly customization, squeezing margins for platforms serving mixed-use facilities.
- Legacy Hardware Dependencies:On-premise server farms in smaller independent operators create stranded asset risks during cloud migration.
Strategic Opportunities
- Home Care Agencies:Mobile-first platforms capture emerging demand from aging-in-place populations requiring remote monitoring outside facility walls.
- API Convergence:Real-time data exchange between pharmacy networks, family portals, and physician dashboards creates integrated care ecosystem lock-in.
- Medicaid Certification:State-level certification requirements in the United States fragment vendor landscapes, opening niche compliance service revenue streams.
Industry Challenges
- Caregiver Technology Adoption:Frontline staff resistance to digital documentation tools slows implementation velocity and undermines data quality.
- CMS Reimbursement Alignment:Software-as-a-medical-device classification intersects with evolving CMS rules, complicating product roadmaps and go-to-market timing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Assisted Living Software Market |
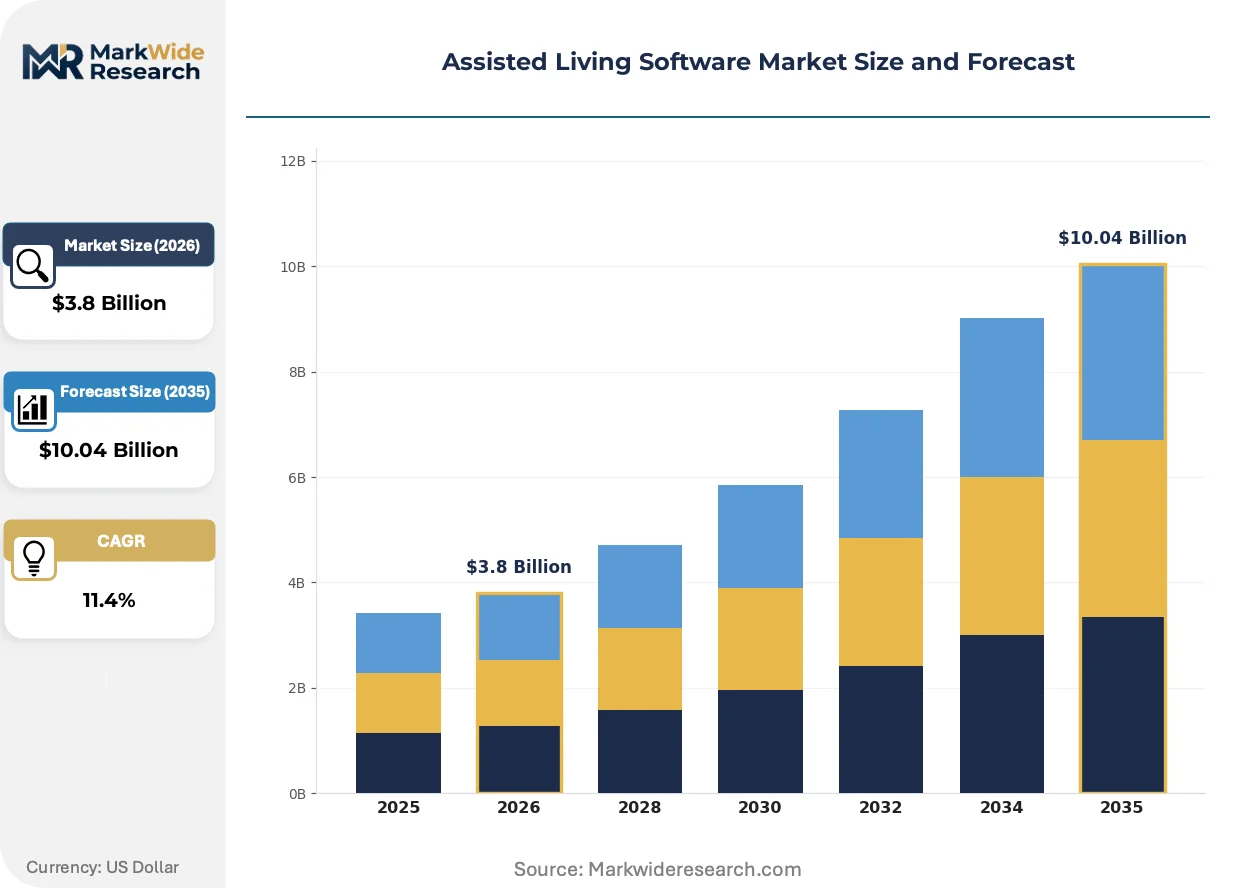
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Care Management, Financial Management, Resident Management, Medication Management Deployment: On-Premise, Cloud-Based, Hybrid, Enterprise End User: Senior Living Communities, Nursing Homes, Home Care Agencies, Adult Day Care Centers Feature: Billing Solutions, Scheduling Tools, Reporting Analytics, Communication Portals |
| Companies Covered | Eldermark, PointClickCare, DosePacker, AlayaCare, WellSky, MatrixCare, Yardi, Caremerge, ECP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Assisted Living Software Market Emerging Trajectories
Artificial intelligence and ambient sensing technologies are compressing response times for critical resident events while regulatory pressure accelerates platform consolidation.
Passive infrared and radar-based fall detection systems is expanding into resident rooms and common areas without wearable dependencies. Senior living communities in Japan and Australia are piloting these sensor arrays to reduce nighttime staffing ratios. The technology is expanding into liability reduction strategies for multi-facility operators seeking insurance premium relief.
MDR certification requirements in Europe are elevating clinical evidence standards for software designated as medical devices. Vendors must now submit technical documentation and post-market surveillance plans to notified bodies before commercial deployment. German and Swiss operators increasingly prioritize CE-marked platforms to preempt liability exposure.
Family portal engagement patterns are shifting from passive information consumption to active care plan collaboration. Adult children of residents now expect real-time medication adherence visibility and direct messaging with care teams. This behavioral pivot is most pronounced in US markets where consumer expectations mirror retail healthcare experiences.
Assisted Living Software Market Segmentation
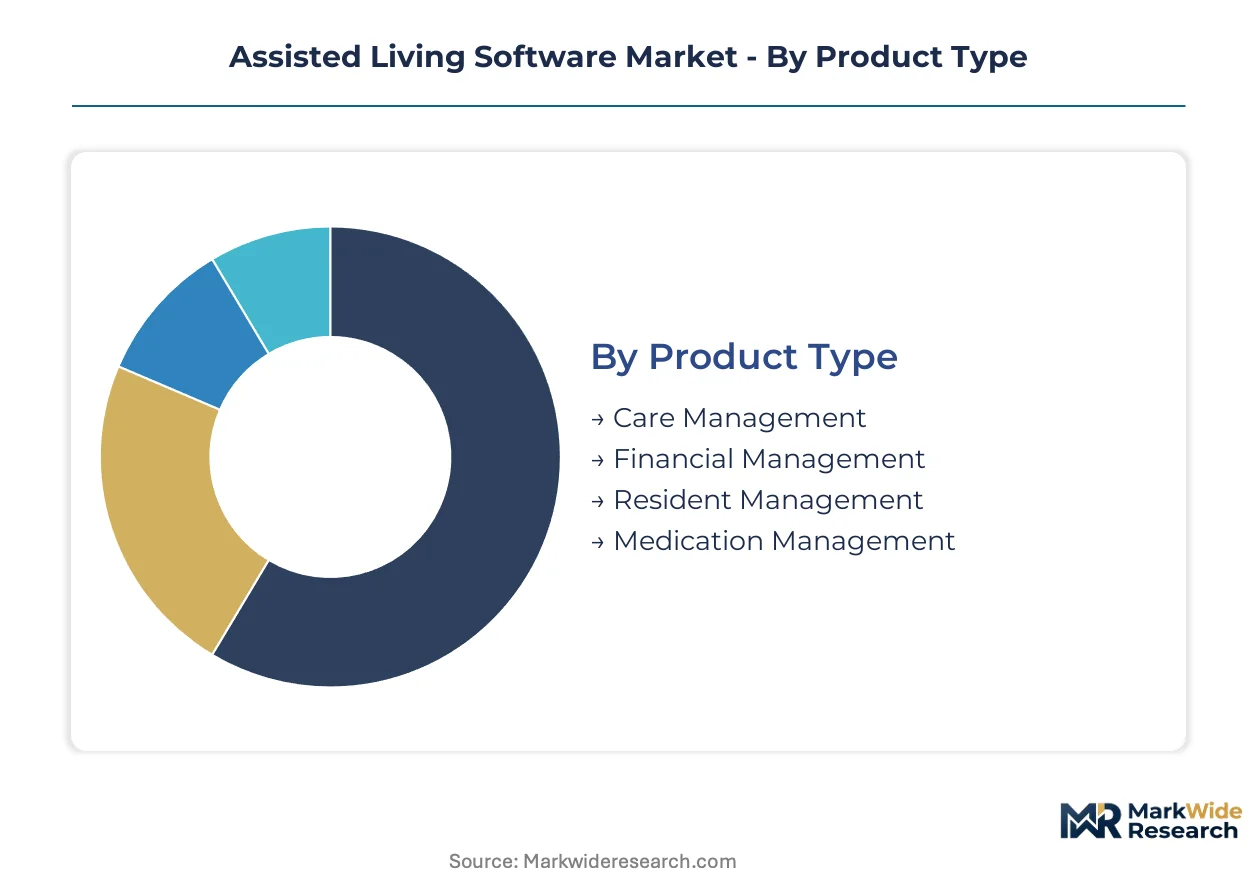
Segmentation in assisted living software reflects divergent operational maturity across facility types. Cloud-native platforms serve multi-site operators with centralized compliance needs, while modular point solutions address independent operators with constrained IT budgets.
Product Type:
Customization intensity varies sharply across this category, with clinical modules demanding specialized workflows versus administrative tools permitting standardized deployments.
- Care Management:Platforms orchestrate fall prevention protocols, wound care documentation, and chronic disease monitoring through integrated care plans. Demand concentrates in US senior living communities facing HIPAA interoperability mandates and liability reduction priorities. Sensor-driven analytics embedded within these modules compress emergency response times while lowering insurance premiums.
- Financial Management:Systems automate Medicaid billing reconciliation, private-pay invoicing, and occupancy-based revenue recognition across mixed payer environments. German multi-facility operators prioritize these tools to navigate complex long-term care insurance reimbursement structures. Real-time integration with pharmacy networks prevents revenue leakage from medication billing errors.
- Resident Management:Databases track admission workflows, family communication preferences, and discharge planning milestones.
- Medication Management:Modules enforce eMAR compliance, allergy cross-checks, and controlled substance audit trails.
Leading the category by volume: Care Management. Growing fastest: Medication Management.
Deployment:
Cost tier stratification dominates procurement decisions, with capital expenditure constraints separating enterprise deployments from subscription-based alternatives.
- Cloud-Based:Architectures enable centralized oversight across distributed facilities with automatic security patching and API connectivity to EHR networks. Australian and Japanese multi-site operators favor these deployments despite data sovereignty compliance burdens. HIPAA mandates in the United States accelerate replacement of legacy installations with cloud-native alternatives.
- On-Premise:Installations retain footholds where regional data localization laws mandate physical server control within national boundaries. Smaller independent operators in Germany maintain these systems to satisfy Bavarian and North Rhine-Westphalian data residency requirements. Stranded asset risks emerge as federal standards consolidate around interoperability frameworks.
- Hybrid:Configurations isolate sensitive resident data on local servers while routing administrative functions to cloud infrastructure.
- Enterprise:Deployments bundle dedicated instance isolation with custom development environments for large operator chains.
Expanding most quickly: Cloud-Based. Retaining largest installed base: On-Premise.
End User:
Application complexity separates institutional facilities requiring comprehensive platforms from emerging segments demanding mobile-first simplicity.
- Senior Living Communities:Independent living, assisted living, and memory care facilities deploy integrated suites spanning clinical, operational, and family engagement functions. US operators lead procurement volume as CMS reimbursement alignment forces software upgrades. Fall detection sensor arrays and family portal collaboration tools rank highest in RFP priorities.
- Home Care Agencies:Providers serving aging-in-place populations require lightweight mobile applications with GPS-verified visit documentation and remote monitoring connectivity. Demand is climbing fastest in Japan where METI policies promote community-based care alternatives to institutionalization. Battery-optimized field worker apps with offline synchronization distinguish competitive offerings.
- Nursing Homes:Skilled nursing facilities prioritize post-acute care workflow integration with hospital discharge systems.
- Adult Day Care Centers:Part-time care providers seek scheduling-centric tools with transportation coordination features.
Dominating procurement spend: Senior Living Communities. Steepest expansion trajectory: Home Care Agencies.
Feature:
Margin profiles diverge between commoditized administrative functions and specialized analytics commanding premium pricing.
- Reporting Analytics:Dashboards aggregate quality metrics, regulatory compliance scores, and predictive risk indicators for executive decision-making. Swiss and German operators increasingly demand CE-marked analytics modules under MDR certification requirements for software-as-a-medical-device. Real-time visualization of fall patterns and medication variance trends supports insurance negotiations.
- Communication Portals:Family-facing interfaces enable direct messaging with care teams, photo sharing, and care plan collaboration. Adult children of US residents drive adoption through consumer expectations shaped by retail healthcare experiences. Passive consumption is giving way to active participation in medication adherence monitoring.
- Billing Solutions:Engines automate claims scrubbing, denial management, and payer-specific formatting rules.
- Scheduling Tools:Systems optimize staff-to-resident ratios against regulatory minimums and union contract constraints.
Commanding premium pricing: Reporting Analytics. Gaining share fastest: Communication Portals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Bavaria and North Rhine-Westphalia concentrate German vendor development, while HIPAA compliance zones in the United States drive replacement demand. Japanese METI-designated community care districts accelerate mobile-first adoption.
United States
HIPAA interoperability mandates force legacy system overhauls across senior care networks. CMS reimbursement alignment pressures operators toward certified platforms. California and Florida senior living clusters lead procurement volume for fall detection sensor arrays.
Germany
Complex long-term care insurance reimbursement structures prioritize financial management automation. MDR certification requirements elevate clinical evidence standards for software-as-a-medical-device. Bavarian multi-facility operators drive cloud procurement despite North Rhine-Westphalian data residency constraints.
Japan
METI policies promoting community-based care alternatives expand mobile-first platform demand. Battery-optimized field worker apps with offline synchronization capture aging-in-place populations. Tokyo and Osaka metropolitan clusters pilot radar-based fall detection to reduce nighttime staffing ratios.
Australia
Regional data localization laws fragment vendor compliance architectures and inflate engineering overhead. TGA oversight intersects with state-level aged care quality standards. New South Wales and Victoria multi-site operators favor centralized oversight tools despite sovereignty burdens.
United Kingdom
NHS digital transformation programs accelerate EHR integration requirements for care providers. CQC regulatory pressure elevates documentation and reporting standards. London and Southeast England senior living clusters prioritize family portal collaboration tools.
Assisted Living Software Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressures favor platforms with deep pharmacy and billing network integrations. Three archetypes dominate: enterprise suite vendors, post-acute workflow specialists, and compliance-focused independents. M&A activity concentrates around API connectivity assets while vertical integration into sensor hardware emerges as a defensive maneuver.
Within the enterprise suite tier, PointClickCare and WellSky occupy anchor positions representing divergent specialization vectors—pharmacy-billing integration depth versus post-acute workflow dominance. Eldermark exemplifies the independent operator-focused archetype, navigating compliance complexity for smaller footprints. These three entities collectively illustrate how vendor positioning stratifies across integration depth, clinical specialization, and target facility scale.
| Leading Market Players |
|---|
| Eldermark |
| PointClickCare |
| DosePacker |
| AlayaCare |
| WellSky |
| MatrixCare |
| Yardi |
| Caremerge |
| ECP |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure cost indices cascading from hyperscaler pricing resets compress margin structures for SaaS vendors while amplifying tier separation between enterprise-grade and independent-operator offerings. HIPAA compliance engineering and MDR certification documentation concentrate cost burdens upstream, forcing subscription pricing to stratify by integration depth and regulatory coverage.
Pricing Analysis
Short lead-time premiums for rapid HIPAA-compliant deployments command 15-25% subscription markups over standard implementation cycles, while surplus on-premise license inventory from legacy migrations trades at distressed spot rates. Pricing stratifies across enterprise, mid-market, and independent tiers based on EHR integration complexity and state-level Medicaid certification coverage. Cost compression in the mid-market tier intensifies as PointClickCare and WellSky bundle pharmacy network connectivity into base subscriptions. Independent operators exhibit highest price sensitivity due to constrained IT capital budgets, while multi-facility chains prioritize total cost of ownership over sticker price.
Supply Chain Analysis
Reverse-logistics flows for decommissioned on-premise server hardware create refurbishment channels extending asset lifecycles for smaller German operators facing Bavarian data residency mandates. Supply concentration clusters in the United States for HIPAA-certified cloud infrastructure, Germany for MDR-compliant analytics modules, and Japan for battery-optimized mobile field hardware. Engineering talent dependencies draw from Indian development centers, Eastern European QA specialists, and US-based clinical workflow designers. Single-source vulnerability concentrates in pharmacy network API gateways controlled by dominant incumbents. Distribution runs through direct enterprise sales teams for large operators, value-added resellers for mid-market penetration, and OEM partnerships with EHR vendors for bundled deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HIPAA interoperability engineering capacity functions as the binding constraint propping pricing power for certified platforms, with qualified compliance architects commanding premium compensation that vendors struggle to scale.
For Market Incumbents: Cement platform stickiness through captive pharmacy network integrations that raise switching costs for multi-facility operators. Deepen backward integration into sensor hardware manufacturing to preempt margin erosion from third-party fall detection suppliers. Threat vectors include mobile-first entrants targeting home care agencies with lightweight deployment models and METI-funded Japanese challengers exploiting community-based care policy tailwinds. For New Entrants and Emerging Players: Independent operators with 50-150 beds represent the most penetrable buyer archetype, underserved by enterprise suites and frustrated with legacy on-premise fragmentation. Home care agencies in Japan's METI-designated community care districts offer regulatory-sanctioned entry points with lower competitive density. API-first architectures enabling rapid EHR connectivity provide the strongest go-to-market angle against incumbent integration moats. For Investors and Strategic Acquirers: Distressed-cycle entries favor MDR-certified analytics specialists in Germany and Switzerland where clinical evidence requirements elevate barriers. Long-term viability centers on platforms with pharmacy-billing network density that compounds data network effects. Acquisition target archetypes include mobile-first field worker platforms with offline synchronization IP and state-level Medicaid certification service providers. The signal to watch is CMS reimbursement rule finalization timing, which will trigger replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacy Network Integration | Deep EHR-pharmacy connectivity locks in recurring revenue from medication management workflows. |
| MDR Certification Pathway | CE-marked analytics modules preempt liability exposure for German and Swiss operators under clinical evidence mandates. |
| Mobile-First Platform Launch | Battery-optimized field apps capture METI-promoted community-based care demand in Japan. |
| Sensor Hardware Backward Integration | In-house fall detection production defends margins against third-party component suppliers. |
| State Medicaid Certification Services | Compliance specialization opens niche revenue streams fragmented across US jurisdictions. |
Methodological Framework
Document review covered CMS reimbursement rulemaking dockets, FDA software-as-a-medical-device guidance, and state-level Medicaid certification requirements, complemented by interviews with senior care facility CIOs, EHR integration specialists, pharmacy network operations directors, and long-term care insurance reimbursement analysts. Secondary validation drew from CMS Medicare cost report data, HIPAA breach notification archives, and METI community care policy white papers. Bottom-up facility census modeling triangulated against top-down vendor revenue aggregation.
Segmentation outputs reflect deployment model, facility scale, care setting, and regional regulatory cluster variations across the projection horizon. CAGRs derived from facility construction pipelines, software replacement cycle surveys, and interoperability mandate implementation timelines. Industry-specific inputs included HIPAA compliance cost engineering estimates and MDR certification documentation burden assessments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CMS reimbursement rule finalization and METI policy continuity. Practitioners should monitor federal interoperability standard consolidation and hyperscaler pricing reset announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Non-Clinical Homecare Software Market
Healthcare IT
IT-Enabled Healthcare Market
Healthcare IT
Healthcare Mobility Solutions Market
Healthcare IT
Global Personal Health Records Software Market
Healthcare IT
Clinical Healthcare IT Market
Healthcare IT
Hospital Workforce Management Software Market
Healthcare IT
Global Cancer Registry Software Market
Healthcare IT
Integrated Operating Room Management Systems Market
Healthcare IT
Digital Mhealth Solution Market
Healthcare IT
Metabolic Rate Analysis System Market
Healthcare IT
Global RFID in Healthcare Market
Healthcare IT
Patient Self-Service Kiosks Market
Healthcare IT
Senior Care Technologies Market
Healthcare IT
Operating Room Management Software Market
Healthcare IT
Americas Healthcare Human Resources (HR) Software Market
Healthcare IT
Global Emergency Department Information System Market