
 Hospital Lighting Market | 2026-2036
Hospital Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Lighting Market Intelligence
The division between premium, tunable white fixtures for patient-centric applications and commodity fluorescent lamps for general areas is shifting the market's value proposition. This dynamic creates distinct competitive arenas. Signify Holding BV leverages its extensive portfolio in LED systems and controls to capture large-scale projects. In contrast, Zumtobel Group specializes in high-specification architectural lighting solutions designed for complex healthcare environments, including operating theaters.
Hospital lighting encompasses specialized illumination systems designed to meet the rigorous functional and hygienic requirements of healthcare facilities. These systems must provide high Color Rendering Index (CRI) values, typically above 90, to ensure accurate diagnosis and procedural precision. Among product types, LED lights continue to displace legacy fluorescent and halogen lamps due to superior energy efficiency and longevity. Application-wise, surgical suites represent the highest-value segment, demanding glare-free, shadowless illumination with precise color tuning capabilities.
Product design and market access are governed by stringent standards, including CE marking in Europe, which mandates safety and performance criteria. In the United States, while the FDA does not directly regulate general lighting, its oversight of medical devices influences requirements for lights integrated into surgical equipment. Stakeholders must now focus on integrating lighting controls with building management systems to optimize energy use and support human-centric lighting protocols.
Market Dynamics
The integration of lighting controls with building management systems is the central force shaping the market. This shift moves illumination from a standalone utility to a core component of patient care protocols and facility-wide energy optimization strategies.
Growth Catalysts
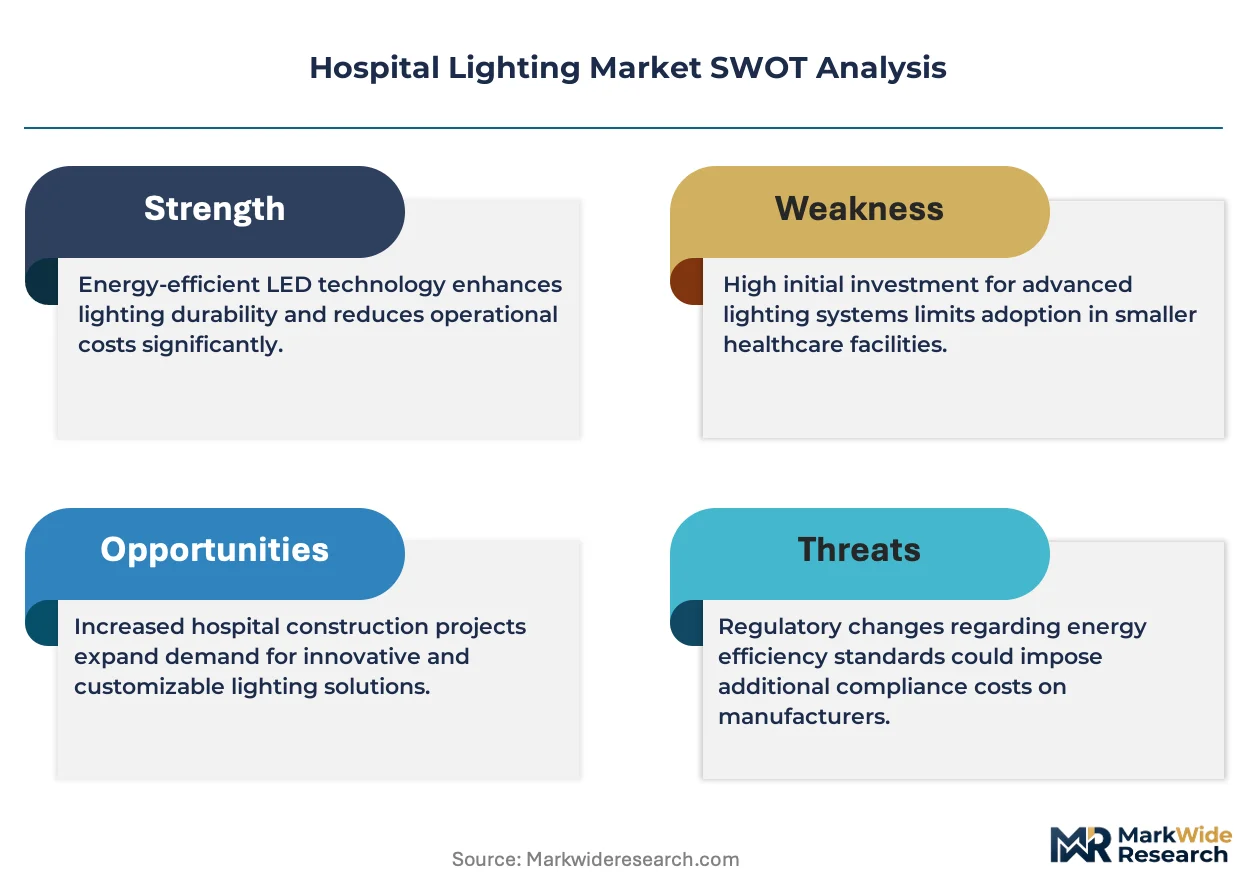
- New Construction Mandates:Hospital construction programs in Germany mandate energy-efficient lighting, directly fueling demand for modern LED fixtures and advanced control systems.
- Human-Centric Lighting Adoption:Clinical validation of lighting supporting circadian rhythms drives adoption in patient rooms and ICUs to improve recovery and well-being.
- Regulatory Upgrades:The EU’s Medical Device Regulation (MDR) imposes stricter rules on surgical lights, compelling upgrades to compliant, high-CRI systems.
Market Restraints
- High Initial Cost:The significant capital investment for integrated LED systems and networked controls is a barrier for facilities with constrained budgets.
- Integration Complexity:Interoperability issues between proprietary lighting controls and existing building management systems (BMS) delay projects and increase costs.
- Lack of Standardization:The absence of universal standards for implementing human-centric lighting creates uncertainty for specifiers and hospital administrators.
Strategic Opportunities
- UVC Integration:Combining automated UVC disinfection within general illumination fixtures offers a solution to enhance infection control protocols in unoccupied spaces.
- Geographic Expansion:Healthcare infrastructure investments in Middle Eastern countries like the UAE create new markets for advanced hospital lighting solutions.
- Data-Driven Services:Using sensor data from connected lighting to offer services like asset tracking and occupancy analytics creates new revenue streams.
Industry Challenges
- System Interoperability:Ensuring seamless communication between multi-vendor lighting components and a hospital’s central building automation system remains a significant technical hurdle.
- Specialized Skills Gap:A shortage of facility managers and technicians trained to commission, program, and maintain complex networked lighting control systems hinders effective deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital Lighting Market |
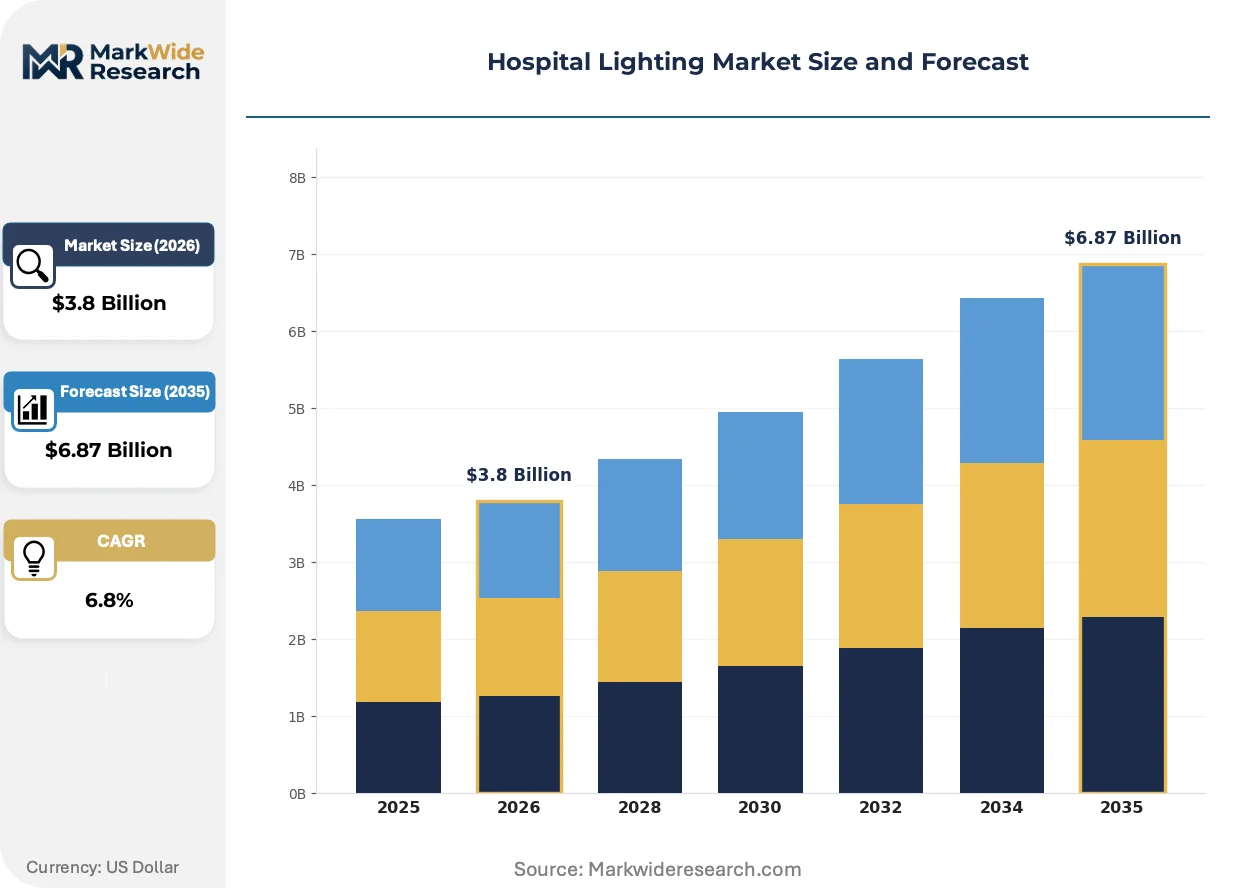
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.87 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Lights, Fluorescent Lamps, Halogen Lamps, OLED Panels, Induction Lamps Application: Surgical Suites, Patient Rooms, Emergency Rooms, Diagnostic Areas, Laboratories End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Diagnostic Laboratories Installation Type: Ceiling Mounted, Wall Mounted, Portable, Recessed, Pendant |
| Companies Covered | Hubbell Incorporated, Signify Holding BV, Acuity Brands Inc., General Electric Company, Zumtobel Group, KLS Martin Group, Koninklijke Philips NV, Kenall Manufacturing Company, Eaton Corporation PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Lighting Market Strategic Shifts & Innovations
The market is shifting from providing simple illumination toward delivering integrated systems that are foundational to patient care and operational efficiency. This evolution positions lighting as an active, data-generating asset within the clinical environment, not just a passive utility.
Networked lighting controls, using protocols like Power-over-Ethernet (PoE), provide granular control over individual fixtures. Large hospital systems are adopting this technology in new construction to enable dynamic lighting scenes. This lighting control infrastructure is converging with building automation networks, allowing for unified management of energy, patient comfort, and operational alerts.
Europe's Medical Device Regulation (MDR) elevates compliance burdens for any lighting classified as a medical accessory, such as surgical or examination lights. This directive mandates more rigorous technical documentation, clinical evaluation, and post-market surveillance. Manufacturers of high-specification fixtures are most affected, requiring significant investment in recertification to maintain access to the EU market.
A shift from one-time capital purchases toward long-term service agreements is gaining traction for large-scale lighting upgrades. This model disrupts traditional sales channels by emphasizing lifecycle performance and maintenance over the initial hardware transaction. This trend is most pronounced in North American and European hospital networks seeking to transfer technology risk and align operational budgets.
Hospital Lighting Market Segmentation
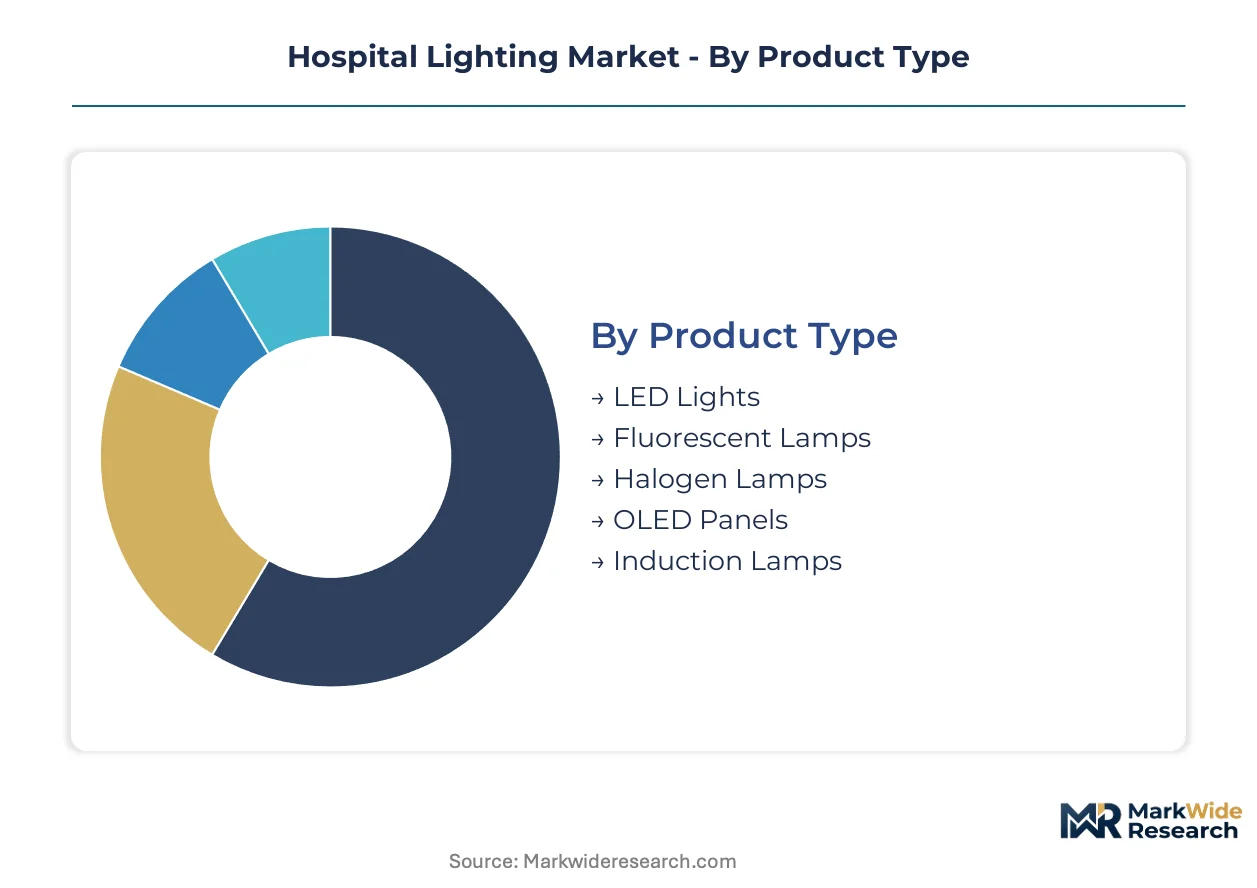
The Hospital Lighting Market is intricately segmented, reflecting the diverse and specialized illumination demands across healthcare facilities. Each segment addresses unique functional requirements, from precision lighting in surgical environments to patient-centric systems that influence well-being and recovery. Understanding these distinctions is crucial for manufacturers to tailor solutions effectively and for facilities to optimize operational efficiency.
Product Type:
The product type segment spans a spectrum from highly standardized, general illumination sources to specialized, customizable light engines for critical medical functions.
- LED Lights:These advanced luminaires offer superior energy efficiency, extended lifespan, and precise color rendering capabilities, often exceeding 90 CRI. Demand concentrates heavily in new hospital construction projects and comprehensive facility upgrades in Germany, driven by mandates for energy-efficient lighting.
- OLED Panels:Characterized by their thin, diffuse, and low-heat emission properties, OLED panels provide uniform, glare-free illumination suitable for sensitive environments. Demand for these innovative panels is emerging in niche applications such as patient room ambient lighting and advanced diagnostic imaging areas, where visual comfort is paramount.
- Fluorescent Lamps:These legacy lighting solutions provide general illumination but are being progressively phased out due to lower energy efficiency and environmental concerns.
- Halogen Lamps:Primarily used in older surgical and examination lights, halogen lamps are known for high heat output and shorter lifespans compared to modern alternatives.
- Induction Lamps:Offering a long operational lifespan and high energy efficiency, induction lamps find limited, specialized use in hospital settings, often in utility or maintenance areas.
Leading the category by volume: Fluorescent Lamps. Growing fastest: LED Lights.
Application:
Application areas in hospital lighting are differentiated by their functional criticality and the precision required from illumination systems.
- Surgical Suites:This segment demands highly specialized, glare-free, and shadowless illumination with precise color tuning capabilities and high CRI values for accurate tissue differentiation. Upgrades to compliant, high-CRI systems are compelled by regulatory changes like the EU’s Medical Device Regulation (MDR).
- Patient Rooms:Focuses on human-centric lighting systems that mimic natural daylight cycles to support circadian rhythms, improving patient comfort and recovery outcomes. Clinical validation of these systems drives adoption in newly constructed patient rooms and intensive care units.
- Emergency Rooms:Requires robust, reliable lighting capable of supporting rapid response and critical care procedures, often with adjustable intensity.
- Diagnostic Areas:Illumination in these areas necessitates consistent light quality and accurate color rendering to support precise medical imaging and examination.
- Laboratories:Uniform, bright, and often flicker-free illumination is essential for detailed analytical work and ensuring visual comfort for technicians.
The segment with the most stringent technical requirements is Surgical Suites, while Patient Rooms exhibits significant expansion.
End User:
End-user segments vary significantly in their scale of procurement and the complexity of their lighting infrastructure needs.
- Hospitals:These large facilities require comprehensive lighting solutions integrated with building management systems, covering diverse areas from operating theaters to administrative offices. New construction and renovation projects in Germany represent a large portion of this demand.
- Ambulatory Surgical Centers:These centers focus on outpatient procedures, demanding high-specification lighting for surgical precision and efficient, infection-controlled environments. Healthcare infrastructure investments in countries like the UAE create new markets for these advanced solutions.
- Specialty Clinics:These facilities require tailored lighting solutions specific to their medical focus, such as ophthalmology or dermatology, often emphasizing examination quality.
- Diagnostic Laboratories:These facilities utilize lighting to ensure optimal visual conditions for detailed analysis and accurate test results.
The largest consumer of hospital lighting solutions remains Hospitals, with Ambulatory Surgical Centers demonstrating robust growth.
Installation Type:
Installation types range from permanent, integrated fixtures to flexible, mobile solutions catering to dynamic clinical environments.
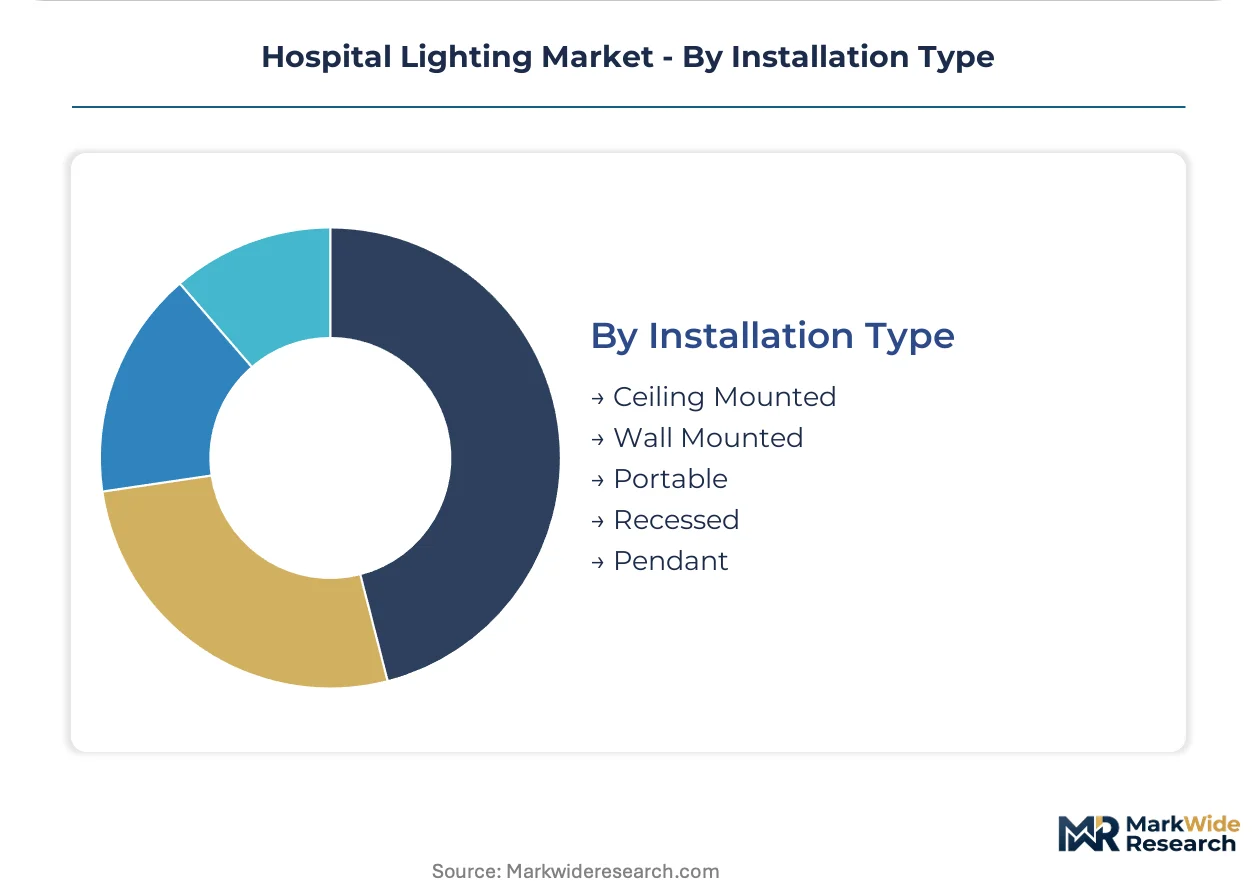
- Ceiling Mounted:These fixtures form the primary source of illumination in most hospital areas, often integrated into the architectural design and networked for centralized control. Demand is strong in new facility designs and general ward lighting, ensuring uniform light distribution.
- Portable:Offering flexibility and mobility, portable lights are essential for examination, minor procedures, and emergency situations, often featuring adjustable arms and battery power. Demand for these solutions is growing in remote clinics and flexible diagnostic setups.
- Wall Mounted:These fixtures provide ambient or task lighting in patient rooms, corridors, and waiting areas, contributing to overall visual comfort.
- Recessed:Integrated flush with ceilings or walls, recessed lighting offers a clean aesthetic and is often preferred in sterile or clean room environments.
- Pendant:Suspended from the ceiling, pendant lights typically provide direct task illumination over examination beds or reception desks.
Fixed installations like Ceiling Mounted fixtures form the backbone, while Portable solutions are gaining traction for procedural flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt, as a central hub for medical technology in Germany, drives significant demand for advanced hospital lighting solutions. This concentration of medical innovation and infrastructure development positions Germany as a key market. The regional landscape is shaped by stringent regulatory frameworks and a strong emphasis on patient-centric care across several developed and emerging economies.
Germany
New hospital construction mandates in Germany directly fuel demand for modern LED fixtures and advanced control systems. The EU’s Medical Device Regulation (MDR) compels upgrades to compliant, high-CRI systems, particularly for surgical lights. Berlin's Charité hospital network and surrounding medical technology firms are actively adopting advanced LED systems to meet both energy efficiency and clinical performance standards.
United States
Human-centric lighting adoption in patient rooms and intensive care units drives demand for sophisticated lighting systems across the United States. The FDA's oversight of medical devices influences requirements for lights integrated into surgical equipment, ensuring safety and performance. Boston's dense concentration of healthcare facilities and biotech companies continues to drive innovation in patient-centric lighting solutions.
United Arab Emirates
Extensive healthcare infrastructure investments in the United Arab Emirates create new markets for advanced hospital lighting solutions. MOHAP (Ministry of Health and Prevention) standards guide facility design and equipment procurement, emphasizing high-specification systems. Dubai Healthcare City and Abu Dhabi's Khalifa City are rapidly adopting advanced lighting technologies in newly constructed medical facilities.
Japan
Patient well-being and technological advancements in OLED panels are key demand drivers for hospital lighting in Japan. METI (Ministry of Economy, Trade and Industry) promotes energy-efficient building standards, encouraging the adoption of modern lighting solutions. Tokyo's leading hospitals and research institutions are pioneering the use of OLED lighting in diagnostic areas for enhanced visual comfort and precision.
Hospital Lighting Market Key Industry Players
Premium-margin players sit above commodity-margin players across the solution complexity dimension within hospital lighting. The market exhibits a tiered structure, with a clear distinction between providers of highly specialized, integrated systems and those offering more standardized general illumination products. Strategic archetypes include high-specification architectural lighting specialists and large-scale integrated LED system providers. Competitive moves often involve portfolio diversification, particularly into advanced LED systems and controls, alongside specialization in complex healthcare environments.
Among the prominent solution providers, Signify Holding BV and Koninklijke Philips NV represent global-scale enterprises leveraging extensive portfolios in LED systems and controls. These companies capture large-scale projects by offering comprehensive lighting infrastructure. Zumtobel Group occupies a position as a specialist in high-specification architectural lighting, designing solutions tailored for complex healthcare environments, including operating theaters. These players exemplify the market's division between broad system integration and specialized high-performance offerings.
| Leading Market Players |
|---|
| Hubbell Incorporated |
| Signify Holding BV |
| Acuity Brands Inc. |
| General Electric Company |
| Zumtobel Group |
| KLS Martin Group |
| Koninklijke Philips NV |
| Kenall Manufacturing Company |
| Eaton Corporation PLC |
| Others |
Cost & Logistics Intelligence
Hospital procurement groups, especially those in Germany, drive project-based pricing for integrated lighting systems. This consolidation of purchasing power influences the long-term service agreements now gaining traction.
Pricing Analysis
Value-based pricing tied to patient recovery outcomes anchors the premium segment for human-centric lighting. The market employs a hybrid of project-based pricing for new installations and contract-based models for long-term service agreements. CE marking certification level and customization for surgical suites drive significant price differentiation. Pricing softness in general illumination fixtures stems from intense competition among LED manufacturers, making public hospitals most price-sensitive, while private specialty clinics prioritize performance.
Supply Chain Analysis
Single-source vulnerability sits with specialized component manufacturers in East Asia for advanced LED drivers and optical lenses. China and Germany are key manufacturing hubs for LED components and finished luminaires, drawing from critical inputs like rare earth elements for phosphors and semiconductor chips. Geopolitical tensions and trade restrictions pose a structural risk to component availability. Distribution runs through a mix of direct sales to large hospital networks and specialized medical equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hospital lighting market is a consolidation play, driven by the increasing complexity of integrated systems. This technical barrier forces out smaller players unable to invest in R&D and interoperability solutions.
For Market Incumbents:
Anchor market position by deepening vertical integration into control system software development. Invest in proprietary networking protocols to mitigate interoperability issues and enhance system reliability in complex healthcare environments. Focus R&D on UVC integration for infection control, leveraging existing fixture designs. This strategy counters the threat of commodity LED suppliers and reinforces premium pricing for integrated solutions.
For New Entrants and Emerging Players:
Online architectural specification platforms offer a direct digital-channel route to penetrate the specialty clinics segment. Target underserved regional markets in the Middle East with pre-configured, human-centric lighting packages. Emphasize ease of installation and compliance with MOHAP standards as a key go-to-market angle, bypassing established distribution networks. This approach focuses on rapid deployment and niche market capture.
For Investors and Strategic Acquirers:
The window for entry favors strategic acquirers seeking to consolidate fragmented control system providers. Long-term viability over the next 5-10 years hinges on securing intellectual property in AI-driven lighting management and data analytics. Target mid-sized firms with strong regional installation capabilities and proprietary software. The signal to watch is the widespread adoption of Power-over-Ethernet (PoE) in new hospital construction projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Portfolio in Human-Centric Lighting | Meets growing demand for patient recovery and staff well-being in new hospital construction. |
| Develop Integrated UVC Disinfection Solutions | Addresses critical infection control needs within healthcare facilities, enhancing safety protocols. |
| Invest in Proprietary Lighting Control Software | Improves system interoperability and offers advanced data-driven services for operational efficiency. |
| Pursue CE Marking and FDA Compliance Upgrades | Ensures market access and strengthens competitive positioning for high-specification medical lighting. |
| Establish Long-Term Service Agreements | Shifts revenue model from capital expenditure to recurring operational budgets for hospital networks. |
Research Approach
Document review covered EU Medical Device Regulation (MDR) guidelines, METI reports, and MOHAP standards, complemented by interviews with hospital facility managers, biomedical engineers, and lighting procurement specialists. Secondary validation utilized industry reports, academic studies on circadian lighting, and company annual filings. This approach combined bottom-up market sizing with top-down validation from industry experts to ensure accuracy.
Historical market data was cross-referenced against expert panel input to build the forecast framework over the projection horizon. Segmentation dimensions modeled included product type, application, end-user, and installation type, alongside regional regulatory impact. Compound Annual Growth Rates (CAGRs) were derived from a multi-variant regression analysis. Key forecast inputs included new hospital construction pipelines and regulatory upgrade cycles.
The model holds under current regulatory stability and projected healthcare infrastructure investments; deviation in global economic conditions or rapid technological obsolescence would shift market trajectories. Forecasts reflect these assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Facilities
Qatar Senior Living Market
Healthcare Facilities
Micro-Hospitals Market
Healthcare Facilities
Asia-Pacific Smart Hospital Market
Healthcare Facilities
US Assisted Living Facility Market
Healthcare Facilities
US Hospital Facilities Market
Healthcare Facilities
Mobile Hospitals Market
Healthcare Facilities
Global Healthcare Facilities Management Market
Healthcare Facilities
US Ambulatory Surgery Centers Market
Healthcare Facilities
Assisted Living Facilities Market
Healthcare Facilities
Sauna and Spa Market
Healthcare Facilities
Trauma Care Centers Market
Healthcare Facilities
Ambulatory Surgical Centers Market
Healthcare Facilities
Global Ambulatory Surgery Centers (Ascs) Market
Healthcare Facilities
US Office-Based Labs Market
Healthcare Facilities
US Skilled Nursing Facility Market
Healthcare Facilities
Longevity Clinic Chain Infrastructure Market