
 Global Ambulatory Surgery Centers (Ascs) Market | 2026-2036
Global Ambulatory Surgery Centers (Ascs) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ambulatory Surgery Centers (Ascs) Market Foresight
Real estate investment trust leasing and sale-leaseback structures is tilting capital requirements away from balance-sheet-heavy operators toward asset-light management companies. United Surgical Partners International leverages its partnership model with health systems to sustain de novo development pipelines. Surgery Partners anchors its position through concentrated orthopedic and gastroenterology service lines across Sun Belt markets. HCA Healthcare competes via hospital-affiliated ASC networks that capture downstream referrals.
Ambulatory Surgery Centers are Medicare-certified facilities providing same-day surgical, diagnostic, and preventive procedures requiring general or regional anesthesia without overnight inpatient admission, typically operating under state CON exemptions and CMS Conditions for Coverage. The ownership model dimension reveals hospital-affiliated structures capturing the deepest payer contracts while private equity platforms drive rollup velocity across fragmented metro markets. Primary specialization in ophthalmology and gastroenterology generates the highest case volumes, though orthopedic ASCs command superior per-procedure margins due to implant-intensive workflows and bundled payment participation.
CMS site-neutral payment rules, state CON programs, and FDA 510(k) clearance requirements for surgical devices collectively shape ASC expansion feasibility and equipment procurement cycles. Accreditation by AAAHC or The Joint Commission determines Medicare deeming status and commercial payer network eligibility. Stakeholders must monitor CMS procedural code additions to the ASC-payable list as the primary demand catalyst beyond demographic trends.
Market Dynamics
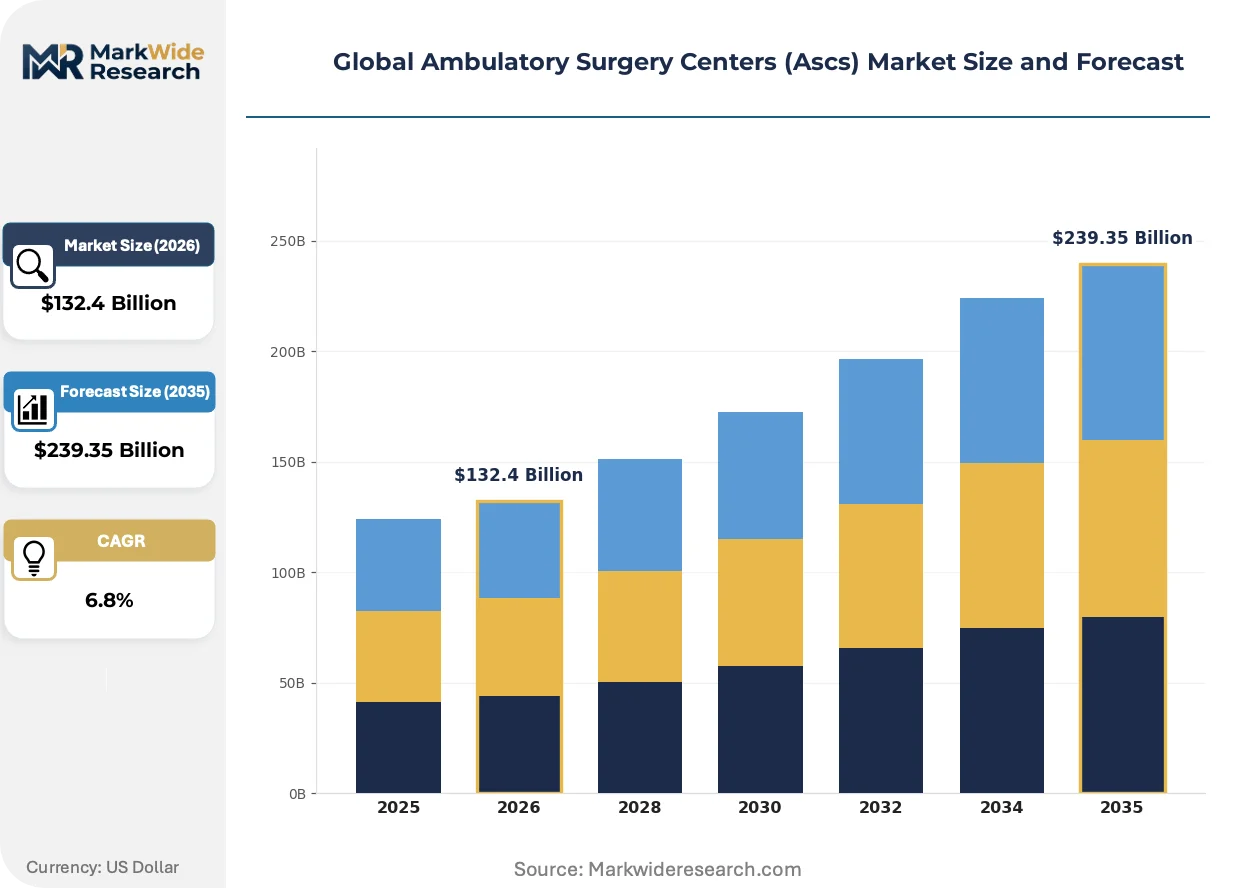
CMS site-neutral payment reforms are compressing reimbursement differentials between hospital outpatient departments and freestanding ASCs, redirecting procedural volume toward lower-cost settings while reshaping capital deployment strategies across the provider landscape.
Growth Catalysts
- Medicare's ASC-payable list expansion:CMS annual procedural code additions now cover total joint arthroplasty and complex spine procedures, unlocking orthopedic case migration from inpatient settings.
- Private equity rollup velocity:Platform investments in multi-site ASC networks are consolidating fragmented metro markets and standardizing operational protocols across previously independent facilities.
- Physician joint venture structures:Surgeon ownership stakes align clinical decision-making with facility economics, accelerating case recruitment and reducing referral leakage to competing hospital systems.
Market Restraints
- Certificate of Need (CON) moratoriums:State-level CON programs in 35 US states restrict de novo development and facility expansion, creating artificial scarcity in high-demand metropolitan corridors.
- Implant cost pass-through limitations:Bundled payment structures for orthopedic procedures cap device reimbursement, squeezing margins on implant-intensive workflows where supply costs dominate case economics.
- Anesthesiologist staffing shortages:Regional concentration of CRNA and physician anesthesiologist talent in hospital systems limits ASC operational capacity and extends case scheduling backlogs.
Strategic Opportunities
- Cardiovascular procedure migration:Transcatheter interventions and electrophysiology ablations represent underpenetrated clinical domains as device manufacturers pursue ASC-specific 510(k) clearances from FDA.
- Sale-leaseback monetization:Real estate investment trust structures unlock capital tied to physical assets, enabling management companies to fund technology upgrades and de novo development without balance-sheet expansion.
- India's outpatient surgical infrastructure:Private hospital chains are replicating US ASC models in tier-2 cities, capitalizing on CDSCO streamlined device approvals and rising medical tourism flows.
Industry Challenges
- Accreditation timeline compression:AAAHC and Joint Commission deeming status applications require 12-18 month preparation cycles, delaying Medicare certification and commercial payer network participation for new facilities.
- EHR interoperability gaps:ASC-specific practice management systems often lack native integration with hospital ADT feeds and HIE networks, complicating care coordination and pre-authorization workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ambulatory Surgery Centers (Ascs) Market |
| Market Size in 2026 | $132.4 Billion |
| Market Size in 2035 | $239.35 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Outpatient Surgery, Diagnostic Procedures, Preventive Treatments, Rehabilitation Services Facility Size: Small Clinics, Medium Centers, Large Complexes, Specialty Units Ownership Model: Private Equity, Physician-Owned, Hospital-Affiliated, Independent Corporations Primary Specialization: Orthopedic, Gastroenterology, Ophthalmology, General Surgery |
| Companies Covered | United Surgical Partners International, Surgical Care Affiliates, Amsurg Corporation, Surgery Partners, HCA Healthcare, Tenet Healthcare, Universal Health Services, Envision Healthcare, TH Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ambulatory Surgery Centers (Ascs) Market Shifts & Advancements
Robotic surgical platforms are penetrating outpatient settings at accelerating rates, compressing the technology gap between hospital operating rooms and ambulatory environments while redefining minimum viable facility specifications.
Minimally invasive spine instrumentation is migrating from inpatient-only applications to ASC-payable procedures, enabling same-day discharges for lumbar decompression and cervical fusion cases previously requiring overnight observation. Orthopedic-focused ASCs in Florida and Texas are deploying these systems to capture bundled payment episodes from commercial payers. The structural consequence is a compression of case-mix thresholds, with facilities now competing for higher-acuity procedures that were exclusively hospital-based five years prior.
REACH substance restrictions and EU MDR technical documentation requirements are extending device approval timelines for manufacturers seeking CE marking for ASC-specific surgical tools. European facilities face procurement delays for novel implants and powered instruments, diverting near-term supply toward US markets with established 510(k) pathways. German and French ASC networks are responding by consolidating purchasing through group purchasing organizations to buffer regulatory friction.
Self-insured employers are contracting directly with ASC networks for shoppable procedural bundles, bypassing traditional payer intermediaries and demanding transparent all-inclusive pricing for arthroscopy, colonoscopy, and cataract extraction. This channel disintermediation is most visible in Texas and California markets where large employer coalitions have established narrow networks with guaranteed case volume minimums.
Global Ambulatory Surgery Centers (Ascs) Market Segmentation
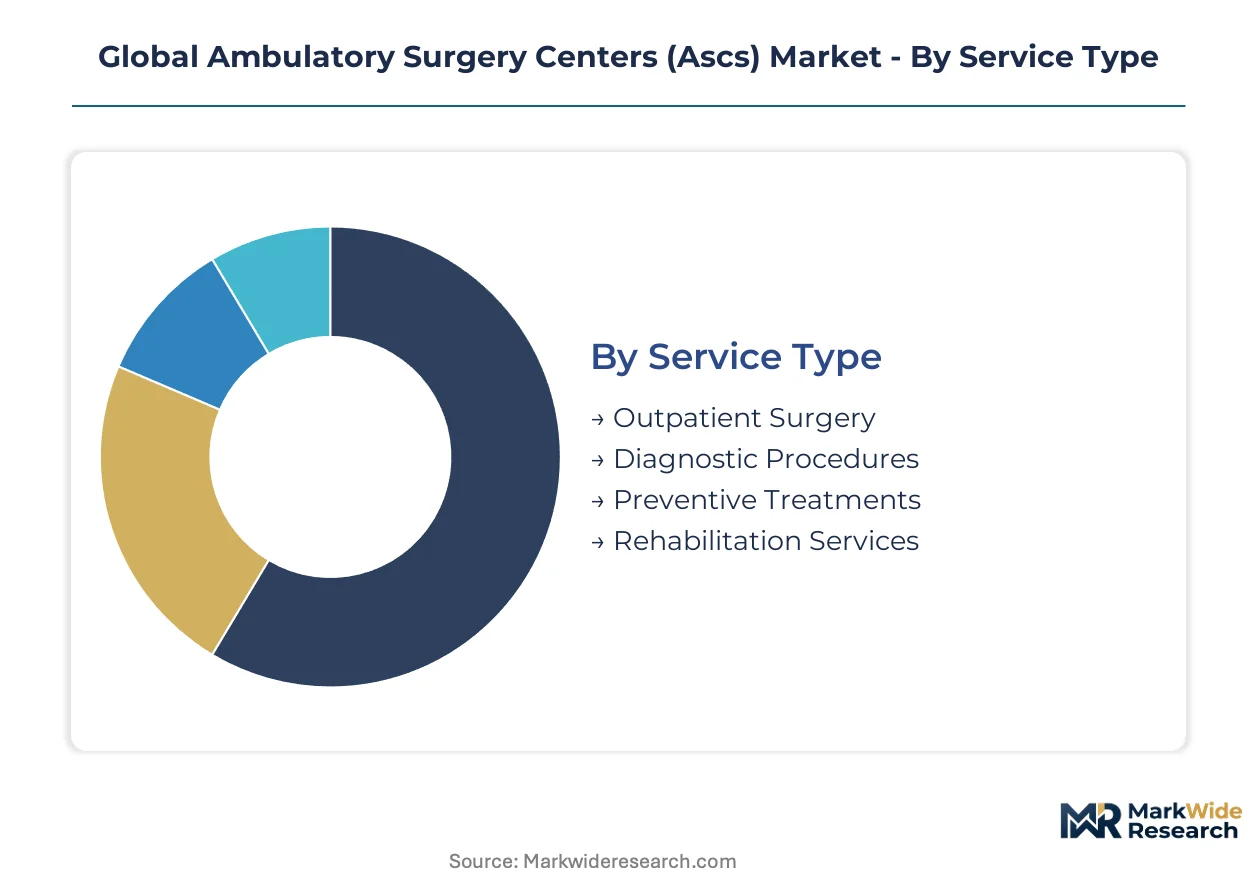
ASC segmentation reveals how capital structure, clinical focus, and operational scale determine competitive positioning across fragmented metro markets. Service mix and ownership architecture directly shape reimbursement capture and physician recruitment economics.
Service Type:
After-sales service intensity varies sharply across service lines, with implant-dependent procedures requiring extensive device vendor support and outcome tracking.
- Outpatient Surgery:Procedures requiring general or regional anesthesia with same-day discharge, spanning orthopedic arthroscopy to laparoscopic cholecystectomy. Demand concentrates in Sun Belt states where physician joint ventures with United Surgical Partners International and Surgery Partners dominate case recruitment. Medicare's annual expansion of ASC-payable procedural codes accelerates volume migration from hospital outpatient departments.
- Diagnostic Procedures:Endoscopy, colonoscopy, and cardiac catheterization performed under moderate sedation or anesthesia. Colorectal cancer screening mandates in employer-sponsored health plans drive volume, with gastroenterology-focused ASCs in Texas and Florida capturing bundled commercial contracts.
- Preventive Treatments:Cataract extraction and minor dermatologic interventions with minimal postoperative monitoring requirements.
- Rehabilitation Services:Postoperative physical therapy and pain management protocols delivered within facility walls or through affiliated outpatient clinics.
Outpatient surgery holds the largest share; momentum sits with diagnostic procedures as screening compliance targets expand.
Facility Size:
Capital deployment thresholds scale non-linearly with facility size, determining which ownership structures can sustain construction and technology upgrade cycles.
- Small Clinics:Single-specialty operations with two to three operating rooms, often constrained by anesthesiologist staffing shortages and limited implant inventory.
- Medium Centers:Multi-specialty facilities with four to eight operating rooms that balance case volume against Certificate of Need restrictions in 35 US states. These structures anchor private equity rollup strategies by offering scalable operational templates.
- Large Complexes:Regional hubs with 10-plus operating rooms, advanced imaging, and overnight observation capabilities. HCA Healthcare and Tenet Healthcare deploy these formats to capture complex spine and total joint cases migrating from inpatient settings.
- Specialty Units:Purpose-built environments for ophthalmology or orthopedics with dedicated equipment suites and procedure-specific workflows.
Medium centers dominate transaction volume; specialty units are expanding most quickly as procedure-specific reimbursement improves.
Ownership Model:
Control architecture determines access to payer contracts, capital for de novo development, and physician alignment mechanisms.
- Private Equity:Platform investments by firms including Kohlberg Kravis Roberts and Bain Capital consolidating fragmented metro markets through multi-site networks. Standardized protocols and group purchasing power compress supply costs across previously independent facilities.
- Physician-Owned:Surgeon majority stakes aligning clinical decision-making with facility economics, reducing referral leakage to competing hospital systems. These structures face regulatory scrutiny under federal anti-kickback statutes and state corporate practice of medicine doctrines.
- Hospital-Affiliated:Health system subsidiaries capturing downstream referrals and securing favorable commercial payer contracts through integrated network participation.
- Independent Corporations:Unaffiliated operators relying on management services organizations for revenue cycle and supply chain functions.
Hospital-affiliated structures command the deepest payer contracts; private equity platforms are gaining share fastest through rollup velocity.
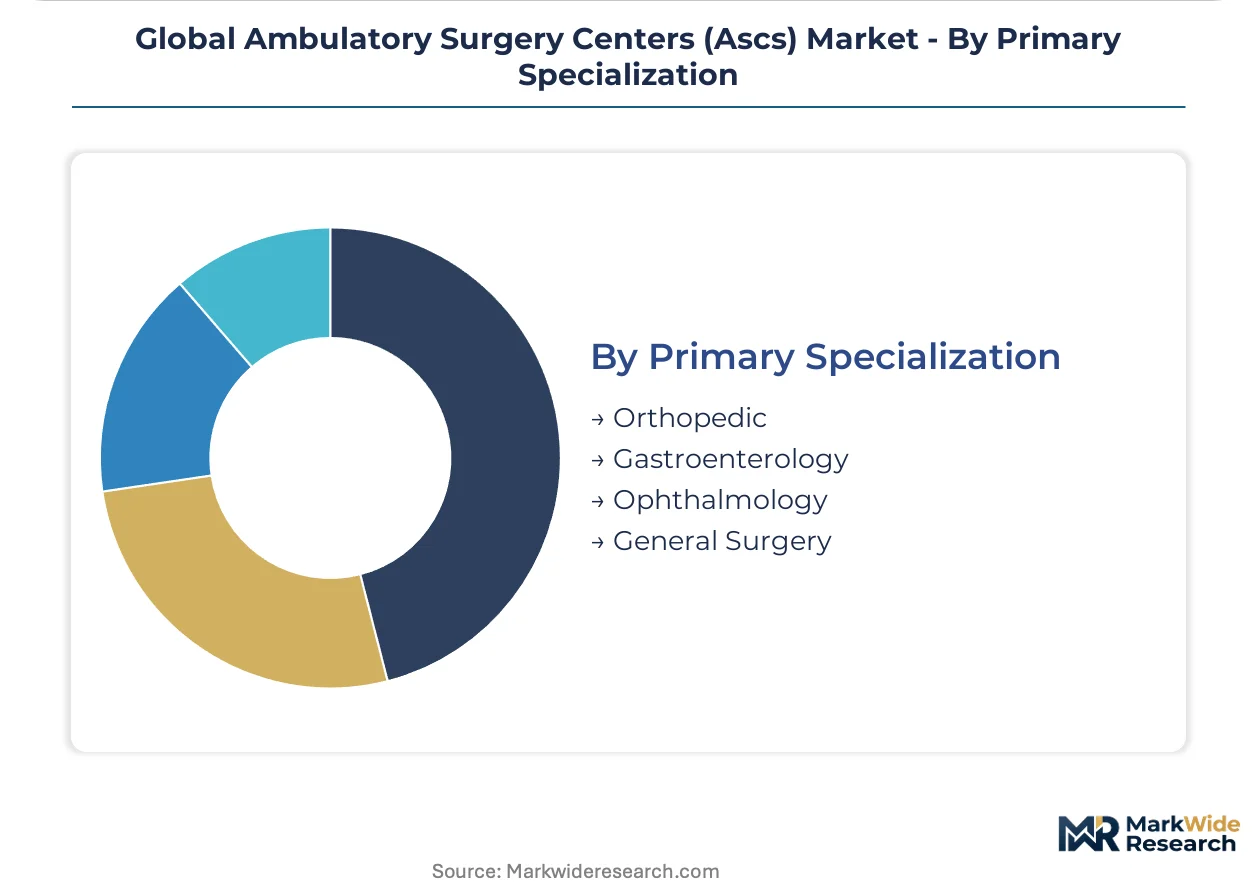
Primary Specialization:
Clinical focus determines case volume potential, per-procedure margin structure, and technology investment requirements.
- Orthopedic:Joint arthroscopy, spine procedures, and total joint replacement with implant-intensive workflows. Bundled payment participation and Medicare's addition of total knee and hip arthroplasty to the ASC-payable list compress case-mix thresholds.
- Gastroenterology:Screening and diagnostic colonoscopy generating the highest procedural volumes across all ASC categories. Employer screening mandates and commercial payer preventive care incentives sustain demand.
- Ophthalmology:Cataract extraction and retinal procedures with rapid patient turnover and minimal anesthesia requirements.
- General Surgery:Hernia repair, gallbladder removal, and breast biopsy procedures with established ASC reimbursement pathways.
Gastroenterology holds the largest share; orthopedic specialization shows the steepest expansion trajectory as higher-acuity cases migrate outpatient.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States exports ASC management expertise and surgical technology while importing specialized implants and capital equipment from European and Asian suppliers, creating a trade dynamic that favors domestic facility operators with established vendor relationships.
United States
Medicare's site-neutral payment reforms and physician joint ventures with United Surgical Partners International drive facility construction across Sun Belt states. CMS Conditions for Coverage and state CON exemptions shape regulatory feasibility. Dallas and Houston anchor Texas expansion where Surgery Partners concentrates orthopedic and gastroenterology service lines.
Germany
Outpatient surgical migration accelerates under DRG reimbursement pressure and aging population demand for cataract and joint procedures. EU MDR technical documentation requirements and REACH substance restrictions extend device procurement timelines. The Rhine-Ruhr corridor hosts concentrated ASC networks competing for statutory health insurance contracts.
India
Private hospital chains replicate US ASC models in tier-2 cities, capitalizing on CDSCO streamlined device approvals and medical tourism flows from Gulf states and Africa. Central Drugs Standard Control Organization regulations govern implant quality. Chennai and Hyderabad emerge as hubs where corporate hospital groups deploy ambulatory surgical infrastructure.
United Kingdom
NHS waiting list backlogs push elective procedure outsourcing to independent sector treatment centers with ASC capabilities. Care Quality Commission registration and NHS England procurement frameworks determine network participation. Greater London and Manchester concentrate private equity-backed platforms consolidating previously independent day surgery units.
Australia
Private health insurance coverage incentives sustain same-day surgical volume growth, particularly in ophthalmology and orthopedics. TGA device approvals and state-based private health facility licensing regulate entry. Sydney and Melbourne metropolitan areas host hospital-affiliated ASC networks capturing referrals from integrated specialist practices.
Global Ambulatory Surgery Centers (Ascs) Market Competitive Landscape
On the supply side, the industry is consolidating through private equity platform investments that aggregate fragmented metro markets into multi-site networks with standardized protocols. Hospital-affiliated structures and physician-owned joint ventures comprise the remaining ownership archetypes. Rollup velocity through acquisition and sale-leaseback monetization of real estate assets constitute the dominant competitive moves reshaping capital deployment.
Among US-based operators, United Surgical Partners International, Surgery Partners, and HCA Healthcare exemplify the three prevailing strategic archetypes. United Surgical Partners International anchors the health system partnership model. Surgery Partners occupies a position within the orthopedic and gastroenterology concentration strategy. HCA Healthcare represents hospital-affiliated network expansion capturing downstream referrals through integrated delivery systems.
| Leading Market Players |
|---|
| United Surgical Partners International |
| Surgical Care Affiliates |
| Amsurg Corporation |
| Surgery Partners |
| HCA Healthcare |
| Tenet Healthcare |
| Universal Health Services |
| Envision Healthcare |
| TH Medical |
| Others |
Supply & Pricing Matrix
Dallas-Fort Worth anchors North American ASC equipment manufacturing capacity, with concentrated orthopedic implant production and surgical device assembly determining downstream pricing power for multi-site networks negotiating vendor contracts. CMS site-neutral payment reforms compress reimbursement spreads, forcing facilities to extract procurement concessions from concentrated supplier bases or absorb margin erosion.
Pricing Analysis
Commercial payer networks anchor ASC pricing structures around bundled episode payments for orthopedic and gastroenterology procedures. Three-tier pricing structure across premium, standard, and economy levels differentiates by case complexity and implant tier, with FDA 510(k) clearance status and brand recognition driving tier placement. Pricing pressure stems from Medicare's annual ASC-payable list expansion lowering per-procedure rates. Self-insured employers demonstrate highest price sensitivity, while hospital-affiliated networks leverage integrated delivery system scale for least sensitivity.
Supply Chain Analysis
Contract manufacturing for ASC surgical devices concentrates with specialized orthopedic implant foundries in Warsaw, Indiana, and Tijuana, Mexico, alongside German precision instrument makers in the Black Forest region. Supply chains draw from titanium alloy feedstock, polyetheretherketone biomaterials, and single-use sterile disposables. Single-source vulnerability runs through FDA-regulated implant suppliers with extended 510(k) clearance timelines. Distribution runs through group purchasing organizations consolidating procurement across multi-site networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through private equity platform consolidation and health system vertical integration, fragmenting independent physician-owned facilities into price-takers. This shift demands defensive repositioning from incumbents and targeted white-space entry from challengers.
For Market Incumbents: Insulate margin structures through backward integration into implant sourcing and captive anesthesia staffing pools. Private equity rollup velocity threatens independent facility economics; counter by securing exclusive surgeon joint ventures with equity participation. Invest in AAAHC accreditation ahead of Medicare deeming status requirements to lock payer network participation. For New Entrants and Emerging Players: Tier-2 Indian cities with underdeveloped outpatient surgical infrastructure represent the most penetrable entry point for replicating US ASC management models. Cardiovascular procedure migration into ambulatory settings offers second white-space opportunity as device manufacturers pursue ASC-specific FDA clearances. Partner with domestic hospital chains for regulatory navigation and physician recruitment. For Investors and Strategic Acquirers: Long-term, this sits as a demographic-capture play because Medicare eligibility expansion and commercial payer cost-containment mandates structurally favor outpatient migration regardless of reimbursement cycle fluctuations. Target acquisition archetype: multi-specialty medium centers with four to eight operating rooms in CON-restricted Sun Belt metros. Monitor CMS annual procedural code additions to the ASC-payable list as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Sale-Leaseback Monetization | REIT structures unlock capital for technology upgrades without balance-sheet expansion. |
| Physician Joint Venture Formation | Surgeon equity alignment reduces referral leakage to competing hospital systems. |
| FDA 510(k) Clearance Pathway | Device-specific approvals enable higher-acuity procedure migration to ASC settings. |
| Hospital System Partnership | Integrated network participation secures favorable commercial payer contracts. |
| Reimbursement Strategy | Medicare site-neutral payment participation determines case-mix competitiveness. |
Research Methodology
A spread of perspectives from ASC facility operators, health system strategy officers, biomedical procurement managers, and private equity platform directors converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation against CMS Medicare cost reports, FDA 510(k) clearance databases, state CON program filings, and hospital GPO contract disclosures. Bottom-up facility count triangulation against top-down reimbursement flow analysis anchored market sizing.
Demand-supply balance across the analysis window modeled procedural volume migration from hospital outpatient departments against ASC capacity expansion constrained by Certificate of Need moratoriums. Segmentation dimensions included service type, facility size tier, ownership architecture, and primary clinical specialization. CAGRs derived from procedure volume elasticity to Medicare payable-list expansion and commercial bundled payment adoption curves. Forecast inputs incorporated anesthesiologist staffing availability and implant cost pass-through limitations.
Practitioners should monitor CMS procedural code additions, state CON legislative activity, and FDA orthopedic device clearance timelines for early signals of volume or capacity inflection. Quarterly review of Medicare Advantage network participation rates and commercial payer bundled payment penetration is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Facilities
Longevity Clinic Chain Infrastructure Market
Healthcare Facilities
Private Office-Based Clinics Market
Healthcare Facilities
Sauna and Spa Market
Healthcare Facilities
Asia-Pacific Smart Hospital Market
Healthcare Facilities
US Skilled Nursing Facility and Rehabilitation Market
Healthcare Facilities
Confinement Center Market
Healthcare Facilities
Qatar Senior Living Market
Healthcare Facilities
Ambulatory Surgical Centers Market
Healthcare Facilities
US Office-Based Labs Market
Healthcare Facilities
Micro-Hospitals Market
Healthcare Facilities
US Assisted Living Facility Market
Healthcare Facilities
US Skilled Nursing Facility Market
Healthcare Facilities
US Ambulatory Surgical Centers Market
Healthcare Facilities
Global Healthcare Architecture Market
Healthcare Facilities
Mobile Hospitals Market
Healthcare Facilities
Hospital Lighting Market