
 Global Electronic Drug Delivery Systems Market | 2026-2036
Global Electronic Drug Delivery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electronic Drug Delivery Systems Market Foresight
Hospital procurement of electronic drug delivery systems is tilting toward direct manufacturer partnerships and away from traditional distributor intermediaries. Medtronic leverages its vertically integrated manufacturing footprint to secure long-term supply contracts with major health systems. Insulet Corporation specializes in patch-based insulin delivery, occupying a defensible niche in the wearable pump segment. Novo Nordisk A/S competes through its deep therapeutic expertise, extending device offerings that pair with its pharmaceutical portfolio.
Electronic drug delivery systems comprise programmable electromechanical devices that administer precise medication doses through controlled mechanisms such as peristaltic pumping, piezoelectric nebulization, or electrophoretic transdermal transport, typically incorporating flow sensors, pressure transducers, and microprocessor-controlled feedback loops to ensure dosing accuracy within ±5% variance. These systems serve primarily to enable self-administration of chronic therapies while capturing real-time adherence data for clinical decision support. Insulin pumps lead product type revenue due to established reimbursement pathways and patient familiarity, though wearable injectors represent the fastest-expanding category as biologics manufacturers seek alternatives to conventional syringes. Bluetooth connectivity dominates technology adoption because of its low-energy profile and compatibility with existing smartphone ecosystems, while sensor integration commands premium positioning through closed-loop algorithm enablement.
FDA premarket notification requirements under 21 CFR Part 870 and EMA Medical Device Regulation (MDR) compliance frameworks shape product development timelines, connectivity validation protocols, and software documentation burdens for manufacturers seeking multi-territory approval. The EU AI Act introduces additional algorithmic transparency obligations for devices employing dose-adjustment machine learning, compelling firms to restructure quality management systems. Stakeholders must monitor evolving cybersecurity guidance from national regulators and determine whether to pursue modular platform architectures or dedicated single-therapy designs.

Market Dynamics
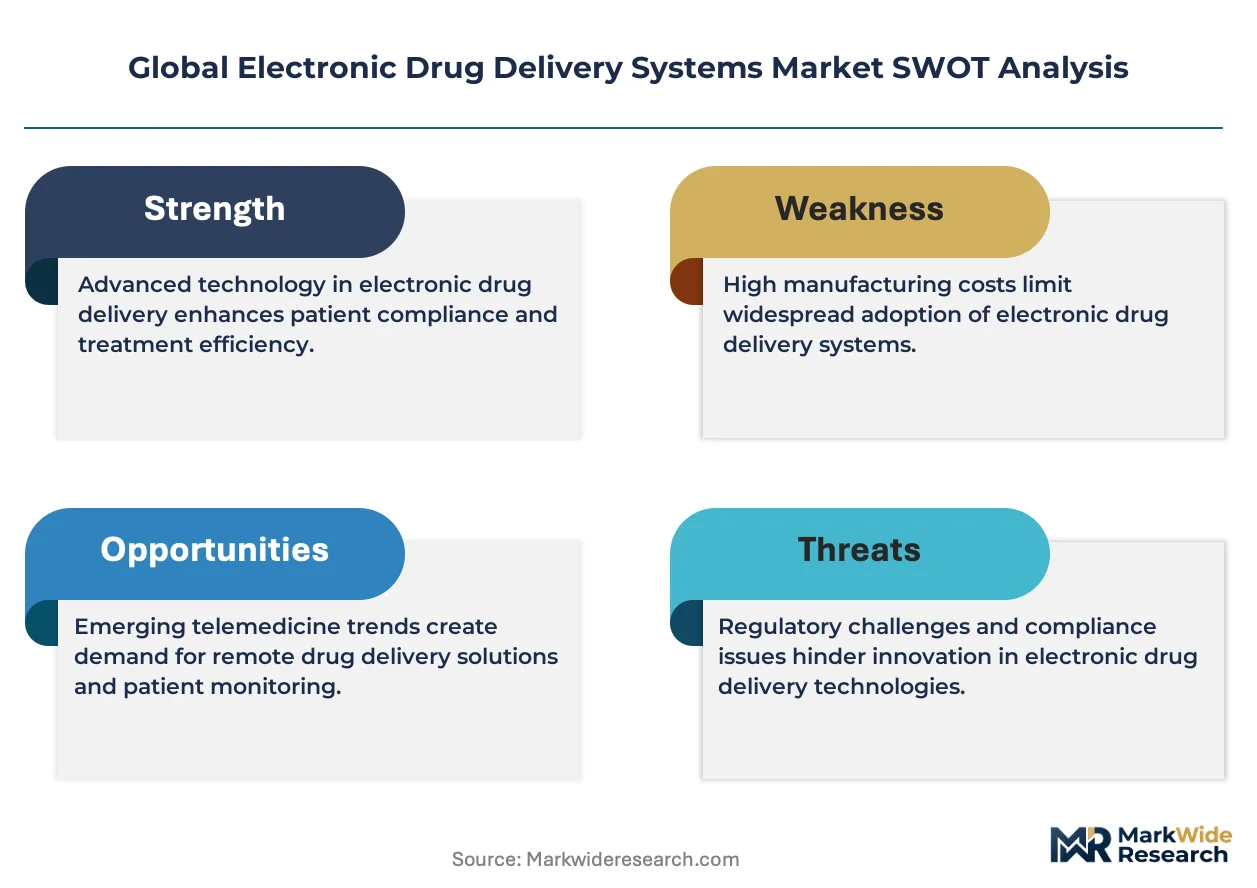
FDA and EMA tightening of connectivity validation protocols is compressing product development timelines while simultaneously elevating capital barriers for new entrants seeking multi-territory approval.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Device manufacturers restructuring quality management systems to accommodate machine learning dose-adjustment documentation are capturing premium positioning in closed-loop insulin delivery.
- Home care provider expansion:Wearable injector adoption for diabetes self-administration is accelerating as reimbursement pathways mature in the United States and Germany.
- Bluetooth Low Energy ecosystem penetration:Smartphone-compatible drug delivery devices are reducing patient training burdens and expanding addressable populations beyond traditional pump users.
Market Restraints
- Software documentation burdens:EMA MDR compliance frameworks and FDA 21 CFR Part 870 premarket notification requirements are extending approval timelines by 18-24 months for connectivity-enabled devices.
- Sensor component supply concentration:Flow sensors and pressure transducers face concentrated sourcing from East Asian contract manufacturers, creating vulnerability to geopolitical trade friction.
- Mechanical syringe cost advantage:Conventional disposable injectors maintain 60-70% lower unit economics for single-dose biologics, limiting electronic system penetration in price-sensitive therapeutic categories.
Strategic Opportunities
- Japan's aging demographic:METI-supported remote monitoring infrastructure investments are creating favorable reimbursement conditions for cloud-connected drug delivery systems in chronic disease management.
- Electrophoretic transdermal transport convergence:Combination with microneedle array technology is opening needle-free administration pathways for peptide therapeutics previously limited to injection.
- Direct manufacturer contracting:Hospital procurement bypass of traditional distributor intermediaries is enabling margin capture and longitudinal patient data ownership for vertically integrated device-pharma pairings.
Industry Challenges
- Cybersecurity engineering talent scarcity:FDA guidance on premarket submission of threat modeling and vulnerability analysis is outpacing specialized workforce availability in medical device hubs.
- Legacy health record integration complexity:Closed-loop algorithm enablement requires real-time bidirectional data exchange with hospital EHR systems that lack standardized interoperability protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electronic Drug Delivery Systems Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $33.79 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pumps, Nebulizers, Wearable Injectors, Inhalers, Transdermal Patches Technology: Bluetooth Connectivity, Wireless Communication, Sensor Integration, Mobile App Interface, Cloud Data Storage End User: Hospitals, Home Care Providers, Specialty Clinics, Research Institutions, Long-term Care Facilities Application: Diabetes Management, Respiratory Therapy, Pain Management, Oncology Treatment, Hormone Replacement |
| Companies Covered | Medtronic, Insulet Corporation, Novo Nordisk A/S, Bayer AG, Gerresheimer AG, BD, Tandem Diabetes Care, Ypsomed AG, Merck Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electronic Drug Delivery Systems Market Shifts & Advancements
Piezoelectric nebulization architectures and sensor-integrated feedback loops are compressing dosing variance tolerances while enabling new therapeutic categories for electronic administration.
Closed-loop algorithmic control incorporating continuous glucose monitoring data streams is rendering obsolete open-loop insulin pumps requiring manual bolus calculation. Pediatric endocrinology practices and Type 1 diabetes management centers are adopting these systems at the fastest clip. The technology is compressing HbA1c variability and reducing hypoglycemic events, shifting competitive advantage toward firms with captive sensor supply.
EMA Medical Device Regulation cybersecurity annex requirements and FDA software as a medical device (SaMD) guidance are mandating structured cybersecurity risk management throughout product lifecycles. Manufacturers must now maintain post-market surveillance for connected device vulnerabilities and deploy over-the-air patching capabilities. Wearable injector segments with Bluetooth connectivity face the steepest compliance cost escalation.
Health system procurement departments are consolidating vendor relationships around longitudinal data-sharing agreements rather than discrete device transactions. Integrated delivery networks in the United States are negotiating direct partnerships with manufacturers for insulin pump fleets bundled with adherence analytics. This behavior is most visible in Medicare Advantage-contracted systems seeking quality metric optimization through real-time therapy monitoring.
Global Electronic Drug Delivery Systems Market Segmentation
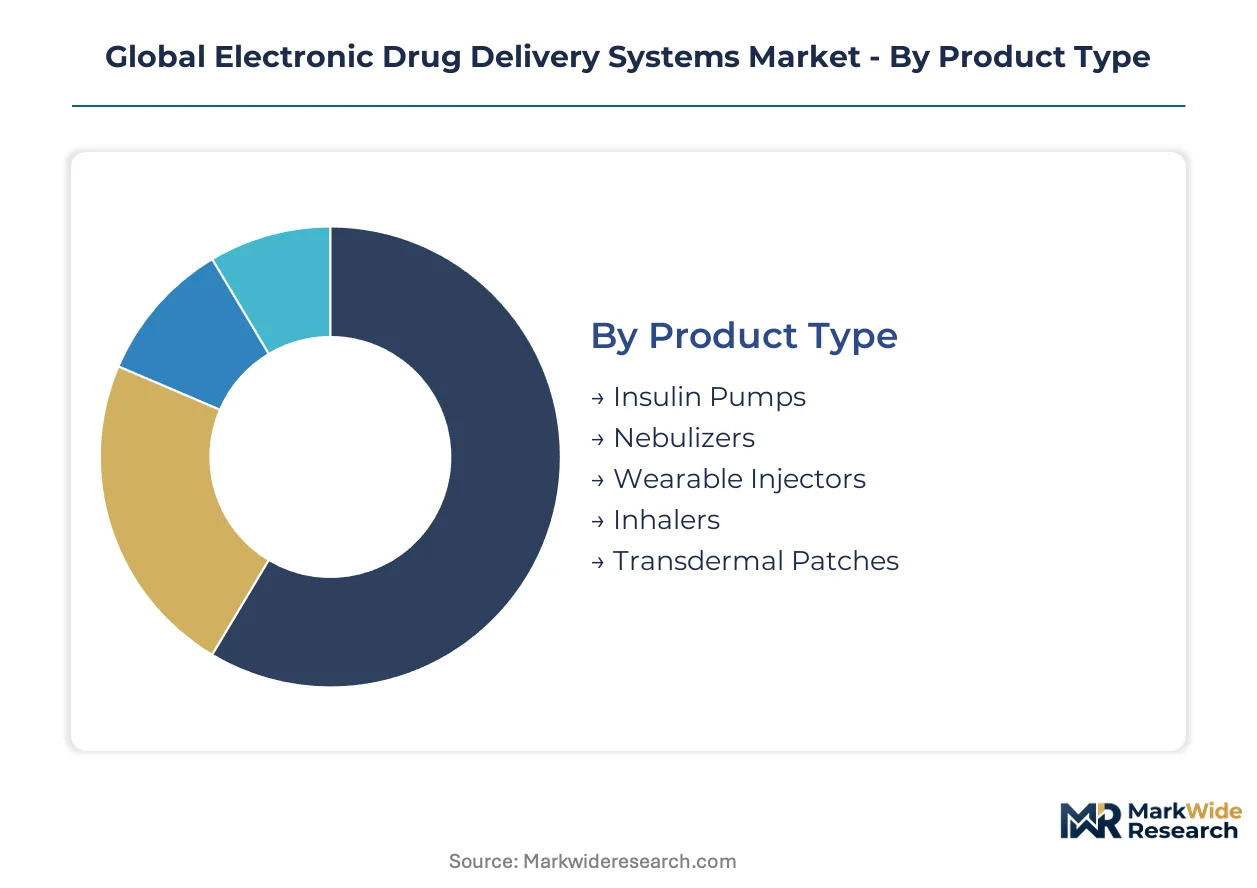
Electronic drug delivery systems fragment across four operational dimensions that determine reimbursement pathways, regulatory scrutiny, and patient training requirements. Product type distinctions govern mechanical complexity and consumables economics. Technology tiers separate basic connectivity from algorithmic closed-loop capabilities. End user channels dictate procurement scale and data integration depth. Application areas define therapeutic risk profiles and clinical evidence thresholds.
Product Type:
Mechanical sophistication and consumables attachment rate determine margin architecture across device categories.
- Insulin Pumps:Electromechanical reservoirs with peristaltic or syringe-drive pumping mechanisms deliver basal and bolus insulin through subcutaneous infusion sets. Demand concentrates in the United States and Germany where established reimbursement codes support 4-year device replacement cycles and bundled consumables revenue. Closed-loop algorithm integration with continuous glucose monitors is compressing HbA1c variability and locking in patient switching costs.
- Wearable Injectors:Adhesive patch-based devices with pre-filled drug reservoirs and piezoelectric or spring-driven actuation mechanisms administer single doses of biologics over extended duration. Adoption accelerates among home care providers in Japan seeking alternatives to conventional syringes for peptide therapeutics. Bluetooth Low Energy connectivity reduces training burden for elderly patient populations.
- Nebulizers:Compressor or vibrating mesh systems aerosolize liquid formulations for pulmonary deposition.
- Inhalers:Breath-actuated or pressurized metered-dose devices with electronic dose counters and adherence tracking.
- Transdermal Patches:Electrophoretic or iontophoretic systems driving drug permeation through controlled electrical fields.
Insulin pumps command the established base. Wearable injectors trace the steepest expansion trajectory.
Technology:
Connectivity depth separates commodity hardware from premium-positioned systems capable of clinical decision support.
- Bluetooth Connectivity:Low-energy wireless protocols enable smartphone pairing for dose logging, remote monitoring, and patient-facing adherence dashboards. Penetration dominates mass-market devices in the United States where patient smartphone ownership exceeds clinical system integration maturity. FDA premarket notification timelines under 21 CFR Part 870 compress for single-function connectivity without algorithmic dose adjustment.
- Sensor Integration:Flow sensors, pressure transducers, and continuous glucose monitors feed real-time data into microprocessor-controlled feedback loops ensuring dosing variance within ±5%. Demand clusters in closed-loop insulin delivery systems qualifying for premium reimbursement in Germany. Captive sensor supply chains differentiate vertically integrated manufacturers from module-assemblers.
- Wireless Communication:Cellular or Wi-Fi direct-to-cloud transmission bypassing smartphone intermediaries.
- Mobile App Interface:Patient-facing software for dose calculation, logging, and educational content delivery.
- Cloud Data Storage:Centralized adherence analytics and longitudinal therapy records for health system quality metrics.
Bluetooth connectivity secures volume leadership. Sensor integration climbs the fastest toward premium positioning.
End User:
Procurement scale and data ownership requirements fragment customer economics across care settings.
- Home Care Providers:Patients or informal caregivers operating devices in residential settings with remote clinical oversight. Expansion concentrates in Japan where METI-supported remote monitoring infrastructure investments create favorable reimbursement for cloud-connected systems. Wearable injector adoption reduces nursing visit frequency for chronic biologic administration.
- Hospitals:Acute care facilities deploying infusion pumps and nebulizers under centralized biomedical engineering oversight. Procurement in the United States is consolidating around direct manufacturer partnerships for insulin pump fleets bundled with adherence analytics. Longitudinal data-sharing agreements are displacing traditional distributor intermediaries.
- Specialty Clinics:Endocrinology and respiratory-focused outpatient settings with device training capabilities.
- Research Institutions:Academic medical centers conducting clinical trials requiring precise dosing documentation.
- Long-term Care Facilities:Skilled nursing environments with staff-administered therapy and centralized medication management.
Hospitals anchor procurement volume. Home care providers gain share fastest as reimbursement pathways mature.
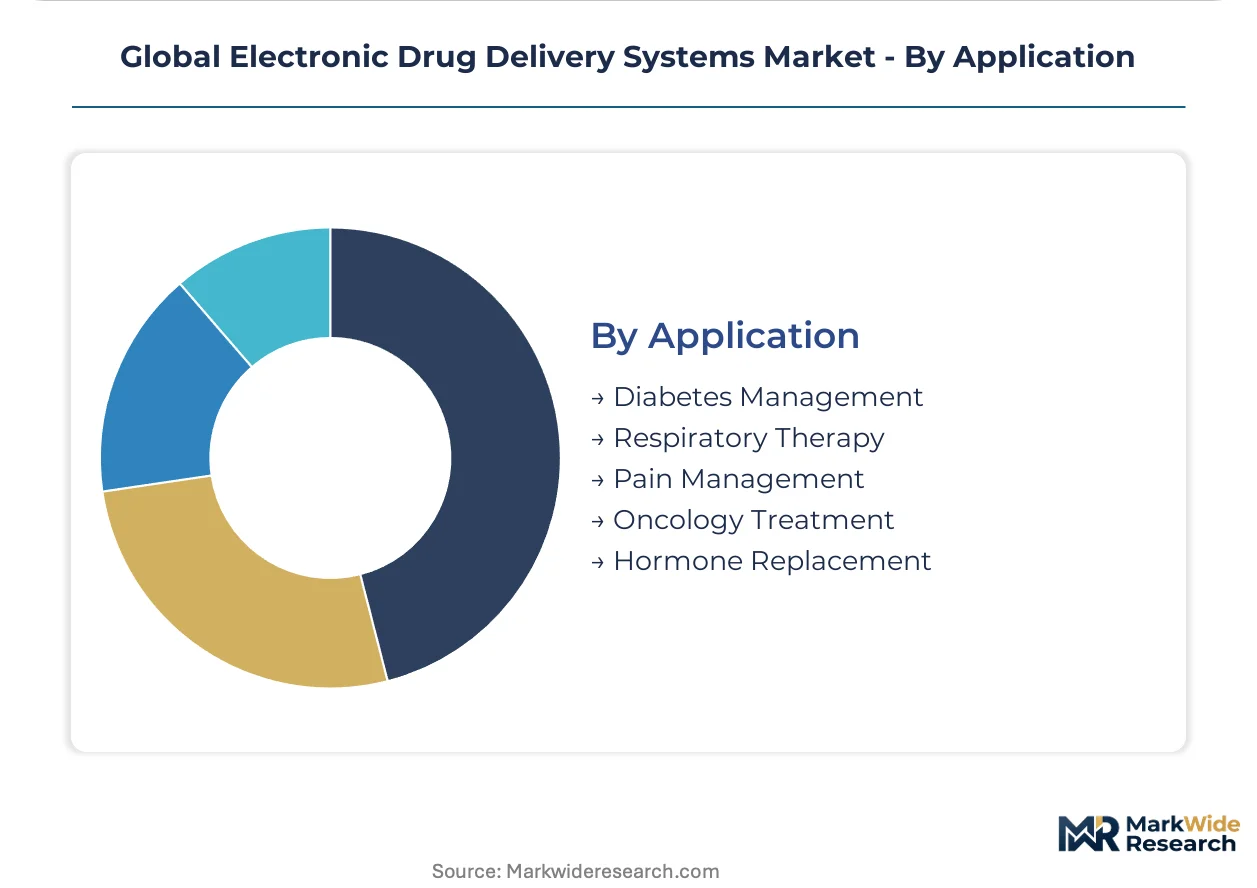
Application:
Therapeutic risk profiles and clinical evidence requirements shape regulatory pathway selection and market entry sequencing.
- Diabetes Management:Insulin delivery systems with basal-bolus programming or closed-loop algorithmic control. Demand concentrates in pediatric endocrinology practices and Type 1 diabetes centers in the United States adopting continuous glucose monitor-integrated pumps. FDA software as a medical device guidance and EMA MDR cybersecurity annex requirements extend approval timelines for connectivity-enabled systems.
- Respiratory Therapy:Nebulized and inhaled drug delivery for asthma and chronic obstructive pulmonary disease. Adoption runs through specialty clinics in Germany where pulmonary rehabilitation reimbursement supports device provision. Electronic dose counters address adherence documentation requirements for payor quality programs.
- Pain Management:Patient-controlled analgesia pumps and transdermal systems for chronic or post-operative pain.
- Oncology Treatment:Ambulatory infusion pumps for chemotherapy and supportive care biologics.
- Hormone Replacement:Subcutaneous or transdermal delivery of peptide hormones including growth hormone and fertility therapies.
Diabetes management holds the installed base. Respiratory therapy expands most quickly through payor quality incentive alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics infrastructure underwrites Europe's distribution dominance for temperature-sensitive drug delivery devices. High-voltage grid interconnects in the Tokyo-Osaka corridor power Japan's precision manufacturing clusters for miniaturized electromechanical components.
United States
Hospital procurement consolidation around direct manufacturer partnerships is displacing traditional distributor intermediaries for insulin pump fleets. FDA software as a medical device guidance and 21 CFR Part 870 premarket notification requirements extend approval timelines for connectivity-enabled systems. The Minneapolis-St. Paul medical device corridor hosts vertically integrated manufacturers securing long-term supply contracts with Medicare Advantage-contracted health systems.
Germany
Established reimbursement codes for 4-year insulin pump replacement cycles and bundled consumables revenue sustain device demand. EMA Medical Device Regulation cybersecurity annex requirements and EU AI Act algorithmic transparency mandates compel quality management system restructuring. The Baden-Württemberg precision engineering cluster concentrates flow sensor and pressure transducer manufacturing for closed-loop delivery systems.
Japan
METI-supported remote monitoring infrastructure investments create favorable reimbursement conditions for cloud-connected drug delivery systems in chronic disease management. PMDA device approval pathways are tightening connectivity validation protocols for smartphone-compatible systems. The Kansai region's aging demographic drives wearable injector adoption among home care providers seeking alternatives to conventional syringes.
Switzerland
Swissmedic's streamlined approval processes for algorithmic dose-adjustment devices attract manufacturers seeking premium positioning in closed-loop insulin delivery. The country's private health insurance landscape supports reimbursement for sensor-integrated systems with ±5% dosing variance. Basel's pharmaceutical-device convergence cluster anchors captive sensor supply chain development for vertically integrated firms.
United Kingdom
NHS long-term plan commitments to diabetes technology access are expanding closed-loop insulin pump provision through integrated care systems. MHRA post-Brexit regulatory alignment with EMA MDR frameworks maintains multi-territory approval pathway coherence. The Cambridge-London health tech corridor concentrates startups developing Bluetooth Low Energy-enabled adherence tracking platforms.
Global Electronic Drug Delivery Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensors, pumps, and connectivity modules. The vendor base concentrates around three strategic archetypes: vertically integrated device-pharma pairings, pure-play wearable injector specialists, and diversified medical technology conglomerates. Competitive dynamics center on direct hospital contracting for longitudinal data ownership and captive sensor supply chain construction.
Among vertically integrated device-pharma pairings, Medtronic and Novo Nordisk A/S exemplify the archetype of manufacturers leveraging therapeutic expertise to extend device offerings alongside pharmaceutical portfolios. Insulet Corporation occupies a defensible niche within the pure-play wearable pump segment. These three firms anchor the competitive structure, with Medtronic's manufacturing footprint, Novo Nordisk's diabetes therapeutic depth, and Insulet's patch-based specialization representing distinct strategic positions within the market's tiered architecture.
| Leading Market Players |
|---|
| Medtronic |
| Insulet Corporation |
| Novo Nordisk A/S |
| Bayer AG |
| Gerresheimer AG |
| BD |
| Tandem Diabetes Care |
| Ypsomed AG |
| Merck Group |
| Others |
Supply & Pricing Matrix
Undercapacity in East Asian sensor fabrication is compressing component availability while elevating procurement leverage for vertically integrated device manufacturers with captive supply arrangements. This utilization squeeze transmits directly into pricing postures across the insulin pump and wearable injector tiers, where flow sensor and pressure transducer sourcing dominates bill-of-materials volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs the market, with FDA 510(k) clearance tier and closed-loop algorithm certification separating premium positioning from commodity Bluetooth-enabled devices. Price differentiation rests on sensor integration depth and EMA MDR cybersecurity annex compliance status. Cost compression in the standard tier is intensifying because mechanical syringe alternatives retain sixty to seventy percent unit cost advantages for single-dose biologics. Hospital procurement committees exhibit highest price sensitivity through direct manufacturer contracting negotiations, while Medicare Advantage-contracted health systems show lowest sensitivity due to quality metric optimization incentives.
Supply Chain Analysis
Extended payment terms from Japanese and German hospital procurement departments are forcing working capital restructuring among contract manufacturers serving the device ecosystem. Component sourcing concentrates in Japan for precision electromechanical assemblies, Germany for flow sensor fabrication, and Taiwan for Bluetooth Low Energy module production. Raw material dependencies include medical-grade polymers, piezoelectric ceramics, and glucose oxidase sensor membranes. Single-source vulnerability in East Asian pressure transducer supply creates exposure to geopolitical trade friction. Distribution runs through direct manufacturer partnerships with integrated delivery networks, bypassing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as home care provider expansion and aging demographic shifts in Japan create niche entry points for specialized wearable injector platforms outside incumbent insulin pump strongholds.
For Market Incumbents: Build captive sensor supply chain moats through backward integration into flow sensor and pressure transducer manufacturing. Secure long-term direct contracting relationships with Medicare Advantage-contracted health systems to lock in longitudinal data ownership. Counter emerging pure-play wearable injector specialists by accelerating closed-loop algorithm development for pediatric endocrinology segments. For New Entrants and Emerging Players: Japan's underpenetrated home care provider channel offers the most accessible white-space target, where METI-supported remote monitoring infrastructure reduces reimbursement friction for cloud-connected devices. Target wearable injector applications for peptide therapeutics beyond insulin, where conventional syringe alternatives dominate. Pursue partnership-based go-to-market models with German pulmonary rehabilitation clinics for nebulizer platform entry. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated device-pharma pairings with demonstrated regulatory pathway expertise across FDA and EMA jurisdictions. Long-term viability favors manufacturers restructuring quality management systems for EU AI Act algorithmic transparency compliance. Watch PMDA connectivity validation protocol tightening as the inflection signal for Japanese market access premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Direct manufacturer contracting with Medicare Advantage networks secures longitudinal patient data ownership. |
| CE Marking Pathway | EMA MDR cybersecurity annex compliance enables premium positioning in German reimbursement clusters. |
| Software Companion Development | Bluetooth Low Energy smartphone integration reduces training burden for Japan's elderly patient populations. |
| Reimbursement Strategy | METI-supported remote monitoring infrastructure alignment unlocks cloud-connected device adoption in home care. |
| Backward Integration | Captive sensor supply chains insulate against East Asian component concentration and trade friction exposure. |
Research Methodology
Operator-level perspectives from biomedical engineers, hospital procurement managers, GPO contracts specialists, and regulatory affairs directors anchored the qualitative base. Primary interview findings triangulated against FDA 510(k) filings, EMA MDR submission databases, hospital procurement contract records, and CMS Medicare reimbursement data. Bottom-up device shipment modeling and top-down therapeutic category spend analysis converged on volume and value estimates.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning product type, connectivity technology tier, end-user channel, and therapeutic application area. CAGRs derived from installed base replacement cycles, reimbursement pathway maturation curves, and biologics pipeline expansion trajectories. Closed-loop algorithm adoption rates and Bluetooth Low Energy ecosystem penetration served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cash-rich pharmaceutical conglomerates entering device manufacturing would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Ostomy Care and Accessories Market
Medical Devices
Intravaginal Device Market
Medical Devices
Coil Assisted Flow Diverters Market
Medical Devices
Rib Fracture Repair Systems Market
Medical Devices
3D-Printed Maxillofacial Implants Market
Medical Devices
Global Brachytherapy Devices Market
Medical Devices
Global Osseointegration Implants Market
Medical Devices
Software As a Medical Device Market
Medical Devices
North America Cardiac Rhythm Management Devices Market
Medical Devices
Dosage Unit Sampling Apparatus Market
Medical Devices
Global Glucometer Market
Medical Devices
Gutta Percha Obturator Market
Medical Devices
Band Ligators Market
Medical Devices
Global Self-Injection Device Market
Medical Devices
Global Heart Valve Devices Market
Medical Devices
Anesthesia Laryngeal Masks Market