
 US Skilled Nursing Facility and Rehabilitation Market | 2026-2036
US Skilled Nursing Facility and Rehabilitation Market Size, Share, and Industry Trends Forecast 2026-2036
US Skilled Nursing Facility and Rehabilitation Market Intelligence
Post-acute referral sources are bifurcating as health systems and Medicare Advantage plans tighten network exclusivity. Genesis HealthCare leverages scale across multiple states to sustain preferred-provider agreements with integrated delivery networks. The Ensign Group differentiates through local leadership autonomy and property-level operational control. Saber Healthcare Group anchors its footprint in secondary markets where hospital divestiture creates partnership openings.
Skilled nursing facilities and rehabilitation centers provide medically necessary post-acute care including wound management, intravenous therapy, and intensive rehabilitation services delivered under 24-hour licensed nursing supervision. Facilities typically operate 100-200 beds with Medicare-certified therapy gyms, respiratory treatment suites, and dementia-secured units designed to reduce hospital readmission rates. Long-term care and short-term rehabilitation represent the dominant type segments, with memory care commanding premium reimbursement due to specialized staffing ratios and secured-environment capital requirements. Physical therapy leads service-type revenue contribution, while post-surgical patients drive fastest end-user volume growth as ambulatory surgical expansion shifts recovery burden to lower-acuity settings.
CMS, the Department of Health and Human Services, and state-level certificate-of-need agencies govern facility licensing, reimbursement methodology, and capital expansion permissions. PDPM and value-based purchasing programs tie Medicare payment to quality metrics, readmission rates, and functional improvement scores. Stakeholders must monitor Medicare Advantage penetration rates and state Medicaid waiver expansions to anticipate reimbursement mix shifts and capital deployment timing.
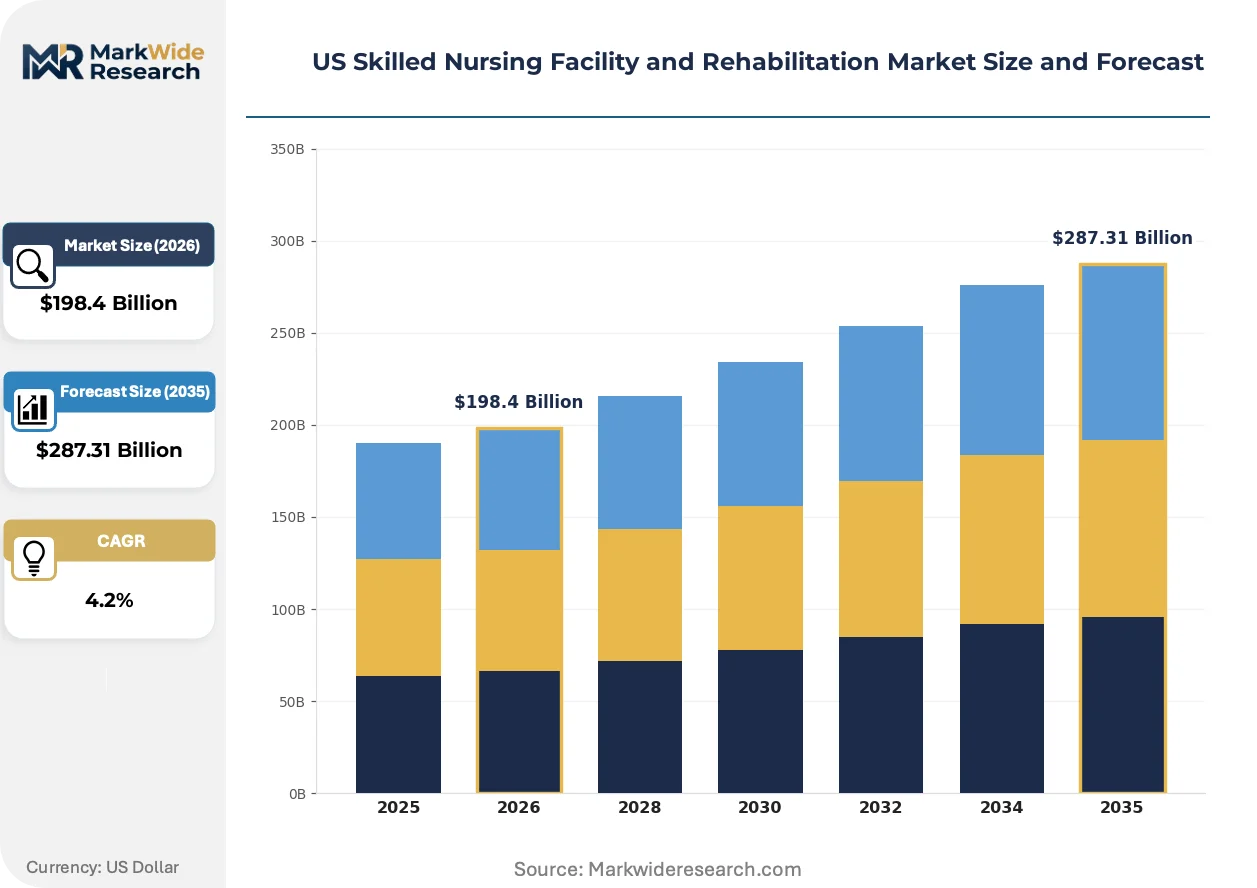
Market Dynamics
CMS value-based purchasing mandates and PDPM payment reforms are compressing reimbursement rates while simultaneously rewarding facilities that demonstrate superior functional outcomes and reduced hospital readmissions. This dual pressure is forcing capital redeployment toward outcome-measurement infrastructure and specialized clinical staffing.
Growth Catalysts
- PDPM Reimbursement Incentives:The Patient-Driven Payment Model rewards facilities for achieving measurable functional improvement scores, directing investment toward intensive therapy staffing and outcome-tracking systems.
- Post-Surgical Volume Migration:Ambulatory surgical centers are discharging patients earlier, transferring recovery and rehabilitation demand to lower-acuity skilled nursing settings with 24-hour nursing coverage.
- Texas and Florida Bed Expansion:Certificate-of-need deregulation in these states permits accelerated facility development where aging migration patterns concentrate demand.
Market Restraints
- CMS Reimbursement Compression:Medicare rate adjustments and sequestration cuts constrain revenue per patient day, limiting margin for technology investment.
- Labor Cost Escalation:Licensed practical nurses and certified nursing assistants command wage premiums in competitive metropolitan markets, elevating operating expense ratios.
- Medicaid Dependency Risk:State budget volatility creates payment timing uncertainty for facilities serving high long-term care populations.
Strategic Opportunities
- Medicare Advantage Network Exclusivity:Tightening preferred-provider agreements with integrated delivery networks creates captive referral streams for contracted facilities.
- Memory Care Premium Positioning:Secured-environment units with specialized staffing ratios command reimbursement premiums from private-pay and supplemental insurance sources.
- Hospital Divestiture Partnerships:Health system exit from post-acute services creates joint venture openings for independent operators in secondary markets.
Industry Challenges
- Interoperability Integration:Electronic health record systems must exchange data with hospital discharge platforms and Medicare reporting databases, requiring substantial IT infrastructure expenditure.
- Quality Metric Compliance:CMS star ratings and readmission penalty programs demand continuous clinical documentation and performance monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Skilled Nursing Facility and Rehabilitation Market |
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $287.31 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Long-Term Care, Short-Term Rehabilitation, Memory Care, Palliative Care Service Type: Occupational Therapy, Physical Therapy, Speech Therapy, Respiratory Therapy End User: Elderly Patients, Post-Surgical Patients, Stroke Survivors, Individuals with Disabilities Facility Size: Small Facilities, Medium Facilities, Large Facilities, Specialty Centers |
| Companies Covered | The Ensign Group, Inc, Genesis HealthCare, Life Care Centers of America, Brookdale Senior Living, Inc, ProMedica Senior Care, Saber Healthcare Group, Sava SeniorCare, Signature HealthCARE, Trilogy Health Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Skilled Nursing Facility and Rehabilitation Market Strategic Shifts & Innovations
Technology deployment is reshaping clinical workflow and patient monitoring capabilities across skilled nursing facilities. Three developments are altering competitive positioning and capital allocation priorities.
Remote patient monitoring systems with wearable biosensors and automated alert protocols are displacing traditional periodic vital sign checks by nursing staff. Post-surgical rehabilitation units in Florida and Texas facilities are deploying these platforms to detect deterioration before emergency transfer becomes necessary. The technology is displacing overnight registered nurse coverage models in lower-acuity wings, enabling labor reallocation toward intensive therapy sessions.
CMS expanded its value-based purchasing program to include skilled nursing facility-specific quality metrics tied to functional improvement and hospitalization rates. Facilities must now report standardized patient assessment data and achieve threshold performance to avoid reimbursement penalties. Texas operators are responding by investing in specialized physical therapy staffing and outcome documentation systems to maintain Medicare revenue integrity.
Integrated delivery networks are consolidating post-acute referral authority through exclusive contracting with preferred skilled nursing partners. Hospital case managers in Florida health systems now route discharged patients to contracted facilities based on quality scores and readmission performance rather than geographic convenience. This concentration is visible most acutely in metropolitan corridors where Medicare Advantage penetration exceeds fifty percent.
US Skilled Nursing Facility and Rehabilitation Market Segmentation
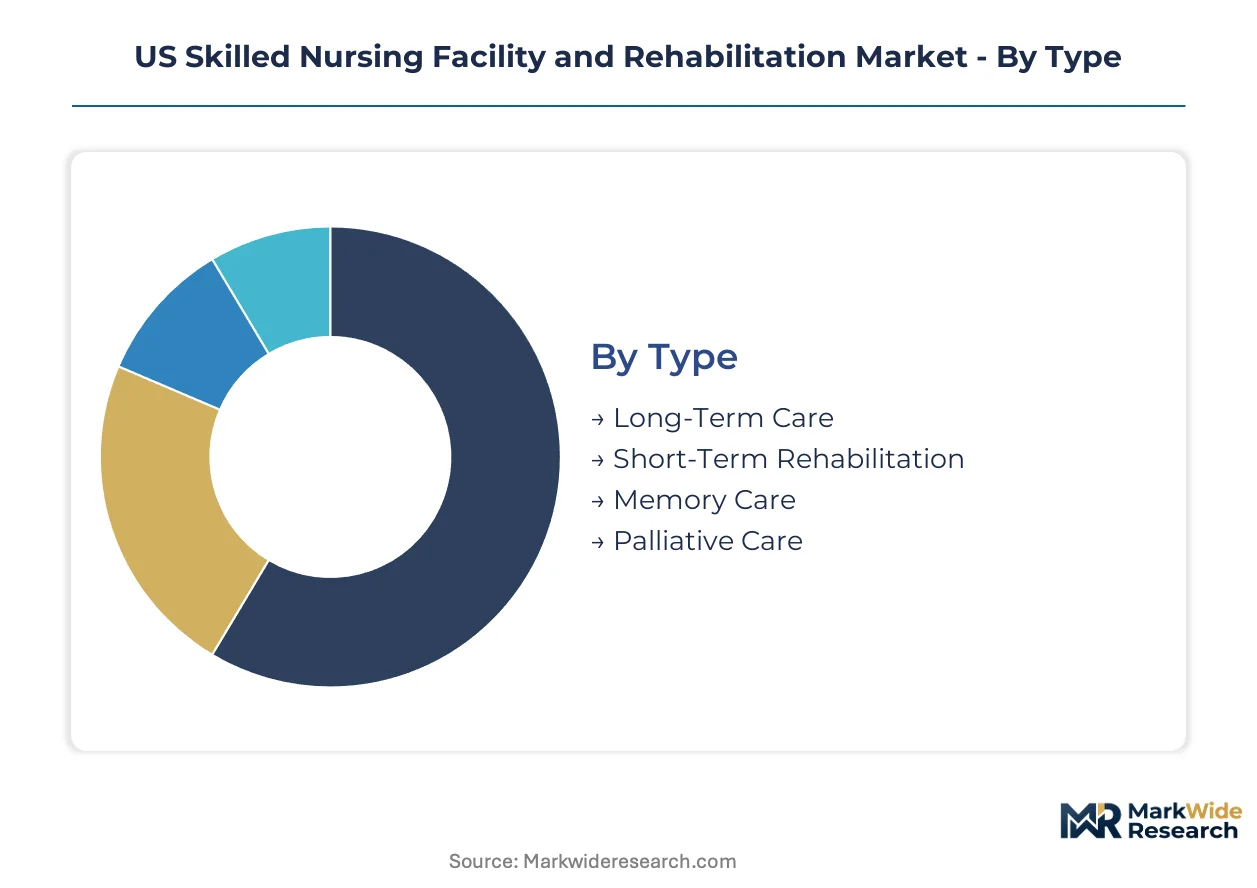
Segmentation in the US skilled nursing market reveals distinct capital intensity profiles and reimbursement dynamics. Facility operators must align service mix with local payer demographics and state Medicaid waiver structures to optimize bed utilization and margin capture.
Type:
Margin pools concentrate in specialized care categories where staffing ratios justify premium reimbursement rates under Medicare and private-pay sources.
- Long-Term Care:Custodial and chronic disease management services delivered in semi-private or private rooms with 24-hour licensed nursing supervision. Demand clusters in Texas and Florida Medicaid expansion counties where aging migration elevates census counts and length-of-stay metrics.
- Short-Term Rehabilitation:Intensive therapy programs designed to restore functional independence following acute hospitalization, typically spanning 20-100 days. Post-surgical patients in Florida metropolitan corridors drive fastest volume expansion as ambulatory surgical centers shorten acute care stays.
- Memory Care:Secured-environment units with specialized dementia training and behavioral management protocols.
- Palliative Care:Symptom-focused medical services for patients with serious illness, emphasizing comfort over curative intervention.
Long-Term Care holds installed capacity. Short-Term Rehabilitation is rotating up the share rankings.
Service Type:
Volume distribution tracks Medicare functional improvement scoring, with therapy minutes directly influencing PDPM reimbursement tiers.
- Physical Therapy:Gait training, strength conditioning, and mobility restoration delivered by licensed therapists in dedicated gym facilities. Texas facilities are expanding PT staffing ratios to capture PDPM case-mix adjustments tied to functional outcome documentation.
- Occupational Therapy:Activities of daily living retraining and adaptive equipment prescription.
- Speech Therapy:Swallowing assessment, cognitive-linguistic intervention, and communication rehabilitation.
- Respiratory Therapy:Ventilator weaning, nebulizer administration, and pulmonary rehabilitation protocols.
Physical Therapy commands the largest labor allocation. Speech Therapy is climbing fastest in specialized neurological recovery units.
End User:
Patient acuity and payer source determine per-diem economics, with commercial insurance and Medicare Advantage creating divergent margin profiles.
- Post-Surgical Patients:Individuals requiring monitored recovery following orthopedic, cardiac, or abdominal procedures. Florida health systems are routing these patients exclusively to contracted skilled nursing partners with demonstrated readmission reduction performance.
- Elderly Patients:Medicare-eligible beneficiaries with multiple chronic conditions requiring coordinated nursing and therapy intervention.
- Stroke Survivors:Patients needing intensive multidisciplinary rehabilitation to regain motor function and speech capacity.
- Individuals with Disabilities:Younger adults with congenital or acquired conditions requiring long-term skilled nursing support.
Elderly Patients constitute the historical census base. Post-Surgical Patients are gaining share fastest through health system integration.
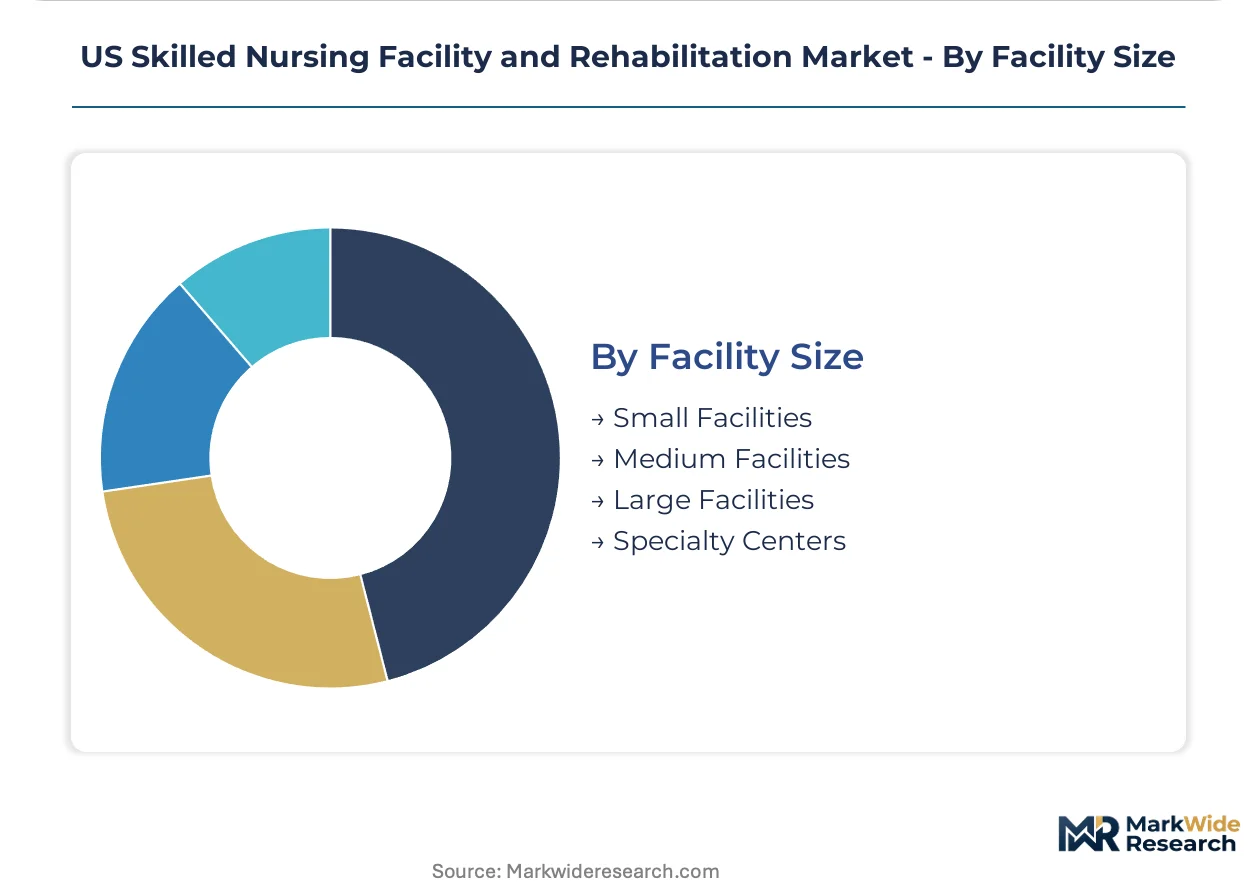
Facility Size:
Scale economics vary with local competitive density and certificate-of-need constraints, with mid-size operations optimizing overhead absorption.
- Large Facilities:150-plus bed operations with dedicated therapy gyms, respiratory suites, and multiple specialized units. Texas CON-deregulated markets permit these developments where land availability and construction costs support capital deployment.
- Medium Facilities:80-150 bed operations balancing clinical breadth with administrative efficiency.
- Small Facilities:Under 80-bed operations serving rural or niche metropolitan submarkets.
- Specialty Centers:Standalone ventilator weaning, wound care, or neurobehavioral facilities with distinct licensing requirements.
Medium Facilities anchor current supply. Large Facilities are expanding most quickly in deregulated Sun Belt markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate Highway System and Medicare reimbursement corridors anchor regional capacity distribution across US skilled nursing markets. Federal highway infrastructure enables patient transport networks that concentrate facility development along migration corridors. State-level certificate-of-need deregulation redirects capital flows toward high-growth corridors.
Texas
Certificate-of-need deregulation permits accelerated bed development in Dallas-Fort Worth and Houston corridors. CMS PDPM reimbursement incentives attract private equity capital toward outcome-measurement infrastructure. Austin and San Antonio metropolitan areas witness fastest large-facility construction as aging migration elevates census demand.
Florida
Medicare Advantage network exclusivity concentrates referral authority in Miami-Dade and Tampa Bay health systems. State Medicaid waiver expansions support long-term care census in retirement migration counties. Orlando and Jacksonville corridor facilities capture post-surgical volume from ambulatory surgical center expansion.
California
OSHA workplace safety mandates and state minimum staffing ratios elevate operating cost structures in Los Angeles and Bay Area markets. Medi-Cal reimbursement compression limits margin for technology investment. San Diego and Inland Empire submarkets attract capital fleeing coastal regulatory intensity.
Ohio
Hospital divestiture of post-acute services creates joint venture openings in Cleveland and Cincinnati integrated delivery networks. State Medicaid managed care penetration reshapes payer mix for Columbus corridor facilities. Midwest labor cost arbitrage supports medium-facility operational efficiency.
Pennsylvania
Philadelphia and Pittsburgh health system consolidation tightens preferred-provider network exclusivity. State-level quality metric reporting requirements parallel CMS star rating systems. Southeastern corridor facilities compete for Medicare Advantage contracted volume through readmission performance differentiation.
US Skilled Nursing Facility and Rehabilitation Market Key Industry Players
Listed leaders compete with private specialists across scale and local operational autonomy dimensions. The market structure fragments between multi-state platforms with integrated delivery network contracts and regional operators with property-level control. Two strategic archetypes dominate: scale-driven consolidators leveraging preferred-provider agreements, and decentralized specialists optimizing local market penetration. Competitive moves concentrate on hospital divestiture partnerships and Medicare Advantage network positioning.
Within the scale-driven tier, Genesis HealthCare and The Ensign Group occupy distinct positioning archetypes. Genesis represents the multi-state platform model with integrated delivery network contracting breadth. Ensign exemplifies decentralized operational control through local leadership autonomy. Saber Healthcare Group anchors the secondary market specialist archetype, capturing partnership openings from hospital post-acute exits. These three patterns illustrate how reimbursement reform and network consolidation reshape competitive positioning across facility types.
| Leading Market Players |
|---|
| The Ensign Group, Inc |
| Genesis HealthCare |
| Life Care Centers of America |
| Brookdale Senior Living, Inc |
| ProMedica Senior Care |
| Saber Healthcare Group |
| Sava SeniorCare |
| Signature HealthCARE |
| Trilogy Health Services |
| Others |
Cost & Logistics Intelligence
Bed-scale economics above 150 units compress per-diem overhead and anchor price floors for Medicare-reimbursed services in Texas and Florida corridors. Certificate-of-need deregulation permits facility clustering that concentrates supply-side capacity, while CMS PDPM reimbursement tiers reward outcome documentation investments that smaller operators cannot absorb.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates memory care secured units from general rehabilitation wings and Medicaid-dependent long-term beds. Price differentiation rests on staffing ratios and outcome-metric certification, with Texas facilities commanding premiums for PDPM-documented functional improvement scores. Pricing pressure stems from Medicare sequestration adjustments and wage inflation for licensed nursing staff. Post-surgical patients routed through Medicare Advantage networks exhibit lowest price sensitivity due to capitated reimbursement structures, while Medicaid-dependent long-term care populations face constrained private-pay capacity.
Supply Chain Analysis
Inbound logistics costs for specialized medical equipment and therapy infrastructure hinge on port congestion at Los Angeles and Houston gateways, with container availability constraining capital deployment timelines for Florida facility expansions. Equipment sourcing draws from domestic manufacturers in Ohio and Pennsylvania for therapy gym apparatus, while respiratory and monitoring systems import from Germany and Japan. Single-source vulnerability concentrates in ventilator and dialysis equipment categories where FDA 510(k) clearance limits supplier substitution. Distribution runs through health system procurement consortia and group purchasing organizations that aggregate demand across integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue layers including remote patient monitoring subscriptions and outcome-based therapy staffing contracts are expanding faster than bed-day reimbursement, creating recurring revenue architectures that decouple operator economics from per-diem volatility.
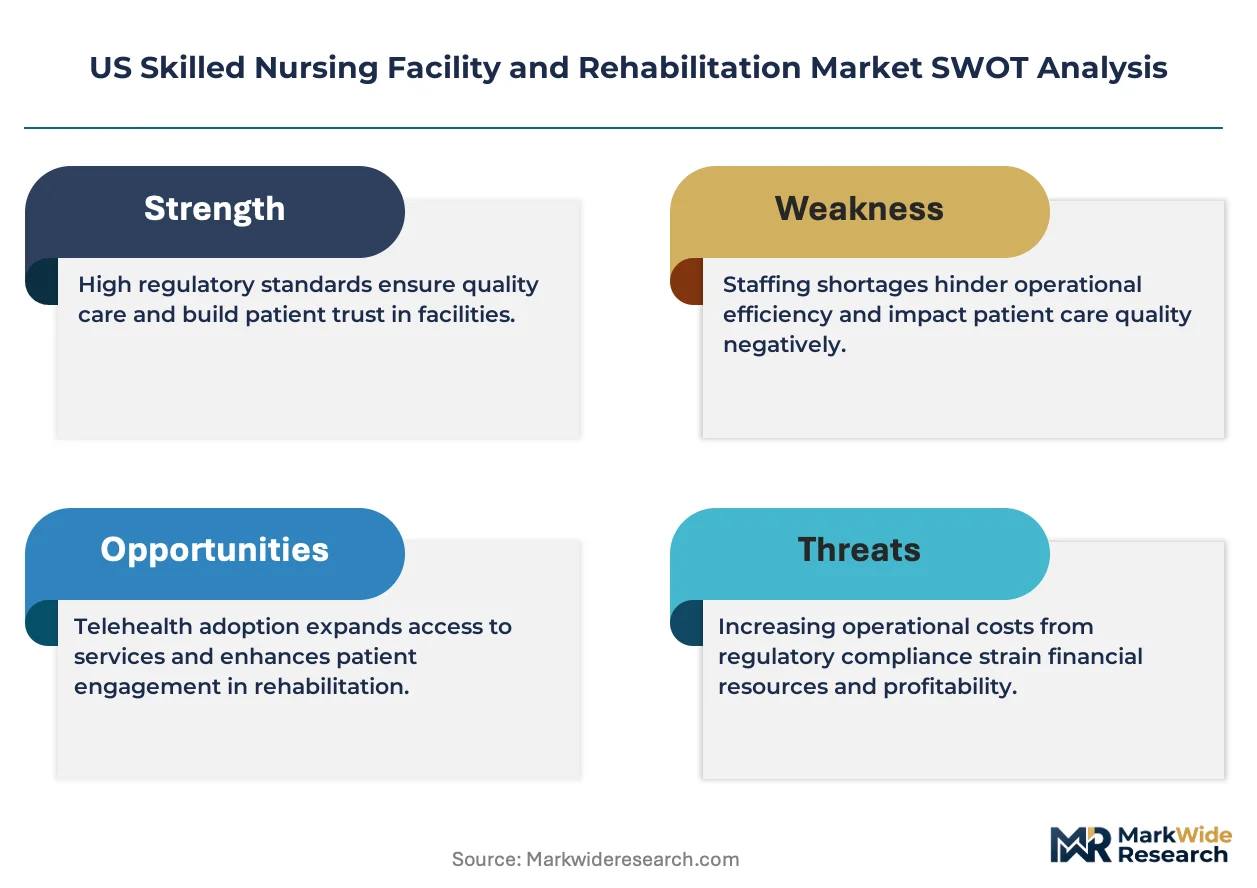
For Market Incumbents: Shield market position by deepening backward integration into therapy staffing agencies and capturing certificate-of-need permits in deregulated Sun Belt corridors before competitor clustering accelerates. CMS value-based purchasing penalties represent the primary threat to revenue integrity, requiring continuous investment in clinical documentation infrastructure. For New Entrants and Emerging Players: Lead with hospital divestiture partnerships in secondary Ohio and Pennsylvania markets where health system exit from post-acute services creates captive referral streams without incumbent scale requirements. Memory care secured-environment units in Florida retirement migration counties offer the most penetrable segment due to private-pay premium capacity and limited specialized supply. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors operators with deployed remote monitoring infrastructure and Medicare Advantage network contracts that lock in referral volume. Long-term viability centers on platforms demonstrating readmission rate performance below CMS penalty thresholds. The signal to watch is Medicare Advantage penetration crossing majority share in target metropolitan corridors, which accelerates exclusive contracting concentration and elevates contracted facility valuations.| Strategic Initiative | Industry Significance |
|---|---|
| PDPM Outcome Documentation Investment | CMS functional improvement scoring directly determines Medicare reimbursement tiers and revenue integrity. |
| Medicare Advantage Network Contracting | Exclusive preferred-provider agreements with Florida and Texas health systems create captive referral streams. |
| Memory Care Secured-Unit Development | Specialized staffing ratios and behavioral management protocols command private-pay premiums above standard rehabilitation. |
| Remote Patient Monitoring Deployment | Wearable biosensor platforms displace overnight registered nurse coverage and enable labor reallocation to intensive therapy. |
| Hospital Divestiture Joint Ventures | Health system exit from post-acute services in Ohio and Pennsylvania creates partnership openings with embedded referral authority. |
Research Approach
Cross-validation between CMS Medicare cost report data and state-level certificate-of-need filings anchors the qualitative findings on capacity deployment patterns. Primary interviews with skilled nursing facility operators, health system case management directors, and Medicare Advantage plan contracting officers combined with secondary validation from CMS star rating databases, state Medicaid waiver filings, and hospital procurement consortium records. Bottom-up bed-count enumeration and top-down reimbursement flow analysis triangulate market sizing across the analysis window.
Sensitivity analysis on PDPM case-mix adjustment coefficients and Medicare Advantage penetration trajectories shapes the analytical framework. Segmentation dimensions modeled include facility type, service mix intensity, payer source concentration, and geographic regulatory cluster. CAGRs derive from regression against demographic migration patterns and reimbursement methodology shifts. Forecast inputs incorporate ambulatory surgical center discharge volume projections and state-level Medicaid waiver expansion schedules.
Forecasts assume regulatory continuity in CMS value-based purchasing and PDPM reimbursement methodologies; material policy shifts would require re-modeling. Specific risks include Medicare sequestration renewal, state Medicaid rate compression, and labor cost acceleration in competitive metropolitan markets. Recalibration cycles align with material shifts in Medicare Advantage network contracting intensity and certificate-of-need regulatory changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Facilities
Sauna and Spa Market
Healthcare Facilities
Qatar Senior Living Market
Healthcare Facilities
Assisted Living Facilities Market
Healthcare Facilities
US Ambulatory Surgery Centers Market
Healthcare Facilities
US Skilled Nursing Facility Market
Healthcare Facilities
Private Office-Based Clinics Market
Healthcare Facilities
Global Healthcare Facilities Management Market
Healthcare Facilities
US Assisted Living Facility Market
Healthcare Facilities
Mobile Hospitals Market
Healthcare Facilities
Confinement Center Market
Healthcare Facilities
Ambulatory Surgical Centers Market
Healthcare Facilities
US and Europe Ambulatory Surgery Centers Market
Healthcare Facilities
Hospital Lighting Market
Healthcare Facilities
US Hospital Facilities Market
Healthcare Facilities
Trauma Care Centers Market
Healthcare Facilities
Longevity Clinic Chain Infrastructure Market