
 Trauma Care Centers Market | 2026-2036
Trauma Care Centers Market Size, Share, and Industry Trends Forecast 2026-2036
Trauma Care Centers Market Intelligence
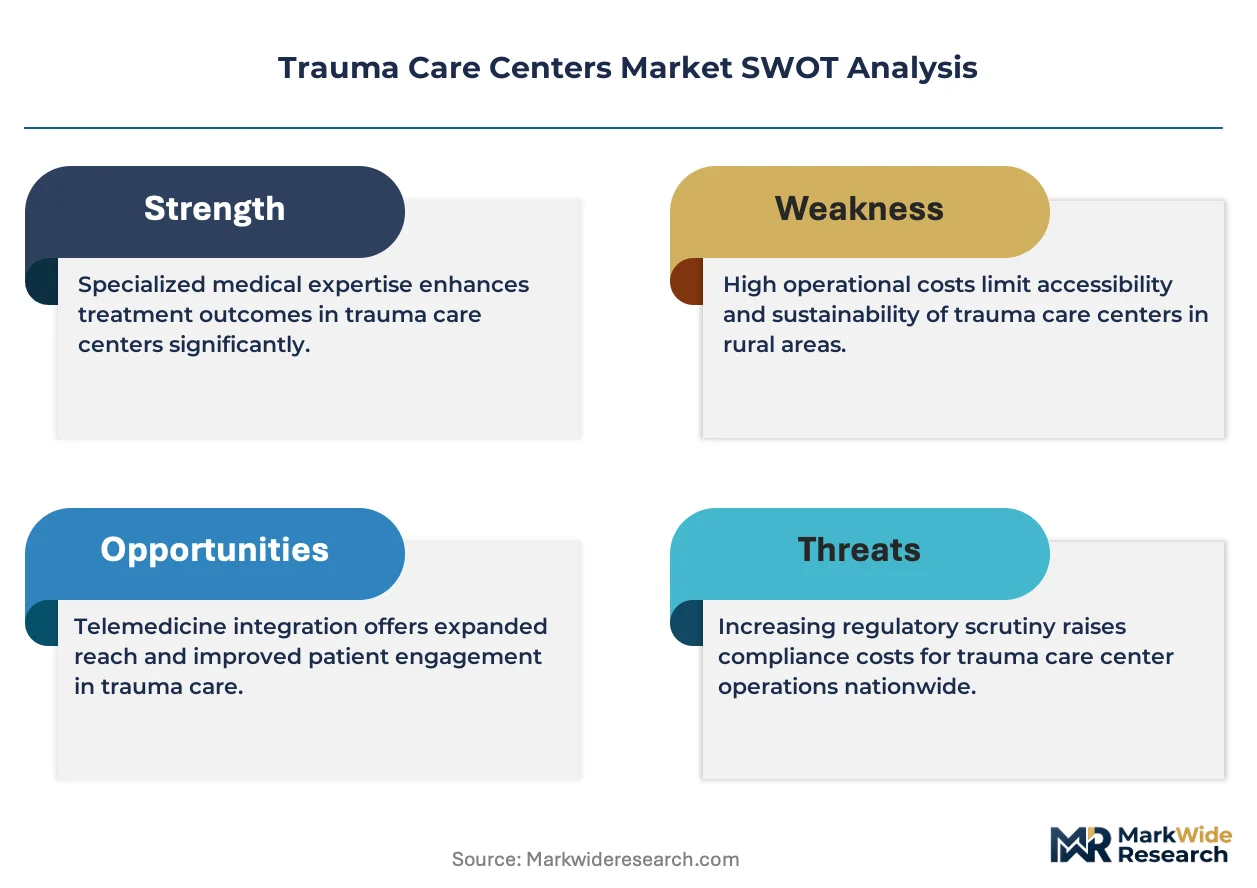
Hospital referral networks is tilting toward regionalized trauma systems that concentrate complex cases at designated centers. HCA Healthcare controls extensive emergency department networks across multiple states. Mayo Clinic anchors its trauma reputation through integrated surgical and rehabilitation pathways. Johns Hopkins Hospital competes on R&D intensity in trauma surgery and critical care protocols.
Trauma care centers deliver time-critical medical intervention for severe injuries, operating under tiered certification systems that mandate specific surgical capabilities, neurosurgical coverage, and blood bank availability around the clock. Emergency departments represent the highest-volume entry point, while surgical intervention commands the largest margin pool due to specialized staffing and equipment intensity. Telemedicine is displacing traditional consultation models for rural trauma triage, and advanced imaging sustains diagnostic speed in high-acuity workflows.
The FDA oversees blood product and device standards used in trauma resuscitation, while state health departments enforce trauma center designation protocols that determine reimbursement eligibility and ambulance routing. CMS conditions Medicare payments on compliance with trauma activation and quality reporting requirements. Stakeholders must monitor how state-level certificate-of-need laws and Medicaid expansion decisions reshape patient volume distribution across competing centers.
Market Dynamics
Regionalized trauma systems are concentrating complex cases at designated receiving facilities, reshaping ambulance routing protocols and reimbursement eligibility across municipal networks. State health departments use Level I through IV certification tiers to mandate surgical capabilities, neurosurgical coverage, and blood bank availability, directly determining which centers capture high-acuity volume.
Growth Catalysts
- CMS Quality Reporting Mandates:Medicare payment conditioning on trauma activation compliance drives capital investment in monitoring infrastructure and staff training protocols.
- Telemedicine Triage Expansion:Rural emergency medical services now route patients through video consultation with trauma surgeons before transport decisions, compressing time-to-treatment metrics.
- Texas Uninsurance Dynamics:Elevated trauma volumes and uncompensated care pools sustain some of the nation's busiest designated receiving facilities, attracting specialized surgical staffing.
Market Restraints
- Surgical Specialist Scarcity:Twenty-four-hour neurosurgical and orthopedic trauma coverage requirements strain staffing pools, particularly in non-urban catchment areas.
- Certificate-of-Need Laws:State-level CON restrictions in multiple jurisdictions block new trauma center designations, protecting incumbent volume but limiting network expansion.
- Blood Product Supply Volatility:O-negative and platelet inventory management requires continuous cold-chain logistics, with regional shortages disrupting resuscitation capacity.
Strategic Opportunities
- Mobile Integrated Healthcare:Community paramedicine programs extend trauma stabilization capabilities into pre-hospital environments, creating new reimbursement categories.
- AI-Assisted Triage Convergence:Machine learning algorithms processing vital signs and injury patterns are digitizing field triage decisions, reducing overtriage rates.
- Medicaid Expansion Tailwinds:States expanding eligibility generate insured trauma volumes that improve center financial sustainability and capital access.
Industry Challenges
- Level I Certification Timelines:The multi-year process for ACS verification and state designation delays operational revenue generation for new entrants.
- Interoperability Friction:Legacy electronic health record systems resist integration with regional trauma registries, complicating quality reporting and outcome tracking.
- Burnout-Driven Turnover:Emergency medicine and trauma surgery subspecialties face elevated attrition, destabilizing the 24/7 coverage models that certification mandates require.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trauma Care Centers Market |
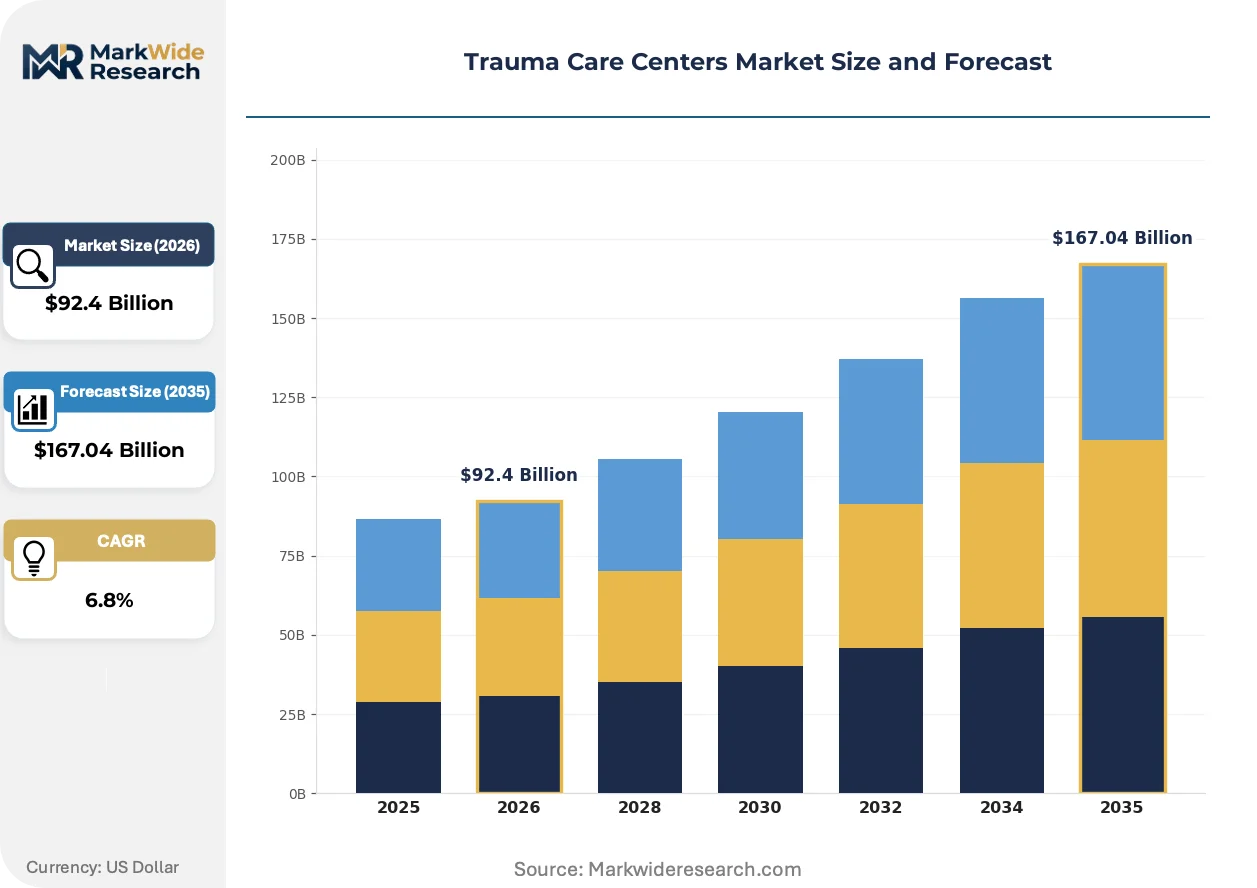
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $167.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Care Setting: Emergency Departments, Urgent Care Facilities, Surgical Centers, Rehabilitation Units Service Type: Acute Care, Surgical Intervention, Post-Operative Care, Counseling Services Patient Demographics: Children, Adults, Elderly, Trauma Survivors Technology: Telemedicine, Advanced Imaging, Wearable Devices, Electronic Health Records |
| Companies Covered | CommonSpirit Health, Cleveland Clinic, Banner Health, HCA Healthcare, Mayo Clinic, Ascension Health, Johns Hopkins Hospital, Community Health Systems, Northwell Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trauma Care Centers Market Strategic Shifts & Innovations
Advanced imaging and artificial intelligence are compressing diagnostic timelines in high-acuity workflows, while regulatory pressure on quality transparency reshapes competitive positioning among designated facilities.
Point-of-care ultrasound is digitizing bedside assessment in emergency departments and field settings. Rural EMS agencies and smaller community hospitals lacking CT capacity now deploy portable devices for FAST examinations and vascular access. This capability is digitizing the traditional radiologist-dependent diagnostic pathway, enabling faster hemorrhage detection and surgical triage decisions.
The FDA enforces blood product and device standards for trauma resuscitation, while state health departments administer designation protocols that determine ambulance routing and reimbursement eligibility. CMS conditions Medicare payments on trauma activation compliance and quality reporting. Level I centers in high-volume states invest most heavily in regulatory infrastructure to maintain preferred receiving status.
Hospital procurement departments now bundle trauma device contracts across integrated delivery networks, consolidating vendor relationships and standardizing implant inventories. This concentration displaces the hospital-by-hospital purchasing patterns that previously dominated orthopedic trauma and neurosurgical equipment markets. Texas and Florida health systems demonstrate the most advanced procurement integration, leveraging scale across multiple designated centers.
Trauma Care Centers Market Segmentation
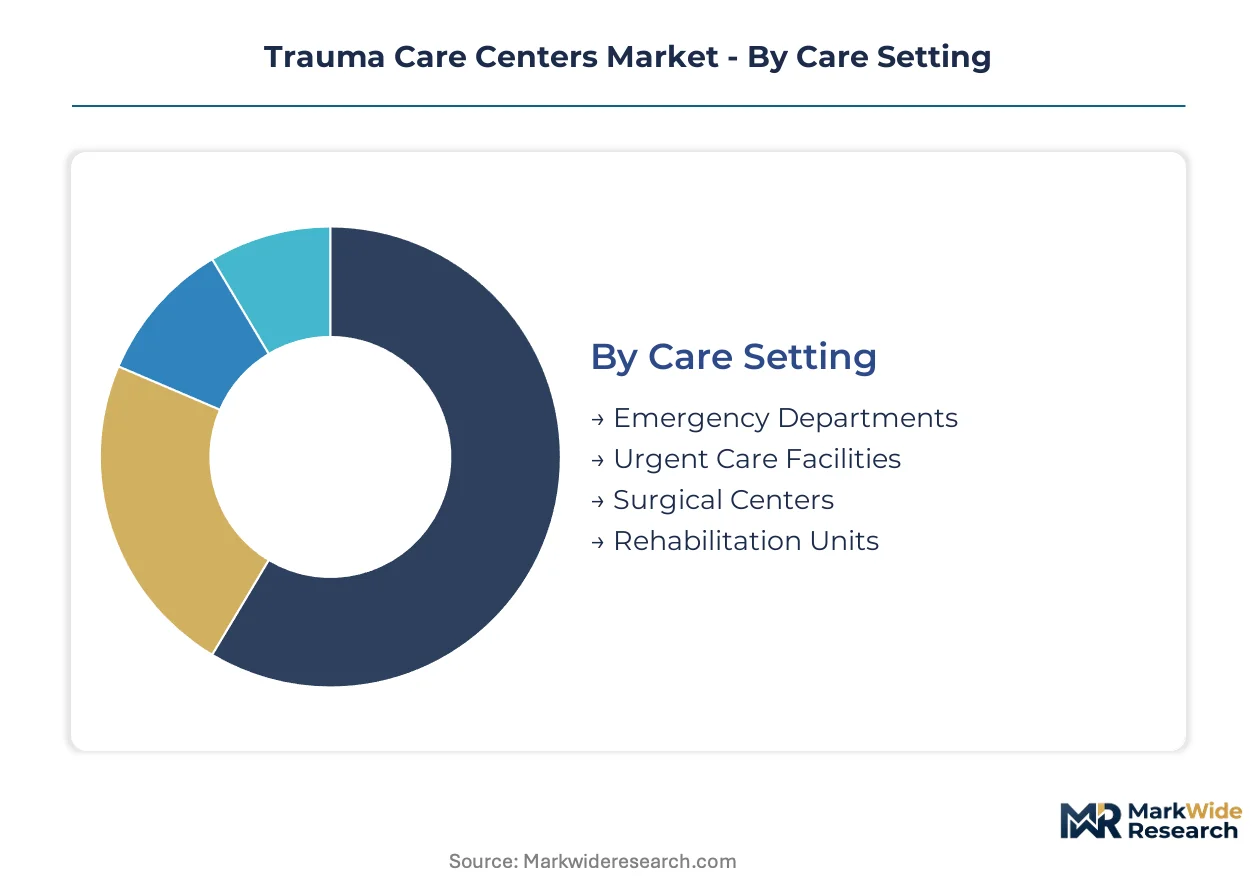
Trauma care delivery fragments across distinct operational models, each carrying unique certification burdens and reimbursement profiles. Understanding how patients flow through these segments clarifies where capital deployment yields the strongest returns.
Care Setting:
Volume concentration across these settings tracks directly to state designation tiers and ambulance routing protocols.
- Emergency Departments:These 24/7 intake nodes manage the highest patient throughput under Level I through IV mandates. Texas and Florida municipal networks route the majority of field-originating cases to designated EDs, sustaining disproportionate trauma activation volumes.
- Surgical Centers:Specialized facilities concentrate complex orthopedic and neurosurgical interventions requiring blood bank proximity and intensivist coverage. Certificate-of-need laws in multiple states protect incumbent surgical center volume by blocking new designations.
- Urgent Care Facilities:Lower-acuity extensions handle stabilized transfers and minor trauma overflow.
- Rehabilitation Units:Post-acute settings manage functional recovery and long-term disability protocols.
Emergency Departments command the established base. The steepest expansion runs through Surgical Centers as regionalization concentrates complex cases.
Service Type:
Margin profiles diverge sharply across these service lines based on staffing intensity and equipment utilization rates.
- Surgical Intervention:Complex procedures generate the largest margin pools through specialized orthopedic, neurosurgical, and thoracic capabilities. Blood product availability and 24-hour anesthesia coverage requirements create high barriers that limit competitor entry.
- Acute Care:Resuscitation and stabilization protocols dominate the immediate post-arrival window. CMS conditions Medicare reimbursement on trauma activation compliance and quality reporting metrics.
- Post-Operative Care:ICU management and step-down monitoring extend length-of-stay economics.
- Counseling Services:Psychological and social work interventions address trauma survivor mental health needs.
Surgical Intervention anchors revenue concentration. Acute Care is gaining share fastest as activation protocols expand to capture more incoming volume.
Patient Demographics:
Reimbursement reliability and clinical complexity vary substantially across age cohorts and injury severity profiles.
- Adults:Working-age trauma victims present the highest absolute volume across motor vehicle collisions, occupational injuries, and interpersonal violence. Commercial insurance penetration in this cohort improves collection rates versus Medicare-dependent elderly populations.
- Elderly:Falls and fragility fractures drive disproportionate resource consumption through longer ICU stays and rehabilitation needs. Medicaid expansion states see improved reimbursement for this demographic.
- Children:Pediatric trauma requires specialized surgical capabilities and dosing protocols.
- Trauma Survivors:Repeat utilizers and complex polytrauma cases strain care coordination resources.
Adults represent the volume core. The elderly demographic is expanding most quickly as population aging accelerates injury-related hospitalization.
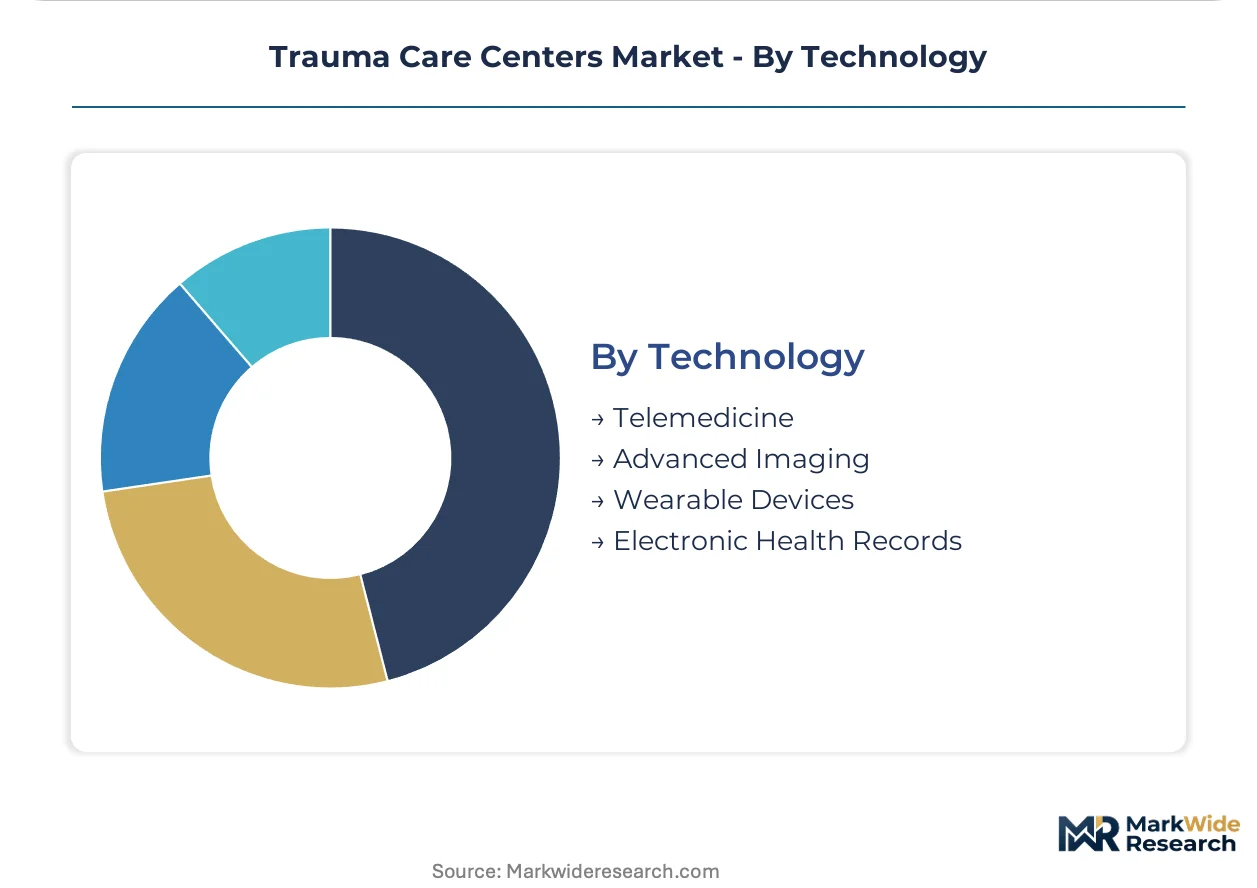
Technology:
Capital allocation across these technology categories determines diagnostic speed and rural reach.
- Advanced Imaging:CT, MRI, and interventional radiology capabilities compress time-to-diagnosis for hemorrhage detection and vascular injury. Point-of-care ultrasound deployment in rural EMS agencies substitutes for radiologist-dependent pathways.
- Telemedicine:Video consultation platforms enable pre-hospital triage decisions by connecting rural EMS with trauma surgeons. Texas health systems demonstrate the most mature telemedicine trauma networks.
- Electronic Health Records:Interoperability with regional trauma registries remains a persistent implementation challenge.
- Wearable Devices:Pre-hospital vital sign transmission and field monitoring applications are emerging.
Advanced Imaging commands the established base. Telemedicine is climbing the fastest as rural network expansion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas trauma centers command premium reimbursement rates against California's compressed Medicaid schedules, creating a pricing-power asymmetry that shapes capital deployment across municipal networks. Designated receiving facilities in high-uninsurance states capture disproportionate federal disproportionate share hospital payments.
United States
Texas sustains the nation's busiest Level I trauma volumes through elevated motor vehicle collision rates and uncompensated care pools. CMS conditions Medicare payments on trauma activation compliance and quality reporting requirements. Houston's Texas Medical Center anchors the country's largest concentration of verified trauma centers.
Germany
The country's national pharmaceutical regulator enforces CE marking requirements for trauma resuscitation devices under EU MDR frameworks. Bavaria's university hospital networks concentrate polytrauma expertise in Munich and Nuremberg metropolitan clusters.
United Kingdom
NHS England's regional trauma networks route complex cases through 27 designated major trauma centers. The Care Quality Commission inspects against National Institute for Health and Care Excellence guidelines. London's Royal London Hospital and Birmingham's Queen Elizabeth Hospital anchor the busiest receiving corridors.
Japan
PMDA oversees medical device approvals for trauma care equipment while METI coordinates emergency medical system standards. Tokyo's St. Luke's International Hospital and Osaka University Hospital anchor designated trauma center networks serving the Kanto and Kansai megaregions.
Australia
TGA regulates blood product standards and trauma device certifications used in resuscitation protocols. New South Wales and Victoria operate the most mature state trauma systems, with Royal North Shore Hospital in Sydney and The Alfred Hospital in Melbourne capturing the highest activation volumes.
Trauma Care Centers Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in device and pharmaceutical supply. The vendor base clusters around three archetypes: integrated delivery networks spanning multiple states, academic medical centers competing on surgical subspecialty depth, and community hospital systems feeding into regional referral hierarchies. Dominant competitive moves include horizontal consolidation through hospital acquisitions and vertical integration into physician staffing.
Within the integrated network tier, HCA Healthcare and CommonSpirit Health exemplify scale-driven platform operators, while Mayo Clinic and Johns Hopkins Hospital occupy positions as academic anchors competing on research intensity and subspecialty reputation. Banner Health and Northwell Health represent regional consolidators building trauma network density across their respective catchment areas.
| Leading Market Players |
|---|
| CommonSpirit Health |
| Cleveland Clinic |
| Banner Health |
| HCA Healthcare |
| Mayo Clinic |
| Ascension Health |
| Johns Hopkins Hospital |
| Community Health Systems |
| Northwell Health |
| Others |
Cost & Logistics Intelligence
The I-35 freight corridor linking Dallas-Fort Worth trauma centers to Houston's Texas Medical Center concentrates blood product logistics costs, with cold-chain transportation premiums widening the spread between Level I certification-grade pricing and standard emergency department rates across municipal networks.
Pricing Analysis
The customization-premium spread between configured trauma activation protocols and standard emergency department pricing runs wide across certification tiers. Three-tier pricing structure across premium, standard, and economy levels segments by ACS verification status, with Level I centers commanding substantial premiums for 24-hour neurosurgical coverage. Cost compression in standard-tier facilities is intensifying because certificate-of-need laws protect incumbent volume while limiting new designation competition. Rural community hospitals exhibit the highest price sensitivity, while integrated delivery networks with multiple designated centers demonstrate the least.
Supply Chain Analysis
Tariff exposure between the United States and China dominates trauma device procurement risk, particularly for orthopedic implants and portable imaging equipment. Manufacturing concentrates in the United States, Germany, and China for specialized surgical instruments and resuscitation devices. Supply chains draw from titanium alloy feedstocks, sterile barrier packaging, and O-negative blood product inventories. Single-source vulnerability persists for platelet apheresis kits and specialized trauma retractor systems. Distribution runs through integrated delivery network procurement departments that bundle contracts across multiple designated centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trauma care centers represent a service-attach opportunity where telemedicine consultation subscriptions and mobile integrated healthcare programs expand faster than physical infrastructure capital, with recurring revenue layers capturing rural network extension economics.
For Market Incumbents: Pre-empt telemedicine platform consolidation by acquiring rural EMS routing contracts before regional competitors lock in exclusive ambulance diversion agreements. HCA Healthcare and CommonSpirit Health demonstrate scale advantages in multi-state network density that new entrants cannot replicate without years of certificate-of-need navigation. Backward integration into blood bank logistics reduces supply volatility exposure. For New Entrants and Emerging Players: Level IV trauma centers in Medicaid expansion states represent the most penetrable entry point, particularly in suburban corridors adjacent to saturated Level I markets. Community paramedicine programs in Florida and Arizona offer lower regulatory barriers than full surgical center designation. Partner with existing ambulance services for preferred routing status rather than building de novo emergency department capacity. For Investors and Strategic Acquirers: Carve-out targets emerge from academic medical center trauma divisions seeking operational efficiency through private equity-backed management services organizations. Long-term viability hinges on Medicare reimbursement stability and state Medicaid expansion trajectories. Watch for CMS trauma activation compliance score changes as early signals of center financial stress.| Strategic Initiative | Industry Significance |
|---|---|
| Telemedicine Triage Network Expansion | Texas health systems compress rural time-to-treatment through video surgeon consultation protocols. |
| Certificate-of-Need Positioning | Incumbent centers in Florida and Georgia protect volume through regulatory barrier maintenance. |
| Blood Bank Logistics Integration | Cold-chain control reduces platelet shortage disruptions during mass casualty events. |
| AI-Assisted Field Triage Deployment | Machine learning algorithms processing EMS vital signs reduce overtriage rates and transport costs. |
| Medicaid Expansion Market Entry | States expanding eligibility generate insured trauma volumes improving center financial sustainability. |
Research Approach
Operator-level perspectives from trauma surgeons, EMS medical directors, hospital procurement managers, and state health department certification officers anchored the qualitative base. Primary interviews combined with secondary validation from CMS Medicare cost reports, state trauma registry submissions, and American College of Surgeons verification databases. Bottom-up facility-level capacity modeling triangulated against top-down health system expenditure tracking across the analysis window.
Scenario-bracketing framed projections across care setting, service type, patient demographic, and technology adoption dimensions. CAGRs derived from regression analysis of historical trauma activation volumes against population injury incidence rates and reimbursement schedule changes. Forecast inputs incorporated telemedicine penetration curves and certificate-of-need law repeal probability assessments.
Practitioners should monitor CMS trauma activation compliance metric revisions and state Medicaid expansion ballot initiatives for early signals of volume redistribution. Forecasts reflect assumptions about regulatory stability and blood product supply continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Facilities
Asia-Pacific Smart Hospital Market
Healthcare Facilities
US Hospital Facilities Market
Healthcare Facilities
Longevity Clinic Chain Infrastructure Market
Healthcare Facilities
Confinement Center Market
Healthcare Facilities
Private Office-Based Clinics Market
Healthcare Facilities
US and Europe Ambulatory Surgery Centers Market
Healthcare Facilities
US Ambulatory Surgery Centers Market
Healthcare Facilities
US Ambulatory Surgical Centers Market
Healthcare Facilities
Ambulatory Surgical Centers Market
Healthcare Facilities
Hospital Lighting Market
Healthcare Facilities
Global Healthcare Architecture Market
Healthcare Facilities
US Assisted Living Facility Market
Healthcare Facilities
US Office-Based Labs Market
Healthcare Facilities
Bedless Hospitals Market
Healthcare Facilities
Sauna and Spa Market
Healthcare Facilities
Micro-Hospitals Market