
 Global Healthcare Facilities Management Market | 2026-2036
Global Healthcare Facilities Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Facilities Management Market Foresight
Modular service bundling is broadening buyer choice across the Global Healthcare Facilities Management Market. ABM Industries leverages its technical workforce scale to anchor integrated hard and soft service contracts for large hospital systems. Sodexo differentiates through foodservice and clinical support integration, while CBRE Group extends its real estate platform into healthcare-specific compliance and capital planning.
Healthcare facilities management encompasses the operational oversight of physical healthcare environments including HVAC filtration performance, emergency power redundancy, infection control protocols, and regulatory compliance maintenance to ensure continuous clinical service delivery. The service type dimension shows maintenance management and energy management commanding the deepest margin pools due to capital-intensive equipment lifecycles and sustainability retrofit mandates. Application segmentation reveals hospitals absorbing the largest contract value, though ambulatory surgical centers represent the fastest-growing site category as outpatient volume shifts accelerate.
FDA environmental health requirements and OSHA workplace safety standards shape service specifications and vendor qualification thresholds across the United States, while the EU Green Deal and REACH chemical protocols drive material substitution and waste stream documentation in European contracts. Stakeholders must monitor how building automation technology integration redefines vendor capability requirements and contract scope boundaries.
Market Dynamics
Healthcare facilities management is restructuring around building automation convergence, where IoT-enabled HVAC and energy systems now demand vendors who can bridge operational technology with clinical compliance rather than siloed maintenance contracts.
Growth Catalysts
- EU Green Deal retrofit mandates:European healthcare estates must achieve building efficiency targets by 2030, forcing integrated energy-service contracts that bundle capital upgrades with long-term operations.
- Outpatient volume migration:Ambulatory surgical centers in the United States require specialized infection control and emergency power protocols, expanding addressable contract scope beyond traditional hospital footprints.
- India's multi-site hospital consolidation:Private chains in Mumbai, Delhi, and Bangalore are standardizing facilities management across networks, creating demand for centralized vendor platforms.
Market Restraints
- Skilled technician scarcity:Certification requirements for medical gas systems and emergency generator maintenance outpace vocational training pipeline expansion in Germany and France.
- Energy price volatility:Natural gas and electricity input cost swings compress margin predictability for fixed-price energy management contracts.
- Legacy infrastructure lock-in:Aging pneumatic HVAC controls in Northeastern US hospitals resist digital retrofit without full system replacement.
Strategic Opportunities
- Saudi Arabia healthcare privatization:Vision 2030 hospital outsourcing creates greenfield integrated facilities management contracts without legacy vendor displacement costs.
- Digital twin convergence:Building information modeling merged with real-time sensor networks enables predictive maintenance pricing models.
- Japan's hospital energy efficiency subsidies:METI incentives for geothermal and solar thermal adoption subsidize vendor-led capital deployment.
Industry Challenges
- Cross-functional credentialing complexity:Joint Commission accreditation, OSHA bloodborne pathogen training, and EPA refrigerant handling certifications create 18-24 month vendor onboarding timelines.
- Interoperability friction:Proprietary building automation protocols from Siemens, Johnson Controls, and Honeywell resist unified dashboard integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Facilities Management Market |
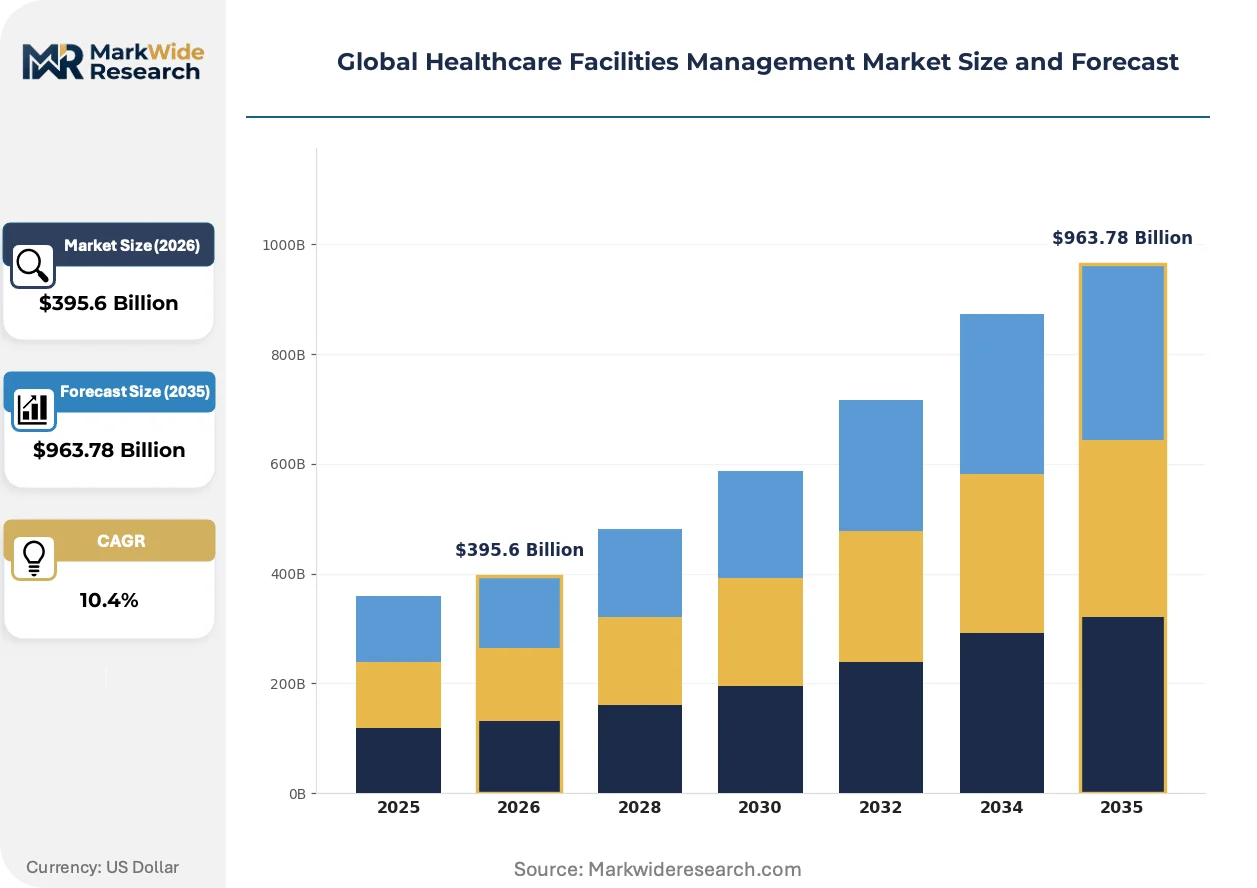
| Market Size in 2026 | $395.6 Billion |
| Market Size in 2035 | $963.78 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance Management, Cleaning Services, Security Management, Waste Disposal, Energy Management, Landscaping Application: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Rehabilitation Centers, Long-term Care Facilities, Medical Offices Technology: IoT Sensors, Building Information Modeling, Computerized Maintenance Management Systems, Automated IoT Controls, Mobile Facility Management Apps, RFID Tracking End User: Hospital Administrators, Clinic Managers, Laboratory Supervisors, Rehabilitation Coordinators, Nursing Home Directors, Outpatient Facility Leaders |
| Companies Covered | ABM Industries, Aramark Corporation, ISS World Services, Sodexo, Ecolab, Compass Group, Cushman & Wakefield, CBRE Group, Jones Lang LaSalle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Facilities Management Market Shifts & Advancements
Facilities management is pivoting from reactive maintenance to predictive operational models, where real-time environmental monitoring and automated compliance documentation reshape vendor capability requirements and contract value capture.
Edge computing architectures embedded within HVAC control panels are decentralizing building management intelligence. Large hospital systems in Texas and Florida are deploying these systems to process filtration performance and occupancy data locally rather than routing through centralized BAS servers. This architecture is decentralizing vendor service models by enabling regional facilities teams to execute autonomous interventions without headquarters escalation.
REACH chemical substitution protocols are forcing material changes in cleaning agents, sealants, and insulation across European healthcare contracts. The regulation bans per- and polyfluoroalkyl substances in waterproofing membranes and mandates waste stream documentation for hazardous material removal. German hospital procurement departments are now requiring vendors to submit full substance inventories and substitution roadmaps as contract preconditions.
Consolidated service agreements are compressing vendor rosters as health systems seek single-accountability partners. United States-based hospital networks are replacing fragmented mechanical, foodservice, and security contracts with unified performance-based arrangements. This concentration is most visible in the Southeast, where systems like HCA and Tenet are bundling five to seven previously separate service lines under master agreements with penalty-clause performance metrics.
Global Healthcare Facilities Management Market Segmentation
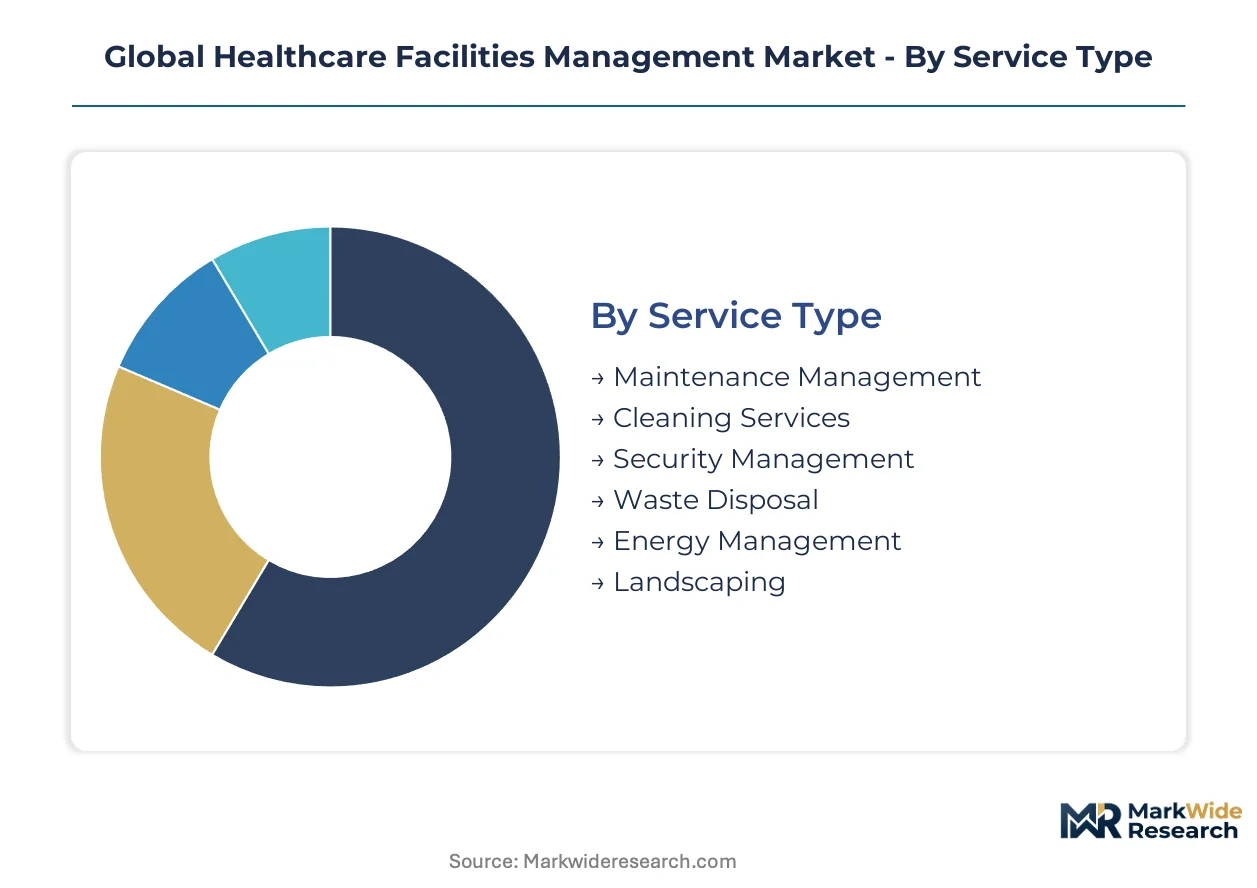
Healthcare facilities management vendors configure service portfolios around clinical risk tiers and infrastructure complexity. Segmentation choices determine margin capture, credentialing requirements, and technology integration depth across acute and non-acute care environments.
Service Type:
Customization intensity varies sharply across this spectrum, from rigid regulatory compliance services to discretionary aesthetic offerings.
- Maintenance Management:Encompasses preventive and corrective upkeep of HVAC, electrical, plumbing, and medical gas systems. Demand concentrates in aging Northeastern US hospital infrastructure where Joint Commission accreditation mandates drive outsourcing. Technicians require EPA refrigerant handling and ASHE healthcare engineering certifications.
- Energy Management:Combines consumption monitoring, efficiency retrofits, and renewable integration under performance contracts. German and French hospital estates dominate procurement volume following EU Green Deal retrofit deadlines and REACH material substitution protocols.
- Cleaning Services:Terminal disinfection, terminal cleaning, and daily environmental hygiene protocols.
- Security Management:Access control, visitor management, and emergency response coordination.
- Waste Disposal:Segregated handling of biohazardous, pharmaceutical, and radioactive streams.
- Landscaping:Exterior grounds maintenance and therapeutic garden upkeep.
Most installed capacity flows through Maintenance Management. Expansion is steepest in Energy Management.
Application:
Site complexity scales from 24/7 critical care environments to scheduled outpatient operations.
- Hospitals:Multi-building campuses requiring integrated hard services, emergency power redundancy, and infection control infrastructure. US health systems in Texas and Florida absorb the largest contract values as they consolidate vendor rosters under master agreements.
- Ambulatory Surgical Centers:Freestanding facilities with specialized HVAC filtration and rapid sterilization turnaround requirements. India's tier-one private chains in Mumbai and Bangalore are deploying standardized facilities management across multi-site networks.
- Diagnostic Laboratories:Controlled environments for specimen processing and equipment calibration.
- Rehabilitation Centers:Patient mobility-focused spaces with adaptive equipment maintenance needs.
- Long-term Care Facilities:Residential care settings with dietary and life safety service integration.
- Medical Offices:Physician practice buildings with lighter compliance burdens.
Hospitals command the deepest contract values. Ambulatory Surgical Centers are climbing the fastest as outpatient migration accelerates.
Technology:
Digital maturity divides vendors between legacy reactive maintenance and predictive operational platforms.
- IoT Sensors:Environmental monitoring nodes tracking temperature, humidity, air pressure, and occupancy in real-time. Texas hospital systems deploy edge-computing architectures that process filtration data locally without centralized BAS server dependency.
- Building Information Modeling:3D digital twins enabling spatial asset tracking and retrofit simulation. Japanese METI-subsidized hospital energy programs leverage BIM-integrated geothermal and solar thermal planning.
- Computerized Maintenance Management Systems:Work order automation and asset lifecycle databases.
- Automated IoT Controls:Self-adjusting HVAC and lighting systems responding to occupancy patterns.
- Mobile Facility Management Apps:Field technician dispatch and documentation tools.
- RFID Tracking:Equipment location and maintenance history tagging.
BIM integration anchors capital planning workflows. IoT Sensors are gaining share fastest as predictive maintenance contracts replace time-based service agreements.
End User:
Decision authority fragments across clinical operations, finance, and compliance functions.
- Hospital Administrators:C-suite executives accountable for total cost of ownership and regulatory risk. Southeast US networks like HCA and Tenet centralize procurement authority under five-to-seven service line bundles with penalty-clause performance metrics.
- Clinic Managers:Operational leaders balancing patient throughput with facility uptime. Saudi Arabia's Vision 2030 privatization creates greenfield integrated facilities management contracts without legacy vendor displacement friction.
- Laboratory Supervisors:Technical managers prioritizing environmental stability for diagnostic accuracy.
- Rehabilitation Coordinators:Patient care directors coordinating adaptive space configurations.
- Nursing Home Directors:Residential care administrators managing dietary and life safety compliance.
- Outpatient Facility Leaders:Ambulatory site managers optimizing scheduling and turnover efficiency.
Hospital Administrators control the largest procurement budgets. Clinic Managers are expanding their vendor selection authority fastest as multi-site standardization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The healthcare facilities management industry traces its modern scaling to post-war hospital construction booms in the United States and Western Europe, where integrated service models first emerged to manage expanding medical campuses. Vendor ecosystems subsequently developed distinct regional specializations shaped by local regulatory architectures and infrastructure maturity.
United States
Joint Commission accreditation mandates and aging Northeastern hospital infrastructure drive outsourcing of mechanical and electrical systems maintenance. OSHA workplace safety standards and EPA refrigerant handling protocols shape technician certification requirements. Texas and Florida health systems deploy edge-computing HVAC architectures across multi-building campuses.
Germany
EU Green Deal building efficiency deadlines and REACH chemical substitution protocols compel integrated energy-service contracts with full material inventory documentation. The country's national healthcare regulator enforces strict medical gas system maintenance standards. Hospital procurement departments in Berlin and Munich require vendor substitution roadmaps as contract preconditions.
India
Private hospital chains in Mumbai, Delhi, and Bangalore standardize facilities management across multi-site networks under centralized vendor platforms. The Central Electricity Authority and Bureau of Indian Standards shape technical specifications for emergency power systems. Tier-one city clusters absorb the fastest contract growth as outpatient volume shifts accelerate.
Saudi Arabia
Vision 2030 healthcare privatization creates greenfield integrated facilities management contracts without legacy vendor displacement friction. The country's national healthcare regulator oversees new hospital commissioning standards. Riyadh and Jeddah medical cities anchor procurement volume for bundled hard and soft service agreements.
Japan
METI subsidies for geothermal and solar thermal adoption subsidize vendor-led capital deployment in hospital energy retrofits. The country's national pharmaceutical and medical device regulator enforces environmental stability standards for clinical spaces. Kanto and Kansai hospital clusters integrate building information modeling with real-time sensor networks.
Global Healthcare Facilities Management Market Competitive Landscape
The competitive structure tilts toward diversified service conglomerates with technical workforce scale. Vendor rosters compress as health systems consolidate previously fragmented mechanical, foodservice, and security contracts under single-accountability master agreements. Three archetypes dominate: integrated hard-soft service providers, real estate platform extenders, and specialized clinical support operators. Competitive moves concentrate on portfolio diversification through bundled performance contracts and technology integration partnerships.
Within the integrated service tier, ABM Industries exemplifies technical workforce scale anchoring multi-site hospital contracts. Sodexo occupies a position representing foodservice and clinical support integration archetypes. CBRE Group sits within the real estate platform extension category, translating property management capabilities into healthcare-specific compliance frameworks.
| Leading Market Players |
|---|
| ABM Industries |
| Aramark Corporation |
| ISS World Services |
| Sodexo |
| Ecolab |
| Compass Group |
| Cushman & Wakefield |
| CBRE Group |
| Jones Lang LaSalle |
| Others |
Supply & Pricing Matrix
Horizontal integration across mechanical, energy, and soft service capabilities anchors vendor pricing power in the Global Healthcare Facilities Management Market. ABM Industries and Sodexo leverage unified service portfolios to command performance-based premiums, while fragmented regional contractors compete on cost in non-critical maintenance tiers.
Pricing Analysis
Performance-based contracting with penalty-clause metrics dominates hospital procurement in the United States, separating integrated service providers from commodity maintenance vendors. Price differentiation rests on Joint Commission certification tiers and geographic density of technical workforces. Cost compression in energy management contracts is intensifying because natural gas price volatility erodes fixed-price margin predictability. Ambulatory surgical centers exhibit highest price sensitivity; large health system administrators least.
Supply Chain Analysis
Refurbishment flows for HVAC compressors and emergency generator components create secondary supply channels that reduce new equipment procurement cycles. Component manufacturing concentrates in Germany, the United States, and Japan for medical-grade filtration systems and building automation controls. Raw material dependencies span copper for electrical infrastructure, specialized refrigerants for EPA-compliant HVAC systems, and lithium-ion cells for backup power storage. Single-source vulnerability runs through proprietary automation protocols from Siemens and Johnson Controls. Distribution runs through direct vendor-health system master agreements rather than distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Healthcare Facilities Management Market functions as a regulatory compounder where EU Green Deal retrofit deadlines and FDA environmental health mandates continuously refresh contract demand.
For Market Incumbents: Anchor technical workforce scale in Texas and Florida health systems where edge-computing HVAC deployments concentrate. Consolidate fragmented security and foodservice contracts under unified performance metrics to defend against specialized clinical support operators. Invest in ASHE healthcare engineering certification pipelines to offset skilled technician scarcity in Germany and France. For New Entrants and Emerging Players: SaaS-enabled facility management platforms offer the lowest barrier entry point into ambulatory surgical center networks in India's tier-one cities. Target standardized multi-site contracts in Mumbai and Bangalore where private hospital chains seek centralized vendor platforms. Pursue greenfield integrated service agreements in Saudi Arabia's Vision 2030 privatization wave. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap technical service specialists because health system procurement departments are compressing vendor rosters under single-accountability master agreements. Over the medium-term horizon, acquire firms with EPA refrigerant handling and medical gas system certifications to capture consolidation premiums. Monitor building automation technology integration depth as the inflection signal for vendor capability relevance.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Bundling | Combines hard and soft services under single accountability, meeting HCA and Tenet procurement consolidation requirements. |
| Building Automation Partnership | Bridges proprietary Siemens and Johnson Controls protocols with unified dashboard platforms. |
| Energy Performance Contracting | Captures EU Green Deal retrofit mandates through capital-upgrade-plus-operations bundling. |
| Technical Certification Investment | Addresses 18-24 month onboarding timelines driven by Joint Commission and OSHA credentialing complexity. |
| Predictive Maintenance Platform | Converts time-based service agreements into sensor-driven contracts with edge-computing architectures. |
Research Methodology
Bottom-up hospital and ambulatory facility modeling reconciled against top-down vendor contract tracking forms the analytical core of this study. Primary interviews with facilities directors, GPO contracts managers, biomedical engineers, and health system procurement executives combined with secondary validation from hospital procurement databases, CMS Medicare cost reports, EU Green Deal implementation tracking, and ASHE engineering workforce surveys. Triangulation across these sources ensures segment-level accuracy.
Input-output matrices map service type, application, technology, and end-user dimensions across the projection horizon. CAGRs derive from modeled contract value expansion in maintenance management, energy management, and integrated service agreements. Forecast inputs include outpatient volume migration rates, EU building efficiency compliance deadlines, and edge-computing HVAC adoption curves in Texas and Florida health systems.
The model assumes a particular technology adoption path; alternative pathways for building automation convergence would alter the outlook. Forecasts reflect assumptions about skilled technician training pipeline expansion and interoperability standards development. Practitioners should monitor regulatory deadline acceleration and energy price volatility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Facilities
US and Europe Ambulatory Surgery Centers Market
Healthcare Facilities
US Ambulatory Surgery Centers Market
Healthcare Facilities
Mobile Hospitals Market
Healthcare Facilities
Assisted Living Facilities Market
Healthcare Facilities
Bedless Hospitals Market
Healthcare Facilities
Trauma Care Centers Market
Healthcare Facilities
Global Healthcare Architecture Market
Healthcare Facilities
Global Ambulatory Surgery Centers (Ascs) Market
Healthcare Facilities
Longevity Clinic Chain Infrastructure Market
Healthcare Facilities
Qatar Senior Living Market
Healthcare Facilities
Confinement Center Market
Healthcare Facilities
Hospital Lighting Market
Healthcare Facilities
US Office-Based Labs Market
Healthcare Facilities
Private Office-Based Clinics Market
Healthcare Facilities
US Hospital Facilities Market
Healthcare Facilities
US Skilled Nursing Facility Market