
 Asia-Pacific Smart Hospital Market | 2026-2036
Asia-Pacific Smart Hospital Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Smart Hospital Market Outlook
AI-enabled diagnostic accuracy tiers are redrawing procurement priorities across Asia-Pacific health systems. Philips leverages its integrated informatics stack to anchor enterprise contracts in Singapore and Australia. Shenzhen Mindray Bio-Medical Electronics specializes in cost-optimized monitoring platforms that dominate public hospital tenders in China and Southeast Asia.
A smart hospital deploys interconnected clinical systems, IoT sensors, and cloud-native analytics platforms to automate patient flow, optimize resource allocation, and enable real-time clinical decision support with sub-100-millisecond latency thresholds. Patient Monitoring Systems capture the largest installed base due to mandatory telemetry expansion in post-acute wards, while AI Solutions within the technology layer are expanding fastest as hospitals deploy predictive sepsis and readmission algorithms. Telemedicine Solutions retain concentrated margin pools in rural network extensions where specialist access gaps persist.
India's CDSCO medical device rules, China's NMPA AI-enabled device approval pathways, and Australia's TGA software-as-a-medical-device framework collectively shape product registration timelines and data governance requirements across the region. Japan's PMDA digital therapeutics reimbursement policies are creating new revenue models for connected care platforms. Stakeholders must monitor divergence in cross-border data localization mandates as cloud architecture decisions increasingly determine market access feasibility.
Market Dynamics
Telemetry infrastructure expansion across Asia-Pacific cardiology departments is redrawing capital allocation priorities as tertiary hospitals prioritize real-time patient monitoring over incremental EHR upgrades. China's tier-one digitization budgets and India's PLI scheme for medical electronics are concentrating supplier attention on these two markets.
Growth Catalysts
- India's PLI scheme for medical electronics:Domestic manufacturing incentives are accelerating local production capacity for patient monitoring devices and reducing import dependency for public hospital procurement.
- Telemetry mandates in post-acute wards:Regulatory requirements for continuous cardiac monitoring are expanding installed bases for wireless patient monitoring systems across tertiary facilities.
- Cloud-native analytics platforms:Sub-100-millisecond latency thresholds for clinical decision support are driving edge computing deployments in hospital IT infrastructure.
Market Restraints
- Cross-border data localization mandates:Divergent cloud architecture requirements between China's cybersecurity laws and Australia's data sovereignty frameworks are fragmenting vendor deployment strategies.
- Semiconductor supply concentration:Reliance on discrete component suppliers in Taiwan and South Korea creates input cost volatility for embedded monitoring device manufacturers.
- NMPA AI-enabled device approval complexity:Extended validation timelines for algorithm-based diagnostic tools are delaying product launches in China's largest hospital systems.
Strategic Opportunities
- Rural telemedicine network extensions:Specialist access gaps in Indonesia's outer islands and the Philippines' archipelago regions retain concentrated margin pools for connected care platforms.
- PMDA digital therapeutics reimbursement:Japan's connected care reimbursement policies are creating new revenue models for chronic disease management platforms.
- AI-IoT convergence in predictive sepsis:Integration of edge sensors with machine learning algorithms is opening clinical workflow automation contracts in Australian and Singaporean health systems.
Industry Challenges
- Interoperability with legacy hospital information systems:HL7 FHIR implementation gaps are forcing costly middleware development for established HIS vendors.
- Clinical AI validation workforce scarcity:Shortage of biomedical informaticists with regulatory submission experience is extending product certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Smart Hospital Market |
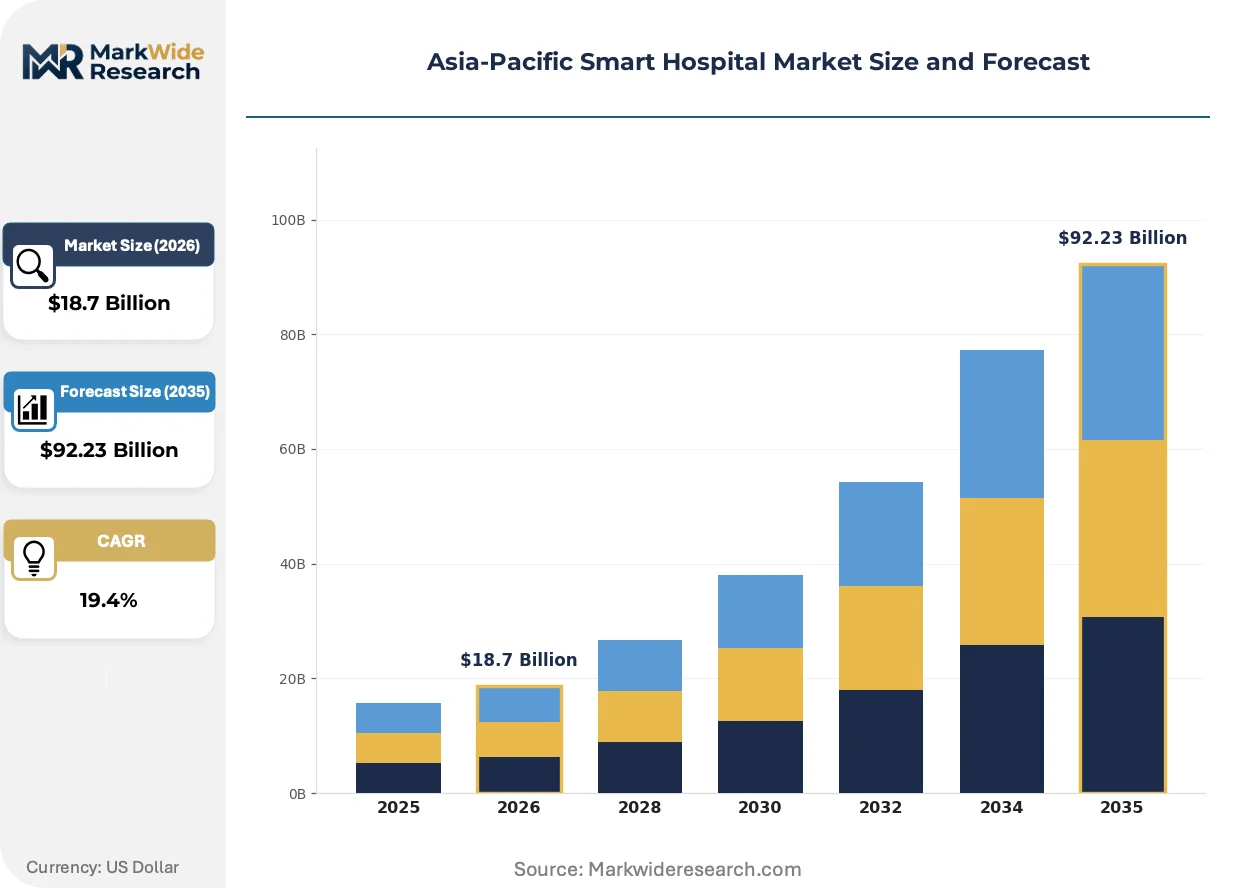
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
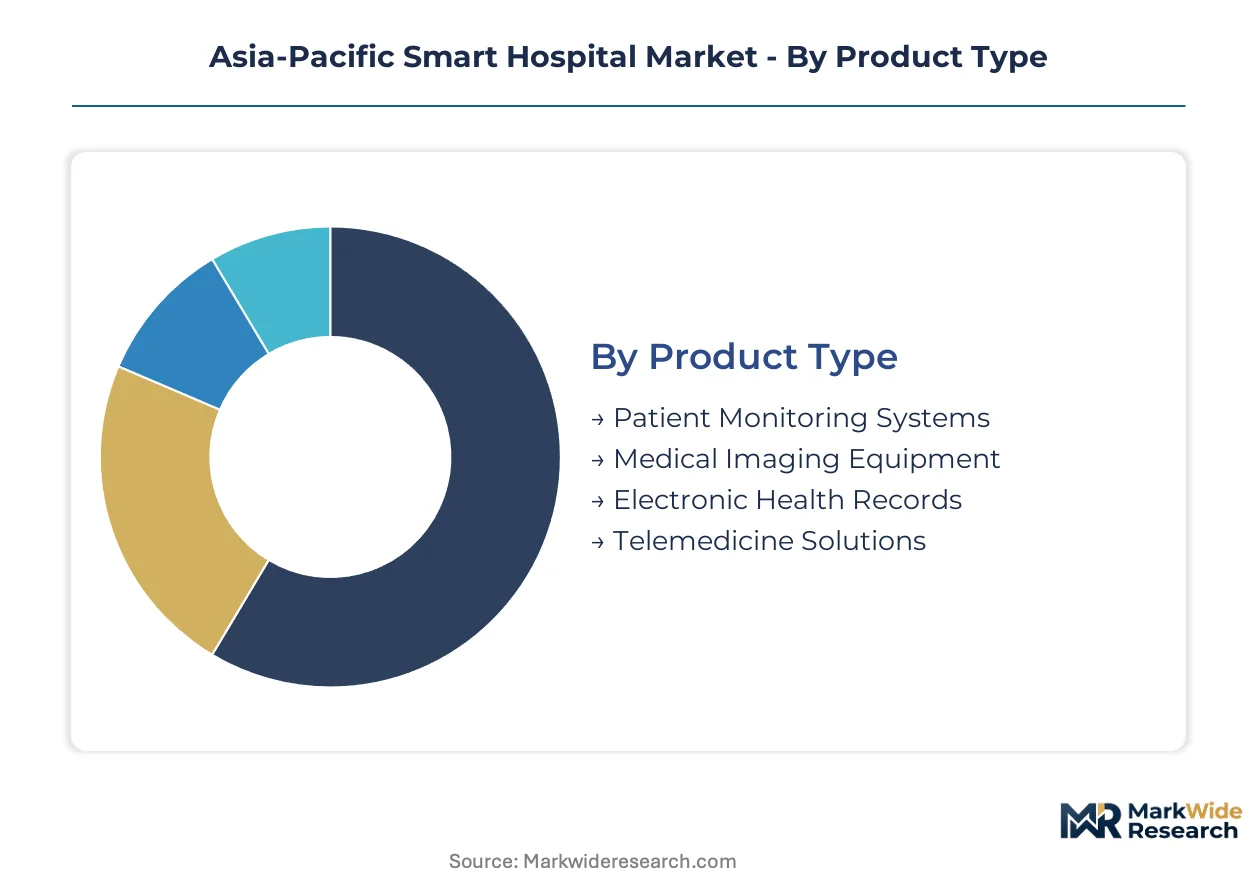
| Segmentation | Product Type: Patient Monitoring Systems, Medical Imaging Equipment, Electronic Health Records, Telemedicine Solutions Technology: AI Solutions, IoT Devices, Cloud Computing, Big Data Analytics End User: Hospitals, Clinics, Research Institutions, Long-Term Care Facilities Application: Remote Patient Monitoring, Healthcare Operations, Patient Engagement, Workflow Optimization |
| Companies Covered | Philips, GE Healthcare, Medtronic, Siemens Healthineers, Shenzhen Mindray Bio-Medical Electronics, Qualcomm Technologies, Intel Corporation, Microsoft, Honeywell International, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Smart Hospital Market Strategic Shifts
Clinical workflow automation is decomposing traditional departmental silos as real-time data streams enable centralized command centers. This shift demands reconfigured staff roles and integrated technology stacks rather than point solutions.
Edge computing architectures for patient monitoring are decomposing the centralized server model that dominated hospital IT for two decades. Cardiology and intensive care units in Singaporean and Australian tertiary hospitals are deploying ward-level processing nodes to achieve sub-100-millisecond alert generation. This topology is compressing infrastructure costs for rural network extensions where bandwidth constraints persist.
China's NMPA software-as-a-medical-device framework is tightening validation requirements for AI diagnostic algorithms. The regulation mandates clinical trial evidence from domestic patient populations, forcing multinational vendors to establish local R&D facilities. Cardiology imaging AI and sepsis prediction tools face the steepest compliance burdens under these pathways.
Public hospital procurement in Southeast Asia is fragmenting as provincial health authorities gain tendering autonomy from central ministries. Indonesian and Vietnamese district hospitals are forming purchasing consortia to negotiate volume discounts with monitoring device suppliers. This decentralization favors vendors with localized service networks over those relying on distributor relationships.
Asia-Pacific Smart Hospital Market Segmentation
Smart hospital procurement in Asia-Pacific fragments across technology maturity tiers and regulatory approval pathways. CDSCO, NMPA, and TGA frameworks create divergent product registration requirements that reshape vendor portfolio priorities across each segment category.
Product Type:
Regulatory differentiation separates Class II device approvals from software-only certifications across Asia-Pacific health systems. NMPA's medical device classification system imposes distinct clinical evidence requirements on hardware-intensive segments versus cloud-native platforms.
- Patient Monitoring Systems:Wireless telemetry hardware with embedded edge processing capabilities for sub-100-millisecond alert latency. Tertiary hospitals in China's tier-one cities and Singapore's public health clusters are expanding mandatory cardiac monitoring in post-acute wards under revised clinical guidelines.
- Medical Imaging Equipment:AI-integrated diagnostic modalities including CT, MRI, and digital radiography systems with native deep learning reconstruction. India's PLI scheme for medical electronics is accelerating domestic manufacturing capacity for mid-range imaging platforms serving district hospital networks.
- Electronic Health Records:Cloud-native clinical data repositories with HL7 FHIR interoperability interfaces. Deployment concentrates in Australian and Japanese health systems with mature digital infrastructure.
- Telemedicine Solutions:Specialist consultation platforms with low-bandwidth optimization for archipelago geographies. Indonesia's outer islands and the Philippines' rural provinces retain concentrated demand for asynchronous diagnostic workflows.
Patient Monitoring Systems handles the majority of throughput; Telemedicine Solutions is gaining share fastest across frontier hospital networks.
Technology:
Cost tier separation distinguishes capital-intensive edge infrastructure from subscription-based cloud services in procurement budgeting cycles.
- AI Solutions:Machine learning algorithms for predictive sepsis, readmission risk stratification, and imaging diagnostic assistance. NMPA's software-as-a-medical-device framework mandates domestic clinical trial evidence, forcing algorithm developers to establish China-based R&D facilities.
- IoT Devices:Networked sensors for environmental monitoring, asset tracking, and patient location services. Deployment accelerates in Singaporean and Australian tertiary facilities with integrated command center architectures.
- Cloud Computing:Hospital IT infrastructure virtualization with data sovereignty compliance for cross-border patient information. China's cybersecurity law and Australia's privacy frameworks fragment vendor deployment strategies.
- Big Data Analytics:Population health platforms aggregating multi-source clinical and operational datasets. Adoption concentrates in Japan's metropolitan hospital networks with advanced health informatics capabilities.
IoT Devices carries the largest installed base expansion; AI Solutions shows the steepest trajectory as predictive algorithms penetrate clinical workflows.
End User:
Customer type determines procurement channel structure, with public tendering dominating hospital segments and direct sales penetrating research institutions.
- Hospitals:Tertiary and secondary acute care facilities with enterprise-scale technology integration requirements. China's tier-one digitization budgets and India's public hospital modernization programs concentrate supplier attention.
- Clinics:Primary care and specialty outpatient facilities with point-solution deployment models. Southeast Asian provincial health authorities are fragmenting procurement autonomy to district-level purchasing consortia.
- Research Institutions:Academic medical centers and clinical trial organizations with experimental technology validation programs. Japan's university hospitals anchor early-stage AI diagnostic partnerships.
- Long-Term Care Facilities:Post-acute and chronic disease management centers with remote monitoring integration. PMDA digital therapeutics reimbursement policies are creating new revenue models for connected care platforms in Japan.
Hospitals absorb the dominant share of capital expenditure; Long-Term Care Facilities is expanding most quickly on aging demographic tailwinds.
Application:
Volume concentration aligns with regulatory mandates for continuous monitoring versus operational efficiency initiatives.
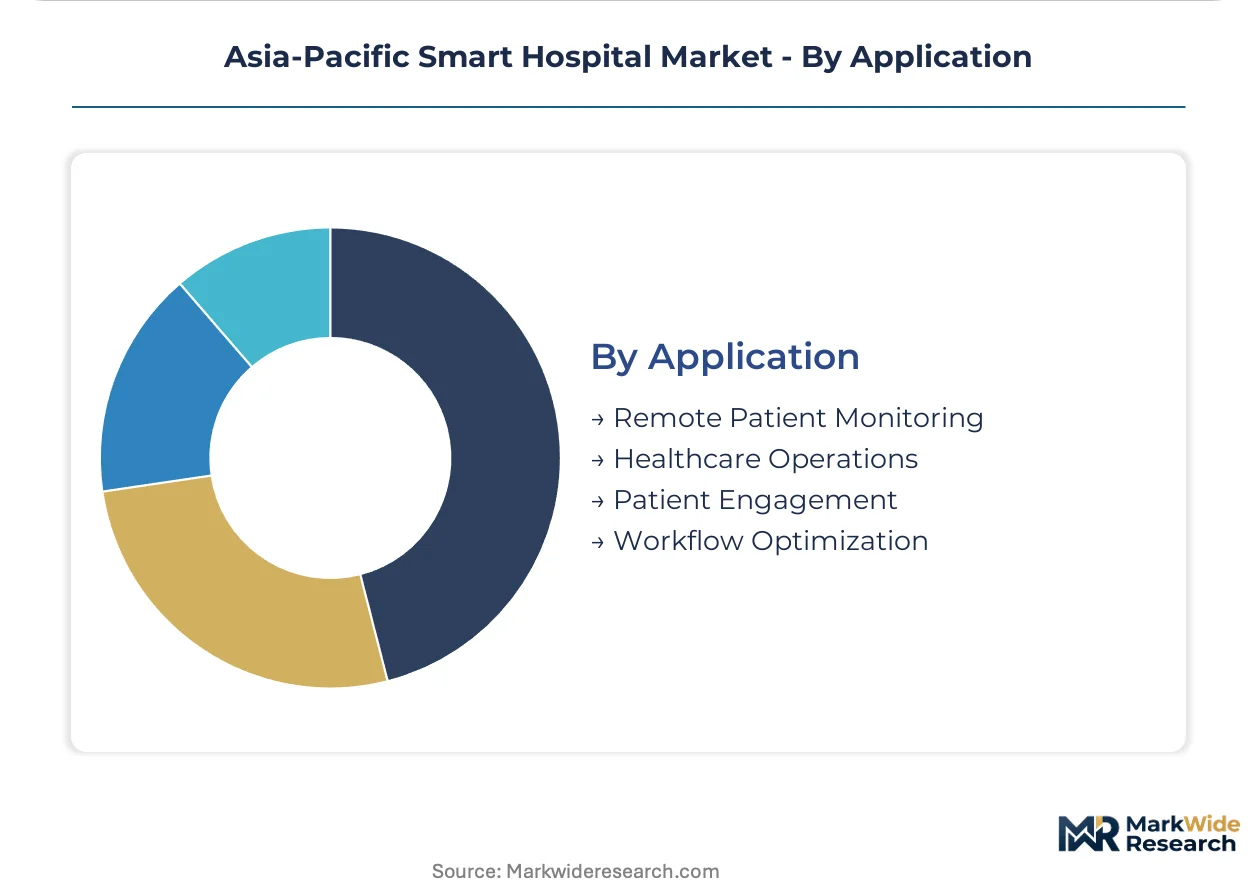
- Remote Patient Monitoring:Continuous physiological data transmission for chronic disease and post-discharge surveillance. Telemetry mandates in cardiology departments are redrawing capital allocation priorities across tertiary facilities.
- Healthcare Operations:Resource allocation, bed management, and supply chain optimization platforms. Australian and Singaporean health systems deploy centralized command centers for real-time operational oversight.
- Patient Engagement:Portal-based health record access and appointment scheduling interfaces. Adoption lags in markets with lower digital literacy penetration.
- Workflow Optimization:Clinical pathway automation and staff scheduling algorithms. Edge computing deployments in intensive care units enable sub-100-millisecond decision support latency.
Remote Patient Monitoring commands the largest technology investment; Workflow Optimization is climbing the fastest as labor efficiency pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Asia-Pacific health systems, with India's public hospital procurement showing acute cost sensitivity while Australia's tertiary networks prioritize integration depth over unit economics.
China
Tier-one cities Beijing, Shanghai, and Shenzhen concentrate digitization budgets exceeding provincial allocations by multiples. NMPA's software-as-a-medical-device framework mandates domestic clinical trials for AI diagnostic algorithms, forcing algorithm developers to establish China-based R&D facilities. The Yangtze River Delta hospital cluster anchors edge computing deployments for sub-100-millisecond clinical decision support latency.
India
Public hospital modernization programs under the National Health Mission are expanding telemetry infrastructure in tertiary cardiac centers. CDSCO medical device rules create distinct registration pathways for wireless patient monitoring systems versus cloud-native platforms. Karnataka's Bengaluru-Tumkur medical device corridor is consolidating contract manufacturing for cost-optimized monitoring hardware serving Southeast Asian export markets.
Japan
Metropolitan hospital networks in Tokyo and Osaka are deploying predictive sepsis algorithms with PMDA-validated clinical evidence requirements. PMDA digital therapeutics reimbursement policies are creating new revenue models for chronic disease management platforms in post-acute care settings. The Kansai region's university hospitals anchor early-stage AI diagnostic partnerships with multinational technology vendors.
Australia
State health clusters in New South Wales and Victoria are consolidating procurement for enterprise-scale EHR modernization with HL7 FHIR interoperability mandates. TGA software-as-a-medical-device frameworks shape validation timelines for algorithm-based diagnostic tools. Sydney and Melbourne tertiary facilities are deploying centralized command centers for real-time operational oversight across multi-site networks.
Singapore
The public health cluster's integrated procurement authority is standardizing IoT sensor deployments for environmental monitoring and asset tracking across all tertiary facilities. Singapore's personal data protection commission frameworks intersect with clinical data governance requirements for cross-border patient information flows. Biopolis and one-north research precincts are anchoring AI-IoT convergence pilots for predictive clinical workflow automation.
Asia-Pacific Smart Hospital Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across Asia-Pacific smart hospital procurement. Integrated health technology conglomerates anchor enterprise contracts in premium-tier markets with full-stack informatics capabilities. Specialized monitoring device manufacturers dominate public hospital tenders through cost-optimized hardware platforms. Semiconductor and cloud infrastructure providers are embedding themselves in hospital IT architectures through edge computing partnerships. Competitive dynamics center on regulatory localization speed and service network density rather than pure product differentiation.
Among diversified health technology conglomerates, Philips and GE Healthcare exemplify the integrated informatics archetype anchoring multi-year enterprise contracts. Siemens Healthineers occupies a comparable position in AI-integrated diagnostic imaging modalities. Shenzhen Mindray Bio-Medical Electronics represents the cost-optimized monitoring specialist archetype that dominates public hospital procurement across China and Southeast Asia through localized manufacturing and service networks.
| Leading Market Players |
|---|
| Philips |
| GE Healthcare |
| Medtronic |
| Siemens Healthineers |
| Shenzhen Mindray Bio-Medical Electronics |
| Qualcomm Technologies |
| Intel Corporation |
| Microsoft |
| Honeywell International |
| Others |
Value Chain & Pricing Dynamics
Edge computing silicon displacing centralized server architectures simultaneously shifts procurement geography toward Taiwan and South Korea while compressing hardware margins for legacy monitoring device manufacturers across Asia-Pacific health systems.
Pricing Analysis
After-sales service contracts and extended warranty tiers drive lifetime value capture across patient monitoring system deployments. Three-tier pricing structure across premium, standard, and economy levels separates Philips and GE Healthcare's integrated informatics bundles from Shenzhen Mindray's cost-optimized hardware platforms. Pricing pressure stems from India's PLI scheme accelerating domestic manufacturing capacity for public hospital tenders. Public procurement committees in Southeast Asia exhibit acute price sensitivity, while Australian state health clusters prioritize integration depth over unit economics.
Supply Chain Analysis
Taiwan and South Korea anchor semiconductor wafer fabrication and memory component production for embedded monitoring devices. Discrete sensor arrays, edge processing chipsets, and wireless telemetry modules draw from concentrated East Asian manufacturing hubs. Single-source vulnerability in advanced node semiconductors creates input cost volatility for device manufacturers. Distribution runs through regional medical device distributors with localized service networks, though direct procurement is expanding in China's tier-one hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native analytics platforms represent a substitution threat to hardware-centric monitoring vendors, forcing incumbents to defend against software-only disintermediation in Asia-Pacific procurement cycles.
For Market Incumbents: Fortify service network density across Indonesia's provincial health authorities and Vietnam's district hospital consortia to defend against decentralized tendering fragmentation. Deepen backward integration into edge computing silicon partnerships with Taiwan semiconductor foundries to secure supply continuity. Counter cloud-native entrants by bundling predictive algorithm subscriptions with legacy telemetry hardware upgrades.
For New Entrants and Emerging Players: Anchor in rural telemedicine network extensions across the Philippines' archipelago regions and Indonesia's outer islands where specialist access gaps retain concentrated margin pools. Target asynchronous diagnostic workflow platforms optimized for low-bandwidth connectivity. Pursue hospital system partnerships through pilot programs with Australian state health clusters seeking operational efficiency solutions.
For Investors and Strategic Acquirers: The market sits at a technology convergence phase that favors AI-IoT integration specialists with regulatory localization capabilities. Long-term viability centers on vendors with established China-based R&D facilities navigating NMPA software-as-a-medical-device frameworks. Monitor PMDA digital therapeutics reimbursement policy expansion as an inflection signal for chronic disease management platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Regulatory Localization | Domestic clinical trial evidence mandates force algorithm developers to establish China-based R&D facilities. |
| Edge Computing Partnership | Sub-100-millisecond latency requirements drive ward-level processing node deployments in Singaporean tertiary facilities. |
| Rural Network Extension | Low-bandwidth telemedicine platforms capture concentrated margins in Indonesia's outer islands and Philippine provinces. |
| PLI Scheme Alignment | India's domestic manufacturing incentives reduce import dependency for public hospital monitoring device procurement. |
| Command Center Integration | Centralized operational oversight platforms consolidate multi-site procurement across Australian state health clusters. |
Study Parameters
Cross-validation between hospital procurement database analysis and regulatory filing review anchors the qualitative findings in this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and CDSCO regulatory affairs specialists combined with secondary validation against NMPA approval databases, TGA software-as-a-medical-device frameworks, and hospital capital expenditure records. Bottom-up telemetry device shipment aggregation and top-down health system digitization budget analysis complete the triangulation.
Sensitivity analysis across technology adoption curves, regulatory approval timelines, and semiconductor supply scenarios shapes the projection framework. Segmentation dimensions span product type, technology layer, end-user category, and application area across the modeling period. CAGRs derive from installed base expansion rates and replacement cycle analysis. Edge computing deployment velocity and AI algorithm validation throughput serve as industry-specific forecast inputs.
Material uncertainties — NMPA approval pathway revisions, cross-border data localization mandate divergence, and semiconductor supply concentration disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about continued telemetry infrastructure expansion and sustained public hospital modernization funding. Recalibration cycles align with material shifts in reimbursement policy and regulatory framework evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Facilities
US Ambulatory Surgery Centers Market
Healthcare Facilities
Global Healthcare Facilities Management Market
Healthcare Facilities
US and Europe Ambulatory Surgery Centers Market
Healthcare Facilities
US Assisted Living Facility Market
Healthcare Facilities
Trauma Care Centers Market
Healthcare Facilities
Assisted Living Facilities Market
Healthcare Facilities
Micro-Hospitals Market
Healthcare Facilities
US Ambulatory Surgical Centers Market
Healthcare Facilities
Mobile Hospitals Market
Healthcare Facilities
Ambulatory Surgical Centers Market
Healthcare Facilities
US Hospital Facilities Market
Healthcare Facilities
Bedless Hospitals Market
Healthcare Facilities
Qatar Senior Living Market
Healthcare Facilities
Sauna and Spa Market
Healthcare Facilities
US Office-Based Labs Market
Healthcare Facilities
Global Healthcare Architecture Market