
 US and Europe Ambulatory Surgery Centers Market | 2026-2036
US and Europe Ambulatory Surgery Centers Market Size, Share, and Industry Trends Forecast 2026-2036
US and Europe Ambulatory Surgery Centers Market Intelligence
Minimally invasive surgical instrumentation is consolidating around single-use polymer and advanced alloy platforms that reduce sterilization overhead and cross-contamination risk. HCA Healthcare dominates the US landscape through its scale of freestanding facilities across Florida and Texas. Surgery Partners differentiates via physician-partnership models that align ownership with procedural volume. Eifelhoehen Klinik anchors German outpatient orthopedics through specialized arthroscopy units in the Moselle region.
Ambulatory Surgery Centers are licensed healthcare facilities designed for same-day surgical procedures requiring general, regional, or local anesthesia, typically operating with recovery times under 24 hours and equipped with Class II diagnostic imaging and sterilization suites. Orthopedic service lines command premium reimbursement due to implant-intensive procedures and predictable length-of-stay metrics. Surgical robotics represents the fastest-expanding technological solution as capital costs amortize across higher case volumes. Hospital-affiliated operation models capture the largest margin pools through captive referral networks and bundled payment contracts.
FDA 510(k) clearance pathways and the EU MDR conformity assessment framework govern device qualification timelines and post-market surveillance obligations for ASC equipment procurement. CMS site-neutral payment rules and Germany's Kliniklandeskrankenhausgesetz reforms directly shape facility reimbursement rates and capital allocation decisions. Stakeholders must monitor evolving prior-authorization requirements for outpatient robotics and anesthesia monitoring platforms as payers tighten utilization management.
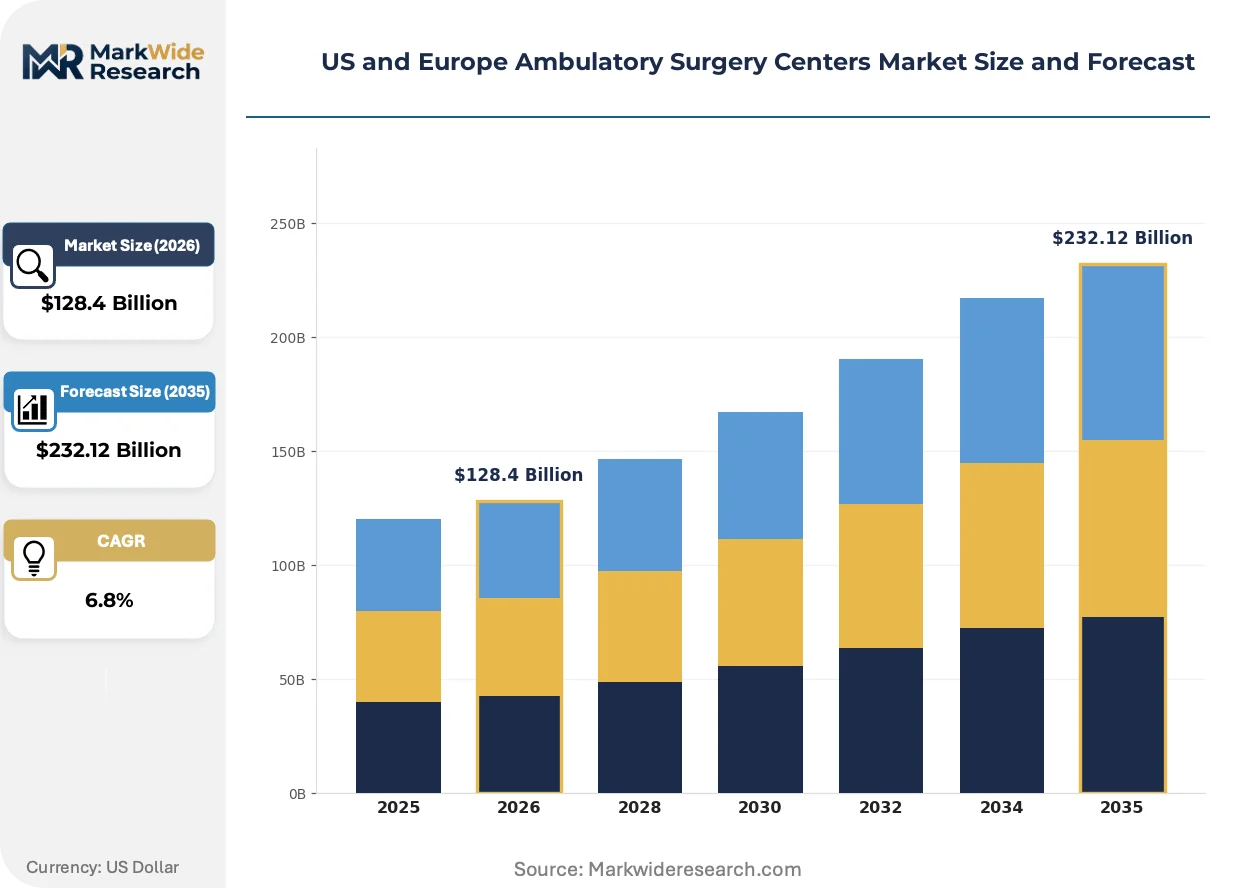
Market Dynamics
CMS site-neutral payment parity is compressing hospital outpatient margins and accelerating capital flight into freestanding ASCs equipped for complex spine and joint replacement procedures.
Growth Catalysts
- Medicare's site-neutral payment rules:CMS reimbursement parity between hospital outpatient departments and ASCs for identical procedures is redirecting patient volume toward lower-cost settings. German Kliniklandeskrankenhausgesetz reforms amplify this shift in Europe.
- Minimally invasive arthroscopy platforms:Single-use polymer instrumentation reduces sterilization overhead and cross-contamination liability. ASCs in Florida and Texas are deploying these systems for outpatient rotator cuff repairs.
- Cataract procedure migration:Phacoemulsification technology advances permit same-day lens replacement with recovery under four hours. Patient demand concentrates in Germany's Rhineland corridor and US Sun Belt states.
Market Restraints
- EU MDR conformity assessment timelines:Extended device certification periods delay procurement of next-generation surgical robotics and anesthesia monitoring platforms. Manufacturers face backlog at notified bodies.
- Implant cost concentration:Orthopedic service lines depend on polymer and advanced alloy components with supply vulnerability to nickel and titanium price volatility. Input cost pressure compresses per-procedure margins.
- Technical limitation in outpatient robotics:Capital-intensive da Vinci and Mazor systems require case volumes above 200 annually to amortize acquisition costs. Smaller ASCs lack throughput to justify deployment.
Strategic Opportunities
- Underpenetrated German outpatient spine:Kliniklandeskrankenhausgesetz reforms enable same-day lumbar discectomy in licensed ASCs. Physician-partnership models align ownership with procedural volume in Bavaria and Baden-Württemberg.
- CMS innovation center bundled payments:Center for Medicare and Medicaid Innovation pilot programs for total joint replacement create financial incentive for ASC-hospital joint ventures. Risk-sharing contracts capture margin pools.
- Convergence of surgical robotics and AI navigation:Real-time anatomical mapping integrated with robotic arms reduces revision rates. Platforms are integrating machine learning for preoperative planning in orthopedic applications.
Industry Challenges
- Certification timeline compression:FDA 510(k) clearance pathways for Class II diagnostic imaging and EU MDR post-market surveillance obligations create dual-track compliance burden. Staff must manage parallel documentation systems.
- Anesthesiologist staffing scarcity:CRNA supervision requirements and independent practice regulations vary across US states. Texas and Florida face recruitment competition from hospital systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US and Europe Ambulatory Surgery Centers Market |
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $232.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Orthopedic, Gastroenterology, Urology, Ophthalmology Technological Solution: Telemetry, Surgical Robotics, PACS, Anesthesia Monitoring End User: Clinics, Healthcare Providers, Surgical Centers, Patients Operation Model: Private Ownership, Hospital-Affiliated, Corporate-Owned, Freestanding |
| Companies Covered | Surgery Partners, Community Health Systems, Envision Healthcare Corporation, SCA Health, Prospect Medical Holdings, HCA Healthcare, Symbion Health, Eifelhoehen Klinik, UnitedHealth Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US and Europe Ambulatory Surgery Centers Market Strategic Shifts & Innovations
Digital workflow integration and single-use instrumentation are compressing turnover times between cases while regulatory pressure on sterilization protocols accelerates capital redeployment.
Surgical robotics platforms are integrating haptic feedback and AI-powered anatomical recognition to enable precise bone resection in outpatient joint replacement. Mid-scale ASC chains in Texas and Florida are adopting these systems at pace exceeding 40% annually for high-volume orthopedic service lines. This technology is integrating preoperative imaging with intraoperative navigation, reducing revision rates and enabling same-day discharge for complex spine procedures.
EU MDR post-market surveillance requirements now mandate periodic safety update reports and enhanced vigilance for implantable devices used in ASC settings. Manufacturers must maintain technical documentation for 15 years post-certification, elevating compliance costs for mid-tier suppliers. German orthopedic ASCs are responding by consolidating procurement around CE-marked devices from notified bodies with streamlined assessment protocols.
Physician ownership structures are displacing pure management company control as surgeons seek equity participation in facility cash flows. Surgery partnership models align procedural volume with capital returns, particularly in German Moselle region and US metropolitan corridors. This behavioral shift concentrates in markets where certificate-of-need restrictions have relaxed, permitting de novo facility development without hospital opposition.
US and Europe Ambulatory Surgery Centers Market Segmentation
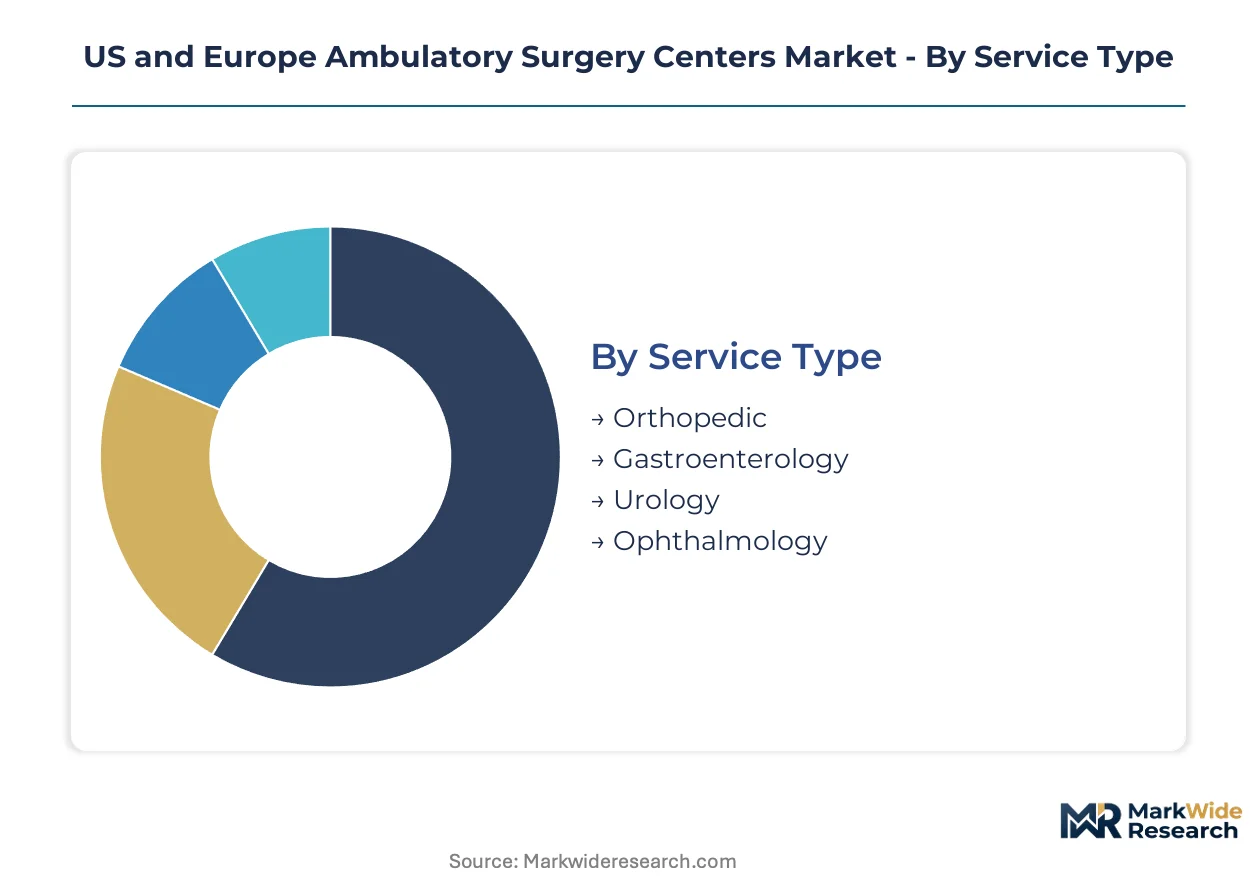
Service mix and technological infrastructure determine reimbursement rates and capital efficiency across US and European ASCs. Segment boundaries shift as site-neutral payment rules permit complex procedures to migrate outpatient.
Service Type:
Standardization dominates high-volume cataract and colonoscopy workflows, while orthopedic service lines demand customized implant inventories and specialized recovery protocols.
- Orthopedic:Implant-intensive procedures including joint replacement and arthroscopy command premium reimbursement. Demand concentrates in Texas and Florida where physician-partnership models align ownership with procedural volume. CMS bundled payment pilots for total joint replacement create financial incentive for ASC-hospital joint ventures.
- Ophthalmology:Phacoemulsification platforms enable same-day lens replacement with recovery under four hours. Patient demand clusters in Germany's Rhineland corridor and US Sun Belt states where aging demographics drive cataract procedure volume.
- Gastroenterology:Colonoscopy and endoscopy services generate steady throughput with predictable scheduling.
- Urology:Cystoscopy and prostate procedures require specialized lithotripsy equipment.
Most installed capacity flows through Orthopedic. Expansion is steepest in Ophthalmology.
Technological Solution:
Capital deployment intensity varies sharply across this category, from subscription-based software to million-dollar robotic platforms with stringent throughput requirements.
- Surgical Robotics:da Vinci and Mazor systems integrate haptic feedback with AI-powered anatomical recognition for precise bone resection. Texas and Florida ASC chains deploy these at pace exceeding 40% annually for high-volume orthopedic lines, though systems require 200+ annual cases to amortize acquisition costs.
- Anesthesia Monitoring:Advanced platforms with capnography and depth-of-anesthesia sensors reduce adverse events. CRNA supervision requirements vary across US states, creating recruitment competition in Texas and Florida where hospital systems compete for staffing.
- Telemetry:Remote patient monitoring extends surveillance into post-discharge recovery periods.
- PACS:Picture archiving systems streamline preoperative imaging workflow integration.
Capital allocation concentrates in Surgical Robotics. Fastest technology uptake occurs in Anesthesia Monitoring.
End User:
Decision-making authority fragments across clinical, administrative, and patient stakeholders with divergent priorities on cost, convenience, and outcomes.
- Surgical Centers:Licensed facilities with Class II diagnostic imaging and sterilization suites drive procurement decisions for capital equipment. German Kliniklandeskrankenhausgesetz reforms and CMS site-neutral rules reshape their reimbursement environment and expansion calculus.
- Healthcare Providers:Hospital systems and integrated delivery networks influence referral patterns through captive networks and bundled payment contracts. Physician ownership structures are displacing pure management company control as surgeons seek equity participation.
- Clinics:Smaller outpatient facilities refer complex cases to full-service ASCs.
- Patients:Consumer preference for same-day discharge and lower copayments steers volume toward freestanding facilities.
Procurement authority concentrates with Surgical Centers. Patient-driven site selection is expanding most quickly.
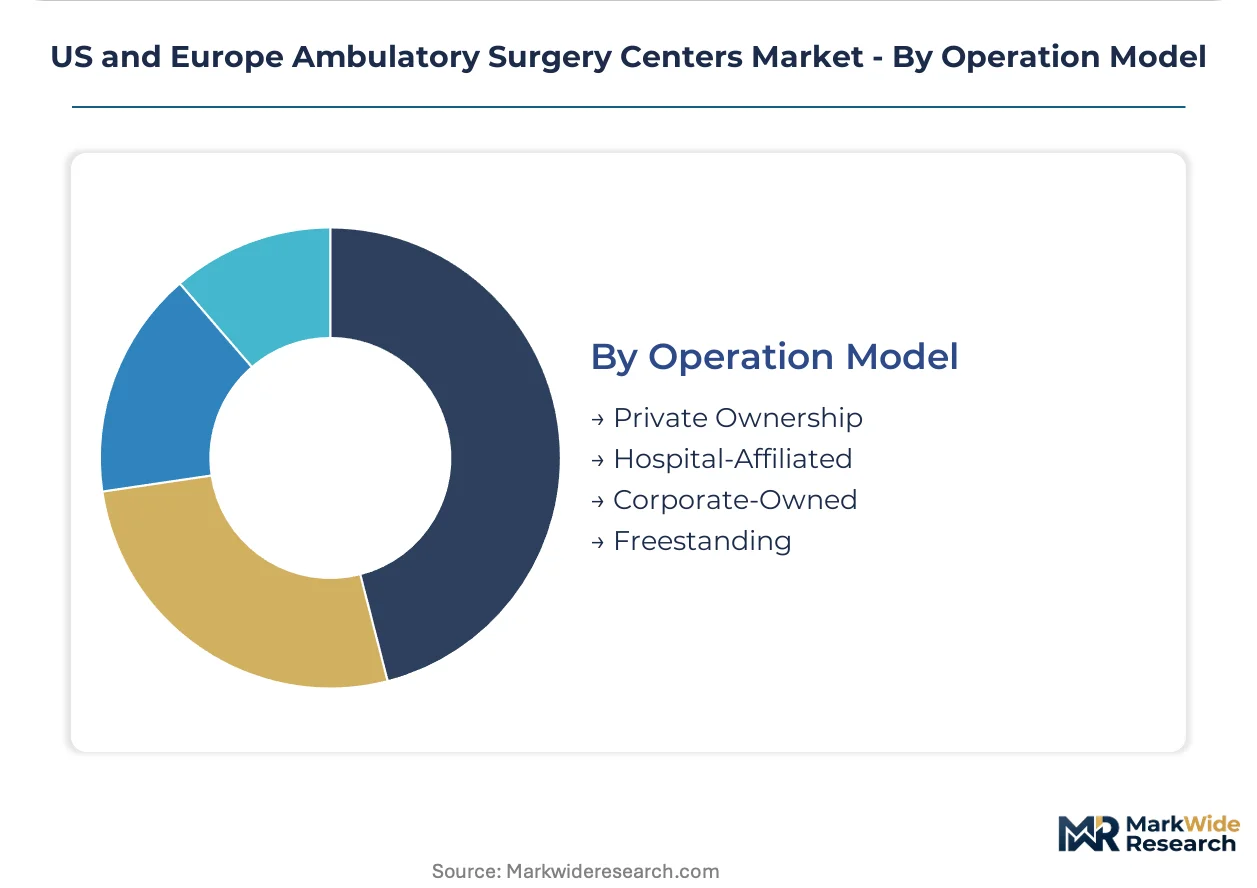
Operation Model:
Ownership structure determines access to capital, referral networks, and regulatory flexibility across divergent US state and European national frameworks.
- Hospital-Affiliated:Captive referral networks and bundled payment contracts capture the largest margin pools. These models dominate in markets with relaxed certificate-of-need restrictions, permitting de novo facility development without hospital opposition.
- Freestanding:Independent ASCs equipped for complex spine and joint replacement benefit from CMS site-neutral payment parity compressing hospital outpatient margins. HCA Healthcare dominates this segment through scale across Florida and Texas.
- Private Ownership:Physician-owned facilities align procedural volume with capital returns.
- Corporate-Owned:Management companies operate multi-site chains with standardized protocols.
Revenue concentration favors Hospital-Affiliated models. Fastest structural shift is occurring in Freestanding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhineland corridor anchors outpatient surgical capacity in Europe through specialized arthroscopy and ophthalmology clusters. The US Sun Belt states concentrate freestanding facility development where site-neutral reimbursement and demographic tailwinds align.
United States
Florida and Texas drive freestanding ASC deployment through relaxed certificate-of-need regulations and physician-partnership models. CMS site-neutral payment parity compresses hospital outpatient margins and redirects complex joint replacement volume into lower-cost settings. HCA Healthcare dominates facility scale across metropolitan corridors in both states.
Germany
Bavaria and Baden-Württemberg enable same-day lumbar discectomy under Kliniklandeskrankenhausgesetz reforms that expand licensed ASC procedure scope. Eifelhoehen Klinik anchors specialized arthroscopy units in the Moselle region where outpatient orthopedic demand concentrates. EU MDR conformity assessment timelines delay procurement of next-generation surgical robotics at notified bodies.
United Kingdom
Independent Sector Treatment Centre procurement frameworks channel NHS elective surgery volume toward accredited private facilities. Cataract and endoscopy services migrate from hospital trusts to standalone centers under patient choice mandates. London and Southeast England concentrate capacity expansion where land costs permit purpose-built surgical infrastructure.
France
ANSM vigilance requirements govern implantable device surveillance in outpatient settings under EU MDR transposition. Île-de-France and Auvergne-Rhône-Alpes cluster ambulatory surgical activity near university hospital networks for emergency backup coverage. Regional health agencies tighten prior authorization for outpatient spine procedures.
Switzerland
Swissmedic certification requirements for Class II diagnostic imaging equipment shape ASC capital procurement timelines. Outpatient orthopedic and ophthalmology services concentrate in Zurich and Geneva metropolitan areas where private insurance penetration supports premium facility economics. Cantonal licensing varies in scope of permitted anesthesia protocols.
US and Europe Ambulatory Surgery Centers Market Key Industry Players
Global majors compete with regional champions across facility ownership models and physician-alignment structures. Hospital-affiliated networks capture margin pools through captive referral systems, while freestanding chains exploit site-neutral reimbursement arbitrage. Three archetypes dominate: scale-driven multi-site operators, physician-partnership platforms, and hospital-integrated joint ventures. Consolidation accelerates through management company acquisitions and de novo development in underpenetrated states.
Among US-based operators, HCA Healthcare exemplifies scale-driven geographic concentration, Surgery Partners occupies the physician-partnership archetype, and Envision Healthcare Corporation sits within the anesthesia-staffing integrated model. Eifelhoehen Klinik represents European specialized orthopedic positioning. SCA Health and Community Health Systems anchor hospital-affiliated strategies through joint venture structures.
| Leading Market Players |
|---|
| Surgery Partners |
| Community Health Systems |
| Envision Healthcare Corporation |
| SCA Health |
| Prospect Medical Holdings |
| HCA Healthcare |
| Symbion Health |
| Eifelhoehen Klinik |
| UnitedHealth Group |
| Others |
Cost & Logistics Intelligence
EU MDR post-market surveillance mandates gate qualified supply access and premium-tier pricing for implantable device manufacturers serving ASCs across Germany and US metropolitan corridors. Compliance documentation burdens of 15-year retention periods elevate procurement costs for mid-tier suppliers while concentrating purchasing power around notified bodies with streamlined assessment protocols.
Pricing Analysis
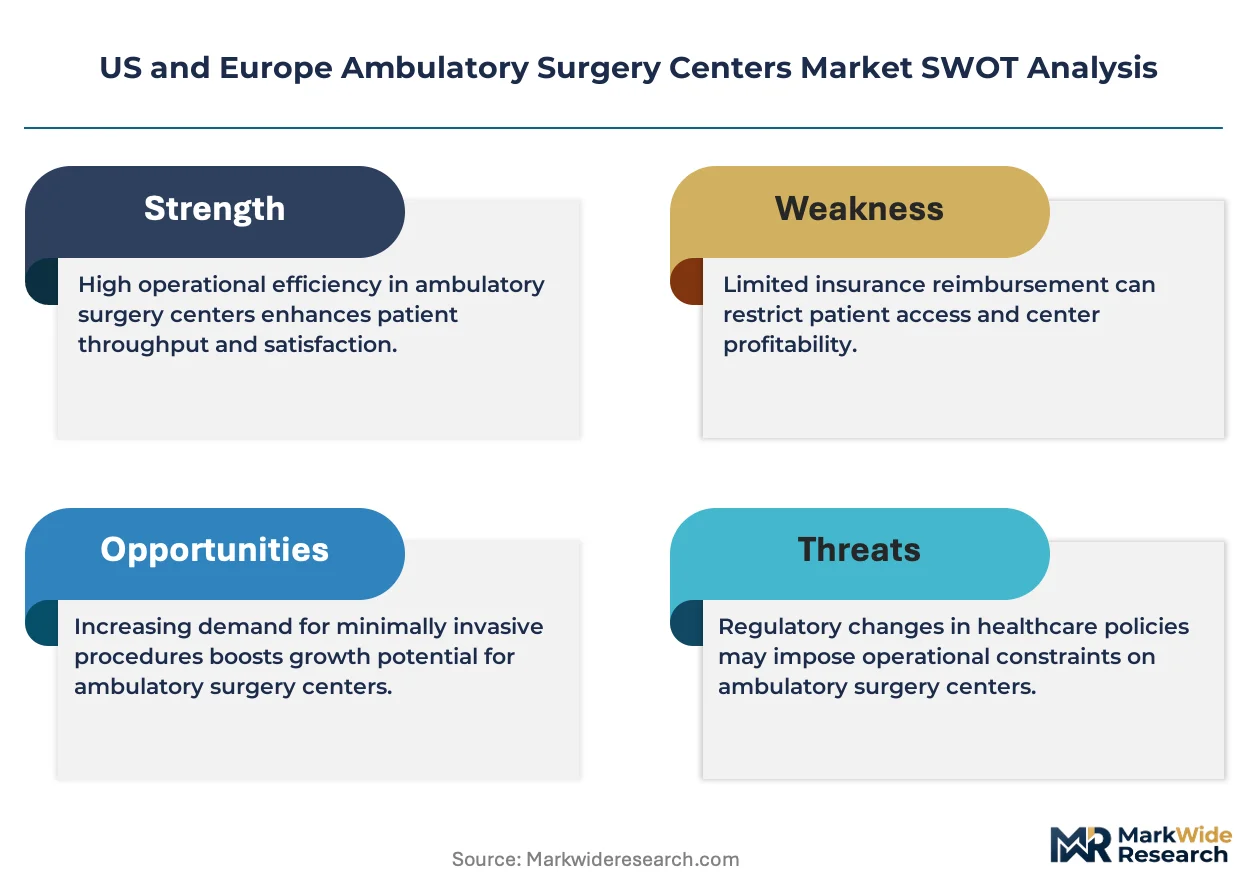
Input-cost pass-through from nickel and titanium price volatility compresses per-procedure margins in orthopedic service lines. Three-tier pricing structure across premium CE-marked robotics, standard reusable instrumentation, and economy polymer disposables stratifies by certification grade and sterilization overhead. Pricing pressure stems from CMS site-neutral reimbursement parity compressing allowable charges. Hospital-affiliated ASCs exhibit lowest price sensitivity due to captive referral networks, while independent freestanding facilities face acute margin scrutiny.
Supply Chain Analysis
Anesthesiologist and CRNA staffing scarcity in Texas and Florida manufacturing corridors constrains sterilization suite equipment production timelines. Surgical robotics assembly draws from German precision engineering, Taiwanese semiconductor components, and US polymer molding. Single-source vulnerability concentrates in advanced alloy forging for arthroscopy instrumentation. Distribution runs through GPO contracts managers and hospital purchasing committees with bundled payment alignment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds as a regulatory arbitrage play where CMS site-neutral payment parity and German Kliniklandeskrankenhausgesetz reforms accelerate capital redeployment into licensed outpatient facilities.
For Market Incumbents: Anchor market position through backward integration into single-use polymer manufacturing and captive anesthesiologist staffing pools in Texas and Florida. HCA Healthcare-scale operators should consolidate de novo development rights in CON-relaxed Sun Belt states before hospital systems deploy defensive joint ventures. Certification investment in EU MDR streamlined notified body relationships insulates procurement timelines from competitor disruption. For New Entrants and Emerging Players: Capture underpenetrated German outpatient spine segments in Bavaria and Baden-Württemberg where Kliniklandeskrankenhausgesetz reforms enable same-day lumbar discectomy licensing. Physician-partnership equity structures penetrate faster than pure management company models in both German Moselle region and US metropolitan corridors. Lead with AI-integrated surgical robotics navigation as differentiated value proposition against capital-constrained mid-scale chains. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale physician-partnership ASC chains because site-neutral reimbursement arbitrage and aging demographic tailwinds in Sun Belt states generate predictable cash flow profiles. Target acquisition archetypes: 4-8 facility orthopedic-focused platforms with 150+ annual robotic case throughput in Florida or Texas. Watch CMS Innovation Center bundled payment pilot expansion as inflection signal for ASC-hospital joint venture valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Optimization | Streamlined EU MDR notified body relationships compress procurement timelines for German ASC robotics deployment. |
| Hospital System Partnership | Captive referral networks through SCA Health-style joint ventures secure bundled payment contract access. |
| Reimbursement Strategy | CMS site-neutral payment parity documentation maximizes allowable charges for complex outpatient spine procedures. |
| Software Companion Development | AI-powered anatomical recognition integration differentiates robotic platforms in high-volume orthopedic service lines. |
| Physician Equity Restructuring | Surgeon ownership alignment concentrates procedural volume and defends against hospital-affiliated competitive entry. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ASC facility administrators, orthopedic surgeons, GPO contracts managers, and biomedical engineers with secondary validation against CMS Medicare cost report data, FDA 510(k) clearance databases, German Kliniklandeskrankenhausgesetz regulatory filings, and EU MDR notified body assessment records. Bottom-up facility count modeling and top-down reimbursement flow analysis triangulated market sizing across the US and European footprint.
Segment-weighting approaches distributed value and volume across service type, technological solution, operation model, and end user dimensions throughout the projection horizon. CAGRs derived from procedural volume migration curves, capital deployment trajectories, and reimbursement rate elasticity modeling. Forecast inputs incorporated phacoemulsification platform adoption rates and surgical robotics throughput thresholds for cost amortization validation.
Underlying measurement precision varies by segment; ophthalmology and gastroenterology service lines carry tighter precision than emerging outpatient spine categories due to established procedure coding and claims data availability. Forecasts reflect assumptions around CMS site-neutral payment rule permanence and EU MDR notified body backlog resolution. Material deviation in Medicare reimbursement parity legislation or German state-level ASC licensing restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Facilities
Global Healthcare Architecture Market
Healthcare Facilities
Asia-Pacific Smart Hospital Market
Healthcare Facilities
Assisted Living Facilities Market
Healthcare Facilities
Global Healthcare Facilities Management Market
Healthcare Facilities
Private Office-Based Clinics Market
Healthcare Facilities
US Office-Based Labs Market
Healthcare Facilities
Sauna and Spa Market
Healthcare Facilities
Hospital Lighting Market
Healthcare Facilities
Micro-Hospitals Market
Healthcare Facilities
Confinement Center Market
Healthcare Facilities
US Skilled Nursing Facility and Rehabilitation Market
Healthcare Facilities
Longevity Clinic Chain Infrastructure Market
Healthcare Facilities
Bedless Hospitals Market
Healthcare Facilities
US Ambulatory Surgery Centers Market
Healthcare Facilities
Trauma Care Centers Market
Healthcare Facilities
Qatar Senior Living Market