
 Indonesia Connected Healthcare Market | 2026-2036
Indonesia Connected Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Connected Healthcare Market Insights
Indonesia's SATUSEHAT interoperability mandate is repositioning procurement priorities for hospital networks nationwide. GE HealthCare leverages its imaging-IT integration expertise to anchor large tertiary hospital contracts. Halodoc competes through a pharmacy-teleconsultation super-app model that dominates urban consumer mindshare. Philips Indonesia sustains its installed base of patient monitoring systems across Indonesia's growing private hospital chains.
Connected healthcare encompasses digital infrastructures that link patients, providers, and devices through real-time data exchange, typically employing HL7 FHIR protocols, cloud-native architectures, and IoT sensor networks to enable continuous care coordination outside traditional facility boundaries. Telehealth solutions lead current revenue generation as post-pandemic consultation habits persist, while remote monitoring tools represent the fastest-growing segment as diabetes and cardiovascular disease prevalence rises among Indonesia's aging population. Wearable devices remain a nascent margin pool constrained by price sensitivity, though mHealth apps occupy an expanding channel for preventive health engagement among smartphone-first users.
Indonesia's Ministry of Health, the national data protection authority, and BIS-equivalent medical device standards bodies collectively shape platform certification requirements, data residency rules, and cross-border health data flow restrictions. Compliance with SATUSEHAT APIs and local cloud hosting mandates determines market access for foreign solution providers. Stakeholders must monitor evolving medical device software classifications and provincial health authority procurement decentralization to anticipate reimbursement and deployment velocity shifts.
Market Dynamics
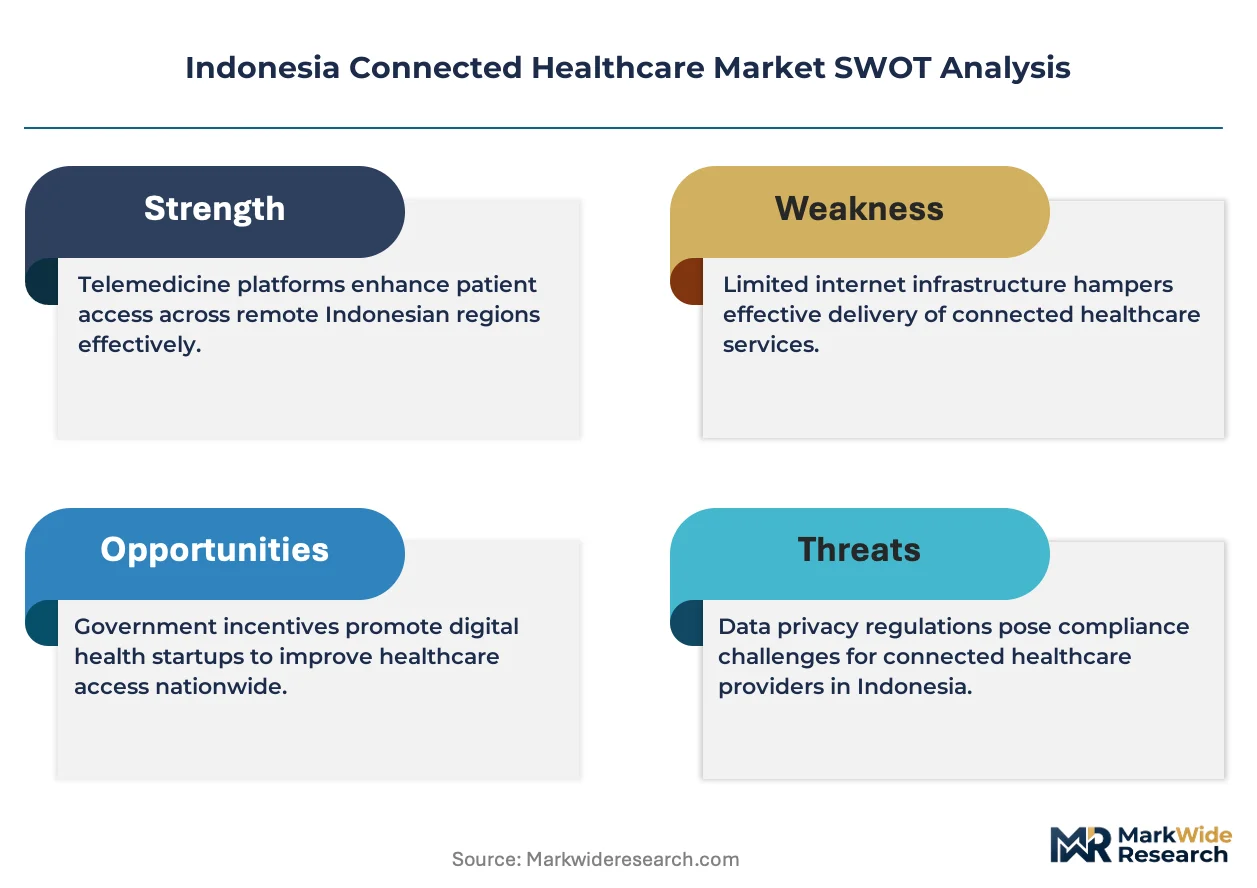
Indonesia's SATUSEHAT interoperability mandate is compressing vendor selection cycles as hospital networks prioritize API-compliant platforms over legacy point solutions. This regulatory pressure is consolidating procurement authority toward integrated system providers capable of seamless data exchange across public and private care settings.
Growth Catalysts
- Telehealth infrastructure expansion:Rural health clinics in East Java and Central Java are deploying cloud-native consultation platforms as primary care access points, extending specialist reach without facility investment.
- Chronic disease monitoring protocols:Diabetes and cardiovascular management programs are integrating continuous glucose monitors and blood pressure wearables into provincial health insurance reimbursement frameworks.
- Ministry of Health digitization roadmap:National funding allocations for electronic medical record modernization are accelerating hospital IT refresh cycles in tier-two cities.
Market Restraints
- Data residency compliance costs:Local cloud hosting mandates under Indonesia's data protection authority rules are inflating operational expenditures for foreign platform providers.
- Medical device software classification delays:Uncertainty around software-as-medical-device thresholds is extending product registration timelines for AI-powered diagnostic tools.
- Specialist physician concentration:Java-based clinical expertise limits telehealth quality assurance for remote island deployments in Papua and Maluku.
Strategic Opportunities
- Home-based elderly monitoring:Surabaya and Bandung private hospital chains are piloting IoT-enabled aging-in-place programs for middle-class families.
- HL7 FHIR-native architecture:Interoperability-first platform design is opening public hospital procurement channels previously locked to incumbent vendors.
- Pharmacy-teleconsultation convergence:Urban consumer demand for prescription fulfillment within single-app experiences is creating channel innovation opportunities.
Industry Challenges
- Clinical informatics talent scarcity:Shortage of FHIR implementation specialists is delaying integration timelines for regional hospital networks outside Jakarta.
- Legacy HIS system fragmentation:Proprietary data formats in existing hospital information systems are complicating SATUSEHAT API migration projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Connected Healthcare Market |
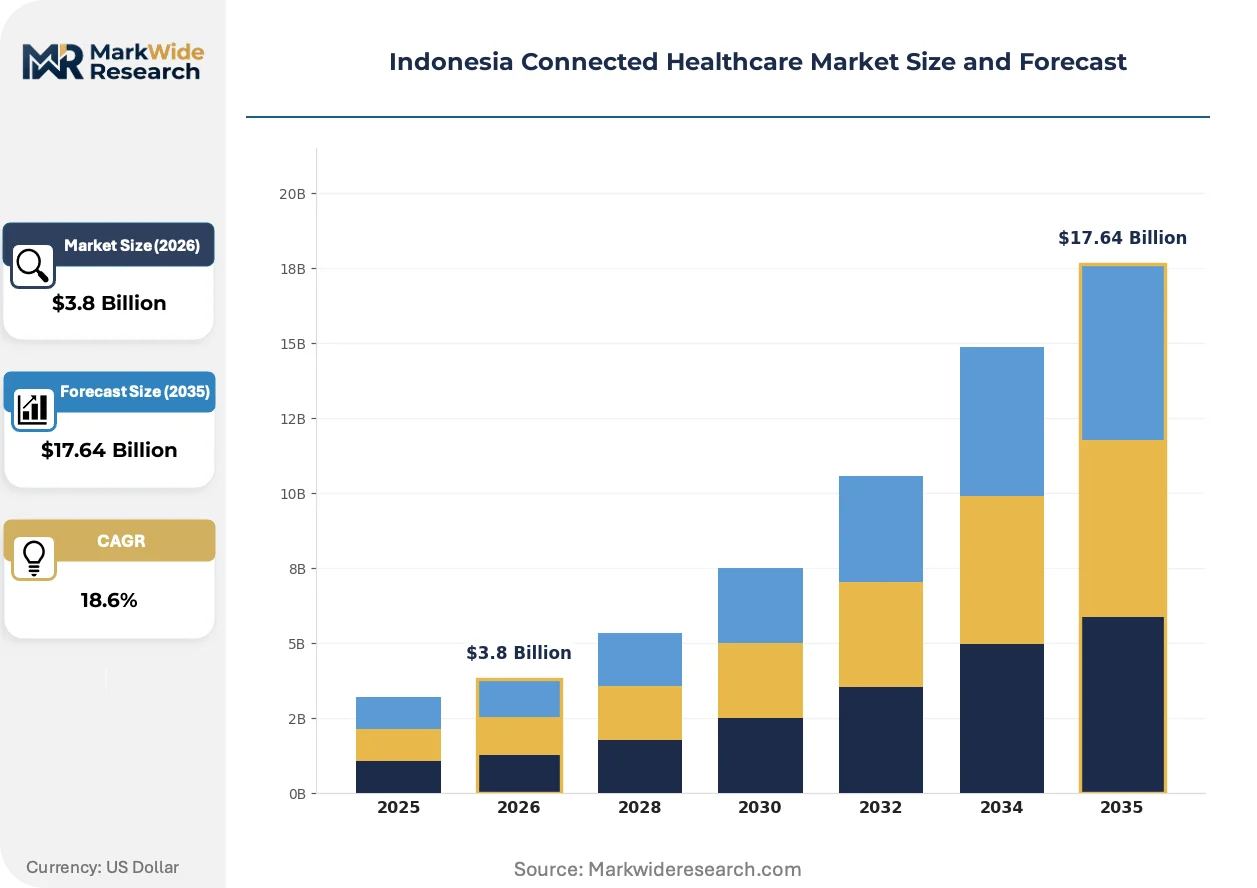
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Telehealth Solutions, Remote Monitoring Tools, mHealth Apps Delivery Mode: Cloud-Based, On-Premises, Hybrid Solutions, Mobile Platforms End User: Hospitals, Clinics, Home Care Providers, Healthcare Professionals Application: Chronic Disease Management, Elderly Care, Mental Health Services, Fitness Tracking |
| Companies Covered | KlikDokter, GE HealthCare, Halodoc, Medtronic PLC, Philips Indonesia, Alodokter, SehatQ, PT Siemens Healthineers Indonesia, Good Doctor, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Connected Healthcare Market Trends and Innovations
Platform architecture decisions are reshaping competitive positioning as interoperability becomes a non-negotiable procurement criterion. Three forces are compressing the technology stack and reconfiguring service delivery models across Indonesian healthcare.
Cloud-native telehealth infrastructure is consolidating point solutions into unified care coordination platforms. Regional hospital networks in Surabaya and Medan are prioritizing vendors offering integrated video consultation, e-prescription, and remote monitoring within single deployments. This technology compression is eliminating standalone niche providers from public procurement shortlists.
Indonesia's Ministry of Health SATUSEHAT mandate is mandating real-time health data exchange standards across all licensed facilities. The regulation is forcing EMR vendors to reengineer proprietary architectures toward open API frameworks. Private hospital chains in Jakarta are responding fastest, using compliance timelines to justify full-stack replacement of aging systems.
Subscription-based platform licensing is displacing perpetual software purchases in provincial health authority procurement. Hospital procurement committees in Central Java and Yogyakarta are negotiating multi-year SaaS contracts bundling implementation, training, and interoperability certification. This financing shift favors vendors with localized support infrastructure over pure-technology exporters.
Indonesia Connected Healthcare Market Segmentation
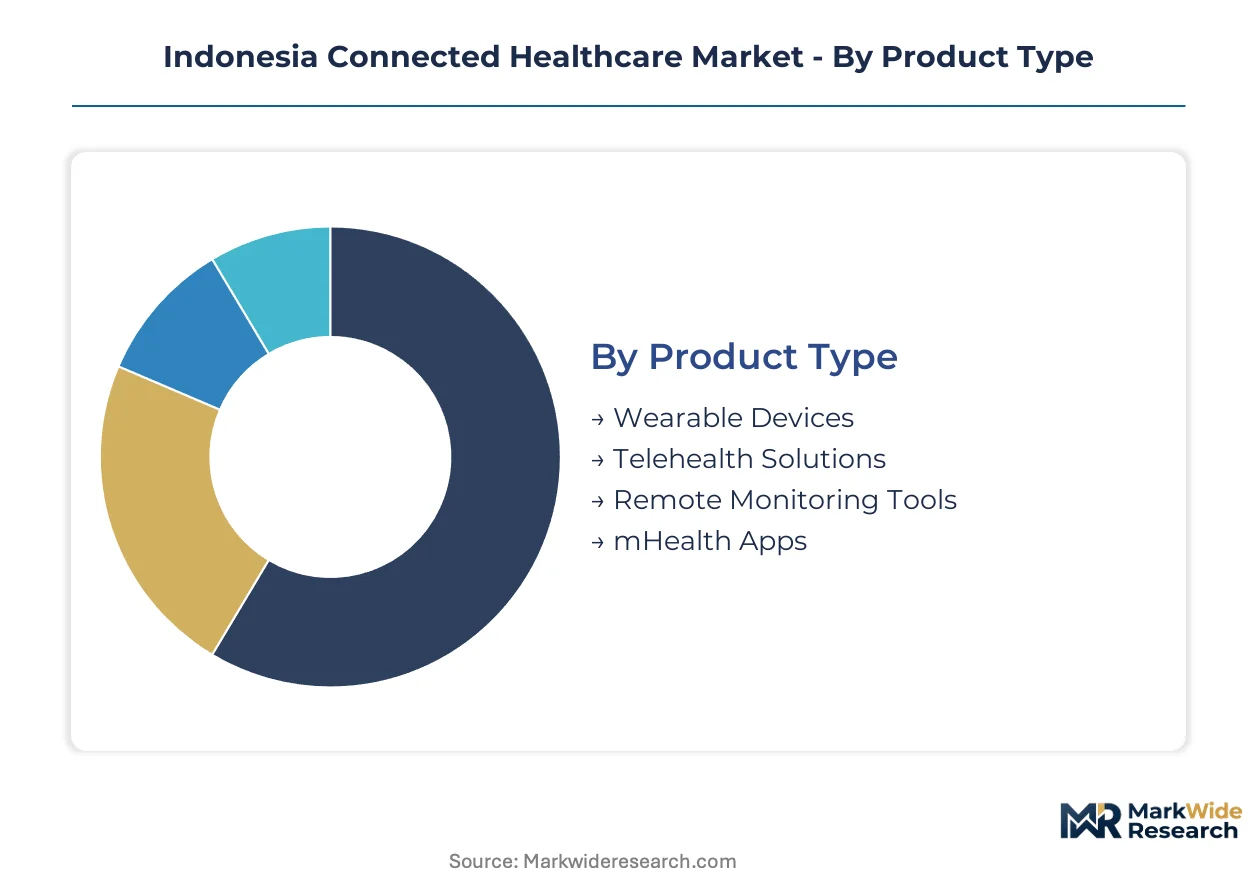
Indonesia's SATUSEHAT interoperability mandate fragments procurement across compliance tiers, with certified platforms commanding premium positioning in public hospital networks. Segmentation reveals where regulatory burden concentrates margin pressure and which delivery modes exploit cloud-native architectures to compress implementation timelines.
Product Type:
Certification requirements from Indonesia's Ministry of Health and the national data protection authority split this category into medical device software classifications versus consumer wellness exemptions, determining registration timelines and local hosting obligations.
- Telehealth Solutions:Cloud-native platforms integrating video consultation, e-prescription, and care coordination dominate procurement in Jakarta and Surabaya hospital networks. Provincial health authorities prioritize these for rural clinic deployments under national digitization funding.
- Remote Monitoring Tools:Continuous glucose monitors and blood pressure wearables feed real-time data into SATUSEHAT-compliant EMR systems. Diabetes management programs in Central Java and Yogyakarta are integrating these into reimbursement frameworks.
- Wearable Devices:Consumer-grade fitness trackers face price sensitivity constraints in price-conscious segments.
- mHealth Apps:Smartphone-first preventive health engagement channels expand reach among urban millennials without device procurement costs.
Telehealth Solutions sits at the top of the volume ranking, with Remote Monitoring Tools climbing the fastest.
Delivery Mode:
Cost tier stratification separates enterprise-grade deployments from budget-constrained provincial implementations, with subscription licensing displacing perpetual purchases fastest in tier-two city procurements.
- Cloud-Based:SaaS architectures with local Indonesia data residency compliance anchor Ministry of Health EMR modernization contracts. Multi-year bundled agreements covering implementation and training are standard in Central Java and Yogyakarta health authorities.
- Hybrid Solutions:Split architectures keeping sensitive patient data on-premises while routing analytics to cloud layers address data protection authority requirements for cross-border flow restrictions. Private hospital chains in Jakarta favor these for legacy system coexistence.
- On-Premises:Capital-intensive deployments persist in security-sensitive tertiary facilities with established IT infrastructure.
- Mobile Platforms:Lightweight deployments target community health worker field operations with intermittent connectivity.
Cloud-Based commands the dominant share of new procurement value, while Hybrid Solutions are gaining share fastest among established hospital networks managing transition risk.
End User:
Customer type maturity determines integration complexity, with hospital networks demanding full-stack interoperability while home care providers prioritize standalone ease of deployment.
- Hospitals:Tertiary and secondary facilities drive SATUSEHAT API compliance investments, replacing aging HIS systems with FHIR-native architectures. Jakarta and Surabaya anchor this demand through private chain digitization and public network consolidation.
- Home Care Providers:IoT-enabled aging-in-place programs for middle-class families in Surabaya and Bandung create deployment momentum. These operators favor plug-and-play monitoring kits with minimal IT overhead.
- Clinics:Rural primary care access points in East Java deploy cloud-native consultation platforms without facility investment.
- Healthcare Professionals:Individual practitioner adoption concentrates in specialist teleconsultation and second-opinion services.
Hospitals absorb the largest absolute technology spend, with Home Care Providers expanding most quickly as private chains pilot subscription-based elderly monitoring programs.
Application:
Geography concentrates demand where disease burden and purchasing power align, with Java-based deployments leading while eastern islands lag in infrastructure readiness.
- Chronic Disease Management:Diabetes and cardiovascular protocols integrate continuous monitoring into provincial insurance frameworks. East Java and Central Java rural clinics use these programs to extend specialist reach without permanent staffing.
- Elderly Care:Aging-in-place IoT deployments target middle-class families in Surabaya and Bandung private hospital catchment areas. Demographic shifts and nuclear family structures drive subscription model acceptance.
- Mental Health Services:Teleconsultation platforms address stigma barriers and specialist scarcity in urban centers.
- Fitness Tracking:Consumer wellness applications face monetization challenges in price-sensitive segments.
Chronic Disease Management leads application-specific procurement volume, with Elderly Care showing the steepest expansion trajectory as private providers build recurring revenue models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's connected healthcare sector traces its modern scaling to post-2010 national health insurance expansion and smartphone penetration waves that enabled platform-based service delivery. Java's hospital networks pioneered EMR digitization, establishing templates now diffusing to provincial health authorities. The SATUSEHAT interoperability mandate of 2022 accelerated this trajectory by forcing technical standardization across public and private systems.
Java
Jakarta anchors national demand through private hospital chain digitization and tertiary facility IT refresh cycles. The Ministry of Health's SATUSEHAT API compliance deadlines drive full-stack EMR replacements in 12 public hospital networks. Surabaya and Bandung clusters concentrate home-based elderly monitoring pilots, with IoT-enabled aging-in-place programs targeting middle-class nuclear families.
Sumatra
Medan's private hospital chains deploy hybrid cloud architectures to manage legacy system coexistence during SATUSEHAT migration. The national data protection authority's local hosting mandates inflate operational costs for foreign platform providers entering North Sumatra's procurement markets. Palembang's provincial health authority negotiates multi-year SaaS contracts bundling implementation and interoperability certification.
Sulawesi
Makassar's regional hospital networks face clinical informatics talent scarcity, delaying FHIR implementation timelines outside established IT hubs. The Ministry of Health's rural clinic digitization funding extends cloud-native telehealth platforms to primary care access points in South Sulawesi. Manado's private providers pilot pharmacy-teleconsultation convergence for urban consumer prescription fulfillment.
Kalimantan
Balikpapan's oil and gas sector employee health programs drive demand for occupational telehealth and remote monitoring deployments. East Kalimantan's provincial health authority struggles with specialist physician concentration gaps, limiting telehealth quality assurance for remote interior deployments. Samarinda's hospital networks prioritize API-compliant platforms over legacy point solutions in compressed vendor selection cycles.
Papua and Eastern Islands
Jayapura's health infrastructure faces the starkest specialist scarcity, constraining telehealth efficacy despite platform availability. The national digitization roadmap allocates limited connectivity investment to Papua and Maluku, lagging Java-based deployment velocity. Biak and Sorong clinics rely on mobile-platform lightweight deployments targeting community health worker field operations with intermittent connectivity.
Indonesia Connected Healthcare Market Competitive Landscape
Capital-heavy medical device producers compete with asset-light platform designers for procurement authority in Indonesia's hospital networks. The vendor base stratifies across three tiers: integrated system providers capable of full-stack SATUSEHAT compliance, specialized telehealth platforms with pharmacy network partnerships, and foreign equipment manufacturers with established imaging-IT installed bases. Consolidation pressure favors integrated vendors as procurement committees eliminate standalone niche providers from public shortlists. Dominant competitive moves include strategic partnerships with provincial health authorities and portfolio diversification into subscription-based SaaS licensing.
Within the integrated system tier, GE HealthCare and Philips Indonesia anchor large tertiary hospital contracts through imaging-IT integration expertise and patient monitoring installed bases. Halodoc occupies the pharmacy-teleconsultation super-app position, dominating urban consumer mindshare through single-app prescription fulfillment experiences. These three exemplify the archetype segmentation compressing Indonesia's vendor landscape: equipment-anchored integrators, platform-native consumer aggregators, and hybrid hardware-software providers navigating SATUSEHAT compliance timelines.
| Leading Market Players |
|---|
| KlikDokter |
| GE HealthCare |
| Halodoc |
| Medtronic PLC |
| Philips Indonesia |
| Alodokter |
| SehatQ |
| PT Siemens Healthineers Indonesia |
| Good Doctor |
| Others |
Pricing and Supply Chain Analysis
FHIR implementation specialists concentrated in Jakarta and Surabaya create labor-cost differentials that widen pricing spreads between SATUSEHAT-certified enterprise deployments and uncertified provincial installations. Cloud-native platform providers absorb premium talent costs in Java while tier-two city procurements face compressed margins from remote integration timelines.
Pricing Analysis
Multi-year SaaS licensing with bundled implementation and training anchors hospital procurement in Central Java and Yogyakarta health authorities. Price differentiation separates API-compliant platforms with local hosting certification from legacy point solutions facing replacement pressure. Cost compression in the economy tier intensifies as provincial health authorities negotiate standardized subscription terms without customization. Private hospital chains in Jakarta demonstrate lowest price sensitivity, prioritizing interoperability certification over licensing cost.
Supply Chain Analysis
Indonesia's data protection authority local hosting mandates reshape sourcing toward domestic cloud infrastructure providers and certified integration partners. Hardware components for patient monitoring systems draw from China, South Korea, and Singapore manufacturing hubs. Software development and FHIR architecture expertise centers on India and Singapore service centers. Single-source vulnerability concentrates in cloud infrastructure provisioning where foreign platform providers face operational expenditure inflation from data residency compliance. Distribution runs through provincial health authority procurement committees and private hospital chain IT departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's connected healthcare sector offers geographic-arbitrage value for vendors able to leverage India's clinical informatics talent density against Jakarta's SATUSEHAT compliance premiums.
For Market Incumbents: Lock in tertiary hospital network relationships through imaging-IT integration contracts before EMR modernization cycles complete. Acquire FHIR implementation specialists in Surabaya and Bandung to defend against remote monitoring entrants targeting home-based elderly care subscriptions. Prioritize backward integration into local cloud hosting infrastructure to neutralize data residency cost disadvantages. For New Entrants and Emerging Players: Launch via pharmacy-teleconsultation super-app partnerships to bypass capital-intensive hospital procurement barriers. Target home care providers in Surabaya and Bandung with plug-and-play IoT monitoring kits priced for middle-class nuclear family budgets. Exploit clinical informatics talent scarcity outside Java by offering remote implementation support bundled into SaaS licensing. For Investors and Strategic Acquirers: Hospital network operators are the most active acquirer in this space, consolidating provincial health authority procurement channels through platform integration plays. Long-term viability hinges on SATUSEHAT API compliance depth rather than standalone feature differentiation. Monitor provincial health authority SaaS contract velocity as the inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| SATUSEHAT API Certification | Unlocks public hospital procurement channels previously restricted to incumbent vendors. |
| Local Cloud Hosting Partnership | Neutralizes data residency compliance cost inflation from Indonesia's data protection authority rules. |
| Pharmacy Network Integration | Captures urban consumer prescription fulfillment demand within single-app experiences. |
| FHIR-Native Architecture Development | Accelerates EMR replacement cycles in Jakarta and Surabaya private hospital chains. |
| Home Care Provider Channel Program | Builds recurring revenue from Surabaya and Bandung aging-in-place pilot expansions. |
Research Methodology
Coverage spans Java, Sumatra, Sulawesi, and Papua, with primary inputs from each region's hospital procurement committees and provincial health authorities. The approach combines structured interviews with hospital IT directors, biomedical engineers, GPO contracts managers, and cloud platform integration specialists alongside secondary validation from Ministry of Health digitization roadmap disclosures, SATUSEHAT API documentation, and provincial health insurance reimbursement framework updates. Bottom-up facility-level deployment tracking triangulates against top-down national health expenditure flows.
Granularity-level modeling segments by product type, delivery mode, end user, and application across the analysis window. Deployment velocity curves for cloud-native telehealth platforms and remote monitoring tool adoption rates inform segment-specific growth trajectories. CAGRs derive from facility penetration assumptions tied to SATUSEHAT compliance deadlines and provincial digitization funding allocations.
Several conditions sit outside the modeled scope, including unannounced regulatory revisions to medical device software classifications and potential telecommunications infrastructure investment accelerations in eastern Indonesia. Forecasts reflect assumptions about SATUSEHAT API stability and specialist physician distribution patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Global Healthcare Informatics Market
Health Informatics
EHR EMR Market
Health Informatics
United States Healthcare Information Exchange Market
Health Informatics
US Laboratory Informatics Market
Health Informatics
Healthcare Prescriptive Analytics Market
Health Informatics
AI in Healthcare Market
Health Informatics
Vocal Biomarkers Market
Health Informatics
United States Healthcare Fraud Detection Market
Health Informatics
United States EHR Cloud Computing Market
Health Informatics
High Acuity Information Systems Market
Health Informatics
Artificial Intelligence in Epidemiology Market
Health Informatics
Healthcare Human Resources (HR) Software Market
Health Informatics
USA Electronic Health Records (EHR) Market
Health Informatics
AI in Epidemiology Market
Health Informatics
Health Information Exchange (HIE) Market
Health Informatics
Global Radiology Information Systems Market