
 Assisted Living Facilities Market | 2026-2036
Assisted Living Facilities Market Size, Share, and Industry Trends Forecast 2026-2036
Assisted Living Facilities Market Insights
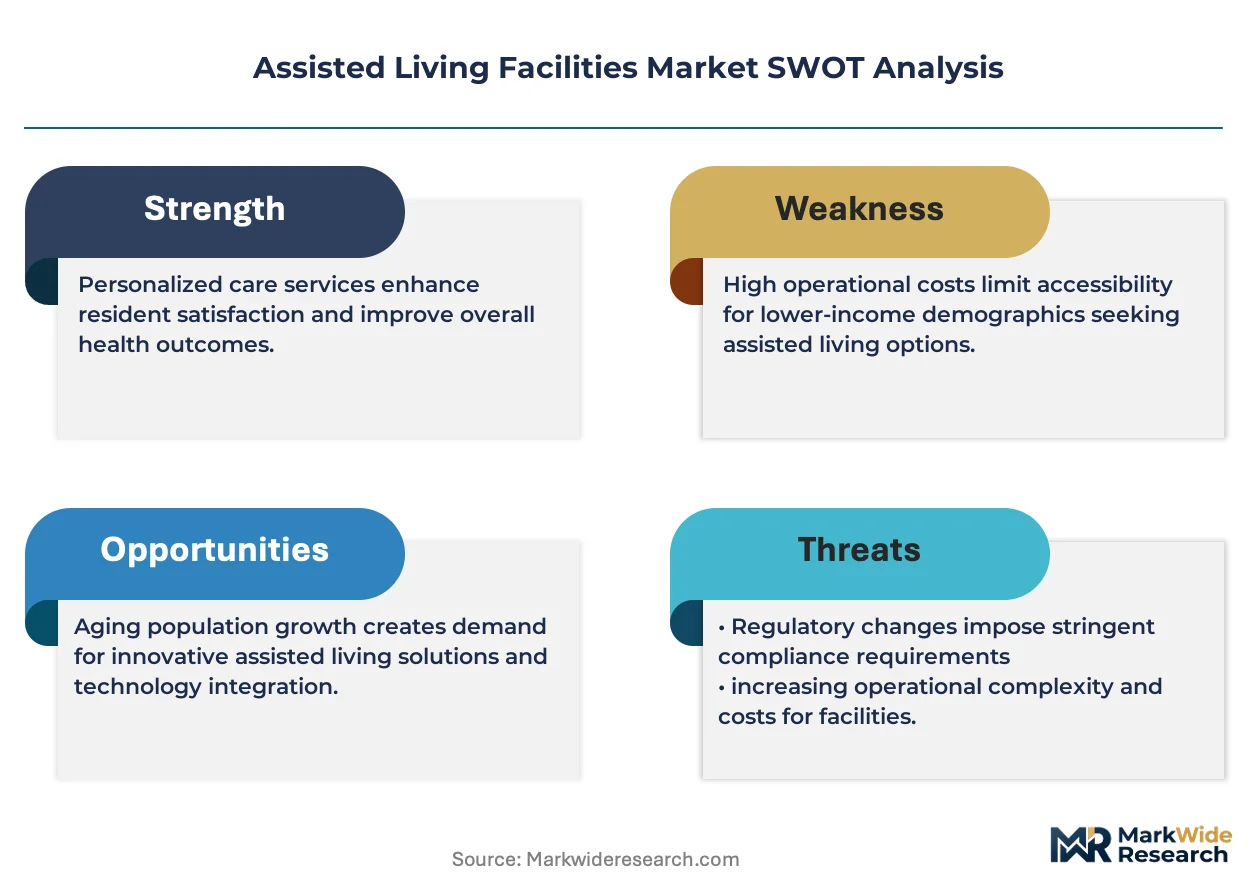
The CMS Five-Star Quality Rating System is pivoting capital allocation across the sector, pressuring operators to upgrade clinical outcomes and resident satisfaction metrics. Brookdale Senior Living leverages its national footprint to spread compliance costs across hundreds of communities. Sunrise Senior Living differentiates through purpose-built memory care environments that command premium private-pay rates. Benchmark Senior Living anchors its expansion in the Northeast corridor, where affluent demographics sustain higher monthly fees.
Assisted living facilities provide residential housing with personal care services, medication management, and 24-hour supervision for individuals requiring assistance with activities of daily living but not continuous skilled nursing care. These facilities typically range from 20 to 200 beds, incorporating emergency call systems, mobility-accessible design, and licensed staff ratios regulated at the state level. Memory Care commands the strongest pricing power within service type segmentation, reflecting specialized staffing requirements and secured environments. Small Facilities face margin compression from fixed cost inefficiency, while Large Facilities achieve operational leverage that supports reinvestment in clinical technology. Luxurious Communities capture disproportionate returns in metropolitan markets where wealth concentration enables amenity-rich programming.
FDA oversight of medical devices used in facilities, combined with CMS reimbursement rules and state-level licensing boards, creates a multi-layered compliance architecture that shapes staffing models and capital deployment. OSHA workplace safety standards and state fire codes further constrain facility design and operational flexibility. Stakeholders must monitor how Medicaid expansion decisions in swing states alter the mix of private-pay versus subsidized residents, as this ratio determines long-term pricing authority and investment returns across portfolios.
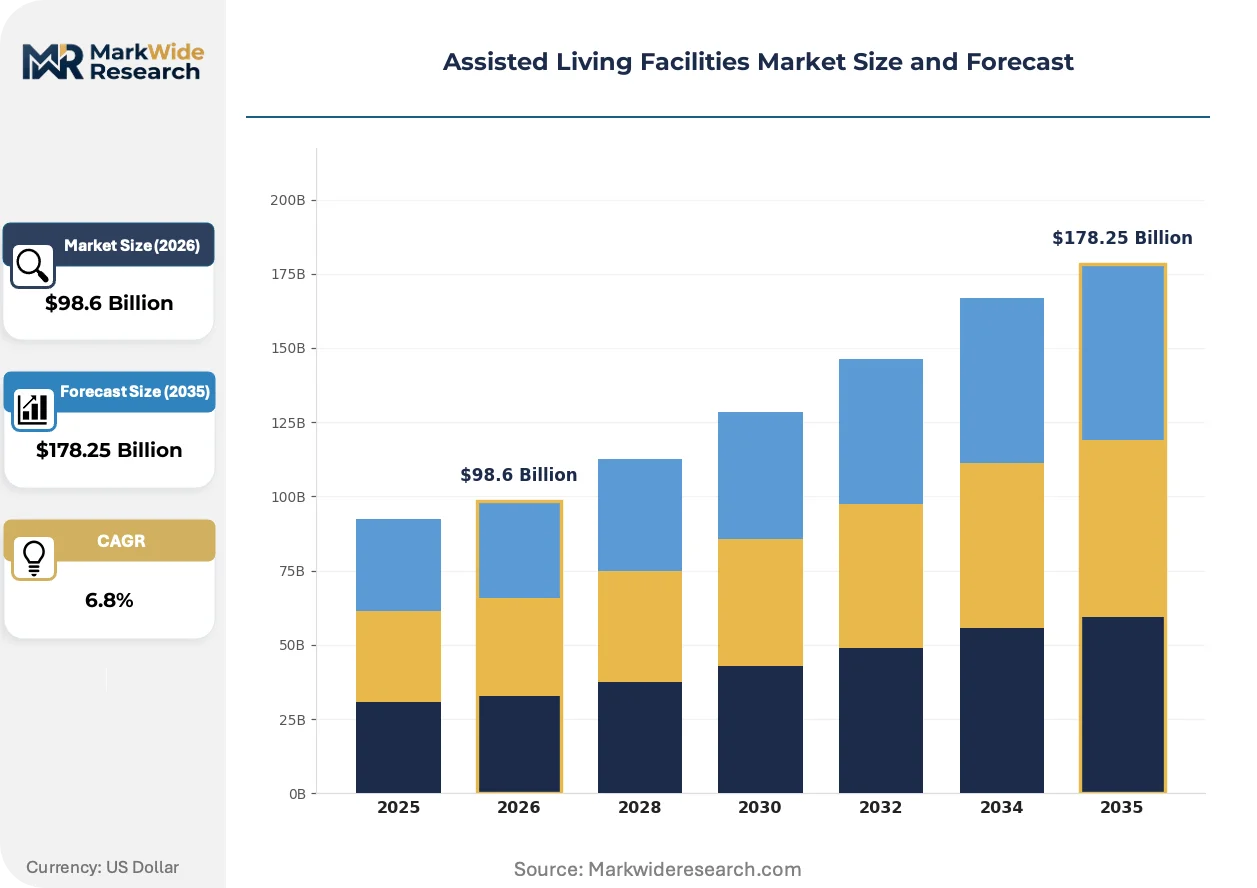
Market Dynamics
CMS Five-Star Quality Rating System revisions are compressing operator margins while simultaneously forcing capital redeployment toward clinical technology and resident experience infrastructure. This regulatory pressure is restructuring competitive positioning across the sector.
Growth Catalysts
- Retiree Migration Patterns:Florida and Texas continue attracting age-qualified households from high-tax northern states, expanding the addressable private-pay population for new facility development.
- Medicaid Expansion:Swing-state decisions to expand Medicaid eligibility are broadening subsidized resident pools and stabilizing occupancy in secondary markets previously dependent solely on private payment.
- Memory Care Specialization:Purpose-built secured environments for dementia care command rate premiums that offset rising labor costs and justify specialized staff training investments.
Market Restraints
- Labor Cost Inflation:Certified nursing assistant wages have escalated faster than rate increases in most markets, compressing facility-level EBITDA.
- State Licensing Variability:Inconsistent staff-ratio requirements across jurisdictions fragment operating models and prevent national scale economies in workforce deployment.
- Real Estate Concentration:Development-grade land scarcity in metropolitan markets with affluent demographics limits greenfield expansion opportunities.
Strategic Opportunities
- Technology-Enabled Remote Monitoring:Integration of FDA-cleared wearable devices with facility electronic health records reduces overnight staffing requirements while improving incident response times.
- Home-Based Care Convergence:Operators establishing licensed home care agencies can capture residents earlier in their aging trajectory and extend relationships through continuum transitions.
- Affluent Suburban Expansion:Secondary markets surrounding major metropolitan areas present underpenetrated demand with lower land acquisition costs and less competition from national brands.
Industry Challenges
- Licensed Nurse Recruitment:Registered nurse availability constrains expansion timelines in markets already experiencing healthcare workforce shortages.
- Legacy System Integration:Electronic health record migrations from outdated platforms to CMS-compliant systems demand substantial capital and operational disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Assisted Living Facilities Market |
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Memory Care, Respite Care, Assisted Daily Living, Skilled Nursing Facility Size: Small Facilities, Medium Facilities, Large Facilities, Luxurious Communities End User: Seniors, Disabled Individuals, Post-operative Patients, Individuals with Chronic Illnesses Payment Model: Private Pay, Long-term Care Insurance, Medicare, Medicaid |
| Companies Covered | Brookdale Senior Living, Atria Senior Living, Sunrise Senior Living, Discovery Senior Living, Five Star Senior Living, Life Care Services, Genesis HealthCare, Benchmark Senior Living, Erickson Senior Living, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Assisted Living Facilities Market Trends and Innovations
Facility operations are absorbing sensor-based ambient monitoring systems that reduce reliance on scheduled room checks. This technology shift is compressing labor models while simultaneously elevating clinical documentation quality.
Passive infrared and acoustic monitoring systems are absorbing the night-shift wellness check function previously performed by hourly floor rounds. Mid-size operators in the southern United States are adopting these platforms fastest, driven by wage pressure and CMS documentation requirements. The technology is absorbing approximately one full-time equivalent position per fifty licensed beds while generating continuous data streams for quality metrics.
OSHA workplace safety standards and state fire codes are mandating enhanced emergency preparedness infrastructure including generator capacity and sprinkler system upgrades. These requirements are forcing accelerated capital expenditure cycles among older facilities built to prior code generations. Operators in Texas and Florida are responding fastest due to hurricane-season reliability demands and corresponding state enforcement intensity.
Adult children are consolidating decision-making authority and demanding transparent pricing with itemized service breakdowns rather than all-inclusive monthly rates. This behavioral shift is disrupting traditional private-pay sales processes and favoring operators with sophisticated revenue management systems. The pattern is most visible in metropolitan markets where adult children maintain professional careers and research facilities through digital channels before scheduling tours.
Assisted Living Facilities Market Segmentation
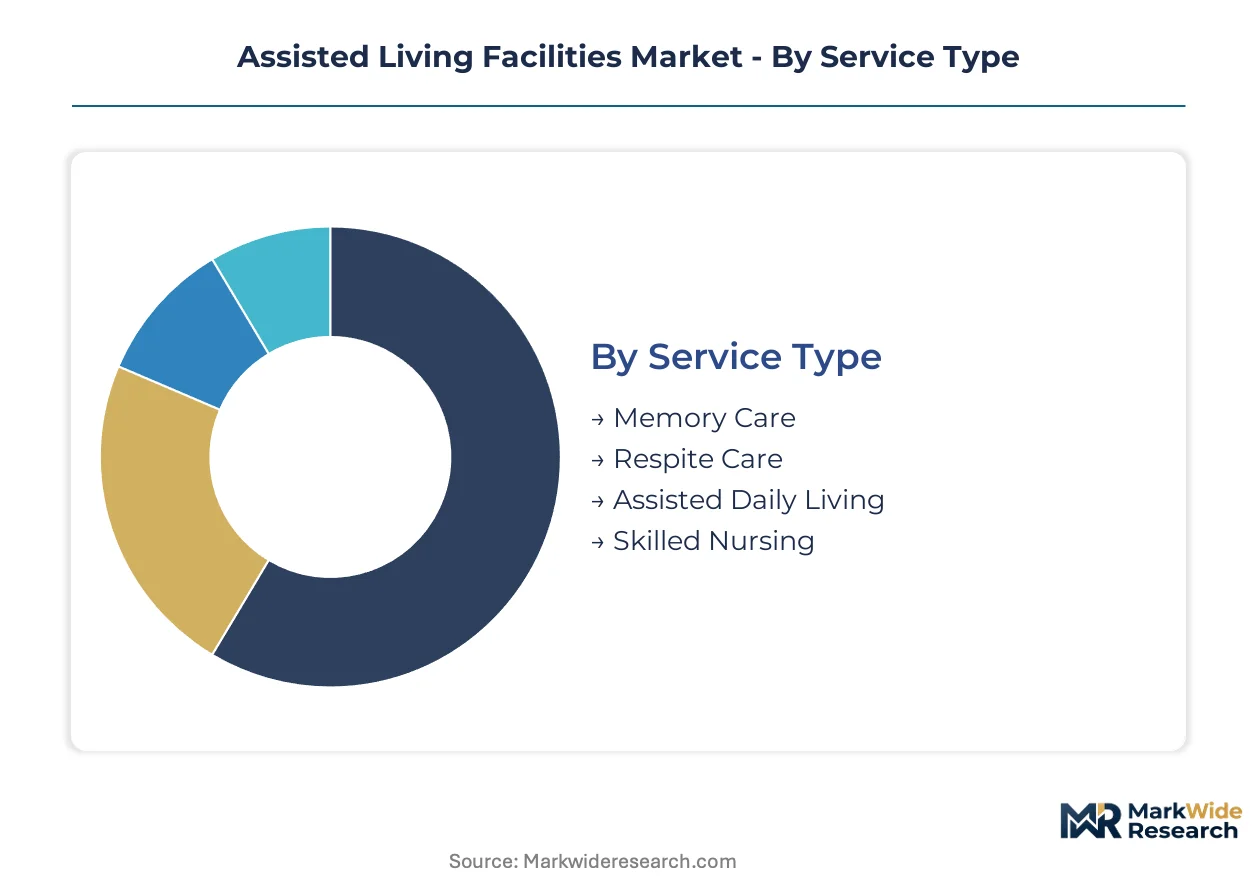
Segmentation in assisted living reveals divergent margin profiles across clinical intensity and capital deployment models. Service specialization and facility scale determine pricing authority, while payment mix constrains reinvestment capacity across operator portfolios.
Service Type:
Memory Care commands rate premiums that offset specialized staffing costs, while Respite Care operates on compressed margins due to short-stay inefficiency.
- Memory Care:Purpose-built secured environments with dementia-specific programming and higher staff-to-resident ratios. Demand concentrates in Florida and Texas retiree corridors where private-pay wealth sustains monthly fees exceeding standard assisted living by substantial margins.
- Assisted Daily Living:Core service tier encompassing medication management, bathing assistance, and mobility support for residents preserving cognitive function. Medium-size operators in the southern United States deploy this as their volume foundation, achieving occupancy stability through standardized care protocols.
- Respite Care:Short-term stays providing temporary relief for family caregivers, typically lasting 30 days or less.
- Skilled Nursing:Clinical services requiring licensed nursing oversight for wound care, IV therapy, and post-acute rehabilitation.
Today's leader: Memory Care. Tomorrow's challenger: Assisted Daily Living.
Facility Size:
Operational leverage separates capital-efficient large campuses from boutique competitors struggling with fixed cost absorption.
- Large Facilities:Campuses exceeding 100 licensed beds achieving procurement scale and administrative cost spreading. Metropolitan markets in Texas and Florida favor these developments where land costs and construction financing demand revenue density.
- Luxurious Communities:Amenity-rich environments targeting affluent households with concierge services, fine dining, and spa programming. Northeast corridor operators command the highest monthly fees in this tier, supported by concentrated wealth demographics surrounding Boston and New York.
- Medium Facilities:50-100 bed operations balancing personalized care with modest scale economies.
- Small Facilities:Under 50 beds with intimate settings but limited ability to spread compliance and technology costs.
Scale advantages currently favor Large Facilities. Regulatory complexity may elevate Luxurious Communities as compliance costs rise.
End User:
Aging demographics and medical advancement are expanding the clinically complex resident population faster than traditional independent seniors.
- Seniors:Age-qualified residents requiring assistance with activities of daily living but preserving decision-making capacity. This cohort dominates occupancy in southern migration destinations where retirees relocate specifically for facility access.
- Individuals with Chronic Illnesses:Residents managing diabetes, heart failure, or COPD requiring coordinated care plans. Medicaid expansion in swing states is broadening subsidized access for this segment, altering payer mix in secondary markets.
- Disabled Individuals:Non-age-related functional limitations requiring residential support services.
- Post-operative Patients:Short-stay residents transitioning from hospital to home with temporary care needs.
Seniors anchor current revenue. Chronic illness residents are gaining share fastest as medical complexity rises.
Payment Model:
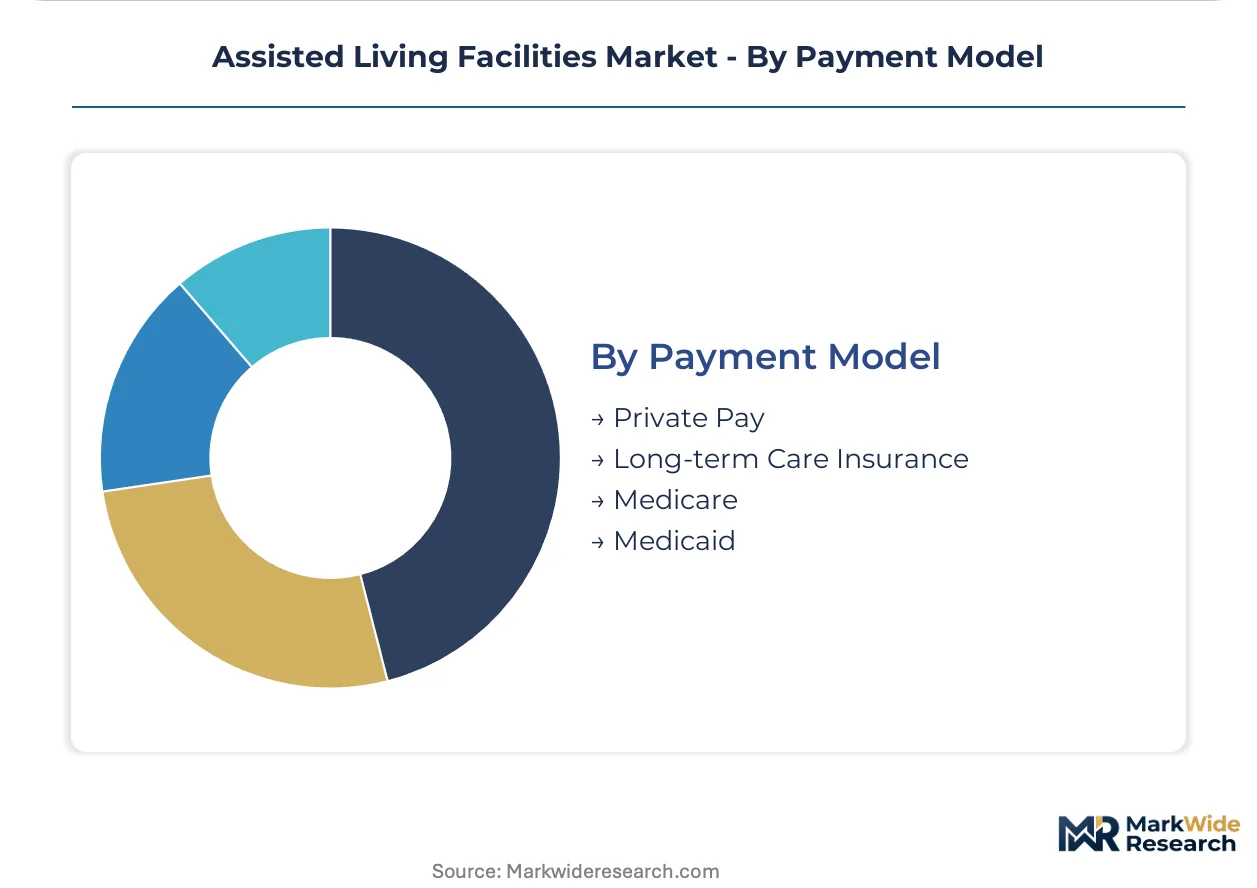
Private-pay concentration determines pricing flexibility, while Medicaid dependency constrains margin expansion across state regulatory environments.
- Private Pay:Direct resident or family payment without insurance intermediation, enabling rate adjustments and service customization. Florida and Texas operators maximize this share through amenity differentiation and transparent pricing structures.
- Medicaid:State-federal partnership covering low-income residents with asset depletion, subject to reimbursement rate caps and eligibility variability. Expansion decisions in Arizona, Georgia, and North Carolina are reshaping addressable markets for operators accepting subsidized residents.
- Long-term Care Insurance:Policy-based payment from products sold decades prior with benefit triggers and daily limits.
- Medicare:Federal coverage strictly limited to skilled nursing following hospitalization, rarely applicable to standard assisted living.
Private Pay dominates value capture. Medicaid expansion states present volume opportunities with compressed returns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern assisted living industry traces its commercial lineage to the United States, where the first purpose-built communities emerged in the 1980s as alternatives to institutional nursing homes. This American origin established the regulatory and operational template that subsequently spread to other developed economies. Today's geographic distribution reflects both demographic aging patterns and wealth concentration that enables private-pay residential care.
United States
Retiree migration from high-tax northern states to Florida and Texas continues reshaping development patterns, with operators prioritizing greenfield projects in Orlando, Tampa, and Austin metropolitan corridors. CMS Five-Star Quality Rating System revisions are forcing capital redeployment toward clinical technology and resident experience infrastructure across the sector. The southern United States concentrates the fastest inventory growth, where favorable operating costs and inbound migration sustain occupancy premiums.
Canada
Provincial health authorities in Ontario and British Columbia are expanding subsidized assisted living capacity to reduce acute care hospitalization among aging populations. Health Canada oversight of medical devices used in facilities creates compliance alignment with US FDA standards, simplifying technology procurement for cross-border operators. Greater Toronto and Vancouver Island host the densest concentration of new developments, driven by Asian immigrant family preferences for formal care arrangements.
United Kingdom
Aging demographics in southeast England and regulatory pressure from the Care Quality Commission are consolidating the historically fragmented operator landscape. The UK government's commitment to adult social care reform remains pending, creating investment uncertainty despite recognized demand expansion. London commuter belt communities and affluent coastal retirement destinations in Sussex and Dorset attract premium-positioned developments targeting equity-release purchasers.
Australia
Consumer-directed care reforms under the Aged Care Quality and Safety Commission are shifting payment authority toward residents rather than institutional allocators. Eastern seaboard metropolitan markets in Sydney and Melbourne face land scarcity constraints that favor brownfield redevelopment over greenfield construction. Queensland's Gold Coast and Sunshine Coast corridors attract interstate retirees seeking climate advantages, replicating the Florida-Texas migration dynamic.
Germany
Long-term care insurance mandates under the Pflegeversicherung system stabilize demand visibility, though reimbursement rate pressures constrain margin expansion for operators. Bavaria and Baden-Württemberg concentrate the highest private-pay willingness, supported by manufacturing wealth and multigenerational household dissolution. Regulatory complexity across Germany's federal state system fragments operating models, preventing the national scale economies visible in North American markets.
Assisted Living Facilities Market Competitive Landscape
Capital-heavy real estate owners compete with asset-light service managers for margin capture across the value chain. The sector exhibits tiered consolidation, with national platforms controlling premium metropolitan inventory while regional operators dominate secondary markets. Three archetypes define competitive positioning: integrated real estate-service platforms, pure-play management companies, and specialized memory care developers. Dominant competitive moves include portfolio acquisitions to achieve geographic density and strategic partnerships with healthcare systems for referral channel security.
Within the integrated platform tier, Brookdale Senior Living and Sunrise Senior Living exemplify scale-driven operators with national footprints spanning multiple regulatory jurisdictions. Atria Senior Living occupies a position emphasizing luxury amenity programming in affluent metropolitan markets. These three companies represent contrasting strategic bets on standardization versus customization, with their divergent approaches to capital deployment and service intensity anchoring competitive reference points across the sector.
| Leading Market Players |
|---|
| Brookdale Senior Living |
| Atria Senior Living |
| Sunrise Senior Living |
| Discovery Senior Living |
| Five Star Senior Living |
| Life Care Services |
| Genesis HealthCare |
| Benchmark Senior Living |
| Erickson Senior Living |
| Others |
Pricing and Supply Chain Analysis
Construction labor cost indices in Texas and Florida cascade through development budgets into monthly resident fee structures, compressing margins at the economy tier while amplifying premiums for amenity-rich communities. This input cost pressure feeds back into site selection decisions, steering capital toward secondary metropolitan corridors where land and labor arbitrage sustains pricing flexibility.
Pricing Analysis
All-inclusive monthly rate bundling dominates private-pay contracts, with three-tier pricing structure across premium, standard, and economy levels separating memory care wings from standard assisted living and shared-room configurations. Price differentiation hinges on staff-to-resident ratios and CMS Five-Star rating attainment, with Florida operators commanding widest spreads. Cost compression in economy tiers is intensifying because Medicaid reimbursement caps lag wage inflation. Adult children with professional careers exhibit lowest price sensitivity; asset-depleted residents dependent on state subsidies face strict eligibility thresholds.
Supply Chain Analysis
Direct-to-facility procurement channels handle bulk purchasing for construction materials and clinical equipment, with distribution runs through regional distributors rather than national platforms. Manufacturing concentrates in the United States for modular building components, Mexico for fixtures and furnishings, and China for electronic monitoring systems. Supply chains draw from lumber futures, HVAC equipment, and FDA-cleared medical devices. Single-source vulnerability in semiconductor-dependent monitoring systems poses structural risk as facilities accelerate technology adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The assisted living sector functions as a regulatory compounder where CMS Five-Star Quality Rating System revisions continuously escalate compliance investment thresholds, embedding demand for clinical technology and specialized staffing infrastructure.
For Market Incumbents: Anchor portfolio resilience through backward integration into home care agency licensing, capturing residents earlier in aging trajectories. Consolidate geographic density in Florida and Texas retiree corridors to spread compliance costs across revenue base. Defend against margin erosion from labor cost inflation by deploying sensor-based ambient monitoring systems that compress overnight staffing requirements.
For New Entrants and Emerging Players: Begin with affluent suburban expansion surrounding Austin, Tampa, and Orlando metropolitan areas, where land costs remain below core urban thresholds and national brand competition thins. Target memory care specialization in secondary markets lacking purpose-built secured environments. Establish transparent itemized pricing structures to capture adult children conducting digital research before facility tours.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale operators in Medicaid expansion swing states possessing untapped private-pay conversion potential. Long-term viability rests on payer mix diversification capacity and technology-enabled operational leverage. Monitor state-level Medicaid reimbursement rate negotiations as inflection indicator for portfolio yield compression or expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology-Enabled Remote Monitoring Deployment | FDA-cleared wearable integration with EHR systems reduces overnight staffing while improving incident response metrics. |
| Home Care Agency Licensing | Licensed home care capture extends resident relationships through continuum transitions before facility admission. |
| Memory Care Wing Development | Purpose-built secured environments command rate premiums that offset specialized dementia-care staffing costs. |
| CMS Five-Star Rating Investment | Quality score improvement directly correlates with pricing authority and referral channel security. |
| Affluent Suburban Geographic Expansion | Secondary metropolitan corridors offer lower land costs with underpenetrated private-pay demand concentration. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining facility occupancy databases and state licensing records with primary discussions involving assisted living operators, CMS compliance officers, state Medicaid directors, and senior housing developers. Secondary validation drew from CMS Medicare cost reports, state health department licensing filings, FDA medical device clearance databases, and construction permitting records across target metropolitan areas. Bottom-up bed-count aggregation and top-down expenditure flow analysis provided cross-verification.
Segment-weighting approaches applied service type, facility size, payment model, and geographic cluster dimensions across the analysis window. CAGRs derived from historical bed inventory expansion correlated with demographic migration patterns and regulatory change timelines. Forecast inputs incorporated retiree migration velocity from high-tax northern states, Medicaid expansion state policy trajectories, and construction labor cost index projections for development-heavy markets.
Several conditions sit outside the modeled scope, including pandemic-era occupancy disruption recurrence, radical Medicaid privatization policy shifts, and breakthrough home-based care technologies displacing residential demand. Forecasts reflect documented assumptions about migration pattern persistence and reimbursement rate stability. Periodic stress-testing of base assumptions is recommended against state budget volatility and workforce shortage severity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Facilities
US and Europe Ambulatory Surgery Centers Market
Healthcare Facilities
Ambulatory Surgical Centers Market
Healthcare Facilities
US Ambulatory Surgery Centers Market
Healthcare Facilities
Global Healthcare Architecture Market
Healthcare Facilities
Mobile Hospitals Market
Healthcare Facilities
Sauna and Spa Market
Healthcare Facilities
Micro-Hospitals Market
Healthcare Facilities
US Ambulatory Surgical Centers Market
Healthcare Facilities
Qatar Senior Living Market
Healthcare Facilities
US Assisted Living Facility Market
Healthcare Facilities
Private Office-Based Clinics Market
Healthcare Facilities
Global Healthcare Facilities Management Market
Healthcare Facilities
US Skilled Nursing Facility Market
Healthcare Facilities
US Office-Based Labs Market
Healthcare Facilities
US Skilled Nursing Facility and Rehabilitation Market
Healthcare Facilities
Trauma Care Centers Market