
 US Artificial Intelligence (AI) Market | 2026-2036
US Artificial Intelligence (AI) Market Size, Share, and Industry Trends Forecast 2026-2036
US Artificial Intelligence (AI) Market Intelligence
Subscription-based access to software-defined AI features is broadening what enterprises purchase rather than build in-house. NVIDIA anchors the infrastructure layer through its dominance in GPU-based training clusters. Microsoft extends its position by integrating copilot capabilities across productivity suites. Anthropic differentiates through specialized focus on constitutional AI safety methodologies.
Artificial Intelligence encompasses computational systems that learn patterns from training data, execute inference through neural network architectures with billions of parameters, and automate decision-making across text, image, and signal domains. Machine Learning and Natural Language Processing command the largest investment flows as enterprises deploy generative interfaces for customer operations. Cloud-Based and Hybrid deployment modes capture accelerating demand as regulated industries balance data sovereignty with computational elasticity. Edge Computing represents the fastest-growing deployment category for autonomous systems requiring sub-millisecond inference latency.
FDA guidance on AI-enabled medical devices shapes validation requirements for healthcare applications, while NIST's AI Risk Management Framework establishes baseline governance expectations for federal contractors and critical infrastructure operators. The SEC's scrutiny of AI disclosures in public filings redirects corporate investment toward explainability tooling. Stakeholders must monitor how state-level algorithmic accountability laws in California, New York, and Illinois fragment compliance obligations beyond federal baselines.
Market Dynamics
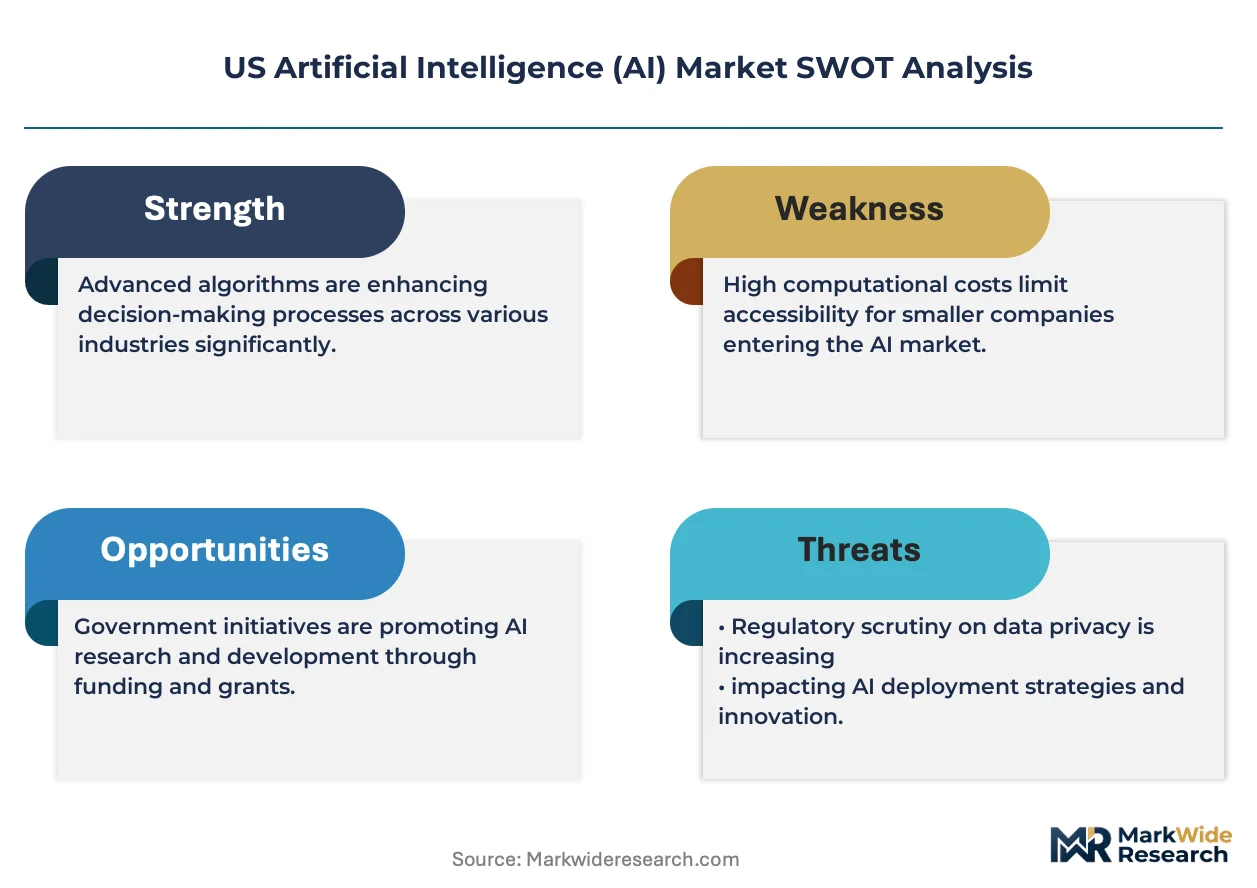
Federal procurement mandates through the NIST AI Risk Management Framework are accelerating enterprise validation spending while compressing vendor qualification timelines for critical infrastructure operators.
Growth Catalysts
- Healthcare algorithm adoption:FDA guidance on AI-enabled medical devices is streamlining 510(k) pathways for diagnostic imaging systems, pulling radiology departments toward automated screening workflows.
- Critical infrastructure mandates:NIST framework requirements for federal contractors are institutionalizing governance tooling procurement across energy, finance, and transportation sectors.
- Bay Area cluster density:San Francisco-San Jose corridor concentration of GPU infrastructure and specialized talent pools is reducing model training costs for enterprise AI labs.
Market Restraints
- GPU supply concentration:Taiwan-based foundry dependency for advanced training chips creates single-point-of-failure exposure for domestic model development pipelines.
- Electricity cost volatility:Data center power consumption for large-scale training runs faces rate pressure from regional grid constraints in Northern California and Virginia.
- State regulatory fragmentation:Algorithmic accountability laws in California, New York, and Illinois impose overlapping compliance architectures that inflate legal overhead for national deployments.
Strategic Opportunities
- Edge inference expansion:Autonomous vehicle and industrial robotics applications in Michigan and Arizona manufacturing corridors are creating demand for sub-millisecond latency architectures outside cloud concentrations.
- IRA clean energy incentives:Tax credits for renewable-powered data centers are repositioning Texas and Oklahoma as alternative training cluster locations with lower carbon compliance costs.
- Small language model specialization:Domain-specific fine-tuning for legal, medical, and financial workflows is opening mid-market penetration paths distinct from general-purpose API competition.
Industry Challenges
- ML operations talent scarcity:Shortage of engineers capable of productionizing research models into governed, monitored systems is extending deployment timelines for regulated enterprises.
- Explainability tooling integration:SEC disclosure requirements for AI-driven financial decisions are forcing retrofit of interpretability layers onto legacy neural architectures not designed for audit trails.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Artificial Intelligence (AI) Market |
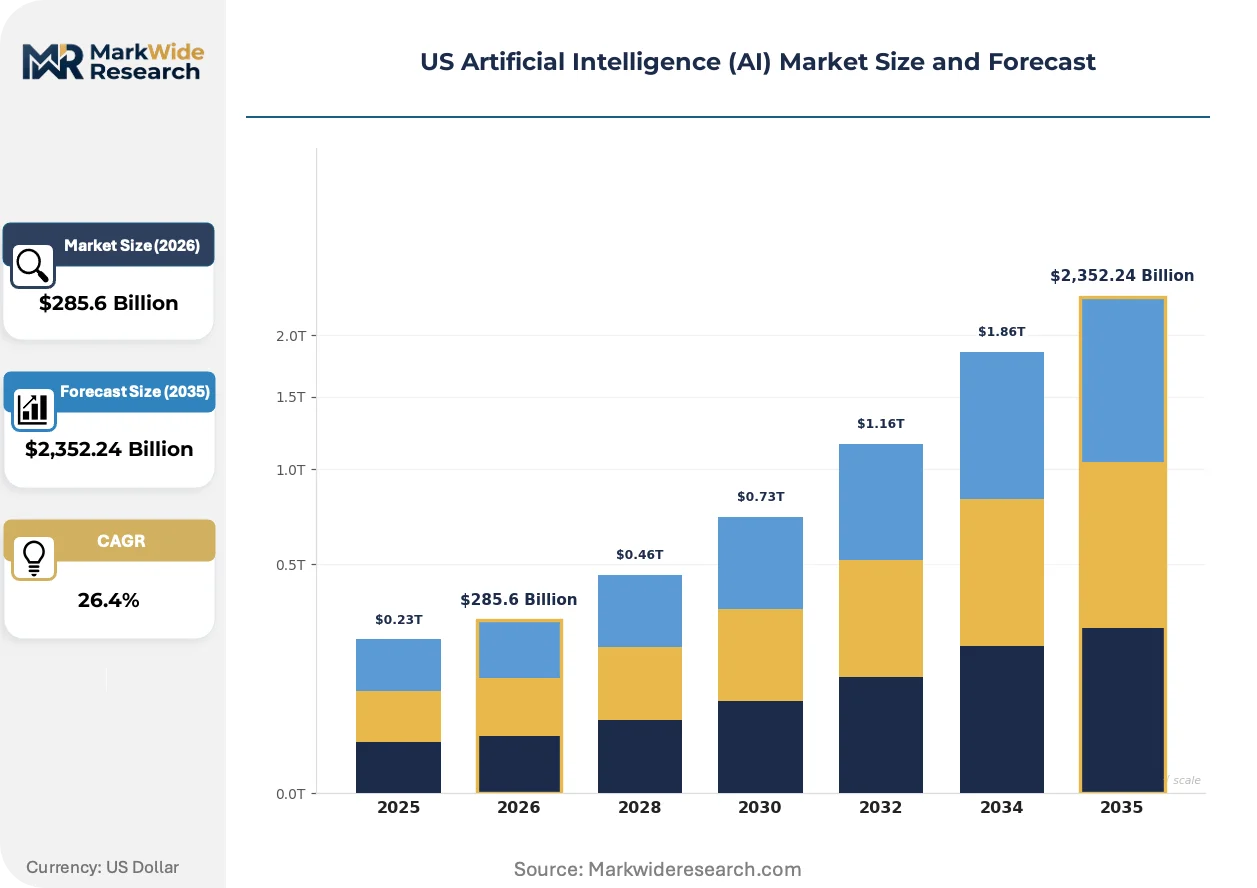
| Market Size in 2026 | $285.6 Billion |
| Market Size in 2035 | $2,352.24 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Computer Vision, Robotics, Speech Recognition, Expert Systems Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing, SaaS, PaaS Application: Fraud Detection, Predictive Maintenance, Customer Insights, Autonomous Systems, Risk Management, Personal Assistants End User: Financial Services, Telecommunications, Manufacturing, Retail Chains, Government Agencies, Education Providers |
| Companies Covered | Amazon, Databricks, NVIDIA, Tesla, Anthropic, Microsoft, Palantir, Intel, Alphabet, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Artificial Intelligence (AI) Market Strategic Shifts & Innovations
Foundation model architectures are fragmenting into specialized vertical stacks as enterprises reject one-size-fits-all APIs in favor of domain-tuned systems with verifiable training provenance.
Retrieval-augmented generation is unifying proprietary enterprise knowledge bases with large language model interfaces. Healthcare systems at Mayo Clinic and Cleveland Clinic are deploying hybrid architectures that ground clinical LLM outputs in institutional electronic health record corpora. This convergence is compressing the competitive window for standalone medical knowledge vendors by embedding diagnostic reasoning directly into hospital IT stacks.
NIST's AI Risk Management Framework is mandating documented bias testing and red-teaming protocols for federal contractors. Defense and energy sector procurement officers are now requiring third-party algorithmic impact assessments as table-stakes for vendor qualification. Critical infrastructure operators in Texas and Pennsylvania are accelerating internal compliance team hiring to meet documentation deadlines ahead of contract renewal cycles.
Enterprise software purchasing is consolidating around subscription tiers that bundle inference capacity with governance tooling. Healthcare and financial services buyers in Chicago and Boston are rejecting per-token pricing in favor of fixed annual contracts with uptime guarantees and audit rights. This bundling is squeezing pure-play model providers who lack adjacent compliance or security features in their product portfolios.
US Artificial Intelligence (AI) Market Segmentation
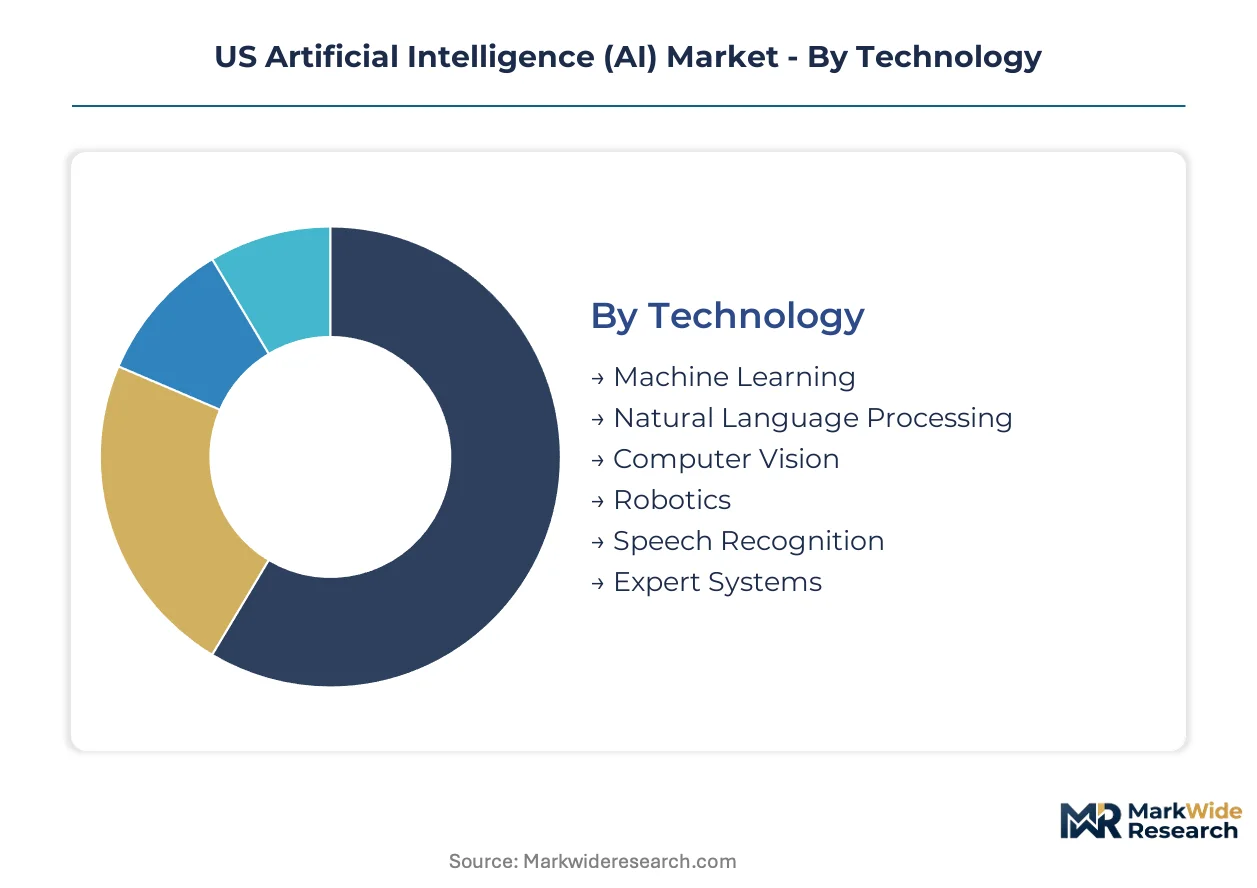
US AI procurement patterns diverge sharply by deployment infrastructure and regulatory exposure. Healthcare and defense contractors prioritize verifiable training provenance over raw performance metrics. Financial services buyers in Chicago and Boston increasingly reject per-token pricing for fixed annual contracts with audit rights.
Technology:
Capital intensity varies enormously across algorithmic approaches, with foundation model training demanding GPU clusters costing nine figures while inference-optimized systems deploy at fraction of that scale.
- Machine Learning:Statistical pattern recognition systems trained on labeled datasets, encompassing supervised, unsupervised, and reinforcement learning architectures. Financial Services in New York and Chicago absorb the bulk of enterprise ML spending for credit scoring and algorithmic trading workflows. Supervised learning dominates production deployments due to interpretability requirements under SEC disclosure rules.
- Natural Language Processing:Transformer-based architectures processing tokenized text for generation, classification, and semantic search. Customer service operations at telecommunications providers and retail chains concentrate demand for conversational interfaces and document automation. Constitutional AI safety methodologies from Anthropic are reshaping procurement criteria for federal contractors.
- Computer Vision:Convolutional and vision transformer networks for image classification, object detection, and segmentation. Manufacturing quality control and autonomous vehicle perception systems drive deployment.
- Robotics:Physical actuation systems integrating perception, planning, and control algorithms. Warehouse automation and surgical assistance applications concentrate demand.
- Speech Recognition:Acoustic modeling and language modeling pipelines for transcription and voice command interfaces. Healthcare documentation and call center analytics dominate uptake.
- Expert Systems:Rule-based inference engines encoding domain knowledge for deterministic decision support. Regulatory compliance and diagnostic assistance in legacy healthcare IT stacks sustain niche demand.
Machine Learning absorbs the bulk of installed capacity; Natural Language Processing is expanding most quickly as generative interfaces penetrate customer operations.
Deployment:
Regulated industries balance computational elasticity against data sovereignty requirements, with HIPAA-covered entities and cleared defense contractors facing distinct constraints from retail or media buyers.
- Cloud-Based:Hyperscaler-managed infrastructure providing elastic compute and storage without capital expenditure. Mayo Clinic and Cleveland Clinic deploy hybrid architectures grounding clinical LLM outputs in institutional EHR corpora. Federal contractors are accelerating compliance team hiring to meet NIST AI Risk Management Framework documentation deadlines ahead of contract renewals.
- Edge Computing:Distributed inference architectures minimizing latency for autonomous decision-making. Autonomous vehicle and industrial robotics applications in Michigan and Arizona manufacturing corridors create demand for sub-millisecond architectures outside cloud concentrations. IRA clean energy incentives are repositioning Texas and Oklahoma as alternative training cluster locations.
- On-Premises:Captive data center infrastructure for workloads requiring air-gapped security or sovereign data control. Classified defense and intelligence applications sustain demand despite higher total cost of ownership.
- Hybrid:Orchestrated workloads spanning private infrastructure and public cloud resources. Energy and transportation sector operators balance burst compute needs against critical asset protection.
- SaaS:Application-layer subscriptions bundling inference capacity with governance tooling. Healthcare and financial services buyers favor fixed annual contracts with uptime guarantees over per-token pricing.
- PaaS:Developer-facing infrastructure abstracts model serving, fine-tuning, and monitoring operations. Enterprise AI labs in the San Francisco-San Jose corridor leverage GPU infrastructure density to reduce training costs.
Cloud-Based deployments retain the largest installed base; Edge Computing is climbing the fastest as autonomous systems proliferate beyond traditional data center geographies.
Application:
Functional use cases map directly to regulatory exposure, with financial decisions and medical diagnoses facing heightened scrutiny versus internal operational optimization.
- Fraud Detection:Anomaly identification systems flagging transactional patterns deviating from established behavioral baselines. Credit card networks and payment processors in Delaware and Georgia concentrate procurement.
- Predictive Maintenance:Sensor fusion and time-series forecasting preventing equipment failure in industrial assets. Manufacturing and energy infrastructure operators drive adoption.
- Customer Insights:Segmentation and propensity modeling for personalization and churn prediction. Retail chains and telecommunications providers compete on recommendation system sophistication.
- Autonomous Systems:Closed-loop perception-planning-actuation for vehicles, drones, and robotic platforms. Arizona and Michigan testing corridors host validation programs for commercial deployment.
- Risk Management:Stress testing and scenario analysis for portfolio and operational risk quantification. SEC disclosure requirements for AI-driven financial decisions force retrofit of interpretability layers onto legacy architectures.
- Personal Assistants:Conversational interfaces for scheduling, search, and task delegation. Enterprise productivity suites integrate copilot capabilities as subscription differentiators.
Risk Management commands the heaviest compliance investment; Autonomous Systems is gaining share fastest as regulatory frameworks for commercial deployment solidify.
End User:
Buyer sophistication and procurement scale vary dramatically, with federal agencies mandating standardized governance tooling while mid-market manufacturers prioritize functional outcomes over documentation depth.
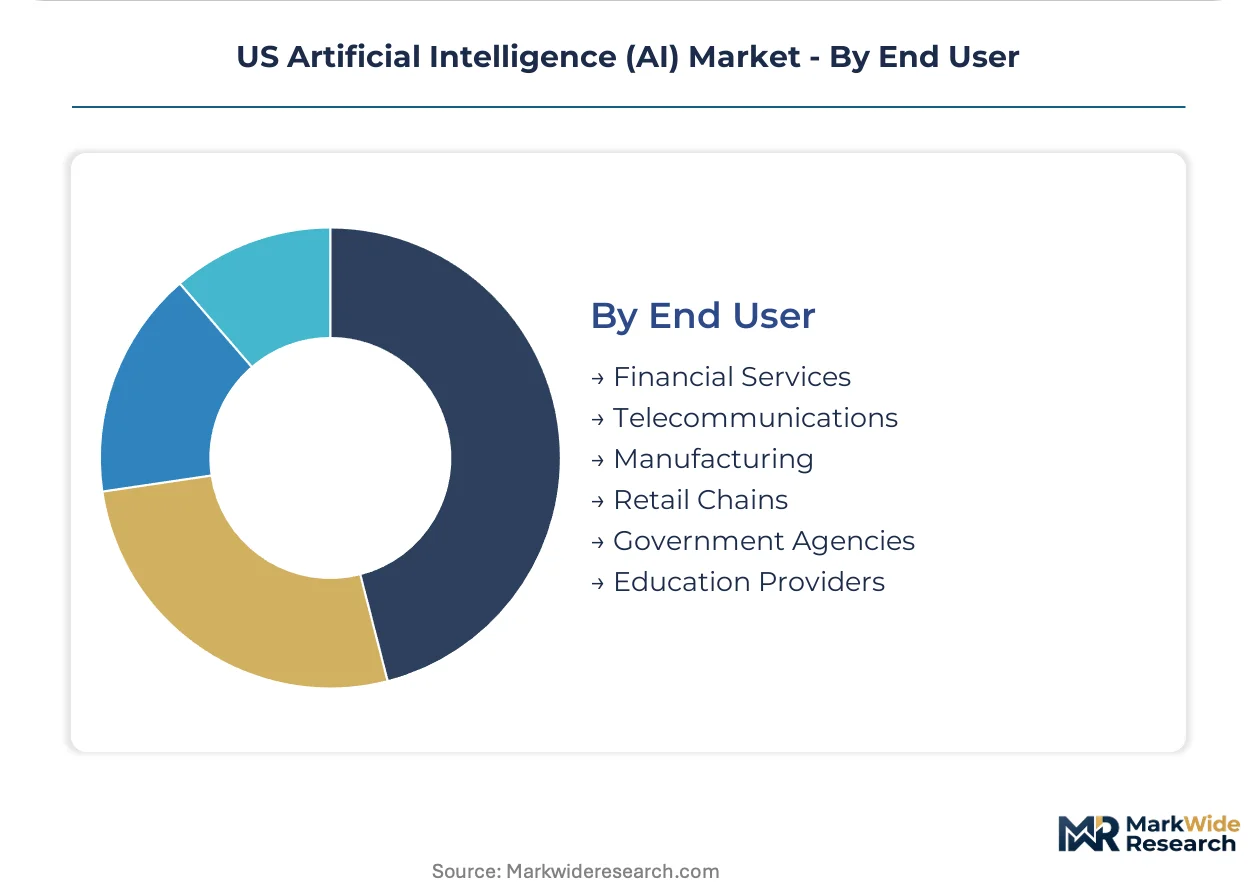
- Financial Services:Banks, insurers, and asset managers deploying algorithmic decision systems under SEC and state regulatory oversight. Chicago and Boston institutions lead fixed-contract subscription adoption with audit rights and uptime guarantees. Explainability tooling integration is forcing retrofit of interpretability layers onto neural architectures not designed for audit trails.
- Government Agencies:Federal, state, and local entities procuring under NIST AI Risk Management Framework mandates. Defense and energy sector procurement officers now require third-party algorithmic impact assessments as table-stakes for vendor qualification.
- Manufacturing:Industrial producers optimizing quality control, supply chain, and predictive maintenance workflows. Michigan and Arizona corridors concentrate autonomous robotics validation programs.
- Telecommunications:Network operators and service providers deploying customer-facing AI and infrastructure optimization. Customer service automation and churn prediction dominate procurement priorities.
- Retail Chains:Consumer-facing merchants personalizing recommendations and optimizing inventory. Recommendation system sophistication separates competitive positioning.
- Education Providers:Universities and K-12 systems deploying adaptive learning and administrative automation. Research institutions maintain training infrastructure for foundational model development.
Financial Services carries the largest compliance overhead burden; Government Agencies is expanding procurement fastest as federal mandates institutionalize AI governance spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California generates the bulk of domestic AI training capacity while consuming disproportionate electricity loads. Texas and Oklahoma capture new investment through renewable tax incentives. Virginia data centers face grid constraints.
California
San Francisco-San Jose corridor concentrates GPU infrastructure and specialized talent pools. NIST AI Risk Management Framework documentation requirements accelerate compliance hiring among federal contractors. Los Angeles media tech clusters deploy generative interfaces for content production workflows.
Texas
IRA clean energy incentives reposition Austin and Dallas-Fort Worth as alternative training cluster locations. ERCOT grid dynamics create rate volatility exposure for large-scale compute operations. Houston energy sector AI labs optimize reservoir modeling and predictive maintenance for upstream assets.
Virginia
Northern Virginia data center concentration faces transmission capacity limits from regional grid operators. Federal procurement mandates through defense and intelligence contracts sustain demand for cleared facility operations. Fairfax County hosts compliance tooling vendors serving NIST framework implementation.
New York
Financial services institutions in Manhattan and Brooklyn drive fixed-contract subscription adoption with audit rights. State-level algorithmic accountability laws impose documentation burdens beyond federal baselines. Albany regulatory technology clusters serve insurance and banking compliance automation.
Illinois
Chicago healthcare systems deploy diagnostic imaging algorithms under FDA 510(k) streamlined pathways. State biometric privacy laws intersect with AI hiring and customer analytics tools. Peoria agricultural equipment manufacturers integrate computer vision for precision farming automation.
US Artificial Intelligence (AI) Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the infrastructure-application divide. Cloud hyperscalers anchor training capacity through captive GPU allocations. Specialized safety researchers differentiate through constitutional methodologies. Boutique model providers face margin pressure from bundled governance tooling subscriptions.
Within the infrastructure tier, NVIDIA exemplifies capital-intensive silicon dominance. Microsoft and Amazon occupy positions spanning cloud compute and application-layer integration. Anthropic represents the specialized safety research archetype with federal contractor qualification pathways.
| Leading Market Players |
|---|
| Amazon |
| Databricks |
| NVIDIA |
| Tesla |
| Anthropic |
| Microsoft |
| Palantir |
| Intel |
| Alphabet |
| Others |
Cost & Logistics Intelligence
GPU foundry capacity in Taiwan flows through hyperscaler procurement contracts into tiered SaaS subscription models, with electricity costs at Northern Virginia and Bay Area data centers stratifying pricing across enterprise buyers. Federal contractors absorbing NIST AI Risk Management Framework compliance costs face divergent pricing pressure from mid-market manufacturers prioritizing functional inference over governance tooling.
Pricing Analysis
Cost-down pressure on inference-optimized deployments accelerates as healthcare systems in Chicago and Boston migrate from per-token consumption to fixed annual contracts bundling uptime guarantees with audit rights. Pricing stratifies across premium tiers with third-party algorithmic impact assessments, standard tiers with basic NIST documentation, and economy tiers serving non-regulated applications. Margin tightening in pure-play model provision reflects bundling of adjacent security features by cloud hyperscalers. Financial services institutions exhibit lowest price sensitivity due to SEC disclosure retrofit requirements, while retail chains and mid-market manufacturers drive hardest bargain negotiations.
Supply Chain Analysis
Regional distribution of GPU training clusters concentrates in California's Bay Area corridor with secondary hubs emerging in Texas and Oklahoma under IRA clean energy incentives. Advanced logic chip fabrication draws from Taiwan-based foundry capacity, HBM memory supply from South Korean manufacturers, and specialized cooling systems from Japanese precision engineering houses. Single-source vulnerability in Taiwan-based advanced node production creates structural exposure for domestic model development pipelines. Distribution runs through hyperscaler captive infrastructure with edge inference nodes dispersing to Michigan and Arizona manufacturing corridors for sub-millisecond autonomous system requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US AI market operates as a cost-of-compliance story where NIST AI Risk Management Framework documentation requirements erect barrier-to-entry moats favoring incumbents with established federal contractor qualification pathways.
For Market Incumbents: To counter margin erosion from bundled governance tooling subscriptions, anchor position through backward integration into GPU cluster infrastructure and accelerate compliance team hiring ahead of defense contract renewal cycles. Prioritize fixed-contract subscription conversion among healthcare systems to lock out pure-play model competitors lacking adjacent security features. For New Entrants and Emerging Players: Capture white-space in domain-specific small language model fine-tuning for legal, medical, and financial workflows where general-purpose API competition thins. Target edge inference architectures for autonomous vehicle and industrial robotics applications in Michigan and Arizona corridors where cloud concentration creates latency gaps. Lead go-to-market with outcome-based pricing tied to measurable operational efficiency gains rather than infrastructure consumption metrics. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized safety research boutiques with federal contractor qualification pathways in the Texas-Oklahoma renewable-powered training cluster corridor. Long-term viability hinges on differentiation through verifiable training provenance and constitutional AI methodologies rather than undifferentiated scale. Monitor IRA clean energy credit utilization rates as inflection indicator for training cost competitiveness shifts away from California grid constraints.| Strategic Initiative | Industry Significance |
|---|---|
| NIST Framework Certification Investment | Federal contractor qualification now requires documented bias testing and red-teaming protocols as table-stakes procurement criteria. |
| Edge Inference Architecture Deployment | Sub-millisecond latency requirements in Michigan and Arizona manufacturing corridors displace cloud concentration for autonomous systems. |
| Constitutional AI Safety Methodology Development | Differentiation through specialized safety research opens procurement pathways among defense and energy sector operators. |
| Renewable-Powered Training Cluster Relocation | IRA tax credits reposition Texas and Oklahoma as lower-carbon-compliance alternatives to Northern California grid constraints. |
| Retrieval-Augmented Generation Platform Integration | Hybrid architectures grounding clinical LLM outputs in institutional EHR corpora compress competitive windows for standalone medical knowledge vendors. |
Research Approach
Multi-period observation of hyperscaler capex disclosures, federal procurement contract awards, and state-level algorithmic accountability legislative tracking anchored the trend analysis, supplemented by interviews with AI lab directors, federal procurement officers, hospital purchasing committee members, and compliance tooling vendors. Secondary validation drew from SEC AI disclosure filings, FDA 510(k) submission databases, NIST framework implementation guidance, and state legislative tracking systems. Bottom-up segment sizing triangulated against top-down infrastructure capacity estimates.
Segment-weighting across deployment mode, end-user vertical, and technology layer informed value distribution modeling throughout the projection horizon. Machine Learning and Natural Language Processing absorption rates were cross-referenced against GPU cluster utilization metrics and federal contract obligation data. CAGRs were derived from infrastructure capacity expansion curves, regulatory mandate implementation timelines, and enterprise software procurement pattern shifts. Industry-specific inputs included NIST framework documentation deadline schedules and FDA diagnostic imaging algorithm approval velocity.
The model holds under sustained federal procurement mandate enforcement and stable Taiwan-based foundry supply; deviation in export control expansion or regional grid instability would shift training cost assumptions and geographic cluster viability. Forecasts reflect documented base conditions with acknowledged sensitivity to algorithmic accountability law fragmentation across California, New York, and Illinois. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Voice Assistance Application Market
Artificial Intelligence (AI)
Automotive Predictive Diagnostic System Market
Artificial Intelligence (AI)
Autonomous AI and Autonomous Agents Market
Artificial Intelligence (AI)
Adaptive AI Market
Artificial Intelligence (AI)
Explainable AI Market
Artificial Intelligence (AI)
North America Chatbot Market
Artificial Intelligence (AI)
Synthetic Data Generation Market
Artificial Intelligence (AI)
Artificial Intelligence in Business Market
Artificial Intelligence (AI)
AI Virtual Assistants Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in BFSI Market
Artificial Intelligence (AI)
Artificial Intelligence for IT Operations (Aiops) Market
Artificial Intelligence (AI)
AI Content Creation Tool Market
Artificial Intelligence (AI)
AI Data Labeling Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Sports Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Assisted Robots Market
Artificial Intelligence (AI)
Intelligent Virtual Assistant Market