
 Voice Assistance Application Market | 2026-2036
Voice Assistance Application Market Size, Share, and Industry Trends Forecast 2026-2036
Voice Assistance Application Market Analytics
Subscription-based software-defined feature packs is broadening how voice assistance platforms monetize beyond hardware sales. Amazon leverages its Alexa developer ecosystem to anchor recurring revenue from smart home integrations. Google competes through deep speech-to-text specialization across Android automotive partnerships. Microsoft sustains enterprise-grade differentiation by embedding voice capabilities within Azure cloud productivity suites.
Voice assistance applications process spoken commands through natural language understanding pipelines, converting acoustic signals into structured intent data via automatic speech recognition with sub-200-millisecond latency targets for real-time responsiveness. These systems serve commercial purposes spanning hands-free device control, automated customer service routing, and contextual information retrieval. Cloud-Based deployment captures the dominant margin pool among deployment models, while Edge Computing architectures gain traction in automotive and wearable segments where latency constraints and data privacy requirements restrict round-trip cloud dependency. Natural Language Processing underpins the core technology stack, though Voice Synthesis investments accelerate as brands seek differentiated sonic identities for their assistants.
The EU AI Act mandates risk classification and human oversight for general-purpose AI systems, directly affecting how voice assistants handle biometric data and generate conversational outputs in European markets. The FDA regulates voice-enabled medical devices as software-as-medical-device when diagnostic or therapeutic claims attach to spoken interactions. China's SAMR enforces algorithmic recommendation provisions on intelligent voice services operating domestically. Stakeholders must weigh jurisdictional compliance burdens against localization investments when prioritizing market entry sequencing.
Market Dynamics
Automotive OEMs now mandate sub-200-millisecond voice response latency as a standard infotainment specification, compressing cloud dependency and accelerating edge-native architecture investments across Tier-1 suppliers.
Growth Catalysts
- EU AI Act transparency mandates:Biometric data handling rules force voice assistant providers to upgrade consent frameworks, creating upgrade cycles for enterprise deployments across European automotive and healthcare verticals.
- Edge computing latency requirements:Wearable and automotive segments demand on-device processing to eliminate round-trip delays, pulling semiconductor foundries toward dedicated neural processing units for acoustic modeling.
- China SAMR algorithmic recommendation rules:Domestic intelligent voice services must register recommendation logic, accelerating localization partnerships for foreign platforms seeking market access.
Market Restraints
- Cloud infrastructure concentration:Hyperscale datacenter capacity for real-time speech-to-text processing concentrates in three US and Chinese provider ecosystems, creating single-source vulnerability for latency-sensitive applications.
- Multilingual training data scarcity:Low-resource language acoustic models require proprietary corpus collection, inflating R&D burn for Indic and African language coverage.
- FDA software-as-medical-device classification:Voice-enabled diagnostic tools trigger 510(k) pathways, extending commercialization timelines for chronic disease monitoring applications.
Strategic Opportunities
- German automotive voice platform integration:Premium OEMs in Stuttgart and Munich seek white-label assistant stacks, opening procurement channels independent of US and Chinese ecosystem dominance.
- Voice synthesis sonic branding:Consumer packaged goods and financial services commission custom neural voices, converting commoditized TTS into differentiated identity assets.
- India PLI scheme for electronics manufacturing:Domestic smart speaker and wearable production incentives attract component suppliers to establish acoustic hardware assembly within tariff-advantaged zones.
Industry Challenges
- Conversational AI talent scarcity:Natural language understanding pipeline engineers with sub-200-millisecond optimization experience command premium compensation, constraining mid-tier platform development velocity.
- Legacy infotainment integration friction:Automotive Tier-1s face software stack incompatibility when embedding modern voice assistants into decade-old head unit architectures still deployed in mass-market vehicle lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voice Assistance Application Market |
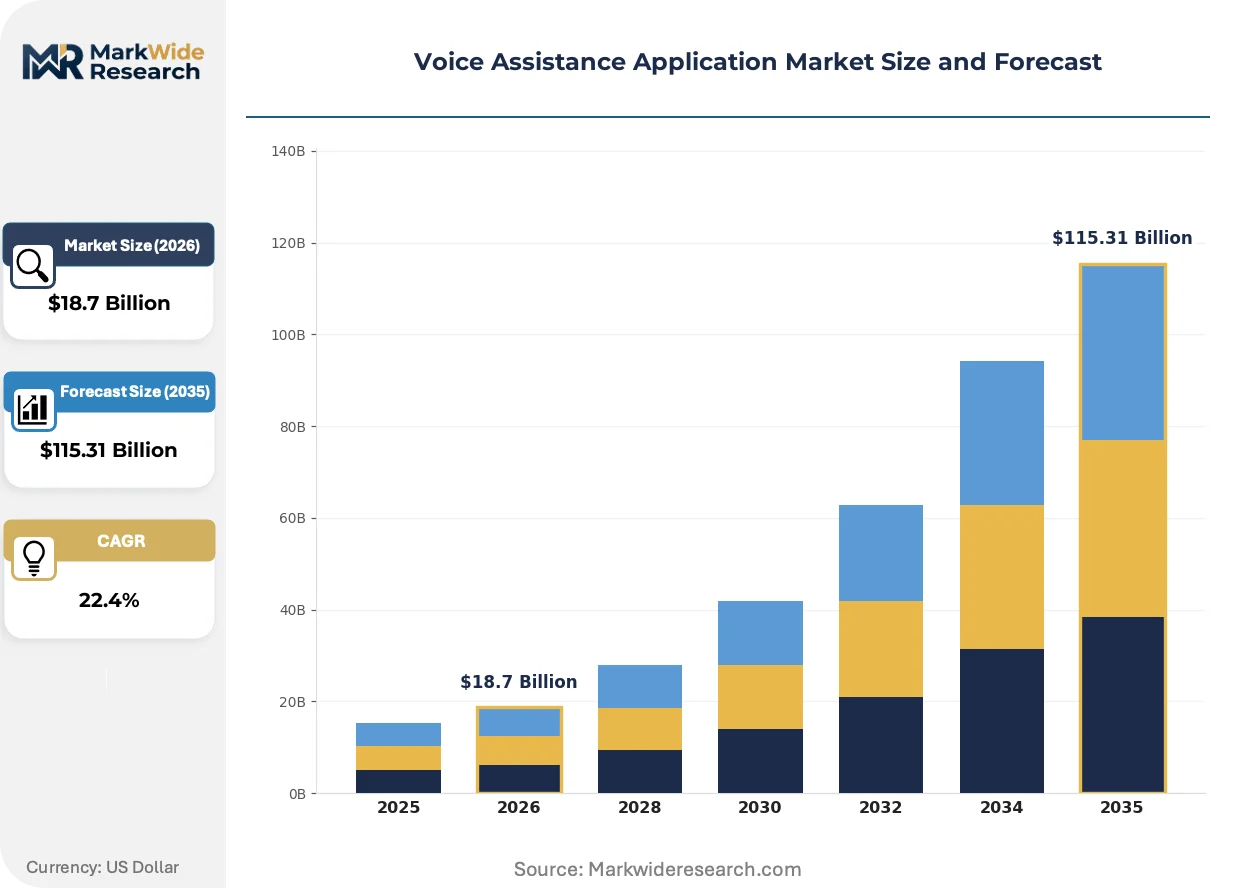
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Smart Home, Wearable Devices, Customer Support, Automotive Technology: Natural Language Processing, Speech Recognition, Voice Synthesis, Machine Learning End User: Individuals, Enterprises, Developers, Retail Deployment Model: Cloud-Based, On-Premises, Hybrid, Edge Computing |
| Companies Covered | Amazon, Google, Apple, Microsoft, Samsung, Baidu, IBM, Nuance Communications, Alibaba, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voice Assistance Application Market Evolving Landscape
Voice assistance architectures are bifurcating between cloud-heavy general-purpose assistants and edge-native specialized stacks, with latency requirements and data sovereignty pressures determining deployment topology.
On-device neural processing for automatic speech recognition is absorbing acoustic inference tasks previously routed to distant datacenters. Automotive Tier-1 suppliers in Germany and Japan are qualifying NPU-integrated system-on-chips for 2026 vehicle programs. This shift is compressing cloud API call volumes while demanding new thermal management solutions for cabin-embedded compute modules.
The EU AI Act's risk classification framework for general-purpose AI systems now governs biometric inference in voice assistants. European automotive OEMs must document human oversight protocols for conversational outputs. Premium vehicle lines destined for German, French, and Italian markets are segmenting voice stack procurement to satisfy documentation burdens that US and Chinese regulatory regimes do not impose.
Enterprise procurement of voice-enabled customer service infrastructure now prioritizes consumption-based pricing over perpetual licensing. Banking and telecommunications buyers in India and Brazil are unbundling implementation services from core platform fees. This pattern is most visible in Asia-Pacific contact center modernization programs where CFO scrutiny of SaaS spend has intensified.
Voice Assistance Application Market Segmentation
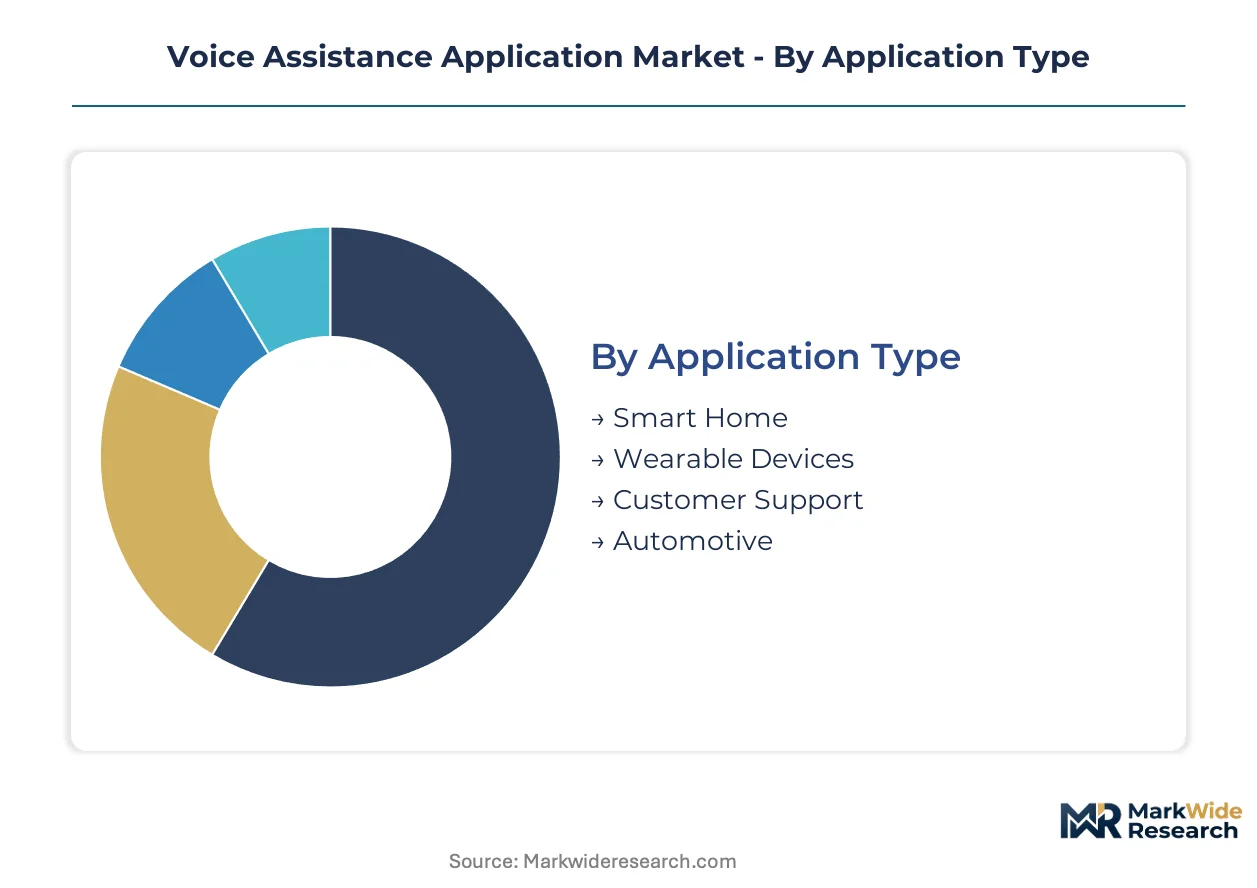
Voice assistance platforms fragment across four structural dimensions that determine procurement economics and technical architecture. Application type dictates latency requirements and privacy sensitivity. Technology stack choices separate general-purpose cloud providers from specialized edge-native vendors. Deployment model selection increasingly reflects data sovereignty pressures rather than pure cost optimization.
Application Type:
Purchase decisions pivot on response latency thresholds and ambient noise tolerance for each use environment.
- Automotive:Sub-200-millisecond response mandates dominate OEM infotainment specifications. Edge-native processing architectures absorb acoustic inference locally to eliminate cloud round-trip delays for Stuttgart and Munich premium vehicle lines.
- Smart Home:Always-listening devices process wake-word detection on-device while routing complex queries to distant datacenters. Fixed-location deployment tolerates higher latency than mobile applications, concentrating volume in speaker and display hardware bundled with ecosystem subscriptions.
- Wearable Devices:Battery-constrained form factors demand aggressive acoustic model compression. Thermal management limits neural processing unit duty cycles in wrist-worn and ear-worn implementations.
- Customer Support:Enterprise contact centers prioritize consumption-based pricing over perpetual licensing. Banking and telecommunications buyers in India and Brazil unbundle implementation services from core platform fees.
Volume sits with Smart Home; growth tilts toward Automotive.
Technology:
Core technology investments concentrate where differentiation creates pricing power against commoditized infrastructure.
- Natural Language Processing:Intent classification and slot-filling pipelines convert acoustic signals into structured command data. The EU AI Act mandates human oversight documentation for general-purpose conversational systems operating in European markets.
- Speech Recognition:Automatic speech recognition with sub-200-millisecond latency targets requires dedicated neural processing units in automotive and wearable segments. Low-resource language acoustic models demand proprietary corpus collection for Indic language coverage.
- Voice Synthesis:Neural TTS enables sonic branding differentiation for consumer packaged goods and financial services. Custom voice commissions convert commoditized text-to-speech into identity assets.
- Machine Learning:Acoustic model training pipelines depend on hyperscale datacenter capacity concentrated in three US and Chinese provider ecosystems.
Speech Recognition captures the dominant investment share; Voice Synthesis climbs the fastest.
End User:
Customer archetypes separate by integration complexity and procurement sophistication.
- Enterprises:Contact center modernization programs drive consumption-based SaaS procurement with CFO scrutiny of recurring spend. Healthcare deployments trigger FDA software-as-medical-device classification when diagnostic claims attach to spoken interactions.
- Individuals:Consumer adoption concentrates in ecosystem-locked smart home hardware with recurring subscription attachment.
- Developers:API-first platforms monetize through per-call pricing for speech-to-text and natural language understanding services.
- Retail:In-store voice commerce implementations remain experimental with limited deployment scale.
Enterprises anchor current revenue; Developers represent the steepest expansion trajectory.
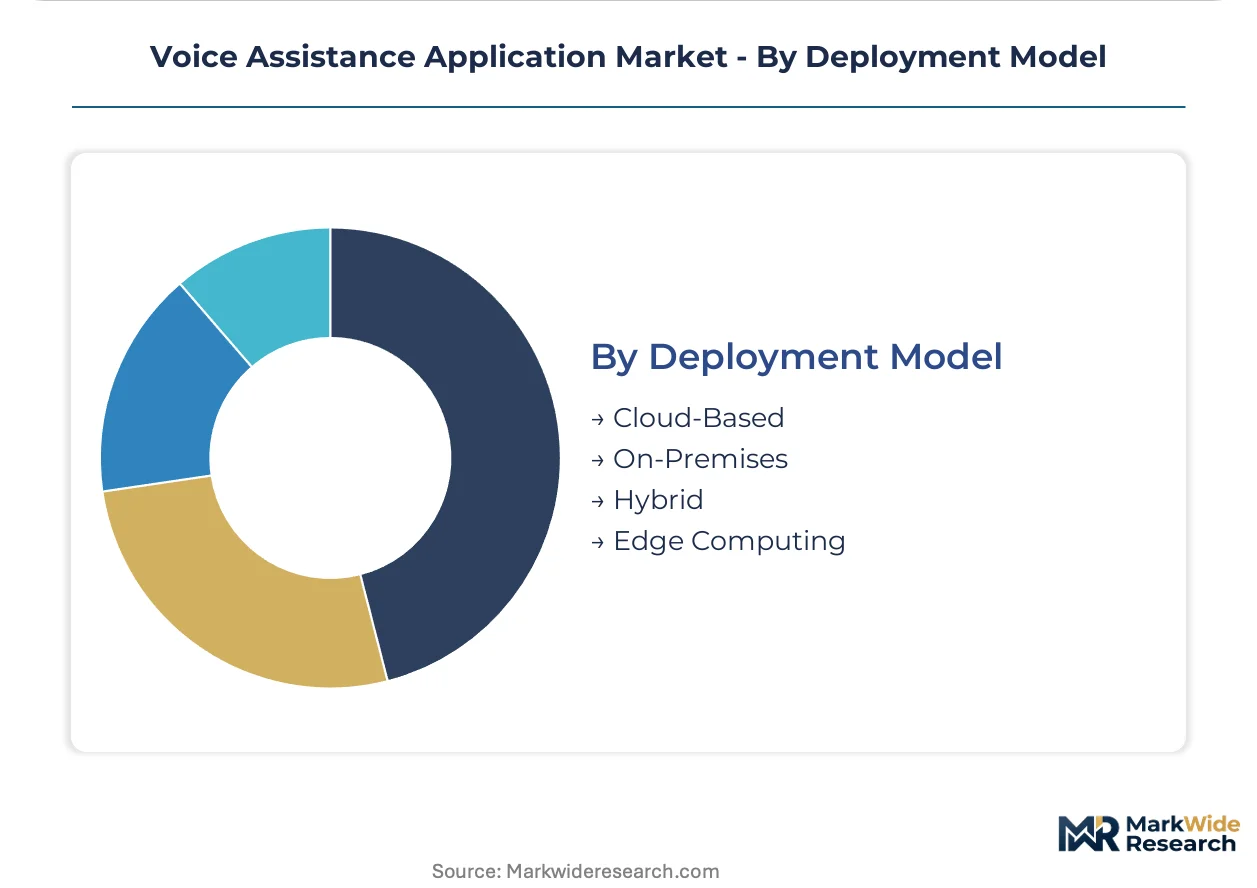
Deployment Model:
Architecture selection reflects latency constraints, data residency requirements, and connectivity reliability.
- Cloud-Based:Dominant margin pool among deployment models with elastic scaling for variable query volumes. Hyperscale concentration creates single-source vulnerability for latency-sensitive applications.
- Edge Computing:On-device neural processing absorbs acoustic inference previously routed to distant datacenters. Automotive Tier-1 suppliers in Germany and Japan qualify NPU-integrated system-on-chips for vehicle programs.
- Hybrid:Wake-word detection runs locally while complex queries traverse cloud APIs. Balances privacy sensitivity with capability depth.
- On-Premises:Financial services and government deployments mandate air-gapped infrastructure for biometric data handling.
Cloud-Based retains volume leadership; Edge Computing gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates voice assistant manufacturing capacity while the United States and Germany dominate enterprise consumption and automotive integration demand. Production of neural processing units and smart speaker hardware clusters in East Asian foundries, whereas software development and premium automotive deployments concentrate in Western technology corridors.
United States
Enterprise contact center modernization and smart home ecosystem penetration drive platform consumption. The FDA regulates voice-enabled diagnostic tools as software-as-medical-device when therapeutic claims attach to spoken interactions. Seattle and San Francisco Bay Area technology corridors host cloud infrastructure hyperscalers that anchor speech-to-text API services for domestic and export markets.
Germany
Premium automotive OEMs mandate sub-200-millisecond voice response latency as standard infotainment specifications. The EU AI Act imposes transparency obligations and human oversight documentation requirements on conversational AI systems operating in European markets. Stuttgart and Munich automotive clusters drive procurement of white-label assistant stacks independent of US and Chinese ecosystem dominance.
China
Domestic smart speaker manufacturing scales under electronics production incentives while intelligent voice services expand across mobile and automotive platforms. SAMR enforces algorithmic recommendation registration provisions on voice services operating domestically. Shenzhen and Beijing technology corridors concentrate NPU-integrated system-on-chip development for edge-native acoustic processing.
India
Multilingual voice platform deployment accelerates across banking and telecommunications customer service infrastructure. The PLI scheme for electronics manufacturing attracts acoustic hardware assembly to tariff-advantaged domestic production zones. Bangalore and Hyderabad technology clusters concentrate Indic language acoustic model development and enterprise SaaS procurement.
Japan
Wearable device integration and automotive Tier-1 supplier partnerships sustain demand for compressed acoustic models in battery-constrained form factors. METI industrial policy supports semiconductor foundry capacity for neural processing unit fabrication. Nagoya and Tokyo metropolitan areas host automotive electronics suppliers qualifying edge-native voice stacks for 2026 vehicle programs.
Voice Assistance Application Market Competitive Landscape
Capital-heavy cloud infrastructure operators compete with asset-light specialized voice platform developers for enterprise and consumer deployment contracts. The market structure concentrates around three hyperscale ecosystems with substantial datacenter capacity, while mid-tier specialists occupy vertical-specific niches requiring localized language support or regulatory compliance documentation. Strategic archetypes separate into ecosystem-locked hardware bundlers, API-first developer platforms, and white-label automotive stack suppliers. Competitive moves center on semiconductor foundry partnerships for NPU integration and consumption-based SaaS pricing unbundling from perpetual licensing.
Within the hyperscale ecosystem tier, Amazon, Google, and Microsoft anchor distinct competitive positions. Amazon leverages its Alexa developer ecosystem to anchor recurring revenue from smart home hardware integrations. Google competes through deep speech-to-text specialization across Android automotive partnerships. Microsoft sustains enterprise-grade differentiation by embedding voice capabilities within Azure cloud productivity suites.
| Leading Market Players |
|---|
| Amazon |
| Apple |
| Microsoft |
| Samsung |
| Baidu |
| IBM |
| Nuance Communications |
| Alibaba |
| Others |
Value Network & Pricing Analysis
Natural language understanding pipeline engineers concentrated in Seattle and San Francisco Bay Area technology corridors command premium compensation packages, compressing margins for mid-tier voice platform developers and widening pricing-tier spreads between hyperscale ecosystems and specialized vendors.
Pricing Analysis
Margin tightening in enterprise SaaS tiers reflects CFO scrutiny of recurring contact center spend across banking and telecommunications verticals. Three-tier pricing structure across premium, standard, and economy levels separates consumption-based API pricing from perpetual licensing with implementation bundling. Price differentiation hinges on latency performance guarantees and EU AI Act compliance documentation. Healthcare deployments exhibit lowest price sensitivity due to FDA software-as-medical-device classification barriers, while smart home hardware buyers drive cost-down pressure through ecosystem-locked subscription bundling.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for neural processing unit fabrication, where foundry capacity constraints throttle automotive Tier-1 qualification timelines. The supply chain draws from Japanese precision components for acoustic sensors, Chinese final assembly for smart speaker hardware, and German automotive electronics integration. Tariff exposure runs through India PLI scheme-dependent acoustic hardware zones. Distribution runs through hyperscale cloud API marketplaces and direct enterprise SaaS procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over NPU-integrated system-on-chip supply separates margin leaders from contract manufacturers.
For Market Incumbents: Deepen semiconductor foundry partnerships for dedicated acoustic inference silicon, securing allocation priority as automotive edge-native demand accelerates. Fortify EU AI Act compliance documentation capabilities to capture Stuttgart and Munich premium OEM procurement independent of US and Chinese ecosystem bundling. Counter emerging white-label automotive stack suppliers through exclusive Tier-1 supplier integration commitments. For New Entrants and Emerging Players: Launch via consumption-based SaaS pricing models targeting India and Brazil banking contact center modernization programs, where CFO scrutiny has unbundled implementation services from core platform fees. Exploit multilingual acoustic model gaps for Indic language coverage, where proprietary corpus collection barriers deter hyperscale investment. Prioritize edge-native wearable implementations with aggressive thermal management solutions for battery-constrained form factors. For Investors and Strategic Acquirers: Re-rating potential sits with specialized voice synthesis studios given sonic branding commission demand from consumer packaged goods and financial services. Long-term viability favors asset-light platforms with vertical integration into NPU supply chains rather than pure software licensing models. Watch automotive Tier-1 supplier qualification announcements for 2026 vehicle programs as inflection indicators for edge-native architecture adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Foundry Partnership | Secures NPU allocation priority for sub-200-millisecond automotive voice stacks. |
| EU AI Act Compliance Certification | Unlocks Stuttgart and Munich premium OEM procurement channels. |
| Indic Language Corpus Development | Captures banking and telecommunications customer service modernization in India. |
| Custom Neural Voice Commissioning | Converts commoditized TTS into differentiated sonic identity assets. |
| Edge-Native Wearable Integration | Addresses thermal management constraints in battery-constrained form factors. |
Research Methodology
Multi-period observation of hyperscaler capex disclosures, automotive Tier-1 supplier qualification timelines, and EU AI Act implementation guidance anchored the trend analysis, supplemented by interviews with conversational AI engineering directors, enterprise contact center procurement officers, automotive platform integration leads, and semiconductor foundry account managers. Secondary validation drew from SEC filings, SAMR algorithmic registration databases, FDA software-as-medical-device classification records, and IHS Markit vehicle production data. Bottom-up segment sizing triangulated against top-down ecosystem revenue attribution.
Input-output matrices modeled deployment architecture shifts across cloud-based, edge-native, and hybrid topologies, with technology stack segmentation capturing natural language processing, speech recognition, voice synthesis, and machine learning investment flows. CAGRs derived from elasticity-adjusted adoption curves across automotive infotainment, smart home hardware, wearable devices, and enterprise customer support verticals. Forecast inputs incorporated NPU integration timelines, EU AI Act documentation burden estimates, and India PLI scheme capacity buildout trajectories.
The model assumes a particular technology adoption path; alternative pathways for on-device neural processing would alter the outlook if thermal management breakthroughs accelerate or cloud latency improvements compress edge-native advantages. Forecasts reflect assumptions about regulatory enforcement consistency, foundry capacity expansion, and multilingual training data availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
AI in Retail Market
Artificial Intelligence (AI)
Explainable AI Market
Artificial Intelligence (AI)
Europe Artificial Intelligence Market
Artificial Intelligence (AI)
Global Call Center AI Market
Artificial Intelligence (AI)
AI in Fashion Market
Artificial Intelligence (AI)
Artificial Intelligence in Business Market
Artificial Intelligence (AI)
Artificial Intelligence Systems Spending Market
Artificial Intelligence (AI)
Decision Intelligence Market
Artificial Intelligence (AI)
Chatbot Market
Artificial Intelligence (AI)
Artificial Intelligence in Supply Chain Management Market
Artificial Intelligence (AI)
United States Conversational AI Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Stadium Market
Artificial Intelligence (AI)
Asia-Pacific Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
AI in Food & Beverages Market
Artificial Intelligence (AI)
Far-Field Speech and Voice Recognition Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Supply Chain Market