
 Automotive Predictive Diagnostic System Market | 2026-2036
Automotive Predictive Diagnostic System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Predictive Diagnostic System Market Outlook
Commercial fleet management is shifting toward predictive uptime models as logistics operators prioritize asset utilization over reactive maintenance schedules. Robert Bosch GmbH leverages embedded sensor networks to anchor its position in powertrain prognostics. Continental AG competes through integrated vehicle health monitoring that spans braking, chassis, and thermal systems. Aptiv specializes in edge-computing architectures that process diagnostic signals locally before cloud transmission.
An automotive predictive diagnostic system comprises sensor arrays, telemetry modules, and algorithmic platforms that analyze operational parameters to forecast component failures before functional degradation occurs. These systems typically process vibration signatures, temperature gradients, and electrical impedance patterns through machine learning models trained on historical failure modes to enable preemptive service scheduling. Cloud Computing delivery modes are capturing expanding margin pools as fleet-scale data aggregation improves algorithm accuracy across vehicle populations. IoT Connectivity infrastructure is maturing fastest in embedded telematics, while Data Analytics capabilities differentiate providers through proprietary training datasets. On-Board Diagnostics products retain the largest installed base but face displacement by integrated engine management platforms that unify prognostic functions.
The US NHTSA mandates event data recorder standards that shape diagnostic data architecture requirements for vehicles sold in the United States. The EU's F-Gas Regulation and CE marking framework influence thermal system monitoring protocols embedded within European predictive diagnostic platforms. Stakeholders must monitor evolving cybersecurity standards from ISO and IEC as connected diagnostic channels become attack vectors requiring hardened authentication and encrypted telemetry pipelines.
Market Dynamics
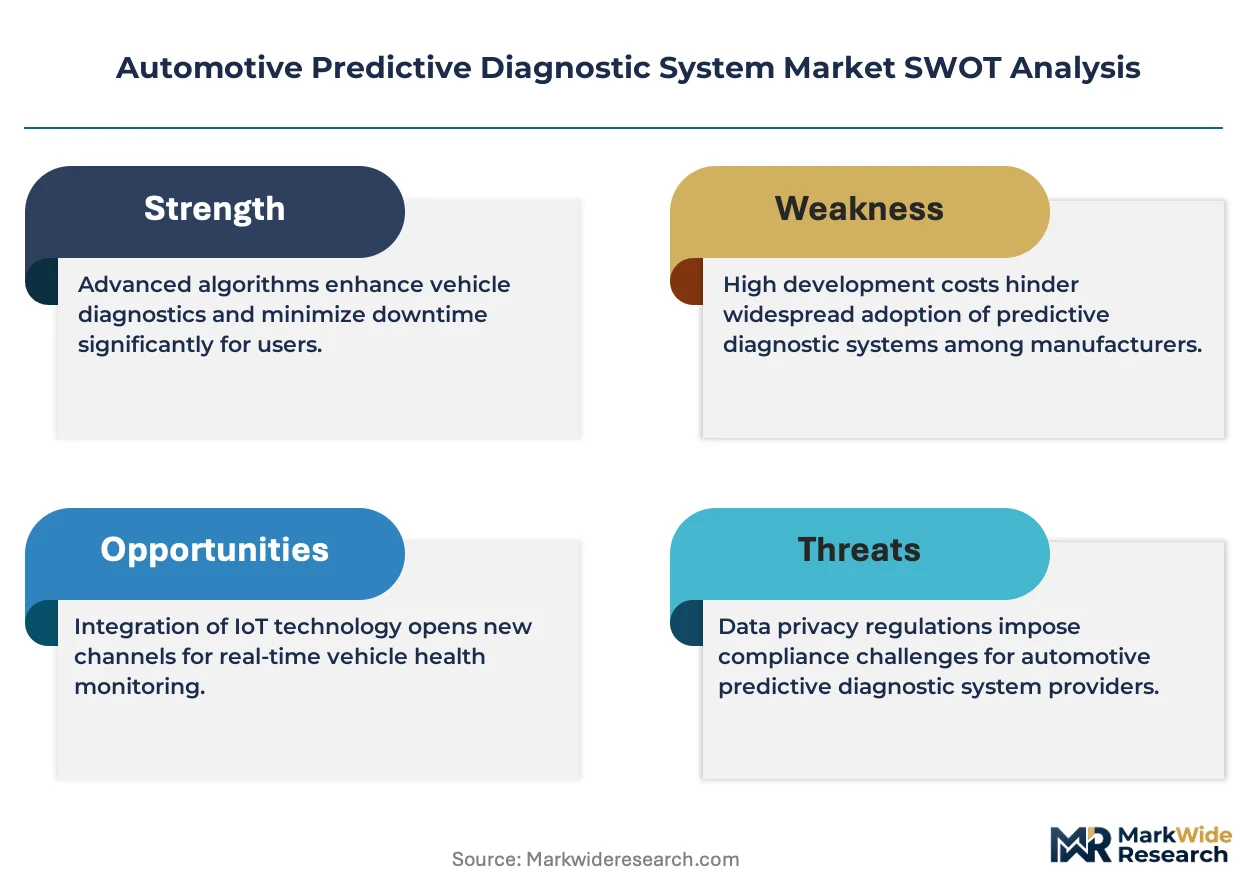
Fleet operators are compressing maintenance cycles from reactive to predictive models, driven by telematics infrastructure maturation and emissions compliance mandates that require real-time powertrain monitoring.
Growth Catalysts
- EU Green Deal emissions protocols:Mandatory carbon tracking for commercial fleets accelerates sensor deployment across engine and exhaust systems.
- Edge computing architectures:Localized diagnostic processing reduces latency for critical failure alerts in long-haul trucking applications.
- German automotive cluster concentration:OEM and Tier-1 supplier co-location in Stuttgart and Munich corridors fast-tracks integrated vehicle health platform development.
Market Restraints
- Semiconductor input volatility:Discrete sensor chip supply concentrates in East Asian foundries, exposing diagnostic module producers to allocation constraints.
- Cybersecurity certification friction:ISO 21434 automotive security standards impose 18-24 month validation timelines for connected diagnostic channels.
- Legacy OBD-II substitution ceiling:Mandated onboard diagnostic ports in US EPA vehicle inspection regimes slow full-platform displacement.
Strategic Opportunities
- India commercial vehicle penetration:Underdeveloped aftermarket diagnostic infrastructure creates first-mover positioning for cloud-native platform providers.
- Battery electric vehicle thermal monitoring:Cell-level temperature prognostics emerge as a distinct application vertical with specialized algorithm requirements.
- US IRA clean fleet incentives:Tax credits for zero-emission commercial vehicles bundle predictive maintenance subscriptions in procurement packages.
Industry Challenges
- Embedded systems engineering talent scarcity:Shortage of firmware developers with automotive safety-critical experience extends product development cycles.
- Multi-protocol integration complexity:Harmonizing CAN, LIN, and Ethernet diagnostic buses with legacy powertrain control modules strains engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Predictive Diagnostic System Market |
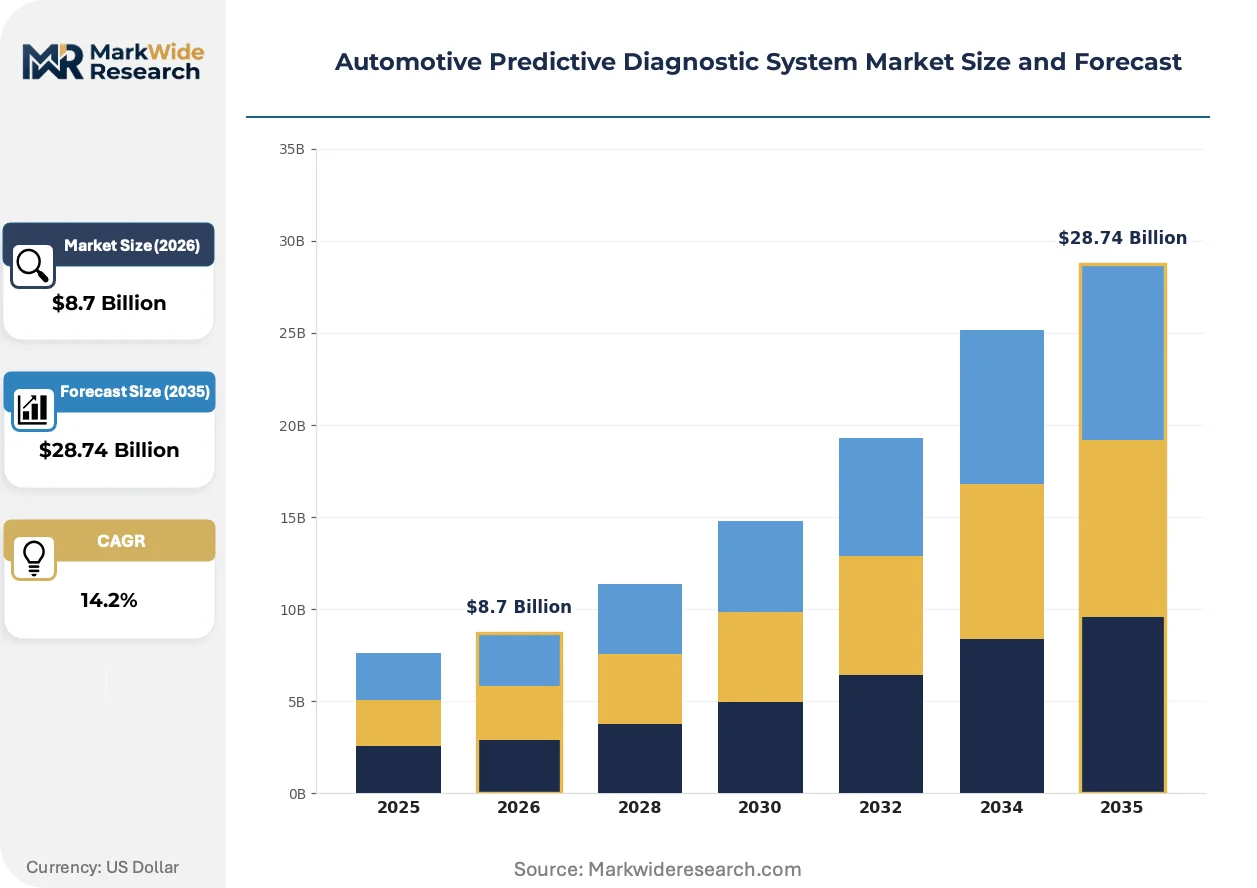
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Board Diagnostics, Engine Management Systems, Tire Pressure Monitoring Systems, Infotainment Systems Technology: Machine Learning, IoT Connectivity, Cloud Computing, Data Analytics End User: OEMs, Aftermarket Providers, Fleet Operators, Vehicle Manufacturers Delivery Mode: Software as a Service, On-Premise Solutions, Mobile Applications, Embedded Systems |
| Companies Covered | Robert Bosch GmbH, Continental AG, Aptiv, ZF Friedrichshafen AG, Valeo, Siemens AG, KPIT Technologies Ltd, Harman International, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Predictive Diagnostic System Market Strategic Shifts
Diagnostic platform architecture is fragmenting from monolithic systems into composable software stacks, enabling tiered service delivery across vehicle lifecycle stages and operator scale segments.
Digital twin technology is modularizing predictive maintenance workflows by creating virtual powertrain replicas that simulate degradation under varied load cycles. Tier-1 suppliers deploy these models for warranty risk assessment. Fleet operators gain component-level visibility without physical teardown, compressing root-cause analysis from weeks to hours.
EU F-Gas Regulation enforcement is tightening thermal system leak detection mandates, forcing refrigerant circuit monitoring integration into climate control prognostics. Compressor failure prediction algorithms now incorporate pressure transducer arrays. Aftermarket service providers in Germany and France retrofit existing fleets to avoid penalty exposure.
Service contract unbundling is fragmenting diagnostic value capture from hardware sales to recurring software licenses. Independent repair chains in the United States subscribe to cloud-based failure prediction APIs rather than investing in captive diagnostic equipment. OEM captive finance arms respond with bundled uptime guarantees that internalize prognostic platform costs.
Automotive Predictive Diagnostic System Market Segmentation
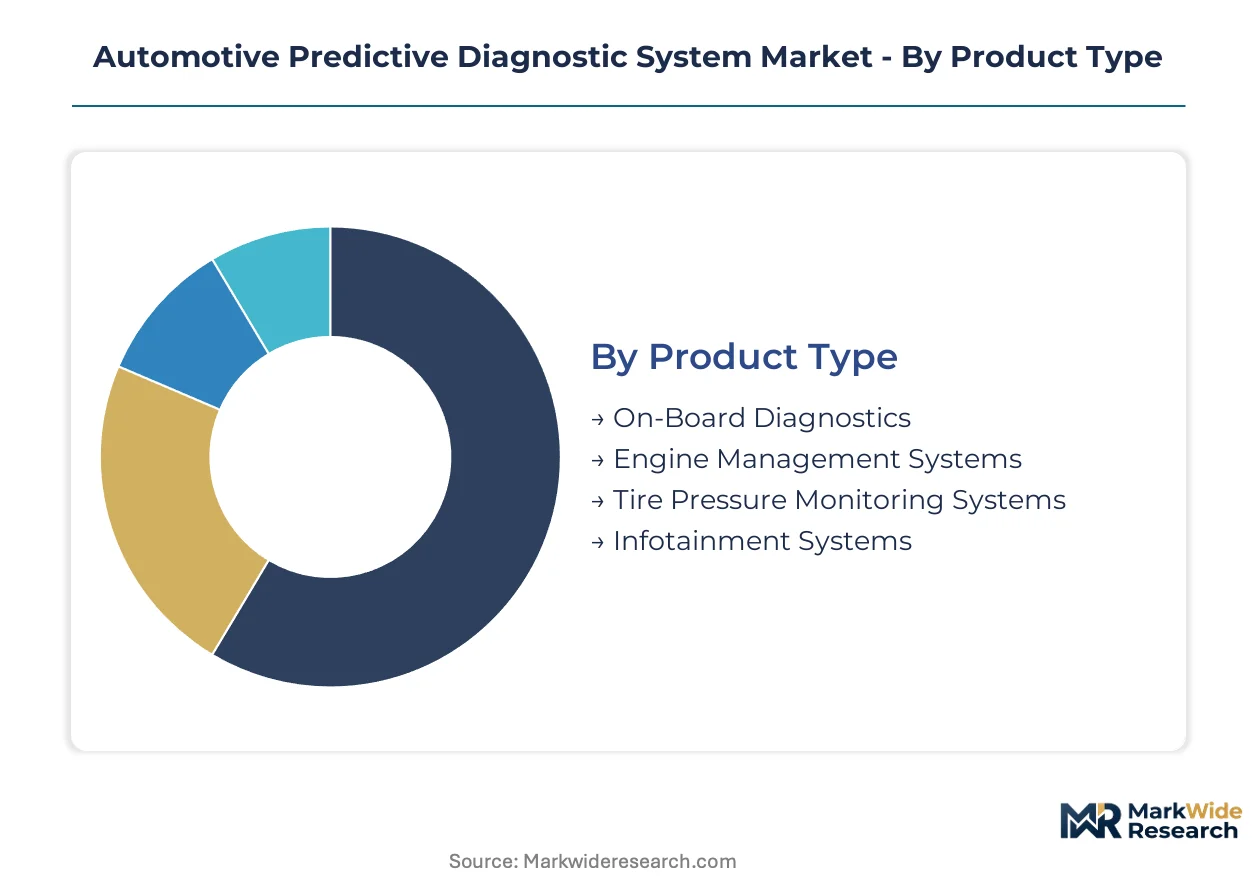
Automotive predictive diagnostic systems fragment across hardware, software, and service layers. Each axis carries distinct margin profiles and technical barriers to entry.
Product Type:
Powertrain integration depth defines competitive positioning across hardware categories.
- On-Board Diagnostics:Self-contained diagnostic ports and processors monitor emissions-related powertrain parameters per EPA and EU regulations. Fleet operators in Germany retrofit legacy commercial vehicles to meet tightening emissions audit requirements. Mature deployment sits with On-Board Diagnostics. Newer deployment is concentrated in Engine Management Systems.
- Engine Management Systems:Unified control modules embed prognostic algorithms directly into powertrain ECUs, processing crankshaft vibration and combustion pressure signatures in real time. Stuttgart-based OEMs prioritize these integrated platforms for next-generation diesel and hydrogen combustion engines.
- Tire Pressure Monitoring Systems:Wheel-mounted sensors transmit temperature and pressure telemetry to central diagnostic gateways.
- Infotainment Systems:Cabin-facing platforms aggregate diagnostic alerts for driver notification and service scheduling.
Hardware margins compress where regulatory mandates standardize specifications. Differentiation shifts toward software stack integration.
Technology:
Algorithm sophistication and data infrastructure maturity separate technology tiers.
- Cloud Computing:Centralized data lakes aggregate fleet-wide failure patterns to refine machine learning model accuracy. Logistics operators in the United States subscribe to cloud-native platforms that cross-train algorithms on multi-vehicle populations. Cloud Computing is gaining share fastest as fleet-scale data aggregation improves predictive precision.
- IoT Connectivity:Embedded telematics modules transmit sensor streams via cellular and satellite networks to remote processing centers. German Tier-1 suppliers dominate cellular V2X integration for commercial vehicle corridors.
- Machine Learning:Supervised and unsupervised models classify vibration, thermal, and electrical signatures against historical failure libraries.
- Data Analytics:Visualization dashboards and anomaly detection tools translate raw telemetry into maintenance recommendations.
Processing location determines latency-critical versus latency-tolerant applications. Edge deployment dominates safety-critical alerts; cloud handles fleet optimization.
End User:
Procurement authority and vehicle lifecycle control shape demand patterns.
- Fleet Operators:Commercial logistics and passenger transport companies purchase predictive maintenance subscriptions to minimize asset downtime and extend powertrain replacement intervals. US-based trucking fleets bundle diagnostic services with vehicle financing through captive OEM arrangements.
- OEMs:Vehicle manufacturers integrate diagnostic capabilities at design phase to enable over-the-air updates and warranty risk management. German automotive groups embed proprietary algorithms across model lineups.
- Aftermarket Providers:Independent service chains and parts distributors retrofit diagnostic hardware to out-of-warranty vehicle populations.
- Vehicle Manufacturers:Assembly plant operators deploy predictive systems for quality control and end-of-line testing.
Direct OEM relationships capture highest lifetime value per vehicle. Aftermarket channels address installed base expansion with lower per-unit economics.
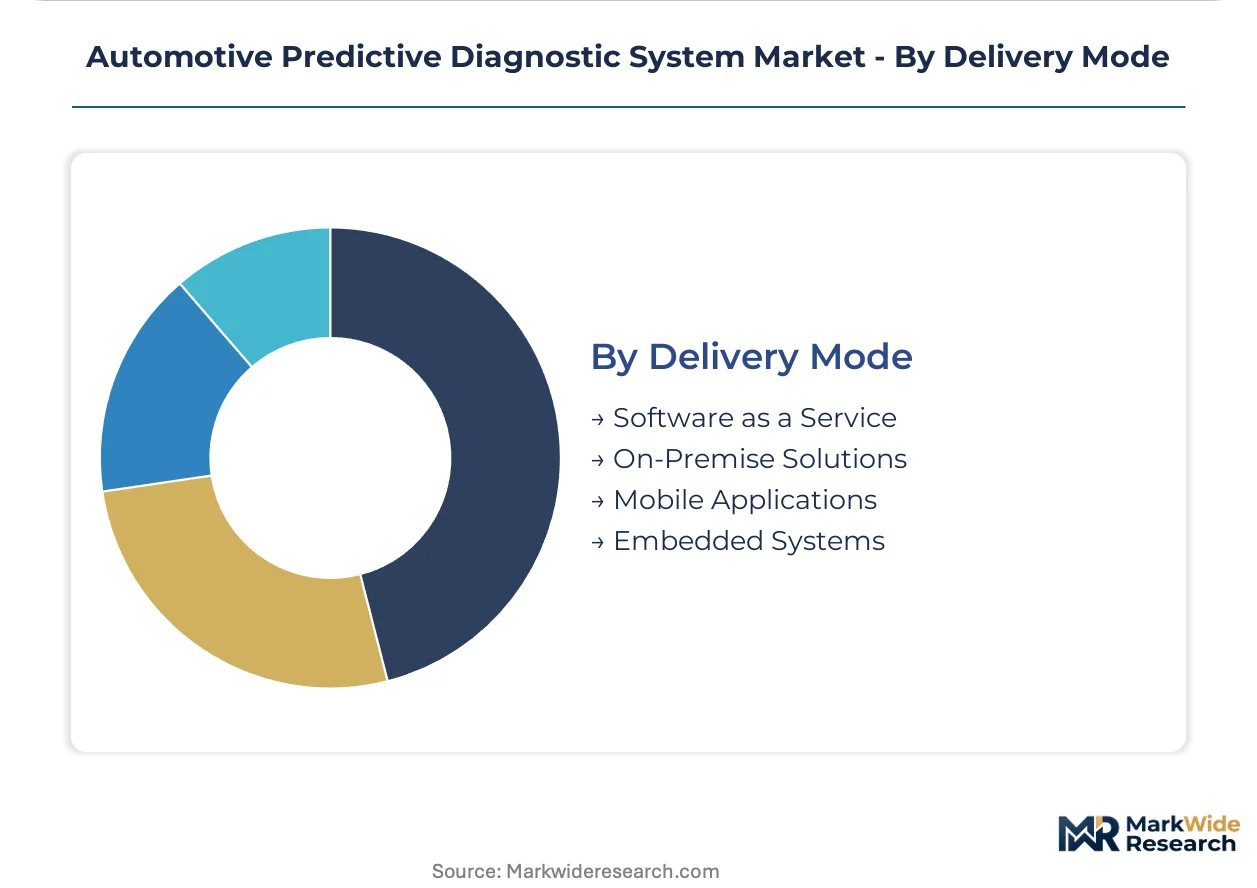
Delivery Mode:
Deployment architecture determines recurring revenue potential versus one-time hardware capture.
- Software as a Service:Subscription-based diagnostic platforms deliver algorithm updates and fleet analytics through browser-based interfaces. French commercial fleet managers favor SaaS models to avoid capital expenditure on captive diagnostic infrastructure.
- Embedded Systems:Factory-installed hardware-software combinations reside permanently within vehicle electronic architectures. Munich-based OEMs specify embedded platforms for premium vehicle segments requiring deterministic failure alerting.
- On-Premise Solutions:Local server installations process diagnostic data within fleet operator IT environments for cybersecurity-sensitive applications.
- Mobile Applications:Smartphone-based interfaces provide driver-facing diagnostic alerts and service scheduling tools.
SaaS and embedded systems command divergent margin structures. Hybrid deployments combining embedded sensors with cloud analytics are expanding across mid-market fleet segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Stuttgart and Munich concentrate German OEM engineering resources. Tax incentives for connected vehicle R&D in Bavaria attract Tier-1 supplier facilities. Industrial policy in China designates intelligent connected vehicles as a strategic emerging industry.
United States
Long-haul trucking fleets in the Midwest and Southeast compress maintenance cycles through telematics subscriptions. The NHTSA mandates event data recorder standards that shape diagnostic data architecture requirements for vehicles sold domestically. Detroit's automotive corridor anchors development of integrated engine management platforms for commercial vehicle applications.
Germany
Commercial fleet operators retrofit legacy vehicles to meet tightening EU Green Deal emissions audit requirements. The KBA enforces type-approval standards for connected diagnostic systems accessing safety-critical vehicle networks. Stuttgart and Munich corridors host co-located OEM and Tier-1 engineering centers that fast-track vehicle health platform development.
China
Domestic EV manufacturers deploy cell-level thermal prognostics across battery electric vehicle lineups. MIIT regulations mandate data security assessments for connected vehicle diagnostic channels transmitting telemetry across borders. The Yangtze River Delta clustering of semiconductor and automotive electronics suppliers supports localized sensor module production.
India
Commercial vehicle fleet operators in Maharashtra and Gujarat adopt cloud-native diagnostic platforms to address aftermarket infrastructure gaps. The PLI scheme for automotive and auto components incentivizes domestic manufacturing of telematics hardware. Chennai and Pune industrial corridors attract foreign Tier-1 suppliers establishing embedded systems engineering centers.
Japan
Precision manufacturing supply chains in Aichi and Kanagawa prefectures specialize in vibration sensor arrays for powertrain prognostics. METI guidelines promote standardization of automotive cybersecurity frameworks for connected diagnostic channels. Nagoya's automotive cluster concentrates development of deterministic edge-computing architectures for safety-critical failure alerting.
Automotive Predictive Diagnostic System Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated system providers capturing premium positions while modular component suppliers serve cost-sensitive fleet retrofit markets. Market structure concentrates around three to five dominant engineering conglomerates with captive automotive electronics divisions, supplemented by specialized software vendors and regional telematics integrators. Strategic archetypes include full-stack platform providers, sensor-hardware specialists, and cloud-native analytics vendors. Capacity expansion in East Asian semiconductor foundries and strategic partnerships between Tier-1 suppliers and cloud infrastructure providers represent the dominant competitive moves.
Within the full-stack platform tier, Robert Bosch GmbH and Continental AG exemplify European engineering conglomerates with integrated automotive electronics portfolios. Aptiv occupies a position among specialized electrical architecture providers with edge-computing capabilities. These three anchors illustrate divergent strategic postures: diversified industrial conglomerates versus focused automotive technology specialists versus software-centric platform vendors.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Aptiv |
| ZF Friedrichshafen AG |
| Valeo |
| Siemens AG |
| KPIT Technologies Ltd |
| Harman International |
| IBM |
| Others |
Value Chain & Pricing Dynamics
Captive sensor fabrication in German and Japanese automotive corridors anchors premium positioning for integrated diagnostic platforms while exposing cost-sensitive fleet retrofit channels to spot-market semiconductor volatility. Tier-1 suppliers with in-house MEMS foundries command pricing power over aftermarket distributors dependent on East Asian chip brokerage.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to cloud-native diagnostic platforms serving US long-haul fleets with compressed deployment windows. Three-tier pricing structure across premium, standard, and economy levels segments by algorithm sophistication and data refresh frequency. Pricing pressure stems from semiconductor spot-market instability forcing hardware module producers to absorb margin compression. Fleet operators in commercial logistics exhibit highest price sensitivity, while OEM captive finance arms internalize prognostic costs through bundled uptime guarantees.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand through Stuttgart and Munich corridor engineering centers, while aftermarket distributors serve fragmented fleet retrofit demand via regional telematics integrators. Sensor module production concentrates in Taiwan, South Korea, and China's Yangtze River Delta. Supply chains draw from silicon wafers, automotive-grade microcontrollers, and cellular modem chipsets. Single-source vulnerability in East Asian foundry capacity creates allocation risk for diagnostic hardware producers. Distribution runs through Tier-1 supplier direct sales for OEM integration and independent service chains for aftermarket penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's emissions monitoring mandates construct a compliance moat that elevates capital requirements for diagnostic platform entrants, favoring incumbent engineering conglomerates with established certification pathways.
For Market Incumbents: Hedge semiconductor supply exposure through multi-foundry qualification programs spanning Taiwan and Japanese fabs. Deepen backward integration into edge-computing silicon design to defend margin position against cloud-native software entrants. Prioritize ISO 21434 cybersecurity certification investment to extend validation timelines as competitive barrier.
For New Entrants and Emerging Players: Battery electric vehicle thermal monitoring algorithms offer technology-first wedge into specialized application vertical with distinct training data requirements. Target India's underdeveloped aftermarket diagnostic infrastructure through cloud-native platform deployment. Pursue white-label partnerships with regional telematics integrators rather than direct OEM sales cycles.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by automotive engineering conglomerates seeking software-defined vehicle capabilities. Long-term viability favors platforms with proprietary training datasets and deterministic edge architectures. Monitor MIIT cross-border data security enforcement as inflection indicator for China market access risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Silicon Design | In-house ASIC development reduces latency for safety-critical failure alerts in German OEM platforms. |
| Cloud-Native Platform Launch | SaaS delivery captures recurring revenue from French fleet operators avoiding capital expenditure. |
| Cybersecurity Certification Investment | ISO 21434 compliance extends product validation timelines as competitive moat against unqualified entrants. |
| India Market Entry Partnership | PLI scheme alignment enables domestic telematics hardware production for Maharashtra commercial fleets. |
| Battery Thermal Monitoring Specialization | Cell-level temperature prognostics address distinct algorithm requirements in China EV lineups. |
Study Parameters
Multi-period observation of fleet telematics adoption rates, regulatory enforcement timelines, and semiconductor allocation patterns anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and fleet operations managers. Secondary validation drew from vehicle production databases, EPA and KBA type-approval filings, EU emissions audit reports, and customs trade records for diagnostic hardware imports. Bottom-up segment sizing triangulated against top-down market aggregation.
Input-output matrices mapped sensor hardware volumes, software subscription renewals, and service contract attach rates across vehicle class, propulsion architecture, and OEM tier dimensions. CAGRs derived from logistic growth curves fitted to historical adoption S-curves and regulatory mandate effective dates. Forecast inputs included fleet operator IT spending surveys and foundry capacity expansion announcements.
Several conditions sit outside the modeled scope, including geopolitical trade restrictions on semiconductor exports, force majeure disruptions to cellular network infrastructure, and unannounced regulatory cybersecurity standard revisions. Forecasts reflect documented assumptions regarding emissions compliance timeline adherence and cloud infrastructure cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Voice Cloning Market
Artificial Intelligence (AI)
Mlops Market
Artificial Intelligence (AI)
AI in Life Sciences Market
Artificial Intelligence (AI)
Asia-Pacific Synthetic Data Generation Market
Artificial Intelligence (AI)
Machine Learning As a Service (Mlaas) Market
Artificial Intelligence (AI)
Artificial Intelligence and Machine Learning Market
Artificial Intelligence (AI)
AI in Food & Beverages Market
Artificial Intelligence (AI)
Global Cognitive Computing Technology Market
Artificial Intelligence (AI)
Latin America Artificial Intelligence Market
Artificial Intelligence (AI)
AI-Ready Enterprise Knowledge Graph Market
Artificial Intelligence (AI)
Semantic Web Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Social Media Market
Artificial Intelligence (AI)
AI Datasets Market
Artificial Intelligence (AI)
AI Image Recognition Market
Artificial Intelligence (AI)
Self-Supervised Learning Market
Artificial Intelligence (AI)
Cognitive Computing Market