
 Adaptive AI Market | 2026-2036
Adaptive AI Market Size, Share, and Industry Trends Forecast 2026-2036
Adaptive AI Market Analytics
Healthcare providers is repositioning as the dominant end-user vertical for adaptive AI systems, displacing earlier retail-centric deployment patterns. NVIDIA Corp. anchors the hardware layer with GPU architectures optimized for real-time model retraining. Microsoft Corp. extends cloud-native adaptive AI services through Azure's machine learning pipelines. IBM Corporation differentiates via enterprise governance tooling that addresses regulatory audit requirements.
Adaptive AI denotes machine learning systems that autonomously modify algorithmic parameters, network architectures, or decision thresholds in response to shifting input distributions without explicit human reprogramming. These systems typically employ continuous feedback loops with inference latencies under 50 milliseconds for edge deployments, enabling dynamic optimization in manufacturing quality control and autonomous vehicle perception. Software dominates current revenue composition, though edge computing represents the fastest-expanding deployment category as latency-sensitive use cases proliferate. Cloud-based solutions sustain margin concentration among hyperscale providers, while hardware specialization intensifies around inference accelerators for federated learning workloads.
The EU AI Act, FDA software-as-medical-device guidance, and China's algorithmic recommendation provisions collectively reshape product certification pathways and cross-border data governance requirements. The EU AI Act's prohibited-practice list and high-risk system obligations directly constrain model architectures for financial institutions and healthcare providers operating in European jurisdictions. Stakeholders must monitor divergence between binding sectoral rules and voluntary technical standards to anticipate compliance cost allocation across the value chain.
Market Dynamics
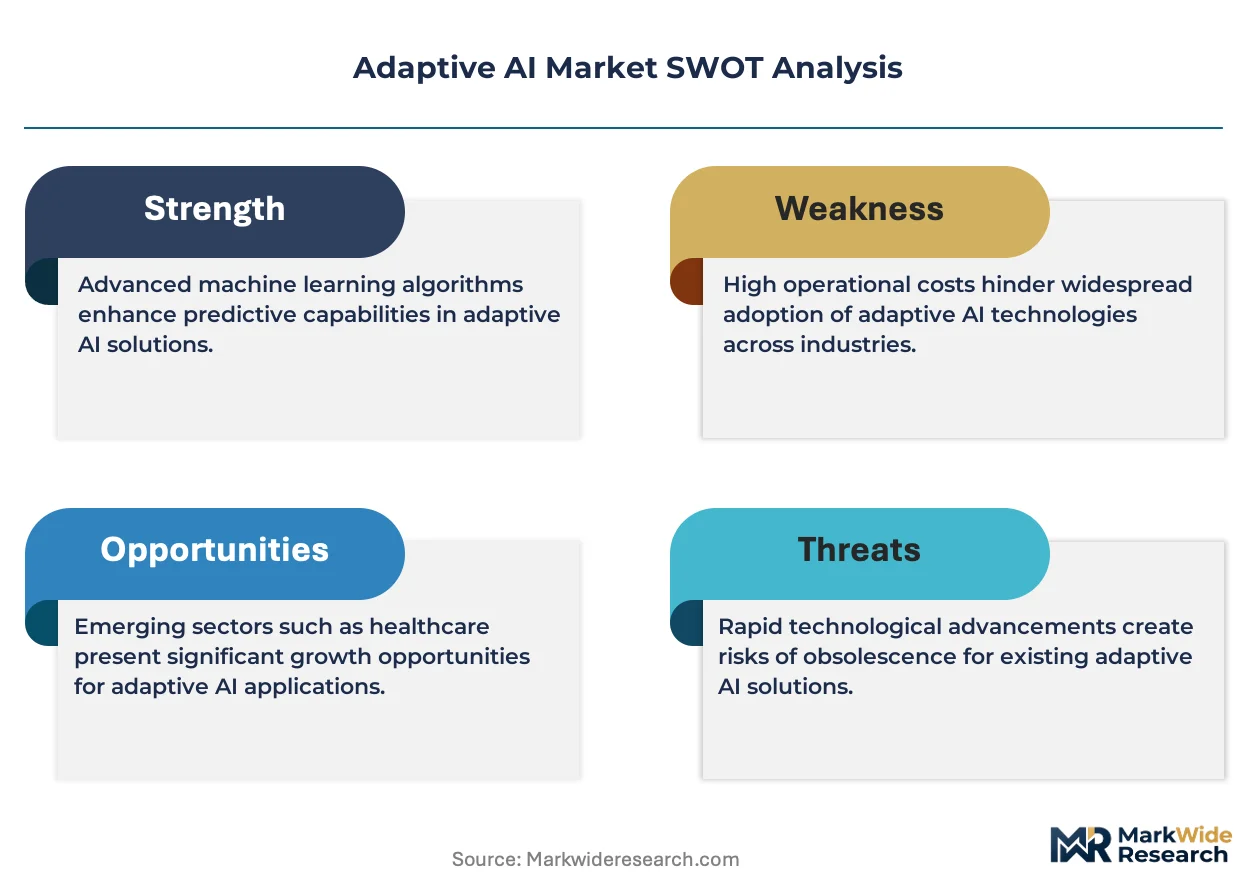
The central structural force reshaping adaptive AI deployment centers on the EU AI Act's risk-based classification system, which mandates algorithmic transparency and human oversight for high-risk applications across healthcare and financial services. This regulatory architecture is forcing vendors to reengineer model architectures and governance tooling ahead of enforcement deadlines.
Growth Catalysts
- FDA Software-as-Medical-Device Guidance:The FDA's evolving framework for adaptive algorithms in diagnostic imaging accelerates hospital procurement of self-updating clinical decision support systems. Healthcare providers gain clearer premarket pathways for continuously learning models.
- Edge Computing Hardware Maturation:Inference accelerators achieving sub-50-millisecond latency enable real-time model retraining on manufacturing floors. Automotive and industrial quality-control deployments expand without cloud dependency.
- United States Federal Procurement Mandates:Defense and civilian agencies now require explainable AI for contract eligibility. This policy pull concentrates vendor development resources on interpretability features and audit-ready documentation.
Market Restraints
- GPU Supply Concentration:NVIDIA's dominance in training-grade silicon creates single-source vulnerability for model development pipelines. Foundry capacity constraints in Taiwan extend lead times for specialized inference chips.
- EU AI Act Compliance Cost Burden:High-risk system obligations impose documentation, human oversight, and conformity assessment requirements that disproportionately burden mid-tier software vendors.
- Algorithmic Explainability Technical Ceiling:Deep neural network opacity limits deployment in regulated domains requiring causal reasoning transparency. This constrains architecture choices for financial credit-scoring applications.
Strategic Opportunities
- Federated Learning in Germany:Strict data localization requirements and industrial data sovereignty norms create demand for distributed training architectures that keep sensitive manufacturing data on-premise.
- India's PLI Scheme for AI Hardware:Production-linked incentives for electronics manufacturing attract assembly investment for edge inference devices serving domestic and export markets.
- Neuromorphic-Analog Convergence:Brain-inspired computing architectures promise orders-of-magnitude efficiency gains for always-on adaptive sensors. Early pilots in battery-constrained IoT deployments validate the approach.
Industry Challenges
- MLOps Talent Scarcity:The intersection of machine learning engineering and production systems administration remains understaffed. Organizations struggle to hire professionals capable of managing continuously deployed adaptive pipelines.
- Cross-Border Data Governance Fragmentation:Divergent requirements between GDPR, China's algorithmic recommendation provisions, and sectoral US privacy laws complicate multi-jurisdictional model training and deployment architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adaptive AI Market |
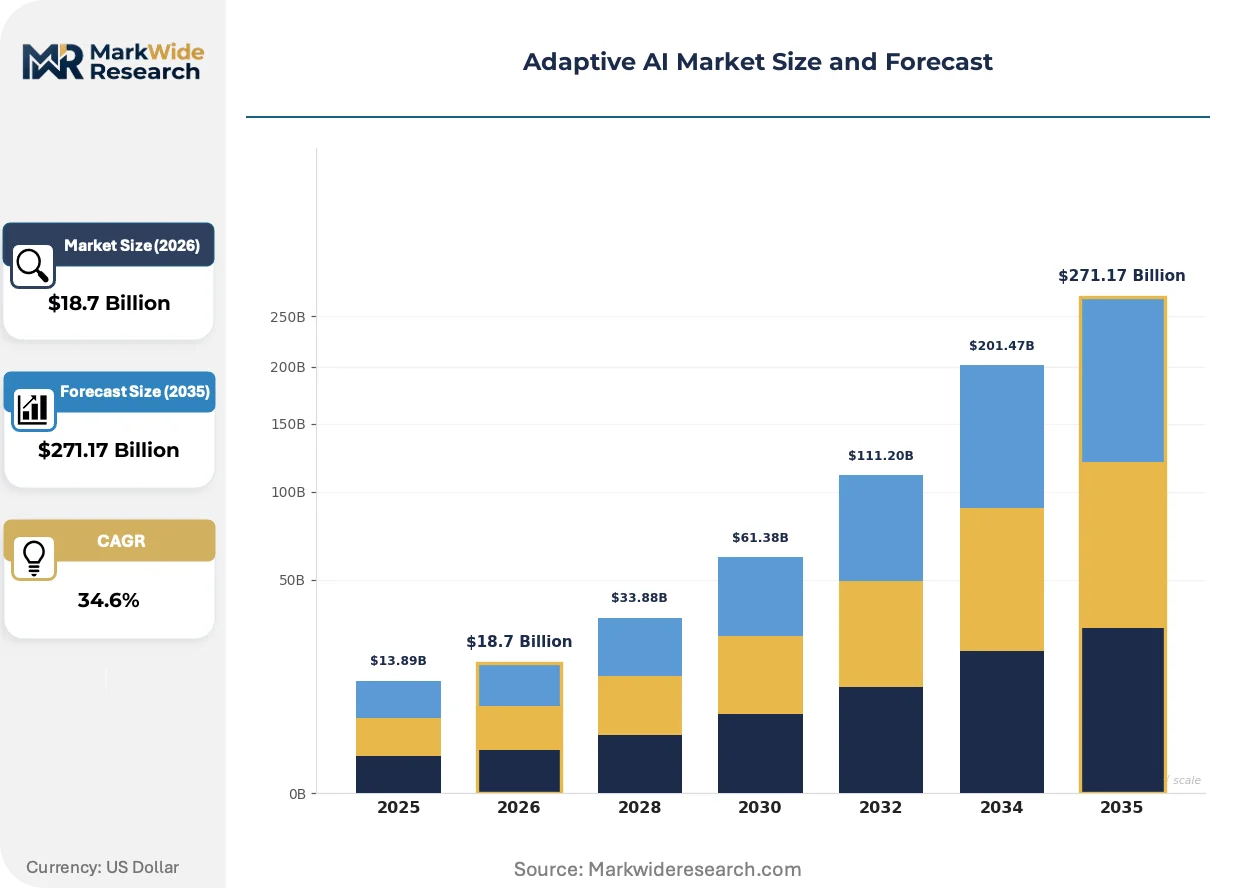
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $271.17 Billion |
| CAGR (2026 – 2036) | 34.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Cloud-based Solutions, Edge Computing End User: Healthcare Providers, Financial Institutions, Retail Chains, Educational Institutes Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-premises Application: Predictive Analytics, Personalization, Automation, Risk Management |
| Companies Covered | LeewayHertz, Suffescom Solutions, Markovate, Risingmax, IBM Corporation, Google LLC, Amazon Web Services, Microsoft Corp., NVIDIA Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adaptive AI Market Evolving Landscape
Adaptive AI markets are undergoing architectural transformation as real-time learning migrates from centralized clouds to distributed edge infrastructure. Three interconnected developments are compressing deployment timelines and reconfiguring vendor competitive positions.
Neuromorphic computing hardware is converging with conventional GPU inference stacks to enable ultra-low-power continuous learning in resource-constrained environments. Industrial sensor manufacturers in Germany and Japan are piloting spiking neural network chips for predictive maintenance applications. This convergence is collapsing the power-performance tradeoff that previously forced a choice between model sophistication and deployment flexibility.
The EU AI Act's high-risk system obligations are mandating human-in-the-loop oversight mechanisms and algorithmic impact assessments for healthcare and credit-scoring deployments. Financial institutions operating across European jurisdictions are restructuring model governance committees and documentation workflows. Banking compliance functions in France and the Netherlands are absorbing the largest organizational adaptation burden as they retrofit existing adaptive credit models.
Hospital procurement departments are unbundling adaptive diagnostic software from bundled equipment service contracts and evaluating standalone algorithm performance through independent validation studies. Radiology departments in the United States and United Kingdom now require prospective clinical trials before contract renewal. This behavioral shift elevates evidence-generation costs for vendors while compressing sales cycles for those with published outcomes data.
Adaptive AI Market Segmentation
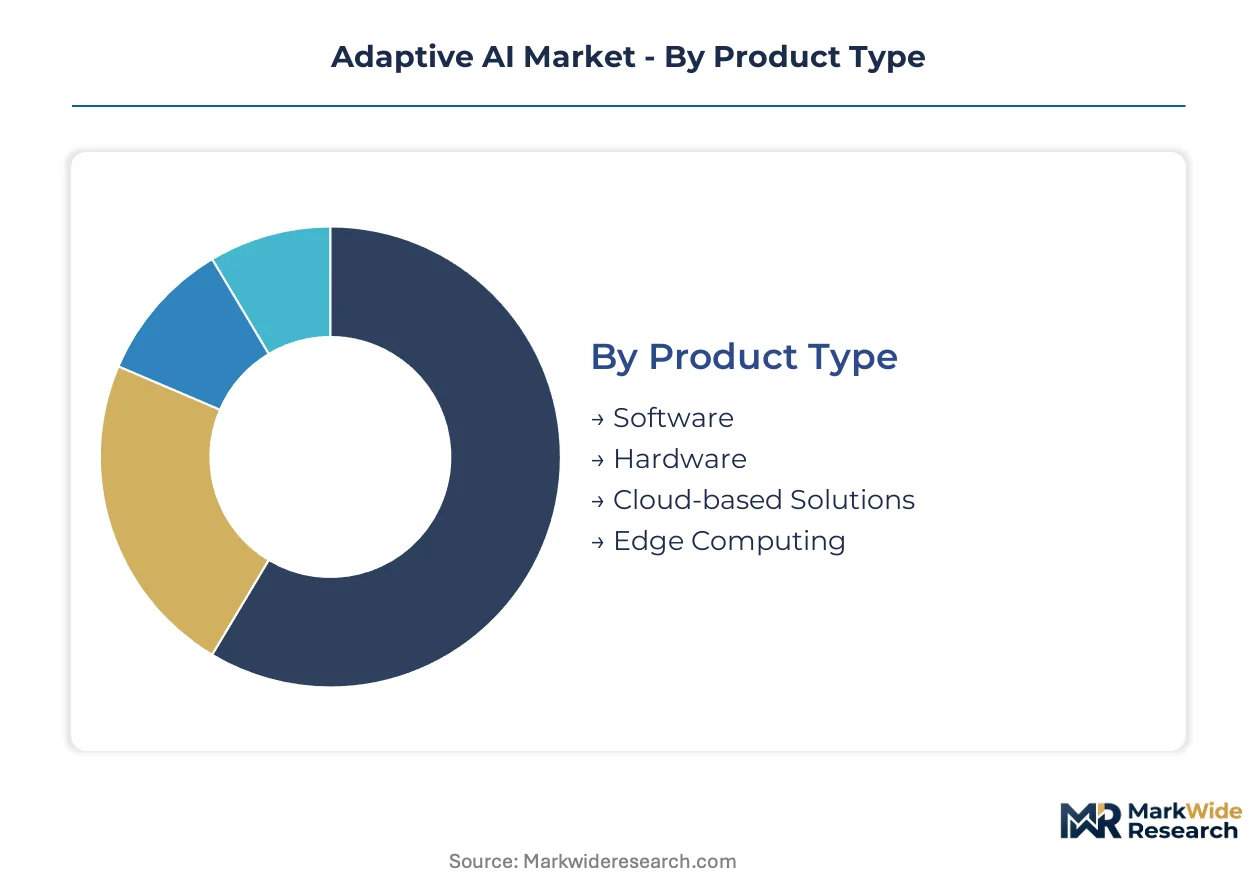
Adaptive AI segmentation reveals how architectural choices determine deployment feasibility across latency-sensitive and regulated environments. Product configuration, end-user requirements, and infrastructure topology collectively shape vendor competitive positioning and margin structures.
Product Type:
Technology architecture defines performance ceilings and cost structures for adaptive system deployment.
- Software:Algorithmic layers enable continuous parameter adjustment and model retraining without hardware dependency. Healthcare providers in the United States and Germany concentrate procurement here, driven by FDA and EU AI Act documentation requirements for clinical decision support systems.
- Hardware:Dedicated inference accelerators achieve sub-50-millisecond latency for real-time adaptive feedback. Demand clusters in Japanese automotive manufacturing and German industrial quality control, where edge autonomy eliminates cloud dependency.
- Cloud-based Solutions:Hyperscale providers host centralized model training and distributed inference APIs.
- Edge Computing:Distributed processing architectures keep sensitive data on-premise while enabling local model updates.
Mature deployment sits with Software. Newer deployment is concentrated in Edge Computing.
End User:
Customer type determines regulatory exposure and procurement sophistication.
- Healthcare Providers:Hospitals and diagnostic networks deploy adaptive imaging algorithms and clinical decision support. United States radiology departments now require prospective validation studies before contract renewal, elevating evidence-generation costs for vendors.
- Financial Institutions:Banks and insurers use adaptive credit scoring and fraud detection. EU AI Act high-risk system obligations force French and Dutch compliance functions to restructure model governance committees and documentation workflows.
- Retail Chains:Dynamic pricing and inventory optimization drive procurement.
- Educational Institutes:Adaptive learning platforms personalize curriculum delivery.
Procurement maturity concentrates with Financial Institutions. Evidence requirements are stiffening fastest for Healthcare Providers.
Deployment Model:
Infrastructure topology shapes data sovereignty compliance and operational control.
- Public Cloud:Shared infrastructure delivers elastic compute for model training at lowest unit cost. United States federal procurement mandates for explainable AI are redirecting some defense and civilian workloads toward audit-ready configurations.
- Private Cloud:Single-tenant environments satisfy data residency requirements. German manufacturing firms favor this model under strict industrial data sovereignty norms, keeping sensitive production data within national boundaries.
- Hybrid Cloud:Split architectures train models centrally while deploying inference at edge nodes.
- On-premises:Fully captive infrastructure eliminates third-party data exposure.
Cost optimization centers on Public Cloud. Control requirements are driving expansion in Private Cloud.
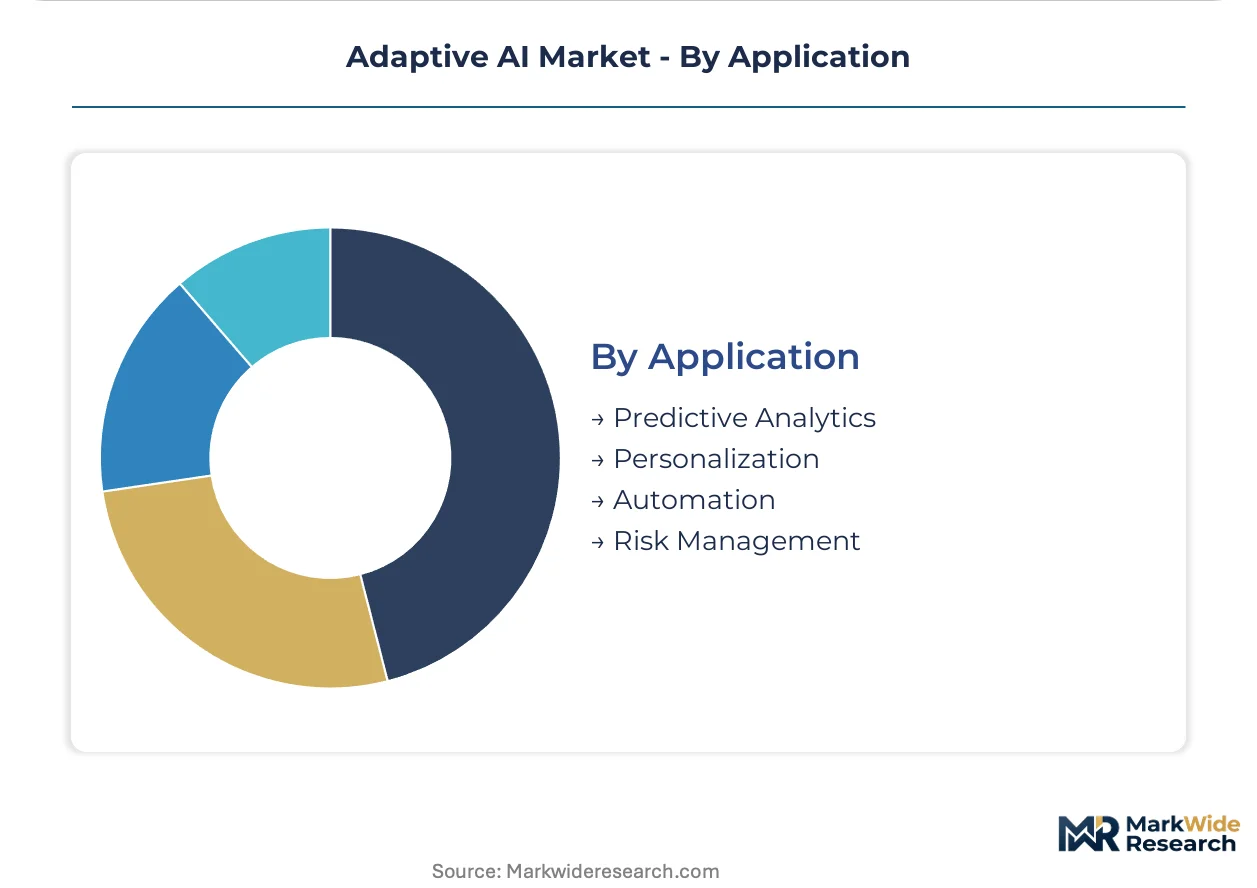
Application:
Use case type determines model complexity requirements and explainability thresholds.
- Predictive Analytics:Forecasting systems anticipate equipment failure and demand fluctuations. Industrial sensor manufacturers in Germany and Japan pilot neuromorphic chips for predictive maintenance, collapsing power-performance tradeoffs.
- Personalization:Real-time content and recommendation adaptation responds to behavioral signals. China's algorithmic recommendation provisions impose disclosure and user control obligations that constrain architecture choices.
- Automation:Self-optimizing process control reduces human intervention.
- Risk Management:Dynamic threat detection and exposure adjustment protects institutional value.
Regulatory scrutiny is deepest for Personalization. Technical innovation is accelerating fastest in Predictive Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's concentration of venture capital and defense procurement contracts anchors North American adaptive AI deployment. Tax incentives under the CHIPS and Science Act accelerate domestic semiconductor fabrication for inference accelerators.
United States
Defense agencies and healthcare systems drive procurement of explainable adaptive systems. The FDA's software-as-medical-device guidance creates premarket pathways for continuously learning diagnostic algorithms. Boston's hospital networks and Washington D.C.'s federal contracting corridor concentrate vendor development resources on audit-ready documentation.
Germany
Industrial manufacturers demand federated learning architectures for predictive maintenance on factory floors. The EU AI Act's high-risk system obligations force restructuring of model governance committees across Frankfurt and Munich banking centers. Stuttgart's automotive cluster pilots neuromorphic chips for real-time quality control.
China
Smart city deployments and algorithmic recommendation platforms scale domestic adaptive AI consumption. The MIIT's algorithmic governance provisions impose disclosure requirements on personalization engines. Shenzhen's hardware ecosystem and Beijing's AI research institutes anchor development of edge inference devices.
India
Production-linked incentives for electronics manufacturing attract assembly investment for adaptive edge devices. The country's data localization norms create demand for on-premise training infrastructure. Bangalore's software services corridor and Gujarat's semiconductor assembly zones concentrate vendor expansion efforts.
United Kingdom
Radiology departments require prospective clinical validation before renewing adaptive diagnostic contracts. The Medicines and Healthcare products Regulatory Agency aligns software guidance with EU AI Act transparency requirements. London's financial compliance functions absorb organizational adaptation burdens for credit-scoring model governance.
Adaptive AI Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hyperscale cloud providers capturing margin concentration in centralized training infrastructure while hardware specialists dominate edge deployment. The vendor landscape organizes around three strategic archetypes: cloud-native platform operators, semiconductor fabricators with inference-optimized architectures, and enterprise governance tooling specialists. Capacity expansion in Taiwanese foundries and strategic partnerships between software vendors and hospital procurement departments represent the dominant competitive moves reshaping positioning.
Within the enterprise governance tier, IBM Corporation exemplifies the compliance-focused archetype addressing regulatory audit requirements. NVIDIA Corp. anchors the hardware layer with GPU architectures optimized for real-time model retraining. Microsoft Corp. occupies a central position in cloud-native adaptive AI services through machine learning pipeline integration. These three entities represent distinct strategic vectors rather than direct substitutes, with each anchoring a separate value chain layer.
| Leading Market Players |
|---|
| LeewayHertz |
| Suffescom Solutions |
| Markovate |
| Risingmax |
| IBM Corporation |
| Google LLC |
| Amazon Web Services |
| Microsoft Corp. |
| NVIDIA Corp. |
| Others |
Value Network & Pricing Analysis
Machine learning engineering talent concentration in the San Francisco Bay Area and Bangalore drives labor-cost differentials that widen pricing-tier spreads between premium consulting-led deployments and economy self-service platforms.
Pricing Analysis
Premium pricing attaches to sub-90-day implementation timelines for FDA-validated clinical decision support systems, while spot inventory of pre-trained edge models trades at discounts. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with EU AI Act conformity assessment adding margin to high-risk system tiers. Cost compression in economy SaaS tiers intensifies because hyperscale providers subsidize customer acquisition. Healthcare procurement committees exhibit lowest price sensitivity due to liability exposure, whereas retail chains negotiate aggressively on per-inference fees.
Supply Chain Analysis
Single-source vulnerability sits with NVIDIA for training-grade GPU silicon, exposing model development pipelines to foundry capacity constraints. Hardware supply concentrates in Taiwan, South Korea, and the United States for advanced inference accelerators. Raw material dependencies include high-bandwidth memory modules, specialized substrates, and rare earth elements for magnetic components. Tariff exposure on Chinese-assembled edge devices is forcing relocation of final assembly to Vietnam and Mexico. Distribution runs through direct hyperscale marketplaces for cloud instances and regional systems integrators for on-premise deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU AI Act compliance costs force mid-tier vendors toward strategic exits or acquisition.
For Market Incumbents: Anticipate margin compression from hyperscale bundling of adaptive AI APIs into productivity suites. Defend position by deepening backward integration into custom inference silicon and securing hospital system partnerships with prospective clinical validation commitments. Certification investment in EU AI Act high-risk system documentation creates switching costs against emerging entrants. For New Entrants and Emerging Players: The price-point gap between premium enterprise governance tooling and economy API access opens white-space in mid-market manufacturing quality control. Target German industrial sensor networks with federated learning architectures that satisfy data sovereignty norms. Go-to-market leverage rests on pre-integrated MLOps templates reducing deployment timelines. For Investors and Strategic Acquirers: The window for entry favors compliance-technology specialists with EU AI Act audit tooling. Long-term viability centers on vendors bridging explainability gaps for financial credit-scoring applications. Acquisition target archetype: mid-cap software vendors with hospital procurement relationships and pending FDA submissions. Signal to watch: divergence between binding sectoral enforcement and voluntary technical standards adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | EU AI Act conformity assessment opens procurement pathways for French and Dutch banking centers. |
| Edge Hardware Partnership | Neuromorphic chip collaboration with Stuttgart automotive cluster collapses power-performance tradeoffs. |
| Hospital System Validation Study | Prospective clinical trials satisfy United States radiology department renewal requirements. |
| Federated Learning Platform Launch | On-premise training architecture addresses German industrial data sovereignty norms. |
| Strategic Acquisition of MLOps Specialist | Talent scarcity in production pipeline management creates defensive moat against hyperscale encroachment. |
Research Methodology
Document review covered SEC filings from hyperscale providers, FDA software-as-medical-device guidance documents, and EU AI Act implementing acts, complemented by interviews with chief technology officers at hospital networks, procurement leads at German automotive manufacturers, and regulatory affairs directors at financial institutions. Secondary validation drew from hyperscaler capex disclosures, hospital procurement databases, and GPO contracts. Bottom-up deployment estimates triangulated against top-down market sizing from cloud infrastructure spend allocations.
Cross-referencing historical adoption curves with panel input from platform engineering leaders shaped the analytical framework across the analysis window. Segmentation dimensions modeled include deployment topology, end-user vertical regulatory exposure, and inference latency requirements. CAGRs were derived from elasticity-adjusted spend trajectories. Industry-specific inputs incorporated FDA premarket submission timelines and EU AI Act enforcement phase transitions.
Inputs from hospital procurement committees and federal contracting officers were available through the study window; gaps in real-time edge deployment metrics introduce uncertainty bands around manufacturing quality control estimates. Deviation in EU AI Act enforcement stringency or GPU foundry capacity allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
AI Mirror Market
Artificial Intelligence (AI)
CLV and Churn Prediction AI Market
Artificial Intelligence (AI)
Industrial AI Software Market
Artificial Intelligence (AI)
Asia-Pacific Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
Model Validation and Automation Market
Artificial Intelligence (AI)
Conversation Intelligence Software Market
Artificial Intelligence (AI)
Global Artificial Intelligence-Emotion Recognition Market
Artificial Intelligence (AI)
Global AI in Social Media Market
Artificial Intelligence (AI)
AI Voice Cloning Market
Artificial Intelligence (AI)
Europe Generative AI Market
Artificial Intelligence (AI)
Cognitive Services Platform Market
Artificial Intelligence (AI)
Enterprise LLM Market
Artificial Intelligence (AI)
MENA Artificial Intelligence Market
Artificial Intelligence (AI)
AI in Life Sciences Market
Artificial Intelligence (AI)
Global Cognitive Automation Market
Artificial Intelligence (AI)
Neural Network Market