
 Intelligent Virtual Assistant Market | 2026-2036
Intelligent Virtual Assistant Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Virtual Assistant Market Analysis
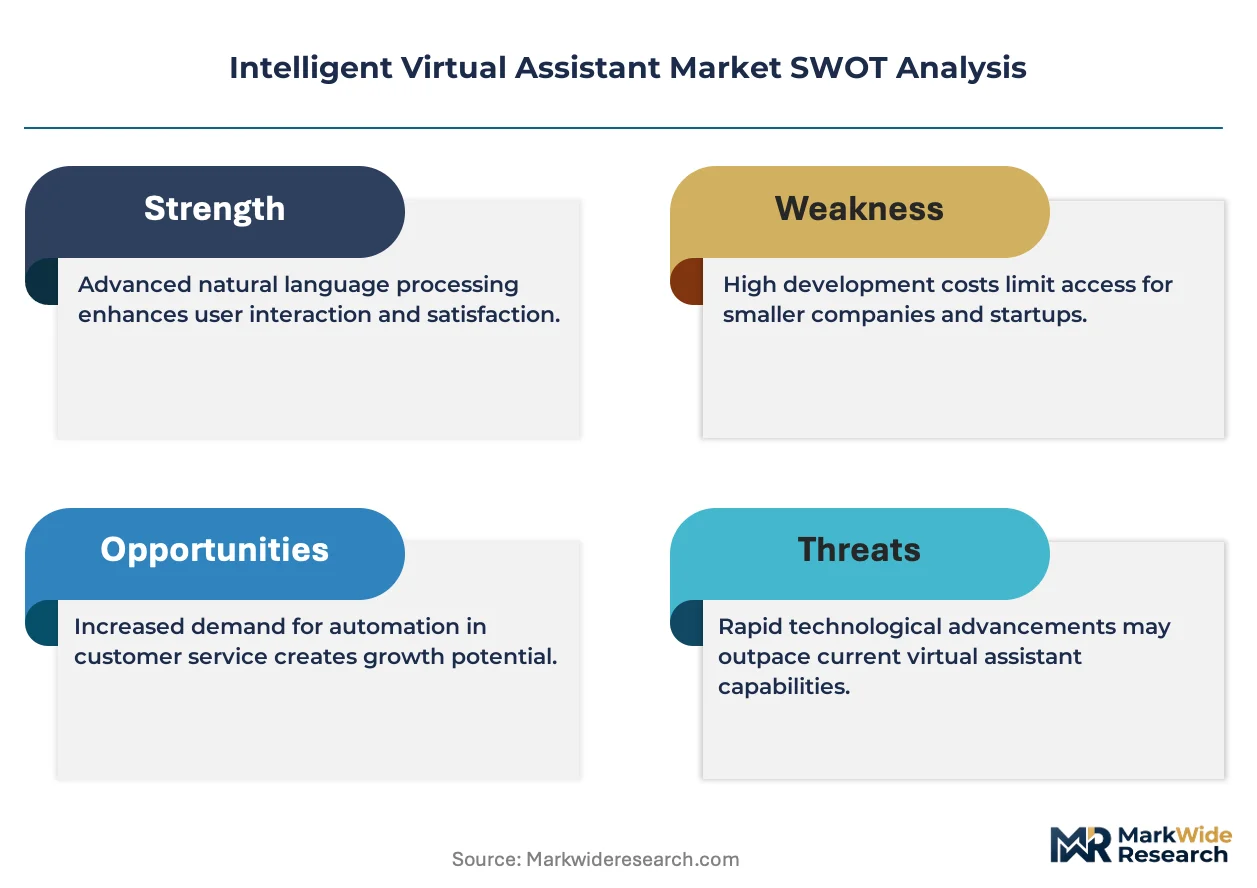
Platform bundling of conversational AI with existing enterprise software suites is hardening buyer expectations for seamless integration. Microsoft Copilot leverages its Office 365 ecosystem to embed assistant capabilities directly into workflow tools. Google Gemini competes through deep integration with cloud infrastructure and search capabilities. IBM watsonx Assistant differentiates via industry-specific compliance modules for regulated sectors.
An intelligent virtual assistant is a software agent that interprets natural language inputs through natural language processing and machine learning algorithms, then generates contextual responses via speech recognition and text-to-speech synthesis to automate human-computer interaction. Its primary commercial purpose is reducing operational labor in high-volume inquiry environments while maintaining conversational fidelity. Customer support deployments occupy the largest revenue pool as enterprises deflect repetitive tickets, though health monitoring represents the fastest structural expansion as remote patient engagement protocols mature. Cloud-based delivery dominates technology spending, while hybrid architectures capture margin premiums from financial services buyers with data residency requirements.
The EU AI Act and GDPR impose transparency and data minimization obligations on virtual assistant deployments processing personal information in European jurisdictions. The FDA exercises oversight of clinical decision-support assistants in the United States, requiring validation of health monitoring outputs. China's SAMR and MIIT enforce algorithmic accountability standards for consumer-facing AI services. Stakeholders must monitor evolving liability frameworks for autonomous agent actions as regulatory divergence between jurisdictions complicates cross-border product standardization.
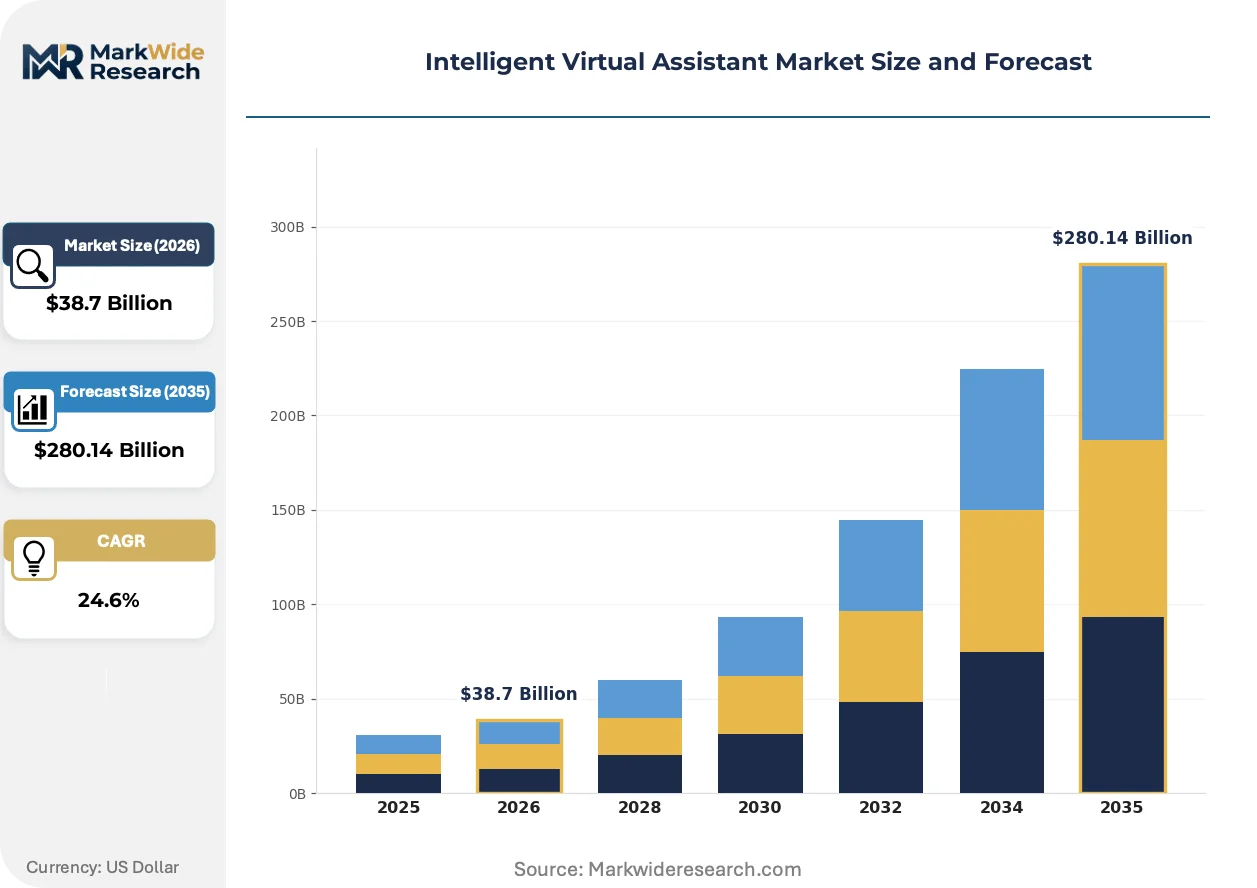
Market Dynamics
Platform bundling by Microsoft, Google, and IBM is compressing standalone virtual assistant margins while elevating buyer expectations for native integration with productivity suites.
Growth Catalysts
- EU AI Act compliance mandates:Healthcare and financial services enterprises across Germany, France, and Italy must deploy auditable conversational AI systems, accelerating procurement of assistants with built-in transparency logging.
- Remote patient monitoring protocols:Post-pandemic care models in the United States require scalable patient engagement infrastructure, driving hospital system adoption of voice-enabled triage and medication adherence tools.
- Large language model cost curves:Inference expenses for transformer-based dialogue systems have fallen substantially, enabling mid-market enterprises to deploy enterprise-grade assistants previously accessible only to technology majors.
Market Restraints
- GPU supply concentration:Training and inference workloads for sophisticated assistants depend on semiconductor fabrication capacity concentrated in Taiwan and South Korea, creating input cost volatility and procurement delays.
- GDPR data minimization requirements:European deployments face structural constraints on conversation logging and model retraining, increasing compliance engineering overhead relative to other jurisdictions.
- Human agent substitution limits:Complex emotional interactions and escalated complaints resist full automation, capping deflection rates and extending payback periods for high-touch implementations.
Strategic Opportunities
- India's digital public infrastructure:The country's unified payments interface and health stack create integration-ready environments for voice-first banking and telemedicine assistants targeting 1.4 billion potential users.
- FDA 510(k) pathway for clinical decision support:Validated diagnostic assistants command premium pricing in the United States, with reimbursement tailwinds from Medicare Advantage plans seeking remote monitoring efficiencies.
- Multimodal convergence:Synthesis of speech recognition, computer vision, and biometric sensing enables ambient intelligence in automotive and smart home environments, opening device-embedded revenue streams beyond cloud subscriptions.
Industry Challenges
- Conversational AI engineering talent scarcity:Demand for prompt engineering, RLHF specialists, and dialogue systems architects exceeds supply, inflating compensation and slowing deployment timelines for complex vertical implementations.
- Legacy CRM integration complexity:Enterprise buyers operate fragmented customer data platforms across Salesforce, ServiceNow, and custom databases, requiring expensive middleware development for seamless assistant handoffs.
- ISO/IEC 42001 certification timelines:AI management system audits for enterprise procurement eligibility extend 12-18 months, delaying revenue recognition for vendors targeting regulated buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Virtual Assistant Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $280.14 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Customer Support, Personal Assistant, E-commerce, Health Monitoring Technology: Natural Language Processing, Machine Learning, Speech Recognition, Text-to-Speech End User: Small Businesses, Large Enterprises, Healthcare Providers, Retailers Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | ChatGPT, Conversica, Microsoft Copilot, Jasper, Otter.ai, Google Gemini, Lindy, Gong, IBM watsonx Assistant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Virtual Assistant Market Emerging Trajectories
Foundation model architectures are compressing development cycles for specialized assistants while regulatory pressure and buyer sophistication reshape competitive differentiation.
Retrieval-augmented generation is unifying proprietary enterprise knowledge bases with large language model fluency. Healthcare providers in the United States are adopting RAG-enabled assistants at accelerating pace to surface clinical guidelines without hallucination risk. This architecture is unifying previously siloed document management and patient interaction systems into single conversational interfaces.
The EU AI Act's risk classification framework imposes conformity assessment obligations on high-risk virtual assistant deployments in credit scoring and employment contexts. European enterprises must maintain technical documentation and human oversight protocols, increasing vendor compliance burdens. Financial services buyers in Germany and the Netherlands are prioritizing providers with pre-certified quality management systems to accelerate procurement.
Subscription fatigue among mid-market enterprises is compressing willingness-to-pay for standalone assistant licenses. Buyers increasingly demand consumption-based pricing tied to resolved inquiries rather than seat-based models. This preference shift is most visible in the United States, where CFO scrutiny of SaaS sprawl favors platform-embedded solutions over point products.
Intelligent Virtual Assistant Market Segmentation
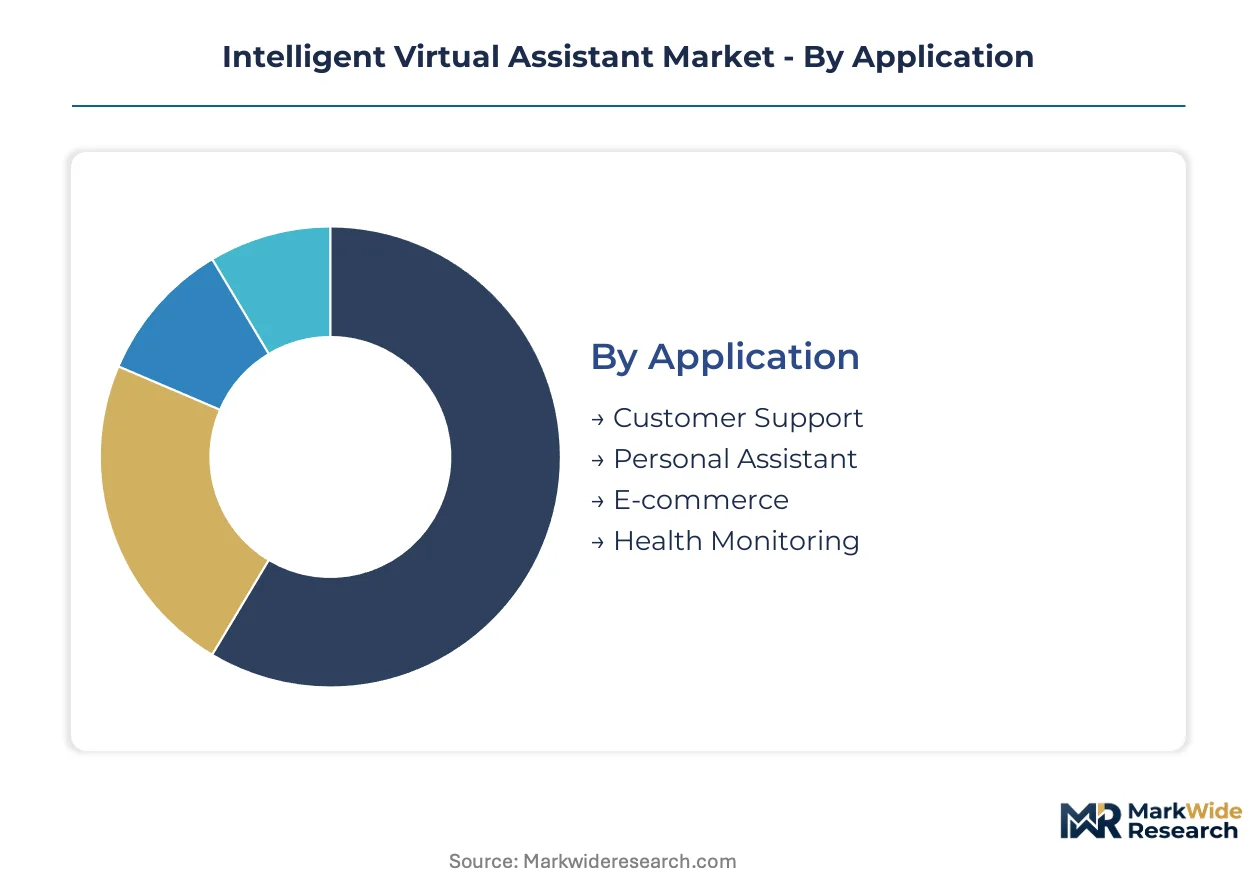
Segmentation in the intelligent virtual assistant market reveals how deployment constraints, regulatory boundaries, and workflow integration requirements fragment buyer priorities. Understanding these axes enables vendors to align engineering roadmaps with procurement patterns across regulated and unregulated environments.
Application:
Natural language processing capabilities determine which use cases achieve production-grade reliability versus experimental deployment.
- Customer Support:Ticket deflection systems automate repetitive inquiry handling through intent classification and scripted response generation. Enterprise contact centers in the United States prioritize these deployments to reduce labor costs in high-volume environments, though escalation protocols to human agents remain mandatory for complex complaints.
- Health Monitoring:Voice-enabled triage and medication adherence tools integrate with electronic health records for remote patient engagement. Hospital systems across Germany, France, and Italy are accelerating procurement under EU AI Act compliance mandates for auditable clinical decision support.
- Personal Assistant:Consumer-facing scheduling and information retrieval applications compete through smartphone ecosystem integration.
- E-commerce:Product discovery and transaction completion assistants reduce cart abandonment through conversational guided selling.
Customer Support leads on scale; Health Monitoring leads on momentum.
Technology:
Computational requirements and data residency constraints shape which technology layers capture investment versus remain commoditized infrastructure.
- Natural Language Processing:Transformer-based architectures power intent recognition and entity extraction for enterprise dialogue systems. GDPR data minimization requirements in European deployments constrain conversation logging and model retraining, increasing compliance engineering overhead relative to other jurisdictions.
- Machine Learning:Reinforcement learning from human feedback refines response quality through iterative preference optimization. Mid-market enterprises in the United States are deploying enterprise-grade assistants as inference cost curves for large language models compress previously inaccessible capabilities into reachable budgets.
- Speech Recognition:Acoustic modeling converts voice inputs to structured text for hands-free interaction workflows.
- Text-to-Speech:Neural vocoders generate naturalistic audio responses for multimodal assistant interfaces.
Natural Language Processing dominates current spending; Machine Learning is climbing the fastest as foundation model adoption accelerates.
End User:
Procurement sophistication and integration complexity create distinct vendor selection criteria across organizational scale and sector.
- Large Enterprises:Multi-department deployments demand SSO integration, audit logging, and custom knowledge base ingestion. Financial services buyers in Germany and the Netherlands prioritize providers with pre-certified ISO/IEC 42001 quality management systems to accelerate procurement under EU AI Act timelines.
- Healthcare Providers:Clinical environments require FDA-validated outputs for diagnostic support and HIPAA-compliant data handling. Medicare Advantage plans in the United States are driving reimbursement tailwinds for remote monitoring efficiencies through validated 510(k) pathway assistants.
- Small Businesses:Limited IT staff favor turnkey cloud solutions with minimal configuration requirements.
- Retailers:Seasonal demand volatility favors consumption-based pricing models over fixed licensing.
Large Enterprises command the deepest integration budgets; Healthcare Providers are gaining share fastest as post-pandemic care models mature.
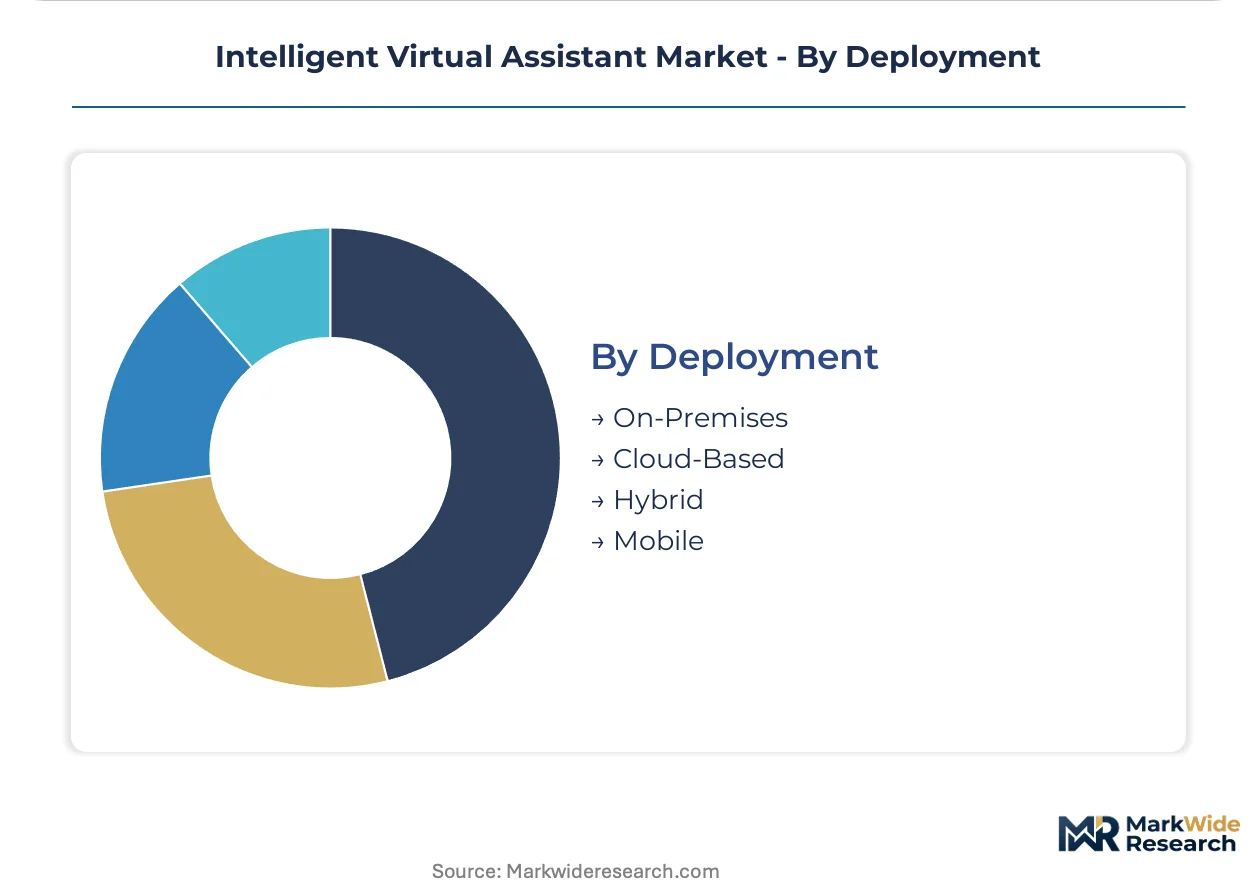
Deployment:
Data sovereignty requirements and latency sensitivity partition infrastructure choices across regulatory jurisdictions and use case criticality.
- Cloud-Based:Scalable API consumption dominates technology spending through managed service offerings. India's digital public infrastructure creates integration-ready environments for voice-first assistants targeting 1.4 billion potential users through unified payments interface connectivity.
- Hybrid:Split architectures process sensitive data on-premises while leveraging cloud inference for non-critical workloads. Financial services buyers with data residency requirements capture margin premiums for architectures satisfying national regulator mandates.
- On-Premises:Air-gapped installations serve classified government and defense environments with zero external connectivity.
- Mobile:Edge-deployed models enable offline functionality for automotive and field service applications.
Cloud-Based leads on scale; Hybrid is expanding most quickly as regulatory fragmentation deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The intelligent virtual assistant industry traces its commercial origins to the United States, where early consumer voice platforms and enterprise software ecosystems established the technical and business models now diffusing worldwide. This historical foundation shapes current geographic deployment patterns.
United States
Hospital systems deploy voice-enabled triage tools for remote patient monitoring under Medicare Advantage reimbursement protocols. FDA oversight of clinical decision-support assistants mandates validation for diagnostic outputs. Boston's health technology corridor hosts concentrated development of HIPAA-compliant conversational AI for provider workflows.
Germany
Financial services enterprises in Frankfurt and Munich procure auditable conversational AI systems to satisfy EU AI Act transparency requirements. BSI and KBA regulators enforce algorithmic accountability standards for automated credit and employment decisions. The Rhine-Main metropolitan region anchors compliance-focused assistant development for regulated European sectors.
India
Voice-first banking assistants integrate with the unified payments interface to reach 1.4 billion potential users across tier-2 and tier-3 cities. RBI guidelines govern data localization for financial AI deployments. Bengaluru's technology corridor concentrates engineering talent for multilingual natural language processing at scale.
China
Consumer-facing AI services face SAMR and MIIT algorithmic accountability enforcement for recommendation and conversational systems. Cloud infrastructure providers embed assistants within super-app ecosystems for commerce and mobility. Shenzhen's hardware-software integration cluster advances device-embedded voice interfaces for smart home and automotive applications.
United Kingdom
Enterprise software buyers in London's financial district demand seamless integration with existing productivity suites and CRM platforms. FCA guidance shapes governance frameworks for AI-driven customer interactions in banking and insurance. The Cambridge-Oxford technology arc supplies natural language processing research talent to assistant developers.
Intelligent Virtual Assistant Market Vendor Landscape
The competitive structure tilts toward platform-scale technology conglomerates with existing cloud and productivity ecosystems. Microsoft, Google, and IBM bundle conversational AI with established enterprise software suites, compressing margins for standalone assistant vendors while elevating buyer integration expectations. Three strategic archetypes dominate: ecosystem-embedded platforms, vertical specialists with compliance modules, and emerging foundation model API providers. Consolidation pressure manifests through strategic partnerships and technology licensing rather than outright acquisition, as incumbents seek to neutralize capability gaps without absorbing startup operational overhead.
Within the ecosystem-embedded tier, Microsoft Copilot and Google Gemini anchor competitive positioning through native integration with productivity and cloud infrastructure. IBM watsonx Assistant occupies a specialized position serving regulated industries with pre-certified compliance architectures. These three exemplify how platform bundling reshapes procurement criteria toward seamless workflow embedding rather than standalone feature comparison.
| Leading Market Players |
|---|
| ChatGPT |
| Conversica |
| Microsoft Copilot |
| Jasper |
| Otter.ai |
| Google Gemini |
| Lindy |
| Gong |
| IBM watsonx Assistant |
| Others |
Supply Flow & Price Mechanics
Consumption-based pricing demands from mid-market CFOs in the United States are forcing vendors to abandon seat-based SaaS models, compressing margins while GPU supply concentration in Taiwan and South Korea amplifies input cost volatility across deployment tiers.
Pricing Analysis
Subscription tiers anchored to resolved inquiry volumes dominate enterprise procurement, with premium-mid-economy pricing differentiation separating HIPAA-validated healthcare modules from standard customer support deployments. ISO/IEC 42001 certification premiums command higher rates in German and Dutch financial services. Cost compression in mid-market cloud subscriptions is intensifying because hyperscaler bundling embeds assistant capabilities at marginal cost. Small businesses exhibit highest price sensitivity, while healthcare providers with Medicare Advantage reimbursement tailwinds show lowest.
Supply Chain Analysis
India's domestic-content mandates for financial AI are reshaping sourcing patterns for voice-first banking assistants targeting UPI integration. NVIDIA H100 and AMD MI300X clusters concentrate in Taiwan, South Korea, and the United States. Transformer inference feeds from specialized AI foundry capacity and high-bandwidth memory modules. Single-source vulnerability in TSMC's advanced packaging creates procurement chokepoints. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intelligent virtual assistant market compounds steadily as foundation model cost curves democratize enterprise-grade capabilities previously locked behind technology-major infrastructure.
For Market Incumbents: To counter standalone vendor margin compression from Microsoft Copilot and Google Gemini ecosystem bundling, deepen proprietary compliance module development for FDA and EU AI Act pathways while securing exclusive hospital system partnerships in Boston's health technology corridor. For New Entrants and Emerging Players: Launch via India's unified payments interface integration to capture voice-first banking white space in tier-2 and tier-3 cities, targeting 1.4 billion potential users with minimal incumbent saturation and RBI data localization as competitive moat. For Investors and Strategic Acquirers: Asymmetric upside sits with vertical specialists possessing pre-certified quality management systems and validated clinical decision-support outputs, with FDA 510(k) clearance velocity serving as the critical inflection signal for premium exit multiples.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Pre-certified transparency logging accelerates procurement cycles for German and Italian healthcare enterprises. |
| Retrieval-Augmented Generation Integration | RAG-enabled clinical guideline surfacing reduces hallucination liability for United States hospital systems. |
| Hybrid Architecture Development | Split cloud-on-premise deployments capture margin premiums from financial services data residency mandates. |
| Multimodal Convergence Investment | Speech-vision-biometric synthesis opens automotive and smart home device-embedded revenue streams. |
| ISO/IEC 42001 Quality Management | Pre-audited systems reduce 12-18 month procurement delays for regulated European buyers. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary dialogue with CTOs, IT procurement officers, platform engineers, and hospital purchasing committees against secondary validation through SEC hyperscaler capex disclosures, App Annie enterprise mobility data, FDA 510(k) filing databases, and CMS Medicare Advantage reimbursement schedules. Bottom-up deployment counts and top-down cloud infrastructure spend triangulated market sizing.
Comparable-period anchoring linked historical adoption curves to projected diffusion patterns across the analysis window, modeling segmentation dimensions spanning deployment architecture, organization scale, vertical compliance intensity, integration complexity, and regional regulatory divergence. CAGRs derived from fitted adoption curves incorporating large language model inference cost trajectories and EU AI Act implementation timelines.
Several conditions sit outside the modeled scope, including sovereign AI export controls, Taiwan semiconductor supply disruption scenarios, and foundation model capability plateau events. Forecasts reflect documented assumptions about continued hyperscaler R&D concentration and reimbursement policy stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Cloud Computing Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Automotive Gesture Recognition Market
Artificial Intelligence (AI)
Global AI Training Dataset Market
Artificial Intelligence (AI)
Neural Network Market
Artificial Intelligence (AI)
Artificial Intelligence in Supply Chain Management Market
Artificial Intelligence (AI)
Underwater Autonomous Data Processor Market
Artificial Intelligence (AI)
Asia-Pacific AI Orchestration Market
Artificial Intelligence (AI)
Cloud Artificial Intelligence Market
Artificial Intelligence (AI)
Cognitive Services Platform Market
Artificial Intelligence (AI)
Consumer Facing AI Products Market
Artificial Intelligence (AI)
Edge AI Hardware Market
Artificial Intelligence (AI)
Brain Machine Interface Market
Artificial Intelligence (AI)
Industrial AI Software Market
Artificial Intelligence (AI)
Global Cognitive Computing Technology Market
Artificial Intelligence (AI)
Europe Artificial Intelligence Market
Artificial Intelligence (AI)
Global Voice Assistant Market