
 Artificial Intelligence in Business Market | 2026-2036
Artificial Intelligence in Business Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence in Business Market Insights
Enterprise procurement of AI capabilities is shifting from single-vendor cloud contracts toward multi-source arrangements that blend hyperscaler infrastructure with specialized model providers. NVIDIA sustains its position through captive control over GPU silicon and software stacks that anchor training workloads. Microsoft competes by extending Azure OpenAI Service across productivity and enterprise resource planning layers. Palantir differentiates through ontology-driven data integration that dominates defense and industrial deployment pipelines.
Artificial intelligence in business encompasses machine learning systems, natural language processing engines, computer vision pipelines, and deep learning architectures that process structured and unstructured enterprise data to automate decisions, generate content, and optimize operations. These technologies typically run on cloud-based or hybrid infrastructure with latency requirements measured in milliseconds for real-time inference. Natural language processing applications currently occupy the largest margin pools as enterprises deploy generative assistants for customer service and internal knowledge management, while computer vision segments are maturing in manufacturing quality control. Machine learning underpins predictive analytics in finance and healthcare, where model interpretability requirements shape vendor selection criteria.
The EU AI Act, FDA guidance on AI-enabled medical devices, and China's algorithmic recommendation regulations are fragmenting compliance requirements across deployment geographies. Enterprises must navigate divergent risk-classification schemes that dictate documentation burdens, human oversight mandates, and market access conditions. Stakeholders should monitor how national implementation timelines for these frameworks reshape cross-border data routing and model hosting decisions.
Market Dynamics
Enterprise AI procurement is converging on multi-cloud architectures that fragment workloads across hyperscalers and specialized inference providers, compressing vendor lock-in premiums while elevating orchestration-layer competition.
Growth Catalysts
- EU AI Act conformity mandates:High-risk application classifications are accelerating enterprise investment in explainability tooling and audit-ready model documentation to secure market access.
- Algorithmic trading expansion:Financial services firms are deploying reinforcement learning systems for real-time portfolio optimization and fraud detection at transaction scale.
- Generative assistants:Natural language processing deployments for customer service automation are absorbing disproportionate IT budget allocations across Fortune 500 enterprises.
Market Restraints
- GPU supply concentration:Advanced training silicon remains captive to TSMC fabrication capacity and NVIDIA's CUDA ecosystem control, creating procurement bottlenecks.
- Cross-border compliance friction:Divergent risk-classification schemes between the EU AI Act, FDA guidance, and China's algorithmic recommendation regulations multiply documentation burdens.
- Model interpretability requirements:Healthcare and finance sectors demand explainable AI architectures that constrain deep learning adoption where black-box predictions face regulatory scrutiny.
Strategic Opportunities
- Industrial computer vision:Manufacturing quality control pipelines remain underpenetrated by AI-enabled defect detection relative to predictive maintenance maturity.
- India's digital infrastructure:The country's PLI scheme for electronics manufacturing and expanding cloud regions create localized model hosting and training demand.
- Edge inference convergence:5G network slicing combined with compact transformer architectures enables millisecond-latency decisioning without cloud round-trips.
Industry Challenges
- MLOps talent scarcity:Enterprises face acute shortages of engineers capable of productionizing models across hybrid infrastructure with continuous monitoring.
- Legacy system integration:ERP and CRM modernization timelines frequently stall AI deployments where API compatibility and data schema standardization remain incomplete.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence in Business Market |
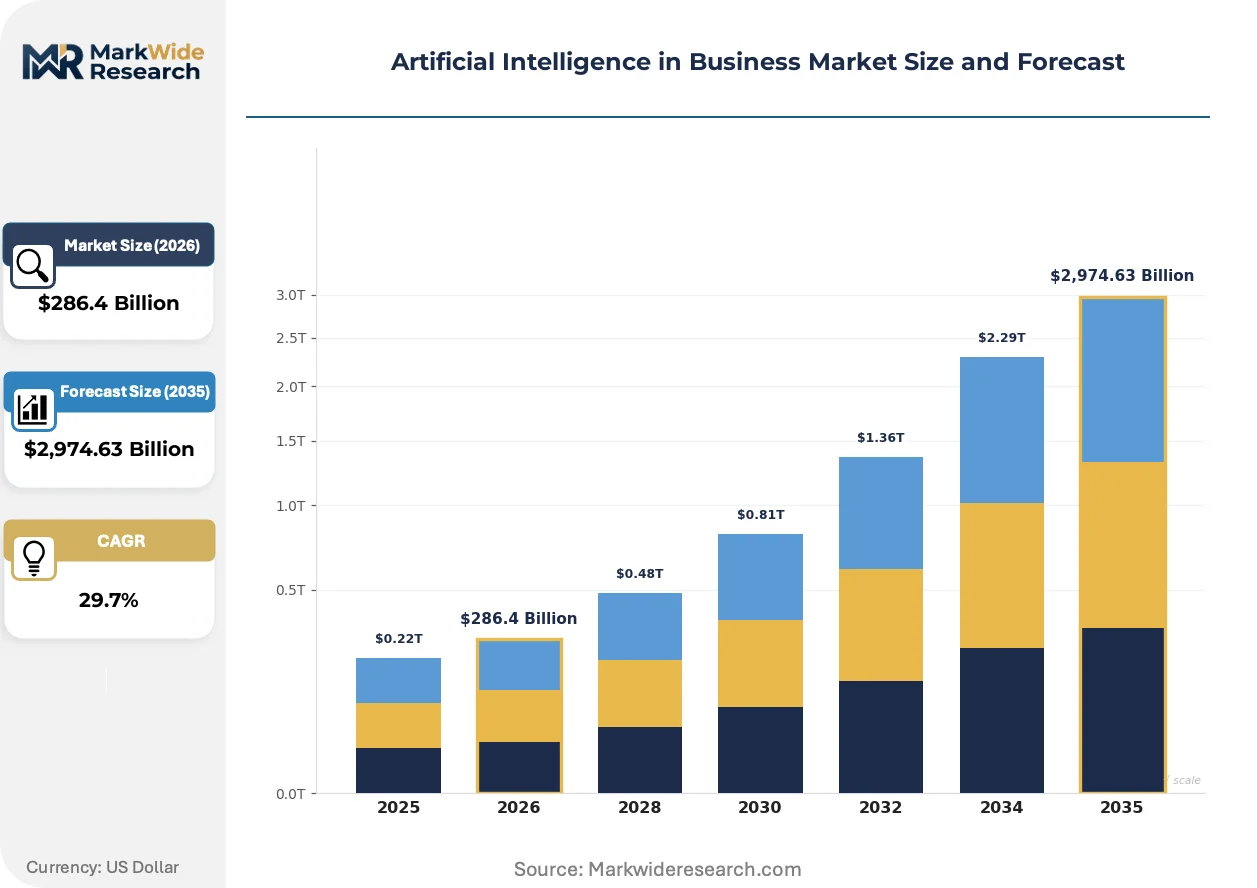
| Market Size in 2026 | $286.4 Billion |
| Market Size in 2035 | $2,974.63 Billion |
| CAGR (2026 – 2036) | 29.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Customer Service, Predictive Analytics, Fraud Detection, Recommendation Systems Technology: Machine Learning, Natural Language Processing, Deep Learning, Computer Vision End User: Retail, Finance, Healthcare, Manufacturing Deployment: On-Premises, Cloud-based, Hybrid, Edge Computing |
| Companies Covered | NVIDIA, Microsoft, Alphabet, Apple, Amazon, Meta Platforms, Palantir, Anthropic, Databricks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence in Business Market Trends and Innovations
Foundation model commodification is redistributing value capture toward proprietary data moats and domain-specific fine-tuning capabilities, eroding raw model performance as a sustainable differentiator.
Retrieval-augmented generation architectures are automating enterprise knowledge management by grounding large language model outputs in proprietary document corpora. Healthcare systems and law firms are deploying these systems at production scale within six-month implementation cycles. The technology is automating paralegal research and clinical decision support workflows that previously required specialized expertise.
The EU AI Act's high-risk system classifications are mandating human-in-the-loop oversight for credit scoring and biometric identification deployments. Industrial consequence includes mandatory conformity assessments and CE marking requirements before market entry. Financial services and public sector procurement in Germany and France are restructuring vendor qualification criteria around these documentation standards.
Enterprise buyers are consolidating AI spend under centralized procurement functions that negotiate enterprise-wide platform licenses rather than departmental point solutions. Systems integrators and managed service providers are displacing direct vendor relationships as the primary contracting channel. This concentration is most visible in United States federal contracting and German automotive supply chains.
Artificial Intelligence in Business Market Segmentation
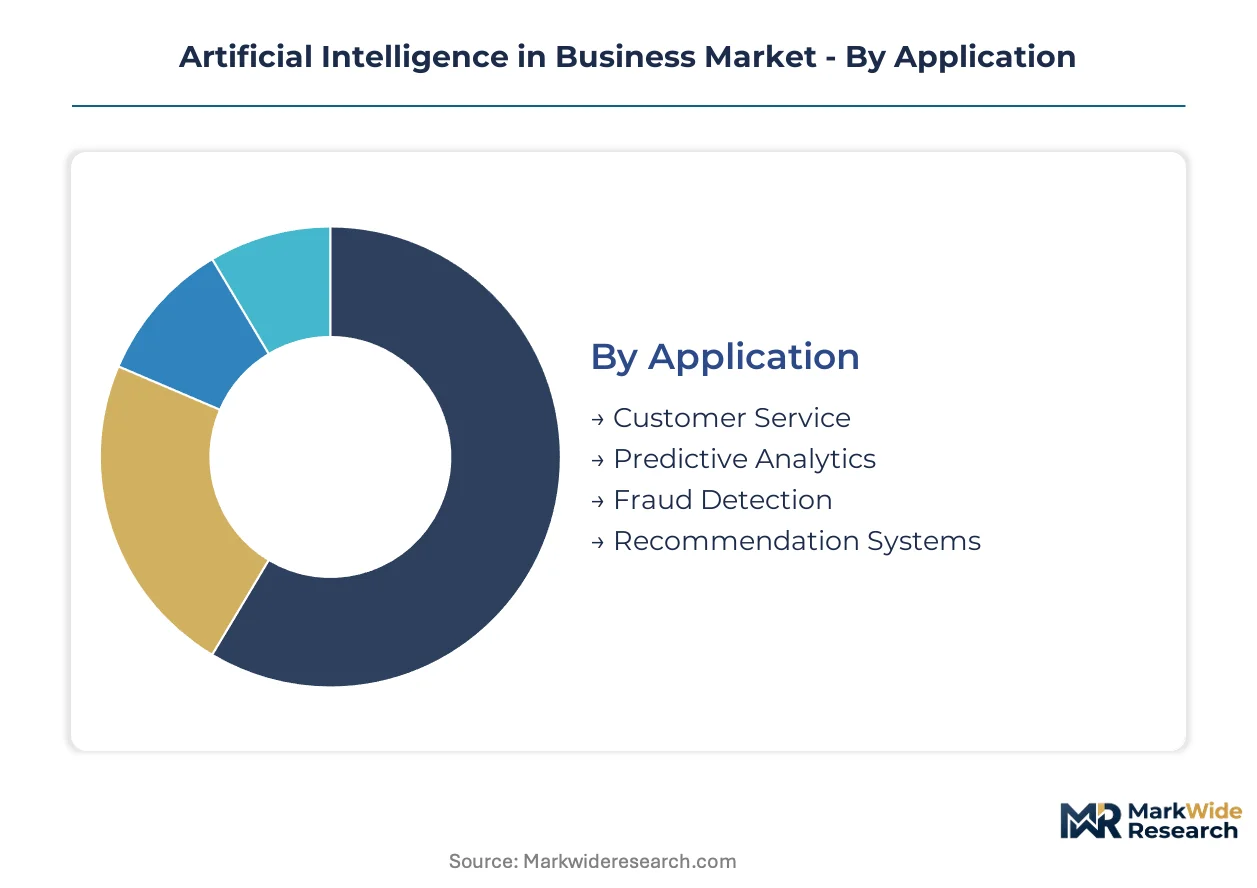
Enterprise procurement patterns in artificial intelligence diverge sharply across application workloads, underlying technologies, and infrastructure footprints. Understanding these segment boundaries clarifies where vendor competition intensifies and where margin pools concentrate.
Application:
Upgrade cycles in enterprise AI software accelerate as legacy rule-based systems face replacement pressure from generative architectures.
- Customer Service:Natural language processing engines power conversational assistants that handle tier-one support queries without human escalation. Financial services firms in the United States and Germany deploy these systems to compress call center operating expenditure while maintaining compliance documentation for EU AI Act audits.
- Predictive Analytics:Machine learning models forecast demand, churn, and equipment failure from structured historical data. Retail chains and industrial manufacturers prioritize these deployments where return-on-investment timelines remain shorter than generative AI initiatives.
- Fraud Detection:Real-time transaction scoring using anomaly detection algorithms.
- Recommendation Systems:Collaborative filtering and content-based engines for e-commerce personalization.
Customer Service sits at the top of the volume ranking, with Fraud Detection climbing the fastest as real-time payment infrastructure expands.
Technology:
Cost tiers in AI infrastructure separate enterprises training foundation models from those consuming API-based inference services.
- Natural Language Processing:Transformer architectures process and generate human text for search, summarization, and code completion. Enterprise demand concentrates in legal and healthcare sectors where document-intensive workflows justify premium licensing for retrieval-augmented generation systems.
- Machine Learning:Supervised and unsupervised statistical methods for classification, regression, and clustering tasks. Manufacturing quality control and supply chain optimization drive sustained deployment across German automotive and Japanese electronics supply chains.
- Deep Learning:Multi-layer neural networks requiring substantial GPU clusters for training.
- Computer Vision:Image classification, object detection, and segmentation pipelines for visual inspection.
Machine Learning maintains the broadest installed base, while Natural Language Processing gains share fastest as generative assistant budgets expand.
End User:
Application maturity varies dramatically across sectors, with regulated industries demanding explainable architectures that constrain deep learning adoption.
- Finance:Algorithmic trading, credit scoring, and anti-money laundering systems operate under strict model interpretability mandates from the SEC and EU AI Act. Banks allocate disproportionate procurement budgets to audit-ready documentation and human-in-the-loop oversight tooling.
- Healthcare:Clinical decision support and medical imaging analysis face FDA and EMA premarket review pathways. Deployment timelines stretch longer than other sectors, but contract values per installation remain the highest across the market.
- Retail:Demand forecasting, inventory optimization, and personalized marketing automation.
- Manufacturing:Predictive maintenance and quality control computer vision pipelines.
Finance commands the largest current procurement volumes, with Healthcare exhibiting the steepest expansion trajectory as diagnostic AI clears regulatory pathways.
Deployment:
Customer type and data sensitivity dictate infrastructure choices, with hybrid architectures emerging as the dominant compromise between control and scalability.
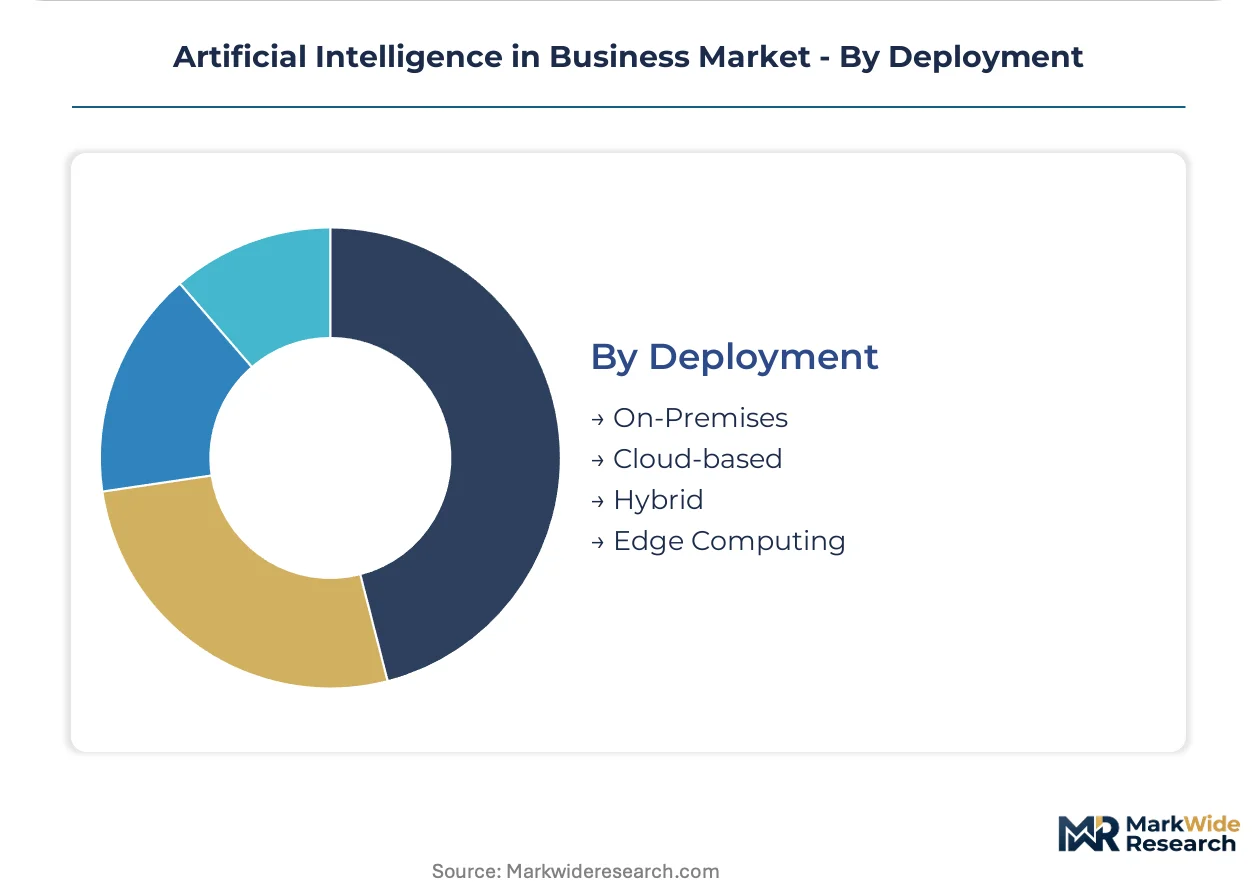
- Cloud-based:Hyperscaler-hosted training and inference workloads leverage economies of scale in GPU provisioning. United States enterprises dominate this segment given concentration of AWS, Azure, and Google Cloud data center regions.
- Hybrid:Sensitive data processing on-premises combines with burst capacity from cloud infrastructure. German automotive and French financial services firms favor this model to satisfy GDPR data residency requirements while accessing elastic compute.
- On-Premises:Fully captive infrastructure for classified or highly regulated workloads.
- Edge Computing:Millisecond-latency inference deployed on factory floors, retail locations, and autonomous vehicle platforms.
Cloud-based deployment retains volume leadership, though Hybrid architectures expand most quickly as data sovereignty requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley anchors enterprise AI deployment density, with venture funding concentration and hyperscaler headquarters creating procurement gravity that shapes vendor qualification standards worldwide.
United States
Fortune 500 enterprises in financial services and defense sectors drive concentrated demand for retrieval-augmented generation systems and secure inference infrastructure. The SEC's model risk management guidance and pending FDA frameworks for clinical decision support shape procurement documentation requirements. Seattle and Redmond host Microsoft's Azure OpenAI Service expansion, while San Francisco-based Anthropic anchors safety-focused foundation model development.
Germany
Automotive supply chains and industrial machinery manufacturers prioritize computer vision for quality control and predictive maintenance workloads. The EU AI Act's high-risk system classifications mandate conformity assessments for credit scoring and biometric applications, restructuring vendor qualification in Frankfurt and Munich financial centers. Stuttgart's manufacturing clusters deploy hybrid cloud architectures to satisfy GDPR data residency while accessing elastic GPU capacity.
China
Domestic cloud providers and state-backed AI labs accelerate foundation model training for sovereign deployment in smart manufacturing and surveillance applications. The MIIT's algorithmic recommendation regulations and data security law fragment compliance requirements for multinational enterprises operating in Shanghai and Shenzhen. Beijing's Zhongguancun cluster concentrates talent for large language model development alongside Hangzhou's e-commerce personalization engines.
United Kingdom
London's financial services sector and Cambridge's research corridor generate demand for explainable AI in algorithmic trading and drug discovery pipelines. The Information Commissioner's Office guidance on automated decision-making shapes procurement criteria for insurance and lending applications. Manchester's emerging tech cluster attracts edge inference deployments for retail and logistics optimization.
India
IT services exporters and domestic fintech platforms drive consumption of API-based natural language processing and document automation. The RBI's guidelines on AI in financial services and the PLI scheme for electronics manufacturing create localized hosting demand. Bangalore's cloud regions and Hyderabad's data center clusters support model training for Southeast Asian market expansion.
Artificial Intelligence in Business Market Competitive Landscape
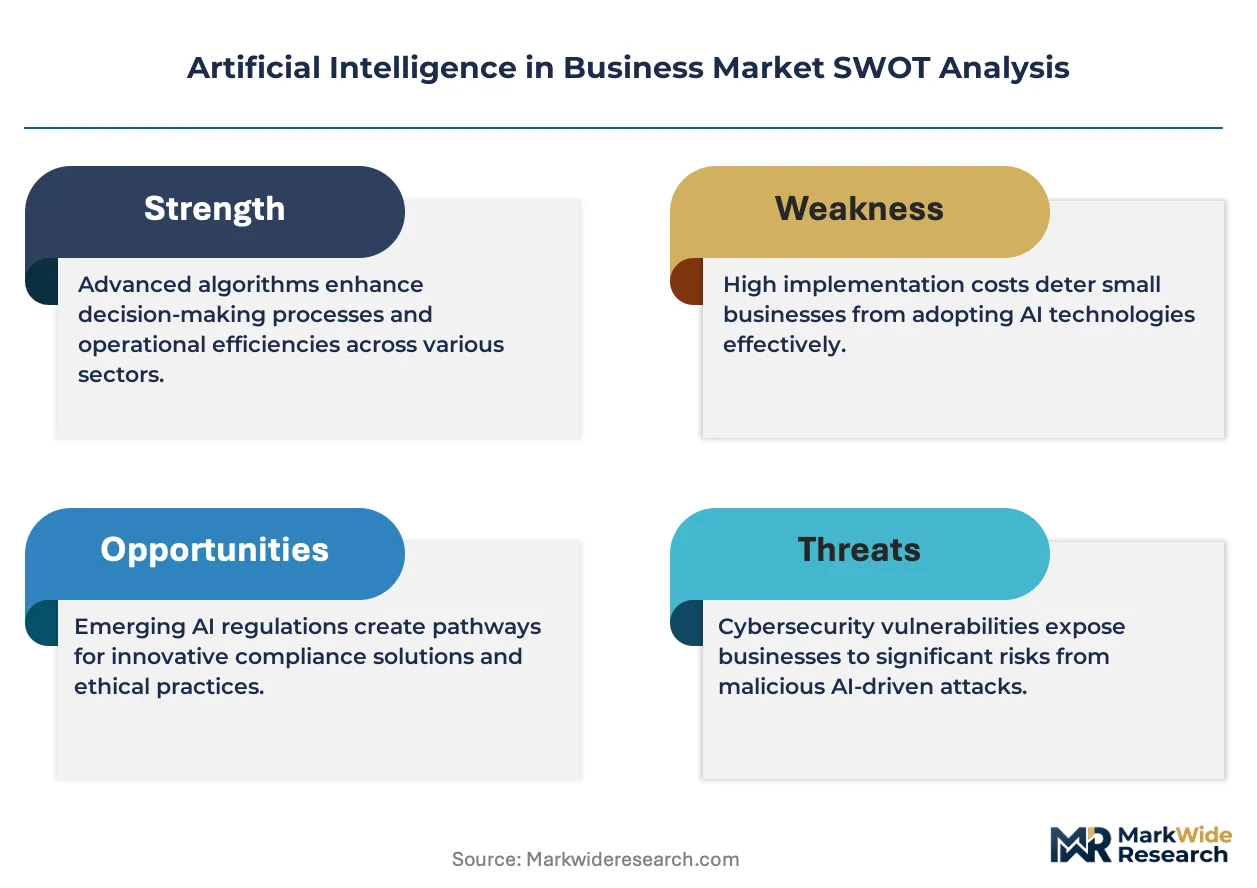
Established producers occupy the standard tier; emerging entrants pursue specialized inference and domain-specific fine-tuning capabilities. The vendor base stratifies across hyperscaler platforms, silicon suppliers, and vertical application specialists with limited mid-tier consolidation. Three archetypes dominate: GPU compute providers anchoring training infrastructure, cloud platforms integrating foundation models into productivity suites, and ontology-driven data integration specialists. Competitive moves concentrate on strategic partnerships between model developers and enterprise software vendors, alongside geographic expansion of sovereign cloud regions.
Within the silicon tier, NVIDIA exemplifies captive supply chain control over advanced training hardware and software ecosystems. Microsoft and Alphabet occupy positions as cloud-integrated platform providers extending AI services across productivity and search layers. Palantir represents the vertical specialist archetype, anchoring defense and industrial deployment pipelines through ontology-driven data integration. These three companies illustrate how value capture concentrates at infrastructure and platform layers rather than raw model provision.
| Leading Market Players |
|---|
| NVIDIA |
| Microsoft |
| Alphabet |
| Apple |
| Amazon |
| Meta Platforms |
| Palantir |
| Anthropic |
| Databricks |
| Others |
Pricing and Supply Chain Analysis
EU AI Act conformity mandates are forcing enterprise buyers to prioritize audit-ready documentation and explainability tooling over raw inference cost, compelling suppliers to absorb compliance engineering expenses while maintaining tiered service levels.
Pricing Analysis
Advanced GPU silicon costs from TSMC fabrication pass through to enterprise training workloads at premium markups, while API-based inference services compete on per-token economics. Pricing stratifies across dedicated infrastructure, reserved capacity, and spot consumption tiers. Cost compression in commodity inference is intensifying because foundation model commodification erodes performance premiums. Mid-market enterprises exhibit highest price sensitivity, while financial services firms in Frankfurt and New York accept premium pricing for regulatory-grade documentation and human-in-the-loop oversight tooling.
Supply Chain Analysis
Advanced training silicon supply rests on TSMC fabrication in Taiwan, NVIDIA's CUDA software ecosystem, and HBM memory production in South Korea. Cloud hyperscalers in the United States anchor downstream distribution through managed service partnerships. Single-source vulnerability concentrates in TSMC's leading-edge node capacity, where geopolitical exposure threatens procurement continuity for foundation model training clusters. Distribution runs through systems integrators and managed service providers that displace direct vendor relationships in United States federal contracting and German automotive supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundation model commodification is compressing raw inference margins while retrieval-augmented generation capabilities and proprietary data integration command expanding premiums.
For Market Incumbents: Acquire specialized MLOps talent pools and domain-specific fine-tuning capabilities to defend against emerging entrants offering verticalized solutions. Consolidate channel control through systems integrator partnerships that centralize enterprise procurement under platform licenses. Expand reserved GPU capacity in India and Germany to satisfy data sovereignty requirements while locking in multi-year commitments before spot market volatility intensifies. For New Entrants and Emerging Players: EU AI Act high-risk system classifications in Germany and France open a window for explainability tooling and audit automation platforms that incumbent hyperscalers underinvest in. Industrial computer vision for manufacturing quality control remains underpenetrated relative to predictive maintenance maturity. Pursue white-label partnerships with German automotive Tier 1 suppliers seeking compliant defect detection pipelines without cloud dependency. For Investors and Strategic Acquirers: Asymmetric upside sits with ontology-driven data integration specialists serving defense and industrial verticals where Palantir's dominance has validated the model. Five-to-ten-year viability hinges on proprietary data moats rather than raw model performance. Watch for inflection when India's PLI scheme electronics manufacturing incentives trigger localized model hosting demand exceeding current cloud region capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Retrieval-Augmented Generation Platform Launch | Grounds large language model outputs in proprietary document corpora for legal and healthcare workflows. |
| Strategic Partnership with Systems Integrator | Displaces direct vendor relationships as primary contracting channel in United States federal procurement. |
| Acquisition of Specialist MLOps Firm | Secures productionization talent scarce across hybrid infrastructure deployment pipelines. |
| Geographic Expansion to Sovereign Cloud Region | Satisfies GDPR data residency requirements for German automotive and French financial services firms. |
| Platform Integration with Enterprise Resource Planning | Extends Azure OpenAI Service across productivity layers as Microsoft competes for procurement consolidation. |
Research Methodology
Bottom-up enterprise deployment modeling reconciled against top-down hyperscaler infrastructure tracking forms the analytical core. Primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists combine with secondary validation from SEC filings, hyperscaler capex disclosures, and EU AI Act implementation timelines. Triangulation across these sources ensures segmentation outputs reflect actual procurement patterns rather than vendor-reported aspirations.
Historical trendline analysis of cloud infrastructure spending and enterprise software budgets establishes baseline growth trajectories. The projection framework models deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern dimensions. CAGRs derive from fitted trend extrapolation adjusted for regulatory implementation schedules and technology substitution effects. Model inputs include GPU supply constraints from TSMC capacity allocation and MLOps talent availability by geography.
Revisions become necessary when TSMC leading-edge node capacity allocation shifts, EU AI Act enforcement intensity exceeds modeled scenarios, or sovereign cloud region buildouts accelerate beyond current infrastructure planning. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
AI in Project Management Market
Artificial Intelligence (AI)
Global AI Governance Market
Artificial Intelligence (AI)
Brain Computer Interface Market
Artificial Intelligence (AI)
Cloud Natural Language Processing (NLP) Market
Artificial Intelligence (AI)
Enterprise AI Governance and Compliance Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Construction Market
Artificial Intelligence (AI)
AI Text Generator Market
Artificial Intelligence (AI)
US Voice Recognition Market
Artificial Intelligence (AI)
Artificial Intelligence in Trading Market
Artificial Intelligence (AI)
Asia-Pacific Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
AI Content Creation Tool Market
Artificial Intelligence (AI)
Latin America Artificial Intelligence Market
Artificial Intelligence (AI)
AI in Food & Beverages Market
Artificial Intelligence (AI)
Emotion AI Software Market
Artificial Intelligence (AI)
Artificial Intelligence in Logistics Market
Artificial Intelligence (AI)
Europe Synthetic Data Generation Market