
 AI Virtual Assistants Market | 2026-2036
AI Virtual Assistants Market Size, Share, and Industry Trends Forecast 2026-2036
AI Virtual Assistants Market Insights
Subscription-based conversational AI platforms is pivoting vendor economics from perpetual licenses toward recurring revenue models. Microsoft Corporation leverages its enterprise cloud footprint to embed assistant capabilities across productivity suites. Amazon.com, Inc. anchors consumer voice interaction through smart speaker ecosystems and developer tools. Google LLC differentiates via real-time multilingual speech recognition and search integration.
AI virtual assistants constitute software agents that process natural language inputs through neural network architectures, typically operating with sub-200-millisecond response latency to simulate human dialogue for task completion and information retrieval. Conversational AI and natural language processing segments attract disproportionate R&D investment as large language models reduce training costs. Cloud-based deployment dominates enterprise uptake while on-premise configurations persist in banking and healthcare settings with stringent data residency requirements.
The EU AI Act classifies virtual assistants by risk tier, mandating transparency disclosures for systems influencing consumer decisions. The FDA evaluates clinical decision-support assistants in healthcare, while China's SAMR enforces algorithmic recommendation provisions affecting domestic platforms. Stakeholders must track evolving liability frameworks governing autonomous agent actions and cross-border data flows.
Market Dynamics
Large language model compression is overtaking transformer architectures as the dominant technical paradigm, slashing inference costs while expanding deployment feasibility across resource-constrained environments.
Growth Catalysts
- EU AI Act transparency mandates:Risk-tier classification creates procurement clarity for enterprise buyers evaluating conversational systems. Healthcare and financial services sectors accelerate vendor qualification processes.
- Edge computing infrastructure:On-device neural processing units enable sub-100-millisecond response latency without cloud dependency. Manufacturing floor applications and automotive cabins drive hardware integration partnerships.
- China's algorithmic recommendation provisions:SAMR enforcement domesticates platform compliance, accelerating localized assistant development. Domestic cloud providers capture enterprise migration from foreign-hosted systems.
Market Restraints
- GPU supply concentration:NVIDIA's datacenter chip dominance creates procurement bottlenecks for training infrastructure. Foundry capacity constraints in Taiwan extend lead times for specialized accelerators.
- FDA clinical decision-support pathways:Software-as-medical-device classification imposes 18-36 month validation timelines. Healthcare assistant deployments stall awaiting 510(k) or De Novo clearances.
- Data residency fragmentation:Divergent national storage mandates multiply infrastructure costs. Brazil's LGPD, India's DPDP Act, and Saudi PDPL each require distinct regional hosting architectures.
Strategic Opportunities
- German Mittelstand manufacturing:Mid-tier industrial firms remain underserved by current enterprise assistant offerings. Technical documentation retrieval and maintenance scheduling applications show minimal penetration.
- Voice biometric authentication:Convergence with liveness detection and behavioral analytics enables passwordless banking interfaces. European payment service providers pilot PSD2-compliant strong customer authentication workflows.
- India's Bhashini platform:Government-funded language dataset infrastructure lowers barrier for Indic-language assistants. 22 scheduled language coverage creates path to 400-million-user vernacular markets.
Industry Challenges
- Conversational AI prompt engineering:Scarce practitioners command compensation premiums exceeding traditional software engineering roles. Enterprise implementation timelines stretch awaiting talent acquisition.
- Cross-border model fine-tuning:Training data licensing complexity fragments model performance across jurisdictions. Copyright uncertainty surrounding synthetic data generation invites litigation exposure.
- Legacy IVR system migration:Touch-tone infrastructure retirement requires staged transition planning. Banking contact centers face 24-month integration horizons for full conversational replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Virtual Assistants Market |
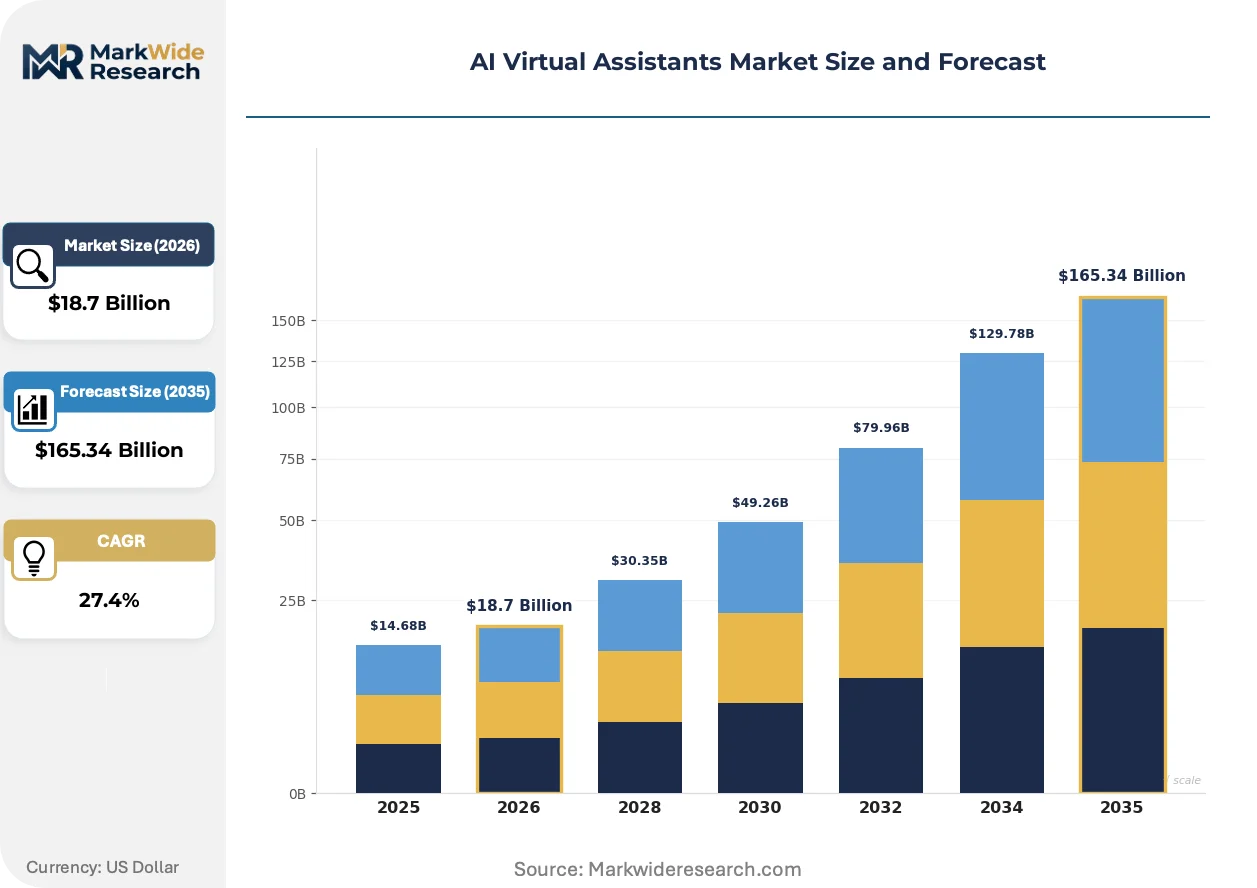
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $165.34 Billion |
| CAGR (2026 – 2036) | 27.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Customer Support, Personal Assistant, Scheduling, Voice Commands Technology: Natural Language Processing, Machine Learning, Speech Recognition, Conversational AI Deployment: Cloud-Based, On-Premise, Hybrid, Mobile End User: Retail, Healthcare, Banking, Education |
| Companies Covered | Microsoft Corporation, Google LLC, Amazon.com, Inc., Apple Inc., IBM Corporation, Oracle Corporation, Samsung Electronics Co., Ltd., SAP SE, Nuance Communications, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Virtual Assistants Market Trends and Innovations
Multimodal reasoning capabilities are compressing the functional gap between narrow task assistants and general-purpose agents, reshaping competitive differentiation around latency-optimized architectures rather than raw model scale.
Retrieval-augmented generation is overtaking pure parametric knowledge storage in enterprise deployments. Financial services compliance teams adopt context-grounded response systems to eliminate hallucinated regulatory guidance. The architecture enables real-time policy document synchronization without full model retraining.
The EU AI Act's high-risk system obligations activate disclosure requirements for credit-scoring and insurance pricing assistants. Providers must document training data provenance and human oversight protocols. German automotive manufacturers restructure in-cabin voice systems to exclude biometric inference from prohibited practices.
Subscription fatigue among mid-market enterprises is fragmenting procurement toward usage-based API consumption. Salesforce-integrated workflow assistants displace standalone platform licenses in North American SaaS stacks. Procurement teams negotiate token-volume commitments rather than seat-based contracts.
AI Virtual Assistants Market Segmentation
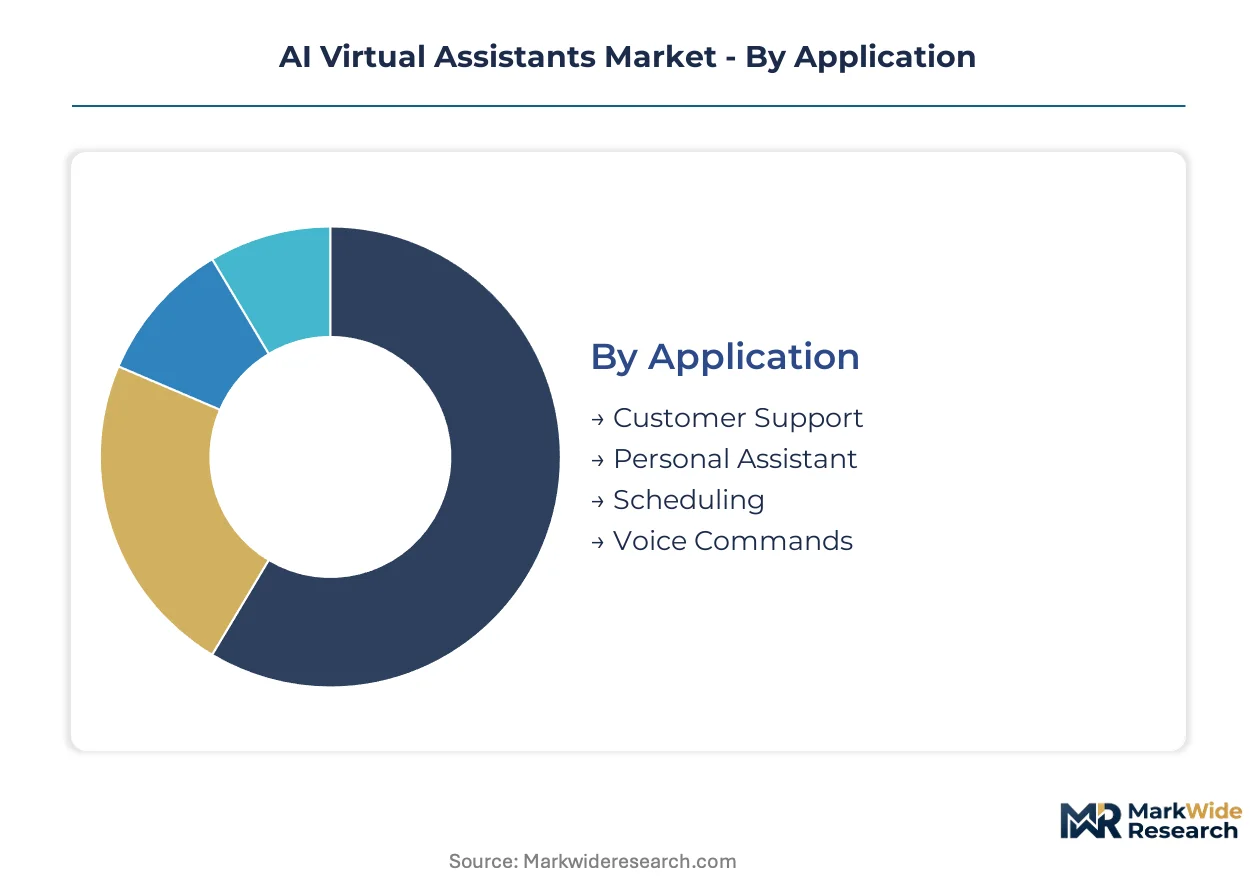
Segmentation in the AI virtual assistants market reveals how deployment constraints and user sophistication shape vendor priorities. Technical architecture choices and regulatory exposure vary sharply across application contexts and end-user industries.
Application:
Volume deployment concentrates in high-interaction service functions, while premium pricing attaches to specialized knowledge work.
- Customer Support:Automated resolution of billing inquiries, order tracking, and technical troubleshooting through intent classification and knowledge base retrieval. Banking call centers in Germany and retail operations in the United States drive procurement, constrained by EU AI Act transparency mandates for systems influencing consumer decisions.
- Personal Assistant:Cross-platform task management integrating calendar, communication, and device control through unified natural language interfaces. Enterprise knowledge workers in China and the United States generate demand, accelerated by Microsoft 365 and Google Workspace embedding strategies.
- Scheduling:Calendar negotiation and resource allocation through email parsing and availability polling.
- Voice Commands:Hands-free device control for smart home and automotive environments.
Mature deployment sits with Customer Support. Newer deployment is concentrated in Personal Assistant.
Technology:
Cost tier stratification separates commodity speech processing from premium reasoning capabilities requiring specialized hardware.
- Natural Language Processing:Syntactic parsing, entity extraction, and semantic role labeling enabling structured understanding of unstructured text inputs. Healthcare clinical documentation in the United States and financial compliance in Germany attract investment, though FDA 510(k) pathways extend validation timelines for medical applications.
- Conversational AI:Multi-turn dialogue management with context retention, disambiguation, and slot-filling for complex task completion. Retail and banking sectors in China deploy localized platforms under SAMR algorithmic recommendation enforcement, displacing foreign-hosted alternatives.
- Machine Learning:Statistical pattern recognition for intent classification and predictive response ranking.
- Speech Recognition:Acoustic modeling and phoneme decoding for audio-to-text transcription.
Speech Recognition shows the steepest commoditization trajectory. Conversational AI commands the highest implementation premiums.
Deployment:
Customer type divides between cloud-native adopters seeking speed and regulated entities requiring data sovereignty guarantees.
- Cloud-Based:Scalable inference through hyperscaler infrastructure with API consumption and auto-scaling for demand spikes. Mid-market enterprises in the United States and Germany favor this model, though subscription fatigue is fragmenting procurement toward usage-based token contracts.
- On-Premise:Air-gapped inference within organizational data centers satisfying data residency and audit requirements. Banking and healthcare institutions in Germany and Saudi Arabia maintain this architecture under LGPD, DPDP Act, and PDPL mandates.
- Hybrid:Tiered processing with sensitive operations on-premise and scalable tasks cloud-distributed.
- Mobile:On-device neural processing through smartphone NPU acceleration for low-latency response.
Cloud-Based deployment captures the broadest enterprise base. On-Premise configurations persist where regulatory exposure is highest.
End User:
Application maturity varies by sector-specific compliance burden and interaction complexity tolerance.
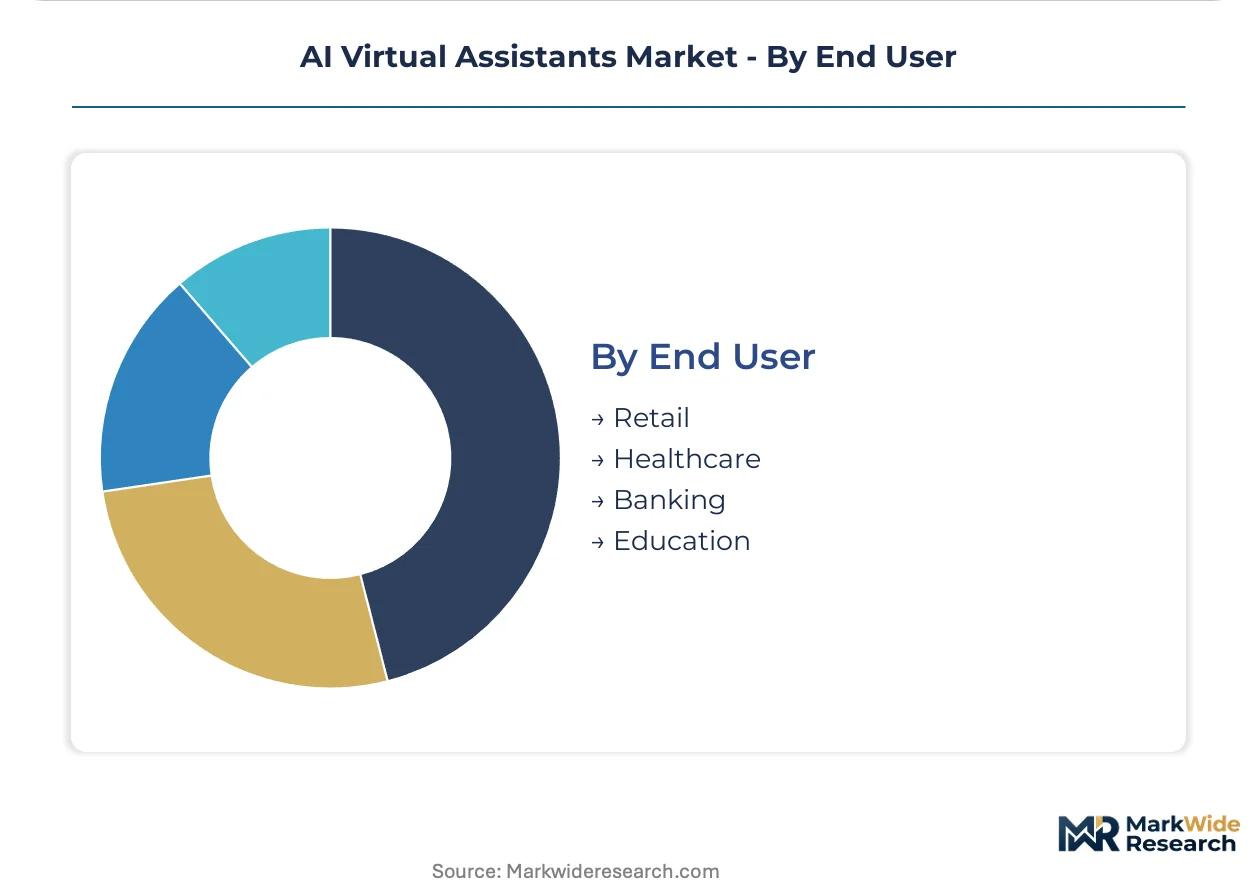
- Banking:Fraud detection assistance, account servicing, and payment authorization through voice biometric authentication. European payment service providers pilot PSD2-compliant strong customer authentication workflows, while German institutions navigate EU AI Act high-risk system obligations for credit-scoring applications.
- Healthcare:Clinical decision support, patient triage, and medication adherence monitoring with diagnostic liability exposure. The FDA evaluates software-as-medical-device classifications imposing 18-36 month clearance timelines, stalling deployment awaiting 510(k) or De Novo pathways.
- Retail:Product search, order management, and returns processing through conversational commerce interfaces.
- Education:Tutoring systems and administrative automation for student services and enrollment management.
Banking leads in production deployment scale. Healthcare shows the most constrained expansion due to validation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of AI virtual assistants concentrates in the United States and China where hyperscaler infrastructure and developer ecosystems dominate, while consumption spreads across Germany, Japan, and India as enterprises automate customer-facing operations.
United States
Enterprise cloud migration and banking contact center modernization drive procurement volumes. The FDA imposes 18-36 month validation timelines on clinical decision-support assistants, slowing healthcare deployment. Seattle and San Francisco Bay Area clusters anchor development of productivity-embedded assistants through Microsoft 365 and Google Workspace integration strategies.
China
Smart speaker penetration and localized enterprise SaaS adoption generate demand across retail and manufacturing sectors. SAMR algorithmic recommendation provisions accelerate domestic platform compliance, displacing foreign-hosted alternatives. Beijing and Shenzhen clusters concentrate conversational AI R&D under state-funded language dataset initiatives supporting 22 scheduled languages.
Germany
Mittelstand manufacturing firms and automotive suppliers pursue technical documentation retrieval applications with minimal current penetration. The EU AI Act risk-tier classification mandates transparency disclosures for credit-scoring assistants, restructuring procurement qualification. Stuttgart and Munich clusters host in-cabin voice system development excluding biometric inference from prohibited practices.
India
BPO sector automation and vernacular language service expansion attract platform investment across 400-million-user markets. The DPDP Act data residency requirements multiply infrastructure costs for foreign-hosted systems. Bangalore and Hyderabad clusters leverage Bhashini government-funded datasets to lower barriers for Indic-language assistant development.
Japan
Aging demographics and labor shortage pressures accelerate healthcare and hospitality assistant deployment. METI standards coordination shapes interoperability requirements for multimodal systems. Tokyo and Osaka clusters focus on eldercare companion applications with sub-100-millisecond latency requirements through edge NPU integration.
AI Virtual Assistants Market Competitive Landscape
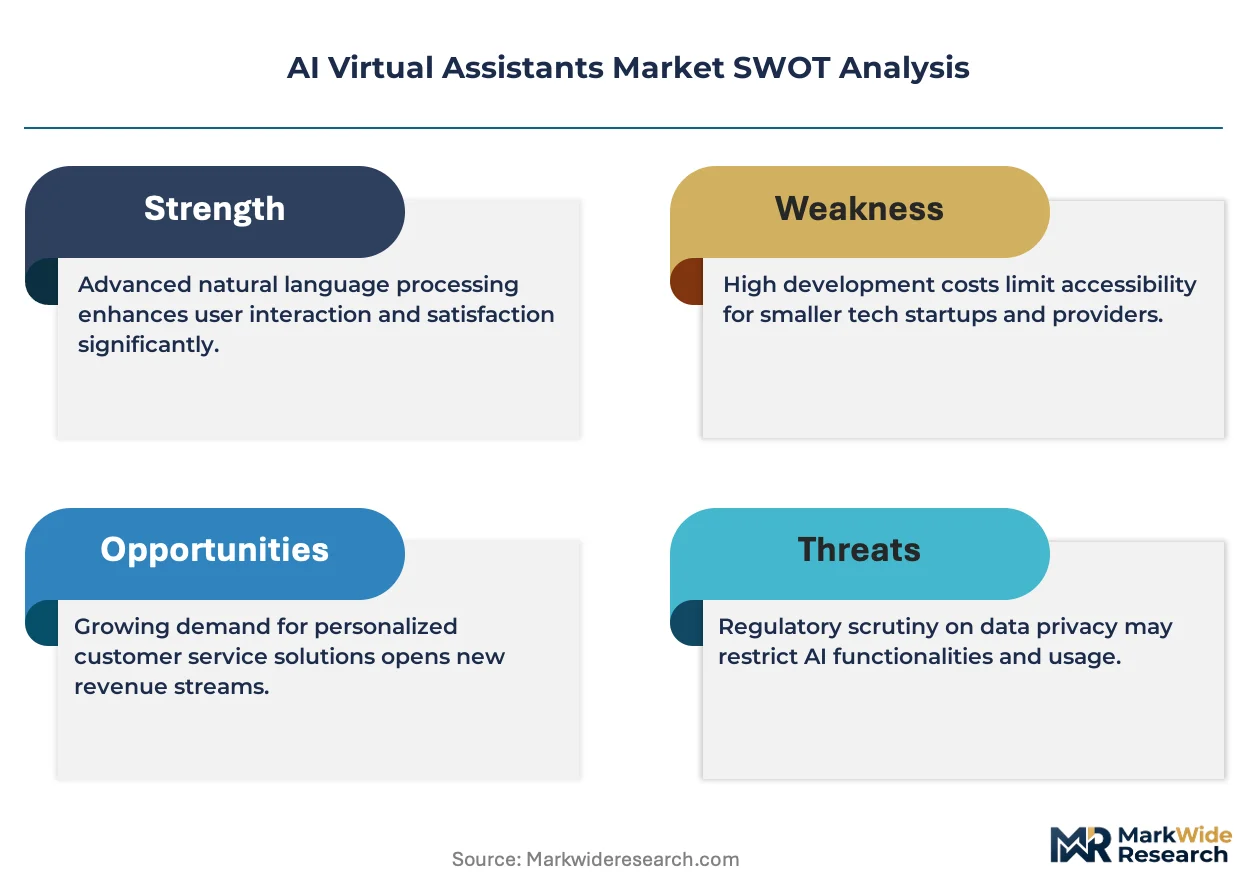
Top-tier vendors anchor hyperscaler ecosystems, while specialized voice AI and enterprise software providers occupy mid-tier positions. The market structure consolidates around cloud infrastructure owners with distribution advantages, though vertical specialists retain pockets of premium pricing in regulated sectors. Two strategic archetypes dominate: platform-embedded generalists and compliance-focused vertical specialists. Competitive moves center on API consumption model transitions and edge hardware partnerships for latency-sensitive applications.
Among hyperscaler-based providers, Microsoft Corporation and Google LLC exemplify platform-embedded archetypes with productivity suite distribution advantages, while Amazon.com, Inc. anchors consumer voice interaction through smart speaker ecosystem control. These three occupy positions defined by infrastructure ownership rather than standalone software licensing, representing the scale-driven consolidation vector reshaping procurement toward token-volume commitments and recurring revenue structures.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Google LLC |
| Amazon.com, Inc. |
| Apple Inc. |
| IBM Corporation |
| Oracle Corporation |
| Samsung Electronics Co., Ltd. |
| SAP SE |
| Nuance Communications, Inc. |
| Others |
Pricing and Supply Chain Analysis
NVIDIA H100 datacenter GPU spot pricing volatility cascades through inference-as-a-service tiers, compressing margins for cloud-native assistant providers while amplifying pricing power for hyperscalers with captive silicon supply. Token-volume commitments now separate enterprise procurement tiers from mid-market API consumption.
Pricing Analysis
Margin tightening in mid-market SaaS tiers reflects GPU rental cost pass-through and subscription fatigue fragmentation. Three-tier pricing structure across premium, standard, and economy levels stratifies by inference latency guarantees and model customization depth. Banking and healthcare segments show least price sensitivity due to compliance-driven procurement. Cost-down pressure on standalone platform licenses accelerates as Salesforce-integrated workflow assistants displace seat-based contracts.
Supply Chain Analysis
Freight cost normalization for edge NPU hardware from Taiwan and South Korea reduces landed cost variance for on-premise deployments. Foundry capacity constraints in Taiwan and South Korea extend lead times for specialized training accelerators. Supply chain risk centers on single-source vulnerability for NVIDIA datacenter chips. Distribution runs through hyperscaler marketplaces and direct enterprise API channels rather than traditional software resale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race, with players pursuing upstream control over specialized training infrastructure and downstream embedding into productivity suites to capture recurring revenue.
For Market Incumbents: Anticipate regulatory fragmentation by pre-structuring EU AI Act compliance documentation and FDA 510(k) pathway templates before competitor qualification delays. Secure GPU supply commitments through multi-year foundry allocations. Defend against emerging localized platform competitors in China by accelerating multilingual model deployment through Bhashini dataset partnerships. For New Entrants and Emerging Players: Launch via usage-based API consumption models targeting German Mittelstand manufacturing documentation retrieval, the most penetrable white-space segment. Voice biometric authentication for European PSD2-compliant banking interfaces offers second entry vector. Avoid direct competition with hyperscaler-embedded productivity assistants. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertical voice AI specialists with healthcare FDA clearance progress in the United States and vernacular language coverage in India. Long-term viability hinges on model compression IP and edge deployment partnerships. Watch for SAMR enforcement intensity in China as inflection signal for domestic platform valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Edge NPU Hardware Partnership | Sub-100-millisecond latency enables automotive cabin and manufacturing floor deployments without cloud dependency. |
| Retrieval-Augmented Generation Platform | Real-time policy synchronization eliminates hallucinated regulatory guidance for financial services compliance teams. |
| Indic-Language Dataset Integration | Bhashini infrastructure access unlocks 400-million-user vernacular markets across 22 scheduled languages. |
| EU AI Act Compliance Certification | Transparency documentation accelerates enterprise procurement qualification for high-risk system classifications. |
| Voice Biometric Authentication Module | PSD2-compliant strong customer authentication enables passwordless banking interfaces for European payment providers. |
Research Methodology
Document review covered hyperscaler capex disclosures, FDA 510(k) submission databases, and EU AI Act implementation guidance, complemented by interviews with conversational AI product managers, enterprise IT procurement officers, and regulatory compliance leads at financial institutions. Secondary validation drew from SAMR algorithmic recommendation enforcement notices, Bhashini platform technical documentation, and cloud infrastructure spend reports. Bottom-up deployment estimates triangulated against top-down market sizing across the analysis window.
Cross-referencing historical adoption curves against panel input from platform engineering directors and channel partners shaped the analytical framework. Segmentation dimensions modeled include deployment architecture, organization size, vertical compliance burden, integration complexity, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to token consumption trajectories and seat-based license conversion rates, with edge computing penetration and LLM compression efficiency as key industry-specific inputs.
GPU supply disruption, EU AI Act enforcement variance, and FDA clearance timeline extension are the dominant revision risks to projection outputs. Forecasts reflect documented assumptions on hyperscaler pricing power and enterprise cloud migration velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
AI Datasets Market
Artificial Intelligence (AI)
Autonomous Agents Market
Artificial Intelligence (AI)
Artificial Intelligence-Based Security Market
Artificial Intelligence (AI)
Artificial Intelligence in Robots Market
Artificial Intelligence (AI)
Artificial Intelligence HPC Cloud Market
Artificial Intelligence (AI)
Underwater Autonomous Data Processor Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Life Science Market
Artificial Intelligence (AI)
Cloud Natural Language Processing (NLP) Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Supply Chain Market
Artificial Intelligence (AI)
AI Search Engine Market
Artificial Intelligence (AI)
Artificial Intelligence Systems Spending Market
Artificial Intelligence (AI)
Human-Computer Interaction (HCI) Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Pharmaceutical Market
Artificial Intelligence (AI)
Global Aiops Platform Market
Artificial Intelligence (AI)
Global Computer Assisted Coding Market
Artificial Intelligence (AI)
Connectivity Constraint Computing Market