
 AI Content Creation Tool Market | 2026-2036
AI Content Creation Tool Market Size, Share, and Industry Trends Forecast 2026-2036
AI Content Creation Tool Market Insights
Enterprise marketing campaign deployment is hardening as the dominant revenue vertical for AI content creation tools. Adobe leverages its Creative Cloud ecosystem to sustain creative workflow integration across enterprise studios. OpenAI competes through API-first infrastructure that anchors developer-facing text generation services. Google dominates search-integrated content optimization, extending its advertising technology stack into generative workflows.
AI content creation tools encompass software systems that apply neural network architectures, including transformer and diffusion models, to autonomously produce or augment text, image, video, and audio assets for commercial publishing and communication purposes. These systems process natural language prompts or visual inputs through latent space encoding to generate outputs meeting specified stylistic, tonal, or format parameters. Text generation and image synthesis segments currently occupy the largest installed bases, while multimodal tools represent the fastest-expanding category as users demand unified interfaces spanning media types. Cloud-based and SaaS deployment models control the majority of recurring revenue streams, with API integration emerging as the preferred delivery mechanism for digital agencies embedding generative capabilities into proprietary workflows.
The EU AI Act imposes transparency and risk-classification obligations on automated content systems deployed in European markets, while the FDA and FTC in the United States scrutinize health-related and deceptive AI-generated material through separate enforcement frameworks. China's SAMR and MIIT enforce algorithmic recommendation and deep synthesis provisions that restrict cross-border data training for domestic platforms. Stakeholders must monitor evolving liability allocations between tool providers and end users as jurisdictions refine accountability standards for AI-generated outputs.
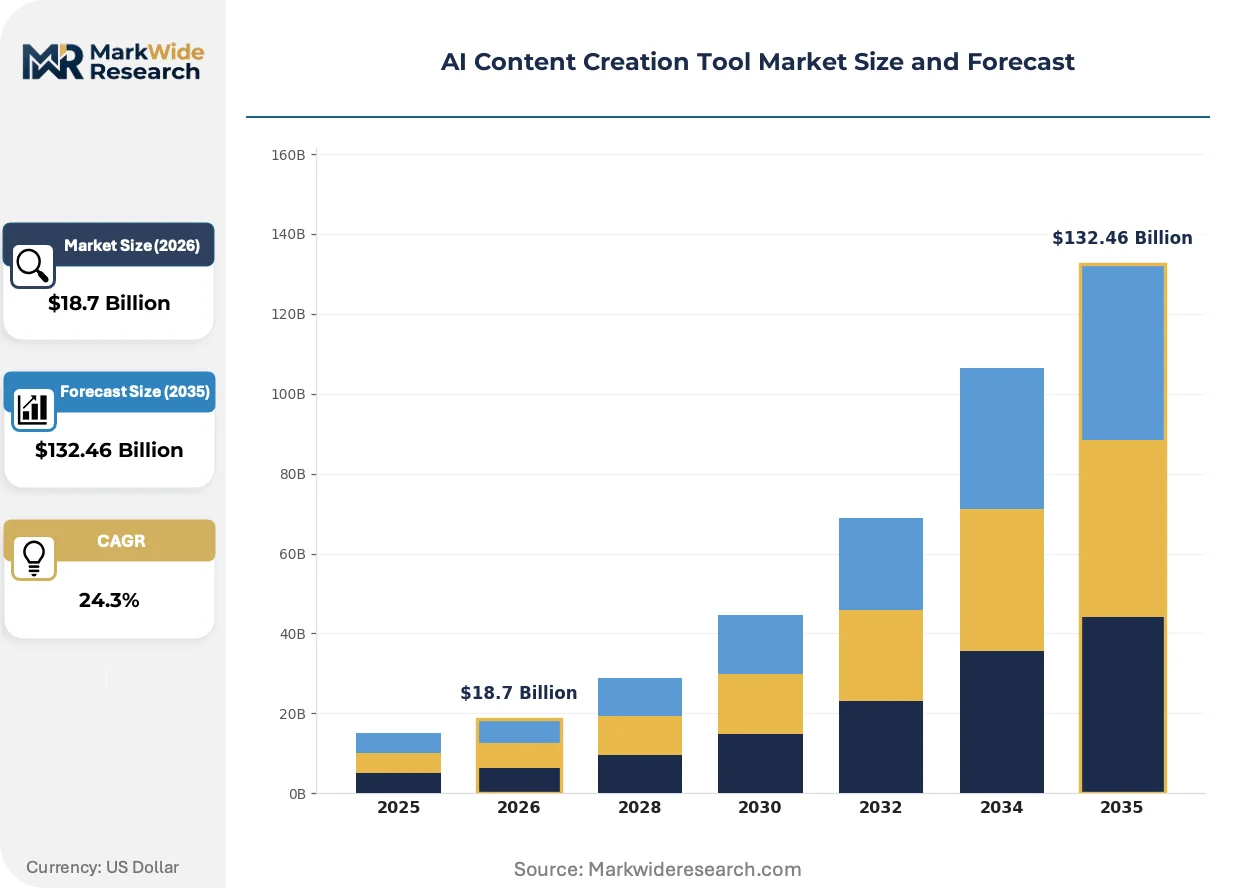
Market Dynamics
Transformer and diffusion model architectures are compressing production timelines for commercial content studios, forcing incumbent platforms to restructure pricing and integration layers around API-first delivery.
Growth Catalysts
- EU AI Act transparency mandates:Compliance requirements for automated content systems are accelerating enterprise procurement of auditable generation platforms across European digital agencies.
- Video editing automation:Neural rendering pipelines are cutting post-production hours for streaming and advertising workflows, pulling demand from traditional editing suites.
- German agency cluster concentration:Berlin and Munich host dense concentrations of creative technology buyers that normalize SaaS subscription models before broader continental adoption.
Market Restraints
- Compute cost volatility:GPU cluster pricing swings and cloud inference tariffs compress margins for API providers serving high-volume text generation workloads.
- Training data licensing friction:Copyright disputes over scraped visual and textual corpora create legal exposure for image synthesis platforms in United States federal courts.
- Synthetic media detection requirements:China's SAMR deep synthesis provisions impose technical compliance burdens that slow cross-border deployment of video generation tools.
Strategic Opportunities
- India's PLI scheme for AI:Domestic data center infrastructure incentives are opening captive deployment models for content tools serving regional language markets.
- Voice-to-video convergence:Unified interfaces combining speech synthesis with avatar generation are creating new product categories for corporate training and customer service verticals.
- Healthcare content compliance:FDA scrutiny of AI-generated medical communications is creating demand for specialized annotation and review workflows among pharmaceutical marketers.
Industry Challenges
- Prompt engineering talent scarcity:Studios struggle to hire specialists who bridge natural language optimization with brand guideline adherence across multimodal outputs.
- Legacy CMS integration complexity:Enterprise marketing teams face months-long reconfiguration cycles when embedding generative APIs into established Adobe or Sitecore publishing stacks.
- Cross-jurisdictional liability allocation:Tool providers and end users dispute accountability for defamatory or infringing AI outputs as courts in multiple countries establish precedent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Content Creation Tool Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $132.46 Billion |
| CAGR (2026 – 2036) | 24.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Text Generation, Image Synthesis, Video Editing, Audio Production, Multimodal Tools Deployment: Cloud-Based, On-Premises, Hybrid, SaaS, API Integration Use Case: Marketing Campaigns, E-Learning Material, Social Media Content, Interactive Storytelling, Corporate Training Customer Type: Digital Agencies, Educational Institutions, Independent Creators, Enterprise Clients, Nonprofit Organizations |
| Companies Covered | Adobe, Canva, OpenAI, Google, Microsoft, Grammarly, Copy.ai, Jasper, Writesonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Content Creation Tool Market Trends and Innovations
Multimodal foundation models are collapsing the boundary between text, image, and video production, forcing vendors to rebuild interfaces around conversational control rather than format-specific tools.
Diffusion-based video generation is rewriting how advertising agencies prototype and finalize commercial spots. Brand teams at consumer packaged goods and automotive manufacturers are adopting these pipelines for rapid concept iteration, compressing the traditional storyboard-to-final-cut timeline from weeks to hours. This acceleration is eroding the competitive position of legacy motion graphics suites that require specialized operator training.
The EU AI Act's risk-classification framework for general-purpose AI models is forcing providers to implement systemic documentation and human oversight protocols. Systems designated as high-risk must maintain audit trails for training data provenance and output logging. Text generation platforms deployed for journalism and financial analysis face the steepest compliance burden, with several vendors restructuring European operations to isolate inference infrastructure within regional cloud zones.
Enterprise procurement teams are unbundling creative software suites and subscribing to specialized generation APIs through direct developer relationships. Media buying departments at Fortune 500 companies now contract separately for text, image, and video capabilities rather than accepting bundled Creative Cloud licensing. This fragmentation is most advanced in the United States, where procurement functions have built internal marketplaces for API credential management and usage tracking.
AI Content Creation Tool Market Segmentation
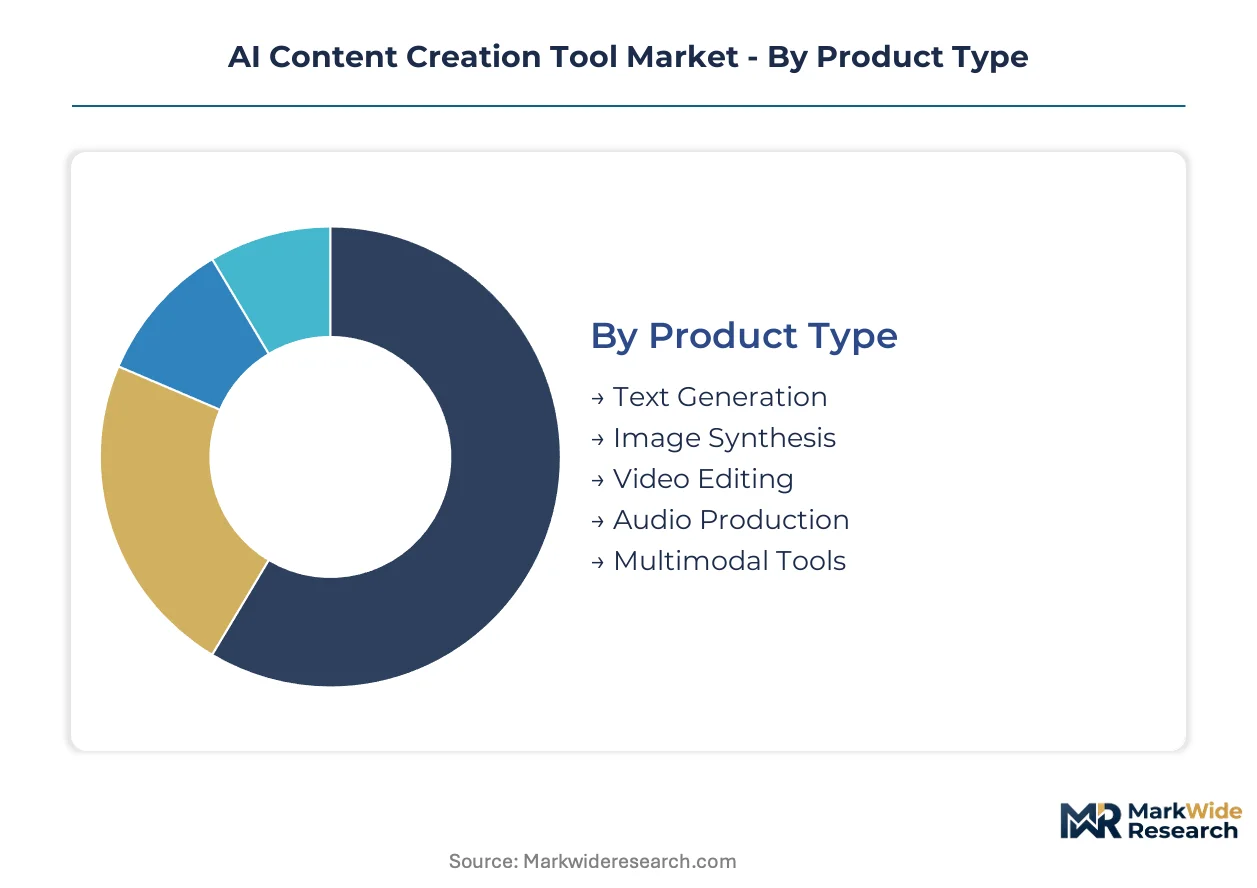
Segmentation reveals how AI content creation tools fragment across technical architectures, delivery mechanisms, and buyer economics. Vendors must align product roadmaps with the divergent infrastructure constraints and workflow integration demands of each slice.
Product Type:
Supply concentrates around transformer-based text engines and diffusion image models, while multimodal architectures are forcing consolidation of previously separate codebases.
- Text Generation:Large language models process natural language prompts through tokenized embeddings to produce marketing copy, code, and long-form documents. Enterprise procurement teams in the United States prioritize API latency and context window depth for high-volume campaign deployment.
- Image Synthesis:Diffusion models encode visual concepts into latent spaces for iterative refinement of brand assets and concept art. German automotive and consumer packaged goods studios drive demand for photorealistic rendering pipelines that compress traditional photography timelines.
- Video Editing:Neural rendering automates post-production workflows for streaming and advertising content.
- Audio Production:Speech synthesis and music generation tools target podcast and voiceover verticals.
- Multimodal Tools:Unified interfaces collapsing text, image, and video generation into conversational control layers.
Text Generation absorbs the bulk of installed capacity; Multimodal Tools is expanding most quickly.
Deployment:
Cost tier stratification separates hyperscaler-hosted inference from captive infrastructure investments by regulated industries.
- Cloud-Based:Third-party GPU clusters deliver elastic compute for variable workloads without capital expenditure. Digital agencies in China leverage domestic cloud zones to satisfy MIIT data localization requirements while maintaining API responsiveness.
- SaaS:Subscription interfaces with pre-built templates dominate mid-market adoption. Educational institutions across Germany normalize per-seat licensing before enterprise procurement teams escalate to API contracts.
- On-Premises:Air-gapped installations serving defense and financial services with strict inference control.
- Hybrid:Split architectures routing sensitive workloads locally and burst capacity to cloud.
- API Integration:Direct developer contracts embedding generation capabilities into proprietary workflows.
SaaS captures the majority of recurring revenue streams; API Integration is climbing the fastest among deployment modes.
Use Case:
Application gravity centers on revenue-generating content pipelines rather than internal corporate communications.
- Marketing Campaigns:Automated generation of display copy, social assets, and video spots across multi-channel sequences. Fortune 500 media buying departments in the United States unbundle creative suites to contract directly with specialized text and image APIs.
- Social Media Content:High-velocity production of platform-optimized assets with format-aware cropping and caption generation. Influencer agencies in China deploy deep synthesis tools under SAMR compliance frameworks for avatar-based broadcasting.
- E-Learning Material:Curriculum-aligned video and assessment generation for scaled education delivery.
- Corporate Training:Scenario-based simulations and multilingual onboarding content.
- Interactive Storytelling:Branching narrative engines for gaming and immersive media.
Marketing Campaigns commands the largest share of vendor revenue; Interactive Storytelling is gaining share fastest as gaming studios adopt generative pipelines.
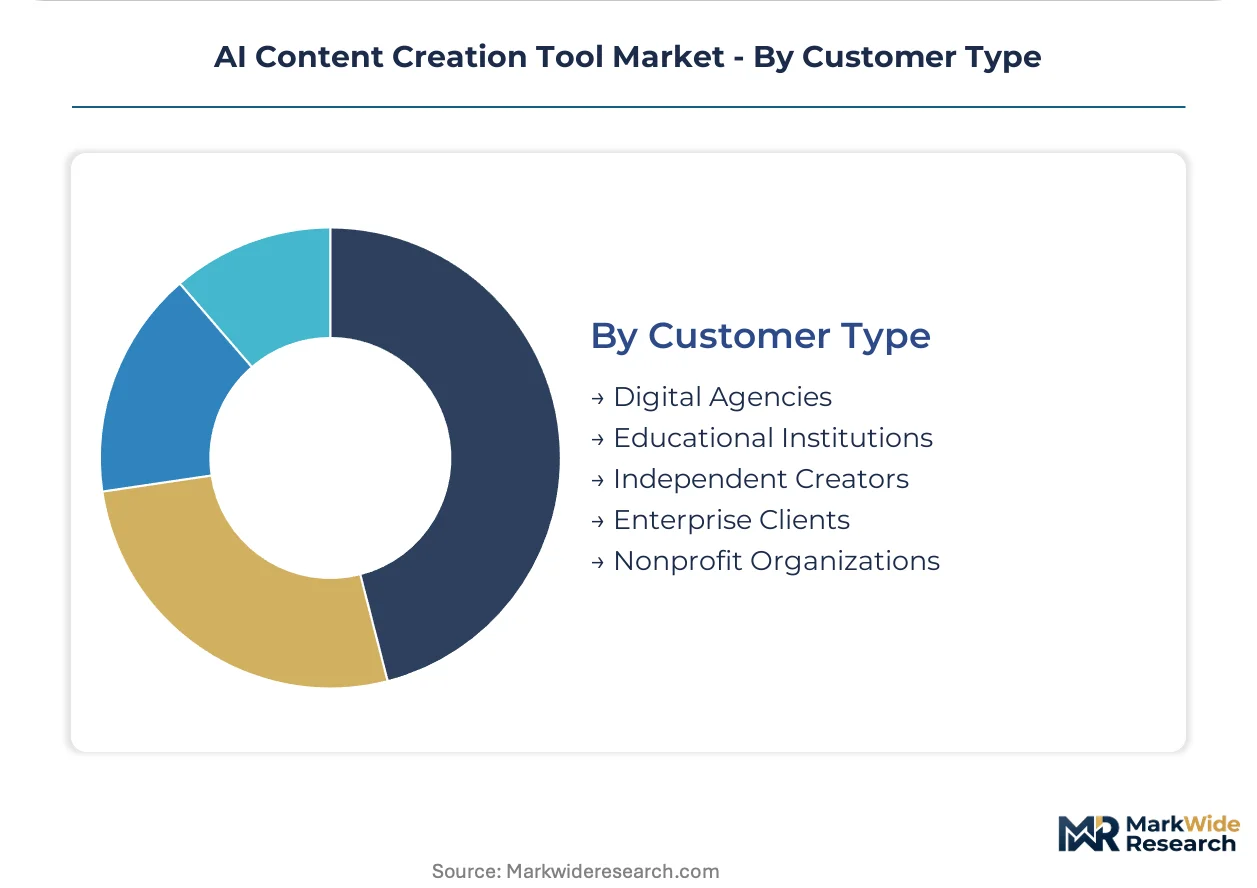
Customer Type:
Margin profiles diverge sharply between price-sensitive independent creators and enterprise clients demanding SLA-backed customization.
- Digital Agencies:Multi-tenant workflows serving brand portfolios with white-labeled generation interfaces. Berlin and Munich agency clusters normalize SaaS subscription economics before broader continental adoption across Germany.
- Enterprise Clients:Dedicated infrastructure with fine-tuned models on proprietary brand guidelines. Pharmaceutical marketers in the United States face FDA scrutiny of AI-generated medical communications, creating demand for specialized review workflows.
- Independent Creators:Individual subscribers prioritizing template simplicity over architectural flexibility.
- Educational Institutions:Volume-discounted licensing for curriculum development and student access.
- Nonprofit Organizations:Grant-funded deployments for advocacy and fundraising content.
Digital Agencies represent the deepest installed base; Enterprise Clients show the steepest expansion trajectory as procurement teams build internal API marketplaces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity for transformer and diffusion models concentrates in the United States and China, while consumption spreads across digital agency clusters in Germany, the United Kingdom, and Japan. Enterprise procurement teams in these markets exhibit divergent compliance priorities shaped by local AI governance frameworks.
United States
Fortune 500 media buying departments unbundle creative suites to contract directly with specialized text and image APIs. The FDA and FTC scrutinize health-related and deceptive AI-generated material through separate enforcement frameworks. New York and San Francisco host dense concentrations of developer-facing platforms that normalize API-first delivery before broader national adoption.
Germany
Automotive and consumer packaged goods studios drive demand for photorealistic rendering pipelines that compress traditional photography timelines. The EU AI Act imposes transparency and risk-classification obligations on automated content systems deployed in European markets. Berlin and Munich agency clusters normalize SaaS subscription economics before broader continental expansion.
China
Domestic platforms face algorithmic recommendation and deep synthesis provisions that restrict cross-border data training. SAMR and MIIT enforce technical compliance burdens that slow deployment of video generation tools. Beijing and Shenzhen technology infrastructure hosts the largest concentrations of multimodal foundation model development outside the United States.
United Kingdom
Digital agencies serving transnational brand portfolios prioritize auditable generation platforms to satisfy EU AI Act transparency mandates for European campaign deployment. The Information Commissioner's Office coordinates with EU regulators on cross-border enforcement of automated decision-making rules. London's financial services sector generates specialized demand for compliance-bound text generation in regulatory reporting workflows.
Japan
Corporate training and customer service verticals create demand for voice-to-video convergence combining speech synthesis with avatar generation. METI promotes domestic AI infrastructure investment through public-private partnerships targeting regional language markets. Tokyo and Osaka enterprise procurement teams favor hybrid deployment models routing sensitive workloads locally while bursting capacity to cloud.
AI Content Creation Tool Market Competitive Landscape
Top-tier vendors anchor the hyperscaler and creative cloud ecosystems, while mid-tier specialists compete through API-first infrastructure and vertical-specific templates. The market structure exhibits tiered consolidation around three to four dominant platform ecosystems with fragmented competition among specialized generation tools. Strategic archetypes include creative suite incumbents extending existing workflows, foundation model providers monetizing through developer APIs, and vertical specialists targeting marketing campaign automation. Competitive moves center on unbundling bundled software suites and restructuring pricing around consumption-based API metering.
Among creative cloud incumbents, Adobe and Canva occupy positions exemplifying ecosystem-anchored competitive strategy. OpenAI represents the foundation model archetype through API-first infrastructure that anchors developer-facing text generation services. Google sits within the search-integrated optimization tier, extending advertising technology stacks into generative workflows.
| Leading Market Players |
|---|
| Adobe |
| Canva |
| OpenAI |
| Microsoft |
| Grammarly |
| Copy.ai |
| Jasper |
| Writesonic |
| Others |
Pricing and Supply Chain Analysis
GPU cluster spot pricing indices cascade through cloud inference tariffs into SaaS subscription tiers, forcing API providers to restructure metering models as compute cost volatility compresses margins for high-volume text generation workloads.
Pricing Analysis
Cost-down pressure on enterprise API tiers accelerates because hyperscaler GPU allocation constraints favor volume-commitment contracts over elastic consumption. Three-tier pricing structure across premium SLA-backed, standard developer, and economy self-serve levels separates latency guarantees from throughput limits. Price differentiation hinges on context window depth and fine-tuning permissions. Independent creators exhibit highest price sensitivity; pharmaceutical marketers facing FDA scrutiny accept premium tiers for audit-trail compliance.
Supply Chain Analysis
NVIDIA H100 and A100 supply rests on Taiwan Semiconductor Manufacturing and South Korean memory fabricators, with final assembly concentrating in Malaysia and Mexico. Raw material dependencies span advanced photolithography equipment, high-bandwidth memory stacks, and rare earth elements for magnetics. Single-source vulnerability around TSMC's leading-edge nodes creates chokepoint exposure for foundation model training clusters. Distribution runs through hyperscaler cloud marketplaces and direct enterprise procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around API-first infrastructure as compute cost volatility and regulatory compliance burdens force subscale providers toward acquisition or exit.
For Market Incumbents: Deploy fine-tuned model marketplaces to lock enterprise clients into proprietary data loops, insulating against OpenAI's developer-facing API dominance. Acquire specialized annotation workflows serving FDA-scrutinized pharmaceutical marketers before vertical specialists capture compliance-bound premiums. Expand inference infrastructure into EU regional cloud zones to satisfy AI Act data residency mandates. For New Entrants and Emerging Players: Mid-market digital agencies in India and Southeast Asia present underserved buyer archetypes seeking regional-language generation tools outside hyperscaler ecosystems. Voice-to-video convergence for corporate training verticals offers penetrable white-space with lower foundation model capital requirements than general-purpose text generation. Pursue PLI scheme partnerships for captive data center deployment. For Investors and Strategic Acquirers: The window for entry favors vertical specialists with healthcare or automotive compliance workflows over horizontal text generation platforms facing margin compression. Long-term viability centers on proprietary training data moats and enterprise SLA relationships rather than API consumption arbitrage. Watch hyperscaler capex allocation shifts as inflection indicator for GPU supply tightness.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Adobe's Creative Cloud embedding positions incumbents against developer-centric challengers. |
| Regional Inference Infrastructure | EU cloud zone expansion satisfies AI Act data localization for European agency clients. |
| Vertical Compliance Workflows | FDA-annotation tooling captures pharmaceutical marketing budgets requiring audit trails. |
| Multimodal Foundation Model Development | Unified text-image-video interfaces collapse separate tool procurement decisions. |
| Strategic Partnership with Hyperscalers | Preferred GPU allocation agreements secure capacity ahead of spot market volatility. |
Research Methodology
Multi-period observation of API pricing disclosures, hyperscaler capex trajectories, and EU regulatory filing timelines anchored the trend analysis, supplemented by interviews with platform engineering leads at digital agencies, enterprise procurement officers, compliance specialists at pharmaceutical marketers, and CTOs at creative technology studios. Secondary validation drew from SEC 10-K infrastructure spend disclosures, EU AI Act implementation guidance, MIIT algorithmic filing records, and cloud provider earnings transcripts. Bottom-up deployment estimates triangulated against top-down market sizing.
Segment-weighting across product type, deployment mode, use case, and customer archetype informed the analytical framework, with CAGRs derived from adoption curve modeling and price elasticity assumptions. Inputs included transformer model parameter scaling rates, diffusion inference cost decline curves, and regional cloud infrastructure buildout schedules across the analysis window.
Revisions become necessary when hyperscaler GPU supply constraints ease substantially, EU AI Act enforcement intensity shifts, or foundation model commoditization accelerates beyond current pricing compression trends. A small set of named triggers—hyperscaler capex reallocation, major copyright liability rulings, and cross-border data training restrictions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
AI in Life Sciences Market
Artificial Intelligence (AI)
AI Platform Market
Artificial Intelligence (AI)
Model Validation and Automation Market
Artificial Intelligence (AI)
Artificial Intelligence Based Personalization Market
Artificial Intelligence (AI)
North America and Europe Chatbot Market
Artificial Intelligence (AI)
Permission-Aware AI Repository Gateway Market
Artificial Intelligence (AI)
AI Watermarking Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Social Media Market
Artificial Intelligence (AI)
Human-Computer Interaction (HCI) Market
Artificial Intelligence (AI)
Cloud Natural Language Processing (NLP) Market
Artificial Intelligence (AI)
Explainable AI Market
Artificial Intelligence (AI)
Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
Affective Computing Market
Artificial Intelligence (AI)
Global AI in Telecommunication Market
Artificial Intelligence (AI)
GCC Artificial Intelligence Market
Artificial Intelligence (AI)
Automotive Gesture Recognition Market