
 Explainable AI Market | 2026-2036
Explainable AI Market Size, Share, and Industry Trends Forecast 2026-2036
Explainable AI Market Insights
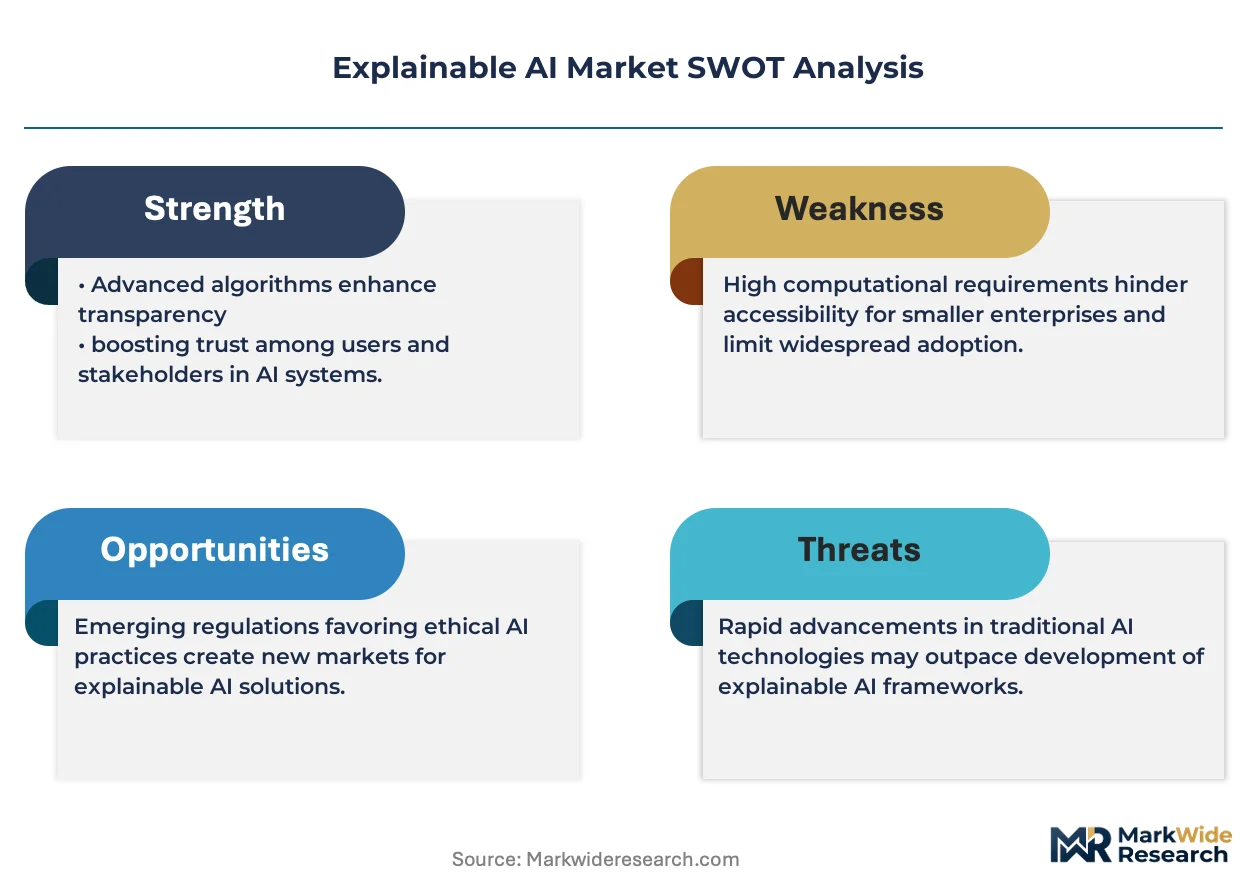
The supply of AI ethics specialists and interpretability engineers is collapsing across North America and Europe, creating acute bottlenecks for enterprises scaling transparent machine learning systems. IBM leverages its Watson OpenScale platform to anchor trust-and-compliance workflows for regulated industries. Google dominates research output in attention-based explanation methods through its DeepMind and Google Research divisions. NVIDIA sustains hardware-software co-design for real-time inference interpretability across its DGX and Jetson product lines.
Explainable AI denotes algorithmic systems engineered to render their decision logic interpretable to human operators through post-hoc attribution maps, surrogate model distillation, or inherently transparent rule structures such as decision trees and generalized additive models. SHAP and LIME frameworks compute feature importance scores by approximating local decision boundaries around individual predictions, enabling clinicians and loan officers to audit specific outcomes rather than black-box aggregates. Model-agnostic explanation technologies capture the widest margin pools because they retrofit interpretability onto existing neural architectures without retraining. Healthcare and finance applications lead current deployment volumes, though retail demand for transparent recommendation engines is accelerating fastest as consumer protection litigation expands.
The EU AI Act imposes mandatory transparency obligations on high-risk AI systems, compelling vendors to document training data provenance and provide user-facing explanation interfaces before CE marking authorization. The US FDA and NHTSA are drafting parallel guidance for AI-enabled medical devices and autonomous vehicle decision logs, tightening market access for non-compliant platforms. Stakeholders must monitor whether emerging national AI safety institutes in the United Kingdom, Singapore, and Japan converge on interoperable audit standards or fragment into incompatible compliance regimes.
Market Dynamics
The EU AI Act's mandatory transparency obligations for high-risk systems are compressing deployment timelines, forcing enterprises to retrofit interpretability onto existing neural architectures or face market exclusion.
Growth Catalysts
- EU AI Act compliance deadlines:High-risk AI systems in finance and healthcare must achieve CE marking with documented training data provenance and user-facing explanation interfaces.
- Autonomous vehicle safety audits:NHTSA guidance for decision-log transparency in self-driving systems creates procurement pull from automotive manufacturers.
- SHAP framework maturation:Model-agnostic attribution methods enable retrofitting onto production neural networks without retraining cycles.
Market Restraints
- AI ethics specialist scarcity:Interpretability engineer supply is collapsing across Germany and the United States, inflating compensation and delaying project ramps.
- Hardware-software co-design costs:Real-time inference interpretability requires DGX-class infrastructure that mid-tier enterprises cannot provision.
- Fragmented audit standards:Divergent national AI safety institute mandates in Singapore, Japan, and the United Kingdom risk incompatible compliance regimes.
Strategic Opportunities
- Retail recommendation transparency:Consumer protection litigation is accelerating demand for auditable product suggestion algorithms.
- Medical device explainability:FDA draft guidance for AI-enabled diagnostics creates first-mover advantage for vendors with validated explanation interfaces.
- Edge deployment interpretability:Jetson-class hardware is miniaturizing attribution computation for industrial automation sensors.
Industry Challenges
- Post-hoc explanation latency:LIME and SHAP computations add inference overhead that violates real-time constraints in high-frequency trading and emergency medicine.
- Cross-border data governance:Training data provenance documentation conflicts with GDPR anonymization requirements in multi-jurisdictional deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Explainable AI Market |
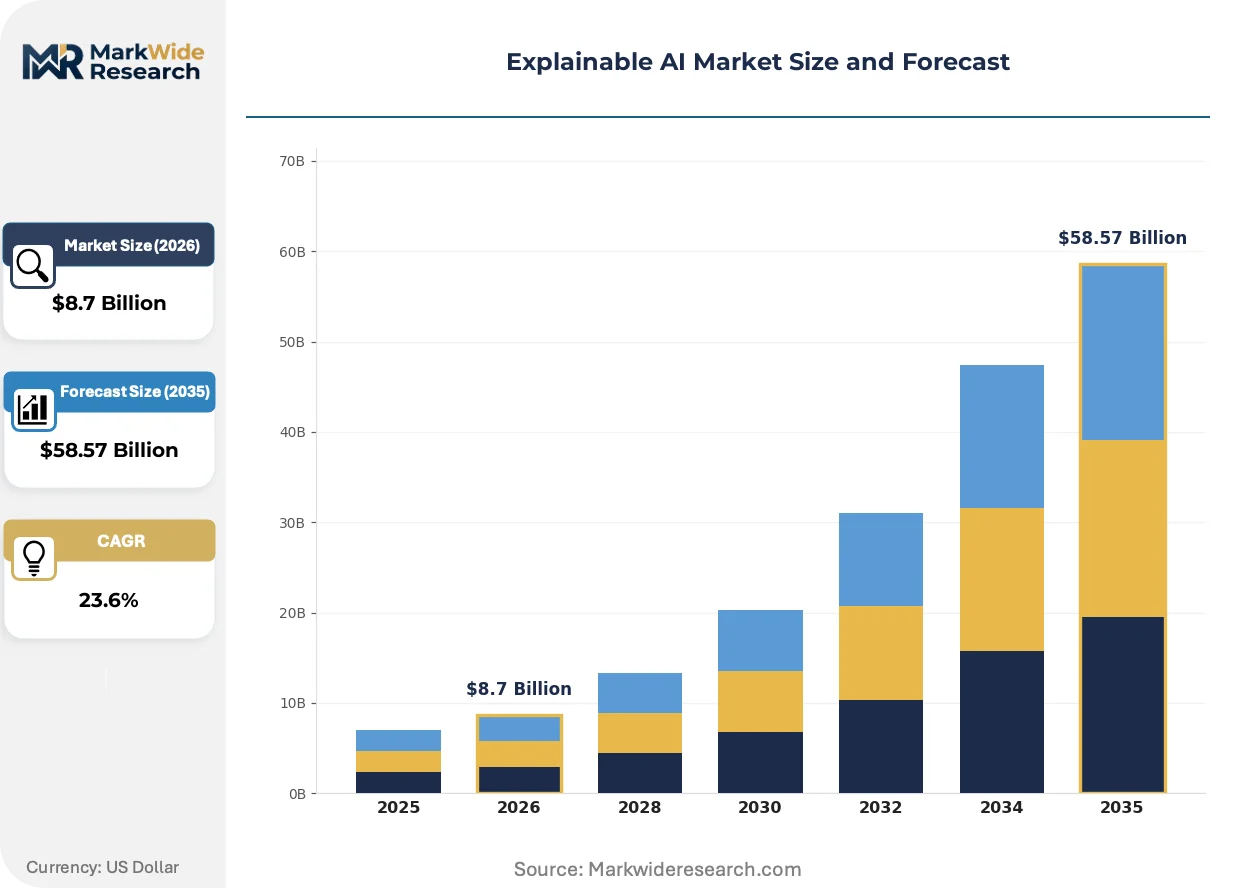
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $58.57 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Model-Agnostic, LIME, SHAP, Rule-Based Application: Healthcare, Finance, Retail, Security End User: Enterprises, Researchers, Government, Academia Deployment: On-Premise, Cloud-Based, Hybrid, Edge |
| Companies Covered | Microsoft, IBM, Google, DataRobot, Amazon Web Services, NVIDIA, Salesforce, Alteryx, Arthur.ai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Explainable AI Market Trends and Innovations
Attention-based explanation methods are displacing gradient-based attribution in production systems, while regulatory pressure is forcing convergence between research-grade interpretability and enterprise audit requirements.
Counterfactual explanation generation is miniaturizing from cloud clusters to edge devices, enabling real-time "what-if" scenario testing for loan officers and clinicians. Automotive manufacturers in Stuttgart and Wolfsburg are piloting these methods for autonomous vehicle incident reconstruction. The compression of explanation latency from seconds to milliseconds is opening deployment in high-frequency decision environments previously closed to interpretability overlays.
The EU AI Act's risk classification system is forcing vendors to pre-certify explanation interfaces before market entry, not after deployment. This front-loads compliance costs but creates defensible moats for prepared vendors. Medical device manufacturers are responding by embedding explanation modules at the architecture stage rather than retrofitting post-hoc.
Buyers in financial services are unbundling interpretability from core AI procurement, demanding standalone explanation audits from third-party validators. This displaces vendor self-attestation with independent certification. German automotive clusters and London-based trading desks are driving this shift, treating explainability as a separable service line with distinct contracting terms.
Explainable AI Market Segmentation
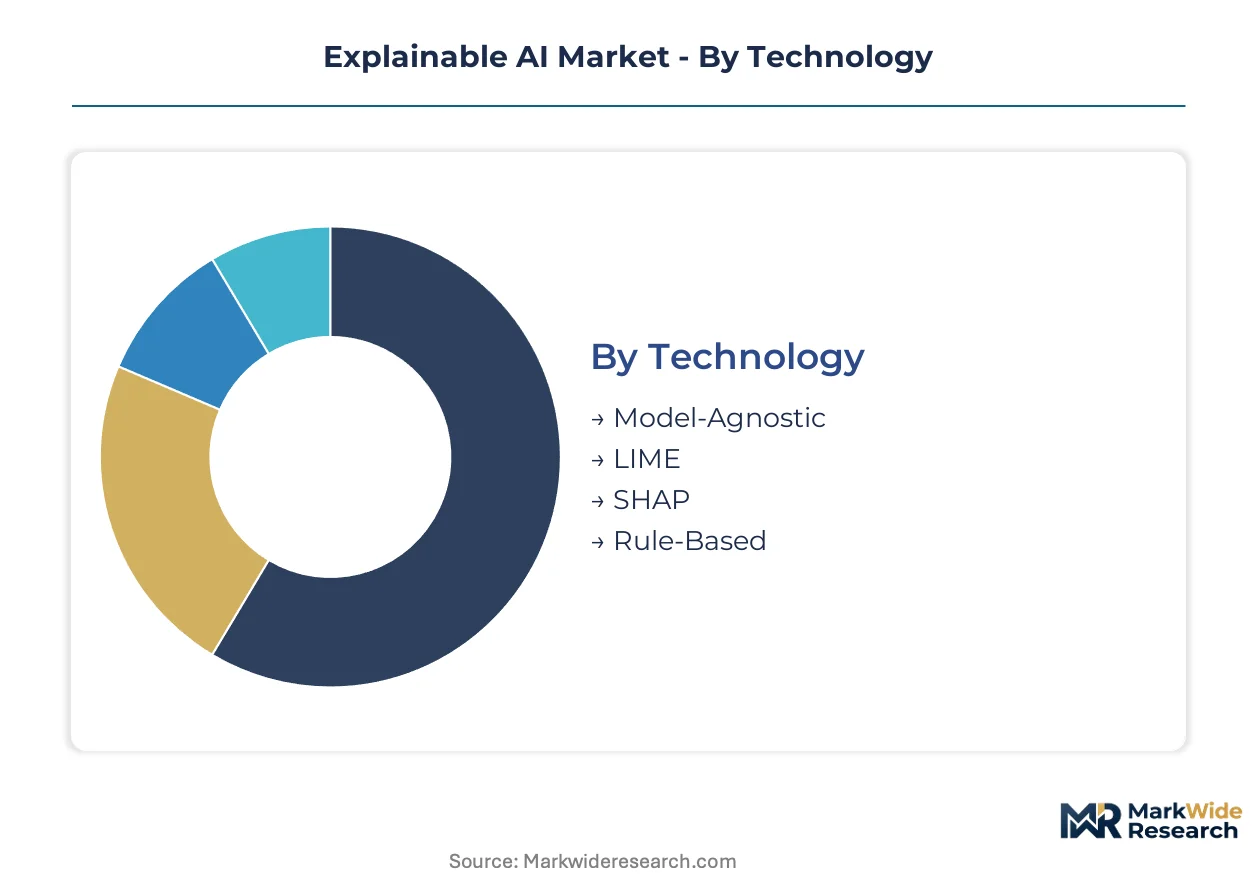
Explainable AI segmentation reveals divergent procurement patterns across regulatory environments and technical maturity levels. Technology choices determine retrofit feasibility for legacy neural architectures, while deployment modes reflect infrastructure constraints and latency requirements.
Technology:
Geographic demand splits sharply between jurisdictions mandating retrofit compatibility and those favoring greenfield transparent architectures.
- Model-Agnostic:These frameworks retrofit interpretability onto existing neural networks without architecture modification or retraining cycles. Financial services procurement in Germany and the United States concentrates here, driven by EU AI Act compliance deadlines for legacy high-risk systems.
- SHAP:Shapley additive explanations compute feature contributions through cooperative game theory, delivering consistent attribution across model types. Healthcare diagnostics deployment in the United States accelerates fastest, pressured by FDA draft guidance requiring validated explanation interfaces for AI-enabled devices.
- LIME:Local interpretable model-agnostic explanations approximate decision boundaries through perturbed sampling.
- Rule-Based:Inherently transparent decision trees and generalized additive models satisfy strictest audit requirements.
Model-Agnostic holds the largest share; momentum sits with SHAP.
Application:
Cost-tier stratification separates premium compliance-driven procurement from efficiency-motivated adoption.
- Healthcare:Clinicians audit individual diagnostic predictions through attribution overlays, satisfying FDA and EMA transparency expectations for AI-enabled medical devices. German university hospitals and United States academic medical centers drive procurement volume.
- Finance:Loan officers document algorithmic decision logic for regulatory examination, with EU AI Act CE marking requirements compressing deployment timelines. London and Frankfurt trading desks prioritize real-time explanation latency.
- Retail:Consumer protection litigation accelerates demand for auditable recommendation engines.
- Security:Threat detection systems require explainable alerts to reduce false positive operational burden.
Healthcare commands premium pricing; retail climbs the fastest.
End User:
Customer-type segmentation reflects divergent technical capabilities and procurement authority structures.
- Enterprises:Regulated industries—financial services, automotive, pharmaceuticals—procure at scale to satisfy EU AI Act, FDA, and NHTSA mandates. Compliance departments now hold budget authority previously residing in IT.
- Researchers:Academic institutions advance attention-based and counterfactual explanation methods, with DeepMind and Google Research dominating publication output.
- Government:National AI safety institutes in Singapore, Japan, and the United Kingdom establish audit standards and certification requirements.
- Academia:University laboratories train the shrinking supply of interpretability engineers.
Enterprises dominate procurement volume; government segment shows steepest expansion trajectory.
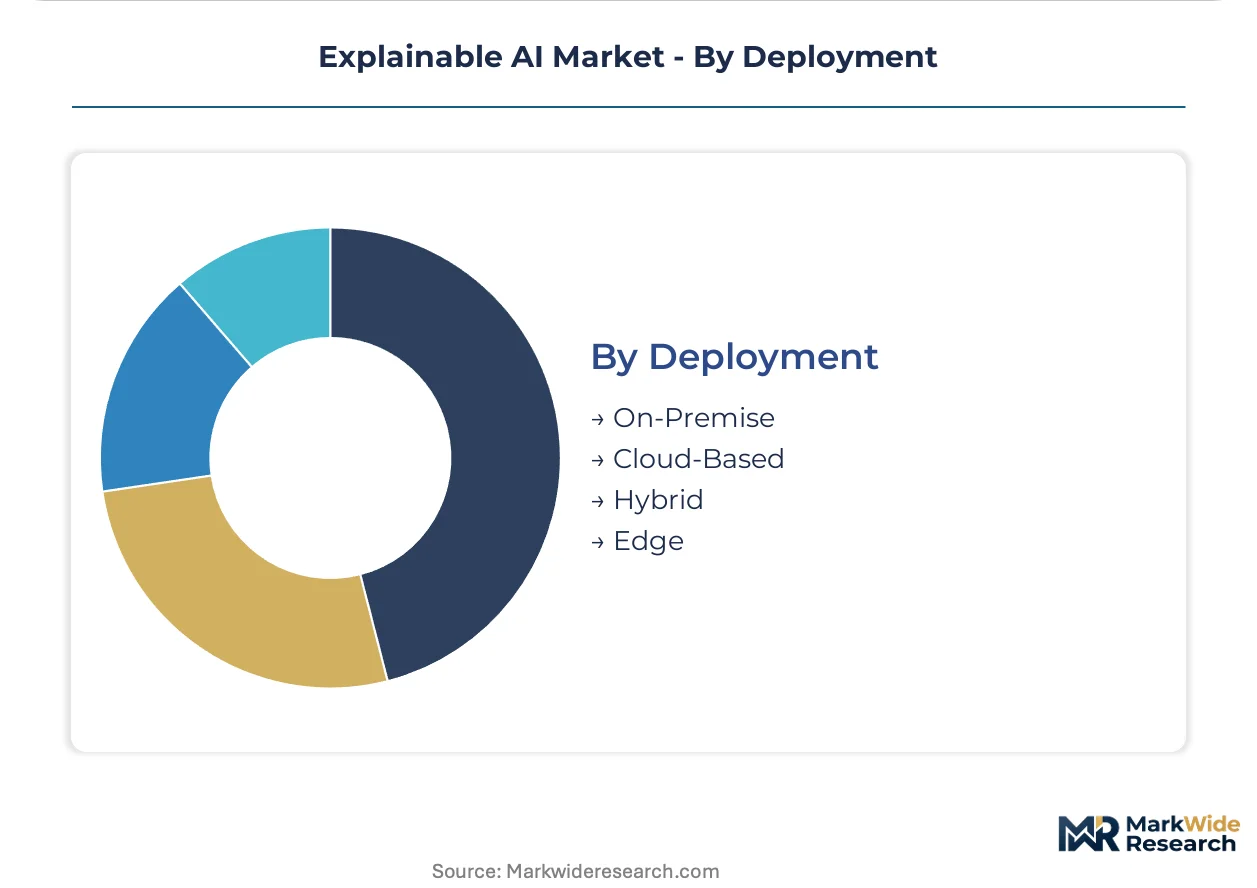
Deployment:
Infrastructure maturity determines feasible explanation latency and data sovereignty compliance.
- Cloud-Based:Centralized attribution computation serves batch analytics and model development workflows. Mid-tier enterprises lacking DGX-class infrastructure default here despite data residency concerns.
- Edge:Jetson-class hardware miniaturizes SHAP and counterfactual computation for industrial automation sensors and autonomous vehicle incident reconstruction. Stuttgart and Wolfsburg automotive clusters pilot real-time explanation at the network edge.
- On-Premise:Air-gapped deployments satisfy financial services data governance requirements.
- Hybrid:Split architectures process sensitive data locally while leveraging cloud for model training.
Cloud-Based holds installed base leadership; edge deployment gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes explainable AI primarily for automotive compliance and industrial automation audit trails, while the United States drives healthcare diagnostics transparency and financial services regulatory documentation. Japan concentrates on manufacturing quality assurance, and Singapore anchors Southeast Asian fintech governance standards. China pursues smart city algorithmic accountability at municipal scale.
United States
FDA draft guidance for AI-enabled medical devices and NHTSA autonomous vehicle decision-log requirements propel procurement across healthcare and automotive sectors. Academic medical centers in Boston and Stanford accelerate SHAP framework validation for clinical diagnostics. Trading desks in Chicago and New York prioritize sub-millisecond explanation latency for algorithmic compliance documentation.
Germany
EU AI Act CE marking mandates for high-risk financial and industrial systems compress deployment timelines for legacy neural architectures. Stuttgart and Wolfsburg automotive clusters pilot real-time counterfactual explanation at the network edge for autonomous vehicle incident reconstruction. Frankfurt trading floors demand auditable algorithmic decision logic under BaFin examination protocols.
United Kingdom
The national AI safety institute establishes audit standards that diverge from EU AI Act specifications, creating compliance complexity for cross-border deployments. London-based financial services firms unbundle interpretability from core AI procurement, mandating standalone third-party explanation audits. Oxford and Cambridge research laboratories advance attention-based explanation methods for regulatory submission.
Japan
METI guidelines for manufacturing AI transparency drive demand for interpretable quality control systems in automotive and electronics supply chains. Nagoya industrial automation clusters deploy edge-based SHAP computation for real-time defect attribution. Tokyo financial institutions prepare explanation interfaces for anticipated FSA algorithmic accountability mandates.
Singapore
The Monetary Authority of Singapore's AI governance framework compels fintech vendors to provide user-facing explanation interfaces for credit scoring and fraud detection systems. The national AI safety institute pilots interoperable audit standards with Japan and the United Kingdom. Marina Bay financial technology clusters procure model-agnostic interpretability tools for cross-jurisdictional compliance.
Explainable AI Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with cloud hyperscalers and semiconductor platforms commanding infrastructure-dependent workflows while vertical-focused vendors capture compliance-driven niches. The market structure reflects dual competitive axes: horizontal platform breadth versus vertical regulatory depth, and real-time inference capability versus batch explanation audit trails. Dominant archetypes include cloud-native AI service providers, hardware-software co-design specialists, and model-agnostic interpretability pure-plays. Competitive moves concentrate on strategic partnerships between semiconductor and cloud platforms, and portfolio diversification into edge deployment modalities.
Within the integrated platform tier, Microsoft and Google exemplify cloud-native AI service provision, anchoring enterprise trust-and-compliance workflows through native explanation toolchains. IBM occupies a position bridging legacy enterprise systems and emerging regulatory mandates, representing the vertical compliance depth archetype. NVIDIA sits within the hardware-software co-design specialist category, with its platform approach spanning data center and edge inference environments.
| Leading Market Players |
|---|
| Microsoft |
| IBM |
| DataRobot |
| Amazon Web Services |
| NVIDIA |
| Salesforce |
| Alteryx |
| Arthur.ai |
| Others |
Pricing and Supply Chain Analysis
Ninety-day lead times for DGX-class GPU clusters concentrate pricing power with NVIDIA and cloud hyperscalers, while mid-tier enterprises face cost compression from hardware-software co-design requirements. This supply constraint feeds directly into tiered SaaS pricing that separates compliance-ready platforms from basic attribution tools.
Pricing Analysis
Long-term enterprise offtake agreements dominate procurement for regulated financial services and healthcare buyers, while spot consumption serves research and development workloads. Three-tier pricing structure across premium, standard, and economy levels separates CE-marking-ready platforms with validated explanation interfaces from uncertified developer tools. Price differentiation hinges on certification grade—FDA-validated medical device modules command substantial premiums over generic SHAP implementations—and vertical integration depth. Pricing pressure stems from AI ethics specialist scarcity inflating implementation costs. Mid-tier enterprises exhibit highest price sensitivity, deferring edge deployment until Jetson-class hardware costs compress.
Supply Chain Analysis
Strait of Malacca transit routes for NVIDIA's Taiwan-fabricated GPUs create chokepoint vulnerability for real-time inference interpretability stacks. Supply concentrates in Taiwan for advanced semiconductors, the United States for cloud infrastructure, and Germany for automotive edge hardware. Component dependencies include HBM memory modules, specialized AI accelerators, and proprietary CUDA software ecosystems. Single-source vulnerability runs through NVIDIA's dominant position in training and inference silicon. Distribution runs through direct enterprise sales for large financial services contracts and cloud marketplaces for mid-market SaaS adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Explainable AI sits in early-cycle expansion as EU AI Act compliance deadlines force retrofit procurement onto legacy neural architectures across high-risk system deployments.
For Market Incumbents: Shield market position by embedding explanation modules at architecture design stage rather than post-hoc retrofit, neutralizing specialist engineering bottlenecks. Deepen certification investment for FDA and CE marking pathways to create regulatory moats against unvalidated entrants. Vertical integration into edge hardware-software stacks captures automotive and industrial automation demand migrating from cloud to Jetson-class deployment.
For New Entrants and Emerging Players: Differentiate on counterfactual explanation latency for high-frequency trading and emergency medicine applications where incumbents face inference overhead constraints. Target retail recommendation transparency as the fastest-climbing segment with lowest incumbent saturation. Pursue standalone third-party audit services as financial services buyers unbundle interpretability from core AI procurement.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because divergence between EU AI Act, FDA, and national AI safety institute standards creates recurring compliance expenditure. Acquisition focus should center on model-agnostic interpretability pure-plays with validated healthcare and financial services deployments. Monitor convergence or fragmentation of UK, Singapore, and Japanese audit standards as the critical inflection signal for platform consolidation versus specialization strategies.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pre-Certification | Front-loaded compliance investment creates defensible market exclusion barriers under EU AI Act mandates. |
| Edge Hardware-Software Co-Design | Jetson-class miniaturization opens autonomous vehicle and industrial sensor deployment previously closed to cloud-only vendors. |
| Third-Party Audit Service Launch | London and Frankfurt financial services procurement now mandates independent explanation validation displacing vendor self-attestation. |
| SHAP Framework Optimization | Sub-millisecond attribution computation satisfies BaFin and NHTSA real-time decision-log requirements for trading and automotive. |
| Academic Partnership Programs | Oxford and Cambridge attention-based research pipelines feed regulatory submission pathways for FDA and EMA. |
Research Methodology
Initial hypotheses were tested against primary input from AI ethics officers, interpretability engineers, compliance directors at financial institutions, and biomedical informaticists at academic medical centers and refined through secondary validation. Primary fieldwork drew from regulatory affairs leads at medical device manufacturers and procurement managers at German automotive clusters. Secondary sources encompassed FDA draft guidance documents, EU AI Act implementing texts, NHTSA autonomous vehicle decision-log proposals, and hyperscaler AI infrastructure capex disclosures. Bottom-up deployment volume estimates triangulated against top-down regulatory mandate sizing across the analysis window.
Variance decomposition across technology, application, end user, and deployment mode segments anchored the analytical framework. Modeled dimensions spanned model-agnostic versus inherently transparent architectures, healthcare versus finance versus retail verticals, enterprise versus researcher versus government customer types, and cloud versus edge versus on-premise infrastructure. CAGRs were derived from segment-level adoption curves weighted by compliance deadline proximity. Industry-specific inputs included EU AI Act CE marking timeline assumptions and FDA guidance finalization trajectories.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement or accelerated standard harmonization would require recalibration. Forecasts reflect documented assumptions regarding specialist labor supply elasticity and semiconductor availability. Practitioners should keep alternative scenarios live as national AI safety institute mandate divergence and GPU supply chain resilience evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
AI Watermarking Market
Artificial Intelligence (AI)
Smart Home Digital Assistant [Voice] Market
Artificial Intelligence (AI)
Multimodal AI Market
Artificial Intelligence (AI)
AI in Construction Market
Artificial Intelligence (AI)
Cognitive Systems Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Construction Market
Artificial Intelligence (AI)
Commercial Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence in Big Data Analysis Market
Artificial Intelligence (AI)
North America Chatbot Market
Artificial Intelligence (AI)
Legal AI Market
Artificial Intelligence (AI)
Global Legaltech Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Home AI Oven Market
Artificial Intelligence (AI)
Global Voice Assistant Application Market
Artificial Intelligence (AI)
AI in Life Sciences Market
Artificial Intelligence (AI)
Legal AI Software Market
Artificial Intelligence (AI)
Artificial Neural Network Market