
 North America Data Center Robotics Market | 2026-2036
North America Data Center Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Data Center Robotics Market Analytics
Direct sales and systems integration channels are rewriting how robotics vendors access hyperscale data center operators. ABB Group leverages its industrial automation heritage to anchor large-scale motor and drive installations across Texas and Arizona facilities. Microsoft Corporation sustains internal robotics development for Azure data center operations, competing directly with external vendors on maintenance automation. Amazon Web Services, Inc. controls its supply chain through in-house production of mobile robots for inventory tracking and server rack movement.
North America data center robotics encompasses autonomous and semi-autonomous mechanical systems engineered for 24/7 operation in controlled environments with ambient temperatures between 18°C and 27°C, performing server handling, thermal management, and security patrol functions. These systems integrate servo motors, LiDAR sensors, and programmable logic controllers to execute repetitive tasks with sub-millimeter precision in aisle widths as narrow as 600mm. Automated Guided Vehicles dominate capital deployment for inventory management and rack transport, while Collaborative Robots capture expanding margin pools in server maintenance applications requiring human-robot task sharing. Artificial Intelligence and Computer Vision segments are growing fastest as operators demand predictive fault detection and real-time anomaly recognition across multi-megawatt facilities.
OSHA workplace safety standards and FCC equipment authorization requirements shape robot design specifications and deployment protocols for U.S. data center operators. The EPA's ENERGY STAR program and emerging state-level carbon disclosure rules in California and Washington are forcing vendors to document power consumption and lifecycle emissions for robotic fleet proposals. Stakeholders must monitor how NIST's evolving cybersecurity frameworks for operational technology will reshape access control and software update requirements for connected robotics platforms.
Market Dynamics
Hyperscale operators in the United States and Canada are compressing deployment timelines for robotic fleets as labor scarcity in Northern Virginia's data center corridor intensifies. Capital allocation now favors integrated automation platforms over point solutions.
Growth Catalysts
- EPA ENERGY STAR certification:Procurement standards for data center equipment now mandate documented power efficiency, accelerating replacement of legacy server handling systems with servo-optimized robotics.
- LiDAR sensor cost curves:Component price compression below $500 per unit enables fleet-scale deployment of autonomous navigation across Dallas-Fort Worth facilities.
- NIST cybersecurity frameworks:Operational technology mandates for connected robotics platforms create compliance-driven refresh cycles in multi-tenant colocation environments.
Market Restraints
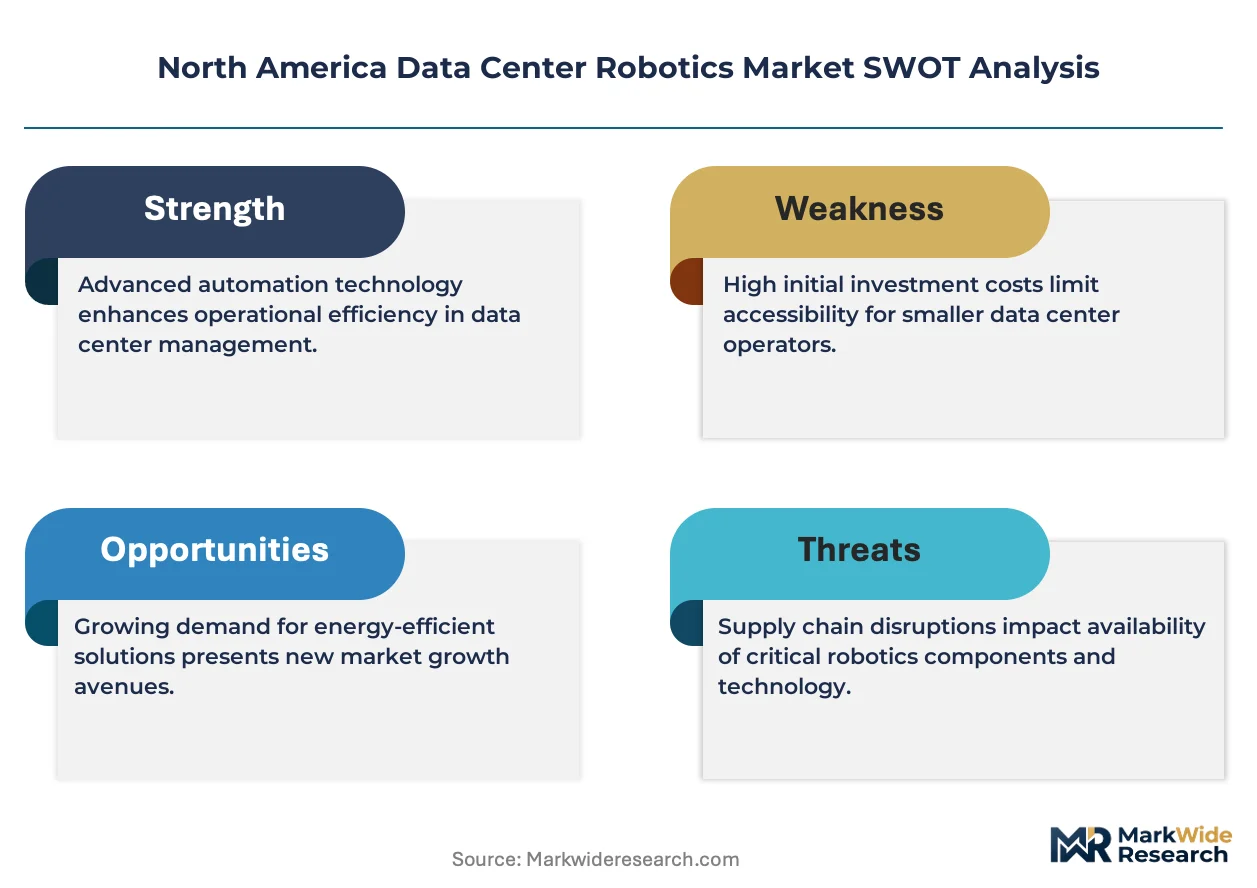
- Rare earth magnet supply concentration:Permanent magnet motors depend on neodymium processing concentrated outside North America, exposing servo motor costs to geopolitical friction.
- OSHA workplace safety standards:Collaborative robot deployment protocols require extensive facility modification, extending commissioning timelines in existing brownfield data centers.
- Technical limitation in narrow aisles:Automated Guided Vehicles face maneuvering constraints below 600mm aisle widths, restricting automation penetration in legacy rack configurations.
Strategic Opportunities
- Canada's carbon disclosure rules:Emerging provincial mandates in British Columbia and Ontario create first-mover advantage for vendors documenting lifecycle emissions in robotic fleet proposals.
- Artificial Intelligence convergence with Computer Vision:Predictive fault detection systems unlock premium pricing for maintenance automation contracts in multi-megawatt facilities.
- Direct sales channel innovation:Systems integration partnerships with electrical contractors bypass traditional distribution, capturing margin in Texas and Arizona greenfield developments.
Industry Challenges
- Programmable logic controller integration:Legacy building management systems in older facilities require custom protocol bridges, complicating robotic fleet deployment.
- FCC equipment authorization timelines:Radio frequency certification for LiDAR and wireless communication modules delays product launches by 4-6 months.
- Mechatronics talent scarcity:Shortage of technicians qualified in servo motor calibration and sensor fusion limits field service expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Data Center Robotics Market |
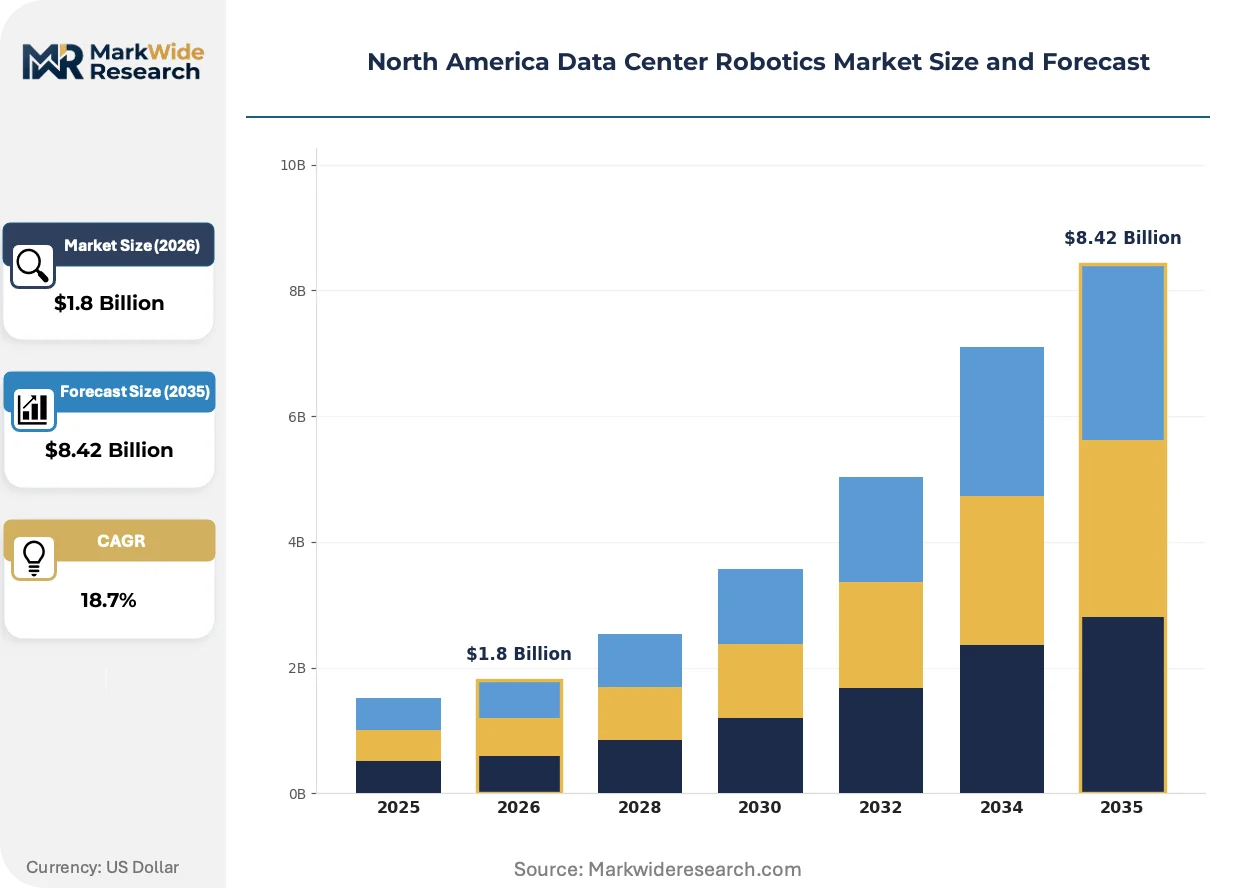
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Guided Vehicles, Robotic Arms, Mobile Robots, Collaborative Robots Technology: Artificial Intelligence, Machine Learning, Computer Vision, IoT End User: Telecommunications, Cloud Services, Internet Service Providers, E-Commerce Application: Inventory Management, Order Fulfillment, Maintenance, Security |
| Companies Covered | ABB Group, Amazon Web Services, Inc, Microsoft Corporation, Equinix, Inc., Cisco Systems, Inc., Siemens AG, Hewlett Packard Enterprise Company, Rockwell Automation, Inc., BMC Software, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Data Center Robotics Market Evolving Landscape
Digital twin technology is compressing commissioning cycles for robotic deployments across hyperscale facilities. Virtualization of physical infrastructure enables remote testing of automated workflows before hardware installation.
Digital twin software is virtualizing server rack movement patterns and thermal load simulations in controlled cloud environments. Hyperscale operators in Northern Virginia deploy these virtual replicas to validate robotic path planning without disrupting live operations. This virtualization is compressing commissioning timelines from months to weeks while reducing physical prototype requirements.
NIST's evolving cybersecurity frameworks for operational technology are mandating encrypted firmware updates and access logging for connected robotics platforms. Equipment vendors must now embed hardware security modules and certificate-based authentication in servo motor controllers. Multi-tenant colocation operators in Texas and Arizona face the steepest compliance costs as they retrofit existing fleets.
After-sales service unbundling is fragmenting traditional robotics vendor relationships in the data center vertical. Hyperscale operators now separate hardware procurement from maintenance contracts, awarding multi-year service agreements to specialized third-party integrators. This pattern is most visible in Dallas-Fort Worth, where facility density supports dedicated on-site technician pools independent of original equipment manufacturers.
North America Data Center Robotics Market Segmentation
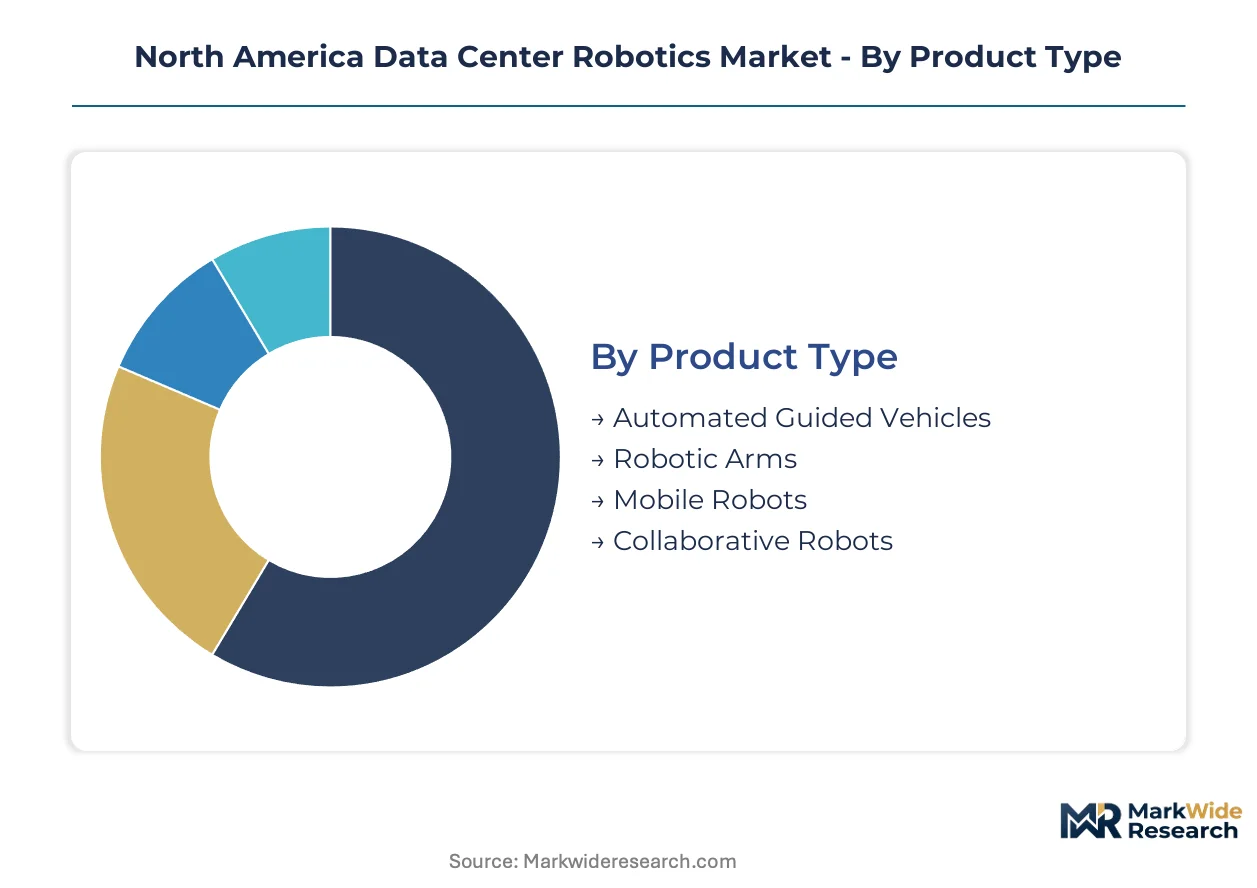
Segmentation reveals how capital flows diverge across automation modalities in North American hyperscale facilities. Product architecture, intelligence layer, buyer vertical, and operational use case each shape procurement specifications and vendor selection criteria differently.
Product Type:
Mature material-handling platforms coexist with emerging collaborative systems as facility automation deepens across the maturity spectrum.
- Automated Guided Vehicles:Wire-guided and vision-navigated platforms transport server racks and inventory across Dallas-Fort Worth and Northern Virginia corridors. Fleet deployments concentrate in greenfield hyperscale campuses where wide aisles accommodate magnetic tape or QR-code navigation infrastructure.
- Collaborative Robots:Force-limited articulated arms perform server component replacement alongside human technicians in brownfield retrofit environments. Demand accelerates in Texas and Arizona facilities where OSHA-compliant safety zones enable human-robot task sharing without full facility isolation.
- Robotic Arms:Fixed-base articulated systems execute precision cable management and thermal interface material application in controlled cleanroom conditions.
- Mobile Robots:Omnidirectional platforms patrol security perimeters and monitor environmental conditions across multi-megawatt campuses in British Columbia and Ontario.
Automated Guided Vehicles handle the majority of throughput; Collaborative Robots are gaining share fastest as labor scarcity intensifies in established data center corridors.
Technology:
Intelligence layer investments stratify by computational intensity required for autonomous decision-making at the edge.
- Artificial Intelligence:Deep learning models predict server failure patterns and optimize thermal load distribution across Azure and AWS facilities. Inference engines run on embedded GPUs in robotic controllers, enabling millisecond-level anomaly response in Northern Virginia's densest clusters.
- Computer Vision:Stereo camera arrays and edge-processed image recognition guide pick-and-place operations in narrow 600mm aisles where LiDAR suffers multipath interference. Canadian operators in Toronto and Montreal deploy these systems for barcode verification and rack alignment verification.
- Machine Learning:Supervised classification algorithms refine path planning efficiency based on historical traffic patterns in shared colocation environments.
- IoT:Sensor mesh networks relay motor health telemetry and power consumption data to centralized facility management dashboards.
Computer Vision commands the densest sensor deployment per square meter; Artificial Intelligence shows the steepest expansion trajectory as predictive maintenance contracts proliferate.
End User:
Buyer sophistication and capital access determine automation depth across vertical infrastructure strategies.
- Cloud Services:Hyperscale operators with captive engineering teams develop proprietary robotic platforms for internal deployment. Internal development programs at major cloud providers in Washington State and Texas bypass external vendor procurement for core automation functions.
- E-Commerce:Fulfillment-integrated data center operators demand robotics compatibility with existing warehouse automation fleets. Shared infrastructure standards in California and Illinois facilities drive cross-platform interoperability requirements.
- Telecommunications:Tier-1 carriers deploy modular robotic systems in edge computing facilities with standardized 19-inch rack configurations.
- Internet Service Providers:Regional hosting providers in secondary markets adopt leasing models for robotic fleet access to avoid capital-intensive ownership.
Cloud Services absorb the largest absolute unit volume; E-Commerce is climbing the fastest on share as fulfillment-data center convergence accelerates.
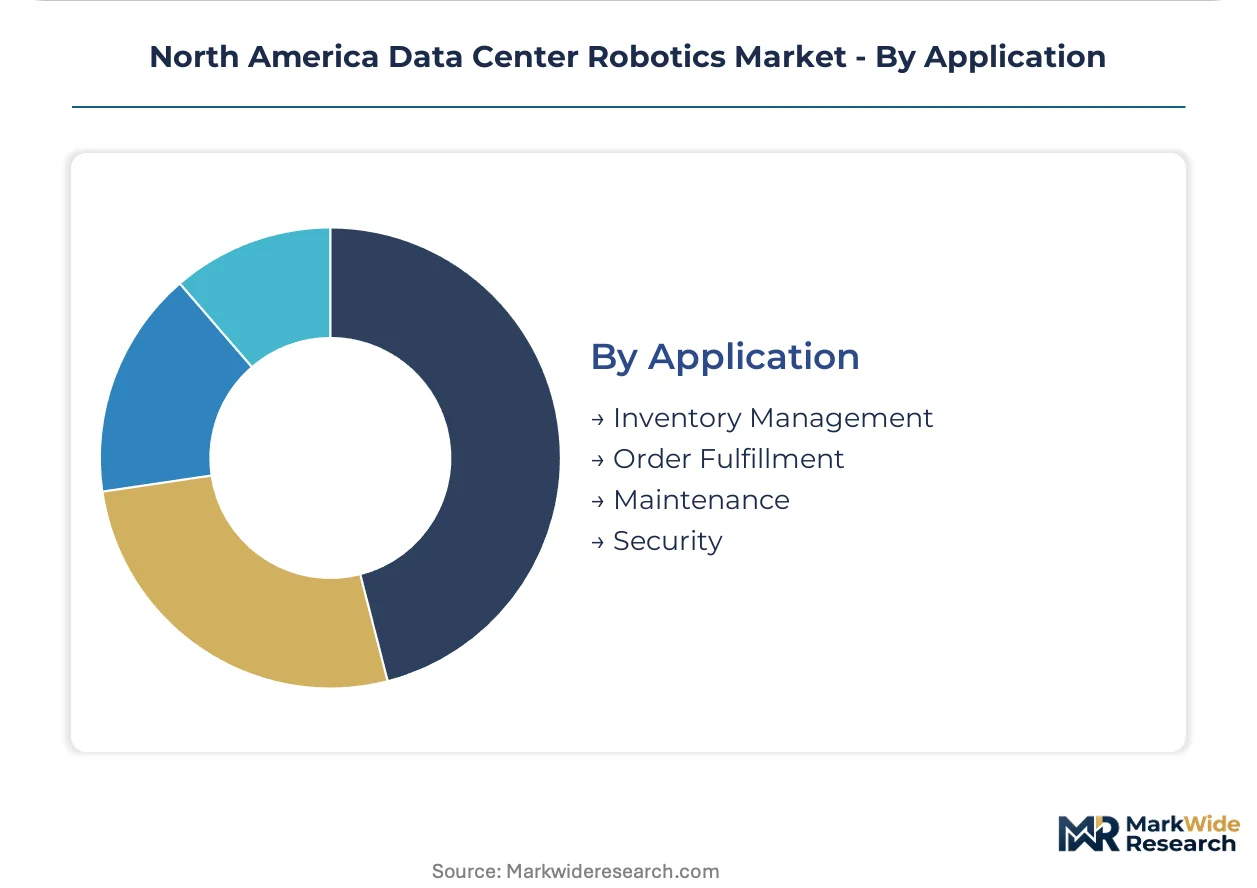
Application:
Operational use case dictates robot form factor, environmental sealing requirements, and integration complexity with building management systems.
- Maintenance:Predictive and corrective server servicing commands premium pricing for sub-millimeter precision systems. Robotic component handling in Arizona's hot aisle environments requires thermal management and electrostatic discharge protection beyond standard industrial specifications.
- Inventory Management:Automated rack location tracking and asset verification dominate capital deployment in Dallas-Fort Worth's high-turnover colocation market. Real-time inventory accuracy requirements in multi-tenant facilities drive RFID-integrated mobile robot adoption.
- Order Fulfillment:Cross-dock automation bridges data center and logistics operations in e-commerce-integrated facilities.
- Security:Autonomous patrol platforms monitor perimeter integrity and environmental anomalies in unmanned remote facilities across the Canadian prairies.
Inventory Management captures the broadest installed base; Maintenance is expanding most quickly as fault prediction capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center robotics procurement in Northern Virginia commands 15-20% pricing premiums over Dallas-Fort Worth due to facility density and labor scarcity. Canadian operators in Toronto and Vancouver face compressed margins from carbon disclosure compliance costs. Mexican border facilities near Tijuana attract cross-border automation investment from California-based hyperscalers seeking cost arbitrage.
United States
Northern Virginia's data center corridor drives fleet-scale deployments as hyperscale operators compress commissioning timelines amid technician shortages. EPA ENERGY STAR certification mandates accelerate servo-optimized robotics replacement in legacy facilities. Dallas-Fort Worth's greenfield campuses absorb the highest absolute capital allocation for Automated Guided Vehicle fleets.
Canada
British Columbia and Ontario provincial carbon disclosure rules create compliance-driven procurement specifications for lifecycle emissions documentation. Health Canada's operational technology cybersecurity guidance shapes firmware update protocols for connected robotics platforms. Toronto's multi-tenant colocation market attracts predictive maintenance automation contracts from cloud services operators.
Mexico
Tijuana and Monterrey industrial corridors capture spillover automation demand from California hyperscalers seeking cost-efficient facility expansion. Mexico's federal energy efficiency standards for industrial equipment influence servo motor selection criteria in border data centers. Querétaro's emerging technology cluster hosts regional integration partnerships for Texas-based robotics vendors.
North America Data Center Robotics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in motor, sensor, and controller supply. The vendor base stratifies between full-stack automation providers and point-solution specialists serving narrow aisle configurations or thermal management niches. Three archetypes dominate: industrial automation conglomerates with data center practices, hyperscale cloud operators with captive robotics development, and specialized systems integrators focused on brownfield retrofit deployment. Competitive positioning hardens around M&A for sensor fusion capabilities and strategic partnerships with electrical contractors bypassing traditional distribution channels.
Within the industrial automation tier, ABB Group and Siemens AG anchor large-scale motor and drive installations across Texas and Arizona hyperscale campuses. Rockwell Automation, Inc. occupies a position exemplifying the systems integration archetype for brownfield facility retrofits. Microsoft Corporation and Amazon Web Services, Inc. represent the captive development model, with internal robotics programs competing directly against external vendors for maintenance automation and inventory management functions.
| Leading Market Players |
|---|
| ABB Group |
| Amazon Web Services, Inc |
| Microsoft Corporation |
| Equinix, Inc. |
| Cisco Systems, Inc. |
| Siemens AG |
| Hewlett Packard Enterprise Company |
| Rockwell Automation, Inc. |
| BMC Software, Inc. |
| Others |
Value Network & Pricing Analysis
Neodymium processing concentration outside North America anchors servo motor cost structures and compresses margin pools for systems integrators deploying robotic fleets across Texas and Arizona hyperscale campuses. Permanent magnet supply vulnerability feeds directly into configured-to-order pricing premiums for AGV and collaborative robot deployments in Northern Virginia's labor-scarce corridor.
Pricing Analysis
The customization-premium spread runs wide between standard AGV platforms and configured-to-order collaborative systems with EPA ENERGY STAR certification. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal management specifications and NIST cybersecurity compliance depth. Pricing pressure stems from LiDAR sensor cost compression below $500 per unit, which erodes hardware margins while expanding addressable fleet scale. Cloud Services operators exhibit lowest price sensitivity due to captive engineering budgets, whereas regional Internet Service Providers in secondary markets demand economy-tier leasing structures.
Supply Chain Analysis
Supplier-financing facilities from Japanese and German component vendors extend payment terms for North American systems integrators, easing working capital burdens on greenfield deployment projects. Servo motors draw from rare earth magnet supply chains concentrated in China and Myanmar, with secondary processing capacity in Japan and Germany. Single-source vulnerability in neodymium oxide refining exposes motor costs to export restriction risk. Distribution runs through direct sales channels and electrical contractor partnerships that bypass traditional industrial distribution, capturing margin in Dallas-Fort Worth and Phoenix metro developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data center robotics sits in early-cycle expansion as hyperscale operators compress commissioning timelines amid persistent technician scarcity in established corridors. EPA ENERGY STAR mandates and NIST cybersecurity frameworks are accelerating replacement cycles beyond typical infrastructure refresh periods.
For Market Incumbents: Pre-empt margin erosion from in-house cloud operator development programs by deepening sensor fusion capabilities through targeted acquisitions. Anchor position in brownfield retrofit workflows where legacy building management system integration complexity deters captive engineering teams. Prioritize certification investment in Health Canada and emerging provincial carbon disclosure compliance to capture Canadian procurement specifications ahead of rule finalization. For New Entrants and Emerging Players: Pursue white-space opportunity in brownfield collaborative robot deployment for multi-tenant colocation operators in Dallas-Fort Worth and Toronto. Target security patrol mobile robots for unmanned Canadian prairie facilities where incumbent coverage remains thin. Lead with systems integration partnerships that bundle electrical contractor relationships and on-site technician training, bypassing traditional OEM distribution channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial automation specialists holding strong positions in servo motor and drive installations but lacking AI-enabled predictive maintenance software stacks. Five-to-ten year viability hinges on convergence between hardware deployment and recurring software revenue from fault detection analytics. Watch for inflection in cloud operator capex reallocation from internal robotics development toward external vendor procurement as AI maintenance contracts prove operationally superior.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Acquisition | Computer vision and LiDAR integration deepens predictive maintenance capabilities for Azure and AWS facilities. |
| Direct Sales Channel Expansion | Electrical contractor partnerships in Texas and Arizona capture margin from greenfield hyperscale developments. |
| Carbon Disclosure Compliance Investment | Lifecycle emissions documentation unlocks procurement specifications under British Columbia and Ontario mandates. |
| Cybersecurity Certification Program | NIST-aligned firmware protocols differentiate offerings for multi-tenant colocation operators facing retrofit costs. |
| Digital Twin Platform Integration | Virtual commissioning capabilities compress deployment timelines from months to weeks in Northern Virginia corridors. |
Research Methodology
Operator-level perspectives from data center facility directors, robotics procurement leads at hyperscale cloud operators, systems integration specialists, and electrical contractor project managers anchored the qualitative base. Primary interview insights combined with secondary validation from EPA ENERGY STAR certification databases, NIST cybersecurity framework documentation, SEC hyperscaler capex disclosures, and OSHA workplace safety guidance. Bottom-up unit deployment estimates across product type and technology segments triangulated against top-down capital expenditure flows from cloud services and colocation operators.
Scenario-bracketing framed the analytical approach across the projection horizon, with base, upside, and downside cases reflecting LiDAR cost curve velocity and cloud operator in-house development intensity. Segmentation dimensions modeled include product architecture, intelligence layer, end-user vertical, and operational use case, with geographic facility density and labor scarcity indices as cross-cutting modifiers. CAGRs derived from historical capital deployment patterns and projected fleet refresh cycles, incorporating hyperscale expansion announcements and provincial carbon rule emergence timelines.
Sensitivities concentrate around rare earth magnet supply disruption, FCC equipment authorization timeline extensions, and cloud operator decisions to expand or contract captive robotics engineering headcount. Forecasts reflect documented assumptions on component cost trajectories and regulatory implementation schedules. Macroeconomic contraction affecting hyperscale capex, trade restriction escalation on critical minerals, or breakthroughs in narrow-aisle AGV maneuvering technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Entertainment Robots Market
Robotics and Automation
Hospitality Robots Market
Robotics and Automation
Drone-Based NDT Inspection Systems for Energy and Infrastructure Assets Market
Robotics and Automation
Robotics Actuators Market
Robotics and Automation
Global Robot Software Market
Robotics and Automation
Asia-Pacific AUV and ROV Market
Robotics and Automation
Africa Agricultural Robots and Mechatronics Market
Robotics and Automation
Robot Market
Robotics and Automation
Asia Pacific Industrial Robots Market
Robotics and Automation
Global IT Robotic Automation Market
Robotics and Automation
Cybersecurity in Robotics Market
Robotics and Automation
Indonesia Robotics Market
Robotics and Automation
High-Precision Truss Robot Market
Robotics and Automation
Pharmaceutical Collaborative Robots Market
Robotics and Automation
Autonomous Drilling Robots Market
Robotics and Automation
United States Articulated Robot Market