
 Autonomous AI and Autonomous Agents Market | 2026-2036
Autonomous AI and Autonomous Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous AI and Autonomous Agents Market Analytics
The United States is fragmenting into competing autonomous AI development clusters centered on San Francisco, Seattle, and Boston research corridors. Microsoft Corporation leverages its Azure cloud infrastructure to anchor enterprise agent deployment pipelines. NVIDIA Corporation dominates specialized silicon supply for training and inference workloads. Google LLC sustains foundational model leadership through DeepMind research integration.
Autonomous AI and autonomous agents denote software systems capable of perceiving environments, reasoning through multi-step objectives, and executing actions without continuous human oversight, typically operating through API orchestration, tool use, and iterative planning loops. These systems serve industrial and commercial purposes ranging from automated customer resolution to autonomous supply chain rebalancing. Machine Learning and Natural Language Processing segments command current revenue concentration due to immediate enterprise deployability, while Reinforcement Learning represents the fastest-expanding technology layer as agentic reasoning capabilities mature. Autonomous Robots within product type classifications sit at the highest margin pool given hardware-software integration complexity and limited supplier density.
The EU AI Act imposes risk-tiered compliance obligations on autonomous agents deployed in European jurisdictions, while the FDA in the United States evaluates autonomous diagnostic systems under evolving software-as-medical-device pathways. China's SAMR and MIIT coordinate algorithmic recommendation and data security standards for domestic autonomous service providers. Stakeholders must monitor regulatory divergence between jurisdictions to determine localization investment sequencing and certification prioritization.
Market Dynamics
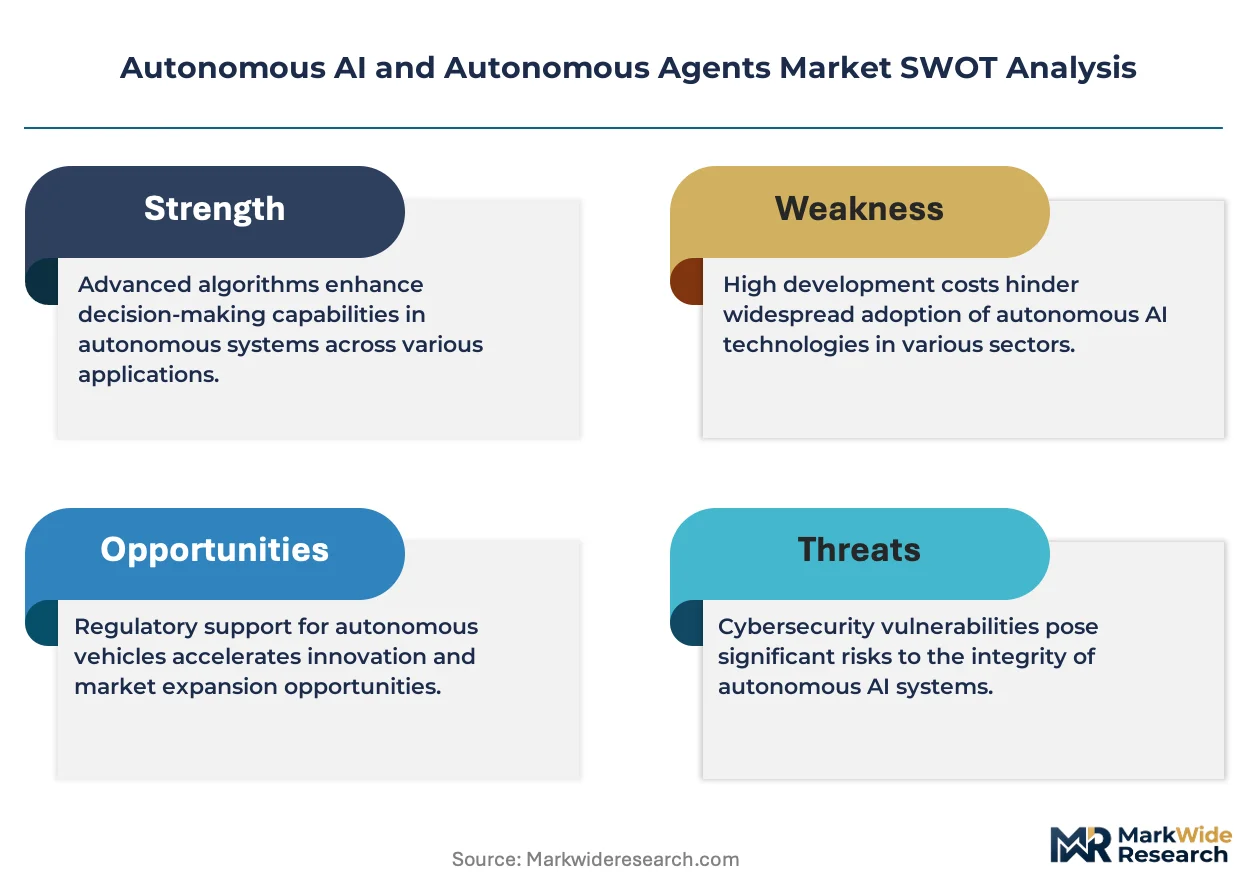
Foundation model commoditization is compressing margins for autonomous agent providers while simultaneously lowering deployment barriers for enterprise adopters. This structural force redirects competitive advantage toward orchestration capabilities, proprietary data moats, and vertical-specific reasoning architectures rather than raw model scale.
Growth Catalysts
- EU AI Act risk-tiered obligations:The regulation's high-risk system classification creates compliance-driven procurement cycles as European enterprises accelerate agent deployment ahead of enforcement deadlines.
- Reinforcement Learning from Human Feedback:This training methodology enables autonomous agents to handle multi-step reasoning tasks previously requiring human oversight, expanding addressable use cases in financial services and healthcare.
- Cloud infrastructure density in the United States:Concentrated hyperscaler capacity in Northern Virginia, Oregon, and Texas enables sub-50ms inference latency for real-time autonomous decision-making applications.
Market Restraints
- NVIDIA GPU supply concentration:Training and inference workload dependence on a single silicon architecture creates procurement bottlenecks and pricing volatility for agent developers.
- Algorithmic accountability standards:Emerging FDA software-as-medical-device pathways and EU AI Act explainability requirements impose documentation burdens that extend commercialization timelines by 12-18 months.
- Substitute human-in-the-loop systems:Lower-cost augmented intelligence workflows retain preference in regulated industries where liability attribution remains unresolved.
Strategic Opportunities
- India's BIS certification alignment:The country's standardization push for AI systems creates first-mover advantage for agents achieving dual compliance with Indian and European frameworks.
- Agent-to-agent protocol standardization:Emerging interoperability specifications enable multi-agent orchestration across enterprise boundaries, unlocking B2B network effects.
- Edge inference deployment:Convergence of model distillation techniques and specialized neural processing units permits autonomous operation in bandwidth-constrained industrial environments.
Industry Challenges
- Reinforcement learning engineering scarcity:Practitioners capable of designing reward functions for complex multi-agent environments command compensation premiums exceeding 40% above standard ML engineering roles.
- Legacy ERP integration complexity:Enterprise resource planning systems from the 1990s and 2000s lack API-native architectures, forcing costly middleware development for autonomous agent connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous AI and Autonomous Agents Market |
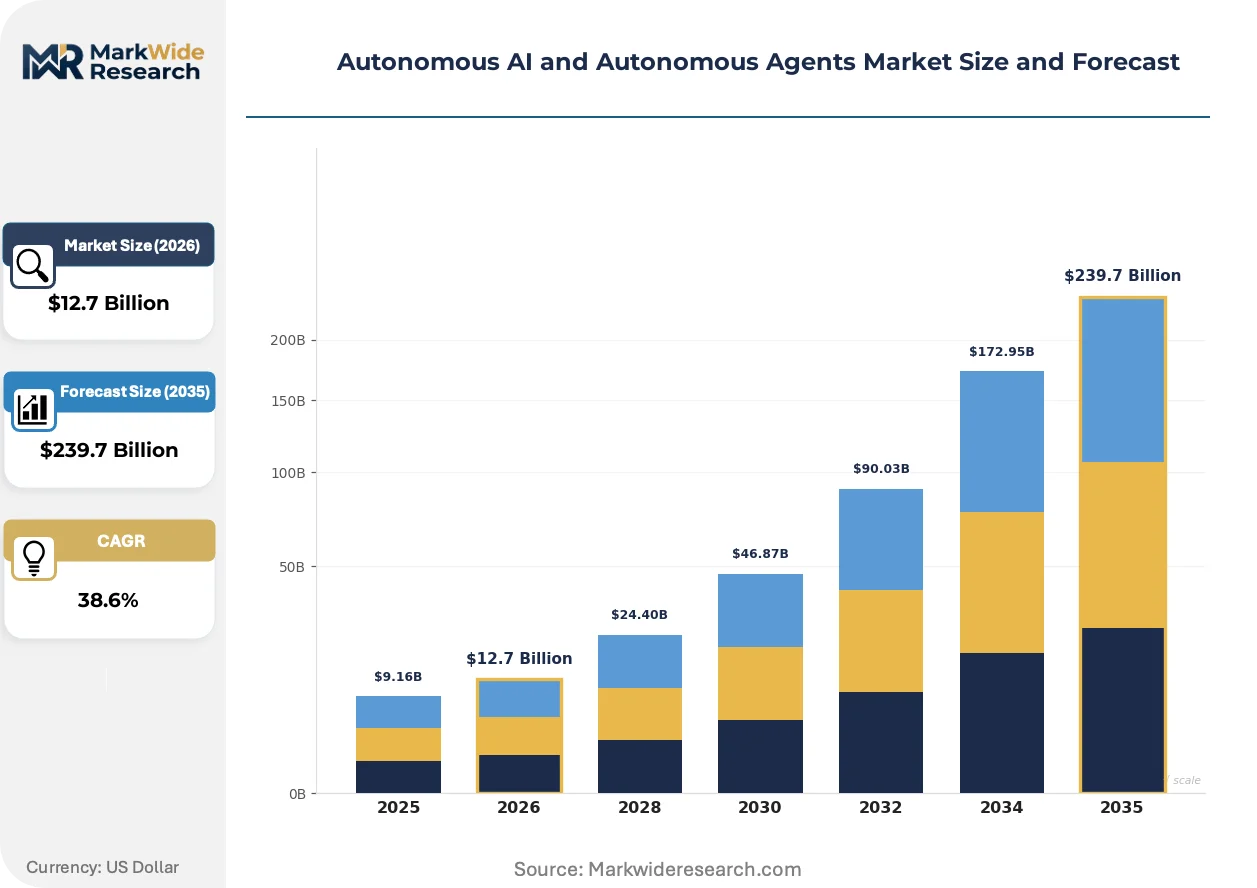
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $239.7 Billion |
| CAGR (2026 – 2036) | 38.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chatbots, Virtual Assistants, Autonomous Robots, Predictive Analytics Application: Customer Support, Supply Chain Optimization, Fraud Detection, Autonomous Vehicles End User: Retail, Automotive, Healthcare, Manufacturing Technology: Machine Learning, Natural Language Processing, Computer Vision, Reinforcement Learning |
| Companies Covered | Microsoft Corporation, Google LLC, Amazon Web Services, Inc., IBM Corporation, NVIDIA Corporation, Baidu Inc., Oracle Corporation, Salesforce, Inc., SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous AI and Autonomous Agents Market Evolving Landscape
Autonomous agent architectures are pivoting from monolithic models toward modular tool-use systems that dynamically compose capabilities. This reconfiguration favors specialized component providers and reshapes how enterprises evaluate vendor lock-in risk.
Multi-modal reasoning engines that process text, structured data, and visual inputs simultaneously are rendering obsolete single-modality chatbot interfaces that dominated early enterprise automation. Manufacturing quality control and insurance claims processing teams in Germany and Japan are deploying these systems at pilot scale. The shift compresses vendor consolidation timelines as point-solution providers lose standalone viability.
The EU AI Act's high-risk system registration requirements are forcing autonomous agent developers to maintain algorithmic change logs and human oversight protocols. Industrial consequence includes mandatory conformity assessment costs exceeding €50,000 per deployment variant. Medical diagnostics and credit underwriting applications face the steepest compliance gradients, with several providers withdrawing from European markets rather than adapting governance infrastructure.
Enterprise procurement teams are compressing vendor evaluation cycles from 18-month RFP processes to 90-day pilot-to-production timelines. This acceleration disadvantages traditional systems integrators and favors API-first agent platforms with pre-built connectors. The pattern is most pronounced in United States financial services and United Kingdom professional services sectors where competitive pressure demands rapid automation deployment.
Autonomous AI and Autonomous Agents Market Segmentation
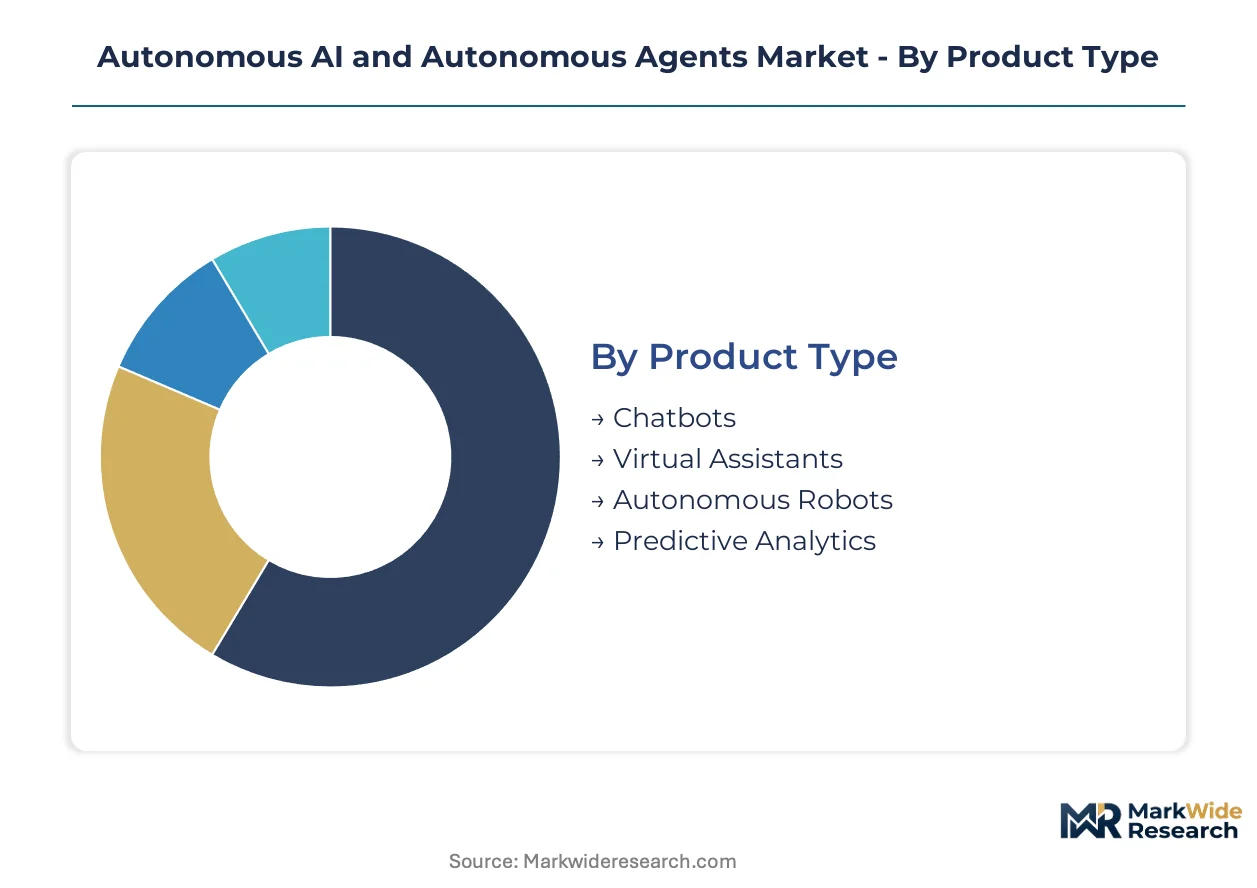
Autonomous AI systems exhibit divergent deployment economics across product architectures, application contexts, and underlying technology stacks. Understanding these segment boundaries clarifies where procurement budgets concentrate and which capability layers command premium pricing.
Product Type:
Cost tier differentiation separates hardware-integrated systems from software-only implementations, with integration complexity driving margin stratification.
- Chatbots:Text-based conversational interfaces handle scripted query resolution through API-connected knowledge bases. Demand concentrates in United States retail banking for first-line customer triage, constrained by escalation protocols for complex disputes.
- Virtual Assistants:Multi-turn dialogue systems integrate calendar, email, and enterprise software access through natural language commands. German automotive suppliers deploy these for engineering workflow orchestration, driven by skilled labor scarcity in technical documentation roles.
- Autonomous Robots:Physical systems combining locomotion, manipulation, and environmental sensing for warehouse and manufacturing tasks.
- Predictive Analytics:Pattern recognition engines forecasting demand, equipment failure, or financial risk from historical data streams.
Chatbots command the established base. The steepest expansion runs through Autonomous Robots.
Application:
Volume concentration follows regulatory tolerance for unsupervised decision-making, with liability-sensitive domains lagging autonomous deployment.
- Customer Support:Ticket routing, response generation, and sentiment escalation for service organizations. United Kingdom telecommunications providers lead deployment scale, pressured by cost-per-contact reduction mandates.
- Supply Chain Optimization:Inventory repositioning, demand sensing, and logistics coordination across distributed networks. Japanese automotive manufacturers drive adoption here, responding to just-in-sequence production complexity.
- Fraud Detection:Real-time transaction scoring and anomaly flagging for financial institutions.
- Autonomous Vehicles:Navigation, obstacle avoidance, and route planning for transport and logistics fleets.
Customer Support anchors current revenue. Supply Chain Optimization gains share fastest as multi-echelon inventory challenges intensify.
End User:
Customer type segmentation reveals divergent readiness for agent delegation, with capital intensity and regulatory exposure shaping adoption velocity.
- Retail:Demand forecasting, personalized recommendation, and automated replenishment for consumer-facing operations. United States e-commerce platforms concentrate investment here, chasing fulfillment cost parity with physical retail.
- Automotive:Manufacturing quality control, predictive maintenance, and autonomous test fleets. German OEMs and their tier-one suppliers dominate procurement volume, driven by software-defined vehicle architectures.
- Healthcare:Diagnostic imaging analysis, patient scheduling, and clinical documentation assistance.
- Manufacturing:Process optimization, defect detection, and autonomous material handling.
Retail holds the largest installed base. Automotive shows the steepest upward trajectory as software capabilities differentiate vehicle platforms.
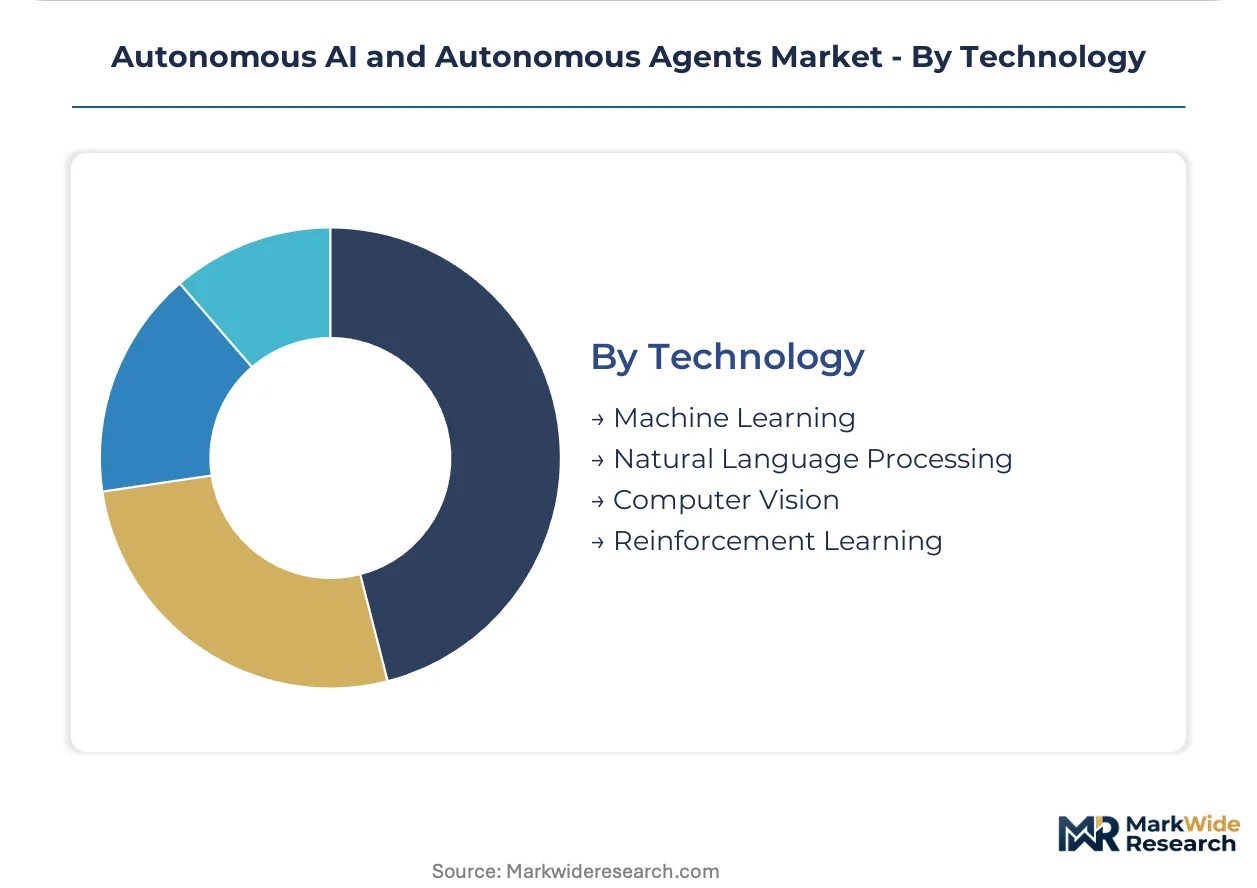
Technology:
Maturity gradients separate production-ready techniques from emerging research frontiers, with implementation risk determining enterprise procurement preferences.
- Machine Learning:Supervised and unsupervised statistical models for classification, clustering, and regression tasks. Financial services in Singapore and Switzerland deploy these at scale for credit scoring and portfolio optimization, constrained by model explainability requirements under national banking regulations.
- Natural Language Processing:Syntactic parsing, semantic understanding, and text generation capabilities. United States legal services and contract management platforms drive demand concentration, motivated by document review automation.
- Computer Vision:Image and video analysis for object detection, segmentation, and scene understanding.
- Reinforcement Learning:Trial-and-error optimization through environment interaction and reward signal feedback.
Machine Learning and Natural Language Processing together anchor commercial deployment. Reinforcement Learning expands most quickly as multi-step reasoning architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by jurisdiction. United States enterprises prioritize real-time inference latency for financial trading applications, while European adopters weight compliance documentation overhead more heavily in procurement decisions. Asian markets emphasize cost-efficient deployment at manufacturing scale.
United States
Financial services firms in Manhattan and Chicago deploy autonomous agents for sub-second trade execution and risk rebalancing. The SEC's emerging algorithmic accountability guidance shapes vendor selection criteria. Research corridors in San Francisco, Seattle, and Boston fragment into competing development clusters anchored by cloud infrastructure density and venture capital availability.
Germany
Automotive OEMs and tier-one suppliers in Stuttgart and Munich integrate autonomous agents into software-defined vehicle architectures. The EU AI Act's high-risk system classification imposes conformity assessment costs exceeding €50,000 per deployment variant. Industrial automation clusters in Baden-Württemberg pilot multi-modal reasoning engines for manufacturing quality control.
China
Domestic cloud providers and fintech platforms drive agent deployment for automated customer resolution and supply chain rebalancing. SAMR and MIIT coordinate algorithmic recommendation and data security standards for autonomous service providers. Manufacturing hubs in the Yangtze River Delta experiment with edge inference deployment in bandwidth-constrained environments.
United Kingdom
Telecommunications providers and professional services firms compress vendor evaluation cycles from 18-month RFP processes to 90-day pilot-to-production timelines. The Information Commissioner's Office interprets GDPR provisions for automated decision-making transparency. London-based financial services procurement teams favor API-first agent platforms with pre-built connectors.
India
IT services exporters and domestic enterprises pursue BIS certification alignment to achieve dual compliance with Indian and European frameworks. The country's standardization push for AI systems creates first-mover advantage for agents meeting multi-jurisdictional requirements. Bengaluru and Hyderabad host engineering workflow orchestration deployments addressing skilled labor scarcity in technical documentation roles.
Autonomous AI and Autonomous Agents Market Competitive Landscape
Capability concentration sits with specialized silicon and foundation model providers; scale advantage sits with hyperscaler cloud platforms. The market structures around three tiers: infrastructure layer specialists, orchestration platform operators, and vertical application developers. Dominant competitive moves include strategic partnerships between model providers and cloud platforms, plus geographic localization investments to satisfy divergent regulatory requirements.
Within the hyperscaler tier, Microsoft Corporation, Google LLC, and Amazon Web Services, Inc. occupy positions defined by cloud infrastructure density and enterprise distribution channels. Microsoft leverages Azure deployment pipelines for enterprise agent commercialization. Google sustains foundational model leadership through research integration. Amazon Web Services anchors scale advantages in inference workload pricing. These three exemplify how cloud-native distribution reshapes competitive positioning against independent software vendors.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Google LLC |
| Amazon Web Services, Inc. |
| IBM Corporation |
| NVIDIA Corporation |
| Baidu Inc. |
| Oracle Corporation |
| Salesforce, Inc. |
| SAP SE |
| Others |
Value Network & Pricing Analysis
NVIDIA GPU supply concentration in Taiwan and South Korea anchors margin distribution across the autonomous AI value chain, with specialized silicon commanding pricing power that compresses downstream software margins. Foundation model commoditization redirects profit pools toward orchestration layers and vertical-specific reasoning architectures.
Pricing Analysis
Long-term enterprise SaaS contracts dominate autonomous agent procurement, with annual subscription tiers scaling by API call volume and deployment complexity. Price differentiation rests on inference latency guarantees and EU AI Act compliance certification status. Cost compression in chatbot implementations intensifies as open-source model alternatives proliferate. Retail banking procurement teams exhibit highest price sensitivity, while pharmaceutical diagnostic applications tolerate premium pricing for FDA-validated pathways.
Supply Chain Analysis
Upstream feedstock for autonomous AI systems draws from Taiwan and South Korea for advanced GPU fabrication, with United States and China contributing cloud infrastructure and rare earth processing respectively. Critical dependencies include high-bandwidth memory modules, specialized neural processing units, and proprietary training datasets. Single-source vulnerability in NVIDIA's foundry relationships creates procurement bottlenecks during capacity expansion cycles. Distribution runs through hyperscaler marketplaces and direct enterprise sales channels with implementation support bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent autonomous AI providers face substitution pressure from open-source model ecosystems and vertically integrated cloud platforms, requiring defensive repositioning around proprietary data moats and regulatory certification barriers.
For Market Incumbents: Pre-empt open-source displacement by deepening proprietary data partnerships in regulated verticals such as healthcare diagnostics and financial underwriting. Secure EU AI Act high-risk system certifications ahead of enforcement deadlines to create compliance moats. Anchor enterprise relationships through middleware investments that ease legacy ERP integration burdens. For New Entrants and Emerging Players: Establish a beachhead in edge inference deployment for bandwidth-constrained manufacturing environments, where incumbent cloud architectures face latency limitations. Target German automotive suppliers and Japanese industrial automation clusters seeking sovereign AI alternatives. Pursue BIS certification alignment to unlock dual-compliance positioning across Indian and European procurement cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed vertical application developers possessing FDA software-as-medical-device clearances or EU AI Act conformity assessments. Long-term viability hinges on orchestration platform differentiation rather than raw model scale. Monitor agent-to-agent protocol standardization momentum as an inflection indicator for network-effect valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | High-risk system registration unlocks European enterprise procurement budgets exceeding €50,000 per deployment variant. |
| Agent-to-Agent Protocol Standardization | Interoperability specifications enable multi-agent orchestration across enterprise boundaries, creating B2B network effects. |
| Edge Inference Deployment | Model distillation techniques and neural processing units permit autonomous operation in bandwidth-constrained industrial environments. |
| Legacy ERP Integration Investment | Pre-built middleware connectors compress enterprise sales cycles from 18-month RFP processes to 90-day pilot timelines. |
| Reinforcement Learning Talent Acquisition | Practitioners capable of multi-agent reward function design command compensation premiums exceeding standard ML engineering roles. |
Research Methodology
Operator-level perspectives from autonomous AI platform engineers, enterprise IT procurement officers, regulatory compliance leads, and vertical application developers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, hyperscaler capex disclosures, EU AI Act implementation guidance, and FDA software-as-medical-device pathway documentation. Bottom-up deployment estimates triangulated against top-down market sizing from cloud infrastructure spending and venture capital flow data.
Scenario-bracketing framed the analytical approach, with growth trajectories modeled across technology maturity, regulatory enforcement intensity, and enterprise adoption velocity dimensions. Segmentation analysis spanned product architecture, application context, underlying technology stack, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to historical SaaS adoption patterns and adjusted for compliance-driven procurement cycle timing. Forecast inputs incorporated reinforcement learning research publication velocity and GPU supply capacity expansion announcements.
Stress conditions across NVIDIA supply constraints, EU AI Act enforcement delays, and open-source model capability convergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding enterprise automation substitution economics and cloud infrastructure pricing trajectories. Cross-checking against hyperscaler earnings call commentary on AI workload growth is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Commercial Artificial Intelligence Market
Artificial Intelligence (AI)
Brain Computer Interface Market
Artificial Intelligence (AI)
United States Artificial Intelligence Market
Artificial Intelligence (AI)
Image Recognition Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Life Science Market
Artificial Intelligence (AI)
Enterprise Generative AI Market
Artificial Intelligence (AI)
Deep Learning Market
Artificial Intelligence (AI)
Global Cognitive Computing Technology Market
Artificial Intelligence (AI)
Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Retail Market
Artificial Intelligence (AI)
AI in Project Management Market
Artificial Intelligence (AI)
Global Artificial Intelligence in E-Commerce Market
Artificial Intelligence (AI)
Enterprise AI Governance and Compliance Market
Artificial Intelligence (AI)
AI in Food & Beverages Market
Artificial Intelligence (AI)
Artificial Intelligence in Supply Chain Management Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Accelerator Market