
 Automated Storage and Retrieval System (AS & RS) Market | 2026-2036
Automated Storage and Retrieval System (AS & RS) Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Storage and Retrieval System (AS & RS) Market Insights
System integrator partnerships are reconfiguring how AS & RS solutions reach mid-sized distribution operators. Daifuku Co., Ltd. leverages its vertical integration in material handling equipment to control project timelines from design through commissioning. SSI SCHAEFER anchors European market presence with dense service networks across German industrial corridors. Knapp AG differentiates through software-agnostic hardware platforms that integrate with diverse warehouse management systems.
An automated storage and retrieval system comprises computer-controlled machines that move vertically and horizontally within defined rack structures to deposit and retrieve loads, typically handling unit loads up to several tons with positioning accuracy within millimeters. These systems eliminate manual travel in warehousing operations, compressing storage density by 40-60% compared to conventional pallet racking while enabling real-time inventory tracking. Shuttle technology commands premium investment flows as e-commerce fulfillment demands sub-hour retrieval cycles that legacy crane-based unit load systems cannot match. Vision guided navigation is displacing wire guided installations in brownfield retrofits where floor-embedded infrastructure proves cost-prohibitive to modify. Third party logistics providers represent the fastest-growing end user category as fulfillment outsourcing accelerates across consumer packaged goods and pharmaceutical distribution channels.
FDA traceability requirements for pharmaceutical distributors mandate lot-level tracking that AS & RS software platforms must validate, while OSHA machine guarding standards shape aisle access protocols and light curtain specifications in US installations. The EU Machinery Directive and CE marking framework enforce functional safety ratings that determine market access for European-deployed equipment. Stakeholders must weigh total cost of ownership against modular upgrade paths as retrieval speed requirements and energy efficiency benchmarks continue tightening across jurisdictions.
Market Dynamics
Shuttle-based retrieval architectures are compressing order cycle times from hours to minutes, forcing warehouse operators to retire legacy crane-dependent layouts or lose e-commerce fulfillment contracts. This speed mandate cascades through equipment procurement, software integration, and facility redesign decisions.
Growth Catalysts
- OSHA machine guarding mandates:US workplace safety rules for collaborative robot zones are accelerating replacement of manually operated forklifts with automated retrieval systems in distribution centers.
- Same-day fulfillment expectations:E-commerce order velocity requirements are pulling capital investment into shuttle-based AS & RS configurations capable of sub-hour retrieval cycles.
- Pharmaceutical lot tracking:FDA traceability requirements for drug distributors are mandating software-validated inventory systems that AS & RS platforms provide.
Market Restraints
- Steel and servo motor cost volatility:Input price swings for rack structures and precision motion components compress project margins during bid-to-commission timelines.
- System integration complexity:Brownfield retrofits face floor-embedded wire guidance infrastructure that proves cost-prohibitive to modify for vision-based navigation.
- EU Machinery Directive compliance:Functional safety certification requirements for CE marking extend equipment validation timelines and limit vendor pool eligibility.
Strategic Opportunities
- Third-party logistics channel expansion:Fulfillment outsourcing acceleration across consumer packaged goods is creating dedicated AS & RS procurement budgets among 3PL operators.
- Brownfield vision navigation retrofits:Camera-based positioning systems eliminate floor-embedded infrastructure requirements, opening retrofit markets in aging European warehouse stock.
- Energy efficiency benchmarking:Tightening EU operational efficiency standards are favoring regenerative drive systems and modular shuttle architectures in new facility specifications.
Industry Challenges
- Controls engineering talent scarcity:Shortage of PLC programmers and warehouse management system integrators extends commissioning timelines and inflates service contract costs.
- Multi-vendor software interoperability:Hardware-agnostic platform claims often mask API limitations that delay WMS integration and inflate customization spend.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Storage and Retrieval System (AS & RS) Market |
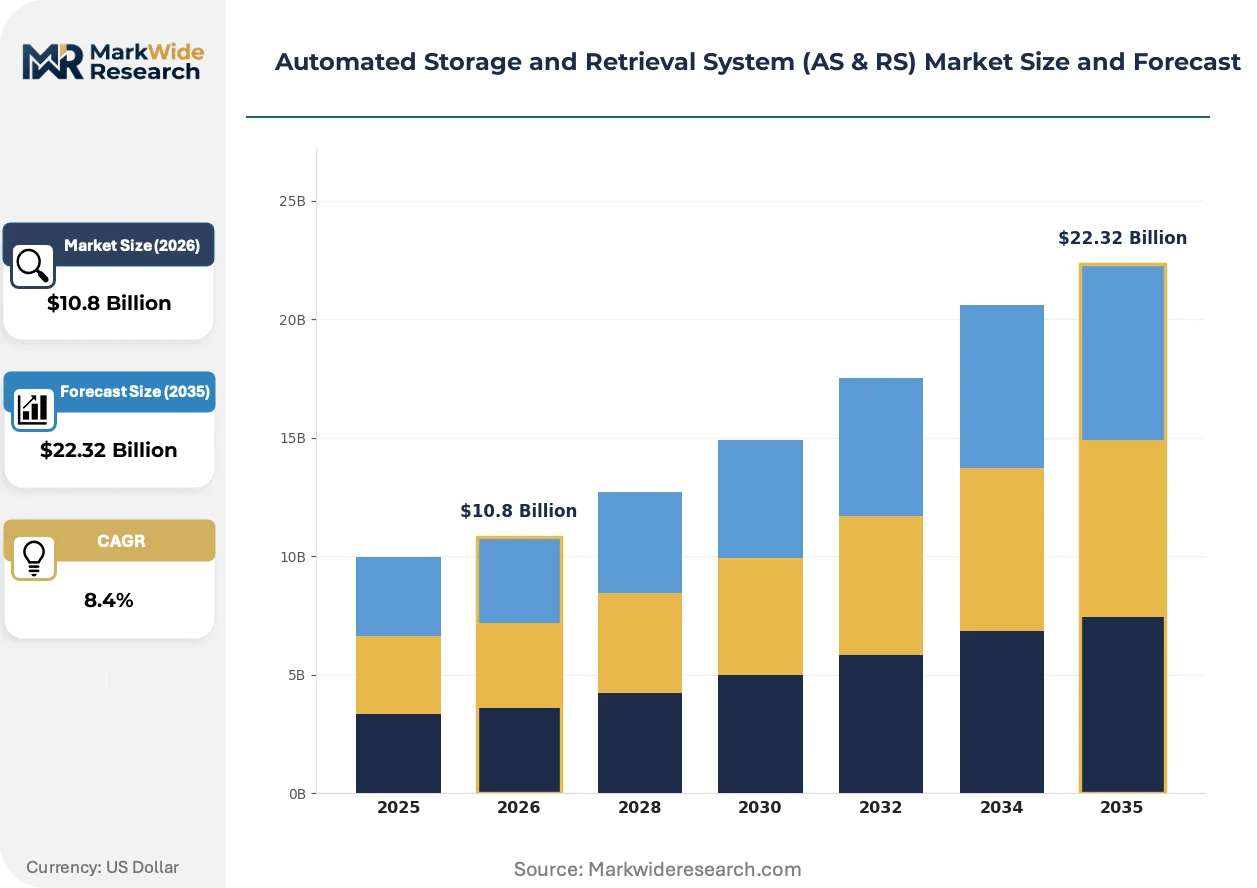
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $22.32 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unit Load, Mini Load, Carousel, Vertical Lift, Shuttle Technology: Wire Guided, Laser Guided, Vision Guided, Automated Guided Vehicle, Radio Frequency Identification Application: Warehouse Management, Order Fulfillment, Inventory Control, Manufacturing Logistics, Distribution Centers End User: E-commerce Vendors, Third Party Logistics, Pharmaceutical Distributors, Food Processing Firms, Aerospace Contractors |
| Companies Covered | TGW Logistics Group, Daifuku Co., Ltd., SSI SCHAEFER, Kardex, Swisslog Holding AG, Murata Machinery, Dematic, Knapp AG, Vanderlande, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Storage and Retrieval System (AS & RS) Market Trends and Innovations
AS & RS architectures are fragmenting into specialized configurations as retrieval speed requirements diverge across pharmaceutical cold chain, automotive sequencing, and e-commerce fulfillment. Equipment vendors are recasting their offerings around software-defined capabilities rather than mechanical throughput specifications.
Vision-guided navigation is hybridizing with traditional wire-guided installations to enable retrofit deployments without floor demolition. Pharmaceutical distributors in Germany and the US are adopting camera-based positioning for existing high-bay facilities where embedded guidance infrastructure would trigger months of operational downtime. This hybrid approach compresses project timelines from 18 months to 8 months while preserving rack structure investments.
EU Machinery Directive functional safety ratings are reshaping vendor qualification criteria for European deployment. CE marking requirements for collaborative robot zones now mandate third-party-validated light curtain specifications and aisle access protocols. German automotive and pharmaceutical clusters are demanding SIL-rated safety systems that exceed baseline compliance, filtering equipment suppliers by certification depth rather than price position.
Service contract unbundling is separating hardware procurement from software maintenance and remote monitoring subscriptions. Third-party logistics operators in consumer packaged goods are rejecting traditional bundled service models in favor of à la carte support tiers matched to seasonal volume fluctuations. This shift is most visible in US distribution corridors where 3PL margins compress during off-peak quarters and fixed service fees erode profitability.
Automated Storage and Retrieval System (AS & RS) Market Segmentation
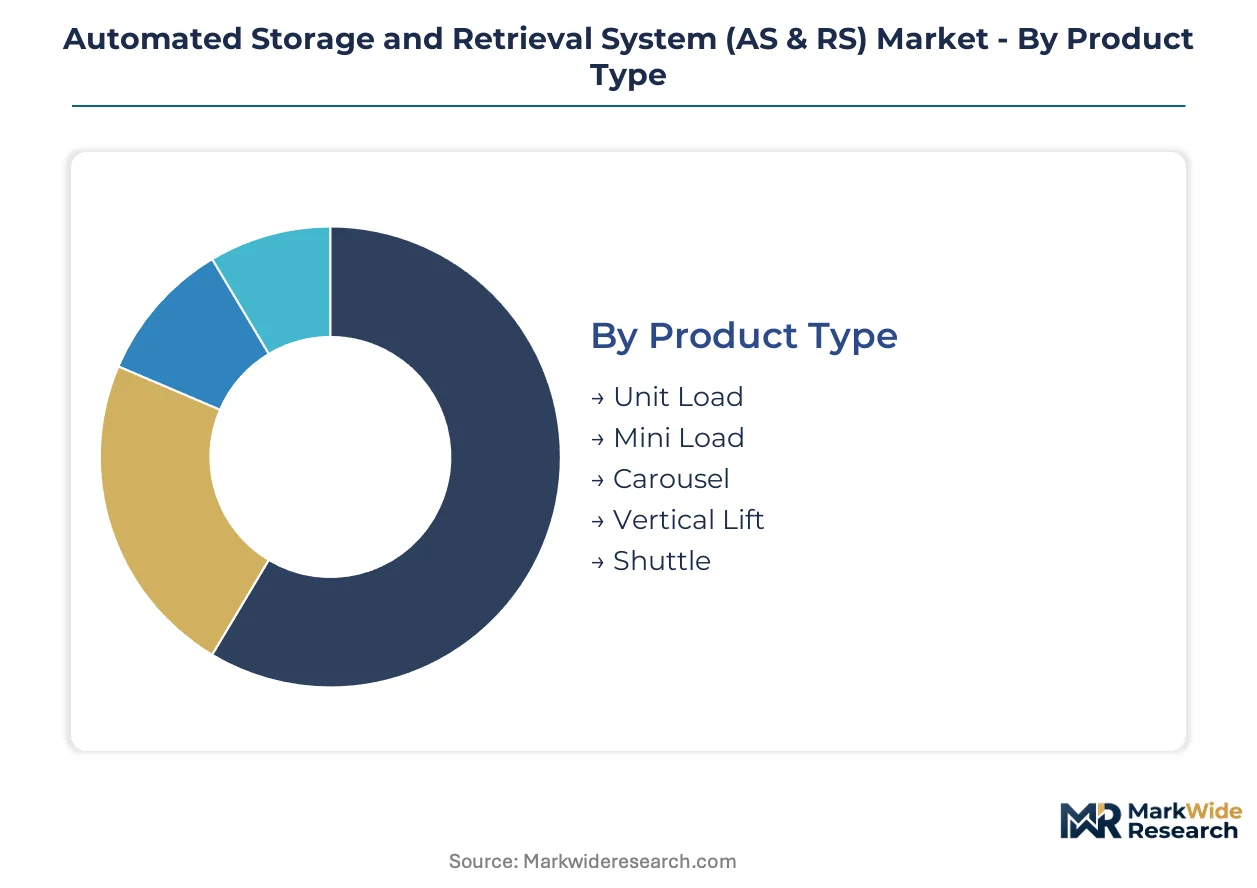
AS & RS procurement decisions fragment across equipment scale, navigation precision, and operational tempo requirements. Each segmentation dimension reveals distinct capital allocation patterns between brownfield retrofits and greenfield automation investments.
Product Type:
Mature crane-based architectures coexist with emerging shuttle configurations as retrieval speed requirements diverge across end-use applications.
- Unit Load:Crane-based systems handle palletized inventory up to several tons within high-bay rack structures. German automotive clusters in Stuttgart and Wolfsburg deploy these configurations for sequencing operations where throughput stability outweighs velocity. OSHA machine guarding mandates for collaborative zones are accelerating forklift replacement programs in US distribution centers.
- Shuttle:Autonomous satellite vehicles traverse rack levels independently, compressing retrieval cycles to sub-hour intervals. E-commerce fulfillment networks in California and Texas are specifying these systems to meet same-day delivery service level agreements. Vision-guided navigation variants eliminate floor-embedded infrastructure requirements in brownfield retrofits.
- Mini Load:Tote-handling systems manage smaller inventory units for pharmaceutical and electronics distribution.
- Carousel:Rotating rack structures deliver items to fixed pick stations, common in healthcare and spare parts operations.
- Vertical Lift:Compact footprint systems integrate storage and retrieval within enclosed columns for space-constrained urban facilities.
Unit Load configurations handle the majority of installed throughput; Shuttle systems are expanding most quickly on share.
Technology:
Navigation precision tiers separate cost-optimized brownfield retrofits from performance-driven greenfield specifications.
- Vision Guided:Camera-based positioning systems calculate real-time coordinates without floor-embedded infrastructure. Pharmaceutical distributors in Germany are adopting this technology for existing high-bay facilities where wire-guided demolition would trigger months of operational downtime. FDA traceability requirements for lot-level tracking favor these systems' software integration capabilities.
- Wire Guided:Electromagnetic floor-embedded tracks deliver proven reliability in high-throughput manufacturing logistics. Automotive sequencing operations in Michigan and South Carolina retain these installations where facility lifespan aligns with equipment depreciation schedules. EU Machinery Directive compliance costs for new safety system retrofits are extending replacement timelines.
- Laser Guided:Reflector-based navigation supports flexible path programming in dynamic warehouse environments.
- Automated Guided Vehicle:Mobile platforms extend AS & RS functionality beyond fixed rack structures for manufacturing logistics.
- Radio Frequency Identification:Inventory tracking layers integrate with retrieval systems for real-time location verification.
Wire Guided retains the largest installed base; Vision Guided is climbing the fastest on new deployment share.
Application:
Operational tempo requirements stratify procurement specifications between inventory accuracy and order velocity priorities.
- Order Fulfillment:E-commerce-driven retrieval operations demand sub-hour cycle times that shuttle architectures uniquely deliver. Third-party logistics operators in consumer packaged goods are rejecting bundled service models in favor of à la carte support tiers matched to seasonal volume fluctuations. Energy efficiency benchmarking under tightening EU standards favors regenerative drive configurations.
- Warehouse Management:Core storage and retrieval functions prioritize density optimization over velocity. Cold chain pharmaceutical operations in New Jersey and Pennsylvania specify these systems for FDA-validated lot tracking compliance. Steel and servo motor cost volatility compress project margins during extended bid-to-commission timelines.
- Inventory Control:Real-time tracking systems integrate with enterprise resource planning platforms.
- Manufacturing Logistics:Production sequencing applications synchronize retrieval with assembly line tempo.
- Distribution Centers:Consolidated fulfillment operations balance throughput across multiple customer channels.
Warehouse Management anchors capital deployment by volume; Order Fulfillment shows the steepest expansion trajectory.
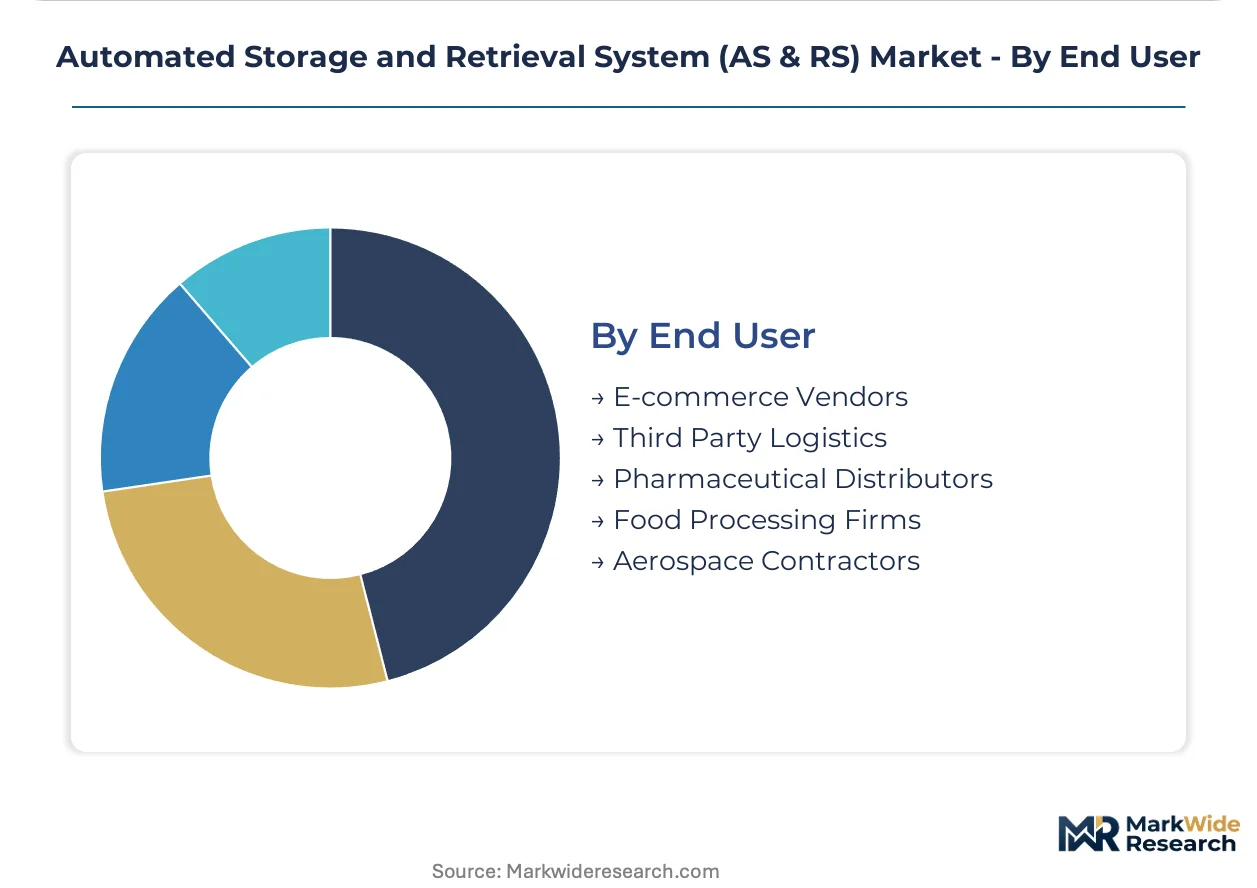
End User:
Customer scale and outsourcing intensity determine procurement sophistication and service contract structuring.
- Third Party Logistics:Outsourced fulfillment operators maintain dedicated AS & RS procurement budgets as consumer packaged goods manufacturers divest distribution infrastructure. 3PL margins compress during off-peak quarters, driving rejection of fixed service fees in favor of seasonal subscription tiers. Controls engineering talent scarcity extends commissioning timelines across US distribution corridors.
- E-commerce Vendors:Direct-to-consumer retailers specify shuttle-based configurations to meet same-day fulfillment expectations. Amazon and Walmart fulfillment networks in Texas and California are accelerating adoption of sub-hour retrieval systems. Multi-vendor software interoperability limitations delay warehouse management system integration and inflate customization spend.
- Pharmaceutical Distributors:FDA traceability mandates require software-validated inventory systems with lot-level tracking.
- Food Processing Firms:Temperature-controlled operations specify AS & RS configurations for cold chain integrity.
- Aerospace Contractors:Large-format inventory handling drives specialized unit load specifications for component storage.
Third Party Logistics commands the largest procurement budget pool; E-commerce Vendors are gaining share fastest on new system specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA workplace safety mandates in the United States are reshaping capital allocation across warehouse automation investments. The report identifies five countries where regulatory pressure and industrial clustering concentrate procurement activity.
United States
Third-party logistics operators in California and Texas are specifying shuttle-based configurations to meet same-day fulfillment service level agreements. FDA traceability requirements for pharmaceutical distributors in New Jersey and Pennsylvania mandate software-validated inventory systems with lot-level tracking. E-commerce fulfillment networks in the Pacific Northwest are accelerating forklift replacement programs under tightened OSHA machine guarding standards for collaborative robot zones.
Germany
Automotive sequencing operations in Stuttgart and Wolfsburg sustain demand for high-bay crane-based unit load systems where throughput stability outweighs velocity. The EU Machinery Directive and CE marking framework enforce functional safety ratings that filter equipment suppliers by certification depth. Pharmaceutical cold chain distributors in Bavaria are adopting vision-guided navigation retrofits to avoid months of operational downtime from floor-embedded wire guidance demolition.
China
E-commerce fulfillment networks in the Yangtze River Delta and Pearl River Delta are driving adoption of sub-hour retrieval systems to match consumer delivery expectations. GB standards and MIIT industrial automation policies shape procurement specifications for domestic warehouse operators. Manufacturing logistics clusters in Shenzhen and Shanghai are integrating AS & RS configurations with dual carbon goals through regenerative drive system specifications.
Japan
Precision electronics distribution in the Kanto region demands millimeter-level positioning accuracy for high-value component handling. METI productivity enhancement programs subsidize automation investments among mid-sized manufacturers with aging warehouse infrastructure. Automotive suppliers in Toyota City and Nagoya are specifying software-agnostic hardware platforms that integrate with diverse enterprise resource planning systems.
South Korea
Consumer electronics fulfillment in the Seoul Capital Area requires retrieval cycles compressed to minutes for same-day delivery commitments. MFDS pharmaceutical distribution regulations mandate validated inventory tracking systems that AS & RS software platforms provide. Semiconductor logistics operators in Suwon and Hwaseong are deploying mini-load configurations for cleanroom-compatible component storage.
Automated Storage and Retrieval System (AS & RS) Market Competitive Landscape
Vertically integrated material handling specialists and software-agnostic hardware fabricators split the market between project timeline control and integration flexibility. The vendor base concentrates around European and Japanese industrial corridors where decades of automotive and pharmaceutical logistics experience accumulated. Three strategic archetypes dominate: full-system integrators with captive component production, modular equipment specialists emphasizing WMS interoperability, and regional service networks anchoring aftermarket revenue. Competitive moves center on system integrator partnerships reconfiguring channel access for mid-sized distribution operators, plus unbundled service contract structures separating hardware procurement from software maintenance subscriptions.
Among full-system integrators with upstream equipment production, Daifuku Co., Ltd. and SSI SCHAEFER exemplify contrasting geographic anchoring strategies. Daifuku represents the vertically integrated archetype with project timeline control extending from design through commissioning. SSI SCHAEFER occupies a position emphasizing dense service networks across German industrial corridors. Within the software-agnostic tier, Knapp AG exemplifies hardware platforms designed for diverse warehouse management system integration. These three companies illustrate how competitive positioning fragments between timeline certainty, geographic service density, and integration flexibility rather than converging on a single optimal configuration.
| Leading Market Players |
|---|
| TGW Logistics Group |
| Daifuku Co., Ltd. |
| SSI SCHAEFER |
| Kardex |
| Swisslog Holding AG |
| Murata Machinery |
| Dematic |
| Knapp AG |
| Vanderlande |
| Others |
Pricing and Supply Chain Analysis
German automotive and pharmaceutical clusters anchor servo motor and precision rack fabrication capacity, concentrating margin capture among vertically integrated equipment fabricators while compressing procurement leverage for mid-sized distribution operators in North American markets. This upstream concentration forces project-based pricing models that extend from design through commissioning timelines.
Pricing Analysis
Geographic price spreads of 15-25 percent separate European installations from Asian deployments, reflecting CE marking compliance costs and localized service network density. Three-tier pricing structure across premium, standard, and economy levels stratifies by safety certification depth, with SIL-rated systems commanding substantial premiums over baseline OSHA-compliant configurations. Pricing pressure stems from steel and servo motor input volatility that compresses margins during extended bid-to-commission cycles. Third-party logistics operators exhibit highest price sensitivity due to seasonal volume fluctuations, while pharmaceutical distributors prioritize validation depth over unit economics.
Supply Chain Analysis
Contract manufacturing concentrates among Japanese precision motion specialists and German structural steel fabricators with captive rack production capabilities. Geographic supply concentration centers on Germany, Japan, and China for servo motors, structural steel, and control systems respectively. Raw material dependencies rest on high-grade steel alloys, rare-earth magnets for drive systems, and semiconductor components for PLC architectures. Single-source vulnerability in precision motion control modules creates bottleneck exposure for project timelines. Distribution runs through system integrator partnerships that reconfigure channel access for mid-sized operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AS & RS procurement is shifting toward platform-economics dynamics as software-agnostic hardware architectures displace vertically integrated legacy configurations, with interoperability emerging as the critical ecosystem battleground for warehouse management system integration.
For Market Incumbents: Entrench position through captive production of safety-critical components and accelerated certification investment under tightening EU Machinery Directive requirements. Deepen backward integration into servo motor and precision rack fabrication to insulate project margins from steel price volatility. Threat of modular shuttle entrants with software-first architectures demands defensive patent positioning in vision-guided navigation systems. For New Entrants and Emerging Players: Pursue brownfield retrofit opportunities in aging European warehouse stock where vision-guided navigation eliminates floor-embedded infrastructure barriers. Target third-party logistics channels in US distribution corridors with à la carte service tiering that aligns with seasonal volume compression. Go-to-market angle should emphasize rapid commissioning timelines and API-first WMS integration to bypass incumbent integration bottlenecks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-defined shuttle architectures as hardware commoditization accelerates. Long-term viability favors platform players with recurring software maintenance revenue over pure equipment vendors exposed to cyclical capital expenditure. Acquisition target archetype: modular equipment specialists with validated API libraries and established 3PL channel relationships. Signal to watch: unbundling rates of service contracts from hardware procurement as indicator of platform transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Vision-Guided Navigation Retrofit | Camera-based positioning eliminates floor demolition, compressing German pharmaceutical project timelines. |
| Software-Agnostic Platform Development | API-first architectures bypass WMS integration bottlenecks that delay 3PL commissioning cycles. |
| SIL-Rated Safety Certification | Exceeds baseline EU Machinery Directive compliance, filtering German automotive supplier pools. |
| Service Contract Unbundling | À la carte tiers align with seasonal 3PL volume fluctuations, preserving margin during off-peak quarters. |
| Regenerative Drive Integration | Meets tightening EU operational efficiency benchmarks favored in new facility specifications. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this analysis. Primary research incorporated structured discussions with warehouse operations directors, system integration engineers, 3PL procurement leads, and aftermarket service heads across German, US, and Japanese industrial corridors. Secondary validation drew from OSHA enforcement databases, EU Machinery Directive notification files, FDA validation guidance documents, and customs trade data for material handling equipment. Bottom-up project pipeline analysis triangulated against top-down capital expenditure tracking across e-commerce and pharmaceutical end-use segments.
Calibration against historical commissioning timelines and equipment replacement cycles shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, navigation technology tier, application tempo requirements, and end-user scale category, with additional weighting for regulatory compliance intensity by jurisdiction. CAGRs were derived from slope analysis of capital deployment trajectories and technology substitution curves. Industry-specific forecast inputs encompassed e-commerce fulfillment service level agreement evolution and pharmaceutical lot tracking mandate implementation schedules.
Sensitivities concentrate around steel and servo motor price volatility, regulatory validation timeline extensions, and WMS integration complexity escalation. Forecasts reflect documented assumptions regarding technology substitution rates and capital allocation priorities across end-use segments. Quarterly review of OSHA enforcement patterns, EU Machinery Directive amendment proposals, and 3PL margin compression indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Global Enterprise File Sharing and Synchronization (EFSS) Market
Storage Solutions
Saudi Arabia Data Center Storage Market
Storage Solutions
United Arab Emirates Data Center Storage Market
Storage Solutions
Nigeria Data Center Storage Market
Storage Solutions
Global in Memory Data Grid Market
Storage Solutions
Indonesia Data Center Storage Market
Storage Solutions
South Africa Data Center Storage Market
Storage Solutions
Stand Alone Cloud Storage Market
Storage Solutions
Vietnam Data Center Storage Market
Storage Solutions
Cloud Storage Market
Storage Solutions
UK Data Center Storage Market
Storage Solutions
Software Defined Storage Market
Storage Solutions
Philippines Data Center Storage Market
Storage Solutions
Data Backup and Recovery Market
Storage Solutions
Consumer Cloud Storage Services Market
Storage Solutions
Global Ethernet Storage Fabric Market